
 North America Enterprise WLAN Market | 2026-2036
North America Enterprise WLAN Market Size, Share, and Industry Trends Forecast 2026-2036
North America Enterprise WLAN Market Insights
The North America Enterprise WLAN market is restructuring around a sharp split between premium cloud-managed platforms and commodity access hardware. Cisco Systems leverages its Meraki cloud stack to capture recurring subscription revenue from mid-market enterprises. Hewlett Packard Enterprise anchors its position through Aruba Central, competing on AI-driven network assurance. Juniper Networks differentiates via Mist AI, specializing in proactive troubleshooting that reduces operational overhead for IT teams.
Enterprise wireless local area networks deliver radio-frequency connectivity across commercial facilities using 802.11ax and emerging 802.11be protocols, with access points typically supporting 2.4 GHz, 5 GHz, and 6 GHz bands to sustain high-density client environments. The primary purpose is seamless mobile connectivity for enterprise applications spanning voice, video, and IoT telemetry. Wi-Fi 6 and cloud-managed deployments lead current upgrade cycles, while mesh networking gains traction in sprawling campus and warehouse settings where cable backhaul proves impractical. Access points command the dominant hardware margin pool, though controllers face displacement as software-defined architectures consolidate management into cloud layers.
FCC Part 15 rules govern unlicensed spectrum use across the United States, while Industry Canada regulates parallel allocations, with both agencies expanding 6 GHz availability that directly shapes equipment certification requirements and refresh timelines. NIST cybersecurity frameworks and HIPAA technical safeguards further constrain how healthcare and financial WLAN deployments authenticate users and segment traffic. Stakeholders must weigh cloud-native management migration against stranded on-premises controller investments as vendor roadmaps diverge.
Market Dynamics
The North America Enterprise WLAN market is restructuring around the FCC's 6 GHz spectrum expansion, which is compressing equipment refresh cycles and forcing architectural migrations from hardware-centric to cloud-native management stacks across United States and Canadian enterprise campuses.
Growth Catalysts
- Wi-Fi 6E Protocol Adoption:Healthcare networks across Texas and California metro corridors are deploying tri-band access points to support IoT medical device density and real-time telemetry workflows mandated by HIPAA technical safeguards.
- FCC Part 15 Rule Expansion:The commission's 2020 decision to open 1,200 MHz of 6 GHz spectrum for unlicensed use is accelerating certification timelines and enabling high-throughput applications in warehouse automation and immersive video collaboration.
- Telemedicine Infrastructure Scaling:Canadian healthcare systems are extending wireless coverage to remote clinics and mobile health units, requiring mesh architectures that eliminate cable backhaul constraints in rural Ontario and British Columbia.
Market Restraints
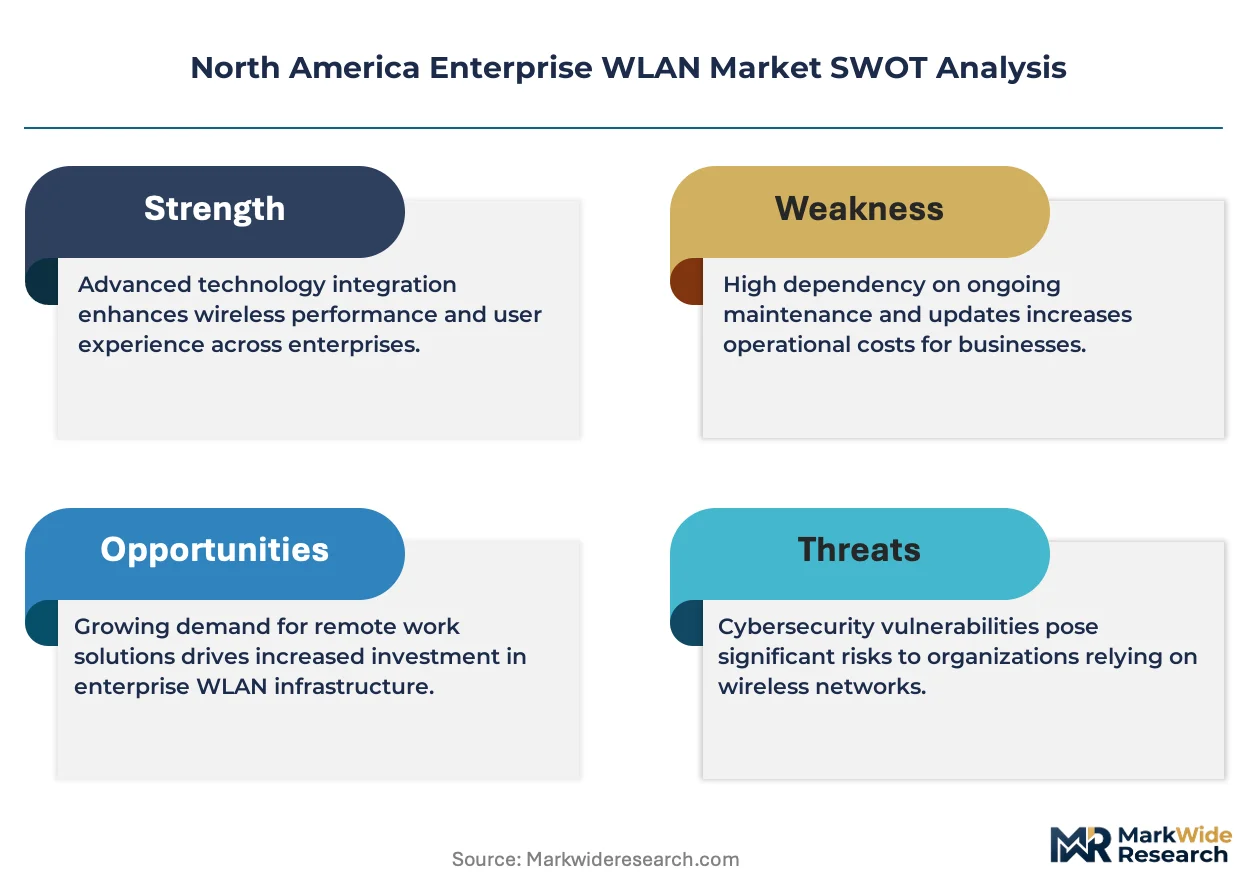
- Silicon Supply Concentration:Enterprise access point production depends on concentrated 802.11ax chipset fabrication in East Asian foundries, exposing North American vendors to lead time volatility and tariff exposure on finished goods.
- Controller Stranding Risk:Organizations with capitalized on-premises wireless LAN controller investments face accelerated depreciation as vendors sunset hardware management platforms in favor of subscription-based cloud stacks.
- Technical Limitation in Legacy Device Coexistence:Wi-Fi 6E's 6 GHz band offers no backward compatibility with 802.11n/ac client devices, forcing parallel infrastructure maintenance or forced endpoint refresh cycles that compress IT budgets.
Strategic Opportunities
- Underpenetrated Canadian Enterprise Segment:Mid-market organizations across Quebec and Alberta lag United States counterparts in cloud-managed deployment penetration, presenting whitespace for managed service provider channel expansion.
- AI-Driven Network Assurance Convergence:The intersection of machine learning inference at the network edge with cloud telemetry streams is enabling predictive fault detection that reduces mean-time-to-resolution for distributed retail and logistics networks.
- IRA-Aligned Smart Building Incentives:United States federal energy efficiency tax credits are accelerating wireless sensor network deployments for HVAC and lighting control integration in commercial real estate retrofit projects.
Industry Challenges
- RF Engineering Talent Scarcity:Enterprise IT departments lack sufficient spectrum analysis and interference mitigation expertise to optimize high-density 6 GHz deployments in steel-and-concrete warehouse environments.
- Multi-Vendor Integration Complexity:Heterogeneous access point estates from merged organizations create authentication and policy orchestration friction that delays unified zero-trust architecture implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Enterprise WLAN Market |
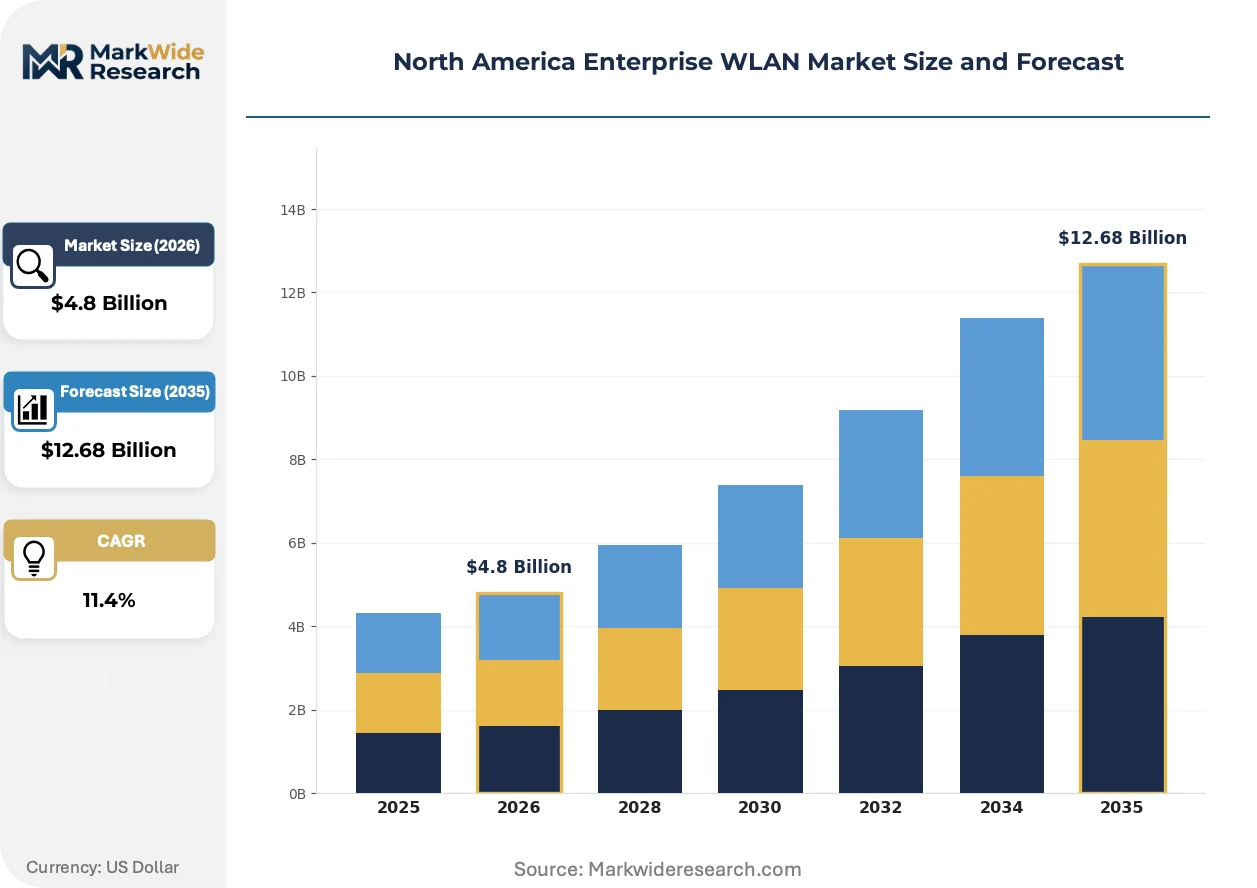
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Points, Routers, Controllers, Switches Technology: Wi-Fi 6, Wi-Fi 5, Mesh Networking, Cloud-managed End User: Retail, Education, Healthcare, Hospitality Installation: Indoor, Outdoor, Campus-wide, Distributed |
| Companies Covered | Cisco Systems, Hewlett Packard Enterprise, Juniper Networks, Extreme Networks, Fortinet, Arista Networks, Ubiquiti, CommScope, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Enterprise WLAN Market Trends and Innovations
Radio-frequency infrastructure across North American commercial facilities is undergoing architectural transformation as spectrum policy, cloud software stacks, and operational models converge to displace legacy controller-based designs.
Cloud-native wireless LAN management is decentralizing network intelligence from physical hardware controllers to distributed software layers running in vendor-operated data centers. Mid-market enterprises across Illinois and Georgia are adopting these platforms at accelerating velocity to eliminate appliance maintenance overhead. This shift is compressing capital expenditure profiles toward recurring operational models while enabling centralized policy enforcement across geographically dispersed sites.
FCC spectrum allocation decisions are reshaping equipment certification requirements and procurement priorities for North American enterprises. The commission's ongoing 6 GHz automated frequency coordination rulemaking will determine power limits for standard-power outdoor access points. Outdoor industrial and agricultural IoT deployments across the United States are awaiting final rules before committing to large-scale infrastructure builds.
Enterprise buyers are consolidating vendor relationships and demanding outcome-based service level agreements that bundle hardware, software, and operational support into single accountability structures. Healthcare and financial services verticals in New York and Toronto are leading this transition, displacing transactional equipment procurement with multi-year managed network contracts. This compression of the traditional value chain is forcing hardware vendors to build or acquire service delivery capabilities.
North America Enterprise WLAN Market Segmentation
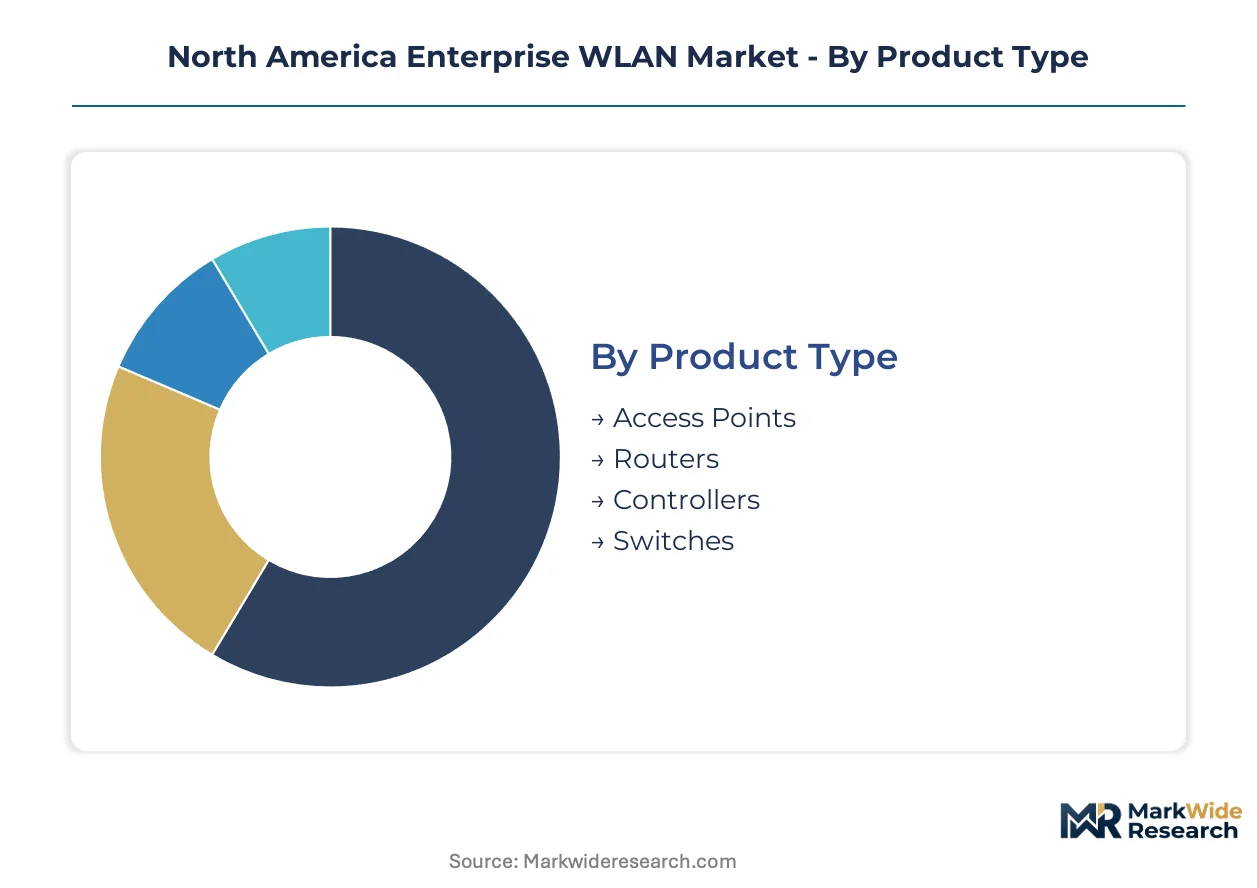
Enterprise WLAN procurement patterns diverge sharply across product architectures, spectrum generations, vertical workflows, and deployment topologies. Buyers prioritize interoperability and lifecycle economics over point specifications, compressing vendor margins in commoditized hardware while amplifying value capture in integrated management stacks.
Product Type:
Standardization dominates access hardware while customization concentrates in controller software and switch configurations tailored to density requirements.
- Access Points:Tri-band 802.11ax/802.11be radios supporting 2.4 GHz, 5 GHz, and 6 GHz bands form the physical edge layer. Healthcare networks across Texas and California metro corridors are deploying these units at highest density to support FDA-regulated IoT medical device telemetry and HIPAA-mandated network segmentation.
- Routers:Enterprise-grade units integrate WAN optimization, SD-WAN policy enforcement, and cellular failover for branch continuity. Retail chains across Illinois and Georgia are standardizing on cloud-orchestrated models to collapse appliance sprawl and unify policy management across hundreds of locations.
- Controllers:Physical appliances are depreciating rapidly as vendors sunset hardware platforms in favor of subscription-based cloud stacks. Stranded controller investments now compress IT depreciation schedules.
- Switches:Power-over-Ethernet models supply both data connectivity and electrical power to access points, eliminating separate cable runs in new construction and major retrofit projects.
Most installed capacity flows through Access Points. Expansion is steepest in Cloud-managed controller alternatives displacing on-premises hardware.
Technology:
Cost tier stratification separates premium 6 GHz deployments from legacy 5 GHz refresh cycles and budget-constrained mesh extensions.
- Wi-Fi 6:802.11ax protocol delivers orthogonal frequency-division multiple access and target wake time for high-density environments. FCC Part 15 rules governing unlicensed spectrum use in the United States and parallel Industry Canada regulations shape certification timelines and deployment eligibility.
- Wi-Fi 5:802.11ac Wave 2 equipment persists in budget-constrained refresh cycles where endpoint density does not justify immediate 6 GHz migration. Educational institutions across Ontario and Quebec are extending depreciation on these assets.
- Mesh Networking:Self-healing wireless backhaul eliminates cable infrastructure in sprawling warehouse and agricultural IoT deployments across rural British Columbia and Alberta. FCC automated frequency coordination rulemaking for standard-power outdoor access points remains pending.
- Cloud-managed:Vendor-hosted control planes consolidate policy, analytics, and firmware management. Mid-market enterprises are adopting these platforms to eliminate appliance maintenance overhead and shift capital expenditure to recurring operational models.
Volume concentrates in Wi-Fi 6 infrastructure. Steepest expansion trajectory belongs to Cloud-managed deployments compressing hardware controller markets.
End User:
Application intensity varies by vertical workflow requirements, with HIPAA and PCI-DSS compliance mandates driving premium procurement in regulated sectors.
- Retail:Point-of-sale continuity, inventory robotics, and customer Wi-Fi analytics demand high availability and seamless roaming. Chains are consolidating vendor relationships and demanding outcome-based service level agreements bundling hardware, software, and operational support.
- Education:K-12 and university campuses support one-to-one device programs and immersive video collaboration. Density spikes during class transitions stress legacy 802.11n/ac infrastructure.
- Healthcare:FDA-regulated IoT medical devices and telemedicine workflows mandate deterministic latency and segmented traffic under HIPAA technical safeguards. United States hospital systems are prioritizing 6 GHz tri-band access points.
- Hospitality:Guest satisfaction metrics tie directly to wireless performance in common areas and guest rooms. Properties are deploying mesh extensions to eliminate dead zones in historic building stock with concrete and steel construction.
Procurement volume flows through Retail networks. Expansion is steepest in Healthcare as FCC 6 GHz allocations enable real-time telemetry density.
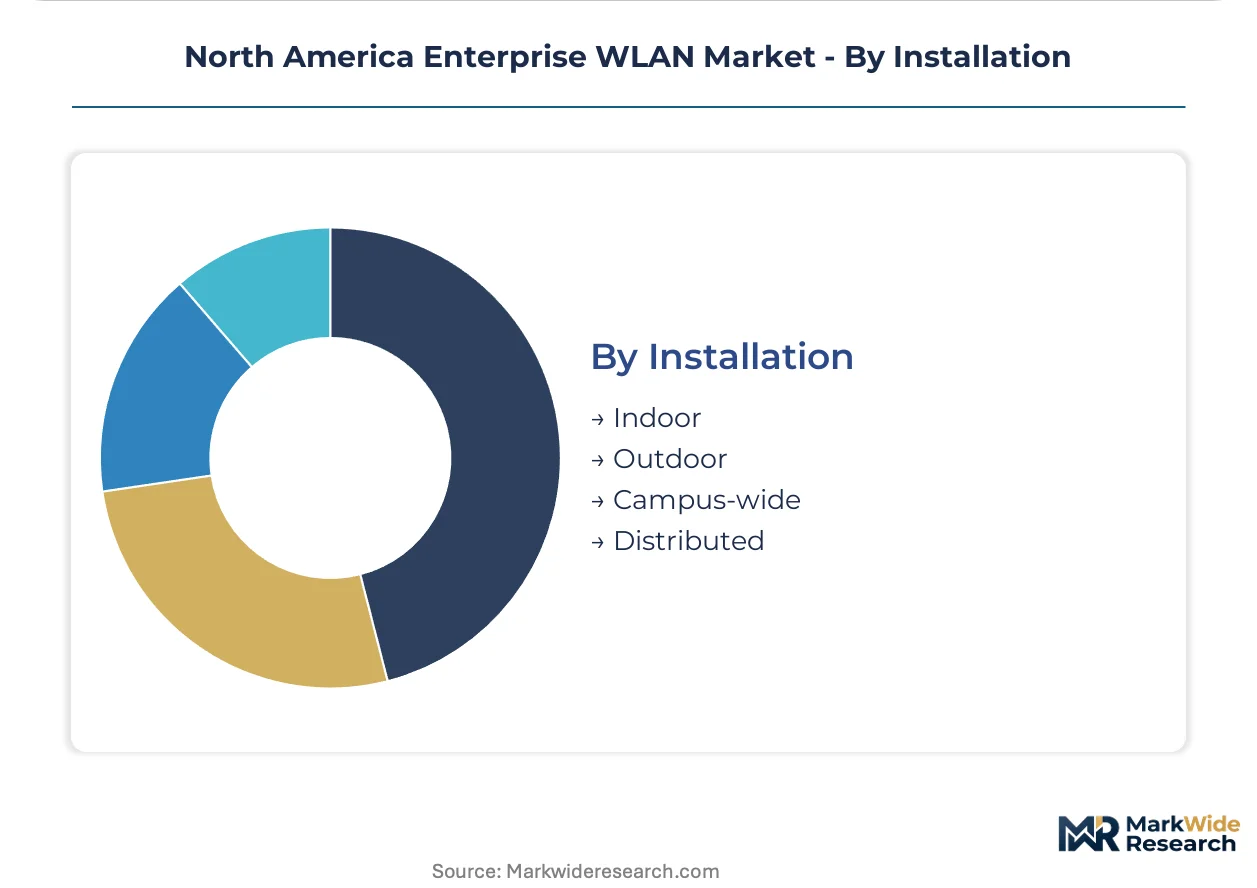
Installation:
Geography and building topology determine whether centralized campus designs or distributed architectures prove economically optimal.
- Indoor:Ceiling-mounted access points with integrated antennas dominate office, classroom, and clinical environments. Density planning requires RF engineering expertise scarce in enterprise IT departments.
- Outdoor:Weatherized enclosures and directional antennas extend coverage to parking structures, loading docks, and agricultural IoT perimeters. FCC standard-power 6 GHz rules for outdoor access points remain under rulemaking.
- Campus-wide:Unified controller domains or cloud-managed sites spanning multiple buildings with centralized policy enforcement. Universities and hospital systems across New York and Toronto are consolidating fragmented estates.
- Distributed:Hundreds to thousands of small-footprint sites with local internet breakout and cloud-managed policy synchronization. Retail and quick-service restaurant chains are standardizing on this topology.
Most deployed infrastructure serves Indoor environments. Expansion is steepest in Distributed architectures enabling lean IT staffing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially greater enterprise WLAN deployment velocity than Canada, driven by denser metro corridors and accelerated FCC spectrum liberalization. Mexico trails both neighbors in cloud-managed adoption but presents whitespace for distributed retail architectures.
United States
Texas and California metro corridors anchor domestic demand as healthcare systems deploy tri-band access points for FDA-regulated IoT medical devices. FCC Part 15 rules governing 6 GHz unlicensed spectrum compress equipment refresh timelines nationwide. New York financial services verticals are consolidating fragmented vendor estates into unified cloud-managed contracts.
Canada
Ontario and Quebec educational institutions extend depreciation on 802.11ac Wave 2 assets while mid-market enterprises lag in cloud penetration. Industry Canada regulations parallel FCC 6 GHz allocations but certification timelines trail United States counterparts by quarters. British Columbia warehouse operators are piloting mesh architectures to eliminate cable backhaul in sprawling distribution facilities.
Mexico
Nuevo León manufacturing clusters and Mexico City financial services drive initial Wi-Fi 6E trials among multinational subsidiaries. Federal telecommunications regulator IFT oversees spectrum coordination with limited 6 GHz commercial deployment to date. Bajío Region automotive suppliers are evaluating distributed architectures to support lean IT staffing across multiple assembly plants.
North America Enterprise WLAN Market Competitive Landscape
Top-tier vendors anchor premium cloud-managed stacks, while mid-tier specialists compete on vertical-specific feature depth. The vendor base stratifies across three tiers: full-stack incumbents with recurring subscription models, hardware-centric challengers pivoting toward software, and cloud-native disruptors attacking mid-market price points. Dominant competitive moves include backward integration into captive silicon supply and geographic expansion through managed service provider channel cultivation.
Within the full-stack tier, Cisco Systems and Hewlett Packard Enterprise exemplify contrasting architectural bets on cloud-native versus hybrid management planes. Juniper Networks occupies a specialist position emphasizing AI-driven operational tooling. These three entities collectively represent the strategic archetypes now dividing procurement decisions across United States and Canadian enterprise campuses.
| Leading Market Players |
|---|
| Cisco Systems |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Extreme Networks |
| Fortinet |
| Arista Networks |
| Ubiquiti |
| CommScope |
| Dell Technologies |
| Others |
Pricing and Supply Chain Analysis
RF engineering talent scarcity across Texas and California metro corridors widens labor-cost differentials between high-density deployment zones and secondary markets, directly amplifying pricing-tier spreads for cloud-managed versus on-premises controller architectures.
Pricing Analysis
The bundled-versus-unbundled service split separates recurring subscription models from transactional hardware procurement across North American enterprise campuses. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under FCC Part 15 rules and volume scale commitments from healthcare and retail verticals. Pricing pressure stems from controller stranding risk as vendors sunset hardware platforms, compressing margins on stranded on-premises investments. Mid-market enterprises across Illinois and Georgia exhibit highest price sensitivity due to constrained IT depreciation schedules, while hospital systems in New York and Toronto demonstrate lowest sensitivity given HIPAA-mandated network assurance requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from retail chains and healthcare systems, while managed service provider distribution feeds mid-market penetration across Canadian provinces. Access point production draws from concentrated 802.11ax chipset fabrication in Taiwan, South Korea, and mainland China foundries. Silicon wafer substrates, RF front-end modules, and power-over-Ethernet switch components constitute critical input dependencies. Single-source vulnerability in East Asian semiconductor fabrication exposes North American vendors to lead time volatility and tariff exposure on finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States and Canadian deployment cycles, with FCC spectrum liberalization compressing refresh timelines south of the border while Industry Canada certification lags create cost-efficient entry windows for cloud-native platforms.
For Market Incumbents: Cement recurring subscription revenue streams through backward integration into captive silicon supply chains that insulate against East Asian foundry concentration. Deepen AI-driven network assurance capabilities to defend against cloud-native disruptors attacking mid-market price points. Prioritize channel control through managed service provider partnerships in underpenetrated Quebec and Alberta enterprise segments. For New Entrants and Emerging Players: Rural Canadian healthcare clinics operating mesh architectures without cable backhaul infrastructure represent the most penetrable buyer archetype for specialized outdoor access point vendors. Target distributed retail architectures across Mexico's Bajío Region automotive suppliers where lean IT staffing models favor cloud-managed simplicity. Pursue outcome-based service level agreements bundling hardware, software, and operational support to bypass incumbent procurement relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among hardware-centric challengers pivoting toward software-defined architectures without established recurring revenue bases. Long-term viability hinges on successful cloud-native management migration and vertical-specific certification depth under FCC and Industry Canada frameworks. Monitor FCC automated frequency coordination rulemaking for standard-power outdoor access points as the critical inflection signal for agricultural and industrial IoT deployment scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Management Migration | Subscription revenue streams displace stranded controller hardware across Texas and California healthcare networks. |
| AI-Driven Network Assurance Development | Mist AI and Aruba Central platforms reduce mean-time-to-resolution for distributed retail estates. |
| 6 GHz Tri-Band Access Point Certification | FCC Part 15 compliance enables real-time IoT medical device telemetry in HIPAA-regulated hospital systems. |
| Managed Service Provider Channel Expansion | Quebec and Alberta mid-market enterprises lag United States cloud penetration by multiple quarters. |
| Mesh Architecture Pilot Programs | British Columbia warehouse operators eliminate cable backhaul constraints in sprawling distribution facilities. |
Research Methodology
Bottom-up enterprise vertical modeling reconciled against top-down chipset supply tracking forms the analytical core of this study. Primary interviews with wireless network architects, healthcare IT directors, retail operations executives, and managed service provider channel heads combined with secondary validation from FCC equipment authorization databases, Industry Canada certification filings, SEC 10-K infrastructure disclosures, and hyperscaler capex reports. Triangulation across these sources ensures segmentation integrity for access point, controller, and cloud-managed deployment categories.
The input-output matrix framing connects spectrum allocation policy decisions to equipment refresh velocity across United States and Canadian metro corridors. Segmentation dimensions span product architecture, protocol generation, vertical workflow intensity, and installation topology throughout the forecast period. CAGRs derive from unit shipment trajectories weighted by average selling price evolution and cloud subscription attach rates. Forecast inputs incorporate FCC 6 GHz automated frequency coordination rulemaking timelines and Industry Canada parallel regulatory developments.
Underlying measurement precision varies by segment; cloud-managed deployment forecasts carry tighter precision than legacy controller displacement estimates due to vendor disclosure transparency. Forecasts reflect assumptions regarding spectrum policy continuity, silicon supply normalization, and enterprise IT budget allocation patterns across the analysis window. Periodic stress-testing of base assumptions is recommended given regulatory rulemaking uncertainty and geopolitical tariff exposure in East Asian semiconductor supply chains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Equipment Market
Network Technology
Global Self-Organizing Network Market
Network Technology
Intelligent Network Management Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Residential Routers Market
Network Technology
Cloud Gateway Module Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Unified Network Management Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Europe Private 5G Network Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Open RAN Market
Network Technology
Wi-Fi Router Market
Network Technology
WAN Optimization Controllers Market
Network Technology
US Private 5G Network Market
Network Technology
Germany Residential Gateway Market