
 5G Radio Access Network Market | 2026-2036
5G Radio Access Network Market Size, Share, and Industry Trends Forecast 2026-2036
5G Radio Access Network Market Intelligence
Open RAN procurement frameworks across European mobile operators are reshaping vendor selection criteria and long-term equipment roadmaps. Telefonaktiebolaget LM Ericsson leverages its silicon-to-software stack to sustain integrated baseband-radio offerings. Nokia anchors its position through Cloud RAN partnerships with hyperscale cloud providers. Samsung Electronics Co., Ltd. competes aggressively in mmWave massive MIMO with operators across Northeast Asia.
A 5G Radio Access Network comprises the base stations, remote radio heads, antennas, and baseband units that connect user equipment to the core network through standardized 3GPP air interfaces operating across sub-6 GHz and millimeter-wave spectrum bands. Massive MIMO arrays with 64+ antenna elements dominate capital deployment in macro coverage layers due to spectral efficiency gains. Small cells and distributed antenna systems capture disproportionate growth in indoor enterprise and stadium venues where macro signals attenuate. Cloud RAN architectures are displacing traditional distributed baseband hotel designs as operators virtualize layer 2-3 functions onto commercial servers.
The Federal Communications Commission in the United States auctions mid-band spectrum while the European Commission enforces Open RAN interoperability through its 5G cybersecurity toolbox. Germany's Federal Network Agency and Japan's Ministry of Internal Affairs and Communications both mandate supply chain diversification benchmarks for critical network infrastructure. Stakeholders must monitor standardization timelines at 3GPP Release 18 and beyond to time silicon and software investments against spectral refarming schedules.
Market Dynamics
Open RAN interoperability mandates and mid-band spectrum refarming are compressing vendor consolidation cycles while fragmenting procurement authority across mobile network operators and hyperscale cloud providers.
Growth Catalysts
- Mid-band spectrum auctions:The FCC's C-band and 3.45 GHz releases in the United States are triggering macro site modernization cycles. Operators are replacing 4G massive MIMO with 5G-capable 64T64R arrays.
- Smart city densification:Seoul and Singapore are procuring millimeter-wave small cells for urban corridors and transportation hubs. Municipal budgets are co-funding radio infrastructure deployments.
- Open RAN mandates:Germany's Federal Network Agency and Japan's Ministry of Internal Affairs and Communications enforce supply chain diversification benchmarks. These frameworks are accelerating multi-vendor integration testing.
Market Restraints
- Silicon supply concentration:Advanced 7nm and 5nm baseband processor fabrication concentrates at TSMC and Samsung Foundry. Geographic concentration in Taiwan and South Korea creates single-point-of-failure exposure for radio unit production.
- Millimeter-wave propagation physics:Rain attenuation and non-line-of-sight blockage limit outdoor coverage radius to 150-200 meters. This constraint forces site density economics that challenge rural deployment viability.
- Legacy hardware stranded assets:Operators with recent 4G massive MIMO investments face accelerated depreciation schedules. The 3GPP Release 15/16 equipment lacks forward-compatible software architectures.
Strategic Opportunities
- Private 5G networks:Germany's Industrie 4.0 manufacturing clusters and Japan's automated ports are deploying dedicated campus radio networks. These verticals require localized baseband processing and spectrum leasing flexibility.
- Cloud RAN virtualization:Layer 2-3 function disaggregation onto AWS, Azure, and Google Cloud infrastructure is creating new managed service revenue pools. Operators are outsourcing baseband hotel operations to hyperscalers.
- Indoor enterprise DAS replacement:Stadiums, convention centers, and healthcare campuses are migrating from passive distributed antenna systems to active small cell architectures. This shift enables precise capacity scaling per venue.
Industry Challenges
- Open RAN integration complexity:Multi-vendor radio unit and baseband software interoperability requires extensive field testing. Operators are absorbing integration costs that traditional single-vendor contracts eliminated.
- Radio frequency engineer scarcity:Millimeter-wave beamforming optimization and massive MIMO array calibration demand specialized expertise. Training pipelines lag deployment timelines across operator engineering teams.
- 3GPP release synchronization:Feature development across Release 18 and 19 timelines creates silicon roadmap uncertainty. Chipset vendors face commitment decisions before standards finalize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Radio Access Network Market |
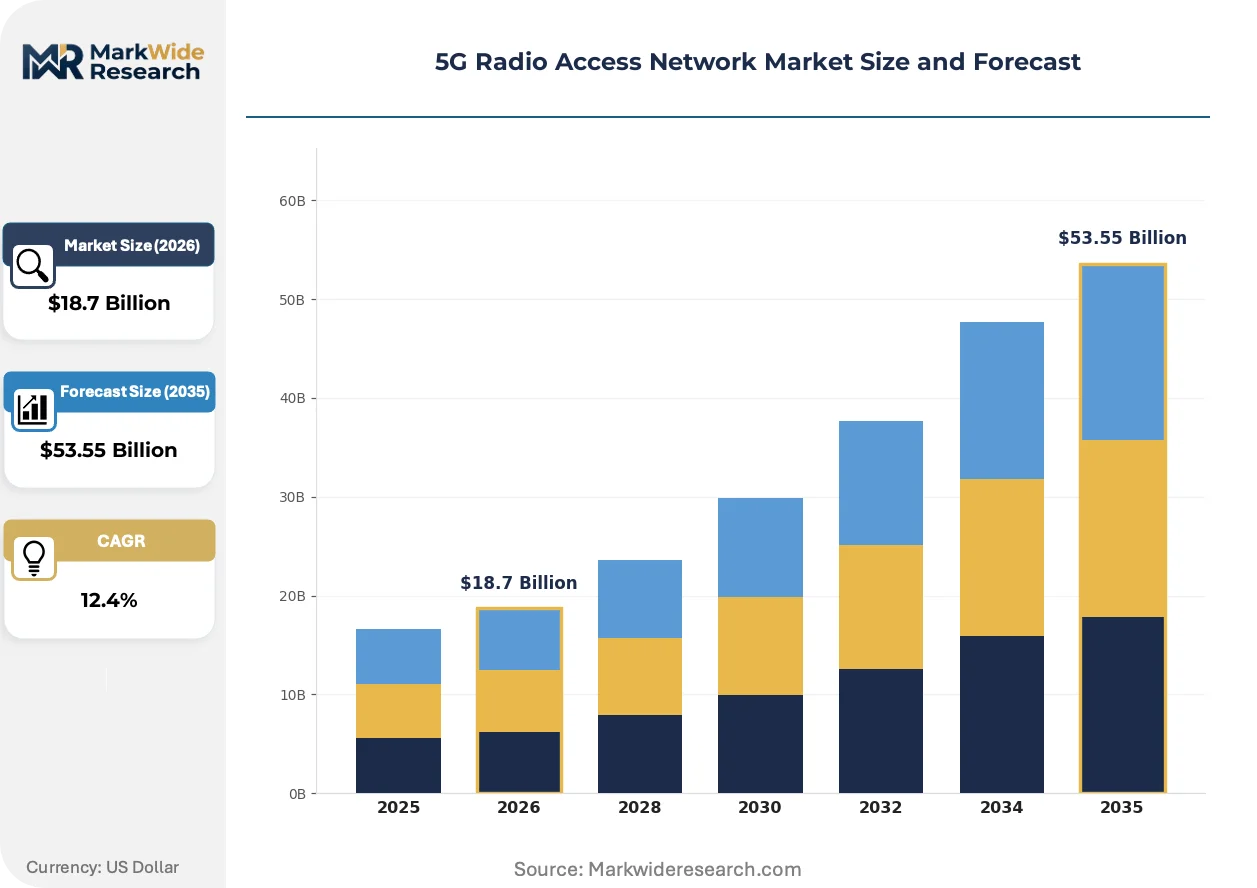
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $53.55 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Massive MIMO, Beamforming, Small Cells, Distributed Antenna Systems Deployment Model: Private Network, Public Network, Hybrid Network, Cloud RAN End User: Telecommunications, Automotive, Healthcare, Smart Cities Frequency Band: Sub-6 GHz, mmWave, Dynamic Spectrum Sharing, Licensed Spectrum |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Huawei Technologies Co., Ltd., Nokia, Samsung Electronics Co., Ltd., Qualcomm Technologies, Inc., Cisco Systems, Inc., Intel Corporation, Verizon Communications, Inc., VMware, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Radio Access Network Market Strategic Shifts & Innovations
Virtualization of layer 2-3 network functions and disaggregation of hardware-software stacks are redefining competitive boundaries between traditional telecom vendors and cloud-native entrants.
Massive MIMO active antenna units are migrating from proprietary digital beamforming ASICs to merchant silicon with programmable FPGA overlays. Tier-1 operators in South Korea and the United States are piloting these reconfigurable architectures to enable software-defined spectrum refarming. This technology migration is compressing hardware refresh cycles from seven years toward four-year replacement timelines.
The European Commission's 5G cybersecurity toolbox mandates vendor diversification and security certification for critical network components. Germany's implementation through the Federal Network Agency requires operators to document supply chain provenance for radio and baseband equipment. Macro network procurement in France and Italy is now conditioning contract awards on Open RAN interoperability demonstrations.
Enterprise buyers are unbundling network equipment procurement from managed services contracts. Manufacturing and logistics campuses in Japan and Germany are negotiating direct radio unit purchases while sourcing cloud baseband capacity separately. This buying pattern fragmentation is most visible in automotive production facilities deploying private 5G for automated guided vehicle coordination.
5G Radio Access Network Market Segmentation
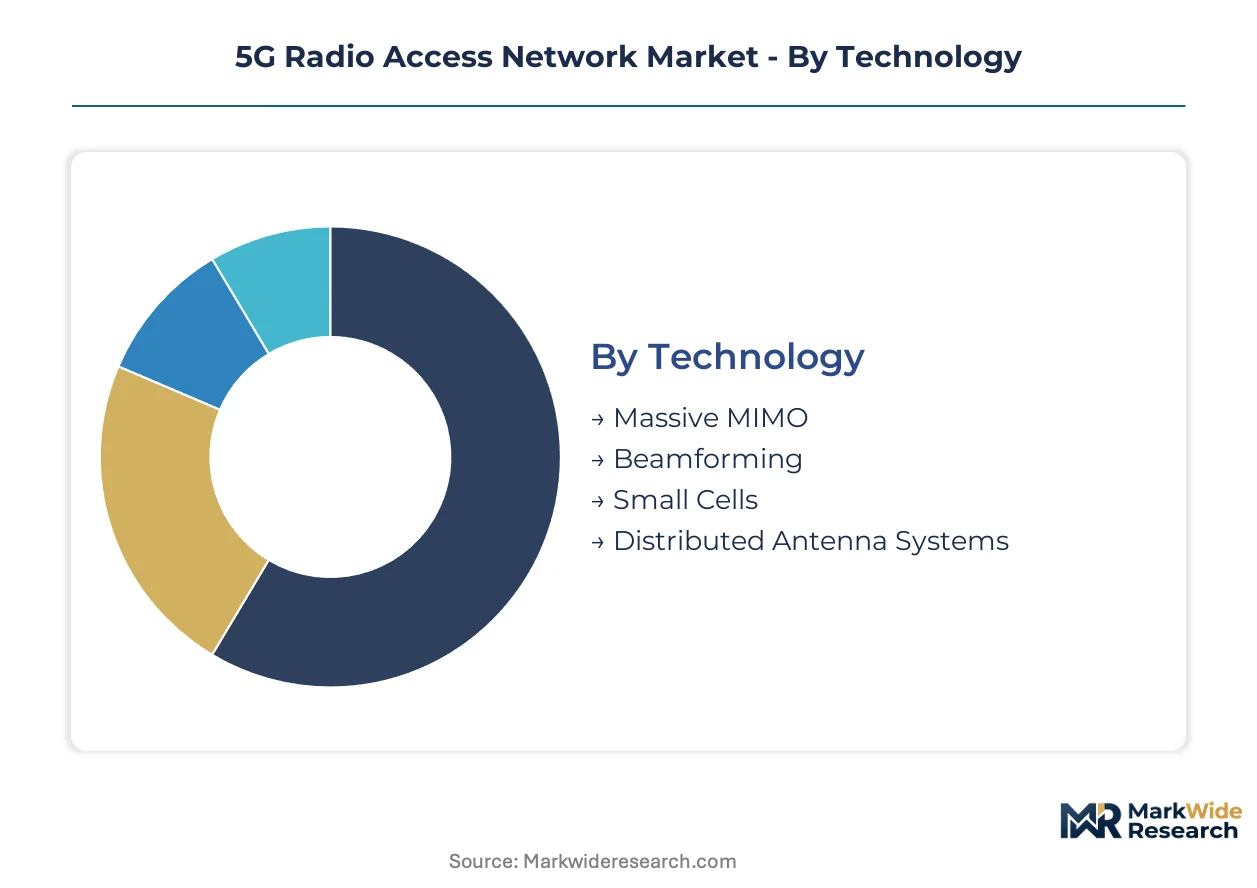
Technology heterogeneity across 5G Radio Access Network deployments demands precise segmentation mapping. Procurement patterns diverge sharply between macro coverage layers and indoor enterprise venues, while regulatory mandates on Open RAN interoperability reshape vendor selection criteria across each technical dimension.
Technology:
Mature architectures dominate macro deployment budgets while emerging techniques capture disproportionate growth in specialized coverage scenarios.
- Massive MIMO:Active antenna units integrate 64T64R arrays with proprietary digital beamforming ASICs or merchant silicon overlays. South Korean operators in Seoul's dense urban corridors deploy these for spectral efficiency gains in sub-6 GHz macro layers. Equipment refresh cycles compress from seven years toward four as programmable architectures enable software-defined refarming.
- Beamforming:Dynamic beam steering algorithms optimize signal propagation through millimeter-wave spectrum. Singapore's smart city corridors deploy beamforming-intensive small cells for transportation hub coverage, constrained by rain attenuation physics limiting outdoor radius to 150-200 meters.
- Small Cells:Low-power radio units address indoor enterprise and stadium venue capacity gaps where macro signals attenuate. Municipal co-funding accelerates procurement in Seoul and Singapore.
- Distributed Antenna Systems:Passive coaxial-fed architectures migrate toward active fiber-connected small cell replacements in healthcare campuses and convention centers.
Massive MIMO retains volume leadership; Small Cells holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates capital-intensive integrated stacks from emerging disaggregated alternatives with lower entry thresholds.
- Private Network:Dedicated campus radio deployments with localized baseband processing serve Industrie 4.0 manufacturing clusters in Germany and automated ports in Japan. Spectrum leasing flexibility and guaranteed latency drive procurement from automotive and logistics verticals.
- Public Network:Traditional macro network infrastructure operated by mobile network operators delivers wide-area coverage through 3GPP standardized interfaces. FCC C-band and 3.45 GHz auctions in the United States trigger macro site modernization cycles replacing 4G equipment.
- Hybrid Network:Combined public-private architectures partition control plane functions across operator core and enterprise edge.
- Cloud RAN:Layer 2-3 function virtualization onto AWS, Azure, and Google Cloud infrastructure creates managed service revenue pools. Germany's Federal Network Agency and Japan's Ministry of Internal Affairs and Communications mandate supply chain diversification benchmarks that accelerate multi-vendor integration testing.
Public Network retains volume leadership; Cloud RAN holds the steepest expansion curve.
End User:
Application-specific performance requirements dictate radio unit specifications and baseband processing architectures.
- Telecommunications:Mobile network operators procure integrated baseband-radio stacks or disaggregated Open RAN components for wide-area coverage. Germany's Federal Network Agency enforces vendor diversification documentation for critical network infrastructure.
- Automotive:Production facilities negotiate direct radio unit purchases for automated guided vehicle coordination while sourcing cloud baseband capacity separately. Manufacturing campuses in Japan and Germany drive unbundled procurement patterns.
- Healthcare:Hospital campuses require precise indoor coverage with electromagnetic interference shielding compliance.
- Smart Cities:Municipal budgets co-fund millimeter-wave densification in urban corridors and transportation hubs. Seoul and Singapore anchor procurement volume with aggressive small cell deployment timelines.
Telecommunications retains volume leadership; Smart Cities holds the steepest expansion curve.
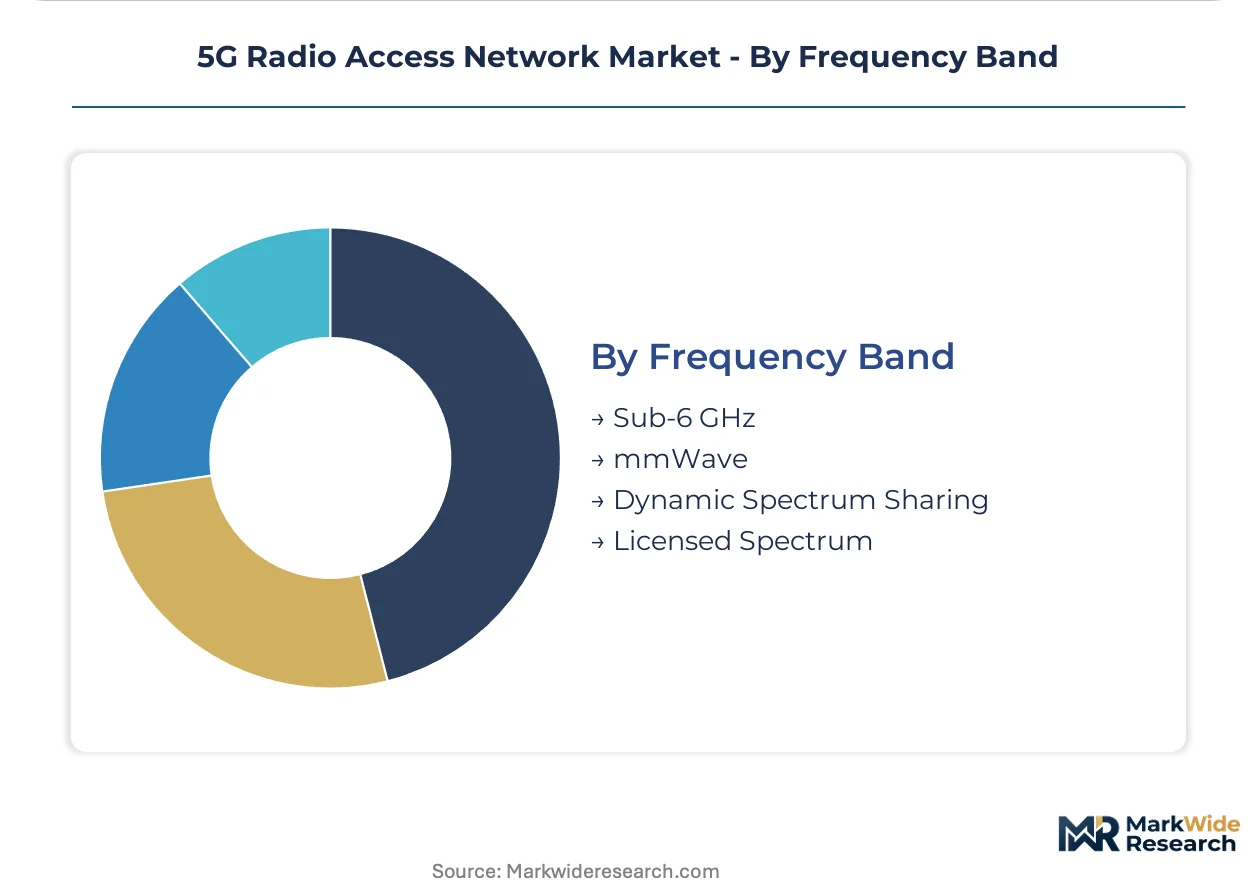
Frequency Band:
Geographic licensing frameworks and propagation physics segment procurement by coverage-coverage tradeoffs.
- Sub-6 GHz:Mid-band spectrum delivers balanced coverage and capacity for macro layer deployment. FCC auctions in the United States release C-band and 3.45 GHz allocations triggering equipment replacement cycles.
- mmWave:Millimeter-wave bands enable gigabit throughput in dense urban hotspots. Rain attenuation and non-line-of-sight blockage constrain outdoor coverage radius, forcing site density economics that challenge rural viability.
- Dynamic Spectrum Sharing:Software-defined coexistence of 4G and 5G services on identical carrier frequencies extends legacy asset utilization.
- Licensed Spectrum:Exclusive frequency allocations guarantee interference protection for critical communications.
Sub-6 GHz retains volume leadership; mmWave holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 5G Radio Access Network Market spans infrastructure deployments anchored by submarine cable landings, fiber backhaul corridors, and spectrum licensing regimes that shape procurement intensity across national markets.
United States
FCC C-band and 3.45 GHz spectrum auctions triggered macro site modernization cycles replacing 4G massive MIMO with 5G-capable 64T64R arrays. The Federal Communications Commission enforces supply chain security reviews through its 5G cybersecurity framework. Dense urban corridors in New York and Los Angeles anchor millimeter-wave densification timelines.
Germany
Industrie 4.0 manufacturing clusters drive private 5G network procurement with localized baseband processing requirements. The Federal Network Agency mandates supply chain diversification benchmarks and vendor documentation for critical network infrastructure. Automotive production facilities in Bavaria and Baden-Württemberg negotiate direct radio unit purchases.
Japan
Automated port terminals and manufacturing campuses accelerate dedicated campus radio deployments with guaranteed latency specifications. The Ministry of Internal Affairs and Communications enforces Open RAN interoperability testing and supply chain diversification requirements. Tokyo and Osaka metropolitan areas concentrate macro network densification investments.
South Korea
Seoul's dense urban corridors anchor the fastest millimeter-wave densification timelines globally with aggressive small cell procurement. Municipal budgets co-fund radio infrastructure through smart city deployment frameworks. Samsung Electronics Co., Ltd. competes aggressively in mmWave massive MIMO across Northeast Asian operator networks.
Singapore
Smart city transportation hubs and urban corridors drive millimeter-wave small cell procurement with municipal budget co-funding mechanisms. The Infocomm Media Development Authority coordinates spectrum allocation and infrastructure deployment standards. The city-state's compact geography enables rapid site density economics for outdoor coverage layers.
5G Radio Access Network Market Key Industry Players
On the supply side, the industry is consolidating around integrated silicon-to-software stacks while fragmenting procurement authority across multi-vendor Open RAN configurations. Tier-1 integrated vendors compete against cloud-native disaggregated entrants and specialized component suppliers. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and vertical integration into baseband processor design.
Within the integrated vendor tier, Telefonaktiebolaget LM Ericsson and Nokia occupy positions defined by their silicon-to-software stack depth and Cloud RAN partnership architectures. Samsung Electronics Co., Ltd. anchors the Northeast Asian competitive vector through mmWave massive MIMO specialization. These three exemplify divergent strategic responses to Open RAN interoperability mandates compressing traditional single-vendor contract structures.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Huawei Technologies Co., Ltd. |
| Nokia |
| Samsung Electronics Co., Ltd. |
| Qualcomm Technologies, Inc. |
| Cisco Systems, Inc. |
| Intel Corporation |
| Verizon Communications, Inc. |
| VMware, Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in 7nm and 5nm baseband processor fabrication across Taiwan and South Korea is compressing supplier margins while inflating long-term contract premiums for radio unit procurement. Mobile network operators absorb this cost pass-through through accelerated depreciation schedules on stranded 4G assets.
Pricing Analysis
Volume-discount tiering separates hyperscale cloud providers purchasing baseband capacity at scale from municipal smart city budgets procuring small cell clusters in single-digit quantities. Price differentiation rests on certification grade for Open RAN interoperability and geographic delivery cost to dense urban corridors versus rural macro sites. Cost compression in mid-band massive MIMO arrays is intensifying because merchant silicon overlays displace proprietary ASICs. Municipal procurement teams exhibit highest price sensitivity; Tier-1 mobile operators with spectrum auction debt service demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for baseband processor and radio unit sourcing. Advanced semiconductor fabrication concentrates in Taiwan, South Korea, and the United States. Raw material dependencies span gallium nitride substrates, high-purity silicon wafers, and specialized RF filter ceramics. Single-source vulnerability at TSMC and Samsung Foundry creates geographic concentration exposure. Distribution runs through direct OEM contracts to mobile operators and hyperscale cloud providers, with systems integrators mediating multi-vendor Open RAN configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interoperability mandates are compressing vendor consolidation cycles, creating high-growth disruption as traditional single-vendor contracts fragment across multi-supplier procurement frameworks.
For Market Incumbents: Pre-empt margin erosion in integrated baseband-radio stacks by accelerating Cloud RAN partnerships with AWS, Azure, and Google Cloud. Invest in backward integration into merchant silicon design to offset proprietary ASIC displacement. Counter emerging cloud-native entrants through certification pre-qualification for Germany's Federal Network Agency and Japan's Ministry of Internal Affairs and Communications supply chain diversification benchmarks. For New Entrants and Emerging Players: Build out Open RAN software layer specialization targeting multi-vendor integration testing services where incumbent operators absorb cost premiums. Target private 5G network deployments in Germany's Industrie 4.0 manufacturing clusters and Japan's automated port terminals as most penetrable verticals. Pursue direct radio unit sales to automotive production facilities unbundling procurement from managed services contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Cloud RAN virtualization sub-segments as layer 2-3 functions migrate to commercial servers. Long-term viability favors asset-light software vendors over capital-heavy integrated hardware manufacturers over the coming decade. Monitor 3GPP Release 18 and 19 standardization timelines as inflection indicators for silicon roadmap commitment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud RAN Partnership Formation | Hyperscale cloud providers capture baseband hotel operations from traditional mobile network operators. |
| Open RAN Interoperability Certification | Germany's Federal Network Agency and Japan's MIC mandate multi-vendor testing documentation. |
| Merchant Silicon Migration | Programmable FPGA overlays enable software-defined spectrum refarming, compressing hardware refresh cycles. |
| Private 5G Network Deployment | Automotive and logistics verticals in Japan and Germany demand localized baseband processing with guaranteed latency. |
| Small Cell Densification | Seoul and Singapore municipal budgets co-fund millimeter-wave infrastructure in urban transportation corridors. |
Research Approach
The analysis maps macro coverage layers, indoor enterprise venues, Cloud RAN virtualization, and private network deployments, each validated through network planning engineers, procurement officers at mobile operators, hyperscale cloud infrastructure architects, and regulatory affairs specialists at national telecom authorities. Primary interviews triangulate against secondary sources including FCC spectrum auction records, 3GPP standardization documents, SEC filings from listed equipment vendors, and national regulator supply chain security frameworks. Bottom-up equipment shipment data reconciles with top-down operator capex disclosures.
Assumptions held fixed include 3GPP Release 18 standardization timelines, existing spectrum licensing frameworks across modeled geographies, and current tariff structures affecting semiconductor trade. Variables include Open RAN procurement penetration rates, cloud provider market share in baseband virtualization, and millimeter-wave small cell deployment velocity in smart city corridors. CAGRs derive from equipment replacement cycle compression, virtualization adoption curves, and vertical-specific private network buildouts across the projection horizon.
Practitioners should monitor 3GPP release synchronization delays, foundry capacity utilization inflections, and Open RAN interoperability test failure rates for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Turkey Telecom Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Satcom Terminal Market
Telecommunications
Cellular Modem Market
Telecommunications
Belgium ICT Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Mobile Voice Market
Telecommunications
5G Connections Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Indonesia ICT Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Esim Subscription Market
Telecommunications
Promotional Sms Market
Telecommunications
Peru Telecom Market
Telecommunications
5G System Integration Market