
 Microduct Market | 2026-2036
Microduct Market Size, Share, and Industry Trends Forecast 2026-2036
Microduct Market Outlook
Modular bundled configurations is consolidating as the dominant procurement format for large-scale fiber deployments. Dura-Line leverages its manufacturing scale across North America to supply pre-integrated duct bundles for telecom operators. Sterlite Technologies Limited anchors its position through backward integration into polymer compounding for optical-grade conduits. Hexatronic Group AB differentiates via specialized aerial microduct systems designed for Nordic climate extremes.
Microduct denotes a small-diameter conduit, typically fabricated from high-density polyethylene or polypropylene, engineered to house and protect fiber optic cables through blown-fiber or pull-through installation methods. Wall thickness, inner diameter tolerance, and friction coefficient determine blow distance and cable protection performance in field conditions. Multi-wall product configurations command margin premiums due to crush resistance requirements in direct burial utility applications. Blown fiber technology segments are expanding fastest as operators prioritize speed of deployment over traditional pull-through methods in greenfield networks.
FCC broadband equity programs in the United States, EU Green Deal digital infrastructure targets, and REACH material compliance standards in Europe collectively shape product certification and market access requirements for microduct suppliers. ECHA substance restrictions on plastic additives are forcing reformulation of jacket compounds across export-oriented manufacturers. Stakeholders must monitor evolving national broadband subsidy eligibility rules, as procurement specifications tied to infrastructure funding increasingly dictate material grades and installation method approvals.
Market Dynamics
Fiber-to-the-home deployment velocity is compressing installation timelines and forcing material specification upgrades across utility and telecom procurement channels. Blown-fiber technology adoption is displacing pull-through methods in greenfield networks, rewriting competitive requirements for duct friction coefficients and wall thickness tolerances.
Growth Catalysts
- FCC Broadband Equity Access Deployment:Federal subsidy eligibility rules mandate fiber-deep infrastructure in underserved US census tracts, pulling microduct volumes into rural utility corridors.
- EU Green Deal digital infrastructure targets:Carbon-neutral network construction mandates accelerate demand for recycled-content HDPE formulations in European fiber deployments.
- Smart grid integration:German utility operators are bundling fiber and power infrastructure in single-trench deployments, creating specification demand for crush-resistant multi-wall duct configurations.
Market Restraints
- Polymer feedstock volatility:High-density polyethylene resin prices fluctuate with ethylene cracking margins, compressing converter margins on fixed-price municipal contracts.
- ECHA additive restrictions:REACH substance restrictions on phthalate plasticizers and flame retardants force compound reformulation, extending certification timelines for export-oriented manufacturers.
- Direct burial copper legacy:Existing metallic infrastructure in established markets creates stranded asset resistance to fiber overbuilds in last-mile access networks.
Strategic Opportunities
- India BharatNet Phase III:Rural broadband saturation targets create demand for aerial microduct systems in terrain where trenching costs exceed cable installation economics.
- 5G fronthaul densification:Small cell fiber backhaul requirements are pulling microduct into urban street furniture and utility pole attachments.
- Pre-integrated bundle channels:Direct contracting between polymer compounders and telecom operators bypasses traditional distribution, capturing margin from specification control.
Industry Challenges
- Blow-distance engineering talent:Field optimization of fiber cable air-blowing requires specialized technicians scarce outside Nordic and German training pipelines.
- Multi-standard certification stacking:Products must simultaneously satisfy FCC broadband subsidy rules, ECHA material compliance, and utility-specific crush-test protocols, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microduct Market |
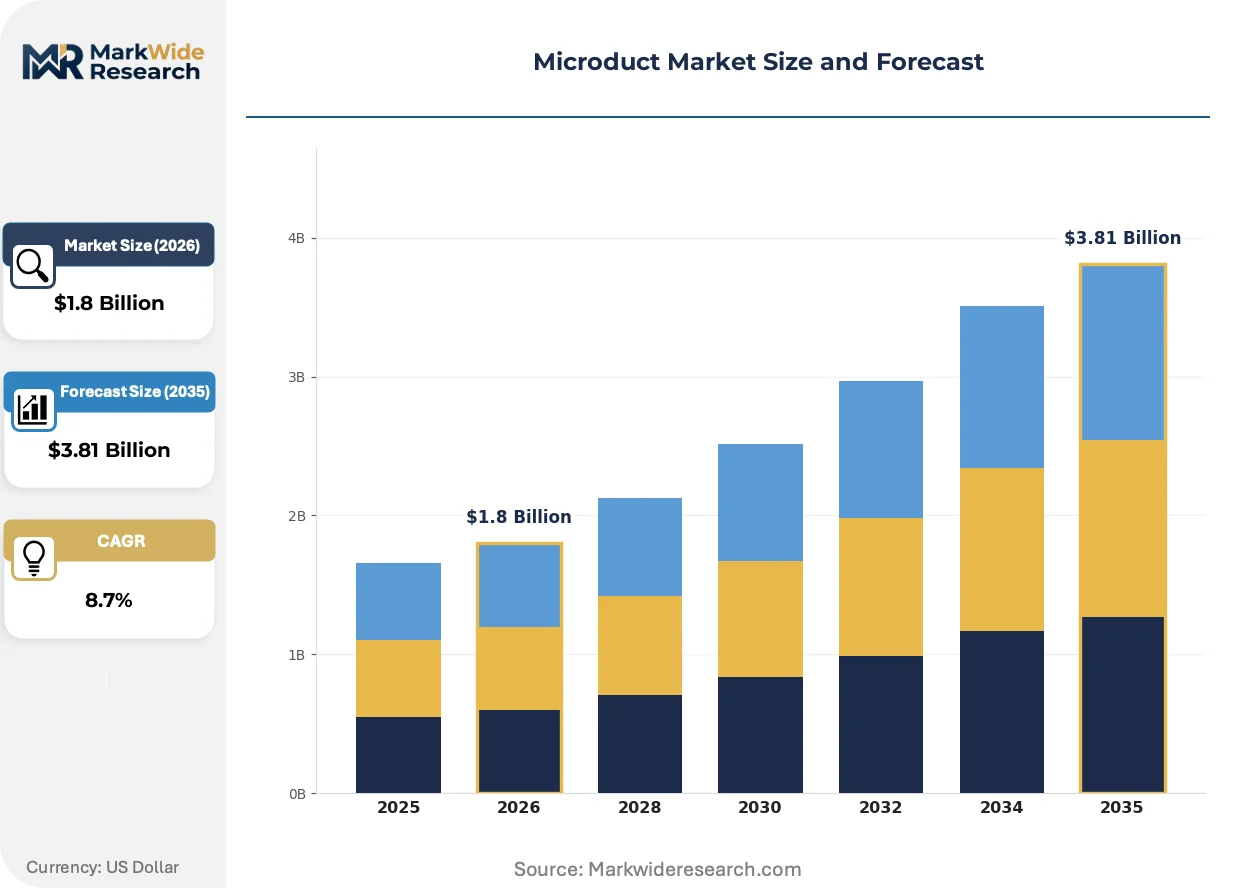
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall, Multi-Wall, Pre-terminated, Custom Solutions Installation Method: Direct Burial, Aerial, Underground, Indoor Technology: Blown Fiber, Traditional Fiber, Hybrid Systems, Maintenance-Free End User: Telecommunications, Data Centers, Utility Providers, Others |
| Companies Covered | Dura-Line, Datwyler IT Infra., Emtelle Holdings Ltd, Sterlite Technologies Limited, Egeplast International GmbH, Hexatronic Group AB, Clearfield Inc., Sumitomo Electric Industries Ltd, Prysmian Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microduct Market Strategic Shifts
Material science advances and installation method preferences are converging to redefine performance benchmarks and procurement specifications across fiber infrastructure deployment.
Silicon-coated inner duct surfaces are electrifying blow-distance capabilities in high-density polyethylene conduits. Tier-one telecom operators in Germany and the United States are specifying these low-friction formulations for metropolitan ring networks where installation speed determines project economics. The technology is electrifying competitive differentiation around coefficient-of-friction metrics previously treated as commodity specifications.
REACH substance restriction expansions are forcing reformulation of jacket compounds across European export supply chains. ECHA restrictions on halogenated flame retardants and certain phthalate plasticizers now cover microduct applications previously exempt under construction-product derogations. Compounders serving Nordic markets are responding fastest, leveraging existing bio-based polymer development pipelines to maintain market access.
Specification-driven procurement is consolidating buyer power around fiber network operators with in-house engineering capabilities. Traditional distribution channels serving smaller regional contractors are losing volume to direct manufacturer relationships where technical collaboration shapes material selection. This pattern concentrates most visibly in German utility-grade deployments where smart grid integration requirements demand application-specific duct configurations unavailable through catalog distribution.
Microduct Market Segmentation
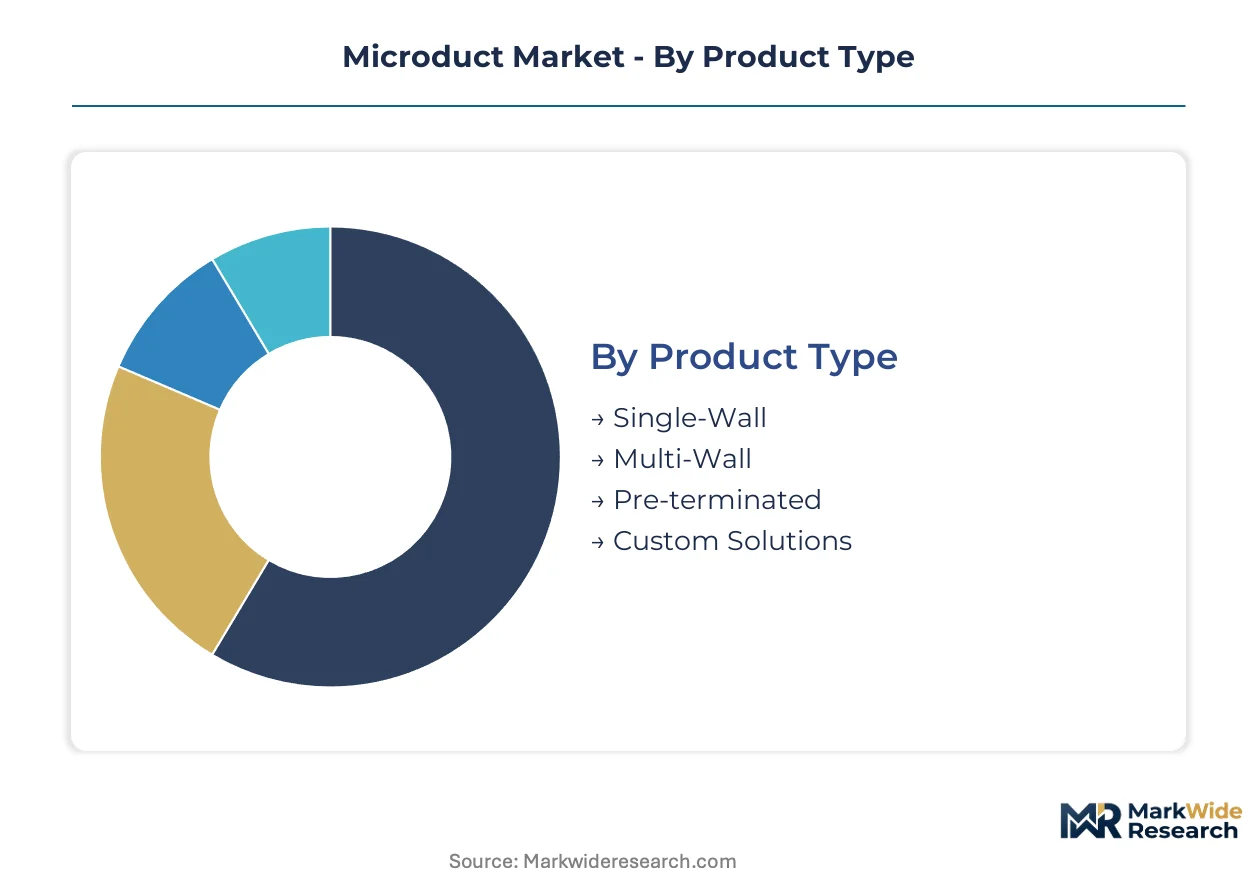
Microduct procurement decisions cascade from product architecture through installation constraints to end-use performance requirements. Specification control at the segment level determines competitive positioning for compounders and converters serving fiber infrastructure buildouts.
Product Type:
Supply concentration among large-scale extruders favors standardized wall configurations, while specialty compounders capture margin in application-specific formulations.
- Single-Wall:Monolithic HDPE construction offers baseline crush resistance for aerial and indoor deployments where mechanical loading remains moderate. German telecom operators specify these for metropolitan fiber rings with existing pathway protection.
- Multi-Wall:Nested concentric tubes with corrugated outer shells deliver superior radial compression strength for direct burial utility corridors. Smart grid integration projects in Germany are absorbing capacity for power-fiber co-location trenches requiring enhanced mechanical protection.
- Pre-terminated:Factory-integrated cable-duct assemblies reduce field splicing labor for rapid-deployment scenarios.
- Custom Solutions:Application-engineered profiles serve unique pathway geometries or environmental constraints.
Multi-wall configurations absorb the bulk of installed capacity in utility-grade deployments; pre-terminated bundles are expanding most quickly in subsidy-driven rural broadband programs.
Installation Method:
Cost tier differentiation separates trench-intensive methods from aerial alternatives where terrain or right-of-way constraints dominate project economics.
- Direct Burial:Trench-placed ducts with native backfill or controlled low-strength material surround suit greenfield utility corridors. FCC broadband equity programs are pulling volumes into rural US census tracts with favorable soil conditions.
- Aerial:Messenger-supported or self-supporting microducts attach to existing utility poles or dedicated strand infrastructure. India's BharatNet Phase III targets are creating demand in Himalayan and Northeastern terrain where trenching costs exceed cable installation economics.
- Underground:Conduit-in-conduit or microtrenching deployments in urban rights-of-way.
- Indoor:Plenum-rated or riser-rated formulations for building distribution and data center interconnection.
Direct burial retains the largest share of annual volume; aerial methods are gaining share fastest in mountainous or flood-prone geographies.
Technology:
Customer type preferences are bifurcating between speed-optimized blown-fiber systems and reliability-focused traditional pull-through methods.
- Blown Fiber:Compressed air propels fiber through lubricated ducts at velocities exceeding traditional mechanical pulling. Silicon-coated inner surfaces specified by tier-one German and US operators are extending blow distances beyond prior mechanical limits.
- Traditional Fiber:Conventional pull-through installation with winch-assist or manual placement suits short-reach applications or retrofit scenarios. Established contractors in markets with legacy copper infrastructure favor familiar installation protocols.
- Hybrid Systems:Configurable for either blown or pulled deployment depending on field conditions.
- Maintenance-Free:Sealed or gel-filled designs eliminate future access requirements for submarine or inaccessible routes.
Blown fiber is climbing the fastest as operators prioritize deployment velocity in greenfield networks; traditional methods retain share in retrofit and short-reach applications.
End User:
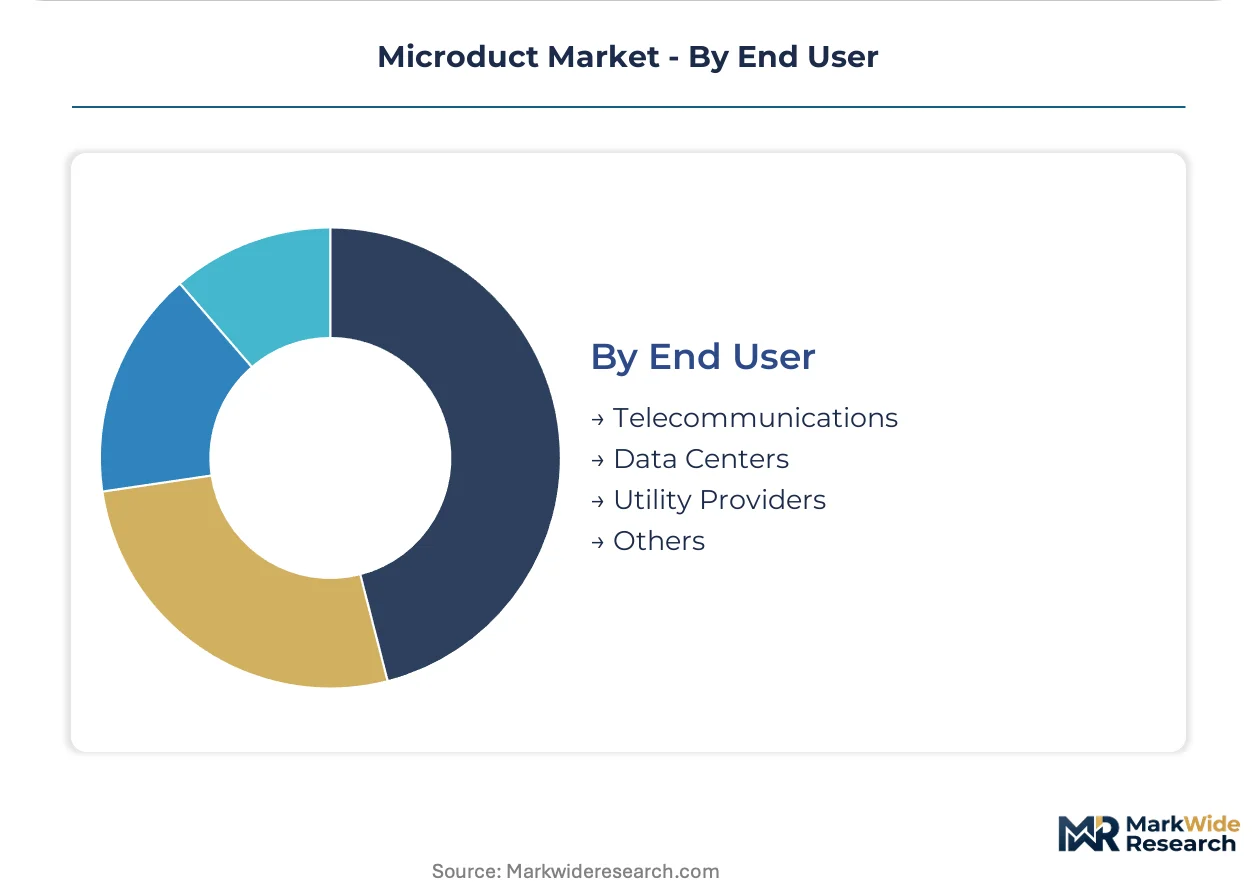
Margin structure varies sharply across customer categories, with utility providers demanding multi-wall crush resistance and data centers prioritizing flame-rated indoor formulations.
- Telecommunications:Fiber-to-the-home and 5G fronthaul deployments drive volume for both aerial and underground configurations. Subsidy eligibility rules in the US and EU Green Deal targets are concentrating procurement specifications among national operators with in-house engineering capabilities.
- Data Centers:Hyperscale and colocation facilities require plenum-rated, low-smoke formulations for intra-building and campus interconnect. REACH restrictions on halogenated flame retardants are forcing compound reformulation for European facility deployments.
- Utility Providers:Power grid operators bundle fiber for smart grid communications within single-trench power infrastructure. German distribution system operators are leading specification development for crush-resistant multi-wall configurations.
- Others:Transportation, defense, and enterprise campus networks with specialized pathway or security requirements.
Telecommunications absorbs the dominant share of volume; utility providers are expanding most quickly as smart grid fiber integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Germany and the United States while deployment demand spreads across subsidy-driven rural corridors and urban densification zones. This production-consumption divide shapes logistics costs and specification transfer between compounders and field operators.
United States
FCC Broadband Equity Access Deployment programs are pulling microduct volumes into underserved census tracts across rural utility corridors. Federal subsidy eligibility rules mandate fiber-deep infrastructure specifications that exceed legacy copper replacement standards. Deployment clusters concentrate in Texas and the Southeast where favorable soil conditions support direct burial methods.
Germany
Utility-grade smart grid integration projects are absorbing multi-wall crush-resistant configurations for power-fiber co-location trenches. EU Green Deal digital infrastructure targets and REACH material compliance standards shape procurement specifications for recycled-content HDPE formulations. Industrial concentration centers on North Rhine-Westphalia where distribution system operators lead specification development.
India
BharatNet Phase III rural broadband saturation targets are creating demand for aerial microduct systems in Himalayan and Northeastern terrain. TRAI infrastructure sharing mandates and CEA power sector integration guidelines enable fiber bundling with existing utility corridors. Deployment activity concentrates in Maharashtra and Gujarat where state-level digital infrastructure programs accelerate procurement.
China
Dual carbon goals and MIIT broadband infrastructure targets are driving demand for low-friction blown-fiber configurations in metropolitan ring networks. GB standards for plastic conduit materials and NMPA-equivalent certification requirements for utility applications shape import substitution dynamics. Manufacturing clusters in the Yangtze River Delta supply domestic operators while serving export markets.
Sweden
Nordic climate extremes are driving specification demand for specialized aerial microduct systems with enhanced temperature cycling resistance. ECHA substance restrictions on halogenated flame retardants are accelerating bio-based polymer formulation adoption among compounders. Deployment expertise concentrates around Stockholm and Gothenburg where blown-fiber technician training pipelines originated.
Microduct Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the microduct value chain. Tier-one telecom operators concentrate procurement power through direct manufacturer relationships that bypass traditional distribution channels. Three strategic archetypes dominate: large-scale extruders with polymer compounding integration, climate-specialized system designers, and pre-integrated bundle suppliers. Competitive moves center on backward integration into optical-grade resin formulation and direct contracting channels that capture specification control.
Within the integrated manufacturing tier, Dura-Line and Sterlite Technologies Limited exemplify scale-driven compounder-converter models. Hexatronic Group AB occupies a specialist position anchored in Nordic climate engineering capabilities. Emtelle Holdings Ltd and Clearfield Inc. represent the pre-integrated bundle channel that is displacing catalog distribution in subsidy-driven deployments.
| Leading Market Players |
|---|
| Dura-Line |
| Datwyler IT Infra. |
| Emtelle Holdings Ltd |
| Sterlite Technologies Limited |
| Egeplast International GmbH |
| Hexatronic Group AB |
| Clearfield Inc. |
| Sumitomo Electric Industries Ltd |
| Prysmian Group |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon-neutral network construction mandates gate qualified supply and premium-tier pricing access by disqualifying non-compliant compounders from German utility procurement channels. REACH-certified recycled-content HDPE formulations command margin premiums while conventional virgin resin suppliers face volume displacement in subsidy-driven deployments.
Pricing Analysis
Margin tightening in multi-wall utility-grade configurations reflects polymer feedstock volatility compressing converter margins on fixed-price municipal contracts. Three-tier pricing structure across REACH-compliant premium, standard virgin HDPE, and economy-grade recycled formulations differentiates by certification level and crush-test performance. Cost-down pressure on aerial microducts accelerates because BharatNet Phase III procurement favors lowest-qualified-bidder awards. Regional telecom operators exhibit highest price sensitivity; German distribution system operators prioritize specification compliance over unit cost.
Supply Chain Analysis
Freight cost differentials between Yangtze River Delta manufacturing clusters and European deployment corridors favor regional compounding investments near North Rhine-Westphalia demand centers. Supply concentrates in China, Germany, and the United States for optical-grade HDPE resin extrusion. Raw material dependencies rest on ethylene cracking margins, silicon lubricant additives, and recycled polymer feedstock streams. Single-source vulnerability in halogenated flame retardant alternatives creates reformulation bottlenecks under ECHA restrictions. Distribution runs through direct manufacturer-telecom operator relationships bypassing traditional catalog channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified polymer compounding capacity constraints prop pricing power for REACH-certified suppliers serving German smart grid integration projects. Backward integration into optical-grade resin formulation represents the critical bottleneck constraining volume expansion.
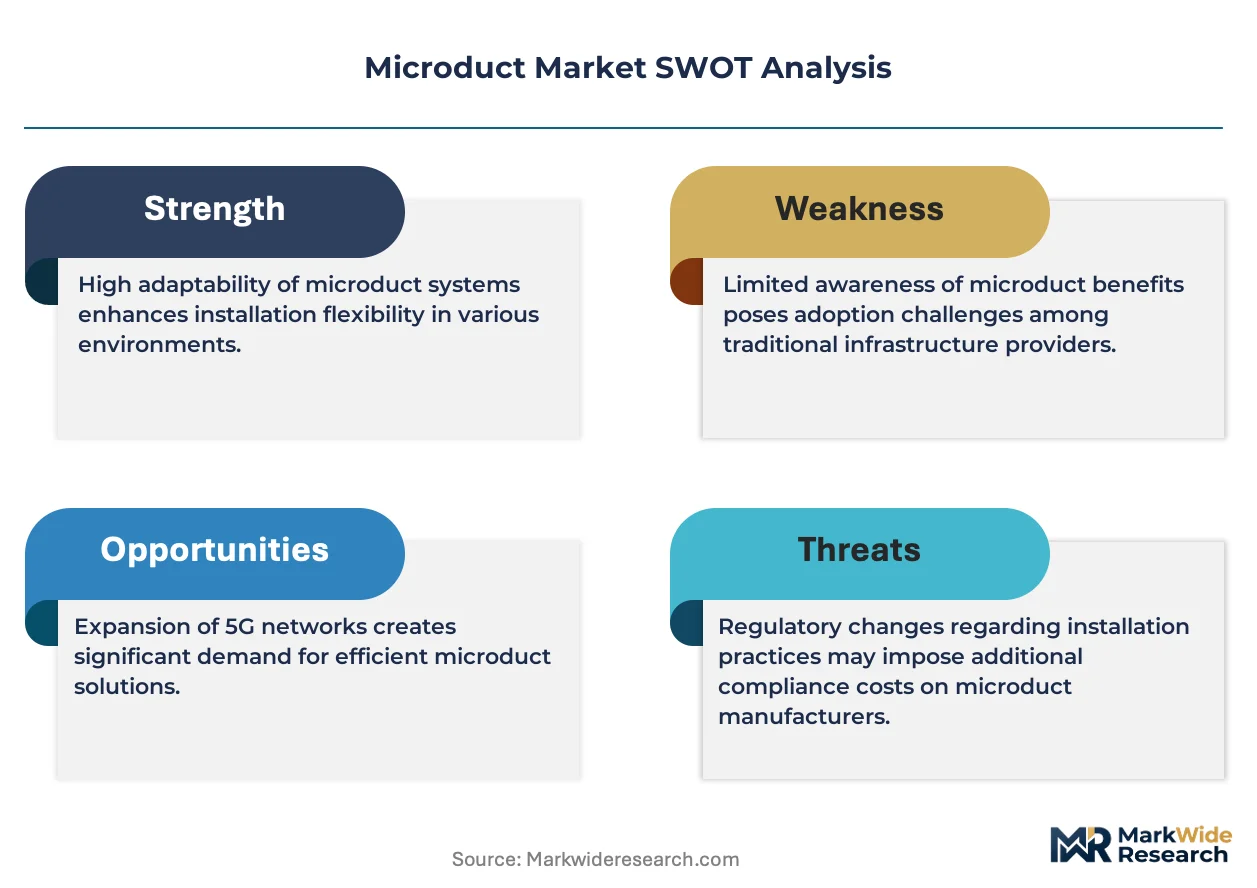
For Market Incumbents: Hedge against ECHA substance restriction expansions by accelerating bio-based polymer R&D pipelines and securing alternative flame retardant certifications before derogation deadlines. Capture specification control through direct contracting with national telecom operators, displacing distribution intermediaries in subsidy-driven rural broadband programs. Prioritize crush-test protocol pre-certification for multi-wall utility configurations. For New Entrants and Emerging Players: Begin with aerial microduct specialization for Himalayan and Northeastern Indian terrain where trenching economics favor messenger-supported installations over direct burial. Target state-level digital infrastructure programs in Maharashtra and Gujarat with localized technical service capabilities. Establish blown-fiber technician training partnerships with Nordic engineering institutes to differentiate deployment support. For Investors and Strategic Acquirers: German distribution system operator multi-wall specification adoption is the leading indicator that utility-grade fiber-power co-location demand will sustain premium pricing tiers. Five-to-ten year viability hinges on compounders with captive recycled-content HDPE supply and REACH compliance infrastructure. Acquisition target archetype: mid-scale extruders with polymer compounding integration and utility-sector certification track records. Monitor ECHA restriction expansion timelines as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive optical-grade HDPE supply secures margin and REACH compliance for German utility deployments. |
| REACH-Certified Recycled Content Formulation | EU Green Deal eligibility unlocks subsidy-driven procurement channels across European fiber infrastructure. |
| Direct Telecom Operator Contracting | Bypassing distribution intermediaries captures specification control in FCC Broadband Equity programs. |
| Blown-Fiber Technician Training Programs | Nordic-origin expertise scarcity creates service differentiation for speed-optimized metropolitan deployments. |
| Multi-Wall Crush-Resistance Certification | Utility-specific protocols enable power-fiber co-location in German smart grid integration trenches. |
Study Parameters
Independent corroboration across compounder production data, telecom operator procurement disclosures, and ECHA regulatory filings underwrites the qualitative findings presented. Primary interviews with polymer extrusion plant managers, telecom network engineering directors, utility procurement leads, and blown-fiber installation contractors combined with secondary validation from customs trade records, SEC 10-K filings, and EU infrastructure funding databases. Bottom-up volume estimates triangulate against top-down subsidy allocation trajectories.
Comparable-period anchoring to historical FCC broadband subsidy disbursement cycles and EU Green Deal implementation timelines structured the forecast window. Segmentation modeling spans product architecture, installation method constraints, technology preferences, and end-use performance requirements across the projection horizon. CAGRs derive from installation velocity assumptions tied to subsidy eligibility rules and polymer feedstock price trajectory scenarios. Industry-specific inputs include ethylene cracking margin forecasts and ECHA restriction implementation schedules.
Underlying measurement precision varies by segment; blown-fiber technology adoption rates and German utility procurement volumes carry tighter precision than emerging market aerial deployment estimates. Forecasts reflect assumptions about subsidy program continuity, regulatory restriction timelines, and polymer feedstock price stability. Stakeholders should weight assumptions against their own operating context and monitor ECHA expansion proposals for revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Cloud Gateway Module Market
Network Technology
Protocol Analyzer Market
Network Technology
US Private 5G Network Market
Network Technology
ISP Management Systems Market
Network Technology
Network Equipment Market
Network Technology
North America Enterprise WLAN Market
Network Technology
Hyperconnectivity Market
Network Technology
Router and Switch Market
Network Technology
IT Connector Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
CPE Router Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Industrial Ethernet Market