
 5G Core Market | 2026-2036
5G Core Market Size, Share, and Industry Trends Forecast 2026-2036
5G Core Market Intelligence
The telecom vendor channel is fragmenting as cloud-native software displaces traditional hardware-centric procurement. Nokia Corporation leverages its end-to-end portfolio to anchor large-scale operator contracts across Europe. Huawei Technologies Co. Ltd. competes aggressively on price-performance in emerging markets despite supply constraints. Samsung Electronics Co. Ltd. specializes in vRAN-to-core integration for Tier-1 providers seeking open architectures.
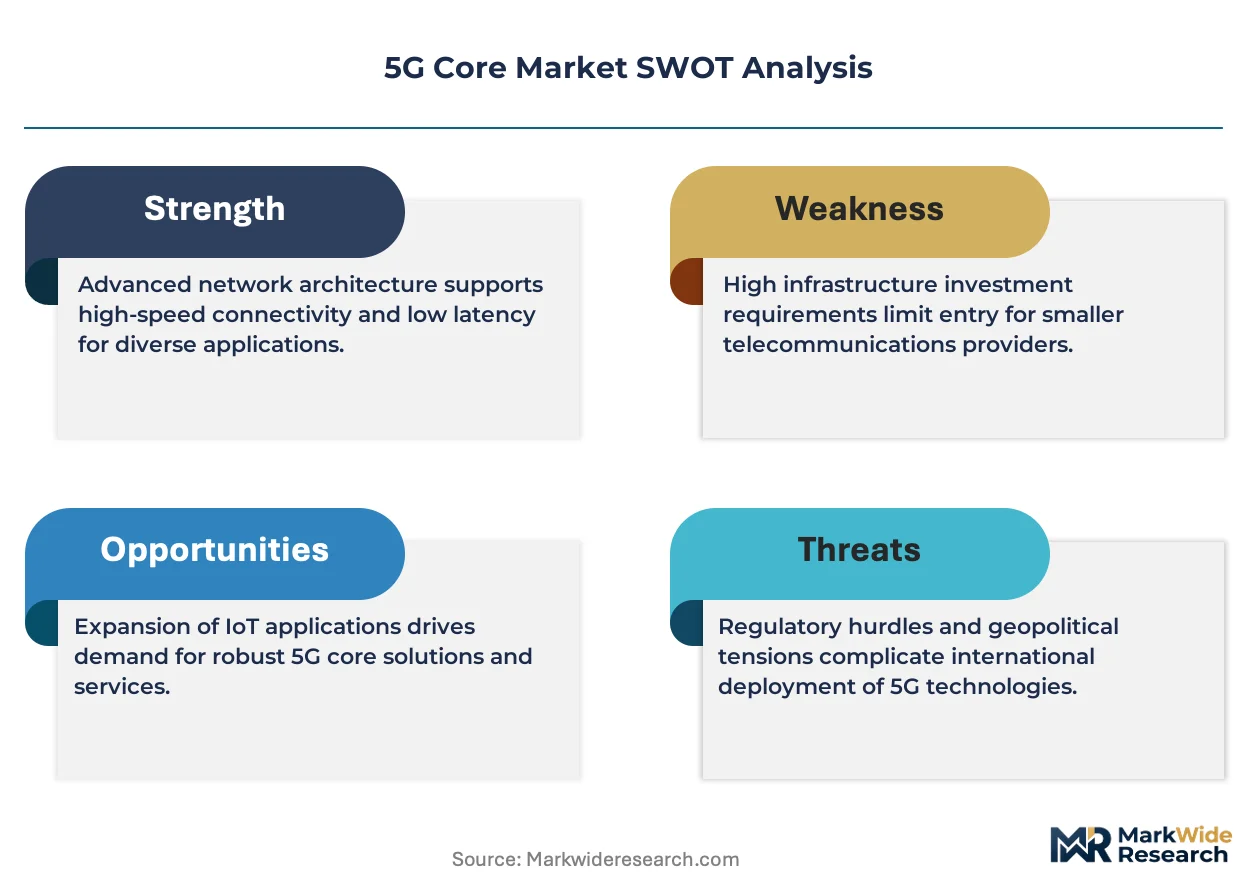
The 5G Core constitutes the centralized control plane of fifth-generation mobile networks, orchestrating session management, subscriber authentication, and network slicing through service-based architectures interfacing with AMF, SMF, and UPF network functions. Its primary purpose is to enable dynamic resource allocation supporting latency-sensitive industrial automation and massive IoT density. Cloud-native deployment leads solution uptake as operators virtualize infrastructure to reduce capex cycles and accelerate feature velocity. Network slicing commands premium positioning among solution types by guaranteeing quality-of-service isolation for enterprise private networks and ultra-reliable low-latency applications. Private networks represent the fastest-expanding use case as manufacturing, logistics, and energy buyers bypass public infrastructure for sovereign control.
ETSI NFV standards and 3GPP Release 17 specifications shape product interoperability mandates across European deployments, while FCC Part 96 rules govern Citizens Broadband Radio Service spectrum access that underpins private 5G core buildouts in the United States. The EU Cybersecurity Act and NIS2 Directive impose certification and incident-reporting burdens that filter vendor eligibility and elevate compliance costs for non-European suppliers. Stakeholders must monitor Open RAN policy shifts and sovereign cloud requirements as procurement criteria harden around supply-chain provenance and interface openness.
Market Dynamics
Cloud-native containerization is fragmenting vendor power in the 5G Core market as operators decouple software from proprietary hardware stacks, forcing incumbents to restructure pricing models around recurring subscriptions rather than perpetual licenses.
Growth Catalysts
- Network Slicing Mandates:ETSI NFV standards compel European operators to deploy service-based architectures that isolate latency-critical traffic for industrial automation clients.
- Private Spectrum Allocation:FCC Part 96 rules in the United States unlock Citizens Broadband Radio Service bands for manufacturing facilities seeking sovereign 5G infrastructure control.
- Container Orchestration Maturation:Kubernetes-based deployment frameworks slash operator capex cycles by automating elastic scaling of AMF, SMF, and UPF network functions.
Market Restraints
- Silicon Supply Concentration:Advanced FPGA and DPU sourcing bottlenecks from Taiwan-based foundries constrain core infrastructure buildout timelines for Tier-2 operators.
- Interoperability Certification Costs:3GPP Release 17 compliance testing imposes six-figure validation burdens per vendor platform, filtering smaller software entrants from procurement shortlists.
- Legacy SS7 Integration Complexity:Existing 4G EPC investments in signaling gateways resist seamless migration to HTTP/2 service-based interfaces, prolonging hybrid operation costs.
Strategic Opportunities
- Industrial Private Networks:German automotive clusters in Baden-Württemberg are procuring standalone 5G cores for robotic assembly line synchronization, bypassing public carrier infrastructure.
- Open RAN-Core Convergence:O-RAN Alliance specifications for open fronthaul interfaces are hybridizing with cloud-native core deployments, creating integrated procurement bundles for greenfield operators.
- Sovereign Cloud Incentives:EU Cybersecurity Act certification requirements for critical infrastructure are elevating European-headquartered core vendors in public-sector tenders.
Industry Challenges
- Cloud-Native Talent Scarcity:Container orchestration and microservices architecture expertise remains concentrated among Silicon Valley and Bangalore engineering pools, inflating implementation costs for operators in secondary markets.
- Multi-Vendor Integration Friction:Disaggregated procurement of AMF, SMF, and UPF functions from separate suppliers introduces service-mesh configuration failures that degrade session reliability.
- Security Patch Velocity:Continuous deployment pipelines for containerized network functions expose operators to CVE disclosure windows that outstrip traditional telecom change-management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Core Market |
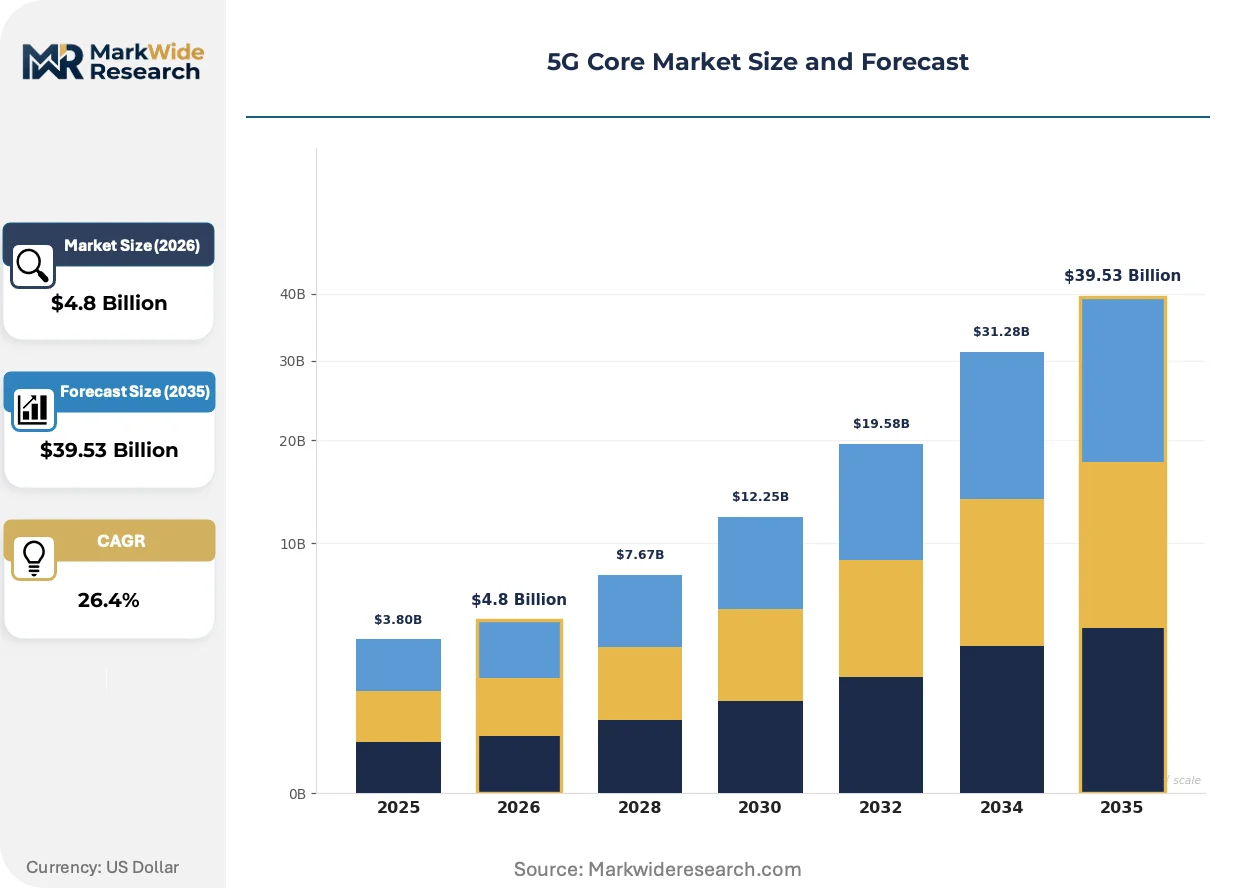
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $39.53 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Native, Virtualized, On-Premise, Hybrid, Edge-Based Solution Type: Network Slicing, Policy Control, Subscriber Data Management, Session Management, Analytics Use Case: Enhanced Mobile Broadband, Massive IoT, Ultra-Reliable Low Latency, Fixed Wireless Access, Private Networks End User Segment: Mobile Network Operators, Tier-1 Providers, System Integrators, Managed Service Providers, Enterprises |
| Companies Covered | Nokia Corporation, Telefonaktiebolaget LM Ericsson, Huawei Technologies Co. Ltd., ZTE Corporation, Samsung Electronics Co. Ltd., Cisco Systems Inc., NEC Corporation, Mavenir Systems Inc., Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Core Market Strategic Shifts & Innovations
Service-based architectures are compressing feature deployment cycles from quarters to weeks, while regulatory pressure on supply-chain provenance is hardening procurement criteria around interface openness and geographic vendor eligibility.
Cloud-native network functions are hybridizing control plane operations through Kubernetes-orchestrated microservices that replace monolithic EPC software. Manufacturing operators in the Ruhr industrial corridor are adopting these containerized cores for sub-10 millisecond latency guarantees. This architectural shift is compressing incumbent hardware attach rates as software-only vendors capture standalone core contracts.
EU NIS2 Directive incident-reporting mandates are compelling core vendors to embed automated threat-detection telemetry directly into SMF and AMF network functions. Industrial consequences include mandatory 24-hour breach notification workflows that reshape operational expenditure structures. Private network deployments in German chemical processing facilities are most affected, with operators pre-qualifying only vendors holding EU Cybersecurity Act certification.
Subscription-based core licensing is displacing perpetual purchase agreements as mobile network operators prioritize opex predictability over upfront capital deployment. Traditional systems integrators are losing attach revenue to vendor-direct SaaS models. This transition is most visible among North American Tier-1 carriers restructuring vendor relationships around throughput-tiered annual contracts.
5G Core Market Segmentation
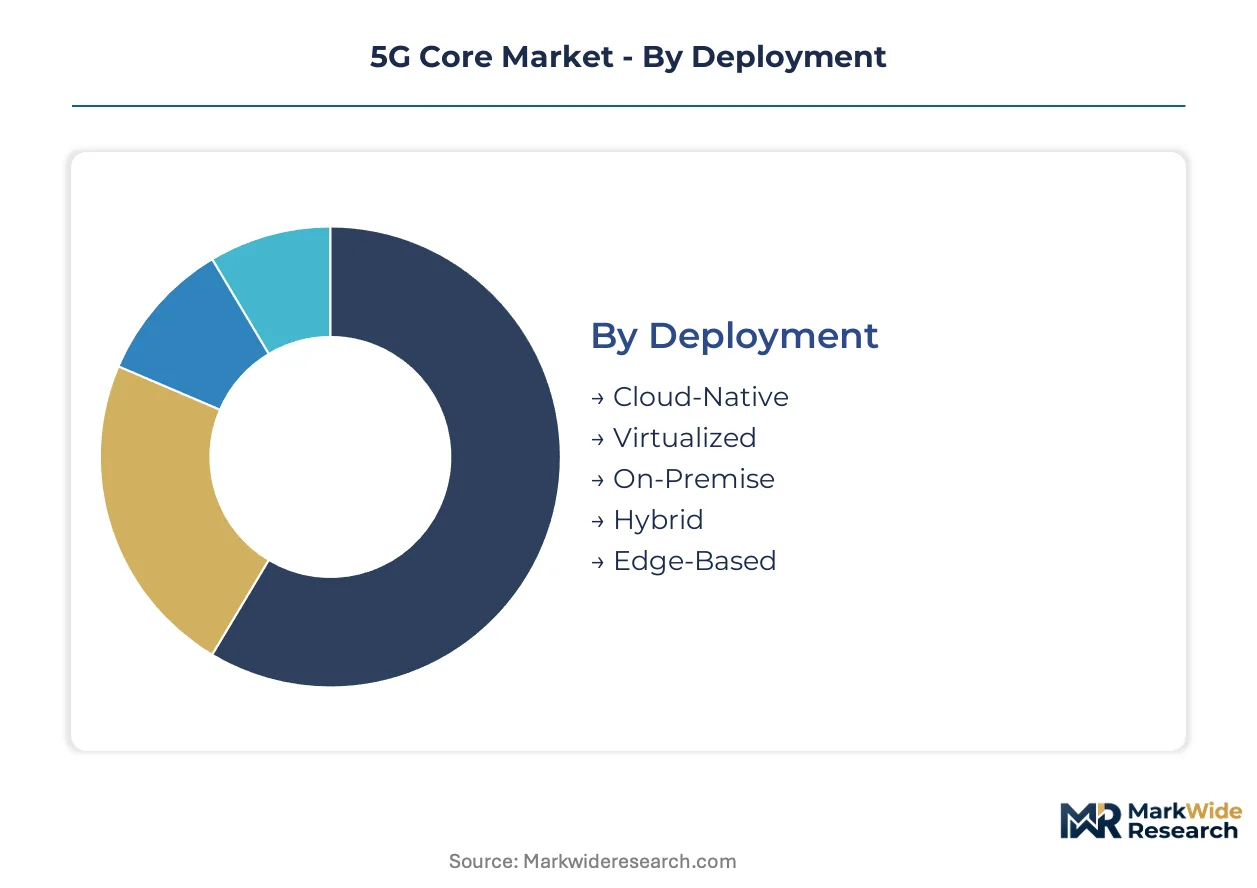
5G core procurement patterns diverge sharply across deployment architectures and buyer sophistication levels. Operators weigh capex flexibility against latency sovereignty when selecting solution configurations. Segmentation reveals how cloud-native abstraction is redrawing traditional vendor boundaries.
Deployment:
Mature virtualization stacks now compete with emerging edge-distributed architectures for operator preference.
- Cloud-Native:Kubernetes-orchestrated microservices enable elastic scaling of AMF, SMF, and UPF functions through containerized network function packages. German automotive manufacturers in Stuttgart and Wolfsburg are mandating this architecture for sub-10 millisecond robotic synchronization requirements.
- Virtualized:NFV-based deployments abstract network functions from proprietary hardware using commercial off-the-shelf servers, preserving existing operator infrastructure investments while enabling software upgrade paths. Tier-2 carriers in Eastern Europe favor this intermediate step given constrained capex cycles.
- On-Premise:Dedicated hardware stacks deliver deterministic performance for classified government networks.
- Hybrid:Split control-user plane architectures let operators anchor sensitive functions locally while bursting capacity to public cloud.
- Edge-Based:Distributed core instances positioned at baseband hotel sites minimize transport latency for industrial automation.
Cloud-Native retains volume leadership; Edge-Based holds the steepest expansion curve.
Solution Type:
Cost tier differentiation separates premium orchestration capabilities from commoditized data plane functions.
- Network Slicing:Service-based architecture isolation mechanisms guarantee quality-of-service boundaries for concurrent enterprise tenants sharing physical infrastructure. South Korean smart factory deployments require this capability for coexisting AR maintenance and safety-critical control traffic.
- Policy Control:Real-time charging and traffic steering rules enforce subscriber-tier service differentiation.
- Subscriber Data Management:Unified data repositories consolidate authentication states across roaming footprints.
- Session Management:SMF functions handle IP address allocation and tunnel management for user plane paths.
- Analytics:AI-driven telemetry extraction from control plane traffic enables predictive congestion management.
Network Slicing commands premium pricing; Analytics is gaining share fastest as operators monetize telemetry.
Use Case:
Application criticality determines whether buyers accept public infrastructure dependency or demand sovereign control.
- Enhanced Mobile Broadband:Consumer video streaming and enterprise VPN aggregation over standard priority bearers. Japanese urban corridors deploy this for stadium and transit hub capacity surges.
- Massive IoT:Narrowband signaling optimization for sensor density exceeding thousands per square kilometer.
- Ultra-Reliable Low Latency:Deterministic transport for remote surgery and autonomous vehicle coordination.
- Fixed Wireless Access:Residential broadband substitution using CPE terminals in fiber-unserved exurbs.
- Private Networks:Standalone cores for manufacturing, mining, and energy facilities requiring absolute spectrum and routing control.
Enhanced Mobile Broadband sustains subscriber volume; Private Networks shows the steepest expansion trajectory.
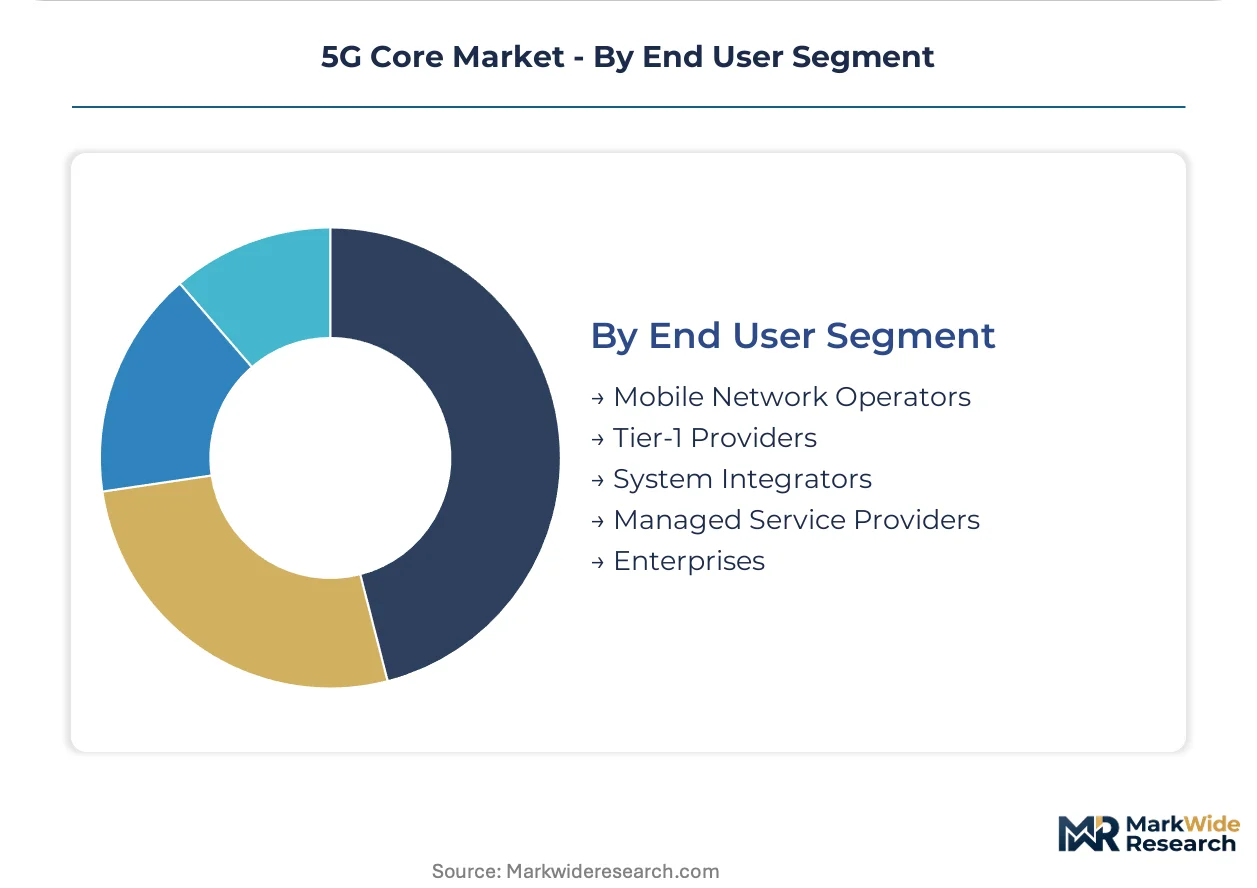
End User Segment:
Customer type dictates procurement complexity tolerance and integration support requirements.
- Mobile Network Operators:Full-stack buyers seeking vendor consolidation across radio, transport, and core layers. Verizon and Deutsche Telekom exemplify this profile with multi-year framework agreements.
- Tier-1 Providers:Wholesale capacity resellers requiring interoperable roaming interfaces.
- System Integrators:Services-heavy procurement for custom enterprise vertical deployments.
- Managed Service Providers:Outsourced network operations for spectrum-light virtual operators.
- Enterprises:Direct core purchases by logistics and energy firms bypassing carrier intermediation.
Mobile Network Operators dominate current procurement; Enterprises are climbing the fastest as private spectrum allocations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial buyers command 40% pricing premiums over equivalent deployments in India, reflecting divergent regulatory burdens and labor arbitrage in systems integration.
United States
Verizon and AT&T are accelerating cloud-native core migrations under FCC Part 96 spectrum rules for private network buildouts. The Citizens Broadband Radio Service framework unlocks 150 MHz of mid-band spectrum for manufacturing facilities. Automotive plants in Detroit and South Carolina are procuring standalone cores for robotic assembly synchronization.
Germany
Industrial private networks in Baden-Württemberg and North Rhine-Westphalia drive carrier-grade core investments for sub-10 millisecond latency guarantees. The EU Cybersecurity Act and NIS2 Directive impose mandatory 24-hour breach notification workflows that reshape vendor qualification. BMW and Siemens facilities in Munich and Wolfsburg mandate ETSI NFV-compliant architectures.
China
MIIT spectrum allocations for 5G-Advanced are propelling standalone core deployments across smart manufacturing zones. National data localization requirements under the Cybersecurity Law compel on-premise control plane anchoring. Shenzhen and Shanghai industrial parks are integrating private cores with municipal IoT infrastructure.
South Korea
Smart factory deployments in Gyeonggi Province require network slicing capabilities for coexisting AR maintenance and safety-critical control traffic. MSIT spectrum policy prioritizes enterprise private networks over public capacity expansion. Samsung and Hyundai facilities in Suwon and Ulsan are deploying integrated vRAN-to-core solutions.
Japan
NTT Docomo and KDDI are virtualizing core functions under METI industrial digitalization mandates for Society 5.0 targets. The Telecommunications Business Act amendments strengthen data sovereignty requirements for critical infrastructure. Toyota production facilities in Aichi Prefecture are testing edge-distributed core instances for autonomous logistics coordination.
5G Core Market Key Industry Players
End-to-end systems integrators and cloud-native software specialists split the market between consolidated operator contracts and disaggregated enterprise deployments. Incumbent telecom infrastructure vendors retain anchor positions with Tier-1 mobile network operators through multi-year framework agreements. Open-source contributors and container-native entrants are capturing standalone core contracts from manufacturing buyers bypassing traditional carrier intermediation. Competitive moves concentrate on Kubernetes orchestration partnerships and sovereign cloud certification acquisitions.
Within the European-headquartered tier, Nokia Corporation and Telefonaktiebolaget LM Ericsson exemplify end-to-end portfolio strategies that anchor large-scale operator relationships. Among Asia-Pacific-based vendors, Huawei Technologies Co. Ltd. occupies a position shaped by price-performance positioning in emerging markets despite supply constraints. Samsung Electronics Co. Ltd. represents the vRAN-to-core integration archetype for Tier-1 providers pursuing open architectures.
| Leading Market Players |
|---|
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Huawei Technologies Co. Ltd. |
| ZTE Corporation |
| Samsung Electronics Co. Ltd. |
| Cisco Systems Inc. |
| NEC Corporation |
| Mavenir Systems Inc. |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
The Kaohsiung-to-Los Angeles transpacific corridor drives freight cost volatility that amplifies pricing spreads between customized cloud-native core deployments and standard virtualized packages, while silicon sourcing bottlenecks from Taiwan-based foundries compress margins for Tier-2 operators unable to absorb logistics premiums.
Pricing Analysis
The customization-premium spread separates configured-to-order cloud-native cores from standard virtualized deployments by a substantial margin gap. Subscription-based SaaS-tiered licensing dominates as operators prioritize opex predictability over perpetual licenses. Price differentiation rests on EU Cybersecurity Act certification grade and volume throughput scale, with certified vendors commanding substantial premiums. Cost compression in the standard tier is intensifying because container-native entrants are undercutting incumbent hardware bundles. Tier-2 carriers in Eastern Europe exhibit highest price sensitivity, while German automotive manufacturers demonstrate lowest sensitivity due to latency sovereignty requirements.
Supply Chain Analysis
Contract-manufacturing concentration centers on Taiwan Semiconductor Manufacturing Company and Samsung Foundry for advanced FPGA and DPU fabrication, with Foxconn and Jabil handling systems integration. Geographic supply concentrates in Taiwan, South Korea, and the United States for critical silicon. Raw material dependencies draw from advanced node wafers, high-bandwidth memory modules, and specialized cooling substrates. Single-source vulnerability from Taiwan-based foundries poses structural risk given geopolitical exposure. Distribution runs through vendor-direct SaaS platforms and systems integrator channels for enterprise private networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native containerization is disrupting vendor power structures as Kubernetes-orchestrated deployments fragment procurement patterns, with FCC Part 96 spectrum rules accelerating private network buildouts that bypass traditional carrier intermediation.
For Market Incumbents: Harden subscription revenue streams by embedding automated threat-detection telemetry directly into SMF and AMF network functions to meet EU NIS2 Directive mandates. Consolidate Kubernetes orchestration partnerships to defend against container-native entrants capturing standalone core contracts. Invest in EU Cybersecurity Act certification to maintain eligibility for German public-sector tenders.
For New Entrants and Emerging Players: Eastern European Tier-2 carriers represent underpenetrated whitespace where constrained capex cycles favor virtualized intermediate deployments over full cloud-native migration. Target manufacturing facilities in the Ruhr industrial corridor seeking sovereign control through private spectrum allocations. Pursue vendor-direct SaaS models that displace systems integrator attach revenue.
For Investors and Strategic Acquirers: Container-native software specialists with Kubernetes orchestration expertise present acquisition targets as manufacturing buyers bypass traditional carrier intermediation. Long-term viability favors vendors with sovereign cloud certification and open RAN integration capabilities. Monitor Open RAN policy shifts as the signal to watch for procurement criteria hardening around interface openness.
| Strategic Initiative | Industry Significance |
|---|---|
| Kubernetes Orchestration Partnership | Container-native deployment frameworks slash operator capex cycles through automated elastic scaling. |
| EU Cybersecurity Act Certification | Mandatory certification elevates European-headquartered vendors in German public-sector tenders. |
| Private Network Vertical Integration | Standalone core deployments for manufacturing facilities bypass public carrier infrastructure dependency. |
| Open RAN-Core Convergence | O-RAN Alliance specifications hybridize with cloud-native deployments for greenfield operators. |
| Subscription Licensing Transition | Throughput-tiered annual contracts displace perpetual licenses among North American Tier-1 carriers. |
Research Approach
The analysis maps cloud-native, virtualized, edge-based, and hybrid deployment architectures, each validated through chief technology officers, network planning executives, and procurement leads at mobile network operators and manufacturing enterprises. Primary interviews with container orchestration specialists and systems integration directors combined with secondary validation from 3GPP Release 17 specifications, ETSI NFV standards documentation, FCC Part 96 rulemakings, and SEC filings from publicly traded telecom infrastructure vendors. Bottom-up deployment volume estimates triangulate against top-down spectrum allocation data and capex disclosure trends.
The assumption-set holds FCC spectrum allocation timelines and EU Cybersecurity Act certification requirements fixed while varying private network adoption rates and container orchestration maturation curves across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type, use case criticality, and end-user sophistication tier. CAGRs derive from elasticity-adjusted adoption curves incorporating industrial automation latency requirements and sovereign cloud procurement mandates. Forecast inputs include German automotive cluster investment patterns and North American CBRS spectrum utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive SaaS pricing moves by container-native entrants would shift outcomes substantially. Quarterly review of Open RAN policy developments and sovereign cloud certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Ireland Telecom Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Costa Rica Telecom Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Fixed Voice Market
Telecommunications
Diameter Signaling Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
United Arab Emirates Telecom Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
Indonesia Telecom Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Switzerland Telecom Market