
 Industrial Wireline Networking Market | 2026-2036
Industrial Wireline Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wireline Networking Market Outlook
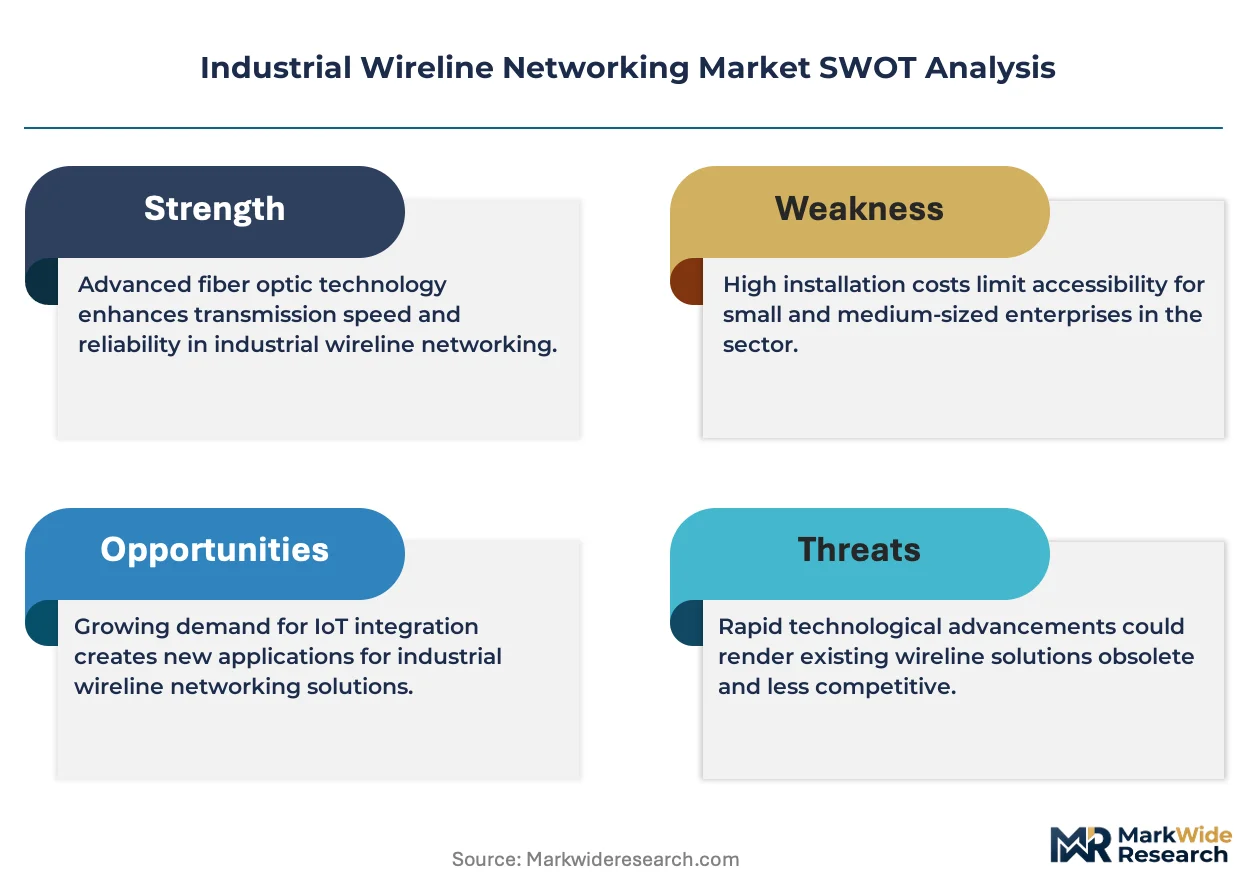
The EU Green Deal's industrial decarbonization mandates is broadening the addressable market for deterministic wireline infrastructure in European process industries. Cisco Systems leverages its industrial Ethernet switch portfolio to anchor automation backbones across automotive and chemical plants. Siemens sustains technology leadership through its proprietary PROFINET ecosystem and integrated TSN capabilities. Belden Inc. specializes in ruggedized cabling and connectivity systems that withstand extreme temperatures in oil field environments.
Industrial wireline networking encompasses the physical layer and protocol infrastructure that transmits data between machines, controllers, and enterprise systems in harsh operational environments, typically employing shielded twisted-pair copper, fiber optic strands, or coaxial media rated for electromagnetic interference immunity and temperature extremes spanning minus forty to plus seventy-five degrees Celsius. Ethernet dominates new installation spend as Time-Sensitive Networking standards mature, while fiber optic segments capture premium value in long-haul underground mining and subsea oil platform applications where copper attenuation proves prohibitive. Manufacturing applications absorb the largest deployment volume, though utilities represent the fastest structural expansion as grid modernization mandates proliferate across jurisdictions.
The US Occupational Safety and Health Administration and the Federal Communications Commission jointly shape equipment certification requirements for industrial networking gear deployed in hazardous locations and licensed spectrum environments. European manufacturers must additionally satisfy CE marking under the Machinery Directive and electromagnetic compatibility frameworks administered by national market surveillance authorities. Stakeholders must monitor evolving TSN interoperability certification programs and determine whether single-vendor protocol stacks or open-standard architectures better align with their operational technology refresh timelines.
Market Dynamics
Time-Sensitive Networking protocol maturation is compressing refresh cycles across automotive and chemical manufacturing floors, forcing deterministic Ethernet into positions previously held by proprietary fieldbus systems.
Growth Catalysts
- EU Green Deal industrial efficiency mandates:European process industries face binding decarbonization targets that require real-time energy monitoring through deterministic wireline backbones.
- Automotive smart manufacturing adoption:Assembly lines in Germany's Ruhr corridor are replacing legacy Profibus installations with Ethernet-APL infrastructure to support higher device density.
- TSN interoperability certification programs:IEC/IEEE 60802 conformance testing is reducing buyer risk aversion and accelerating procurement of multi-vendor network architectures.
Market Restraints
- Copper commodity price volatility:Shielded twisted-pair cabling remains cost-sensitive to London Metal Exchange copper fluctuations, squeezing margin on mid-tier switch portfolios.
- Fiber optic supply concentration:Subsea and long-haul mining applications depend on specialty fiber draw towers concentrated in China and the United States, creating geographic single-source exposure.
- Legacy protocol lock-in:Siemens PROFINET and Rockwell EtherNet/IP installed bases create switching friction that delays open-standard TSN adoption in brownfield facilities.
Strategic Opportunities
- Grid modernization mandates:US FERC Order 2222 and state-level renewable integration rules are expanding utility demand for substation-hardened Ethernet switches.
- Ethernet-APL convergence:Single-pair Ethernet physical layer integration with intrinsic safety barriers opens process industries previously blocked by power and hazardous location constraints.
- Channel disintermediation through direct industrial distributor partnerships:Bypassing traditional IT value-added resellers to capture margin in MRO replacement cycles.
Industry Challenges
- OT-IT skill convergence gap:Plant engineers lack TCP/IP stack expertise while IT staff misunderstand deterministic latency requirements, complicating unified network operations.
- Hazardous location certification timelines:ATEX/IECEx flameproof and increased safety testing for Ethernet equipment extends product launch cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wireline Networking Market |
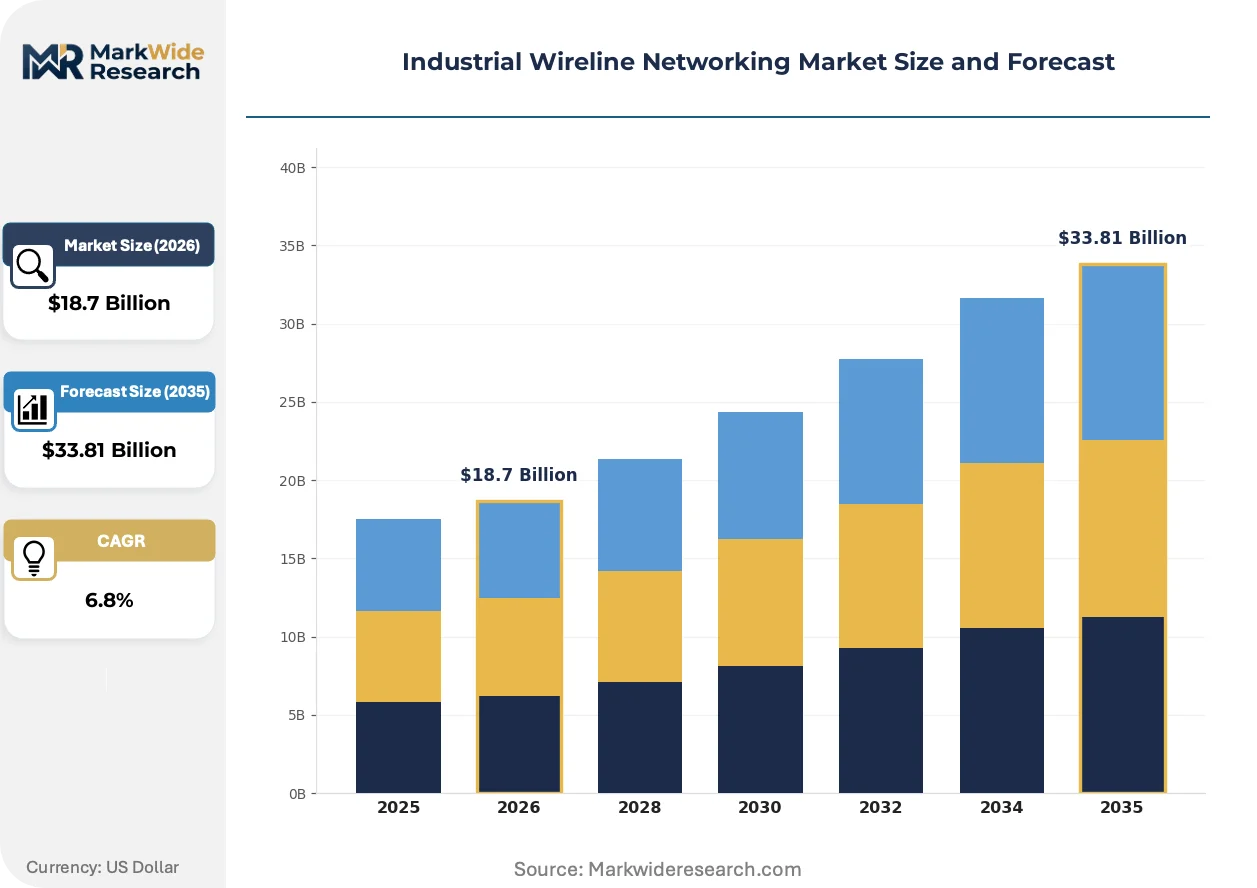
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ethernet, DSL, Fiber Optic, Coaxial Application: Manufacturing, Oil & Gas, Mining, Utilities End User: Industrial Plants, Data Centers, Telecommunications, Energy Providers Deployment: On-Premises, Cloud, Hybrid, Remote |
| Companies Covered | Cisco Systems, Siemens, Schneider Electric, Rockwell Automation, Huawei Technologies, Belden Inc., ABB, Moxa Inc., OMRON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wireline Networking Market Strategic Shifts
Ethernet-APL physical layer specifications are dissolving the final barriers between process automation and discrete manufacturing network architectures.
Single-pair Ethernet with advanced physical layer signaling is overtaking traditional four-pair infrastructure in process industries. Chemical plants and oil refineries are adopting Ethernet-APL for its kilometer-range reach and power delivery over single twisted-pair cables. This technology is overtaking Foundation Fieldbus and Profibus PA in greenfield installations by eliminating separate power trunk requirements.
The EU Green Deal's F-Gas Regulation and industrial emissions trading scheme are mandating continuous emissions monitoring with sub-second data granularity. European chemical manufacturers must deploy deterministic networks to link analyzer systems with control rooms. Germany's national implementation of the Industrial Emissions Directive is driving the fastest regulatory-compliant switch procurement in the Rhine-Neckar chemical cluster.
Buyer preference for certified interoperability over single-vendor stacks is fragmenting procurement authority. Automotive OEMs now require TSN conformance certificates before qualifying switch vendors, displacing informal compatibility claims. This pattern is most visible in Stuttgart's supplier ecosystem, where tier-one parts manufacturers audit network component traceability down to the semiconductor level.
Industrial Wireline Networking Market Segmentation
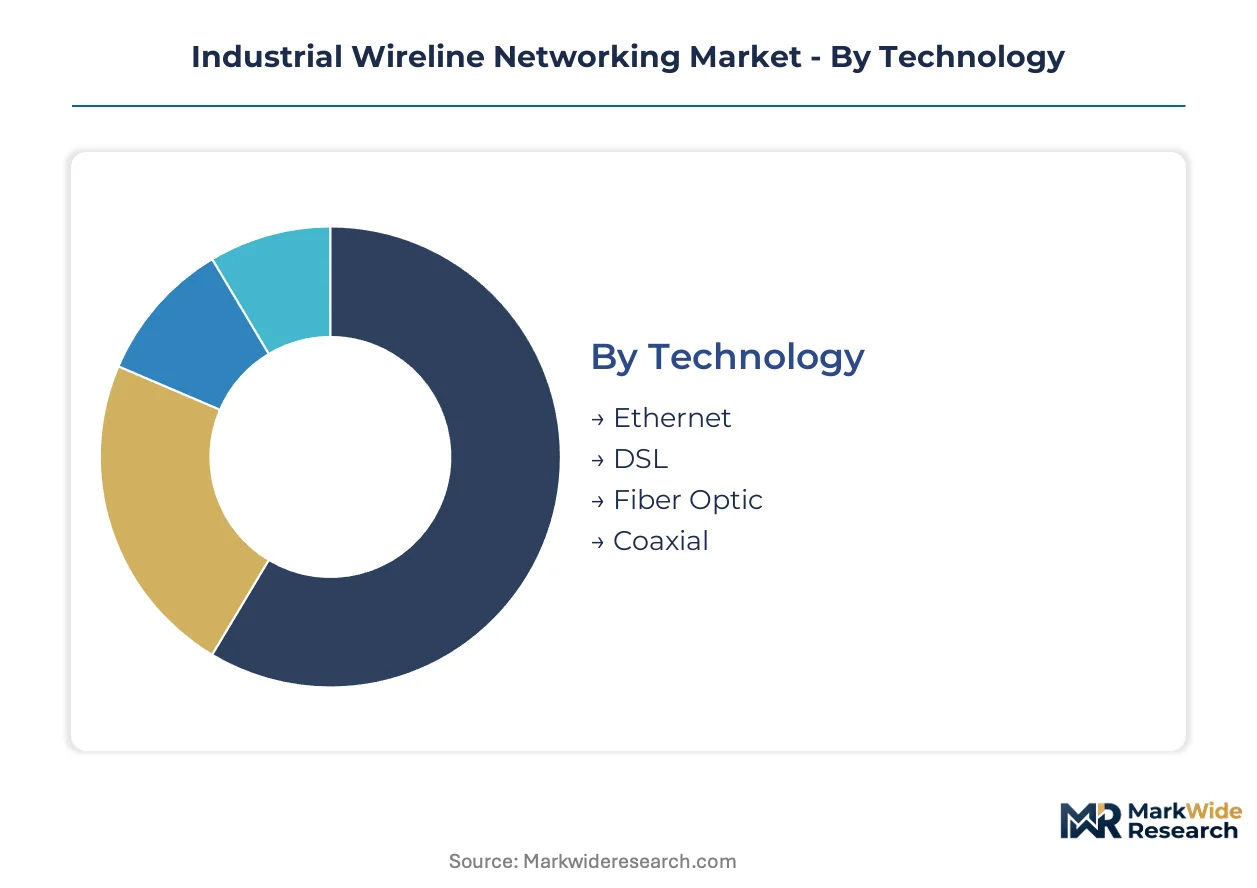
Industrial wireline networking procurement splits across four structural dimensions that determine equipment specifications, certification burdens, and vendor selection criteria. Each segmentation axis carries distinct regulatory weight and operational constraints that shape buyer decision frameworks.
Technology:
Ethernet and fiber optic deployments require ATEX/IECEx hazardous location certification for process industry use, while DSL and coaxial segments face lighter electromagnetic compatibility obligations under CE marking and FCC Part 15.
- Ethernet:Shielded twisted-pair and fiber variants dominate new installation spend. Time-Sensitive Networking conformance testing is accelerating procurement across automotive assembly lines in Germany's Ruhr corridor where deterministic latency is mandatory.
- Fiber Optic:Single-mode and multimode strands rated for minus forty to plus seventy-five degrees Celsius capture premium value in subsea oil platforms and underground mining where copper attenuation proves prohibitive. Long-haul fiber draw tower concentration in China and the United States creates geographic supply exposure.
- DSL:Legacy copper infrastructure persists in brownfield industrial parks with limited refresh budgets, particularly in Eastern European manufacturing zones where Ethernet migration timelines extend.
- Coaxial:Ruggedized coaxial cable retains niche presence in legacy process control systems and video surveillance backbones within chemical refineries.
Ethernet sits at the top of the volume ranking, with fiber optic climbing the fastest.
Application:
Manufacturing and utilities segments concentrate demand for deterministic networking, while oil & gas and mining applications prioritize hazardous location ratings and extreme temperature resilience.
- Manufacturing:Discrete automation and process control drive Ethernet-APL adoption across automotive and chemical plants. Smart manufacturing mandates in the EU Green Deal framework are compressing refresh cycles for legacy fieldbus infrastructure.
- Utilities:Grid modernization rules including US FERC Order 2222 are expanding substation-hardened switch procurement. Renewable integration mandates require real-time monitoring backbones with sub-second data granularity.
- Oil & Gas:Offshore platforms and downstream refineries demand flameproof enclosures and intrinsic safety barriers. Ethernet-APL physical layer specifications are dissolving power trunk requirements in greenfield installations.
- Mining:Underground long-haul applications depend on fiber optic for electromagnetic interference immunity in drill-and-blast operations.
Manufacturing commands the largest deployment base, while utilities gain share fastest on regulatory tailwinds.
End User:
Industrial plants and energy providers face the steepest certification burdens, whereas data centers and telecommunications operators source from enterprise-grade supply chains with lighter hazardous location requirements.
- Industrial Plants:Process and discrete manufacturers require IEC/IEEE 60802 TSN conformance for multi-vendor interoperability. The Rhine-Neckar chemical cluster in Germany shows the fastest regulatory-compliant switch procurement under national Industrial Emissions Directive implementation.
- Energy Providers:Electric utilities and renewable operators need substation-hardened equipment with extended temperature ratings. State-level renewable integration rules across multiple US jurisdictions are expanding addressable demand.
- Data Centers:Enterprise-grade Ethernet switches with standard cooling and power specifications serve industrial edge computing deployments.
- Telecommunications:Carrier-grade wireline infrastructure supports private LTE and 5G backhaul for industrial campuses.
Industrial plants anchor procurement volume, with energy providers expanding most quickly on grid modernization mandates.
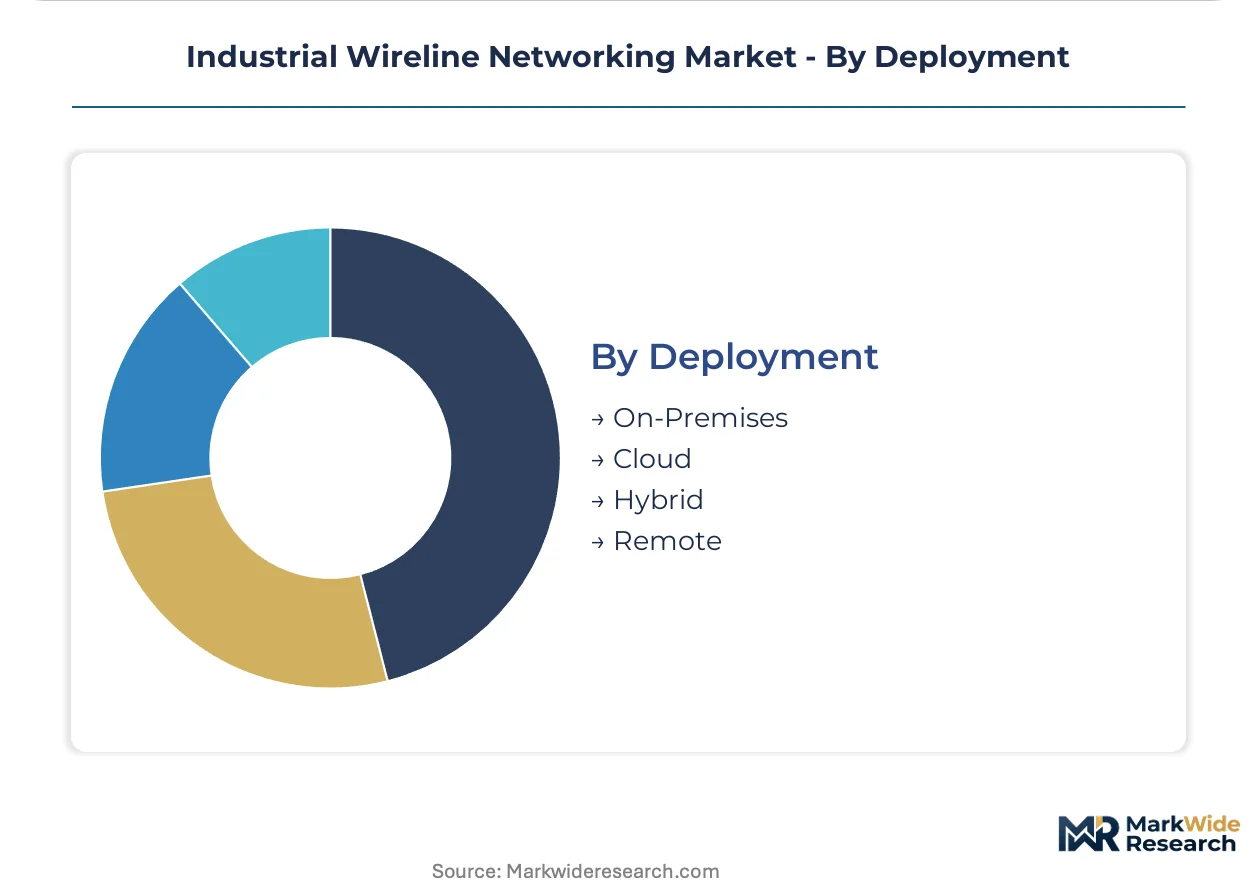
Deployment:
On-premises and hybrid architectures dominate industrial settings where data sovereignty and deterministic latency preclude full cloud migration, while remote deployment gains traction in distributed asset monitoring.
- On-Premises:Local control system integration and cybersecurity air-gapping requirements sustain dominance in chemical and automotive facilities. Stuttgart's automotive supplier ecosystem mandates on-premise network component traceability down to semiconductor level.
- Hybrid:Edge-to-cloud data pipelines balance real-time control with enterprise analytics. This architecture is overtaking pure on-premise designs in brownfield modernization projects.
- Cloud:SaaS-based network management tools penetrate smaller industrial plants with limited OT-IT staffing.
- Remote:Satellite and cellular backhaul serves pipeline monitoring and offshore platform telemetry where fiber installation is uneconomical.
On-premises deployment retains volume leadership, with hybrid architectures gaining the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr Valley birthed industrial fieldbus standards in the 1980s. That legacy now drives the fastest replacement cycles for deterministic Ethernet infrastructure worldwide.
Germany
Automotive OEMs in Stuttgart's supplier ecosystem mandate TSN conformance certificates before qualifying switch vendors. The national implementation of the EU Industrial Emissions Directive compresses procurement timelines. The Rhine-Neckar chemical cluster shows the fastest regulatory-compliant switch deployment as continuous emissions monitoring rules bite.
United States
Grid modernization under FERC Order 2222 expands substation-hardened Ethernet switch demand across independent system operators. State-level renewable integration rules in California and Texas require real-time monitoring backbones. The Permian Basin oil field operators are replacing legacy coaxial infrastructure with fiber optic for drill-and-blast electromagnetic immunity.
China
MIIT's smart manufacturing directives accelerate Ethernet-APL adoption in petrochemical complexes along the Yangtze River Delta. The dual carbon goals mandate sub-second energy monitoring granularity in heavy industry. Shandong Province's chemical parks are deploying single-pair Ethernet physical layers to eliminate separate power trunk requirements.
Japan
METI's Society 5.0 roadmap pushes deterministic networking into precision machinery supply chains. JIS standards for industrial Ethernet interoperability reduce buyer risk aversion. The Chubu region around Nagoya anchors automotive wireline refresh cycles as tier-one suppliers audit component traceability to semiconductor level.
India
PLI scheme incentives for electronics manufacturing draw industrial Ethernet switch assembly to Gujarat and Tamil Nadu. The Central Electricity Authority's grid modernization directives expand utility procurement. Maharashtra's Pune automotive corridor is replacing legacy Profibus with Ethernet-APL infrastructure to support higher device density.
Industrial Wireline Networking Market Competitive Environment
Capital-heavy producers compete with asset-light designers for dominance in industrial wireline networking. Integrated automation conglomerates with captive semiconductor fabrication anchor the premium tier, while specialized connectivity vendors occupy mid-market positions. Three archetypes define competitive positioning: protocol ecosystem owners, ruggedized infrastructure specialists, and enterprise IT incumbents. M&A activity concentrates on TSN software stacks, while strategic partnerships target Ethernet-APL certification acceleration.
Among protocol ecosystem owners, Siemens and Rockwell Automation exemplify vendor lock-in strategies through proprietary fieldbus heritage. Cisco Systems occupies a position bridging enterprise IT and operational technology domains. Belden Inc. represents the ruggedized infrastructure archetype withstanding extreme temperature environments.
| Leading Market Players |
|---|
| Cisco Systems |
| Siemens |
| Schneider Electric |
| Rockwell Automation |
| Huawei Technologies |
| Belden Inc. |
| ABB |
| Moxa Inc. |
| OMRON Corporation |
| Others |
Value Chain & Pricing Dynamics
Ethernet-APL physical layer maturation is compressing cost economics for process industry deployments while concentrating premium component supply among semiconductor foundries with hazardous location certification capabilities. Copper commodity volatility and fiber draw tower geographic concentration simultaneously reshape procurement strategies and margin structures across switch vendor tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ATEX/IECEx-certified switches from commercial-grade alternatives and unbranded white-label imports. Price differentiation hinges on TSN conformance certification tier and after-sales service bundling with predictive maintenance software. Cost compression in mid-tier portfolios is intensifying because shielded twisted-pair cabling remains tethered to London Metal Exchange copper fluctuations. Automotive OEMs in Germany exhibit lowest price sensitivity due to deterministic latency requirements, while Eastern European brownfield facilities show highest sensitivity during legacy fieldbus migration.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific to European industrial corridors is amplifying landed cost differentials between regional assembly hubs and Far East manufacturing centers. Component supply concentrates in China for specialty fiber draw towers, Germany for precision connector manufacturing, and the United States for flameproof enclosure fabrication. Raw material dependencies span copper cathodes from Chilean mines, optical-grade silica from American suppliers, and semiconductor-grade silicon from East Asian foundries. Single-source vulnerability pervades long-haul fiber supply where Chinese and American draw tower capacity dominates subsea and mining applications. Distribution runs through industrial automation distributors and direct MRO channel partnerships rather than traditional IT value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU Green Deal industrial decarbonization mandates shift procurement authority toward premium-certified TSN infrastructure with sub-second emissions monitoring granularity.
For Market Incumbents: Anchor technology leadership through captive TSN software stack development and accelerated IEC/IEEE 60802 certification timelines to defend against emerging Ethernet-APL specialists. Deepen backward integration into semiconductor sourcing for hazardous location-rated components to mitigate single-foundry exposure. Prioritize channel control via direct industrial distributor partnerships that bypass IT reseller margin capture during MRO replacement cycles. For New Entrants and Emerging Players: US FERC Order 2222 in North America opens a window for substation-hardened switch specialists targeting independent system operator grid modernization procurement. Target utility renewable integration mandates as the most penetrable vertical, with Ethernet-APL convergence in process industries as secondary white-space. Pursue go-to-market angles through Ethernet-APL certification acceleration partnerships with established hazardous location testing laboratories. For Investors and Strategic Acquirers: Roll-up economics work for ruggedized connectivity specialists because OT-IT skill convergence gaps create acquisition synergies through integrated training and certification service bundling. Focus on mid-cap vendors with captive semiconductor relationships and existing ATEX/IECEx product portfolios for long-term viability across the analysis window. Monitor TSN interoperability certification program maturation as the critical inflection signal for open-standard architecture displacement of proprietary protocol lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| TSN Software Stack Acquisition | Captures deterministic Ethernet intellectual property as IEC/IEEE 60802 conformance testing accelerates multi-vendor procurement. |
| Ethernet-APL Certification Partnership | Compresses product launch timelines for intrinsic safety barrier integration in chemical and oil field environments. |
| Direct Industrial Distributor Alliance | Bypasses traditional IT value-added reseller channels to capture margin in MRO replacement cycles across automotive corridors. |
| Substation Hardening R&D Investment | Addresses FERC Order 2222 grid modernization procurement requirements with extended temperature rating specifications. |
| Backward Integration into Fiber Draw | Reduces geographic single-source exposure for long-haul mining and subsea oil platform applications. |
Study Parameters
Direct dialogue with plant engineers, automation procurement leads, industrial distributor channel partners, and OT-IT convergence specialists grounded qualitative insights across automotive, chemical, and utility verticals. Secondary validation drew from IEC standards documentation, SEC 10-K filings of listed automation vendors, FERC order records, EU Green Deal implementation texts, and customs trade data for industrial networking equipment. Bottom-up equipment shipment analysis triangulated against top-down industrial capital expenditure surveys to establish market sizing boundaries.
Segmentation outputs across technology, application, end user, and deployment dimensions fed into growth projection modeling throughout the forecast period. CAGRs derived from regression analysis against industrial production indices, regulatory implementation timelines, and fieldbus replacement cycle data. Forecast inputs incorporated Time-Sensitive Networking protocol maturation curves, copper commodity price volatility assumptions, and grid modernization mandate adoption rates across multiple jurisdictions.
Revisions become necessary when TSN interoperability certification program delays, copper supply disruptions, or regulatory implementation timeline shifts materialize beyond modeled assumptions. Forecasts reflect documented assumptions about technology substitution rates and certification burden trajectories. Stakeholders should weight assumptions against their own operating context and supplier relationship structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Managed Wi-Fi Solutions Market
Network Technology
Wimax Solutions Market
Network Technology
Passive Optical Network Market
Network Technology
Mobile Network Optimization Market
Network Technology
Global LWAN Market
Network Technology
Protocol Analyzer Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Wi-Fi Extender Market
Network Technology
Mobile Backhaul Market
Network Technology
Network Devices Market
Network Technology
Netops Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Cloud Gateway Module Market
Network Technology
Fiber to the Premises Market