
 Service Provider Network Infrastructure Market | 2026-2036
Service Provider Network Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Service Provider Network Infrastructure Market Intelligence
Cloud-managed routing revenue is reconfiguring margin pools away from traditional hardware resale toward recurring software subscriptions. Cisco Systems Inc. leverages its Meraki platform to anchor recurring revenue in mid-market service provider channels. Nokia Corporation dominates optical transport with in-house silicon photonics fabrication that sustains cost advantages in long-haul deployments.
Service provider network infrastructure encompasses the physical and virtualized equipment, software stacks, and management systems that enable telecommunications carriers to transmit, route, and secure data traffic across regional and national footprints, typically operating at Layer 1 through Layer 3 with throughput specifications ranging from 100 Gbps to 800 Gbps per optical channel. SD-WAN technology leads technology segment growth as enterprises abandon MPLS circuits for broadband-underlay architectures that reduce branch connectivity costs by half or more. Cloud-based deployment models are displacing on-premise chassis installations among tier-two and tier-three operators seeking operational flexibility without capital-intensive refresh cycles.
The FCC in the United States and Ofcom in the United Kingdom enforce open network interface standards that shape vendor selection criteria and lock-in risk assessments for procurement teams. ETSI and the MEF publish interoperability frameworks that determine which equipment combinations qualify for multi-vendor network bids. Stakeholders must monitor how open-source disaggregation initiatives reshape RFP economics and incumbent pricing power.
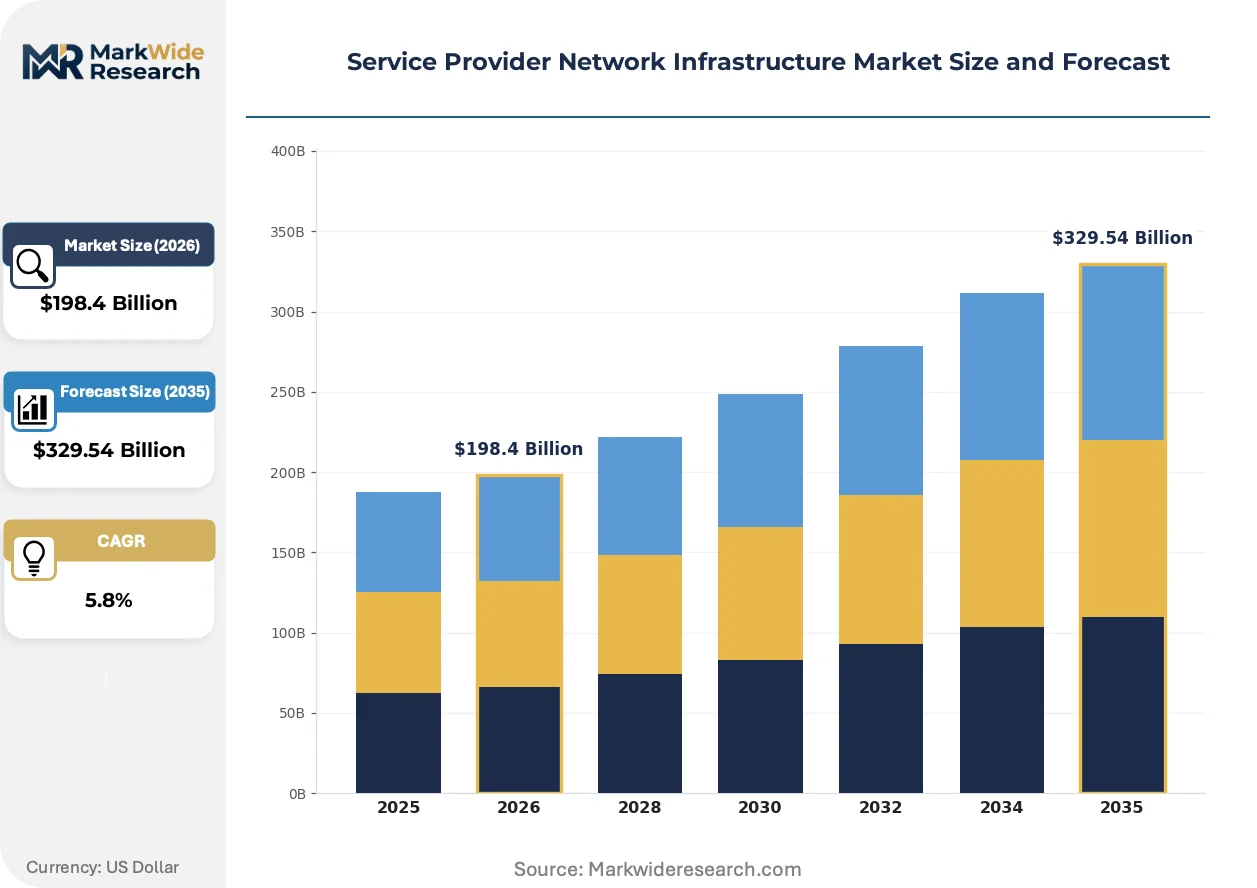
Market Dynamics
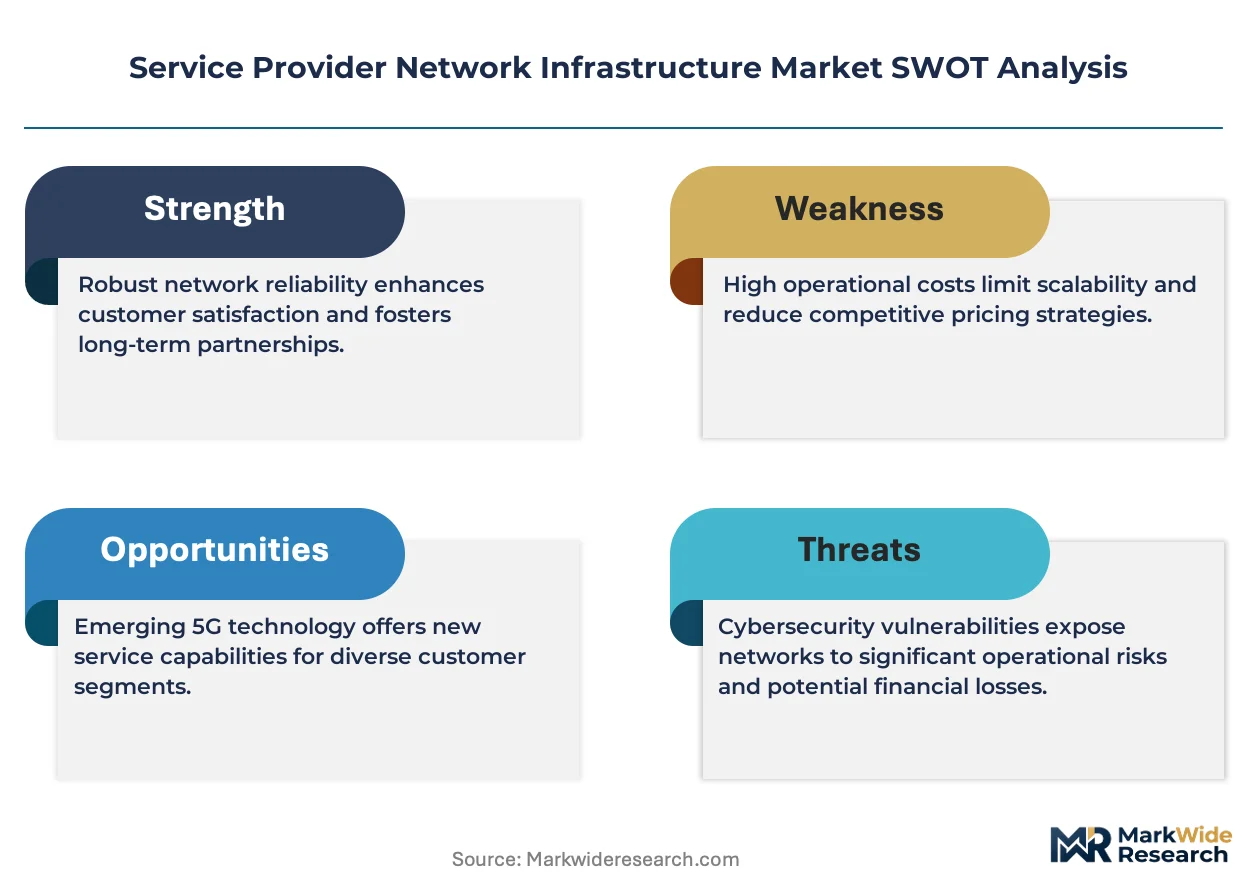
Open RAN interoperability mandates from the FCC and Ofcom are forcing incumbent vendors to disaggregate hardware and software stacks, fundamentally restructuring procurement economics and vendor lock-in risk across carrier networks.
Growth Catalysts
- 5G densification:Telecom operators across Southeast Asia are expanding fiber backbones to support massive small cell deployments, driving demand for high-capacity optical transport and edge routing infrastructure.
- ETSI interoperability frameworks:Standardized open interfaces enable multi-vendor network bids that reduce single-source dependency and accelerate equipment refresh cycles for tier-two operators.
- Greenfield network builds:Reliance Jio and Bharti Airtel in India are constructing massive new networks without legacy baggage, creating concentrated demand for cloud-native infrastructure stacks.
Market Restraints
- Silicon photonics fabrication concentration:Advanced optical component production clusters in select East Asian foundries, creating supply vulnerability for long-haul transport equipment vendors without captive fabrication.
- MPLS circuit stickiness:Enterprise customers in regulated industries maintain legacy private connectivity for compliance reasons, slowing SD-WAN substitution despite cost advantages.
- TRAI spectrum pricing:India's aggressive auction mechanisms strain carrier balance sheets and compress capital available for core network infrastructure investment.
Strategic Opportunities
- Cloud-managed routing penetration:Mid-market service providers represent an underpenetrated channel for subscription-based network management platforms that shift revenue from hardware resale to recurring software.
- EU AI Act compliance infrastructure:European carriers must deploy explainable network automation tools, creating demand for telemetry and analytics layers that satisfy algorithmic accountability requirements.
- Convergence of SD-WAN and SASE:Security-service edge integration with software-defined wide area networking enables bundled offerings that capture enterprise security budgets alongside connectivity spend.
Industry Challenges
- Disaggregated stack integration:Carriers assembling multi-vendor Open RAN solutions face interoperability testing burdens and finger-pointing complexity when performance issues arise.
- Optical engineer scarcity:Deep expertise in coherent transmission physics and photonic system design concentrates among aging specialists, constraining deployment velocity for 800 Gbps upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Provider Network Infrastructure Market |
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $329.54 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bandwidth Management, Security Services, Network Operating Systems, Cloud Services Technology: SD-WAN, MPLS, Ethernet, IP VPN Deployment: On-Premise, Cloud-Based, Hybrid, Virtualized End User: Telecom Operators, Internet Service Providers, Enterprises, Resellers |
| Companies Covered | Nokia Corporation, Juniper Networks Inc, Huawei Technologies Co. Ltd., Hewlett Packard Enterprise Company, Ciena Corporation, ZTE Corporation, Telefonaktiebolaget LM Ericsson, Arista Networks Inc., Cisco Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Provider Network Infrastructure Market Strategic Shifts & Innovations
Network functions virtualization is collapsing the boundary between hardware appliances and software workloads, enabling carriers to deploy capacity as elastic cloud resources rather than fixed chassis investments.
Virtualized radio access network software is virtualizing baseband processing functions that previously required dedicated hardware. Tier-one carriers in South Korea and Japan are deploying cloud-native RAN at scale in dense urban corridors. This architecture is virtualizing the traditional vendor-dominated RAN market by decoupling software from proprietary silicon.
Ofcom's open network interface standards in the United Kingdom mandate disaggregated procurement specifications for public subsidy-eligible rural broadband builds. The regulation fragments incumbent supplier relationships and elevates interoperability certification to a primary vendor selection criterion. Tier-three operators in Scotland and Wales are leveraging these mandates to source white-box hardware with independent software.
Enterprise procurement patterns are compressing vendor evaluation cycles as IT departments prioritize agility over multi-year capital planning. Broadband-underlay architectures are displacing traditional MPLS-managed service relationships in North American branch networks. Financial services and retail verticals exhibit the most aggressive abandonment of circuit-switched connectivity models.
Service Provider Network Infrastructure Market Segmentation
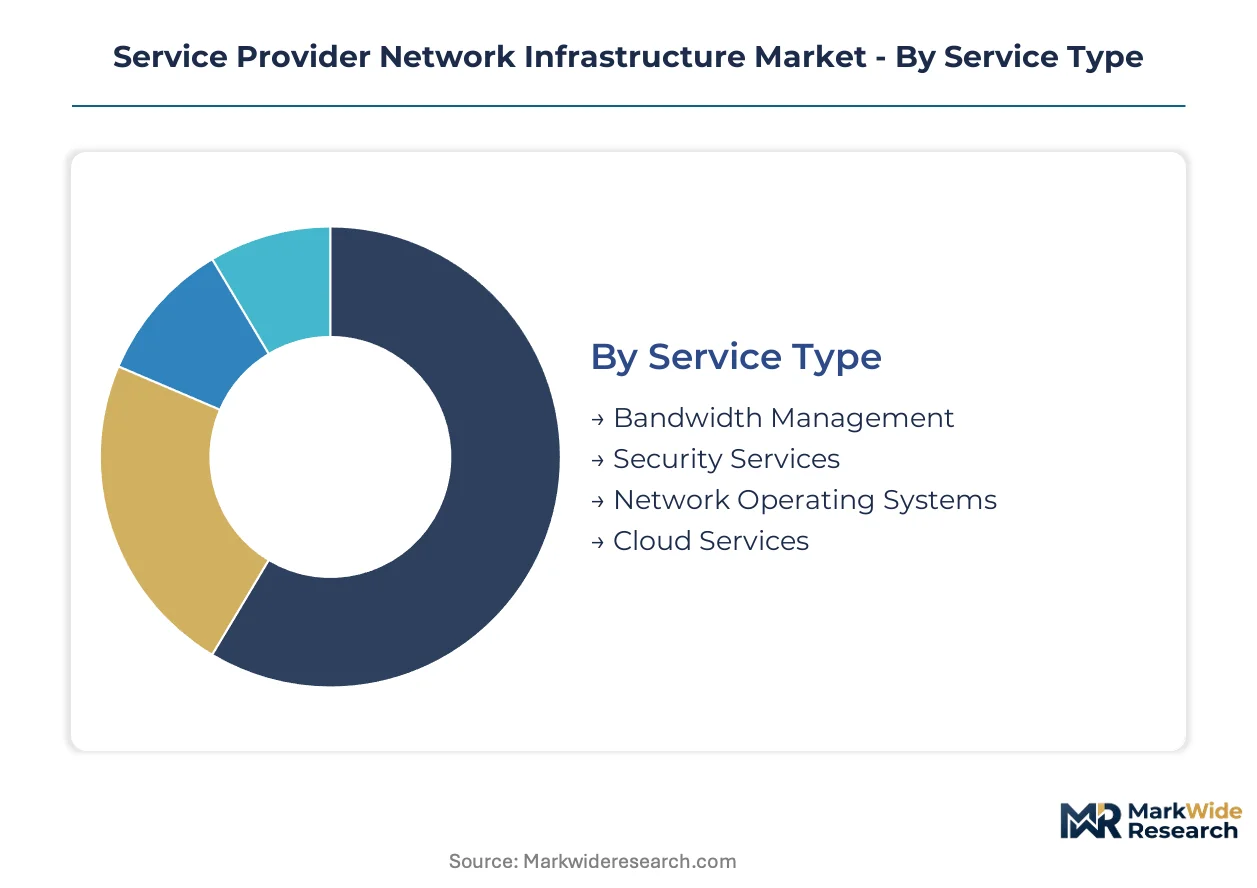
Segmentation in service provider network infrastructure reveals divergent equipment refresh cycles, with cloud-native deployments turning over every 3-4 years while legacy MPLS hardware persists for 7-10 years. Procurement teams use these segment boundaries to balance capital efficiency against performance requirements.
Service Type:
Bandwidth Management solutions refresh fastest due to traffic growth volatility, while Security Services exhibit longer cycles tied to compliance recertification schedules.
- Bandwidth Management:Traffic shaping and quality-of-service enforcement engines process 100-800 Gbps per optical channel. Indian carriers Reliance Jio and Bharti Airtel deploy these systems at network aggregation points to handle video streaming surges that strain backhaul capacity.
- Security Services:Deep packet inspection and DDoS mitigation appliances integrate threat intelligence feeds with line-rate encryption. European operators under EU AI Act pressure are procuring explainable network automation tools that embed security telemetry directly into routing layers.
- Network Operating Systems:Disaggregated NOS distributions run on merchant silicon switches, enabling white-box procurement strategies that bypass traditional vendor lock-in.
- Cloud Services:Managed network functions delivered as subscription services shift capital expenditure to operational budgets for tier-two operators.
Cloud Services anchors the volume base while Bandwidth Management gains share at the steepest rate.
Technology:
Cost tier stratification separates premium SD-WAN deployments from legacy MPLS maintenance contracts, with Ethernet occupying the mid-market connectivity position.
- SD-WAN:Software-defined overlay networks abstract physical transport into policy-driven virtual circuits. Southeast Asian operators expanding fiber backbones for 5G densification deploy SD-WAN at cell site aggregation layers to simplify traffic steering across heterogeneous transport.
- MPLS:Multiprotocol label switching retains dominance in regulated financial services verticals where compliance officers mandate circuit-switched audit trails despite 40-60% cost premiums over broadband alternatives.
- Ethernet:Carrier-grade Ethernet services deliver point-to-point and multipoint connectivity with standardized service level agreements that appeal to mid-market enterprise procurement teams.
- IP VPN:Internet protocol virtual private networks leverage existing broadband infrastructure to deliver encrypted site-to-site connectivity without dedicated circuit provisioning.
Ethernet anchors the volume base while SD-WAN climbs the fastest in share expansion.
Deployment:
Customer type determines deployment preference, with tier-one operators favoring hybrid architectures while tier-three providers pursue fully virtualized stacks to avoid chassis capital intensity.
- On-Premise:Dedicated hardware chassis installations in carrier facilities provide deterministic performance for 800 Gbps coherent optical transport. South Korean and Japanese tier-one operators maintain on-premise baseband processing for ultra-low latency requirements in dense urban 5G corridors.
- Cloud-Based:Fully managed network functions delivered from hyperscaler or telco cloud environments eliminate refresh cycle ownership. Tier-three operators in Scotland and Wales leverage Ofcom's open network interface mandates to source cloud-managed routing without proprietary hardware commitments.
- Hybrid:Split architectures retain critical control plane functions on-premise while offloading user plane processing to cloud instances, balancing latency sensitivity against scalability.
- Virtualized:Containerized network functions deployed on standard compute infrastructure collapse the boundary between hardware appliances and software workloads.
On-Premise anchors the volume base while Cloud-Based exhibits the steepest expansion trajectory.
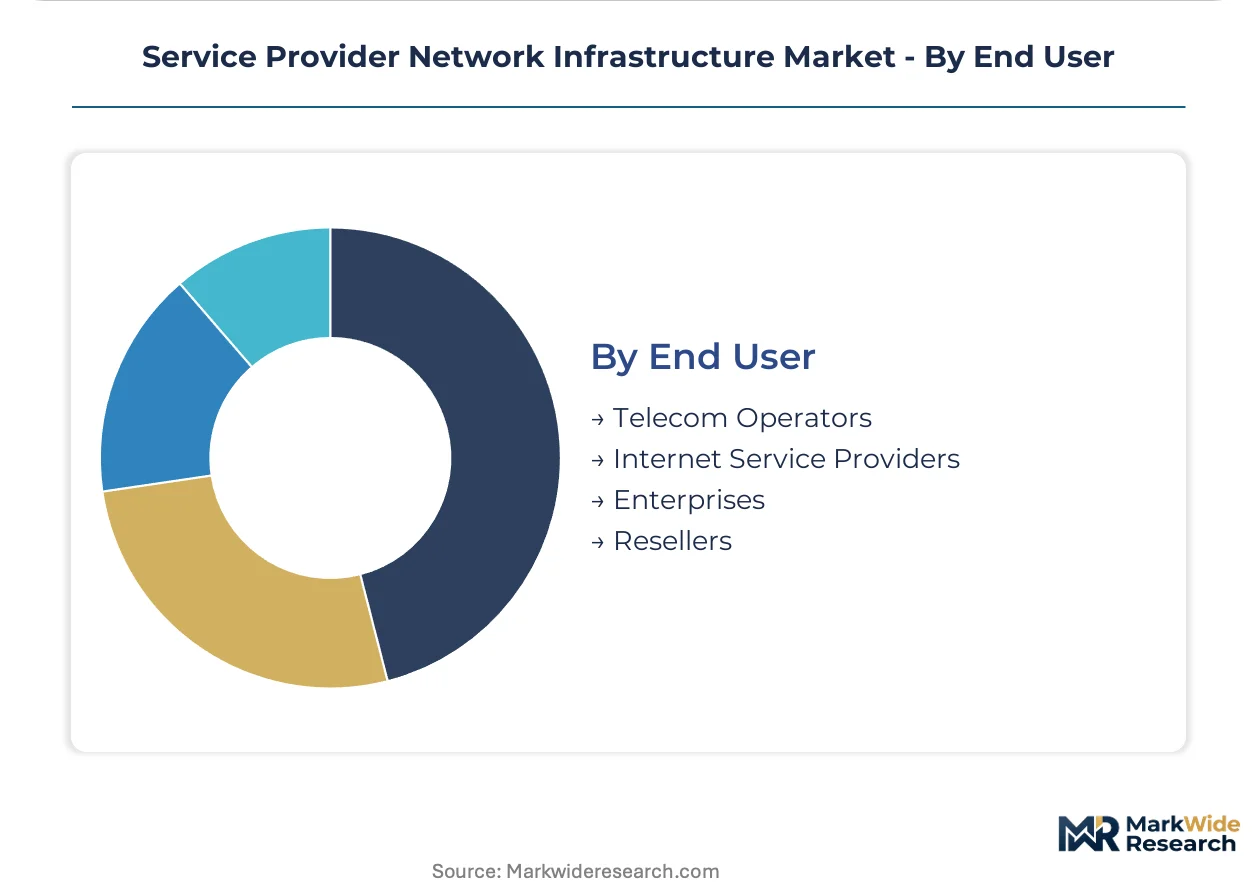
End User:
Application intensity varies sharply, with telecom operators driving 800 Gbps optical upgrades while resellers concentrate on mid-market SD-WAN aggregation.
- Telecom Operators:National and regional carriers deploy core, aggregation, and access layer infrastructure across national footprints. FCC open RAN interoperability mandates force these operators to disaggregate hardware and software procurement, restructuring vendor relationships.
- Internet Service Providers:Fixed and wireless broadband providers optimize last-mile delivery infrastructure. TRAI spectrum pricing pressures in India constrain capital available for core network investment among ISP subsidiaries of national carriers.
- Enterprises:Large organizations with private network requirements procure managed services or build self-operated WANs, with financial services and retail verticals showing aggressive abandonment of MPLS models.
- Resellers:Systems integrators and managed service providers aggregate demand from fragmented mid-market customers, bundling connectivity with security and cloud migration services.
Telecom Operators anchors the volume base while Resellers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exhibits the highest demand elasticity as aggressive spectrum auctions compress carrier capital budgets, while Germany maintains price stability through long-term equipment amortization cycles and captive silicon sourcing.
United States
Verizon and AT&T drive 800 Gbps optical transport upgrades across metro corridors to support AI traffic surges. FCC open RAN interoperability mandates force disaggregated procurement specifications for rural broadband subsidy programs. Dallas-Fort Worth anchors a cluster of systems integrators assembling multi-vendor network stacks for tier-three operators.
India
Reliance Jio and Bharti Airtel construct greenfield 5G networks without legacy chassis constraints, creating concentrated demand for cloud-native infrastructure. TRAI spectrum pricing mechanisms strain carrier balance sheets and redirect capital toward access layer buildouts. Bengaluru hosts a growing ecosystem of disaggregated network software vendors serving domestic operators.
Germany
Deutsche Telekom deploys coherent optical transport across industrial corridors to support manufacturing automation latency requirements. EU AI Act compliance pressures drive procurement of explainable network automation tools with embedded telemetry layers. Munich concentrates silicon photonics R&D facilities supplying European long-haul equipment vendors.
South Korea
SK Telecom and KT Corporation scale cloud-native RAN deployments in dense Seoul urban corridors for sub-5 millisecond edge latency. METI-aligned standards frameworks shape vendor certification requirements for multi-vendor baseband integration. Pangyo Techno Valley clusters virtualization software specialists serving domestic tier-one carriers.
United Kingdom
BT Group and Virgin Media O2 expand fiber-to-the-premises infrastructure under government connectivity targets. Ofcom open network interface standards mandate disaggregated procurement for rural broadband subsidy eligibility. Bristol harbors a concentration of white-box hardware assemblers leveraging regulatory fragmentation of incumbent supplier relationships.
Service Provider Network Infrastructure Market Key Industry Players
Capability concentration sits with optical specialists commanding in-house silicon photonics fabrication; scale advantage sits with diversified networking conglomerates spanning routing, switching, and security portfolios. The market structures around three tiers: integrated systems vendors with captive semiconductor capacity, software-centric disrupters attacking subscription revenue pools, and white-box assemblers exploiting open-source hardware standards. Dominant competitive moves include vertical integration into photonic component supply and strategic partnerships between cloud hyperscalers and telecom equipment vendors.
Among diversified networking vendors, Cisco Systems Inc. and Nokia Corporation exemplify contrasting scale strategies, with the former anchoring cloud-managed subscription revenue in mid-market channels and the latter sustaining cost advantages through captive optical silicon production. Arista Networks Inc. occupies a position within the high-performance data center interconnect tier. These three entities collectively represent the spectrum of competitive positioning from software-recurring models through hardware-integrated fabrication depth.
| Leading Market Players |
|---|
| Nokia Corporation |
| Juniper Networks Inc |
| Huawei Technologies Co. Ltd. |
| Hewlett Packard Enterprise Company |
| Ciena Corporation |
| ZTE Corporation |
| Telefonaktiebolaget LM Ericsson |
| Arista Networks Inc. |
| Cisco Systems Inc. |
| Others |
Cost & Logistics Intelligence
Munich's silicon photonics R&D cluster concentrates coherent optical component fabrication, granting European vendors captive supply advantages that sustain pricing power in 800 Gbps transport negotiations against Asian merchant silicon alternatives. This geographic concentration of photonic expertise creates tiered procurement economics where carriers without backward integration into component supply face 15-25% cost premiums on long-haul equipment.
Pricing Analysis
Software maintenance and subscription renewals generate lifetime value multiples exceeding initial hardware transactions by three to five times. The market operates on a hybrid pricing structure combining capital equipment sales with recurring SaaS tiers for cloud-managed routing platforms. Price differentiation rests on optical performance certification levels and geographic delivery complexity, with sub-5 millisecond latency guarantees commanding substantial premiums. Cost compression in mid-market SD-WAN tiers is intensifying because hyperscaler-backed entrants are subsidizing customer acquisition. Tier-two operators exhibit the highest price sensitivity, while tier-one carriers prioritize interoperability certification over unit economics.
Supply Chain Analysis
Export controls on advanced coherent DSPs and silicon photonics equipment limit technology flows between the United States, China, and select European jurisdictions. Supply concentration sits in Taiwan, South Korea, and Germany for merchant silicon switches, optical transceivers, and specialized photonic components respectively. Raw material dependencies include rare earth elements for optical amplifiers, high-purity germanium for photodetectors, and advanced substrates for indium phosphide lasers. Single-source vulnerability concentrates in East Asian foundries producing 7nm and below networking silicon. Distribution runs through direct carrier procurement teams for tier-one operators and systems integrator channels for mid-market aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service provider network infrastructure represents a service-attach opportunity where cloud-managed routing subscriptions and software maintenance contracts are expanding at double the rate of hardware resale, restructuring vendor economics toward recurring revenue durability.
For Market Incumbents: Harden defensive positions by deepening in-house silicon photonics production to neutralize supply vulnerability in East Asian foundries. Anchor recurring revenue through Meraki-class cloud management platforms that embed switching customers into subscription ecosystems. Prioritize interoperability certification investments to maintain eligibility under FCC and Ofcom open RAN mandates that fragment procurement specifications.
For New Entrants and Emerging Players: Pursue white-box hardware assembly opportunities in Scotland and Wales where Ofcom's rural broadband subsidies mandate disaggregated procurement. Target tier-three operators seeking cloud-native infrastructure without legacy chassis baggage. Lead with subscription-based network operating systems that displace Cisco IOS and Juniper JunOS in greenfield Indian deployments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors disaggregated software vendors with cloud-native RAN stacks over integrated hardware incumbents facing margin compression. Long-term viability centers on vendors controlling both virtualized radio software and telemetry analytics layers demanded by EU AI Act compliance. The signal to watch is carrier capital allocation shifts between access layer 5G densification and core optical transport upgrades.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native RAN Software Development | Virtualized baseband processing collapses proprietary hardware lock-in at SK Telecom and KT Corporation deployments. |
| Silicon Photonics Fabrication Expansion | In-house coherent optical component production sustains cost advantages for Deutsche Telekom's industrial corridor networks. |
| SD-WAN and SASE Platform Integration | Bundled security-service edge offerings capture enterprise budgets alongside connectivity spend at financial services verticals. |
| Open RAN Interoperability Certification | ETSI framework compliance qualifies vendors for multi-vendor bids from Reliance Jio and Bharti Airtel procurement teams. |
| Subscription-Based Network Management | Recurring software revenue reconfigures margin pools away from transactional hardware resale in mid-market channels. |
Research Approach
Desk research of equipment vendor SEC filings, hyperscaler capex disclosures, and carrier procurement databases preceded structured interviews with network architects at tier-one operators, procurement directors at Indian and Southeast Asian carriers, interoperability certification leads at ETSI, and cloud infrastructure strategists at systems integrators. Primary fieldwork captured deployment timelines, refresh cycle patterns, and vendor selection criteria across 5G densification and optical transport projects. Secondary validation drew from TRAI spectrum auction records, FCC rural broadband subsidy filings, and EU AI Act implementation guidance. Bottom-up equipment shipment modeling triangulated against top-down carrier capital expenditure forecasts.
Forecast assumptions held fixed regulatory timelines for open RAN mandates and spectrum auction schedules while varying enterprise SD-WAN substitution rates and cloud-native adoption curves across the projection horizon. The analytical framework modeled segmentation across service type, technology tier, deployment architecture, and end-user category, with additional dimensioning by optical channel capacity specifications from 100 Gbps to 800 Gbps. CAGRs were derived from logistic adoption curves fitted to historical equipment refresh patterns and carrier disclosed buildout timelines. Industry-specific inputs included coherent transmission physics constraints, merchant silicon switch port economics, and virtualization software licensing trajectories.
Sensitivities concentrate around TRAI spectrum pricing volatility, East Asian foundry capacity allocation shifts, and enterprise MPLS abandonment acceleration. Forecasts reflect documented assumptions regarding open RAN interoperability certification timelines and hyperscaler edge computing partnership structures. Material shifts in FCC or Ofcom regulatory enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Europe Self-Healing Networks Market
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Europe Private 5G Network Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
Managed Switches Market
Network Technology
Netops Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
Global LWAN Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Wi-Fi Extender Market
Network Technology
Virtual Router Market
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
Network Performance Monitoring Market
Network Technology
Intelligent Network Management Market
Network Technology
Gigabit Passive Optical Network (GPON) Market