
 Wireless Charger Market | 2026-2036
Wireless Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Charger Market Outlook
The gap between premium certified Qi2 chargers and unbranded commodity pads is broadening in concrete terms of power delivery precision, thermal management, and foreign-object detection reliability. Samsung Electronics leverages its semiconductor ecosystem to sustain vertical integration from coil design to retail packaging. Apple anchors premium pricing through proprietary MagSafe magnetic alignment, which competes against open-standard alternatives. Anker specializes in GaN-based compact form factors that occupy the mid-tier channel on Amazon and electronics stores globally.
Wireless chargers transfer electrical energy across air gaps through electromagnetic induction or magnetic resonance, typically operating at frequencies between 110 and 205 kHz with power outputs ranging from 5W to 100W depending on the protocol. Their primary commercial purpose is eliminating physical connector wear while enabling sealed, waterproof device designs in consumer and automotive environments. Desk chargers dominate volume in corporate deployments where multiple workstations require standardized power delivery. Multi-device chargers represent the fastest-growing product type as households consolidate smartphone, watch, and earbud charging onto single surfaces. Automotive end users command premium margin pools due to thermal cycling requirements and OEM certification timelines that lock in supplier relationships.
The Federal Communications Commission governs radio-frequency emissions from wireless chargers sold in the United States, while the EU Radio Equipment Directive mandates CE marking and interoperability disclosure across member states. China's Ministry of Industry and Information Technology enforces GB standards for electromagnetic compatibility that shape product designs for domestic manufacturers. Stakeholders must monitor how Qi2 protocol certification timelines align with regional power-density thresholds and automotive safety integration requirements.
Market Dynamics
Qi2 protocol standardization is compressing the technical gap between premium and mid-tier wireless charging hardware, forcing manufacturers to differentiate through thermal engineering and multi-device orchestration rather than power output alone.
Growth Catalysts
- Automotive integration mandates:NHTSA guidelines for cabin electronics safety are accelerating OEM adoption of certified wireless charging modules in vehicle center consoles across US production lines.
- EU harmonization pressure:The Radio Equipment Directive's interoperability disclosure requirements are pushing manufacturers toward unified testing protocols that reduce certification duplication across member states.
- GaN semiconductor maturation:Gallium nitride power electronics are enabling smaller coil geometries with equivalent thermal performance, opening premium feature sets to compact form factors.
Market Restraints
- Copper and ferrite supply concentration:Coil winding materials face price volatility due to processing capacity concentration in East Asian metallurgical facilities.
- Radio-frequency emission ceilings:FCC Part 18 restrictions on industrial, scientific and medical equipment frequencies cap power-density scaling in US-bound products.
- Qi legacy device persistence:Hundreds of millions of first-generation Qi smartphones in active use create backward-compatibility burdens that slow protocol migration.
Strategic Opportunities
- India manufacturing incentives:The PLI scheme for electronics hardware is attracting wireless charger assembly operations targeting domestic smartphone bundling contracts.
- Healthcare sterilization applications:Sealed, connector-free charging surfaces are penetrating surgical equipment and patient monitoring device categories where ingress protection is critical.
- Qi2 accessory ecosystem expansion:Magnetic alignment accessories for automotive mounts and furniture integration represent attach-rate growth beyond the charging pad itself.
Industry Challenges
- Foreign-object detection calibration:Precision tuning for coins, keys and medical implants requires extensive field testing that extends product development cycles.
- Cross-protocol certification stacking:Simultaneous Qi, Qi2 and proprietary magnetic alignment approvals demand redundant laboratory engagements with multiple standards bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Charger Market |
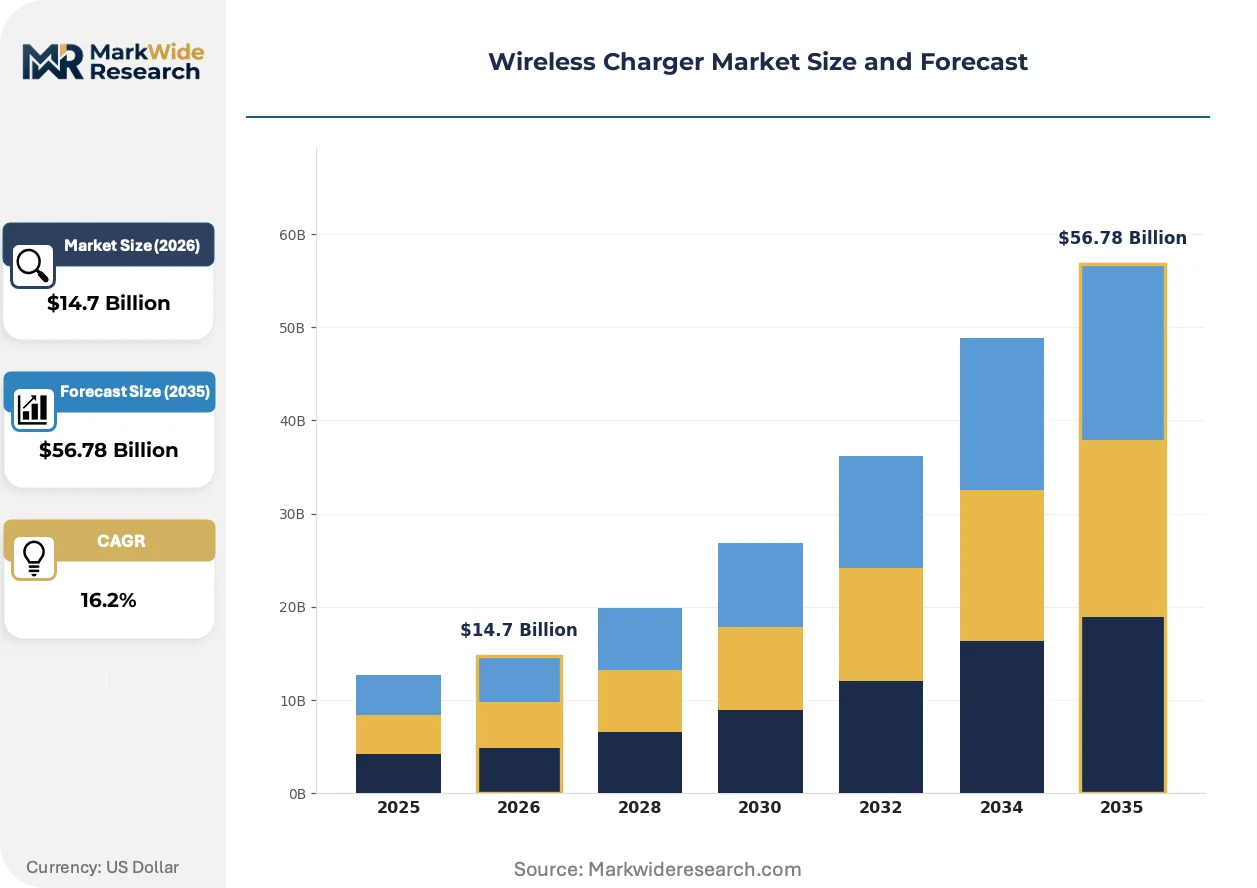
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $56.78 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chargers, Desk Chargers, Car Chargers, Multi-device Chargers Technology: Qi, PMA, Rezence, Inductive Charging End User: Consumers, Corporates, Automotive, Retail Distribution Channel: Online Retailers, Electronics Stores, Hypermarkets, Direct Sales |
| Companies Covered | Samsung Electronics, Apple, Qualcomm Technologies, WiTricity, Belkin, Energizer Holdings, Powermat Technologies, Anker, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Charger Market Strategic Shifts
Magnetic resonance architectures are expanding beyond tight-coupled inductive pads into spatially distributed charging surfaces, while regulatory pressure on electromagnetic compatibility is tightening design constraints faster than component innovation can absorb.
GaN-based power conversion is overtaking silicon MOSFET architectures in wireless charging transmitters above 15W output. Automotive tier-1 suppliers are adopting GaN half-bridge topologies for cabin console modules to reduce heat sinking mass. This transition is compressing bill-of-materials differentiation between premium and standard-tier hardware, forcing competition toward thermal simulation accuracy and coil placement precision.
The EU's updated Radio Equipment Directive enforcement is mandating explicit interoperability disclosure for all wireless power transmitters marketed in member states. Manufacturers must now document frequency stability, spurious emission profiles and foreign-object detection thresholds in standardized technical files. Consumer electronics retailers in Germany and France are already rejecting shipments lacking completed RED compliance folders, compressing time-to-market for non-EU producers.
Enterprise procurement of wireless charging infrastructure is consolidating around managed service contracts rather than discrete hardware purchases. Facility managers in US corporate campuses are contracting charging-surface-as-a-service agreements that bundle installation, maintenance and upgrade cycles into per-workstation fees. This shift is most visible in technology sector headquarters across California and Washington state, where standardized desk configurations dominate fit-out specifications.
Wireless Charger Market Segmentation
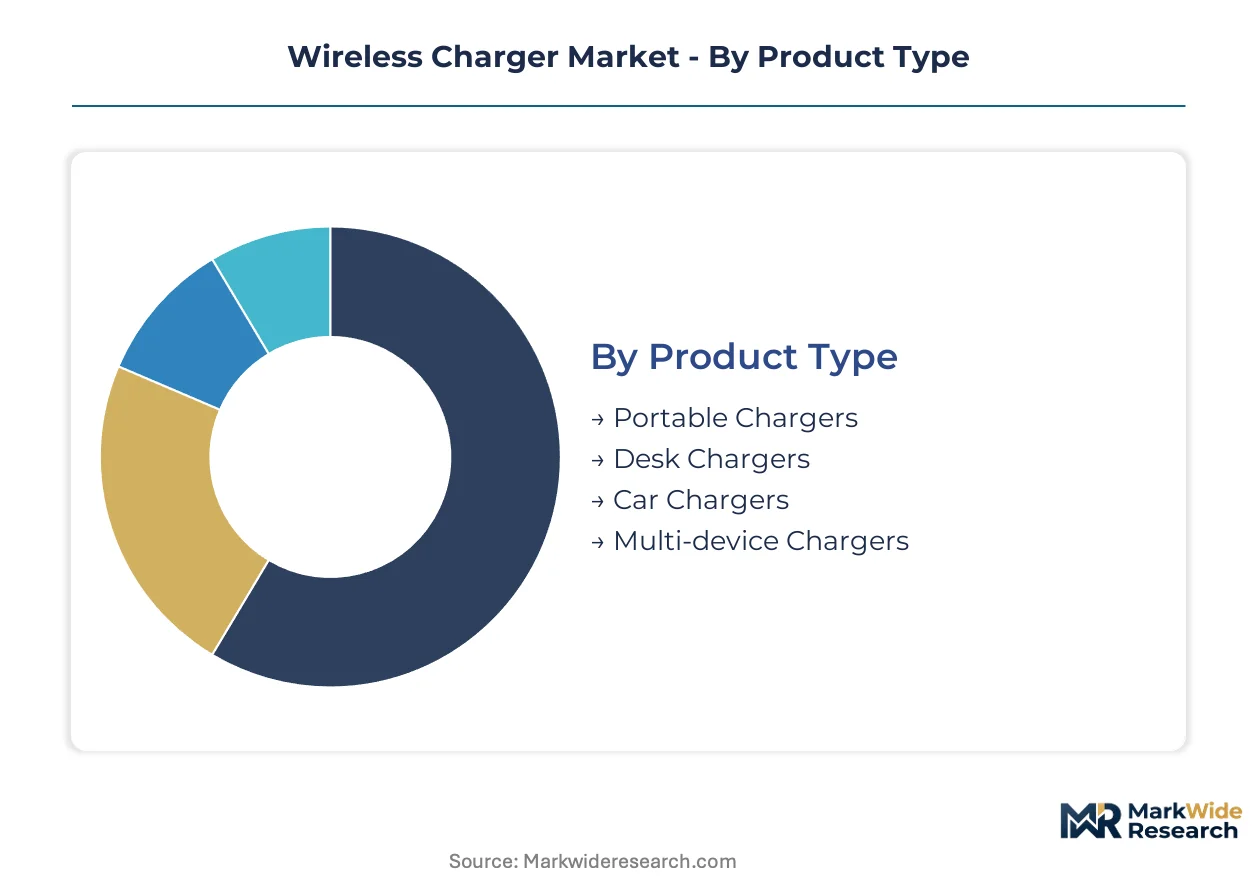
Wireless charger buyers prioritize fundamentally different performance attributes depending on deployment context. Segmentation reveals how power density requirements, spatial constraints, and certification burdens reshape procurement criteria across customer categories.
Product Type:
Buyers differentiate primarily by mobility needs versus fixed-installation permanence, which dictates thermal design tolerance and coil geometry complexity.
- Desk Chargers:Stationary pads with flat or angled coil arrays dominate corporate procurement for standardized workstation deployments. Demand concentrates in US technology campuses where facility managers negotiate managed-service contracts bundling installation and upgrade cycles.
- Multi-device Chargers:Expanded surface areas accommodate simultaneous smartphone, smartwatch, and earbud charging through partitioned coil zones. Households in China drive adoption as domestic smartphone brands bundle these with flagship launches, consolidating clutter reduction with ecosystem loyalty.
- Portable Chargers:Battery-integrated units enable cord-free mobility for travel and field use.
- Car Chargers:Vehicle-integrated pads embed in center consoles with automotive-grade thermal cycling certification.
Desk chargers lead volumes today; multi-device chargers are gaining share fastest.
Technology:
Protocol choice determines interoperability breadth versus proprietary optimization, with certification cost stacking as the decisive commercial variable.
- Qi:The dominant inductive standard operates at 110-205 kHz with power outputs from 5W to 15W for legacy device compatibility. Manufacturing concentrates in China where MIIT enforces GB electromagnetic compatibility standards that shape domestic coil designs.
- Qi2:Magnetic alignment extension of Qi with standardized ring magnets for precise device positioning. Automotive OEMs in Germany specify Qi2 for new center console modules under KBA safety integration timelines, locking in supplier relationships through extended certification cycles.
- PMA:Alternative inductive protocol with distinct frequency allocation, now largely superseded in consumer markets.
- Rezence:Magnetic resonance architecture enabling spatially distributed charging across larger air gaps.
- Inductive Charging:Generic tight-coupled electromagnetic transfer without protocol-specific certification requirements.
Qi dominates installed base; Qi2 shows the steepest expansion trajectory.
End User:
Volume scale, margin tolerance, and technical specification rigor separate procurement behaviors across buyer categories.
- Automotive:Tier-1 suppliers demand extended temperature range performance and NHTSA cabin electronics safety compliance. Production concentrates in Michigan and Baden-Württemberg where OEM certification timelines stretch 18-24 months, creating captive supplier relationships.
- Corporates:Standardized desk configurations across California and Washington headquarters favor charging-surface-as-a-service contracts over discrete hardware purchases.
- Consumers:Individual purchasers prioritize compact form factors and retail availability through Amazon and electronics stores.
- Retail:Hospitality and commercial venue operators deploy charging stations as amenity infrastructure.
Automotive commands premium margins; corporate procurement is climbing the fastest.
Distribution Channel:
Channel selection reflects buyer urgency, technical consultation needs, and post-purchase service expectations.
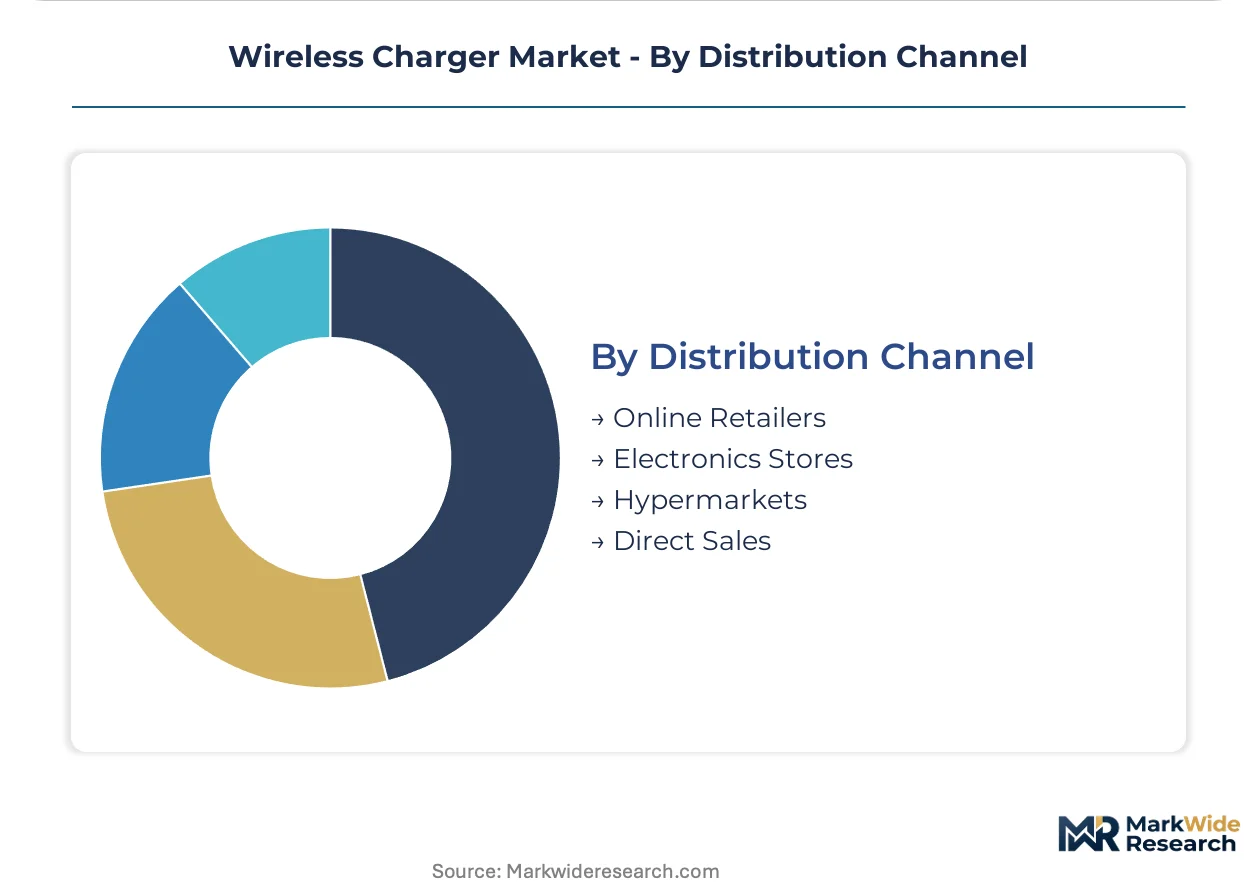
- Online Retailers:Amazon and brand-direct storefronts capture mid-tier volume through GaN-based compact form factors with rapid delivery. Anker specializes in this channel globally, leveraging review aggregation and subscription bundling for repeat purchases.
- Electronics Stores:Physical retail enables hands-on comparison of thermal performance and magnetic alignment precision. Retailers in Germany and France now reject shipments lacking completed EU Radio Equipment Directive compliance folders, compressing time-to-market for non-EU producers.
- Hypermarkets:Mass merchandisers move commodity pads through promotional bundling with smartphone launches.
- Direct Sales:Enterprise and automotive contracts bypass intermediaries for customized thermal engineering and multi-year service agreements.
Online retailers lead transaction volumes; direct sales is expanding most quickly in automotive and enterprise verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Shenzhen, Seoul, and Munich anchor wireless charger development across three continents. These workforce concentrations feed directly into manufacturing ecosystems that shape regional competitive dynamics.
United States
Corporate campus deployments in California and Washington drive desk charger volumes through charging-surface-as-a-service contracts. The FCC's Part 18 restrictions on industrial, scientific and medical equipment frequencies cap power-density scaling for US-bound products. Austin and Detroit host automotive tier-1 engineering centers where NHTSA cabin electronics safety compliance stretches supplier certification timelines.
China
Domestic smartphone brands bundling wireless chargers with flagship launches concentrate demand in Shenzhen and Beijing. MIIT enforces GB electromagnetic compatibility standards that shape coil designs for domestic manufacturers. The Yangtze River Delta manufacturing corridor houses the majority of global coil winding and ferrite processing capacity.
Germany
Automotive OEMs in Baden-Württemberg specify Qi2 for center console modules under KBA safety integration timelines. The EU Radio Equipment Directive mandates CE marking and interoperability disclosure that compresses time-to-market for non-EU producers. Munich and Stuttgart lock in supplier relationships through 18-24 month certification cycles.
South Korea
Semiconductor ecosystem integration from coil design to retail packaging sustains competitive positioning in Seoul and Suwon. METI-aligned technical standards influence regional protocol adoption patterns. The Seoul Capital Area concentrates GaN power electronics research for next-generation transmitter architectures.
India
The PLI scheme for electronics hardware attracts wireless charger assembly operations targeting domestic smartphone bundling contracts. BIS certification requirements shape product configurations for the local market. Tamil Nadu and Karnataka emerge as contract manufacturing hubs for export-oriented production.
Wireless Charger Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the wireless charger value chain. The market structure fragments across coil fabricators, power electronics specialists, and brand-integrated retailers. Three archetypes dominate: semiconductor-integrated conglomerates, GaN-focused compact form factor specialists, and automotive tier-1 module suppliers. Competitive moves concentrate on backward integration into coil materials and strategic partnerships for Qi2 protocol certification.
Within the semiconductor-integrated tier, Samsung Electronics exemplifies captive supply chain control from coil design through retail packaging. Anker occupies the mid-tier channel position through Amazon-centric distribution and subscription bundling. Apple anchors premium pricing architecture through proprietary magnetic alignment ecosystems that compete against open-standard alternatives.
| Leading Market Players |
|---|
| Samsung Electronics |
| Apple |
| Qualcomm Technologies |
| WiTricity |
| Belkin |
| Energizer Holdings |
| Powermat Technologies |
| Anker |
| Delta Electronics |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists in coil fabrication have consolidated ferrite processing capacity across the Yangtze River Delta, tightening supply discipline while enabling coordinated pricing power against downstream brand owners. This ownership concentration feeds directly into margin structures, as captive metallurgical facilities extract rents from GaN power electronics assemblers locked into long-term offtake agreements.
Pricing Analysis
The bundled-vs-unbundled service split separates automotive tier-1 contracts from consumer retail transactions. Automotive procurement runs through multi-year service agreements incorporating thermal engineering support and certification maintenance, while Amazon-centric consumer sales emphasize per-unit transactional pricing with minimal after-sales attachment. Three-tier pricing structure across premium, standard, and economy levels reflects Qi2 certification grade and foreign-object detection precision. Price differentiation hinges on magnetic alignment accuracy and thermal simulation depth. Pricing pressure stems from GaN semiconductor commoditization compressing mid-tier hardware margins. Corporate buyers exhibit lowest price sensitivity due to charging-surface-as-a-service contract structures, while hypermarket consumers drive aggressive promotional bundling demands.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Dongguan have pushed coil winding operations toward automated ferrite core assembly, reducing labor intensity while concentrating technical talent in Qi2 protocol certification labs. China, South Korea, and Vietnam anchor global supply, drawing from copper cathode, manganese-zinc ferrite, and gallium nitride wafer inputs. Single-source vulnerability concentrates in East Asian metallurgical facilities processing specialized ferrite powders. Distribution runs through direct sales for automotive and enterprise verticals, with Amazon and electronics stores capturing consumer volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless charger market functions as a regulatory compounder, where EU Radio Equipment Directive enforcement timelines and NHTSA cabin electronics guidelines create demand acceleration through compliance-driven replacement cycles.
For Market Incumbents: To counter GaN semiconductor commoditization eroding mid-tier margins, Samsung Electronics and Anker should deepen backward integration into ferrite core production and coil winding automation. Certification investment in Qi2 protocol testing laboratories creates defensive moats against emerging entrants lacking capital for multi-standard approval stacking. For New Entrants and Emerging Players: Healthcare sterilization applications represent an underserved buyer archetype with minimal incumbent penetration and premium tolerance for ingress-protected charging surfaces. Surgical equipment manufacturers and patient monitoring device OEMs in Germany and the United States offer white-space expansion with shorter certification cycles than automotive tier-1 qualification. Direct sales partnerships with hospital procurement committees provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among automotive tier-2 module suppliers locked in 18-24 month KBA certification cycles with limited near-term revenue visibility. Long-term viability over the five-to-ten year window rests on Qi2 ecosystem attach rates for magnetic alignment accessories beyond charging pads. The specific signal to watch is NHTSA guideline finalization for cabin electronics safety, which would trigger OEM procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Qi2 Certification Investment | Locks supplier relationships with BMW and Mercedes-Benz under KBA timelines. |
| GaN Power Electronics Transition | Enables compact form factors that compress thermal management differentiation. |
| Healthcare Sterilization Partnership | Opens surgical equipment and patient monitoring categories with premium pricing. |
| Charging-Surface-as-a-Service Launch | Captures California and Washington corporate campus procurement consolidation. |
| India PLI Manufacturing Footprint | Targets domestic smartphone bundling contracts under BIS certification requirements. |
Study Parameters
Coverage spans the United States, China, Germany, South Korea, and India, with primary inputs from each region combining interviews with automotive tier-1 procurement officers, GaN semiconductor R&D directors, electronics store category buyers, and MIIT compliance consultants. Secondary validation draws from FCC Part 18 filings, EU Radio Equipment Directive technical documentation, SEC 10-K disclosures from listed component suppliers, and IHS Markit vehicle production databases. Bottom-up coil shipment modeling triangulates against top-down OEM certification pipeline tracking.
Granularity-level framing segments the market by product type, technology protocol, end-user vertical, and distribution channel, with automotive integration content per vehicle modeled separately. Value projections across the analysis window incorporate GaN adoption curves, Qi2 certification velocity, and regional regulatory enforcement intensity. CAGRs derive from protocol migration rates and automotive production forecasts without year-specific anchoring.
Underlying measurement precision varies by segment; automotive tier-1 volumes carry tighter precision than consumer retail estimates due to visible OEM certification pipelines. Forecasts reflect assumptions about NHTSA guideline finalization timing and EU RED enforcement consistency that could shift with regulatory priority changes. Practitioners should monitor KBA safety integration timeline announcements and MIIT GB standard revision drafts for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
5G Spectrum Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
5G Small Cell Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Wimax Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Underwater Wireless Communication Market