
 Middle East & Africa Video Conferencing Hardware Market | 2026-2036
Middle East & Africa Video Conferencing Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa Video Conferencing Hardware Market Insights
The UAE's Smart Government initiative is broadening procurement criteria for video conferencing hardware across federal ministries and municipal authorities. Cisco Systems Inc. leverages its installed base in oil and gas command centers to sustain recurring upgrade cycles in Abu Dhabi and Dubai. Logitech International SA anchors its position through channel partnerships with regional systems integrators serving mid-market corporate accounts. Huawei Technologies Co. Ltd competes aggressively on price-performance metrics for large-scale government tenders in Saudi Arabia and Egypt.
Video conferencing hardware encompasses dedicated endpoints, cameras, microphones, and codec systems engineered for real-time audiovisual transmission, typically supporting 1080p or 4K resolution with sub-150ms latency for synchronous collaboration. These systems serve commercial and institutional users requiring reliable, secure communication without dependency on consumer-grade software platforms. Integrated systems command the highest average selling prices due to bundled codec, display, and control components demanded by executive boardrooms and telemedicine suites. Cloud-based technology deployments are expanding fastest as enterprises in the UAE and South Africa migrate from legacy ISDN infrastructure to software-defined video collaboration. Corporate end users represent the deepest installed base, though education and healthcare segments are gaining traction through ministry-level bulk purchasing programs.
Saudi Arabia's National Information Center, South Africa's ICASA, and the UAE's Telecommunications and Digital Government Regulatory Authority each enforce type-approval and data-localization requirements that shape hardware certification timelines and feature specifications. BIS-equivalent conformity assessment protocols in Gulf states mandate electromagnetic compatibility and cybersecurity testing before market entry, favoring vendors with established regional testing relationships. Procurement officers and systems integrators must monitor evolving spectrum allocation for wireless video systems and emerging encryption standards that could render current hardware non-compliant.
Market Dynamics
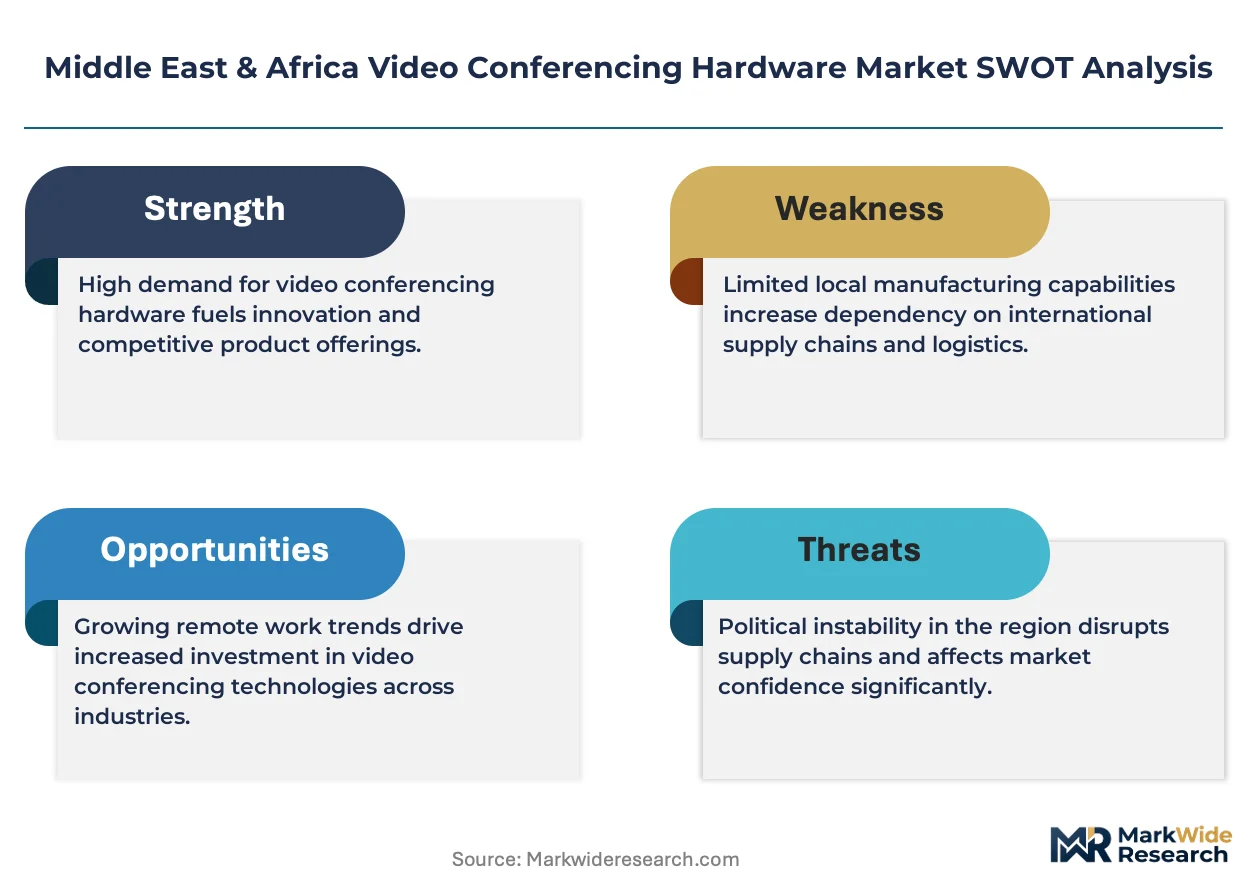
Gulf sovereign mandates for digital government and corporate headquarters modernization are compressing hardware replacement cycles while elevating security certification requirements above price sensitivity.
Growth Catalysts
- Saudi Vision 2030 mandates:Government procurement directives require certified telepresence infrastructure across ministries and state-owned enterprises, creating recurring hardware refresh demand.
- Cloud migration:Enterprises across the UAE and South Africa are abandoning ISDN-based legacy systems for software-defined video collaboration platforms requiring new endpoint hardware.
- Healthcare digitization:Ministry-level bulk purchasing programs in Egypt and Kenya are deploying integrated telemedicine suites with embedded codec systems.
Market Restraints
- Semiconductor supply concentration:Codec processor and image sensor fabrication concentrates in East Asian foundries, exposing lead times to geopolitical friction.
- Data localization compliance:UAE Telecommunications and Digital Government Regulatory Authority type-approval timelines extend 4-8 months for hardware lacking pre-certified encryption modules.
- Consumer-grade substitution:Software-only platforms on commodity laptops erode addressable market for dedicated room systems in sub-50 employee segments.
Strategic Opportunities
- Nigeria's underserved banking sector:Tier-2 financial institutions lack integrated collaboration infrastructure, creating whitespace for mid-market endpoint vendors.
- AI-powered camera framing:Convergence of computer vision chipsets with 4K sensors enables speaker-tracking features without dedicated control room operators.
- Egypt's smart city construction:New administrative capital projects mandate video-enabled municipal services, opening government tender pipelines.
Industry Challenges
- Certification backlog:BIS-equivalent electromagnetic compatibility testing queues in Gulf states delay product launches by 2-3 quarters.
- Integration complexity:Legacy Polycom and Cisco installations require custom middleware for cloud platform interoperability, inflating deployment costs.
- Field engineering scarcity:Shortage of technicians qualified in acoustic calibration and network QoS configuration constrains enterprise rollout velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa Video Conferencing Hardware Market |
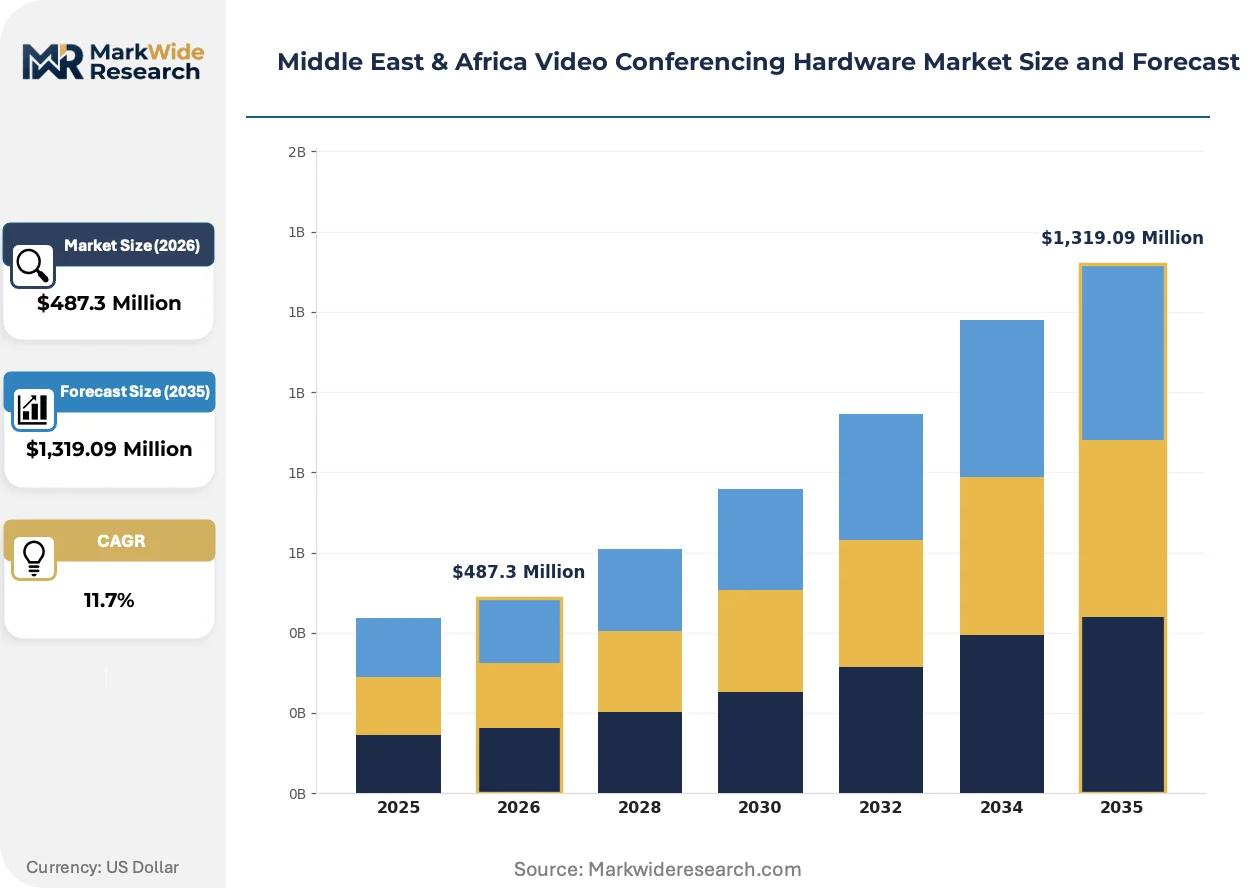
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Systems, Desktop Cameras, Telepresence Solutions, Conference Phones End User: Corporate, Education, Healthcare, Government Technology: Wireless, Wired, Cloud-Based, Hybrid Installation: On-Premise, Remote, Managed Services, DIY |
| Companies Covered | Cisco Systems Inc., Logitech International SA, EPOS, Jabra, Poly Inc., Huawei Technologies Co. Ltd, Crestron Electronics Inc., Microsoft, Avaya, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa Video Conferencing Hardware Market Trends and Innovations
Hardware architectures are pivoting from proprietary closed systems toward modular designs that accommodate rapid software updates and multi-platform interoperability.
USB-C native connectivity is expanding into enterprise room systems, replacing proprietary cable bundles with standardized power, data, and video transmission over single connectors. Mid-market corporate buyers in Dubai and Johannesburg are specifying this flexibility to future-proof against platform churn. The shift is expanding into telepresence suite designs previously dominated by integrated proprietary backbones.
Saudi Arabia's National Information Center has tightened cybersecurity certification protocols for video endpoints processing government data, mandating hardware-rooted encryption and local key storage. Hardware vendors must now submit to penetration testing and source code audits before federal tender eligibility. The policy is compressing vendor qualification timelines and favoring suppliers with established Riyadh testing relationships.
Buying committees in oil and gas conglomerates are unbundling hardware procurement from managed services contracts, separating endpoint ownership from cloud subscription agreements. Systems integrators in Abu Dhabi and Doha are responding with pure resale models and break-fix support tiers. This pattern is most visible among GCC energy sector clients with in-house IT capabilities seeking capital expenditure flexibility.
Middle East & Africa Video Conferencing Hardware Market Segmentation
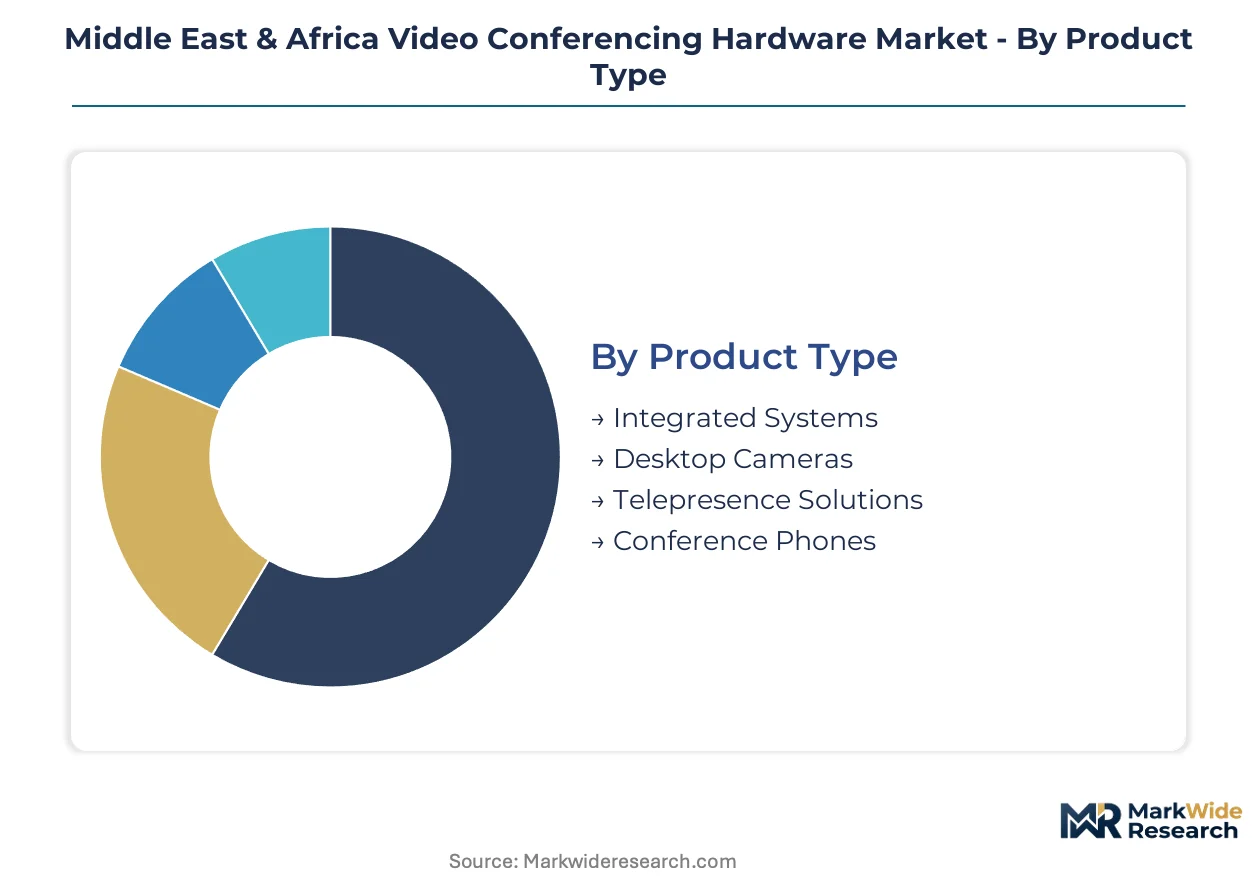
Hardware specification tiers determine procurement workflows across Middle Eastern and African markets. Certification requirements from UAE's Telecommunications and Digital Government Regulatory Authority and Saudi Arabia's National Information Center create divergent compliance pathways by product category.
Product Type:
Resolution standards and codec architecture define the hardware hierarchy, with bundled components commanding distinct average selling price bands.
- Integrated Systems:Bundled codec, display, and control modules engineered for executive boardrooms and telemedicine suites. Demand concentrates in Saudi Aramco headquarters and UAE sovereign wealth fund command centers where sub-150ms latency is mandatory for real-time geological data collaboration.
- Telepresence Solutions:Immersive multi-screen environments with directional audio and life-size video rendering. Procurement cycles accelerate in Riyadh and Dubai government ministries under Saudi Vision 2030 and UAE Smart Government mandates requiring certified federal-grade infrastructure.
- Desktop Cameras:USB-connected peripherals for individual workstations. Nigerian banking sector procurement officers favor these for hybrid trading floor configurations.
- Conference Phones:Audio-centric endpoints with limited video capability. Kenya's Ministry of Health deploys these in rural clinic satellite locations where bandwidth constraints persist.
Mature deployment sits with Integrated Systems. Newer deployment is concentrated in Telepresence Solutions.
End User:
Budget authority and compliance burden vary sharply across institutional buyer types, reshaping vendor qualification requirements.
- Corporate:Oil and gas conglomerates in Abu Dhabi and multinational banks in Johannesburg drive replacement cycles. These buyers unbundle hardware ownership from managed services contracts, seeking capital expenditure flexibility through pure resale models.
- Government:Federal ministries and municipal authorities mandate hardware-rooted encryption and local key storage. Saudi Arabia's National Information Center penetration testing requirements compress vendor qualification timelines to established Riyadh testing relationships.
- Healthcare:Ministry-level bulk purchasing programs in Egypt and Kenya deploy integrated suites for telemedicine. ICASA type-approval delays in South Africa extend procurement cycles for imported codec systems.
- Education:Universities and technical colleges specify USB-C native connectivity for platform interoperability. Dubai's mid-market corporate training centers mirror these specifications.
Corporate buyers anchor volume. Healthcare procurement is climbing the fastest.
Technology:
Connectivity architecture determines interoperability with legacy infrastructure and cloud platform migration pathways.
- Cloud-Based:Software-defined endpoints abandoning ISDN legacy for platform-agnostic collaboration. UAE and South African enterprises lead this migration, requiring new hardware despite sunk costs in proprietary systems.
- Hybrid:Dual-mode systems bridging on-premise infrastructure with cloud subscription services. Cairo's new administrative capital smart city projects mandate this flexibility for municipal service continuity.
- Wireless:Spectrum-dependent systems requiring ICASA and TRA frequency allocation monitoring. Deployment concentrates in Johannesburg flexible office spaces.
- Wired:Ethernet-dependent configurations with deterministic latency. Remains specified in Saudi oil field command centers where electromagnetic interference risks persist.
Wired infrastructure holds existing installed base. Cloud-Based configurations are gaining share fastest.
Installation:
Service model selection reflects internal IT capability depth and total cost of ownership preferences across buyer maturity.
- Managed Services:Full lifecycle contracts including acoustic calibration and network QoS configuration. Doha systems integrators offer these to GCC energy clients lacking qualified field engineering capacity.
- On-Premise:Customer-operated infrastructure with break-fix support tiers. Abu Dhabi oil conglomerates with captive IT departments favor this model for data sovereignty control.
- Remote:Cloud-provisioned configuration with minimal physical deployment. South African mid-market adopters use this to bypass technician scarcity constraints.
- DIY:Self-installation by end users without integrator involvement. Sub-50 employee segments in Lagos and Nairobi select this despite integration complexity risks with legacy Polycom installations.
Managed Services dominates enterprise accounts. DIY procurement shows steepest expansion trajectory in underserved tier-2 markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors procurement velocity across the Middle East & Africa video conferencing hardware market, with Abu Dhabi and Riyadh corridors generating comparable contract volumes through sovereign wealth fund and government ministry mandates.
United Arab Emirates
Federal ministries and municipal authorities under the Smart Government initiative drive certified hardware procurement cycles. MOHAP mandates hardware-rooted encryption for healthcare endpoints processing patient data. Dubai's International Financial Centre concentrates multinational bank headquarters modernizing collaboration infrastructure.
Saudi Arabia
Saudi Aramco headquarters and state-owned enterprise command centers generate demand for sub-150ms latency telepresence systems. The National Information Center enforces penetration testing and source code audits before federal tender eligibility. Riyadh's King Abdullah Financial District anchors corporate deployment of executive boardroom suites.
South Africa
Johannesburg multinational banks and Cape Town corporate campuses drive replacement cycles from legacy ISDN infrastructure. ICASA type-approval timelines extend procurement cycles for imported codec systems lacking pre-certified encryption modules. Mid-market adopters in Gauteng bypass technician scarcity through remote cloud-provisioned configuration.
Egypt
Ministry-level bulk purchasing programs deploy integrated telemedicine suites with embedded codec systems in Cairo and Alexandria healthcare networks. The new administrative capital smart city projects mandate hybrid connectivity architecture for municipal service continuity. Government tender pipelines favor vendors with established Cairo testing relationships.
Nigeria
Tier-2 financial institutions in Lagos lack integrated collaboration infrastructure, creating whitespace for mid-market endpoint vendors. Central Bank procurement guidelines shape hardware certification requirements for banking sector deployments. Lagos Island commercial clusters specify USB-C native connectivity for trading floor hybrid configurations.
Middle East & Africa Video Conferencing Hardware Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and government testing relationships. The vendor base stratifies into three tiers: established integrators with sovereign wealth fund installed bases, mid-market specialists serving corporate accounts through channel partnerships, and price-competitive challengers targeting large-scale government tenders. Archetypes include legacy infrastructure incumbents defending upgrade cycles, modular platform specialists capturing cloud migration demand, and vertically integrated electronics conglomerates bundling network infrastructure with endpoints. Dominant competitive moves encompass geographic expansion through Riyadh and Dubai testing facility investments, plus portfolio diversification into AI-powered camera framing and speaker-tracking features.
Within the established integrator tier, Cisco Systems Inc. and Logitech International SA occupy positions shaped by contrasting channel strategies. Cisco leverages installed base relationships in Abu Dhabi oil and gas command centers to sustain recurring upgrade cycles. Logitech anchors market presence through regional systems integrator partnerships serving mid-market corporate accounts in Dubai and Johannesburg. Huawei Technologies Co. Ltd exemplifies the price-competitive challenger archetype, competing on price-performance metrics for Saudi Arabia and Egypt government tenders.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Logitech International SA |
| EPOS |
| Jabra |
| Poly Inc. |
| Huawei Technologies Co. Ltd |
| Crestron Electronics Inc. |
| Microsoft |
| Avaya |
| Others |
Pricing and Supply Chain Analysis
Codec processor fabrication costs in Taiwanese and South Korean foundries cascade through hardware tiering, with 4K image sensor modules commanding premium placement in Saudi Aramco telepresence suites while USB-C peripherals compete on volume economics in Lagos banking floors.
Pricing Analysis
Hardware-rooted encryption certification anchors value-based pricing for federal-grade endpoints, separating premium telepresence systems from mid-market conference room bundles. Pricing stratifies across federal-certified, enterprise-standard, and SMB-economy tiers, with Saudi NIC penetration testing requirements widening spreads between compliant and non-compliant suppliers. Cost compression in the mid-market tier intensifies because Huawei's price-performance positioning forces margin concessions from established integrators. Corporate oil and gas buyers in Abu Dhabi exhibit lowest price sensitivity due to sovereignty mandates, while Nigerian tier-2 banks represent the most price-constrained segment.
Supply Chain Analysis
Image sensor supply rests on Japanese and South Korean specialty semiconductor producers, with 4K CMOS fabrication concentrated in Sony and Samsung foundries. Codec processor dependencies draw from Taiwan Semiconductor Manufacturing and Intel's Malaysian packaging facilities, while rare earth magnet sourcing for speaker assemblies hinges on Chinese refining capacity. Single-source vulnerability in advanced node fabrication exposes lead times to geopolitical friction across the Taiwan Strait. Distribution runs through Dubai-based systems integrators serving GCC corridors and Johannesburg channel partners covering sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's National Information Center penetration testing mandates erect a cost-of-compliance barrier that favors incumbents with established Riyadh testing relationships, compressing qualification timelines for new entrants lacking federal-grade certification infrastructure.
For Market Incumbents: Anticipate margin pressure from Huawei's aggressive tender positioning in Egypt and Saudi Arabia by deepening backward integration into codec chipset sourcing and accelerating AI-powered camera framing R&D. Secure channel control through exclusive partnerships with Abu Dhabi systems integrators before cloud-native competitors unbundle hardware from managed services contracts. For New Entrants and Emerging Players: Capture whitespace in Nigeria's tier-2 banking sector and Kenya's rural healthcare satellite locations where integrated collaboration infrastructure remains underdeployed. The most penetrable entry point sits with USB-C native desktop cameras for hybrid trading floor configurations, leveraging remote cloud-provisioned configuration to bypass Johannesburg technician scarcity. For Investors and Strategic Acquirers: Federal ministry tender announcements in Cairo's new administrative capital is the leading indicator that hybrid connectivity architecture demand is inflecting toward government-grade specifications. Long-term viability favors acquisition targets with established testing relationships in Riyadh, Dubai, and Cairo plus modular platform architectures accommodating rapid software updates. Watch for ICASA type-approval backlog clearance as the signal that South African enterprise replacement cycles are accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| Riyadh Testing Facility Investment | Accelerates Saudi NIC penetration testing timelines for federal tender eligibility. |
| AI-Powered Camera Framing Launch | Enables speaker-tracking features without dedicated control room operators in Dubai headquarters. |
| USB-C Native Connectivity Expansion | Future-proofs mid-market endpoints against platform churn in Johannesburg corporate campuses. |
| Cloud Migration Partnership | Captures ISDN replacement demand across UAE and South African enterprise accounts. |
| Telemedicine Suite Integration | Addresses Egypt and Kenya ministry-level bulk purchasing program requirements. |
Research Methodology
Multi-period observation of hardware certification timelines, federal tender award patterns, and channel inventory flows anchored the trend analysis, supplemented by interviews with systems integrators in Dubai and Riyadh, procurement officers at Saudi Aramco and UAE sovereign wealth funds, and regulatory affairs specialists at the National Information Center. Secondary validation drew from TRA type-approval databases, ICASA electromagnetic compatibility filings, customs import records for codec systems, and hyperscaler capex disclosures for cloud collaboration infrastructure. Bottom-up endpoint shipment estimates triangulated against top-down government procurement budget allocations.
Segment-weighting across product type, end user, technology, and installation service models structured the analytical framework over the projection horizon. Hardware specification tiers, resolution standards, and compliance pathways formed core segmentation dimensions alongside regional regulatory cluster differentiation. CAGRs derived from install base migration rates, replacement cycle compression, and sovereign mandate procurement velocity. Forecast inputs incorporated cloud platform adoption curves and field engineering capacity constraints.
The model holds under stable geopolitical conditions for Taiwan Strait semiconductor supply; deviation in foundry access restrictions or Gulf state data-localization enforcement would shift hardware availability and certification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Mobile Backhaul Market
Network Technology
Enterprise Routers Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Europe SD-WAN Market
Network Technology
RTP Market
Network Technology
Global Self-Organizing Network Market
Network Technology
Enterprise Network Equipment Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Intelligent Network Management Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
Global Managed Wi-Fi Solutions Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Network Management Solutions Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
Open RAN Market
Network Technology
Cloud Gateway Module Market