
 Enterprise Routers Market | 2026-2036
Enterprise Routers Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Routers Market Analysis
The 400G port-density tier is collapsing the performance-per-watt gap between core and edge routing architectures. Cisco Systems leverages captive silicon development to sustain margin structures across enterprise and service provider accounts. Juniper Networks anchors its position through Contrail software stacks that unify physical and virtual routing planes. Arista Networks differentiates via cloud-optimized platforms purpose-built for hyperscale data center interconnects.
Enterprise routers are Layer 3 network devices that forward data packets between computer networks using routing tables, BGP and OSPF protocols, and hardware-accelerated forwarding engines operating at throughputs from 1 Gbps to multi-terabit chassis densities. Their primary commercial purpose is to enable secure, scalable interconnection across corporate branch offices, data centers, and cloud service endpoints. Modular router platforms command the deepest margin pools due to serviceable lifecycles exceeding seven years and recurring software subscription attach rates. Virtual routers are capturing the fastest expansion trajectory as NFV deployments displace purpose-built hardware in cloud-native environments. Fixed routers retain volume dominance in SME branch deployments where port-count requirements remain below forty-eight interfaces.
The FCC enforces equipment authorization standards under Title 47 CFR Part 15 that constrain electromagnetic emissions profiles and spectrum coexistence behaviors for wireless-enabled enterprise routers. The EU AI Act and NIS2 Directive are imposing cybersecurity certification requirements that reshape product development roadmaps for vendors seeking European market access. India's BIS mandates compulsory registration for networking equipment under the Electronics and Information Technology Goods Order, creating compliance friction for non-domestic suppliers. Stakeholders must monitor how sovereign data routing mandates in Brazil, Saudi Arabia, and Vietnam are fragmenting previously unified product certification pathways.
Market Dynamics
400G port-density tiers are collapsing the performance-per-watt gap between core and edge routing architectures, forcing vendors to consolidate silicon roadmaps and compress hardware refresh cycles across enterprise and service provider deployments.
Growth Catalysts
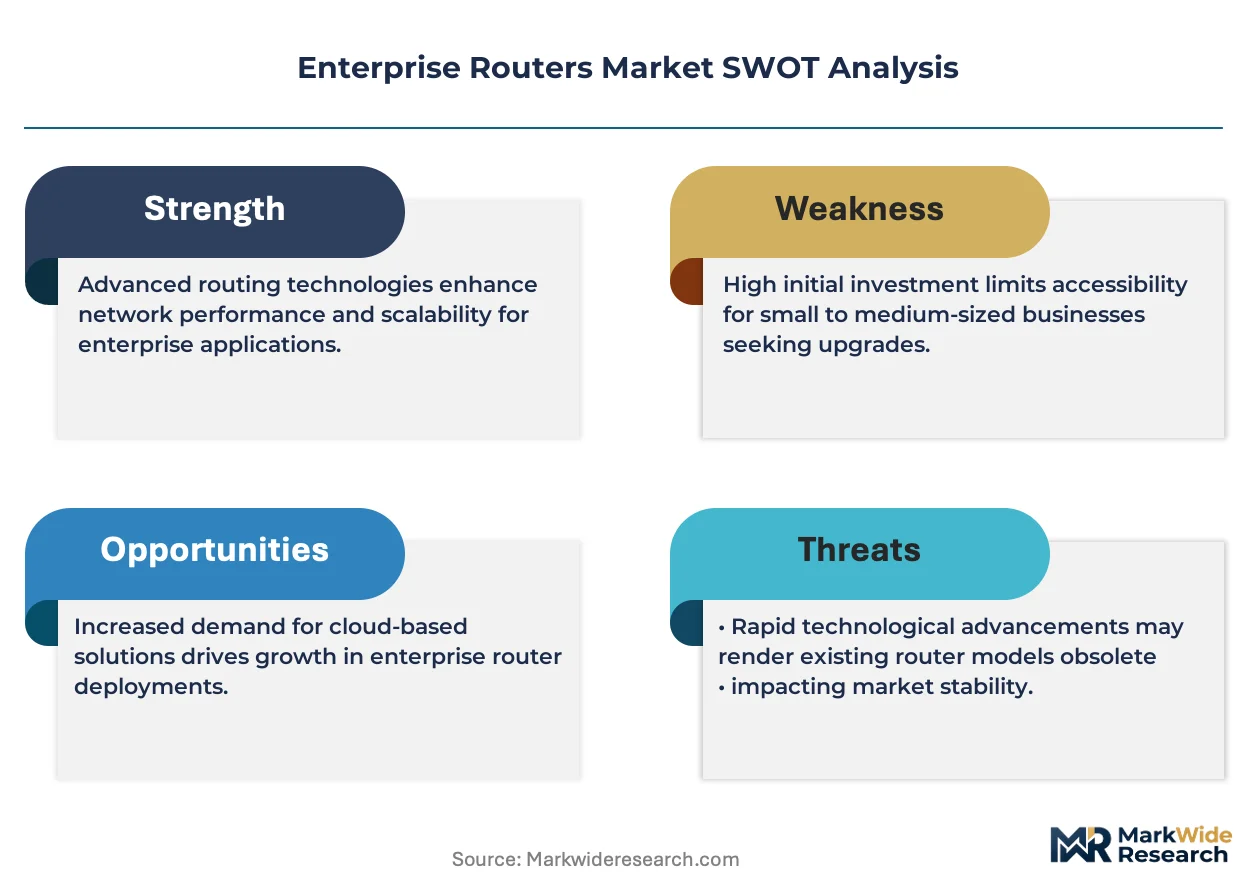
- SD-WAN adoption in financial services:Banks and insurance carriers are replacing MPLS backbones with software-defined overlays to reduce branch connectivity costs and improve cloud application performance.
- FCC broadband infrastructure mandates:Title 47 CFR Part 15 equipment authorization standards are accelerating replacement cycles for wireless-enabled enterprise routers across United States telecommunications infrastructure.
- India data center buildouts:Mumbai, Hyderabad, and Bangalore clusters are driving demand for high-density routing platforms as hyperscale facilities expand interconnection capacity.
Market Restraints
- Silicon supply concentration:Advanced routing ASIC fabrication depends on a concentrated foundry base in Taiwan, creating geopolitical exposure for chassis manufacturers.
- BIS registration friction:India's Electronics and Information Technology Goods Order imposes compulsory certification timelines that delay market entry for non-domestic equipment suppliers.
- Copper and rare earth input volatility:Chassis manufacturing faces cost pressure from fluctuating commodity prices for power supply components and thermal management materials.
Strategic Opportunities
- Hyperscale data center interconnects:Cloud-optimized platforms purpose-built for east-west traffic patterns are capturing expansion in multi-tenant facilities.
- EU AI Act certification pathways:Cybersecurity certification requirements under NIS2 Directive are creating first-mover advantages for vendors with pre-validated product roadmaps.
- NFV displacement of purpose-built hardware:Virtual routers are expanding fastest in cloud-native environments where containerized network functions reduce capital intensity.
Industry Challenges
- Embedded systems security engineering:Vendors face acute shortages of firmware developers capable of implementing zero-trust architectures at the hardware layer.
- Sovereign data routing fragmentation:Brazil, Saudi Arabia, and Vietnam are imposing divergent data localization mandates that splinter previously unified product certification pathways.
- Legacy BGP-OSPF integration complexity:Enterprises struggle to maintain protocol interoperability during multi-year migrations from hardware-centric to software-defined routing stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Routers Market |
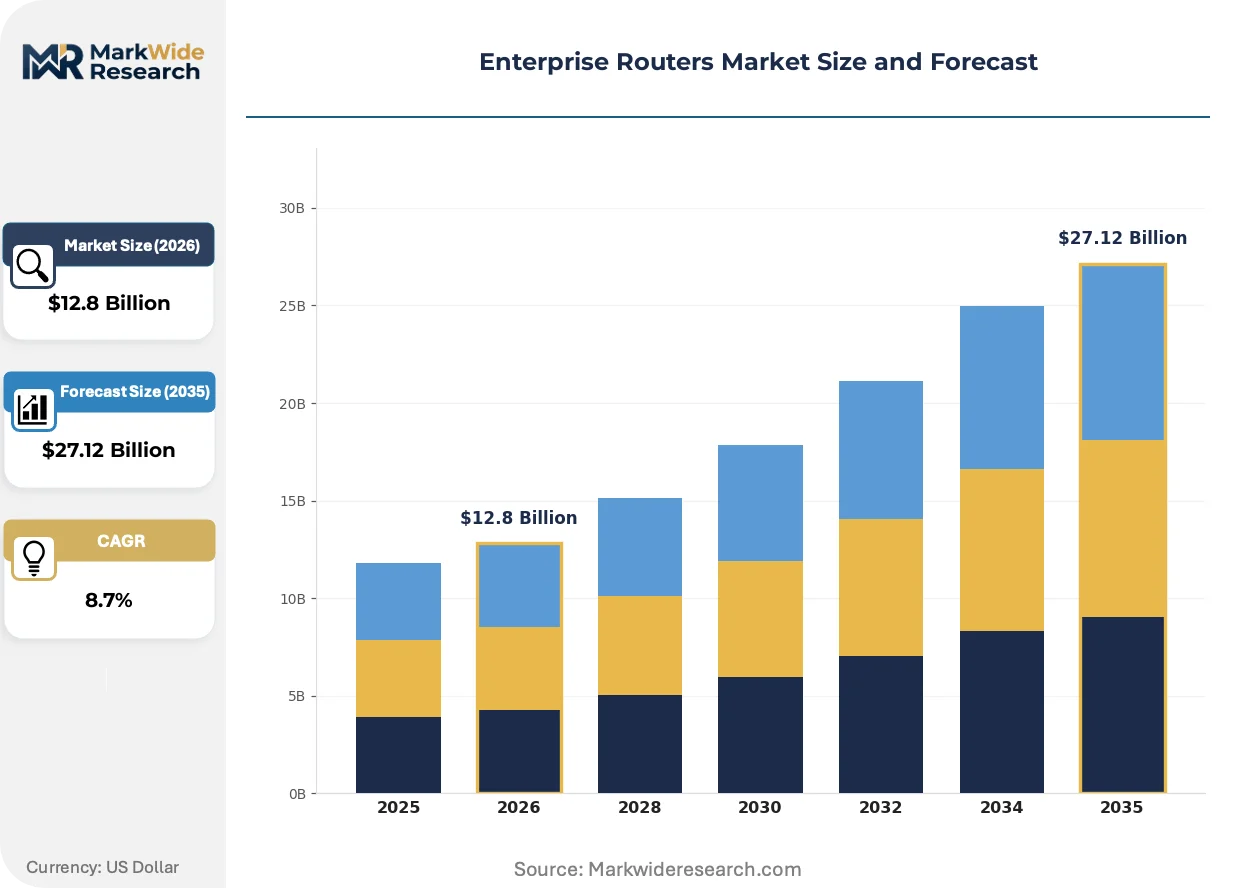
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Routers, Modular Routers, Virtual Routers, Cloud Routers Connectivity: Wired, Wireless, Fiber Optic, Satellite Installation: On-Premises, Cloud-Based, Hybrid, Remote End User: SMEs, Large Enterprises, Government, Educational Institutions |
| Companies Covered | Arista Networks, Extreme Networks, Cisco Systems, Fortinet, Nokia, Juniper Networks, Hewlett Packard Enterprise, Ubiquiti, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Routers Market Emerging Trajectories
Silicon consolidation and regulatory fragmentation are simultaneously compressing hardware differentiation and expanding compliance complexity across vendor portfolios.
Merchant silicon with programmable forwarding pipelines is supplanting custom ASIC development in mid-range enterprise routers. Tier-two cloud service providers and large financial institutions are adopting these platforms to reduce supply chain dependency on single-vendor captive silicon. This shift is enabling faster feature velocity but compressing gross margins for traditional chassis manufacturers who previously relied on proprietary silicon lock-in.
The EU AI Act and NIS2 Directive are imposing mandatory cybersecurity certification requirements that reshape product development roadmaps. European market access now requires documented secure-by-design processes and third-party penetration testing before equipment authorization. Vendors targeting Germany, France, and Netherlands enterprise accounts are accelerating firmware hardening investments to meet these pre-market validation timelines.
Subscription-based software licensing is displacing perpetual hardware-plus-software bundles in procurement negotiations. Large enterprise buyers in United States healthcare and United Kingdom financial services are unbundling support contracts and feature licenses from chassis purchases. This pattern is most visible in modular router platforms where serviceable lifecycles exceed seven years and recurring attach rates determine vendor profitability.
Enterprise Routers Market Segmentation
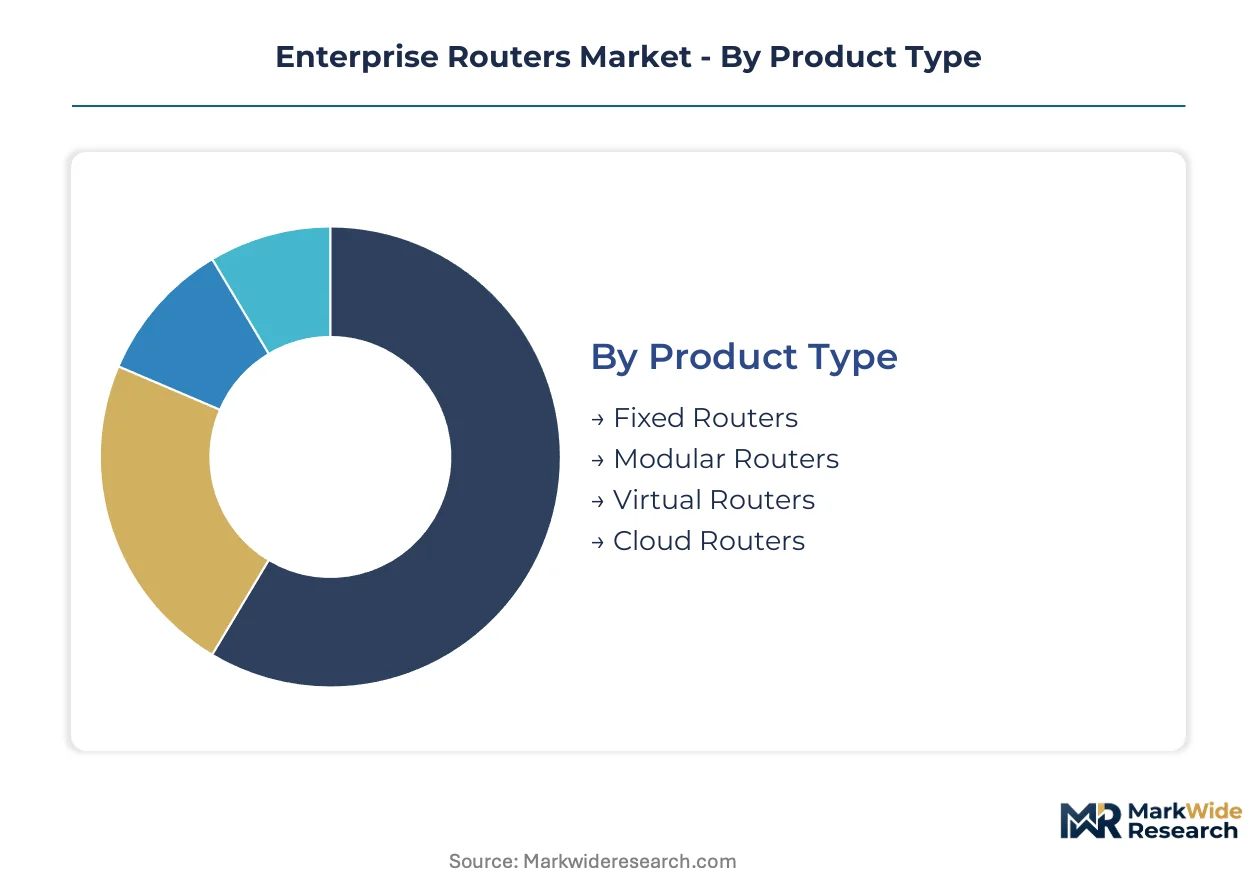
Enterprise router procurement patterns diverge sharply across deployment scale, connectivity requirements, and infrastructure maturity. Segmentation reveals how vendor portfolios must stretch from commodity branch hardware to programmable cloud-native platforms serving multi-terabit interconnects.
Product Type:
Domestic demand concentrates in fixed and modular platforms for branch and campus consolidation, while virtual and cloud router expansion is export-led through hyperscale data center operators with global footprints.
- Fixed Routers:Non-upgradable chassis with fixed port configurations serve SME branch offices where interface counts remain below forty-eight. United States healthcare networks favor these units for clinic deployments requiring rapid provisioning without field engineering support. FCC equipment authorization mandates under Title 47 CFR Part 15 compress procurement timelines for wireless-enabled variants.
- Modular Routers:Serviceable chassis with replaceable line cards command the deepest margin pools through seven-plus year lifecycles and recurring software subscription attach rates. Indian data center buildouts in Mumbai and Hyderabad drive demand for high-density variants supporting 400G port aggregation.
- Virtual Routers:NFV-based software instances displace purpose-built hardware in cloud-native environments where containerized network functions reduce capital intensity. Expansion concentrates among European financial institutions unbundling hardware from software licensing.
- Cloud Routers:Managed routing services delivered through hyperscale provider marketplaces eliminate on-premises hardware ownership. United Kingdom enterprise buyers in professional services sectors favor consumption-based pricing models.
Modular routers hold the largest share; momentum sits with virtual routers.
Connectivity:
Cost tiering separates premium fiber deployments from economy wireless configurations, with satellite emerging as a mid-tier failover option for remote infrastructure.
- Wired:Copper and fiber Ethernet interfaces dominate campus and data center interconnects requiring deterministic latency. German automotive manufacturers specify wired backbones for factory floor automation networks.
- Wireless:LTE and 5G-enabled routers serve mobile branch deployments and temporary construction sites across Saudi Arabia's giga-project developments. TRAI spectrum allocations in India are expanding addressable markets for cellular-backhaul variants.
- Fiber Optic:Single-mode and multi-mode optical interfaces support 100G and 400G densities in hyperscale facilities. Demand clusters in Bangalore's Whitefield and Electronic City corridors where inter-building fiber counts exceed ten thousand strands.
- Satellite:Low-earth orbit and geostationary links provide connectivity for mining operations and maritime vessels outside terrestrial coverage. Brazilian agribusiness operators deploy these units across Mato Grosso soy belt regions lacking fiber infrastructure.
Fiber optic commands the highest unit economics; satellite is climbing the fastest.
Installation:
Application context determines whether enterprises prioritize physical control, cloud agility, or transitional hybrid architectures.
- On-Premises:Physical hardware deployment in customer-controlled facilities satisfies data residency requirements and sub-millisecond latency demands. Vietnam's banking sector mandates on-premises routing for core transaction processing under sovereign data localization rules.
- Cloud-Based:Fully managed routing functions delivered through SaaS consoles eliminate hardware procurement cycles. French retail chains favor these deployments for rapid international expansion without local engineering presence.
- Hybrid:Split traffic processing across on-premises and cloud instances enables gradual migration from legacy MPLS to SD-WAN overlays. United States insurance carriers adopt this architecture during multi-year branch network refresh programs.
- Remote:Zero-touch provisioning and centralized policy management support distributed workforces without IT staff at every location. Australian mining companies deploy remote-managed routers across Pilbara extraction sites.
Hybrid installations retain the largest footprint; cloud-based routing is gaining share fastest.
End User:
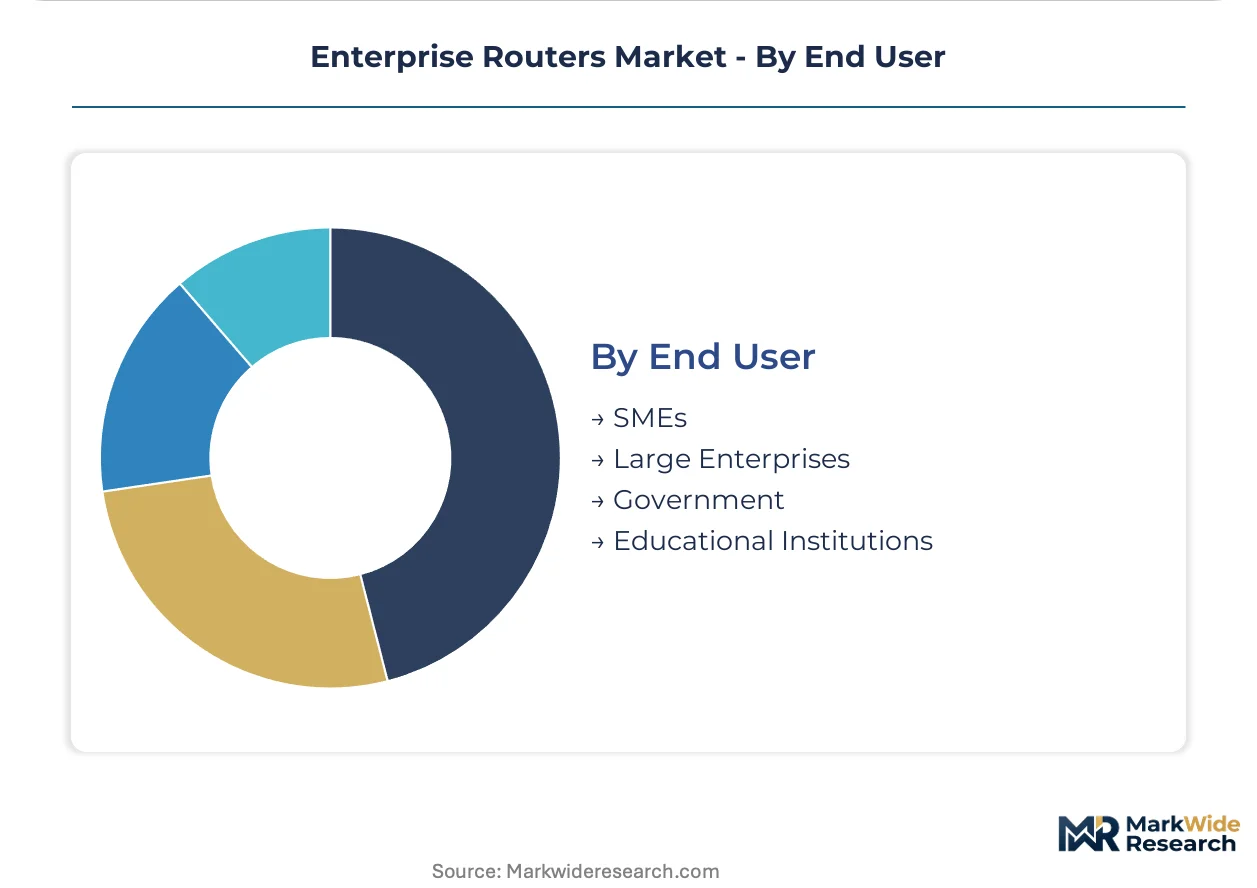
Customer type segmentation maps directly to procurement sophistication, with government and education segments requiring specialized certification pathways.
- SMEs:Organizations below five hundred employees prioritize capital efficiency and simplified management over feature depth. Fixed wireless routers with integrated security stacks dominate procurement across United States professional services firms.
- Large Enterprises:Multi-site corporations with dedicated network engineering teams demand programmable platforms supporting BGP, OSPF, and EVPN protocols. Japanese automotive suppliers specify these capabilities for just-in-time manufacturing network segmentation.
- Government:Public sector procurement requires Common Criteria certification and domestic manufacturing preferences. India's BIS compulsory registration scheme filters non-compliant vendors from defense and civilian agency tenders.
- Educational Institutions:Universities and K-12 districts balance density requirements against constrained capital budgets. South Korean research universities drive demand for 100G-capable modular platforms supporting high-performance computing interconnects.
Large enterprises hold the largest share; government verticals are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced routing ASIC fabrication concentrates in Taiwan, creating geopolitical exposure that shapes procurement patterns across chassis manufacturers. Enterprise router demand clusters in five national markets where data center buildouts, regulatory mandates, and connectivity infrastructure investments are accelerating replacement cycles.
United States
Financial services firms are scaling software-defined WAN deployments to replace MPLS backbones. FCC equipment authorization standards under Title 47 CFR Part 15 compress procurement timelines for wireless-enabled variants. Silicon Valley hyperscale facilities and Dallas-Fort Worth data center corridors drive demand for 400G-capable modular platforms.
Germany
Automotive manufacturers specify wired backbones for factory floor automation networks requiring deterministic latency. EU AI Act and NIS2 Directive cybersecurity certification requirements reshape product development roadmaps for European market access. Frankfurt and Munich financial centers anchor demand for programmable platforms supporting BGP and EVPN protocols.
India
Hyperscale data center buildouts intensify across Mumbai, Hyderabad, and Bangalore clusters. BIS compulsory registration under the Electronics and Information Technology Goods Order creates compliance friction for non-domestic suppliers. Whitefield and Electronic City corridors in Bangalore exceed ten thousand fiber strands driving 100G and 400G density requirements.
Brazil
Sovereign data routing mandates fragment previously unified product certification pathways for equipment suppliers. ANVISA and national telecom regulator frameworks impose divergent validation timelines. Agribusiness operators across Mato Grosso soy belt regions deploy satellite-enabled routers where fiber infrastructure remains absent.
Saudi Arabia
Giga-project developments drive mobile branch deployments requiring LTE and 5G-enabled routers for temporary construction sites. SFDA and national cybersecurity frameworks impose equipment authorization requirements. NEOM Northwest and Riyadh corridor developments concentrate demand for remote-managed zero-touch provisioning platforms.
Enterprise Routers Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the enterprise router market. The vendor base spans captive silicon developers, merchant silicon adopters, and software-centric challengers competing across distinct margin pools. Three strategic archetypes dominate: proprietary silicon incumbents defending serviceable lifecycle economics, cloud-optimized specialists capturing hyperscale interconnect expansion, and virtual router pure-plays displacing hardware in NFV environments. Competitive intensity centers on M&A activity consolidating software stacks and strategic partnerships unifying physical and virtual routing planes.
Among North American networking incumbents, Cisco Systems and Juniper Networks exemplify divergent strategic positions within the proprietary silicon tier. Cisco leverages captive silicon development to sustain margin structures across enterprise and service provider accounts. Juniper anchors its position through Contrail software stacks. Arista Networks occupies a distinct cloud-optimized position purpose-built for hyperscale data center interconnects. These three represent how vendor portfolios must stretch from commodity branch hardware to programmable multi-terabit platforms.
| Leading Market Players |
|---|
| Arista Networks |
| Extreme Networks |
| Cisco Systems |
| Fortinet |
| Nokia |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Ubiquiti |
| Huawei Technologies |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Taiwan-based foundries lock in both advanced routing ASIC supply access and multi-year price visibility for chassis manufacturers serving hyperscale data center operators. These arrangements insulate procurement teams from spot-market silicon volatility while embedding volume commitments that reshape working capital requirements across vendor balance sheets.
Pricing Analysis
FCC equipment authorization standards under Title 47 CFR Part 15 dictate the pricing tier structure for wireless-enabled enterprise routers in United States deployments. Three-tier pricing structure across premium, standard, and economy levels separates modular platforms with 400G densities from fixed-configuration branch units and virtualized NFV instances. Cost compression in the fixed-router tier is intensifying because merchant silicon adoption erodes proprietary ASIC lock-in advantages. SME healthcare networks exhibit the highest price sensitivity, while hyperscale cloud operators negotiating direct silicon partnerships demonstrate the least.
Supply Chain Analysis
Taiwan Strait transit vulnerabilities expose enterprise router supply chains to geopolitical disruption risks that could sever advanced ASIC fabrication flows. Manufacturing draws from Taiwan, South Korea, and United States for leading-edge silicon, with Malaysia and Mexico handling final chassis assembly. Copper power supply components, rare earth thermal management materials, and optical transceiver modules constitute critical input dependencies. Single-source vulnerability concentrates in TSMC's 7nm and 5nm process nodes for high-density routing silicon. Distribution runs through authorized value-added resellers and direct hyperscale procurement teams rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise router procurement power is consolidating among hyperscale cloud operators and multi-national financial institutions capable of unbundling hardware from software licensing. This buyer concentration fragments vendor pricing power and accelerates subscription-based contracting adoption.
For Market Incumbents: Shield recurring revenue streams by deepening captive silicon differentiation through programmable forwarding pipeline investments that merchant silicon cannot replicate. Accelerate Contrail-class software stack development to anchor physical-virtual routing plane unification before NFV pure-plays capture cloud-native displacement. Prioritize BIS pre-registration in India to neutralize compliance friction against domestic challengers.
For New Entrants and Emerging Players: Lead with satellite-enabled wireless routers targeting Brazilian agribusiness and Saudi giga-project construction sites where terrestrial fiber remains uneconomical. Exploit India's BIS registration delays affecting incumbent market entry by establishing local assembly partnerships that satisfy Electronics and Information Technology Goods Order domestic content requirements. Position through zero-touch provisioning capabilities that eliminate field engineering dependencies for remote-managed deployments.
For Investors and Strategic Acquirers: Cloud-native virtual router pure-plays with containerized network function expertise represent the most defensible acquisition archetype for the NFV displacement wave. Monitor hyperscale capex disclosure trends as the inflection signal indicating 400G port-density refresh cycle timing. Long-term viability hinges on software subscription attach rates exceeding hardware lifecycle erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Platform Adoption | Tier-two cloud providers reduce single-vendor dependency while compressing incumbent gross margins. |
| EU NIS2 Certification Pre-Validation | First-mover vendors secure German and French enterprise procurement ahead of mandatory cybersecurity deadlines. |
| Subscription Licensing Unbundling | United States healthcare and United Kingdom financial services buyers separate support contracts from chassis purchases. |
| Hyperscale Data Center Interconnect Expansion | Bangalore Electronic City and Mumbai corridors drive 400G density demand for cloud-optimized platforms. |
| Zero-Touch Provisioning Capability Buildout | Australian mining and Saudi NEOM projects require remote-managed routers without distributed IT staffing. |
Methodological Framework
The analysis maps fixed, modular, virtual, and cloud router sub-sectors, each validated through network engineering directors, hyperscale procurement officers, and value-added reseller channel heads. Primary interviews with data center facility planners, enterprise IT infrastructure leads, and telecommunications equipment authorization specialists combine with secondary validation against FCC equipment authorization databases, BIS compulsory registration filings, EU AI Act implementation guidance, and hyperscaler capital expenditure disclosures. Bottom-up router shipment modeling and top-down infrastructure investment triangulation ensure cross-verified outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, connectivity interface, installation architecture, and end-user scale tier. CAGRs were derived from replacement cycle analysis, regulatory mandate acceleration effects, and data center buildout pipeline tracking. Forecast inputs incorporate FCC broadband infrastructure spending trajectories, India PLI scheme localization incentives, and sovereign data routing mandate proliferation patterns.
Underlying assumptions cover stable Taiwan-based foundry operations, continued EU cybersecurity certification trajectory, and India BIS registration process timelines, with deviation risk concentrated in geopolitical supply disruption and divergent national data localization enforcement. Practitioners should keep alternative scenarios live as foundry concentration and sovereign routing mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Carrier Routing Equipment Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Global LWAN Market
Network Technology
Mobile Network Optimization Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Unified Network Management Market
Network Technology
Global Industrial Ethernet Switch Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
IT Connector Market
Network Technology
WAN Optimization Controllers Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Cloud Gateway Module Market
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
Residential Routers Market
Network Technology
Global Network Switches Market
Network Technology
Global Private 5G Network Market