
 US Pharmaceutical Analytical Testing Outsourcing Market | 2026-2036
US Pharmaceutical Analytical Testing Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
US Pharmaceutical Analytical Testing Outsourcing Market Intelligence
High-resolution mass spectrometry paired with automated sample handling is rewriting the economics of analytical testing for complex biologics. Eurofins Scientific leverages its distributed US laboratory footprint to anchor stability testing contracts with mid-tier biotech sponsors. Charles River Laboratories specializes in integrated safety and analytical packages that extend its value proposition beyond discrete testing into full program support.
US pharmaceutical analytical testing outsourcing encompasses the transfer of chemistry, manufacturing, and controls verification—spanning identity, purity, potency, and stability assessment—to third-party laboratories equipped with validated instrumentation and GLP-certified protocols. Chromatographic separation via HPLC and UHPLC platforms remains the workhorse methodology, with method development cycles typically spanning eight to sixteen weeks depending on molecule complexity and forced-degradation study design. Biologics and biosimilars now command the fastest-growing share of outsourced analytical workload, reflecting the structural shift from small-molecule blockbusters to monoclonal antibodies and cell-culture-derived therapies where impurity profiling demands orthogonal detection strategies. Stability testing generates the most recurring revenue within service portfolios, as ICH Q1A(R2) zone-defined storage conditions mandate multi-year commitment cycles that lock in long-term client relationships.
FDA oversight through current Good Manufacturing Practice enforcement and the agency's emerging guidance on continuous manufacturing validation directly shapes laboratory qualification requirements and data integrity expectations. CDER's Quality Management Maturity program and USP general chapters on analytical instrument qualification create compliance layers that smaller sponsors increasingly outsource rather than maintain in-house. Stakeholders must weigh capital deployment against partnership depth as instrument refresh cycles compress and regulatory documentation burdens intensify.
Market Dynamics
The FDA's Quality-by-Design initiative and ICH Q14 guideline evolution are compressing sponsor-CRO relationships into deeper, longer-term partnerships that embed analytical development earlier in drug discovery cycles.
Growth Catalysts
- Biologics Pipeline Expansion:Monoclonal antibodies and cell-culture-derived therapies now dominate development pipelines, creating demand for orthogonal impurity profiling that exceeds in-house capabilities of mid-tier sponsors.
- FDA Quality Management Maturity Program:CDER's rating system incentivizes sponsors to outsource compliance-heavy analytical instrument qualification and data integrity documentation to specialized laboratories.
- Massachusetts and North Carolina Cluster Density:Concentrated biopharma manufacturing hubs in these states sustain dense outsourcing networks that reduce logistics costs and accelerate method transfer timelines.
Market Restraints
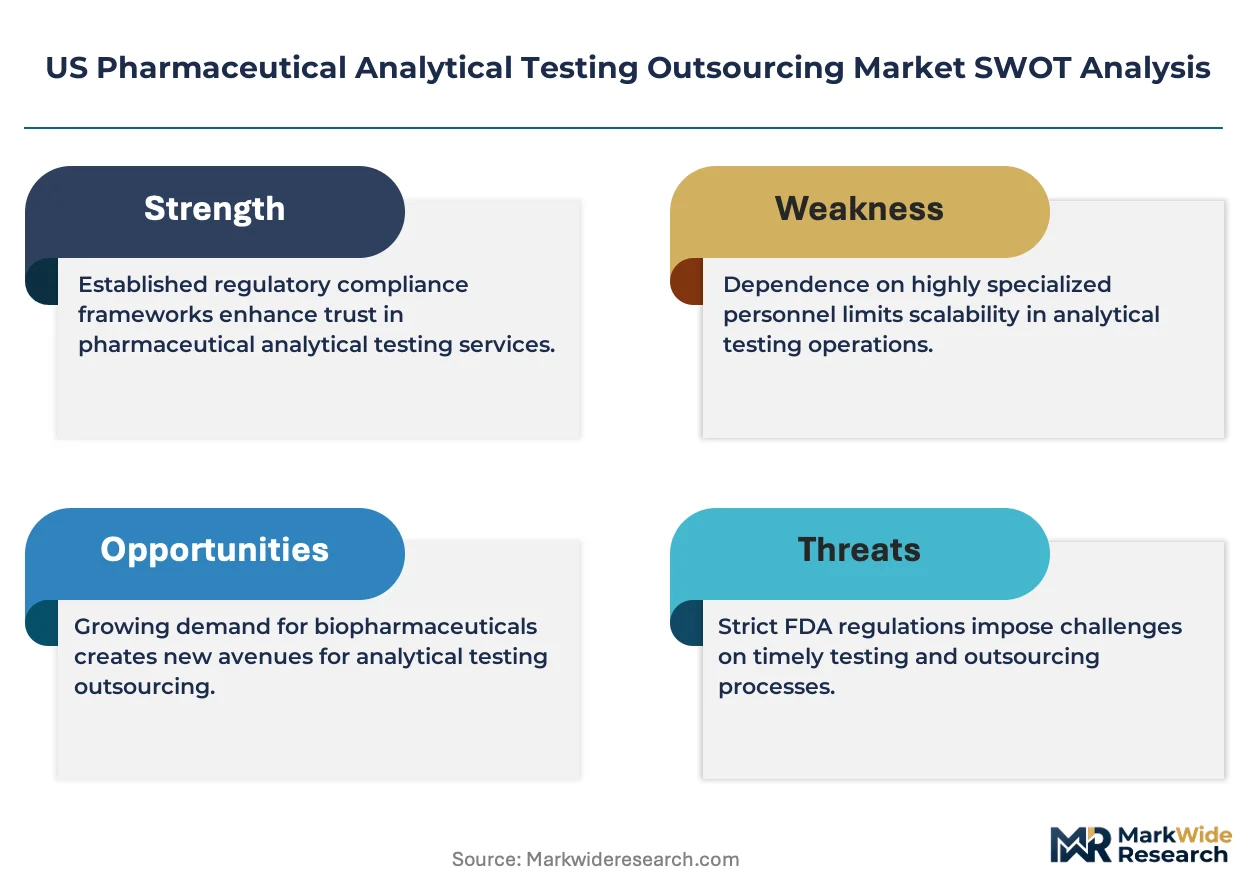
- Specialized Talent Scarcity:Qualified mass spectrometrists and chromatography method developers command premium compensation that inflates service provider operating costs.
- Instrument Capital Intensity:High-resolution mass spectrometry platforms and automated sample handling systems require refresh cycles under five years, straining smaller laboratory balance sheets.
- Regulatory Documentation Burden:USP general chapters on analytical instrument qualification and FDA data integrity expectations multiply protocol validation requirements before revenue recognition.
Strategic Opportunities
- Continuous Manufacturing Validation:FDA emerging guidance on real-time release testing creates demand for integrated analytical packages that monitor critical quality attributes during production rather than post-batch.
- Stability Testing Recurring Revenue:ICH Q1A(R2) zone-defined storage conditions mandate multi-year commitment cycles that lock in long-term client relationships and predictable cash flows.
- Mid-Tier Biotech Service Gap:Sponsors with limited in-house analytical infrastructure seek outsourced partners capable of end-to-end CMC verification from identity through forced-degradation studies.
Industry Challenges
- Method Transfer Complexity:Eight-to-sixteen-week development cycles for HPLC and UHPLC platforms face delays when sponsor-specified forced-degradation study designs conflict with laboratory standard operating procedures.
- GLP Certification Maintenance:Laboratories must sustain current Good Laboratory Practice compliance across multiple FDA inspection cycles while integrating new instrumentation into validated workflows.
- Biologics Structural Characterization:Complex glycosylation patterns and aggregation pathways in monoclonal antibodies demand orthogonal detection strategies that extend analytical timelines beyond small-molecule baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pharmaceutical Analytical Testing Outsourcing Market |
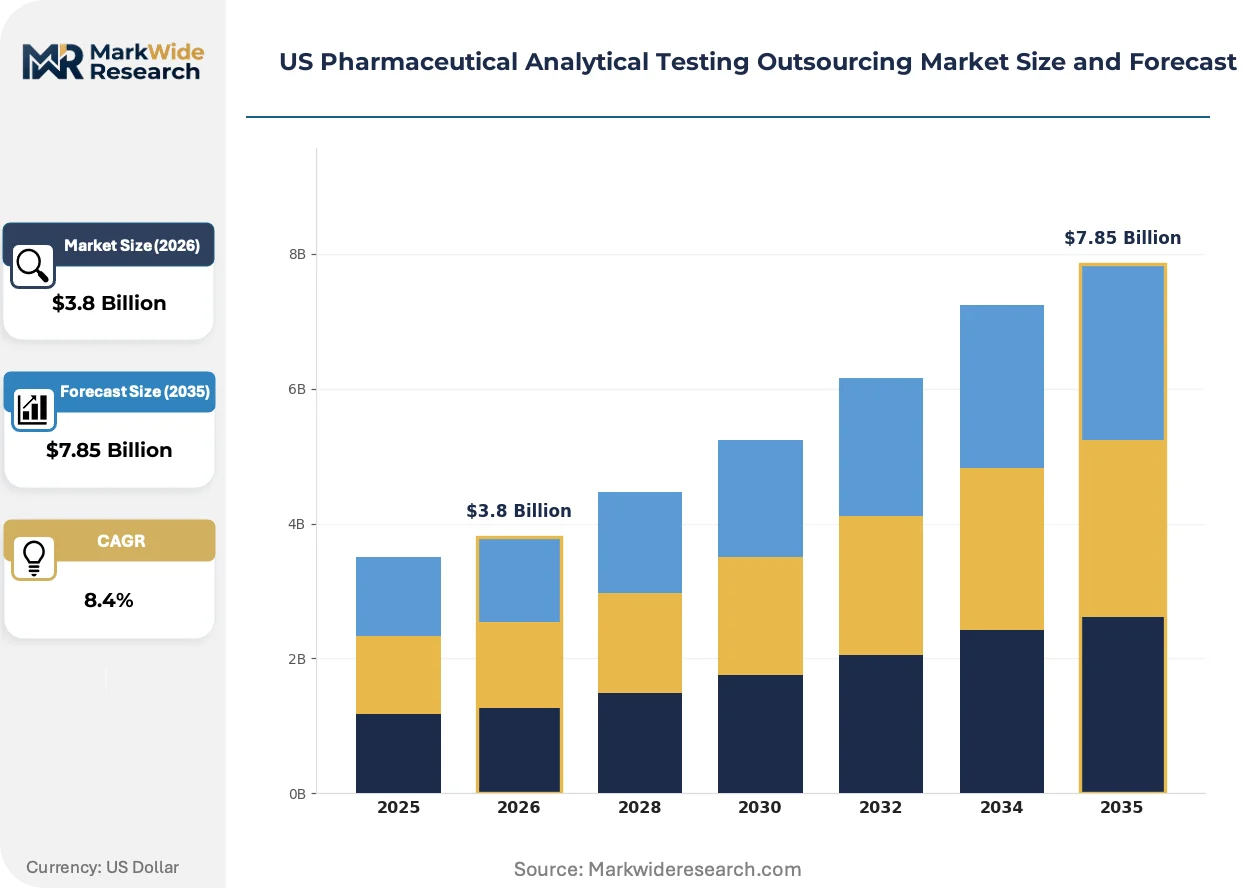
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Raw Material Testing, Stability Testing, Method Development, Microbial Testing Product Type: Biologics, Small Molecules, Vaccines, Biosimilars End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions Technology: HPLC, Mass Spectrometry, NMR, GC |
| Companies Covered | West Pharmaceutical Services, Inc., SGS SA, Eurofins Scientific, Pace Analytical Services LLC, Intertek Group Plc, Pharmaceutical Product Development, LLC., WuXi AppTec, Inc., Boston Analytical, Charles River Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pharmaceutical Analytical Testing Outsourcing Market Strategic Shifts & Innovations
Analytical testing economics are rewriting around automation density and regulatory anticipation, with laboratories competing on protocol integration speed rather than discrete test pricing alone.
High-resolution mass spectrometry is migrating from specialized characterization of unknown impurities to routine release testing for complex biologics. Biologics developers now expect quadrupole time-of-flight platforms in outsourced partner facilities as standard capability. This migration compresses the competitive window for laboratories still relying on lower-resolution detection for critical quality attribute verification.
ICH Q14 guidelines on analytical procedure development are reshaping sponsor expectations for method lifecycle management. The framework mandates enhanced understanding of method design spaces and robustness testing that extends development timelines. US-based biopharma sponsors are responding by embedding CRO partners earlier in clinical phases to share regulatory submission preparation burdens.
Integrated safety and analytical service bundling is displacing discrete testing procurement among venture-backed biotechs. Sponsors now prioritize partners offering full program support from pharmacokinetic assay development through stability protocol execution. This preference shift concentrates contract value with laboratories demonstrating cross-functional toxicology and chemistry expertise rather than specialized analytical shops.
US Pharmaceutical Analytical Testing Outsourcing Market Segmentation
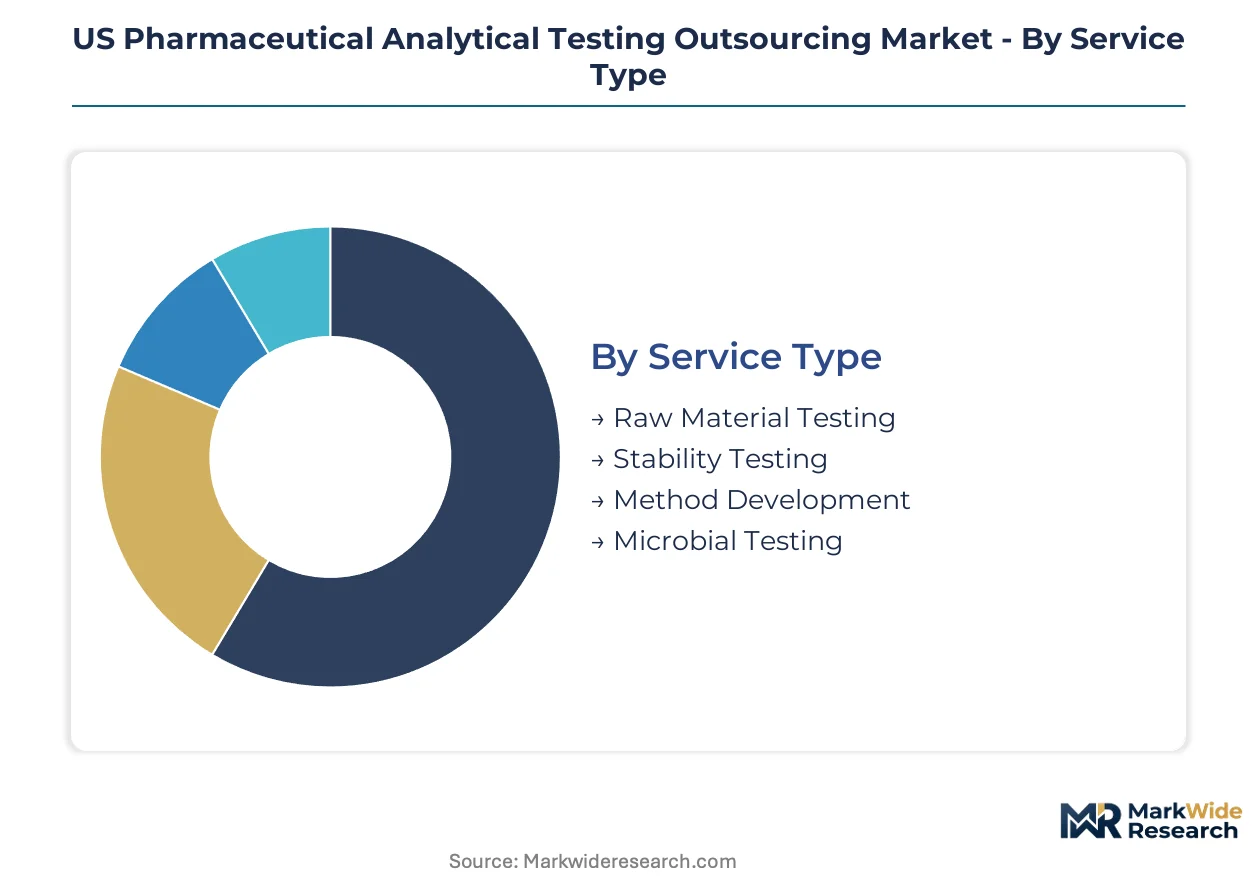
Service differentiation across testing modalities determines contract value and client retention in outsourced pharmaceutical analytics. Laboratories structure portfolios around recurring stability mandates and high-margin method development to balance revenue predictability with growth exposure.
Service Type:
Cost tier differentiation separates commoditized compliance testing from premium development services that anchor multi-year relationships.
- Stability Testing:ICH Q1A(R2) zone-defined storage protocols generate recurring revenue through multi-year commitment cycles. Massachusetts and North Carolina biopharma clusters sustain dense outsourcing networks that reduce logistics costs for stability sample transport.
- Method Development:HPLC and UHPLC platform customization spans eight-to-sixteen-week cycles depending on forced-degradation study complexity. CDER's Quality Management Maturity program drives sponsors to outsource compliance-heavy analytical instrument qualification rather than maintain in-house.
- Raw Material Testing:Identity and purity verification for incoming APIs and excipients under USP general chapters.
- Microbial Testing:Sterility and endotoxin assays required for parenteral and biologic release per FDA current Good Manufacturing Practice.
Stability Testing commands the established base. The steepest expansion runs through Method Development.
Product Type:
Application complexity separates small-molecule workflows from biologics requiring orthogonal detection strategies and extended characterization timelines.
- Biologics:Monoclonal antibodies and cell-culture-derived therapies demand high-resolution mass spectrometry and glycosylation profiling that exceeds mid-tier sponsor capabilities. FDA's emerging guidance on continuous manufacturing validation creates demand for real-time release testing integration.
- Biosimilars:Structural similarity demonstrations require extensive analytical packages comparing innovator and candidate products across critical quality attributes. Sponsors embed CRO partners earlier in clinical phases to share regulatory submission preparation burdens under ICH Q14 frameworks.
- Small Molecules:Traditional chromatographic release testing for synthetic APIs with established USP monographs.
- Vaccines:Potency and adjuvant characterization under specialized cold-chain handling protocols.
Small Molecules retains volume leadership. Biologics is climbing the fastest as pipeline composition shifts.
End User:
Customer type determines contract structure, with venture-backed biotechs prioritizing integrated service bundles over discrete testing procurement.
- Biotechnology Firms:Mid-tier sponsors with limited in-house analytical infrastructure seek end-to-end CMC verification from identity through forced-degradation studies. These clients drive demand for integrated safety and analytical packages that extend beyond discrete testing into full program support.
- Pharmaceutical Companies:Large sponsors outsource specialized capabilities while retaining core release testing, creating spot-demand for high-resolution mass spectrometry during pipeline peaks.
- Contract Research Organizations:Secondary outsourcing for capacity overflow and specialized expertise access.
- Academic Institutions:Method development partnerships for early-stage characterization without commercial release requirements.
Pharmaceutical Companies anchor contract value. Biotechnology Firms is gaining share fastest as pipeline funding concentrates in venture-backed entities.
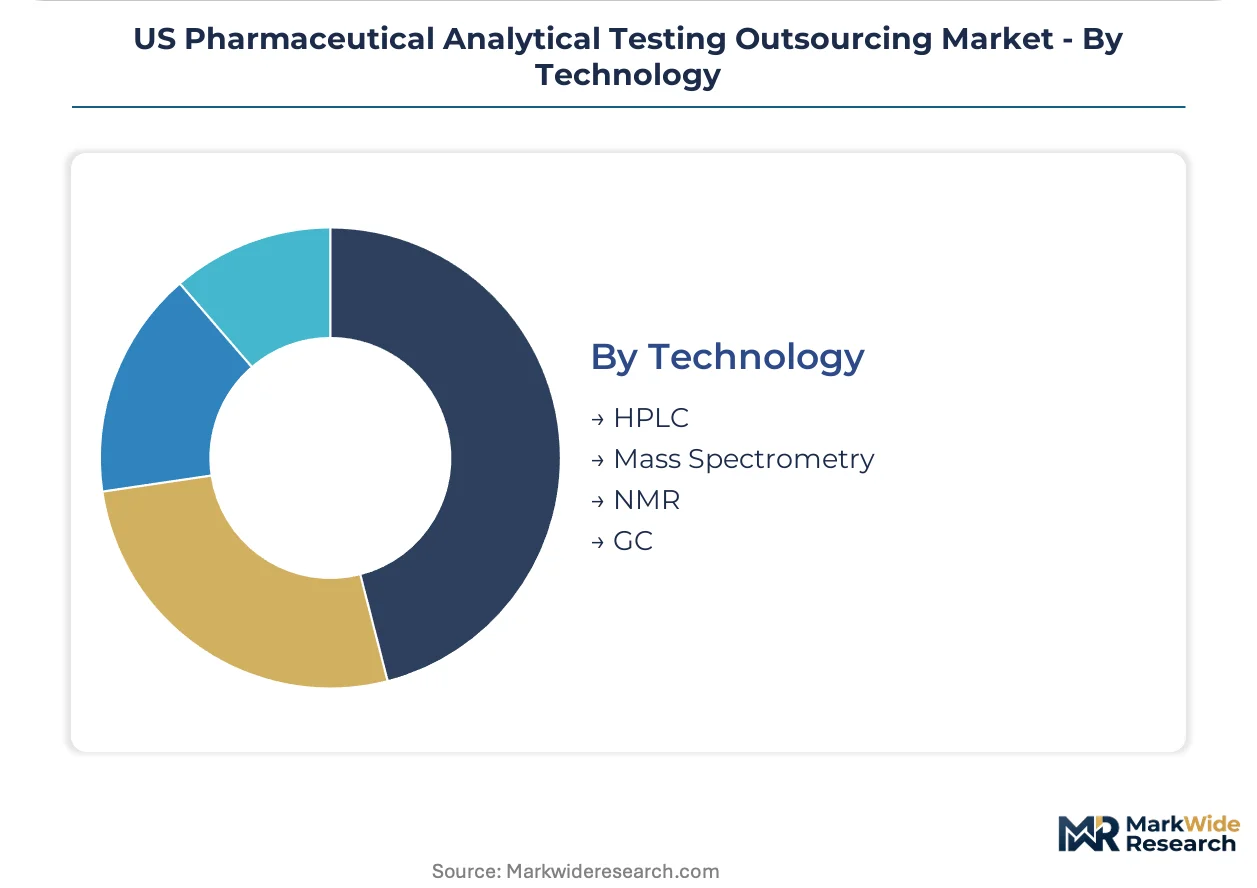
Technology:
Instrument capital intensity stratifies laboratory competitive positioning, with high-resolution platforms becoming baseline expectations for biologics partnerships.
- Mass Spectrometry:Quadrupole time-of-flight systems migrate from specialized unknown impurity characterization to routine release testing for complex biologics. Biologics developers now expect these platforms in outsourced partner facilities as standard capability, compressing competitive windows for lower-resolution laboratories.
- HPLC:Ultra-high-performance liquid chromatography remains the analytical workhorse for identity, purity, and potency verification across small molecules and biologics.
- GC:Residual solvent and volatile impurity analysis per USP <467> guidelines.
- NMR:Structural confirmation and quantitative analysis for specific molecular architectures.
HPLC retains workflow dominance. Mass Spectrometry shows the steepest capability expansion as resolution requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-based analytical testing laboratories export services primarily to Canadian and Mexican pharmaceutical sponsors seeking FDA-aligned quality systems and faster IND-enabling study turnaround.
Massachusetts
Greater Boston's dense biotech cluster generates concentrated demand for biologics characterization and stability protocol design. FDA's Quality Management Maturity program drives local sponsors to outsource compliance-heavy analytical instrument qualification. Cambridge and Worcester sustain the nation's densest network of GLP-certified contract laboratories.
North Carolina
Research Triangle Park anchors analytical outsourcing demand from cell-culture-derived therapy developers. State tax incentives for biopharma manufacturing expansion accelerate sponsor-CRO partnership formation. Durham and Raleigh laboratories specialize in monoclonal antibody forced-degradation studies under ICH Q1A(R2) protocols.
California
San Francisco Bay Area venture-backed biotechs seek integrated safety and analytical packages extending from pharmacokinetic assay development through stability execution. CDER's emerging continuous manufacturing guidance shapes real-time release testing requirements. South San Francisco and San Diego clusters concentrate specialized mass spectrometry capacity.
New Jersey
Legacy pharmaceutical headquarters operations in the Garden State retain specialized release testing outsourcing during pipeline peaks. FDA current Good Manufacturing Practice enforcement maintains rigorous laboratory qualification standards. Princeton and New Brunswick corridors host stability storage facilities serving Mid-Atlantic sponsors.
Illinois
Chicago metropolitan area generic manufacturers and emerging biosimilar developers demand structural similarity demonstration packages. USP general chapters on analytical instrument qualification shape local laboratory capability investments. The region's central logistics position reduces stability sample transport costs for national sponsor networks.
US Pharmaceutical Analytical Testing Outsourcing Market Key Industry Players
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated CROs offering end-to-end CMC verification anchor the premium segment, while specialized analytical shops concentrate on discrete method development and stability execution. Strategic archetypes include platform-scale laboratories with distributed footprints, boutique biologics specialists, and hybrid safety-analytical bundlers. Dominant competitive moves encompass geographic expansion into cluster-dense states and technology licensing for high-resolution mass spectrometry platforms.
Among Switzerland-based testing conglomerates, SGS SA exemplifies the platform-scale archetype through its distributed laboratory footprint. Eurofins Scientific, a Luxembourg-based Co., Ltd., anchors the stability testing recurring revenue model. Charles River Laboratories represents the hybrid safety-analytical bundler positioning that venture-backed biotechs increasingly prioritize over discrete testing procurement.
| Leading Market Players |
|---|
| West Pharmaceutical Services, Inc. |
| SGS SA |
| Eurofins Scientific |
| Pace Analytical Services LLC |
| Intertek Group Plc |
| Pharmaceutical Product Development, LLC. |
| WuXi AppTec, Inc. |
| Boston Analytical |
| Charles River Laboratories |
| Others |
Cost & Logistics Intelligence
German mass spectrometry instrument manufacturers anchor upstream supply for US analytical testing laboratories, concentrating margin capture in the capital equipment tier while service providers downstream compete on automation density and regulatory anticipation. This upstream concentration shapes pricing power dynamics across the value chain, as laboratories face compressed refresh cycles for high-resolution platforms while seeking long-term contract structures to amortize equipment investments.
Pricing Analysis
Next-generation quadrupole time-of-flight systems command premium pricing against prior-generation single-quadrupole platforms, creating a technology-generation pricing gap that stratifies laboratory competitive tiers. Three-tier pricing structure across premium, standard, and economy levels separates GLP-certified biologics specialists from commodity stability providers, with price differentiation driven by FDA certification tier and volume commitment scale. Pricing pressure stems from mid-tier biotech sponsors consolidating vendor relationships to reduce qualification overhead. Biotechnology firms with limited in-house infrastructure demonstrate highest price sensitivity, while large pharmaceutical companies prioritize capability breadth over unit cost.
Supply Chain Analysis
Upstream feedstock for analytical instrumentation concentrates in Germany, Japan, and the United States, with mass spectrometry ion sources and detector assemblies drawing from specialized precision manufacturing clusters in these jurisdictions. Chromatography columns, high-purity solvents, and reference standards rest on chemical supply chains anchored in Switzerland and the Netherlands. Single-source vulnerability in high-resolution mass spectrometry platform supply creates concentration risk for laboratories expanding biologics capabilities. Distribution runs through direct manufacturer relationships for capital equipment, with consumables and reagents flowing through regional distributors serving Massachusetts and North Carolina biopharma clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US pharmaceutical analytical testing outsourcing market sits at a platform-economics inflection, where integrated safety-analytical bundling is displacing discrete testing procurement as venture-backed biotechs prioritize full program support over specialized point solutions.
For Market Incumbents: Harden GLP certification depth across multiple FDA inspection cycles while embedding quality-by-design protocols earlier in sponsor clinical phases to lock in long-term stability contracts. Expand high-resolution mass spectrometry capacity in Research Triangle Park and Greater Boston to defend against emerging biologics specialists. Vertical integration into automated sample handling systems reduces operating cost exposure as labor scarcity intensifies.
For New Entrants and Emerging Players: Illinois biosimilar developers represent underpenetrated demand for structural similarity demonstration packages, with Chicago-area generic manufacturers seeking outsourced analytical partners capable of USP general chapter compliance. Target mid-tier biotechnology firms in California's South San Francisco corridor with integrated pharmacokinetic assay and stability protocol bundles. A go-to-market angle anchored in real-time release testing for continuous manufacturing validation addresses emerging FDA guidance gaps.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics-focused laboratories as quadrupole time-of-flight platforms become baseline capability expectations. Long-term viability over the next decade favors hybrid safety-analytical bundlers with cross-functional toxicology expertise over specialized analytical shops. Acquisition targets should demonstrate embedded sponsor relationships through multi-year stability commitments. The signal to watch is CDER Quality Management Maturity program adoption rates among mid-tier sponsors, as outsourcing intensity correlates with regulatory compliance burden perception.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Resolution Mass Spectrometry Platform Deployment | Quadrupole time-of-flight systems anchor biologics partnerships as FDA Q14 guidelines reshape method lifecycle expectations. |
| Integrated Safety-Analytical Service Bundling | Full program support from pharmacokinetic assay development through stability execution captures venture-backed biotech procurement consolidation. |
| Geographic Expansion into Cluster-Dense States | Massachusetts and North Carolina laboratory footprints reduce logistics costs and accelerate method transfer timelines for regional sponsors. |
| Continuous Manufacturing Validation Capability Buildout | Real-time release testing integration addresses emerging FDA guidance on critical quality attribute monitoring during production. |
| Automated Sample Handling System Investment | Robotics density rewrites analytical testing economics by compressing turnaround times for complex biologics impurity profiling. |
Research Approach
The analysis maps stability testing, method development, raw material testing, and microbial testing sub-sectors, each validated through laboratory operations directors, regulatory affairs leads at sponsor organizations, CMC executives at biotechnology firms, and procurement managers at pharmaceutical companies. Primary interviews with these stakeholders combined with secondary validation against FDA filings, USP general chapter updates, ICH guideline documentation, and CDER guidance releases. Bottom-up and top-down triangulation cross-checks service provider capacity announcements against sponsor outsourcing expenditure patterns.
Assumption sets held regulatory framework evolution and biologics pipeline composition as fixed conditions while varying sponsor consolidation behavior and instrument capital deployment timing across the analysis window. Segmentation dimensions modeled include service type, product type, end user category, and technology platform tier, with additional stratification by regional biopharma cluster density. CAGRs derive from regression analysis against historical outsourcing intensity ratios and sponsor headcount growth in analytical functions. Forecast inputs incorporate ICH Q14 implementation timelines and FDA continuous manufacturing guidance progression.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-scale conglomerates or technology-licensing specialists would shift outcomes through accelerated consolidation. Specific risk factors that could revise projections include FDA enforcement intensity variations, mass spectrometry platform supply disruptions, and sponsor vertical integration into in-house analytical capabilities. Cross-checking against CDER Quality Management Maturity program adoption benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
D-Dimer Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
Global Efficacy Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
Tablet Hardness Testers Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
STD Testing Devices Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Urine Testing Cups Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Global Terminal Sterilization Services Market