
 Small Molecule Innovator CDMO Market | 2026-2036
Small Molecule Innovator CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Small Molecule Innovator CDMO Market Intelligence
Oncology biotechs is restructuring demand for small-molecule CDMO capacity as antibody-drug conjugates and targeted kinase inhibitors claim larger pipeline share. Lonza leverages its high-potency API infrastructure across Swiss and US sites to capture this shift. Catalent Inc. sustains formulation leadership through oral solid dose technologies that serve late-stage innovators. Thermo Fisher Scientific Inc. anchors global reach with integrated drug substance-to-drug product workflows.
Small molecule innovator CDMOs are contract manufacturers that develop and produce chemically synthesized drug substances and finished dosage forms, typically handling potent compounds requiring containment below one microgram per cubic meter and multi-step synthetic routes exceeding twelve stages. Their commercial purpose centers on enabling pharmaceutical innovators to outsource capital-intensive manufacturing while retaining intellectual property control. Active Pharmaceutical Ingredients command the deepest margin pools where containment complexity and regulatory filing burden concentrate value. Formulations segment growth accelerates as innovators seek integrated drug product capabilities to compress development timelines. Process Development services attract early-phase partnerships where CDMOs embed into client pipelines before manufacturing commitments lock in.
FDA, EMA, and ICH Q7 guidelines enforce current Good Manufacturing Practice standards that dictate facility design, validation protocols, and batch documentation for commercial API supply. These frameworks create compliance barriers that favor established CDMOs with proven regulatory inspection histories over new entrants. China's NMPA and India's CDSCO are tightening data integrity requirements that reshape qualification criteria for global innovators sourcing Asian capacity. Stakeholders must monitor how US FDA's quality management maturity program and EU REACH chemical registration obligations converge to redefine supplier audit standards and geographic risk allocation.
Market Dynamics
Oncology biotechs are restructuring capacity demand as antibody-drug conjugates and targeted kinase inhibitors claim larger pipeline share, forcing CDMOs to invest in high-potency containment infrastructure below one microgram per cubic meter.
Growth Catalysts
- EMA Quality Mandates:Tightened GMP enforcement for commercial API supply favors established CDMOs with proven regulatory inspection histories over new market entrants.
- Antibody-Drug Conjugates:Biotech innovators outsourcing linker-payload chemistry manufacturing to access specialized high-containment capabilities without capital deployment.
- Switzerland-Germany Cluster:Concentration of high-containment API capabilities in Basel and Frankfurt anchors European supply security for global innovators.
Market Restraints
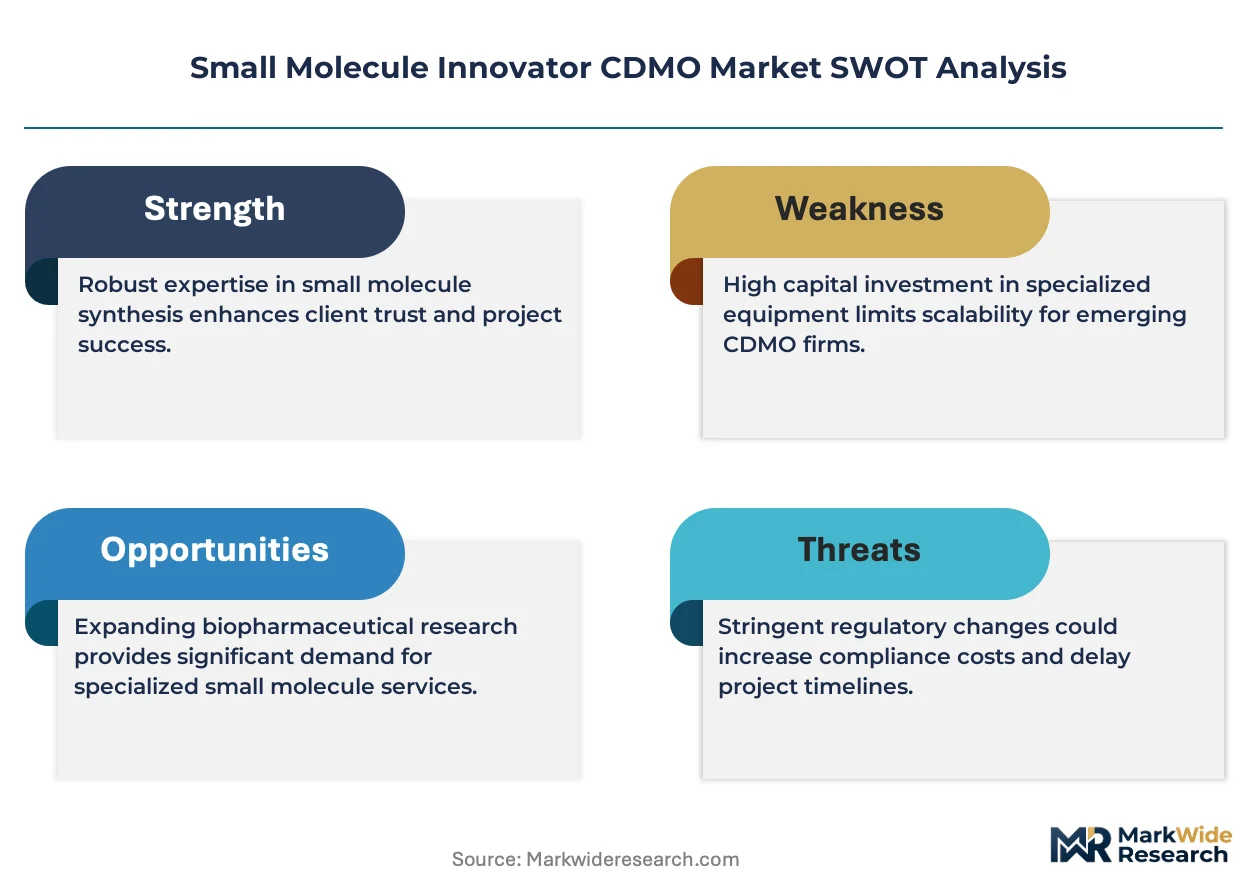
- Specialized Equipment Costs:Isolators and containment systems for potent compounds require capital intensity that limits mid-tier CDMO expansion.
- Asian Regulatory Divergence:NMPA and CDSCO data integrity requirements create qualification friction for innovators sourcing Chinese and Indian capacity.
- Multi-Step Synthetic Complexity:Routes exceeding twelve stages concentrate expertise among few CDMOs with integrated process development-to-manufacturing workflows.
Strategic Opportunities
- Integrated Drug Product Services:Formulation capabilities that compress development timelines attract early-phase partnerships before manufacturing commitments lock in.
- US FDA Quality Management Maturity:The agency's program creates audit standard differentiation that rewards CDMOs with documented compliance histories.
- Continuous Flow Chemistry:Convergence of process analytical technology with modular manufacturing platforms enables smaller batch footprints for clinical supply.
Industry Challenges
- Containment Engineering Talent:Scarcity of process safety engineers with high-potency facility design experience extends project ramp timelines.
- EU REACH Registration:Chemical substance obligations add documentation burden to supplier qualification for European-sourced intermediates.
- Legacy Quality System Integration:Merging acquired CDMO operations with parent company documentation protocols creates batch release friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Molecule Innovator CDMO Market |
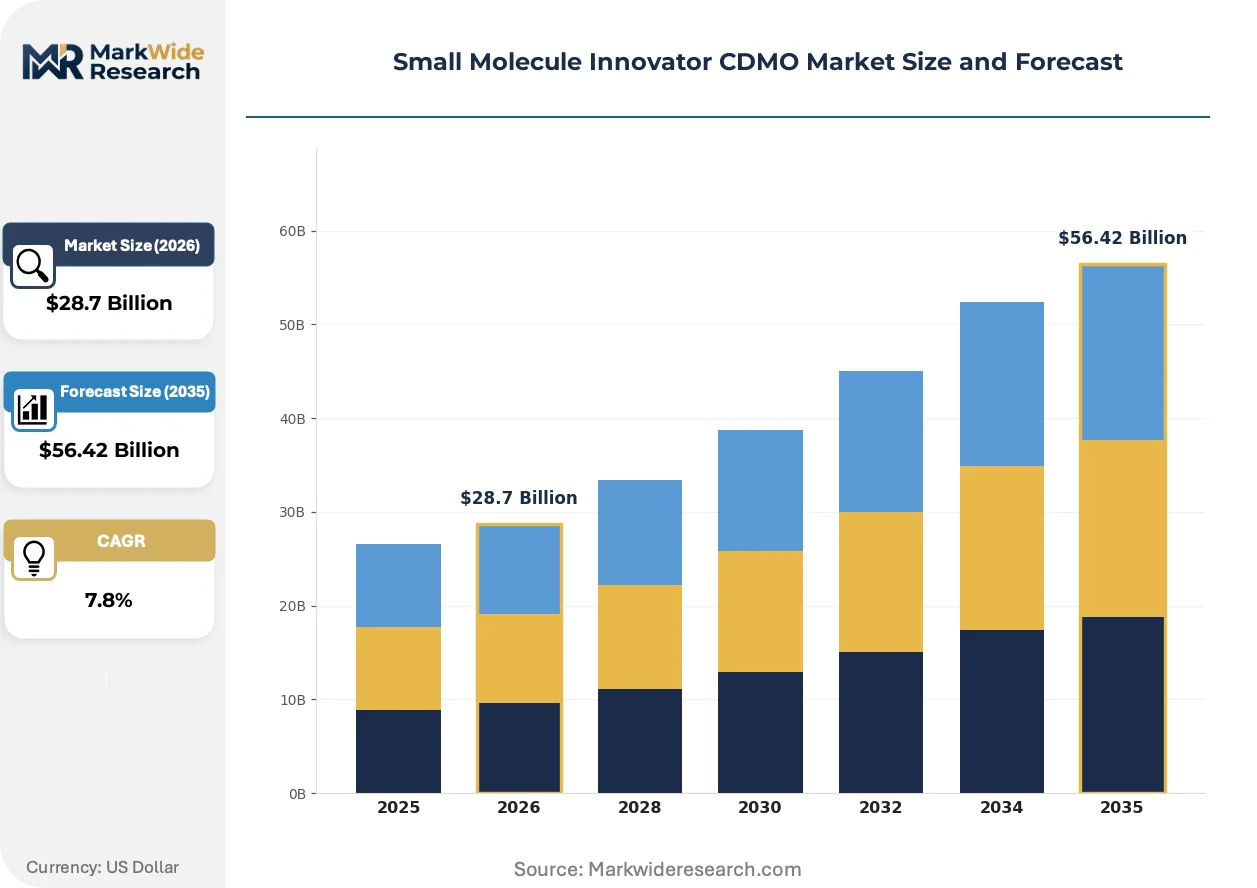
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $56.42 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pharmaceutical Ingredients, Intermediates, Formulations, Bioconjugates End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Startups Delivery Mode: Oral, Parenteral, Topical, Inhalation Service Type: Process Development, Manufacturing, Quality Control, Regulatory Affairs |
| Companies Covered | Lonza, Catalent Inc., Thermo Fisher Scientific Inc., Cambrex Corporation, Piramal Pharma Solutions, WuXi AppTec, CordenPharma International, Siegfried Holding AG, Recipharm AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Molecule Innovator CDMO Market Strategic Shifts & Innovations
Process analytical technology and modular manufacturing platforms are compressing development timelines while regulatory data integrity mandates reshape supplier qualification protocols across innovator procurement functions.
Continuous flow chemistry is automating multi-step synthetic routes that previously required batch-wise processing across discrete reactor trains. Mid-sized oncology biotechs are adopting these platforms for clinical-phase API supply to reduce solvent waste and improve reaction control. The technology is automating real-time quality assurance decisions that formerly depended on offline analytical testing, compressing batch release cycles.
EU REACH chemical registration obligations are converging with FDA quality management maturity assessments to redefine supplier audit standards. CDMOs must now document substance volume tracking and hazard classification alongside GMP compliance for European innovators. High-potency API manufacturers with dual US-EU filing experience capture disproportionate qualification attention from global biotech procurement teams.
Innovator sourcing patterns are consolidating vendor relationships around integrated drug substance-to-drug product capabilities. Biotech procurement functions now favor CDMOs offering unified CMC documentation and single-point regulatory accountability over specialized API-only or formulation-only suppliers. This consolidation is most visible among US-based rare disease developers seeking to minimize technology transfer risks across development phases.
Small Molecule Innovator CDMO Market Segmentation
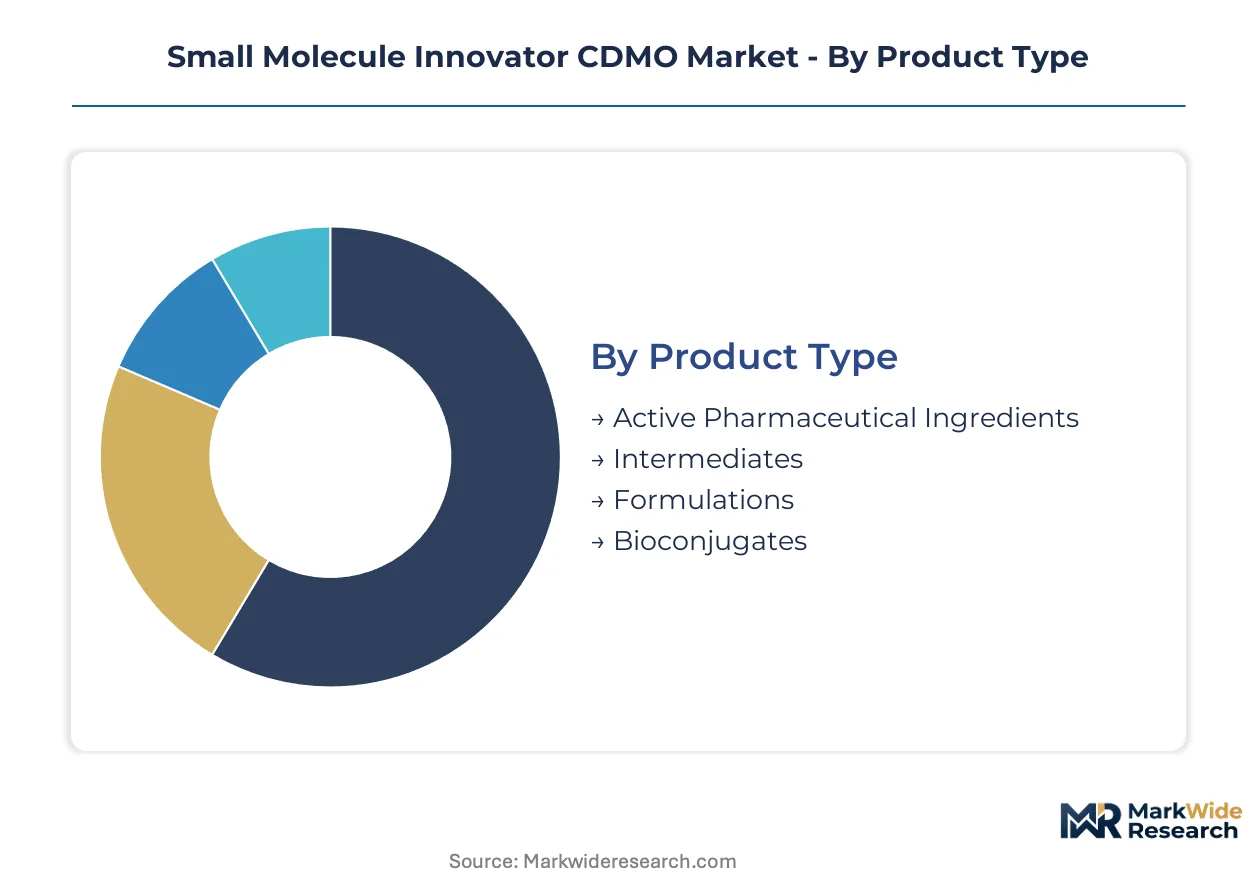
CDMO procurement decisions pivot on containment complexity, regulatory filing burden, and integration depth across the drug substance-to-product continuum. Segment boundaries increasingly blur as innovators demand unified CMC accountability rather than discrete service modules.
Product Type:
Margin capture follows containment engineering intensity and regulatory documentation burden rather than molecular weight or synthetic step count alone.
- Active Pharmaceutical Ingredients:High-potency compounds requiring containment below one microgram per cubic meter command premium pricing where synthetic routes exceed twelve stages. Demand concentrates among Swiss and German manufacturers anchoring European supply security for oncology innovators.
- Formulations:Oral solid dose technologies attract late-stage partnerships seeking to compress development timelines through integrated drug product capabilities. Growth tilts toward integrated service providers offering unified regulatory accountability.
- Intermediates:Early-stage synthetic building blocks with lower containment requirements serve process development partnerships before manufacturing commitments lock in.
- Bioconjugates:Linker-payload chemistry for antibody-drug conjugates requires specialized high-containment infrastructure without capital deployment by innovator clients.
Volume sits with Active Pharmaceutical Ingredients; growth tilts toward Bioconjugates.
End User:
Contract structures vary by R&D maturity, capital constraints, and regulatory filing experience across the buyer spectrum.
- Biotechnology Firms:Oncology and rare disease developers outsource capital-intensive manufacturing while retaining intellectual property control, favoring CDMOs with proven FDA and EMA inspection histories.
- Pharmaceutical Companies:Established innovators restructure capacity demand as antibody-drug conjugates claim larger pipeline share, forcing selective outsourcing of high-potency containment.
- Startups:Early-phase innovators embed CDMOs into pipelines before manufacturing commitments crystallize, prioritizing process development partnerships over scale.
- Contract Research Organizations:Research service providers extend into manufacturing adjacencies, creating hybrid competition for early-phase relationships.
Revenue concentrates with Biotechnology Firms; expansion accelerates among Startups.
Delivery Mode:
Route selection dictates containment architecture, stability testing protocols, and regulatory filing pathways.
- Oral:Solid dose formulations dominate commercial volume through established dissolution and bioavailability frameworks.
- Parenteral:Injectable delivery requires sterile manufacturing infrastructure and container closure integrity validation.
- Topical:Transdermal and dermal formulations demand specialized excipient compatibility and skin permeation testing.
- Inhalation:Pulmonary delivery systems require particle engineering and device integration capabilities.
Commercial scale favors Oral; technical complexity peaks with Inhalation.
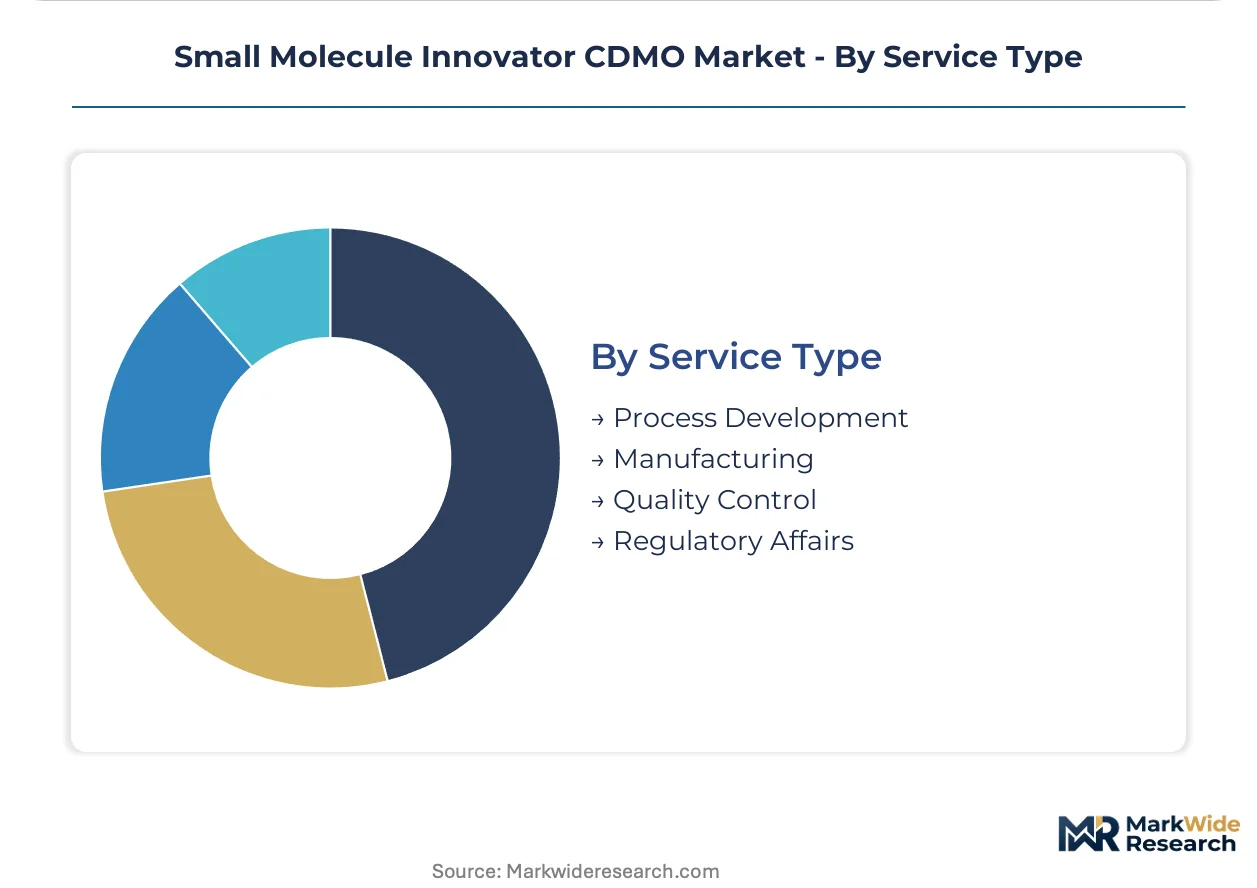
Service Type:
Value migration follows the development timeline from early-phase embedding to commercial manufacturing lock-in.
- Process Development:Early-phase partnerships where CDMOs embed into client pipelines attract disproportionate lifetime value through manufacturing commitment conversion.
- Manufacturing:Commercial-scale production commands the deepest margin pools where containment complexity and batch documentation burden concentrate value.
- Quality Control:Analytical method development and release testing integrate with regulatory filing requirements across FDA, EMA, and ICH Q7 frameworks.
- Regulatory Affairs:CMC documentation and inspection readiness services reduce technology transfer friction for innovators with limited filing experience.
Margin depth concentrates in Manufacturing; relationship origination depends on Process Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss free-trade zones and German chemical parks concentrate high-containment API capacity for oncology innovators. FDA and EMA quality mandates reshape supplier qualification across Basel and Frankfurt clusters. Tax incentives for pharmaceutical manufacturing anchor European supply security.
United States
Oncology biotechs in Boston and San Francisco outsource linker-payload chemistry to access specialized containment without capital deployment. FDA's quality management maturity program rewards CDMOs with documented compliance histories. The Research Triangle and New Jersey corridor host multi-site operators with integrated drug substance-to-product workflows.
Switzerland
Basel's pharmaceutical cluster anchors high-potency API manufacturing for antibody-drug conjugates requiring containment below one microgram per cubic meter. Swissmedic enforces GMP standards that exceed baseline ICH Q7 requirements. Lonza leverages cross-border infrastructure between Visp and Portsmouth to serve dual US-EU filing clients.
Germany
Frankfurt and Ludwigshafen chemical parks concentrate synthetic routes exceeding twelve stages for kinase inhibitors. EMA tightened GMP enforcement creates compliance barriers favoring established manufacturers with proven inspection records. The Rhine-Main region integrates process development with commercial-scale containment engineering.
India
Hyderabad and Ahmedabad hubs supply early-stage intermediates with lower containment requirements before manufacturing commitments crystallize. CDSCO data integrity requirements reshape qualification criteria for global innovators sourcing Asian capacity. Gujarat's special economic zones attract process development partnerships seeking cost-advantaged chemistry.
China
Shanghai and Suzhou biotech clusters embed CDMOs into pipelines before commercial scale commitments lock in. NMPA tightened data integrity mandates create friction for Western innovators qualifying Chinese capacity. The Yangtze River Delta concentrates modular manufacturing platforms for clinical-phase API supply.
Small Molecule Innovator CDMO Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with high-potency API capacity consolidating around Swiss and German infrastructure while formulation services fragment across mid-tier players. Three archetypes dominate: integrated drug substance-to-product operators, high-containment specialists, and process development-focused partnerships. Competitive moves concentrate on M&A for regulatory inspection histories and capacity expansion in Basel-Frankfurt corridor clusters.
Within the integrated services tier, Lonza and Catalent Inc. exemplify archetypes spanning containment engineering to finished dosage forms. Thermo Fisher Scientific Inc. anchors the scale-driven segment with cross-continental facility networks. These three represent the dominant competitive positions without speculative claims about specific strategic actions or financial performance.
| Leading Market Players |
|---|
| Lonza |
| Catalent Inc. |
| Thermo Fisher Scientific Inc. |
| Cambrex Corporation |
| Piramal Pharma Solutions |
| WuXi AppTec |
| CordenPharma International |
| Siegfried Holding AG |
| Recipharm AB |
| Others |
Cost & Logistics Intelligence
EU REACH chemical registration obligations gate qualified supply access and anchor premium-tier pricing power for high-potency API manufacturers with dual US-EU filing experience. Containment engineering intensity below one microgram per cubic meter concentrates value capture among Swiss and German operators while mid-tier CDMOs face margin compression from specialized equipment costs.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid-turn containment capacity with premium positioning while spot inventory availability commands discounts for non-critical intermediates. Three-tier pricing structure across premium, standard, and economy levels segments by containment complexity and regulatory filing burden. Price differentiation hinges on FDA quality management maturity certification tier and geographic delivery cost to Boston or Basel clusters. Cost compression in standard-tier oral solid dose services is intensifying because formulation capabilities fragment across mid-tier players. Startups demonstrate highest price sensitivity; established oncology biotechs prioritize compliance history over unit cost.
Supply Chain Analysis
Process safety engineer scarcity in Basel and Frankfurt extends project ramp timelines and concentrates high-potency capacity among incumbent operators. Supply concentrates in Switzerland, Germany, and the United States for commercial API with sub-microgram containment. Raw material dependencies draw from specialized excipient suppliers, high-purity solvent distributors, and containment-grade equipment manufacturers. Single-source vulnerability in isolator technology vendors creates qualification bottlenecks for capacity expansion. Distribution runs through integrated drug substance-to-product operators offering unified CMC documentation rather than modular API-only suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA quality management maturity program requirements erect barrier-to-entry moats rewarding CDMOs with documented inspection histories.
For Market Incumbents: Deepen high-containment capacity in the Rhine-Main corridor to capture antibody-drug conjugate linker-payload demand from Boston and San Francisco biotechs. Expand process development partnerships before manufacturing commitments crystallize, as emerging modular manufacturing platforms threaten batch-wise processing incumbency. Prioritize dual US-EU filing experience to maintain qualification advantage over Asian competitors facing data integrity friction.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in oral solid dose services creates white-space opportunity for mid-tier CDMOs with isolator-lite containment capabilities. Target early-stage intermediates supply to Hyderabad and Ahmedabad innovators before high-potency manufacturing commitments lock in. Pursue continuous flow chemistry partnerships as the go-to-market angle to differentiate from batch-wise incumbents on development timeline compression.
For Investors and Strategic Acquirers: FDA quality management maturity program enrollment acceleration is the leading indicator that regulatory audit differentiation is hardening into durable competitive moats. Over the projection horizon, integrated drug substance-to-product operators with proven Swissmedic and EMA inspection records represent the most defensible acquisition profile. Monitor CDSCO and NMPA data integrity enforcement tightening as the signal for Western innovator procurement pivot back toward Basel-Frankfurt capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Containment Capacity Expansion | Captures antibody-drug conjugate demand from Boston oncology biotechs requiring sub-microgram containment. |
| Continuous Flow Chemistry Adoption | Compresses clinical-phase API development timelines through real-time process analytical technology integration. |
| Dual US-EU Filing Investment | Secures qualification priority from global innovators navigating FDA quality management maturity and EU REACH convergence. |
| Process Development Partnership Embedding | Locks in manufacturing commitment conversion before late-stage scale decisions crystallize with competitors. |
| Regulatory Inspection History Acquisition | Accelerates compliance moat construction faster than organic qualification timelines permit for new entrants. |
Research Approach
Independent corroboration across drug development executives, regulatory affairs leads, CDMO procurement managers, and containment engineering specialists underwrites the qualitative findings. Secondary validation draws from FDA filings, EMA inspection records, ClinicalTrials.gov pipeline data, and Swissmedic GMP certification databases. Bottom-up capacity assessments across Basel, Frankfurt, and Research Triangle facilities triangulate with top-down oncology pipeline segmentation.
Rate-of-change decomposition separates volume expansion from pricing power migration across the analysis window. Segmentation dimensions model product type, end user maturity, service integration depth, and regional regulatory cluster. CAGRs derive from facility utilization trajectories, containment capacity addition timelines, and innovator outsourcing penetration curves. Forecast inputs incorporate antibody-drug conjugate pipeline share shifts and high-potency API regulatory filing velocity.
Underlying measurement precision varies by segment; high-potency API and bioconjugate categories carry tighter precision than intermediates due to disclosed capacity and containment certification visibility. Forecasts reflect assumptions about FDA quality management maturity program adoption rates and EMA GMP enforcement consistency. Material deviation in NMPA or CDSCO data integrity enforcement timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Critical Care Therapeutics Market
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
In-Silico Drug Discovery Market