
 Small Molecule CDMO Market | 2026-2036
Small Molecule CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Small Molecule CDMO Market Analytics
The small molecule CDMO sector is restructuring around a widening capability gap between high-complexity, patent-protected synthesis and commoditized generic API production. Lonza Group leverages its bioconjugation and potent compound expertise to command premium pricing in oncology-focused manufacturing. Catalent Inc. sustains a North American and European footprint that appeals to sponsors requiring FDA and EMA-aligned facilities. Wuxi AppTec competes aggressively on scale, anchoring substantial small molecule capacity in China with expanding Western client rosters.
Small molecule contract development and manufacturing organizations provide outsourced chemical synthesis, process development, and commercial production of low molecular weight pharmaceutical actives, typically below 900 Daltons, using multi-step organic chemistry, crystallization, and purification workflows. These services enable originator and generic drug companies to access specialized reactor infrastructure, analytical capabilities, and regulatory documentation without capital-intensive facility construction. API Development occupies the largest revenue pool given the technical complexity and regulatory burden of route design, impurity control, and scale-up validation. Continuous Flow Chemistry represents the fastest-expanding technology segment as sponsors pursue improved safety profiles, tighter process control, and reduced solvent waste compared with traditional batch reactors. Formulation Development commands elevated margins where CDMOs integrate active pharmaceutical ingredients into finished dosage forms with bioavailability-enhancing technologies.
FDA inspections under ICH Q7 guidelines, EMA's GMP certificate mutual recognition protocols, and India's CDSCO manufacturing license requirements collectively determine facility qualification and market access for cross-border supply. Sponsors now prioritize CDMO partners with established regulatory inspection histories and documented data integrity systems. Stakeholders must monitor evolving EPA environmental compliance for solvent-intensive synthesis and adapt procurement strategies toward partners with proven green chemistry implementation.
Market Dynamics
Continuous flow chemistry is compressing batch reactor economics across high-potency API manufacturing, forcing CDMOs to retool legacy infrastructure or surrender oncology and antiviral contracts to engineered-flow specialists.
Growth Catalysts
- ICH Q7 Harmonization:The FDA and EMA's aligned GMP inspection protocols reduce dual-qualification costs for multi-site sponsors, accelerating cross-border tech transfers.
- Oncology Pipeline Density:Antibody-drug conjugate payloads and kinase inhibitors require specialized containment infrastructure that originators refuse to build in-house.
- India CDSCO Export Licensing:Streamlined manufacturing license reciprocity with US and EU regulators positions Indian CDMOs as preferred suppliers for post-patent API volumes.
Market Restraints
- Palladium and Rare Earth Input Volatility:Cross-coupling catalysts face price swings tied to South African and Russian supply concentration, squeezing margin on generic API contracts.
- Single-Source Chromatography Media:Protein A resin and specialized sorbent production concentrates in three global suppliers, creating vulnerability for high-purity peptide manufacturing.
- EPA Solvent Emission Caps:N-methyl-2-pyrrolidone and dichloromethane restrictions under the National Emission Standards for Hazardous Air Pollutants force costly abatement retrofits.
Strategic Opportunities
- China NMPA Innovation Track:Domestic drug approval acceleration for novel chemical entities creates captive demand for local CDMOs with dual US-China filing experience.
- AI-Driven Route Scouting:Machine learning retrosynthesis platforms from IBM RXN and DeepMatter converge with robotic reaction screening, collapsing process development timelines.
- Swissmedic High-Potency Certification:Switzerland's centralized European hub status and stringent containment standards attract sponsors seeking premium manufacturing badges for orphan drugs.
Industry Challenges
- Process Analytical Technology Talent Scarcity:Spectroscopic method development and multivariate data analysis skills lag equipment installation, delaying FDA quality-by-design submissions.
- Legacy ERP Integration with E-Records:Electronic batch record migration from paper-based systems fragments data integrity audits and extends qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Molecule CDMO Market |
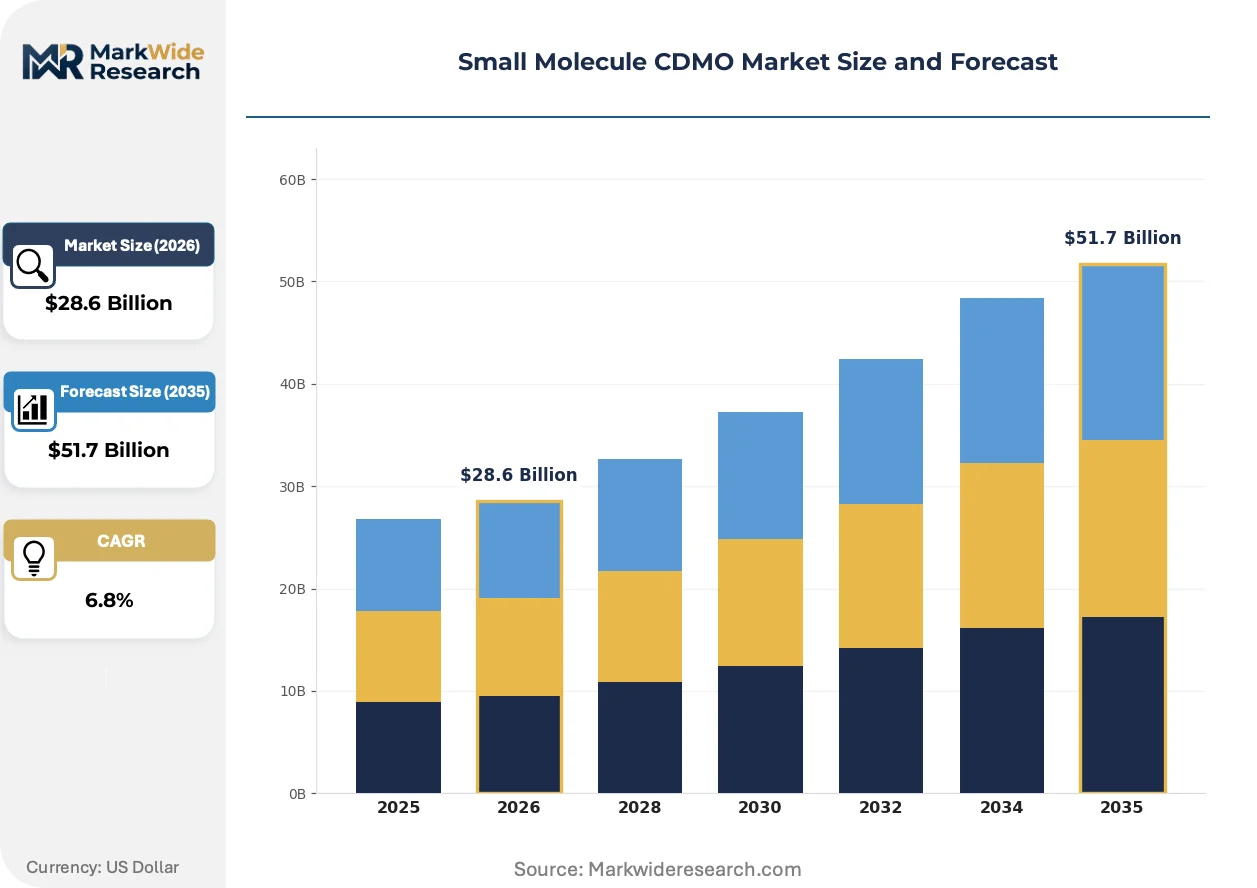
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: API Development, Formulation Development, Packaging, Quality Control End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Generic Manufacturers Technology: Continuous Flow Chemistry, Traditional Batch Processing, Nanotechnology, Green Chemistry Application: Oncology Therapies, Cardiovascular Treatments, CNS Disorders, Infectious Diseases |
| Companies Covered | Cambrex Corporation, Recipharm, Lonza Group, Neuland Laboratories Limited, Wuxi AppTec, Catalent Inc., Siegfried Holding AG, Akums Drugs and Pharmaceuticals, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Molecule CDMO Market Evolving Landscape
Automation and real-time release testing are collapsing traditional quality control bottlenecks, while regulatory pressure on environmental footprint accelerates solvent substitution chemistry.
Continuous flow reactor systems is integrating photochemical and electrochemical activation modules for direct C-H functionalization, eliminating hazardous reagent handling. Mid-sized CDMOs in the Netherlands and Switzerland are adopting these platforms fastest to differentiate from Chinese volume competitors. The technology is integrating process analytical technology sensors for closed-loop control, compressing batch release times from weeks to hours.
EMA's revised Annex 1 on sterile manufacturing mandates barrier isolation and automated decontamination for all new oncology API facilities. This industrial consequence forces CDMOs to abandon open-manip potent compound handling entirely. European sponsors now disqualify partners without documented isolator qualification histories, shifting contract awards toward purpose-built greenfield sites.
Biopharma procurement teams are consolidating vendor panels from twenty-plus suppliers to four or five strategic partners with full-service capabilities. The channel being disrupted is transactional spot-buying for individual API steps, replaced by integrated development-to-commercial contracts with milestone-linked pricing. This concentration is most visible among US-based biotechs with Series C through post-IPO funding, where CFO scrutiny of supply chain overhead has intensified.
Small Molecule CDMO Market Segmentation
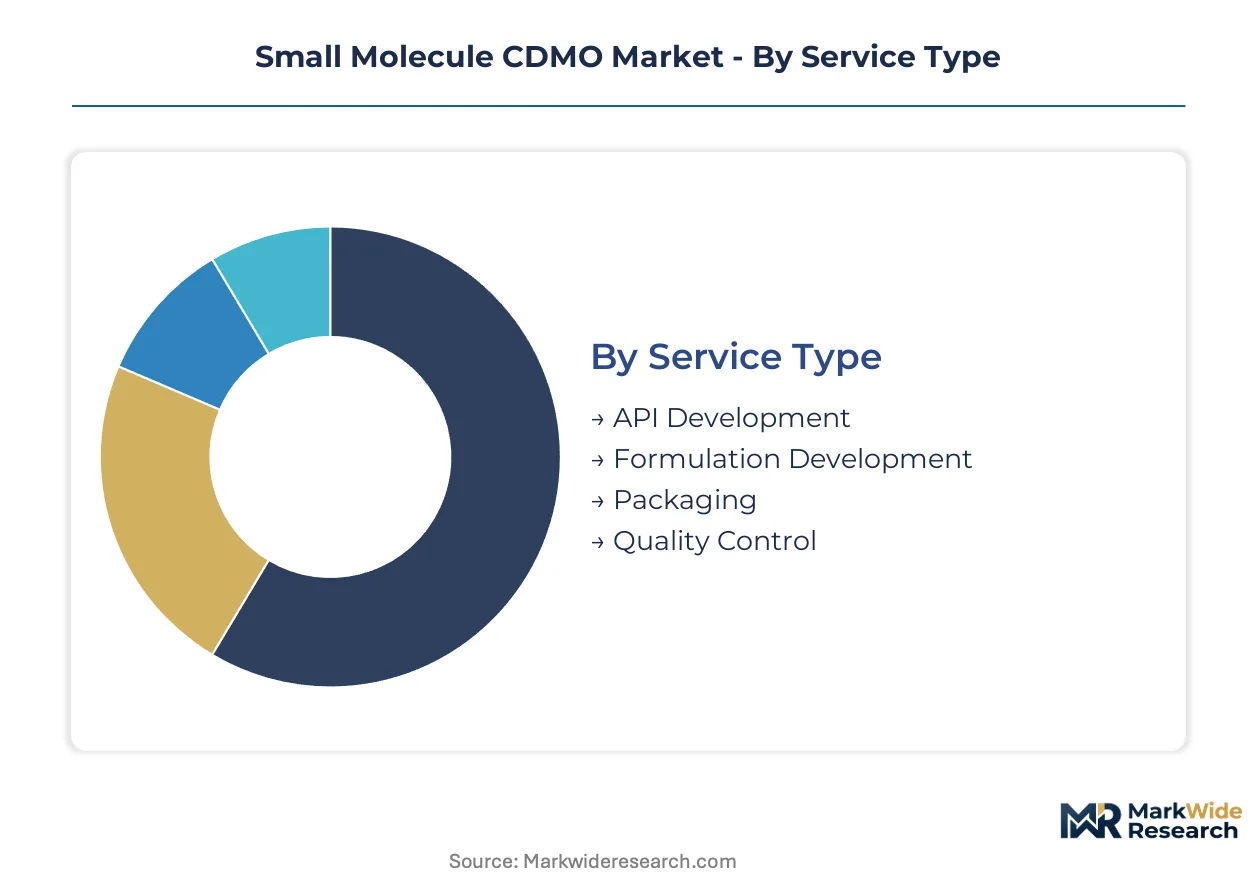
Small molecule CDMO segmentation reveals divergent margin profiles across service depth and technology intensity. Sponsors allocate procurement budgets differently between early-stage route scouting and commercial-scale manufacturing, creating distinct competitive arenas.
Service Type:
Technical complexity and regulatory burden stratify outsourcing decisions across the development-to-commercial continuum.
- API Development:Multi-step organic synthesis, impurity profiling, and scale-up validation consume the largest share of sponsor R&D outsourcing budgets. FDA quality-by-design mandates and EMA filing requirements concentrate demand with CDMOs possessing documented regulatory inspection histories.
- Formulation Development:Bioavailability-enhancing technologies including amorphous solid dispersions and lipid nanoparticle integration command premium pricing. Oncology sponsors in Switzerland and Massachusetts prioritize partners with isolator-qualified potent compound handling.
- Packaging:Blistering, bottling, and serialization services complete the value chain with lower technical barriers but higher capital intensity for EU FMD and US DSCSA compliance.
- Quality Control:Method validation, stability testing, and release analytics support all upstream segments with spectroscopic and chromatographic expertise.
API Development leads on scale; Formulation Development leads on momentum.
End User:
Customer procurement sophistication determines contract structure and pricing power distribution.
- Pharmaceutical Companies:Large originators consolidate vendor panels to four or five strategic partners, favoring integrated development-to-commercial contracts with milestone-linked pricing over transactional spot-buying.
- Biotechnology Firms:Series C through post-IPO funded US biotechs drive demand for flexible, small-batch API manufacturing with rapid scale-up options.
- Research Institutions:Academic and government laboratories require gram-to-kilogram quantities for preclinical and early-phase programs.
- Generic Manufacturers:Post-patent API volume contracts concentrate in Indian CDMOs with CDSCO export licensing reciprocity and cost-competitive large-scale reactor infrastructure.
Pharmaceutical Companies dominate contract value; Biotechnology Firms are expanding most quickly.
Technology:
Process innovation is compressing traditional batch economics and reshaping facility investment priorities.
- Continuous Flow Chemistry:Engineered-flow reactors with photochemical and electrochemical modules enable direct C-H functionalization while eliminating hazardous reagent handling. Dutch and Swiss mid-sized CDMOs adopt these platforms fastest to differentiate from Chinese volume competitors.
- Traditional Batch Processing:Conventional multi-step organic synthesis in stirred-tank reactors retains dominance for generic API volumes where capital depreciation favors legacy infrastructure.
- Nanotechnology:Particle engineering and nano-crystallization enhance solubility for poorly permeable actives.
- Green Chemistry:Solvent substitution, biocatalysis, and waste reduction protocols respond to EPA emission caps and sponsor ESG procurement criteria.
Traditional Batch Processing retains volume leadership; Continuous Flow Chemistry commands the steepest expansion trajectory.
Application:
Therapeutic area requirements dictate containment specifications and regulatory filing strategies.
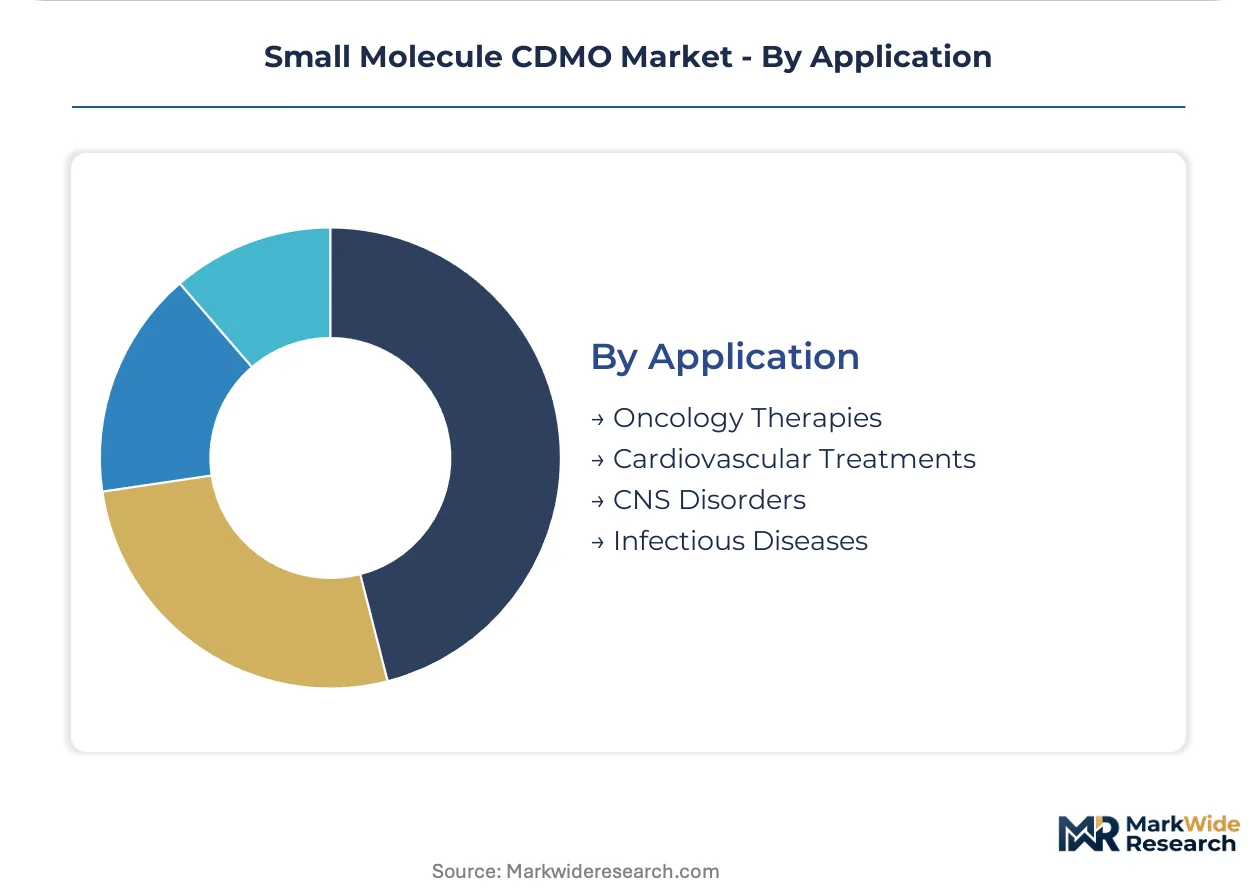
- Oncology Therapies:Antibody-drug conjugate payloads, kinase inhibitors, and cytotoxic agents require specialized isolator infrastructure that originators refuse to build in-house. EMA Annex 1 sterile manufacturing mandates now disqualify open-manip potent compound handling entirely.
- Cardiovascular Treatments:Statins, anticoagulants, and antihypertensives represent mature, high-volume markets with price-sensitive generic competition.
- CNS Disorders:Blood-brain barrier penetration challenges drive formulation complexity for neurodegenerative and psychiatric indications.
- Infectious Diseases:Antiviral and antibiotic manufacturing faces resurgent demand with pandemic preparedness requirements and antimicrobial resistance priorities.
Oncology Therapies lead on technical premium; Infectious Diseases are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical chemists and process engineers concentrate in Basel, Boston, and Hyderabad, anchoring regional manufacturing capabilities. These talent clusters determine where sponsors locate high-complexity synthesis and commercial-scale production.
United States
Series C through post-IPO biotechs in Massachusetts and California drive flexible, small-batch API manufacturing with rapid scale-up options. FDA quality-by-design mandates under ICH Q7 guidelines elevate compliance barriers for domestic facilities. Greater Boston hosts Lonza's bioconjugation operations serving oncology-focused sponsors.
Switzerland
Orphan drug manufacturers prize Swissmedic high-potency certification for premium manufacturing badges. EMA Annex 1 sterile manufacturing mandates position Basel-area CDMOs for antibody-drug conjugate payload production. Siegfried Holding AG exemplifies the containment-specialist archetype in this regulatory environment.
India
Generic API volume contracts concentrate in Hyderabad and Ahmedabad following CDSCO export licensing reciprocity with US and EU regulators. Cost-competitive large-scale reactor infrastructure attracts Western sponsors seeking post-patent manufacturing. Neuland Laboratories Limited and Akums Drugs and Pharmaceuticals occupy positions within this cost-optimized tier.
China
NMPA innovation track acceleration for novel chemical entities creates captive demand for local CDMOs with dual US-China filing experience. Yangtze River Delta facilities leverage scale advantages in multi-step organic synthesis. Wuxi AppTec anchors substantial capacity serving expanding Western client rosters.
Germany
EMA-aligned facilities in Hesse and Bavaria appeal to sponsors requiring European regulatory inspection histories. Process analytical technology integration and green chemistry implementation respond to ECHA REACH solvent restrictions. Recipharm represents the mid-sized European CDMO archetype with documented data integrity systems.
Small Molecule CDMO Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the small molecule CDMO sector. The market structures around a three-tier hierarchy: integrated global platforms, regional scale specialists, and niche technology boutiques. Swiss and German CDMOs exemplify the premium containment tier; Indian and Chinese operators dominate commoditized generic API production. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with sponsors consolidating vendor panels from twenty-plus suppliers to four or five integrated partners.
Within the premium-tier vector, Lonza Group and Catalent Inc. exemplify CDMOs commanding pricing power through specialized infrastructure. Thermo Fisher Scientific occupies a position spanning laboratory services through commercial manufacturing. Wuxi AppTec anchors the scale-driven end with substantial China-based capacity. These three represent contrasting archetypes: Swiss bioconjugation expertise, North American regulatory alignment, and Asian volume manufacturing.
| Leading Market Players |
|---|
| Cambrex Corporation |
| Recipharm |
| Lonza Group |
| Neuland Laboratories Limited |
| Wuxi AppTec |
| Catalent Inc. |
| Siegfried Holding AG |
| Akums Drugs and Pharmaceuticals |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up mid-cap specialists dominate the mid-tier CDMO segment, compressing pricing discipline through portfolio optimization mandates while simultaneously fragmenting supply chain accountability across multiple legacy facilities. This ownership pattern concentrates bargaining power with large pharmaceutical sponsors, who exploit vendor consolidation to extract volume discounts from asset-heavy operators in India and China.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated development-to-commercial contracts from transactional API step sourcing. Three-tier pricing structure across premium, standard, and economy levels reflects containment certification grade and regulatory inspection history. Cost compression in standard-tier generic API manufacturing is intensifying because of palladium catalyst price volatility and Indian CDMO capacity expansion. Generic manufacturers exhibit highest price sensitivity, while orphan drug sponsors in Switzerland accept premium pricing for Swissmedic-certified isolator infrastructure.
Supply Chain Analysis
Certification/qualification gating through FDA ICH Q7 inspections, EMA GMP certificates, and CDSCO export licensing concentrates supply chain access among pre-qualified facility networks. Manufacturing capacity clusters in India, China, and Switzerland, drawing from South African palladium, Chinese rare earth elements, and German chromatography resin. Single-source vulnerability in protein A resin production creates disruption risk for high-purity peptide manufacturing. Distribution runs through sponsor-consolidated vendor panels of four to five strategic partners with full-service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement teams now prioritizing documented data integrity systems and isolator qualification histories over pure cost optimization in oncology-focused manufacturing.
For Market Incumbents: Deepen vertical integration into specialized containment infrastructure and process analytical technology capabilities to defend against engineered-flow specialists capturing high-potency API contracts. Incumbents must accelerate legacy ERP migration to electronic batch records before FDA data integrity audits fragment qualification timelines further. Capacity addition in Switzerland and the Netherlands reinforces premium positioning as EMA Annex 1 mandates disqualify open-manip potent compound handling. For New Entrants and Emerging Players: NMPA innovation track acceleration in China opens a window for domestic CDMOs with dual US-China filing experience to capture captive demand from novel chemical entity sponsors. White-space targets include AI-driven route scouting services and continuous flow chemistry platforms for photochemical C-H functionalization. A go-to-market angle anchored to green chemistry implementation responds to EPA solvent emission caps and sponsor ESG procurement criteria. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light route-scouting boutiques with robotic reaction screening capabilities and machine learning retrosynthesis platforms. Long-term viability over the next decade hinges on regulatory inspection history depth and documented isolator qualification for oncology manufacturing. The signal to watch is sponsor consolidation of vendor panels from twenty-plus suppliers to four or five integrated partners, accelerating M&A pressure on sub-scale operators.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Engineered-flow reactors with photochemical modules enable direct C-H functionalization while eliminating hazardous reagent handling. |
| Isolator Infrastructure Investment | EMA Annex 1 sterile manufacturing mandates now disqualify open-manip potent compound handling entirely for oncology API. |
| AI-Driven Route Scouting | Machine learning retrosynthesis platforms from IBM RXN converge with robotic screening to collapse process development timelines. |
| Dual US-China Filing Capability | NMPA innovation track acceleration creates captive demand for local CDMOs with cross-border regulatory experience. |
| Electronic Batch Record Migration | Legacy ERP integration with e-records fragments data integrity audits and extends qualification timelines without systematic upgrade. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, manufacturing site heads, and procurement directors at biopharmaceutical sponsors with secondary validation against FDA filings, EMA inspection databases, CDSCO manufacturing licenses, and SEC 10-K disclosures from publicly traded CDMOs. Bottom-up facility capacity modeling and top-down sponsor outsourcing budget analysis provided cross-checks on market sizing.
Comparable-period anchoring established baseline volumes from historical API production data and sponsor R&D expenditure patterns, then projected forward across the analysis window using segmented models for service type, end user, technology platform, and therapeutic application. CAGRs were derived from fitted growth curves calibrated to patent cliff timing, pipeline density by therapeutic area, and regulatory inspection capacity constraints. Forecast inputs incorporated sponsor vendor panel consolidation rates and continuous flow chemistry adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden EPA solvent restriction tightening or palladium supply disruption scenarios. Forecasts reflect assumptions about ICH Q7 harmonization durability and CDSCO export licensing reciprocity stability. A model refresh is warranted upon material change in FDA quality-by-design enforcement intensity or EMA Annex 1 sterile manufacturing interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Lyophilization Equipment Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market