
 Urine Testing Cups Market | 2026-2036
Urine Testing Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Urine Testing Cups Market Analysis
OSHA workplace drug testing guidelines is shifting employer procurement standards toward tamper-evident collection systems. Thermo Fisher Scientific leverages its diagnostic supply chain scale to serve high-volume reference laboratories. Quest Diagnostics anchors the North American clinical testing segment through its extensive patient service center network. Drägerwerk AG differentiates with integrated analytical instrumentation paired with specimen collection hardware.
Urine testing cups are single-use specimen collection vessels, typically manufactured from polypropylene or biodegradable polymers with integrated temperature strips and leak-resistant lids, designed to capture, transport, and temporarily store human urine for subsequent chemical or immunoassay analysis. Multi-panel cups now lead product type demand as employers and clinical sites seek simultaneous detection of multiple drug classes from one specimen, while security sealed cups command premium positioning through chain-of-custody compliance features. Home testing applications represent the fastest-growing segment as direct-to-consumer diagnostic channels expand, though hospitals and rehabilitation centers still concentrate the highest volume procurement.
FDA 510(k) clearance governs commercial distribution in the United States, while the EU Medical Device Regulation (MDR) imposes strengthened clinical evidence requirements for cups marketed as sterile collection devices in Europe. ISO 13485 quality management certification shapes supplier qualification criteria for large laboratory buyers and government tenders. Stakeholders must monitor evolving state-level cannabis legalization frameworks, as conflicting federal and jurisdictional drug policies reshape workplace testing menus and cup panel configurations.
Market Dynamics
Workplace drug testing mandates from OSHA and state-level employer liability frameworks are compressing procurement cycles and elevating tamper-evidence specifications across the North American supply base.
Growth Catalysts
- OSHA workplace guidelines:Federal safety mandates now require documented chain-of-custody protocols, forcing employers toward security-sealed collection systems with integrated temperature verification.
- Clinical laboratory expansion:Reference labs in the United States are consolidating specimen processing volumes, creating pull-through demand for standardized multi-panel cup formats compatible with high-throughput immunoassay platforms.
- Polymer stabilization:Advances in polypropylene additive packages now enable longer shelf stability for integrated reagent strips, reducing field failure rates in distributed collection environments.
Market Restraints
- FDA 510(k) clearance timelines:Average review periods for in vitro diagnostic devices now extend 12-18 months, compressing product refresh rates and trapping development capital in regulatory queues.
- Raw material concentration:Medical-grade polypropylene supply concentrates among Gulf Coast petrochemical complexes, exposing molders to hurricane-season disruption and force majeure pricing volatility.
- Saliva-based substitution:Oral fluid collection devices are capturing share in pre-employment screening segments where observed collection is logistically simpler than urine-based protocols.
Strategic Opportunities
- Home diagnostic channels:Direct-to-consumer platforms are creating white-space demand for discreet, single-panel cups with simplified result interpretation for personal wellness monitoring.
- EU MDR clinical evidence pathways:Strengthened documentation requirements for sterile collection devices create first-mover advantage for manufacturers with established ISO 13485 quality systems and notified body relationships.
- Biodegradable polymer convergence:PLA and PHA material platforms are crossing performance thresholds for leak resistance, enabling sustainability-positioned product lines for environmentally contracted government tenders.
Industry Challenges
- Immunoassay chemistry integration:Cup manufacturers must synchronize reagent strip development with shifting analyte detection thresholds set by SAMHSA and state workplace regulators, requiring continuous reformulation cycles.
- Legacy laboratory information system compatibility:New cup formats with RFID or barcode serialization face integration friction with aging LIS platforms in mid-tier hospital networks, delaying adoption despite technical readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urine Testing Cups Market |
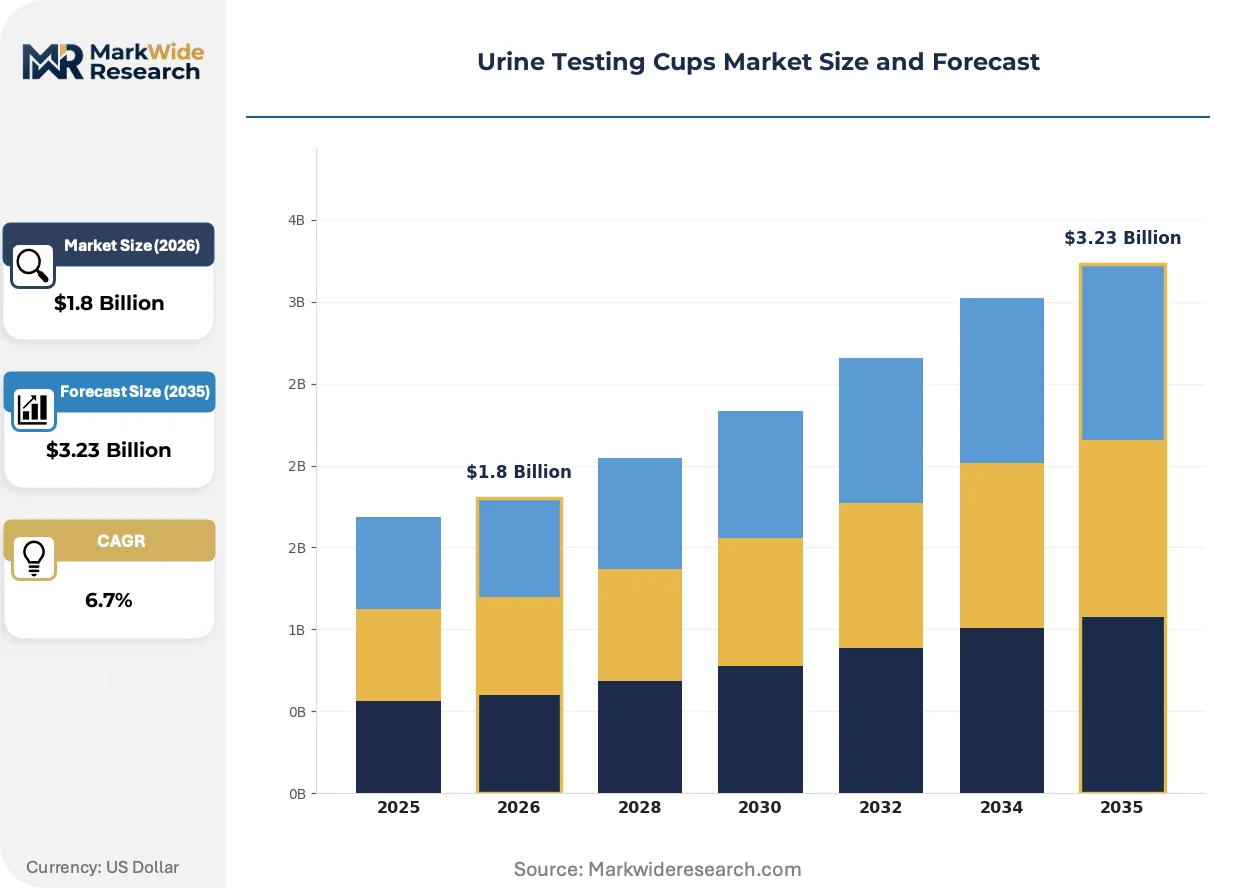
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cups, Security Sealed Cups, Multi-Panel Cups, Disposable Cups Application: Clinical Testing, Sports Testing, Drug Testing, Home Testing End User: Hospitals, Laboratories, Rehabilitation Centers, Clinics Material: Plastic, Polypropylene, Glass, Biodegradable Materials |
| Companies Covered | Quest Diagnostics Incorporated, Laboratory Corporation of America Holdings, Thermo Fisher Scientific, Inc., Alere, Inc., Drägerwerk AG & Co. KGaA, Siemens AG, Shimadzu Corporation, Express Diagnostics Int'l Inc., MPD, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urine Testing Cups Market Emerging Trajectories
Digital connectivity and material science advances are restructuring how specimen integrity is verified and documented across decentralized collection environments, compressing the distance between collection point and analytical result.
RFID-enabled cups with encrypted temperature logging are decentralizing chain-of-custody verification by embedding documentation directly into the collection vessel itself. Occupational health clinics and third-party administrators are piloting these systems for unobserved collection scenarios. This architecture is compressing reliance on human courier documentation and reducing specimen rejection rates at reference laboratory intake.
The EU Medical Device Regulation now imposes clinical performance documentation for cups marketed as sterile collection devices, forcing manufacturers to generate biocompatibility and sterility assurance data previously exempt under the Medical Device Directive. European notified bodies are applying heightened scrutiny to leachable studies from polymer contact surfaces. Manufacturers with legacy CE certificates face renewal cliffs that favor larger competitors with dedicated regulatory affairs infrastructure.
Employer self-collection programs are displacing third-party collection site networks for pre-employment screening, with staffing agencies and transportation fleets leading adoption. This pattern concentrates volume procurement among employers with internal occupational health capabilities rather than distributed clinic networks. The United States Midwest manufacturing belt exhibits the strongest migration toward employer-direct models, driven by tight labor markets and same-day hiring imperatives.
Urine Testing Cups Market Segmentation
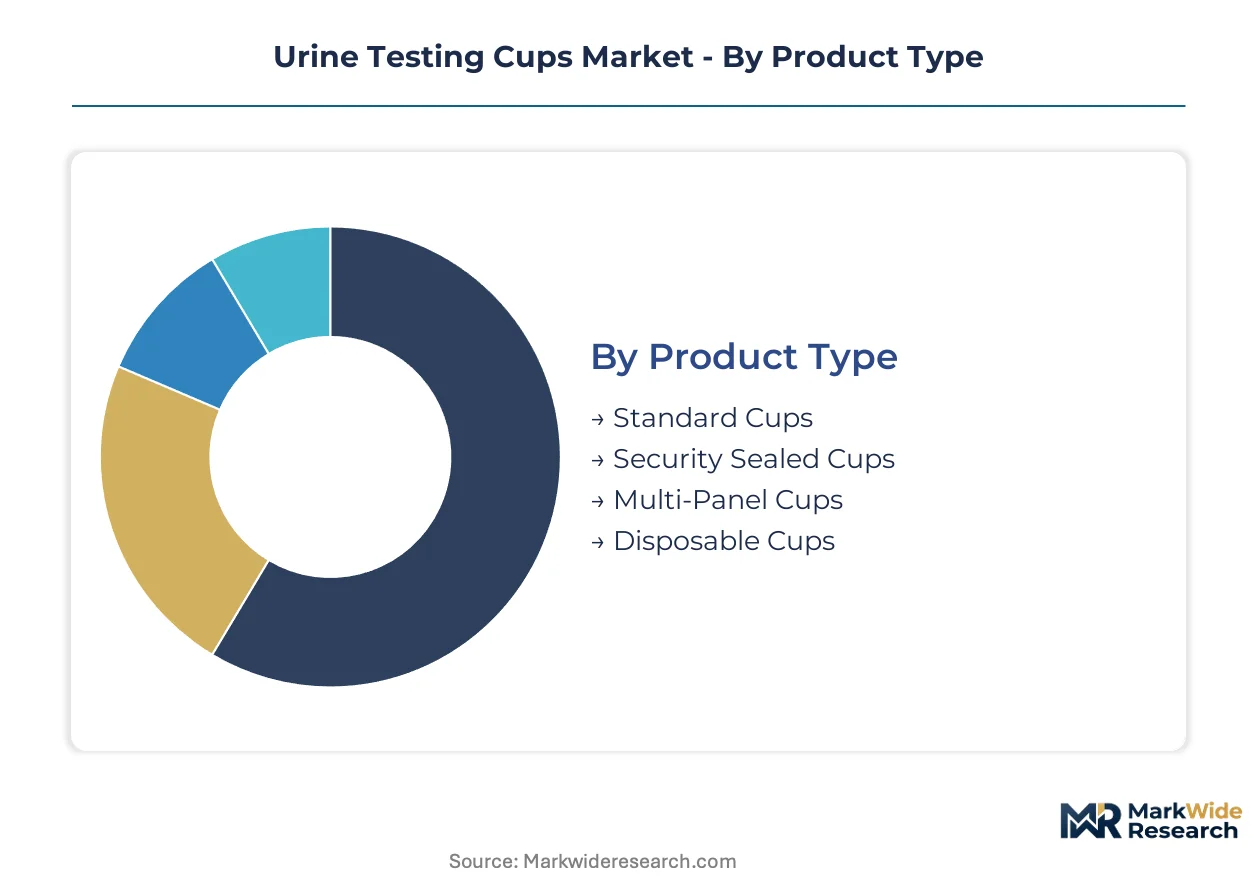
Urine testing cups segment across functional specifications, use environments, and material platforms. Each dimension carries distinct procurement logic, regulatory thresholds, and margin profiles that reshape supplier positioning.
Product Type:
Customization intensity varies sharply across this category, from commodity disposables to engineered security systems with integrated verification features.
- Multi-Panel Cups:These vessels incorporate multiple immunoassay strips for simultaneous detection of drug classes including amphetamines, opiates, cannabinoids, and cocaine metabolites. Employers and clinical sites in the United States now specify these formats to reduce per-specimen processing costs and accelerate turnaround. OSHA workplace guidelines mandating documented chain-of-custody protocols are compressing demand toward cups with built-in adulteration detection.
- Security Sealed Cups:Tamper-evident lids, temperature strips, and serialized labeling create defensible specimen integrity documentation for legal proceedings and employment disputes. Premium positioning reflects compliance value rather than manufacturing cost, with third-party administrators and occupational health clinics absorbing price premiums for liability protection.
- Standard Cups:Basic polypropylene vessels without integrated testing strips serve reference laboratories that perform centralized immunoassay analysis.
- Disposable Cups:Single-use designs minimize cross-contamination risk in high-throughput clinical environments.
Leading the category by volume: Multi-Panel Cups. Growing fastest: Security Sealed Cups.
Application:
Volume concentration sits with institutional purchasers, while margin expansion tracks toward direct-to-consumer channels with minimal distribution intermediaries.
- Drug Testing:Pre-employment screening, random workplace testing, and post-incident investigations consume the majority of specimen collection hardware. United States staffing agencies and transportation fleets are migrating toward employer-direct collection models, bypassing third-party clinic networks. SAMHSA analyte detection thresholds and state-level cannabis policy fragmentation force continuous reconfiguration of testing menus.
- Home Testing:Direct-to-consumer platforms are creating white-space demand for discreet, single-panel formats with simplified result interpretation. Privacy positioning and wellness framing attract consumers outside traditional medical channels, with e-commerce fulfillment reducing retail distribution friction.
- Clinical Testing:Hospital laboratories and reference labs demand standardized formats compatible with automated immunoassay platforms.
- Sports Testing:Anti-doping protocols at collegiate and professional levels require witnessed collection with strict chain-of-custody documentation.
Volume leader: Drug Testing. Steepest expansion trajectory: Home Testing.
End User:
Procurement sophistication divides this category, with integrated health systems demanding supply chain integration and smaller clinics prioritizing spot purchasing flexibility.
- Laboratories:Reference laboratories in the United States consolidate specimen processing volumes, creating pull-through demand for standardized formats compatible with high-throughput immunoassay platforms. Thermo Fisher Scientific and Quest Diagnostics anchor procurement through multi-year supply agreements with volume tiering.
- Hospitals:Inpatient and emergency department testing requires rapid turnaround, with RFID-enabled cups piloting for decentralized chain-of-custody verification.
- Rehabilitation Centers:Substance abuse treatment facilities conduct frequent monitoring with observed collection protocols.
- Clinics:Occupational health and urgent care sites serve as collection nodes for employer screening programs.
Procurement volume concentrates: Laboratories. Fastest adoption of connected formats: Hospitals.
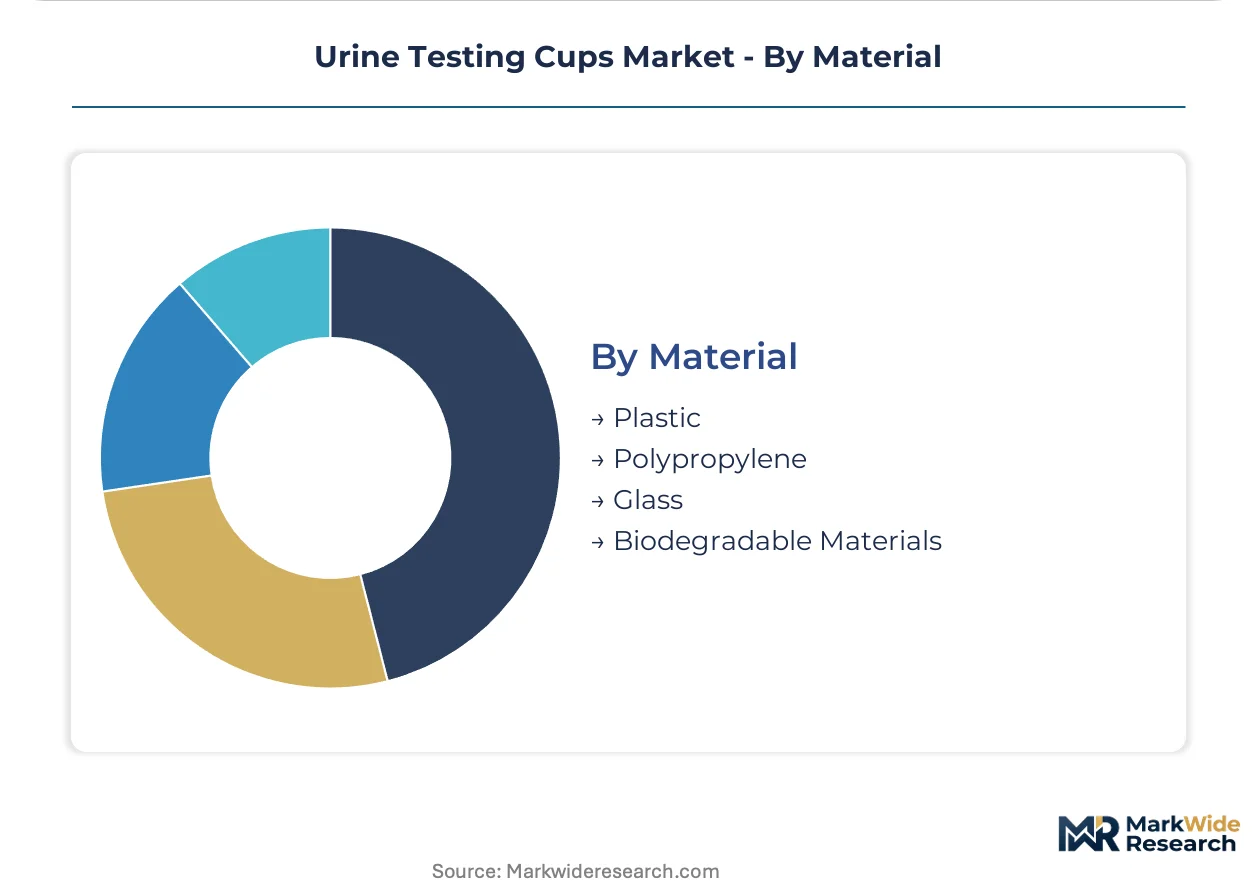
Material:
Performance requirements and sustainability positioning create divergent supply strategies across polymer and alternative platforms.
- Polypropylene:Medical-grade formulations dominate manufacturing due to chemical resistance, dimensional stability, and compatibility with injection molding at scale. Gulf Coast petrochemical concentration exposes molders to hurricane-season disruption and force majeure pricing volatility.
- Biodegradable Materials:PLA and PHA platforms are crossing performance thresholds for leak resistance, enabling sustainability-positioned product lines for environmentally contracted government tenders. European notified bodies apply heightened scrutiny to leachable studies from polymer contact surfaces under EU MDR requirements.
- Plastic:General-purpose polymers serve cost-sensitive segments with lower regulatory exposure.
- Glass:Specialized applications requiring inert contact surfaces and sterilization compatibility.
Supply base anchors on: Polypropylene. Gaining share fastest: Biodegradable Materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American polypropylene supply for medical-grade polymer molding, with Gulf Coast petrochemical complexes feeding injection molders serving diagnostic device manufacturers across the United States clinical laboratory channel.
United States
Workplace drug screening expansion among staffing agencies and transportation fleets compresses procurement cycles toward tamper-evident formats. OSHA federal safety mandates now require documented chain-of-custody protocols, elevating specifications for security-sealed collection systems. Indianapolis and the Midwest manufacturing belt exhibit the strongest migration toward employer-direct collection models, bypassing third-party clinic networks entirely.
Germany
Reference laboratory consolidation across Bavaria and North Rhine-Westphalia generates standardized demand for multi-panel cup formats compatible with automated immunoassay platforms. EU MDR imposes strengthened clinical evidence requirements for sterile collection devices, forcing manufacturers to generate biocompatibility data previously exempt. Frankfurt-Rhine-Main laboratory clusters apply heightened scrutiny to leachable studies from polymer contact surfaces.
China
Domestic diagnostic supply chain expansion in Jiangsu and Zhejiang provinces creates volume demand for injection-molded polypropylene vessels. NMPA regulatory pathways for in vitro diagnostic devices continue elevating product registration thresholds for imported collection hardware. Shanghai-Yangtze River Delta diagnostic manufacturing corridors concentrate mold tooling capacity and sterilization infrastructure.
India
Direct-to-consumer diagnostic channel growth in Maharashtra and Karnataka generates white-space demand for discreet home testing formats. CDSCO medical device regulations impose quality system requirements for sterile collection devices marketed through pharmacy retail. Mumbai-Pune pharmaceutical corridors anchor distribution infrastructure for clinical laboratory supply.
Japan
Aging demographic monitoring protocols in Kanto and Kansai regions sustain institutional procurement of standardized collection vessels. PMDA quality management requirements shape supplier qualification criteria for hospital laboratory networks. Tokyo-Osaka clinical testing corridors concentrate reference laboratory processing volumes and automated platform deployment.
Urine Testing Cups Market Vendor Landscape
Premium-margin players sit above commodity-margin players across regulatory certification intensity, with FDA 510(k) clearance and ISO 13485 quality system infrastructure separating defensible positioning from spot-market participation. The vendor base organizes around three strategic archetypes: integrated diagnostic conglomerates with captive laboratory networks, specialized collection device manufacturers with regulatory affairs depth, and regional molders serving cost-sensitive institutional tenders. Dominant competitive moves include M&A consolidation of laboratory service networks and capacity expansion of medical-grade polymer compounding assets.
Among United States-based diagnostic service conglomerates, Quest Diagnostics Incorporated and Laboratory Corporation of America Holdings occupy positions as anchor procurement entities through multi-year supply agreements with volume tiering. Thermo Fisher Scientific, Inc. represents the integrated supply chain archetype, leveraging diagnostic distribution scale to serve high-volume reference laboratories. Drägerwerk AG & Co. KGaA exemplifies the instrumentation-coupled positioning, with German engineering heritage signaling precision manufacturing credibility across European notified body jurisdictions.
| Leading Market Players |
|---|
| Quest Diagnostics Incorporated |
| Laboratory Corporation of America Holdings |
| Thermo Fisher Scientific, Inc. |
| Alere, Inc. |
| Drägerwerk AG & Co. KGaA |
| Siemens AG |
| Shimadzu Corporation |
| Express Diagnostics Int'l Inc. |
| MPD, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA 510(k) cleared security-sealed cups and unregulated standard vessels manifests in both pricing power and supply chain configurations, with cleared manufacturers commanding 40-60% premiums while concentrating molding capacity near Gulf Coast polypropylene feedstock.
Pricing Analysis
Chain-of-custody compliance value anchors pricing architecture across the urine testing cups market, with security-sealed formats carrying liability-protection premiums that decouple from manufacturing cost. Price differentiation rests on FDA clearance tier and integrated adulteration detection capability, with multi-panel configurations capturing additional value from throughput efficiency. Cost compression in standard cup segments intensifies as Indian and Chinese molders enter institutional tenders. Staffing agencies and mid-tier clinics exhibit highest price sensitivity, while reference laboratories absorbing SAMHSA-mandated protocols show lowest.
Supply Chain Analysis
Domestic-content requirements in United States government tenders and EU MDR clinical evidence mandates are reshaping sourcing patterns toward regionalized production footprints. Medical-grade polypropylene supply concentrates in United States Gulf Coast, German petrochemical corridors, and Chinese state-owned complexes. Manufacturing draws from injection molding tooling clusters in Jiangsu province, sterilization infrastructure in Shanghai-Yangtze Delta, and distribution through diagnostic distributor networks serving hospital GPOs. Single-source vulnerability to hurricane-season disruption in Texas and Louisiana petrochemical complexes poses structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive control over medical-grade polymer compounding to defend margin structure against raw material volatility.
For Market Incumbents: Cement defensible positioning through backward integration into Gulf Coast polypropylene compounding assets and ISO 13485 certification depth that creates renewal cliffs for smaller competitors. Saliva-based collection devices from oral fluid diagnostic specialists threaten pre-employment screening share; counter by embedding RFID serialization for decentralized chain-of-custody verification. For New Entrants and Emerging Players: Direct-to-consumer e-commerce channels offer the most penetrable route, bypassing entrenched distributor relationships that lock hospital and reference laboratory procurement. Target home testing applications with discreet single-panel formats and simplified result interpretation, leveraging wellness framing to attract consumers outside traditional occupational health channels. For Investors and Strategic Acquirers: Re-rating potential sits with specialized collection device manufacturers possessing notified body relationships and EU MDR technical documentation, given the regulatory renewal cliff favoring larger competitors. Monitor state-level cannabis legalization frameworks as inflection indicator for panel reconfiguration demand and testing menu contraction risk.| Strategic Initiative | Industry Significance |
|---|---|
| Medical-Grade Polymer Compounding Integration | Captive supply of FDA-compliant polypropylene reduces hurricane-season disruption exposure for Gulf Coast molders. |
| EU MDR Technical Documentation Investment | Biocompatibility and sterility assurance data generation creates renewal cliff advantage against legacy CE certificate holders. |
| RFID-Enabled Cup Development | Encrypted temperature logging compresses specimen rejection rates at Quest Diagnostics and Thermo Fisher reference laboratories. |
| Biodegradable Polymer Platform Launch | PLA and PHA material lines unlock environmentally contracted government tenders in European Union member states. |
| Home Testing Channel Partnership | Direct-to-consumer platform integration captures fastest-expanding segment outside traditional occupational health distribution. |
Methodological Framework
FDA 510(k) filings, OSHA regulatory guidance documents, and EU MDR notified body guidance formed the secondary backbone, cross-referenced against primary interviews with diagnostic supply chain managers, hospital GPO contract administrators, and occupational health clinic procurement officers. Bottom-up and top-down triangulation validated volume estimates across product type and application segments.
Bottom-up modeling anchored on installed base of immunoassay analyzers and specimen collection throughput per site, while top-down cross-checks drew from diagnostic distributor revenue disclosures and customs data for medical-grade polymer trade flows. Segmentation dimensions included product type, application environment, end-user procurement sophistication, and material platform. CAGRs derived from regression analysis against workplace drug testing policy expansion rates and clinical laboratory consolidation patterns.
Inputs from FDA 510(k) clearance databases and EU notified body technical file reviews were available through the study window; gaps in real-time pricing transparency for security-sealed versus standard cup tiers introduce uncertainty bands around margin structure estimates. Forecasts reflect assumptions regarding OSHA guideline enforcement intensity and state cannabis policy trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
Hbsag Testing Market
Testing Services
Zika Virus Testing Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Global Urinalysis Test Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Blood Testing Market
Testing Services
Global Virology Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Radiographic Testing Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Legionnaire Disease Testing Market