
 Sickle Cell Anemia Testing and Screening Market | 2026-2036
Sickle Cell Anemia Testing and Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Sickle Cell Anemia Testing and Screening Market Intelligence
The capital-intensity divergence between point-of-care developers and centralized laboratory platforms is unwinding competitive assumptions across the testing landscape. Quest Diagnostics leverages its national laboratory network to sustain high-throughput hemoglobin electrophoresis capacity. Bio-Rad Laboratories anchors its position through specialized reagent systems for sickle cell trait confirmation. PerkinElmer competes in newborn screening programs with integrated platform solutions for state public health laboratories.
Sickle cell anemia testing and screening encompasses diagnostic methodologies that detect hemoglobin S variants through electrophoretic separation, chromatographic quantification, or nucleic acid amplification, with sample throughput ranging from single-patient point-of-care cartridges to batch-processed neonatal dried blood spots. Hemoglobin electrophoresis occupies the largest installed base due to decades of clinical validation and reimbursement familiarity, while next-generation sequencing represents the fastest-expanding technology segment as payers gradually accept genomic confirmation for complex trait cases. Molecular diagnostics captures concentrated margin pools in prenatal and carrier screening applications where test complexity justifies premium pricing.
FDA oversight of in vitro diagnostic devices shapes product development timelines and clinical validation requirements for US market entry, while WHO guidelines on hemoglobinopathies influence procurement priorities in endemic regions. The EU In Vitro Diagnostic Regulation introduces new conformity assessment burdens for electrophoresis platforms and molecular assays seeking CE marking. Stakeholders must monitor evolving newborn screening panel expansions and point-of-care reimbursement decisions to align portfolio investments with shifting test location preferences.
Market Dynamics
Newborn screening panel expansions across state public health laboratories are compressing test turnaround times and forcing platform consolidation decisions among diagnostic infrastructure planners.
Growth Catalysts
- US FDA newborn screening guidelines:Expanded hemoglobinopathy inclusion criteria mandate testing protocol updates in state laboratories, creating sustained reagent demand.
- Sub-Saharan African disease burden:Nigeria, Ghana, and Democratic Republic of Congo concentrate over 75% of global sickle cell births, driving donor-funded screening program procurement.
- Point-of-care cartridge platforms:Lateral flow immunoassay miniaturization enables community-level screening without cold-chain logistics or laboratory infrastructure.
Market Restraints
- High-purity hemoglobin reagent costs:Electrophoresis-grade buffer systems and control materials face volatile pricing from limited specialty chemical suppliers.
- EU MDR conformity assessment:CE marking timelines for electrophoresis platforms extended 12-18 months, freezing new platform introductions.
- Next-generation sequencing substitution:Genomic confirmation protocols gradually displace repeat electrophoresis for complex trait resolution in academic medical centers.
Strategic Opportunities
- India national health mission integration:BIS standards alignment for hemoglobinopathy diagnostics opens centralized procurement at district hospital tier.
- Drone-enabled sample logistics:Dried blood spot collection networks bypass road infrastructure gaps in rural Kenya and Tanzania screening corridors.
- WHO prequalification pathway:Accelerated review for point-of-care sickle cell tests unlocks Global Fund and UNICEF procurement eligibility.
Industry Challenges
- Clinical laboratory scientist pipeline:Hemoglobin electrophoresis interpretation requires specialized training unavailable in many endemic-region medical technology programs.
- Laboratory information system integration:Newborn screening data exchange between hospital EHR platforms and state public health databases demands custom HL7 interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sickle Cell Anemia Testing and Screening Market |
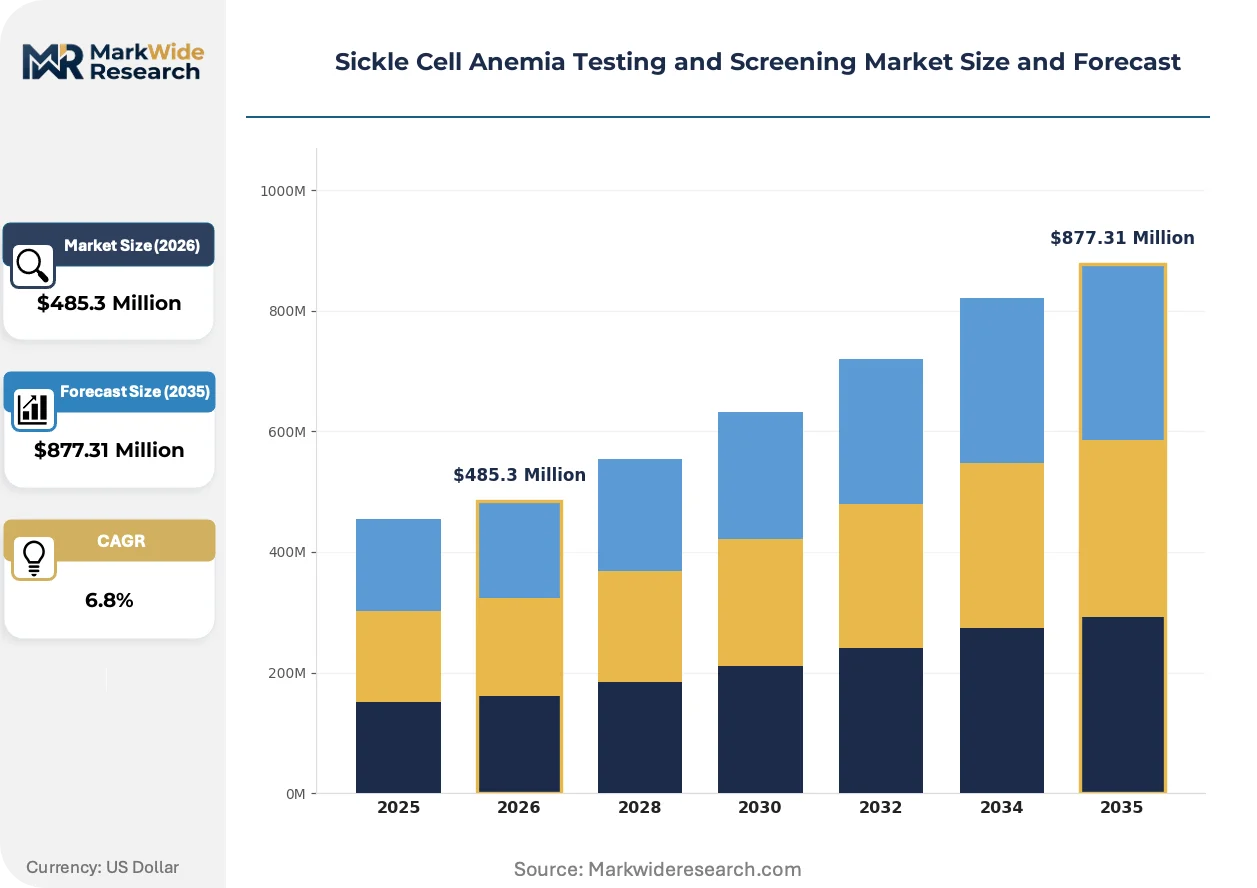
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Hemoglobin Electrophoresis, Newborn Screening, High-Performance Liquid Chromatography, DNA Analysis Technology: Molecular Diagnostics, Immunoassays, PCR, Next-Generation Sequencing End User: Hospitals, Diagnostic Laboratories, Specialty Clinics, Home Care Distribution Channel: Direct Sales, Third-Party Distributors, Online Platforms, Retail Pharmacies |
| Companies Covered | Quest Diagnostics, BioMedomics Inc., STRECK, INC., Silver Lake Research Corporation, HEMEX HEALTH, Bio-Rad Laboratories, Inc., PerkinElmer Inc., Daktari Diagnostics, Laboratory Corporation of America Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sickle Cell Anemia Testing and Screening Market Strategic Shifts & Innovations
Convergence of molecular diagnostic accuracy with point-of-care accessibility is restructuring where testing occurs and who controls result delivery.
Silicon photonic biosensor arrays for hemoglobin variant detection are miniaturizing laboratory-grade quantification into handheld devices. Community health worker programs in Senegal and Mali pilot these platforms for same-day screening and counseling. The technology is compressing the traditional referral cascade from village to district hospital to centralized laboratory.
EU In Vitro Diagnostic Regulation (IVDR) Class C reclassification of hemoglobin electrophoresis devices triggered notified body capacity constraints. Manufacturers face extended technical documentation requirements for clinical performance studies. State public health laboratories in Germany and France delay platform replacement cycles pending supplier certification completion.
Decentralized screening procurement through NGO and foundation channels now rivals government health ministry tenders in volume across West African markets. Partners in Health and the Sickle Cell Disease International Association coordinate pooled purchasing for point-of-care tests. Nigeria's federal Ministry of Health responds with framework contracting reforms to recapture volume leadership.
Sickle Cell Anemia Testing and Screening Market Segmentation
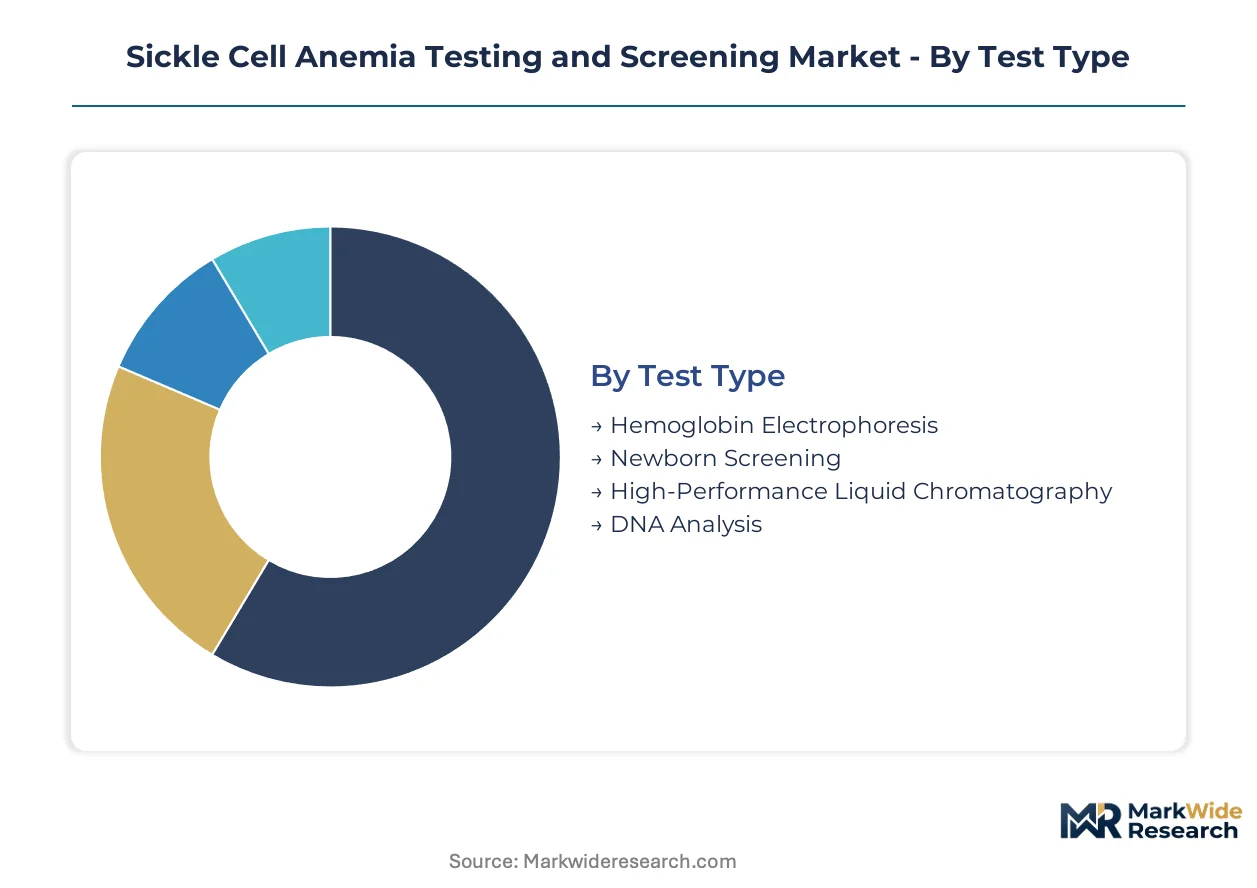
Test modality and access point configurations determine reimbursement pathways and procurement economics across the sickle cell testing landscape. Channel strategy varies sharply between centralized laboratory infrastructure and decentralized community screening programs.
Test Type:
Hemoglobin electrophoresis and newborn screening flow through state public health laboratory networks, while chromatography and DNA analysis concentrate in academic medical centers and specialty reference laboratories.
- Hemoglobin Electrophoresis:Separates hemoglobin variants by charge and size through cellulose acetate or agarose gel matrices. State public health laboratories in Nigeria and Ghana deploy high-throughput systems for newborn screening panels, with reagent contracts bundled into multi-year procurement frameworks.
- Newborn Screening:Dried blood spot collection protocols with standardized filter paper matrices enable population-scale hemoglobinopathy detection. US state laboratories and sub-Saharan African national programs represent the concentrated demand base, driven by WHO guidelines and donor-funded health system strengthening initiatives.
- High-Performance Liquid Chromatography:Quantifies hemoglobin fractions with superior resolution for variant confirmation. Academic medical centers in India and Brazil favor HPLC for complex trait resolution where electrophoresis yields ambiguous patterns.
- DNA Analysis:Targets specific point mutations in the HBB gene for prenatal and carrier screening applications. Molecular diagnostic laboratories in Saudi Arabia and the United Kingdom utilize DNA analysis for family planning counseling in high-prevalence populations.
Hemoglobin electrophoresis dominates installed base. DNA analysis is where expansion concentrates.
Technology:
Platform selection tracks laboratory infrastructure maturity, with molecular methods commanding premium pricing in developed health systems and immunoassays penetrating resource-limited settings.
- Molecular Diagnostics:Encompasses allele-specific PCR and probe hybridization for definitive genotype confirmation. Prenatal diagnostic centers in France and Italy rely on molecular methods for fetal risk assessment in at-risk pregnancies.
- Immunoassays:Lateral flow and ELISA formats enable point-of-care deployment without cold-chain requirements. Community health worker programs in Mali and Burkina Faso pilot immunoassay platforms for same-day screening and counseling.
- PCR:Amplifies target DNA sequences with high analytical sensitivity for low-template samples. Regional reference laboratories in Kenya and Tanzania maintain PCR capacity for quality assurance of field screening results.
- Next-Generation Sequencing:Delivers comprehensive hemoglobin variant detection with concurrent thalassemia screening. Genomic medicine programs in Germany and the Netherlands adopt NGS for multiplexed rare disease panels including sickle cell traits.
Molecular diagnostics commands margin concentration. Next-generation sequencing is climbing the fastest.
End User:
Site-of-care economics fragment procurement authority between hospital laboratory directors, public health program managers, and retail channel purchasers.
- Hospitals:Integrated health systems manage inpatient diagnostic pathways and emergency department sickle cell crisis confirmation. Tertiary hospitals in Lagos and Kinshasa anchor regional referral networks for complex case management.
- Diagnostic Laboratories:Independent and hospital-affiliated laboratories process outsourced testing for physician practices. Quest Diagnostics and similar networks in the United States sustain high-throughput electrophoresis operations through volume aggregation.
- Specialty Clinics:Hematology and genetics centers deliver targeted counseling alongside diagnostic services. Sickle cell specialty clinics in London and Paris coordinate multidisciplinary care with embedded laboratory capacity.
- Home Care:Self-testing applications remain nascent, with fingerstick hemoglobin analyzers emerging for chronic disease monitoring. Pilot programs in the United States explore home-based hydroxyurea response tracking.
Diagnostic laboratories capture volume leadership. Specialty clinics concentrate value per test.
Distribution Channel:
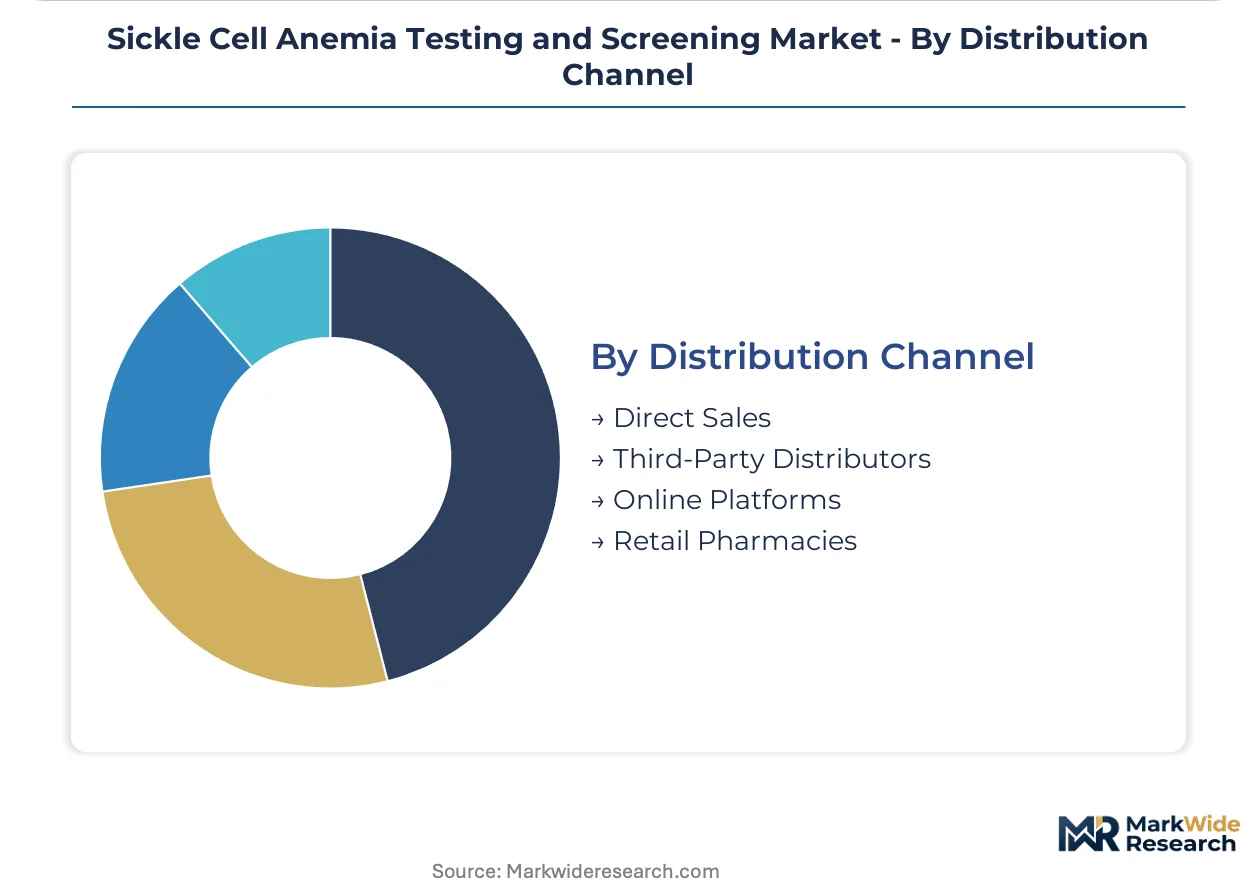
Channel structure reflects equipment-versus-consumable mix, with capital platforms flowing through direct sales and reagents diversifying into distributor networks.
- Direct Sales:Manufacturer field teams negotiate electrophoresis platform placements and service contracts. Bio-Rad Laboratories and PerkinElmer deploy direct salesforces for state laboratory and academic medical center accounts.
- Third-Party Distributors:Regional medical supply houses manage logistics for reagents and consumables. West African distributors buffer inventory for government tender fulfillment across Nigeria, Ghana, and Côte d'Ivoire.
- Online Platforms:E-procurement portals streamline reordering for standardized consumables. US hospital systems increasingly route dried blood spot cards and control materials through contracted e-commerce channels.
- Retail Pharmacies:Limited current penetration, with potential expansion for over-the-counter screening kits. Pharmacy chains in South Africa pilot point-of-care sickle cell testing alongside HIV and malaria rapid diagnostics.
Direct sales anchor platform revenue. Third-party distributors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing platform exports from US and German manufacturers flow toward sub-Saharan African procurement programs, while reagent imports concentrate in national laboratory systems lacking domestic production capacity. This trade pattern shapes regional infrastructure investment priorities.
United States
Newborn screening mandates in all 50 states sustain demand for high-throughput electrophoresis systems, with state public health laboratories operating as centralized procurement nodes. FDA oversight of in vitro diagnostic devices extends validation timelines for platform updates. Boston and Research Triangle Park anchor commercial laboratory networks processing outsourced hemoglobinopathy testing.
Nigeria
Federal Ministry of Health framework contracting reforms target recapture of procurement volume from NGO channels. WHO prequalification pathways unlock Global Fund eligibility for point-of-care test imports. Lagos and Abuja concentrate specialty hematology referral capacity for complex trait confirmation.
Germany
EU IVDR Class C reclassification of electrophoresis devices triggers notified body capacity constraints extending certification timelines. Genomic medicine programs in Heidelberg and Berlin adopt next-generation sequencing for multiplexed rare disease panels. Academic medical centers drive substitution toward molecular confirmation protocols.
India
BIS standards alignment for hemoglobinopathy diagnostics opens centralized procurement at district hospital tier under National Health Mission integration. Maharashtra and Karnataka anchor regional reference laboratory networks for quality assurance of field screening results. State-level tender fragmentation complicates vendor consolidation.
Brazil
Ministry of Health newborn screening expansion targets universal hemoglobinopathy coverage in high-prevalence Northeast regions. ANVISA regulatory pathways for imported diagnostic platforms require local clinical validation studies. São Paulo and Rio de Janeiro concentrate academic medical center capacity for HPLC-based complex trait resolution.
Sickle Cell Anemia Testing and Screening Market Key Industry Players
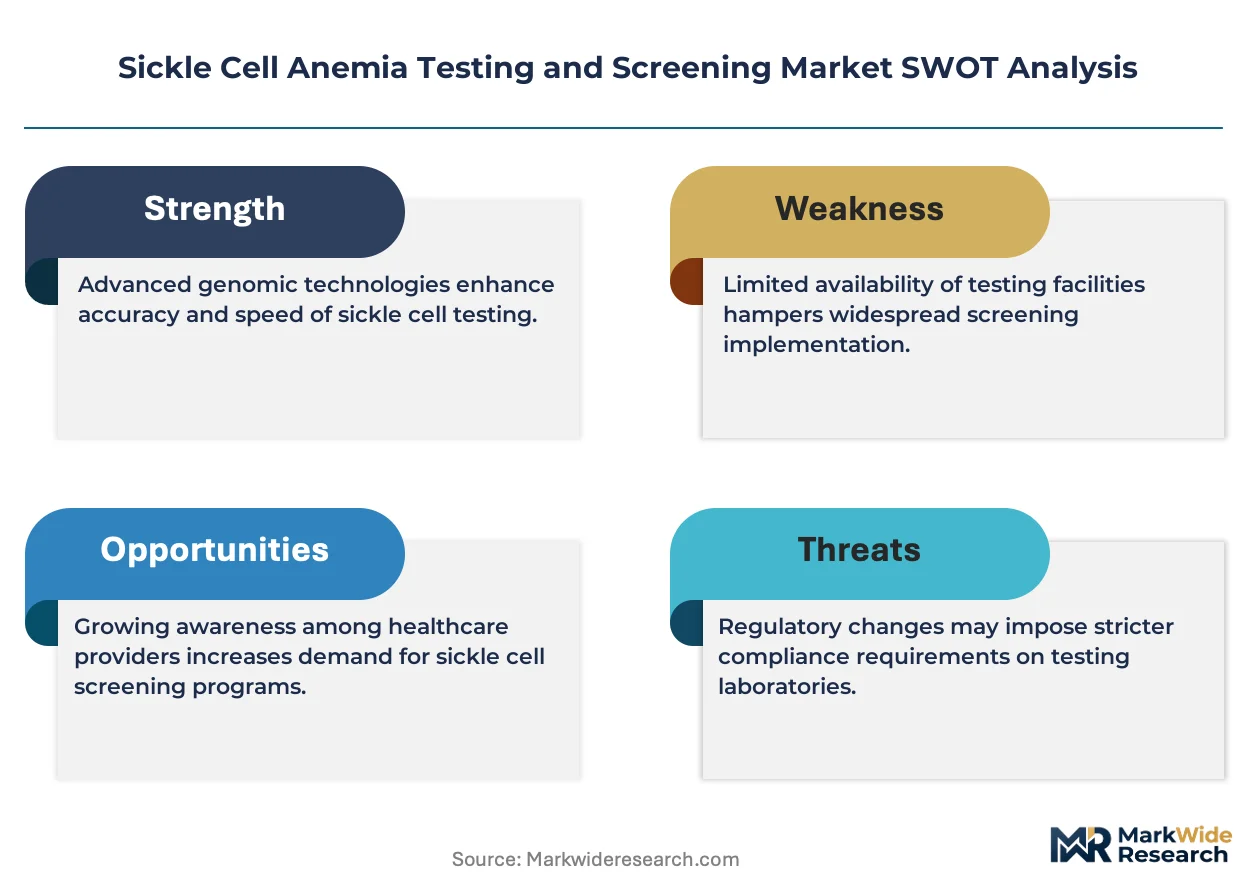
Concentration sits with diversified laboratory conglomerates and specialized diagnostic platform developers. The vendor base splits between national laboratory networks leveraging scale aggregation and point-of-care innovators penetrating resource-limited settings. Two strategic archetypes dominate: integrated platform suppliers bundling hardware, reagents, and service contracts; and cartridge-based developers prioritizing cold-chain independence. Competitive moves center on multi-year procurement framework capture and point-of-care miniaturization to bypass laboratory infrastructure gaps.
Among US-based laboratory services conglomerates, Quest Diagnostics and Laboratory Corporation of America Holdings exemplify the volume-aggregation archetype through national network coverage. Specialized platform developers include Bio-Rad Laboratories, representing the integrated reagent-system approach, and PerkinElmer, occupying a position within newborn screening program infrastructure. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Quest Diagnostics |
| BioMedomics Inc. |
| STRECK, INC. |
| Silver Lake Research Corporation |
| HEMEX HEALTH |
| Bio-Rad Laboratories, Inc. |
| PerkinElmer Inc. |
| Daktari Diagnostics |
| Laboratory Corporation of America Holdings |
| Others |
Cost & Logistics Intelligence
Ninety-day reagent inventory buffers at Nigerian state laboratories signal procurement concentration that amplifies supplier pricing power against fragmented public health buyers. This lead-time asymmetry between electrophoresis-grade hemoglobin suppliers and national screening programs structures contract negotiation leverage across sub-Saharan procurement corridors.
Pricing Analysis
Configured-to-order electrophoresis platform pricing commands a substantial premium over standard cartridge-based immunoassay configurations in donor-funded screening programs. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling, with FDA-cleared systems capturing margin premiums against CE-marked alternatives. Cost compression in economy-tier lateral flow tests is intensifying because WHO prequalification pathways are unlocking pooled NGO procurement volumes. Public health ministries exhibit highest price sensitivity, while academic medical centers demonstrate lowest sensitivity due to research grant funding flexibility.
Supply Chain Analysis
Port congestion at Lagos and Mombasa elevates inbound logistics costs for dried blood spot filter papers and control materials sourced from North American and European manufacturers. Specialty chemical production concentrates in Germany, the United States, and Japan for electrophoresis-grade buffer systems, while cellulose acetate membrane fabrication draws from a narrower supplier base in Italy and the United Kingdom. Single-source vulnerability in high-purity hemoglobin control materials threatens screening program continuity. Distribution runs through regional medical supply houses in West Africa that buffer inventory against government tender delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interpretation-capable laboratory scientists represent the constraining asset class across endemic-region screening scale-up, with training pipeline gaps limiting throughput expansion regardless of equipment procurement budgets.
For Market Incumbents: Compound installed base advantages through multi-year reagent service contracts that lock out point-of-care cartridge substitutes in state laboratory networks. Deepen backward integration into hemoglobin control material production to buffer against specialty chemical supplier volatility. Next-generation sequencing substitution in academic medical centers poses the primary technology displacement threat. For New Entrants and Emerging Players: WHO prequalification fast-track pathways unlock Global Fund and UNICEF procurement eligibility that bypasses government tender fragmentation. Rural Kenya and Tanzania present the most penetrable geography for drone-enabled dried blood spot logistics bypassing road infrastructure gaps. Community health worker deployment models offer the clearest go-to-market angle against centralized laboratory incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a public health infrastructure play because donor-funded screening program sustainability is tethered to endemic-region government budget absorption capacity. Acquisition targets should display point-of-care miniaturization capabilities with cold-chain independence and existing NGO distribution relationships. The signal to watch is Nigeria's federal Ministry of Health framework contracting reform progress against NGO channel volume recapture.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks Global Fund and UNICEF procurement eligibility for point-of-care test manufacturers in West Africa. |
| Drone-Enabled Sample Logistics | Bypasses road infrastructure gaps in rural Kenya and Tanzania screening corridors for dried blood spot networks. |
| CE Marking Pathway | EU IVDR Class C reclassification extends certification timelines for electrophoresis platform suppliers in Germany and France. |
| Hospital System Partnership | Academic medical centers in India and Brazil anchor HPLC-based complex trait resolution referral networks. |
| Reimbursement Strategy | State public health laboratory newborn screening panel expansions in the United States sustain reagent demand contracts. |
Research Approach
A standing panel of state public health laboratory directors, hematology reference laboratory managers, donor agency procurement officers, and biomedical equipment distributors provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, WHO prequalification listings, state newborn screening program annual reports, and EU IVDR notified body certification databases. Bottom-up test volume estimates triangulated against top-down procurement budget allocations across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including national health expenditure accounts, Global Fund disbursement records, and UNICEF supply division procurement disclosures. Segmentation modeling tracked test type, technology platform, end-user site of care, and distribution channel across the projection horizon. CAGRs derived from logistic diffusion curves fitted to newborn screening coverage expansion rates and point-of-care test adoption patterns in endemic-region pilot programs. Reagent pricing trajectories incorporated specialty chemical input cost indices and donor funding cycle volatility.
Decision-makers should treat outputs as directional under assumptions of sustained donor health system strengthening commitments and stable regulatory approval pathways; material deviation in either would warrant model refresh. Forecasts reflect these base conditions without contingency for abrupt trade restriction imposition or pandemic-scale health system disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Allergy Skin Test Market
Testing Services
Americas Sterility Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
Drug Tester Market
Testing Services
Home DNA Testing Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Continuous Tablet Manufacturing At-Line Quality Test Systems Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Over-The-Counter Tests Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Ige Allergy Blood Tests Market