
 Global Multiplex Assays Market | 2026-2036
Global Multiplex Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multiplex Assays Market Foresight
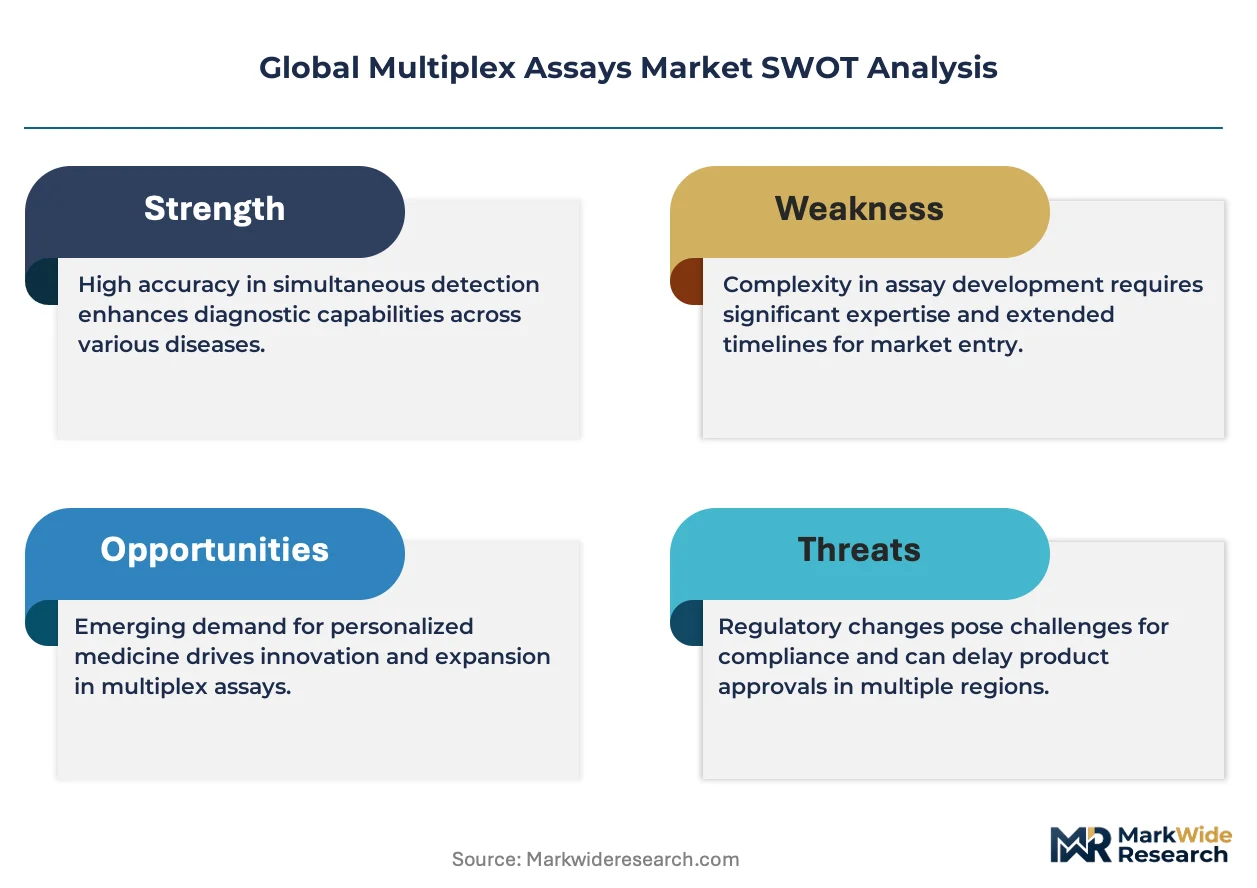
IVDR certification under the EU 2017/746 framework is reorganizing competitive access across European clinical diagnostics, forcing manufacturers to rebuild technical documentation and performance evidence portfolios. Thermo Fisher Scientific leverages its end-to-end platform integration to sustain dominant positions in high-throughput clinical laboratories. QIAGEN NV anchors its competitive stance through automated sample-to-insight workflows that reduce hands-on time for molecular multiplexing. Bio-Rad Laboratories differentiates via droplet digital PCR compatibility with multiplex panels, occupying a specialized niche in rare mutation detection.
Multiplex assays simultaneously detect and quantify multiple analytes within a single reaction vessel, typically measuring dozens to thousands of targets through spatial encoding, spectral differentiation, or microcarrier segregation with detection thresholds reaching picogram-per-milliliter sensitivity. Their primary commercial purpose centers on accelerating biomarker discovery, streamlining drug development safety profiling, and enabling comprehensive disease characterization from minimal sample volumes. Bead-based assays lead clinical diagnostics adoption due to workflow standardization and regulatory precedent, while mass spectrometry multiplexing represents the fastest-expanding technology segment as proteomics laboratories demand label-free quantification with broader dynamic range. Drug development applications command the deepest margin pools because pharmaceutical corporations require customized multiplex panels with extensive analytical validation support.
FDA premarket notification pathways and IVDR technical documentation requirements shape product development timelines and commercial launch sequencing for assay manufacturers seeking dual-territory approval. The EPA and OECD test guideline frameworks additionally govern environmental testing multiplex applications, particularly for water quality and toxicological screening panels. Stakeholders must monitor evolving harmonization efforts between FDA and EMA biomarker qualification programs, as divergent evidentiary standards threaten to fragment global product development strategies and inflate regulatory compliance costs.
Market Dynamics
IVDR 2017/746 is compressing commercial timelines for multiplex assay manufacturers by mandating expanded clinical performance documentation before CE marking, forcing portfolio reprioritization toward high-volume diagnostic categories where validation costs amortize across larger installed bases.
Growth Catalysts
- Companion diagnostic mandates:FDA's increasing requirement for biomarker-stratified enrollment in oncology trials is pulling multiplex panels into front-line pharmaceutical development workflows.
- Precision medicine infrastructure:Germany's Hospital Future Act and similar facility modernization programs across China are embedding high-throughput multiplexing capacity into centralized laboratory networks.
- Mass spectrometry convergence:Label-free proteomic quantification methods are displacing fluorescent bead systems in academic research settings, opening new instrument placement cycles.
Market Restraints
- Reagent supply concentration:Polymerase and fluorescent dye production clusters in select East Asian contract manufacturers create input vulnerability for assay kit producers.
- IVDR technical documentation burden:The European regulation's expanded clinical evidence requirements extend product registration timelines by 18-36 months for novel multiplex platforms.
- Digital PCR substitution:Droplet digital PCR systems from Bio-Rad and others offer absolute quantification without standard curves, capturing rare mutation detection applications from traditional multiplex.
Strategic Opportunities
- India's diagnostic network expansion:The country's National Health Mission and PLI scheme for medical devices are creating first-mover advantages for multiplex platforms meeting CDSCO manufacturing localization requirements.
- Environmental toxicology panels:EPA and OECD test guideline harmonization is standardizing multiplex adoption for water quality screening in municipal utilities.
- Artificial intelligence integration:Machine learning-assisted pattern recognition from complex multiplex readouts is compressing interpretation time for clinical laboratories.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of computational biologists capable of validating multiplex signature algorithms against clinical outcomes is throttling panel development velocity.
- Instrument-platform lock-in:Proprietary bead chemistries and fluidic architectures fragment reagent ecosystems, complicating laboratory procurement standardization efforts.
- Legacy LIS integration:Hospital information systems built for single-analyte reporting require expensive middleware development to accommodate multiplex data structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multiplex Assays Market |
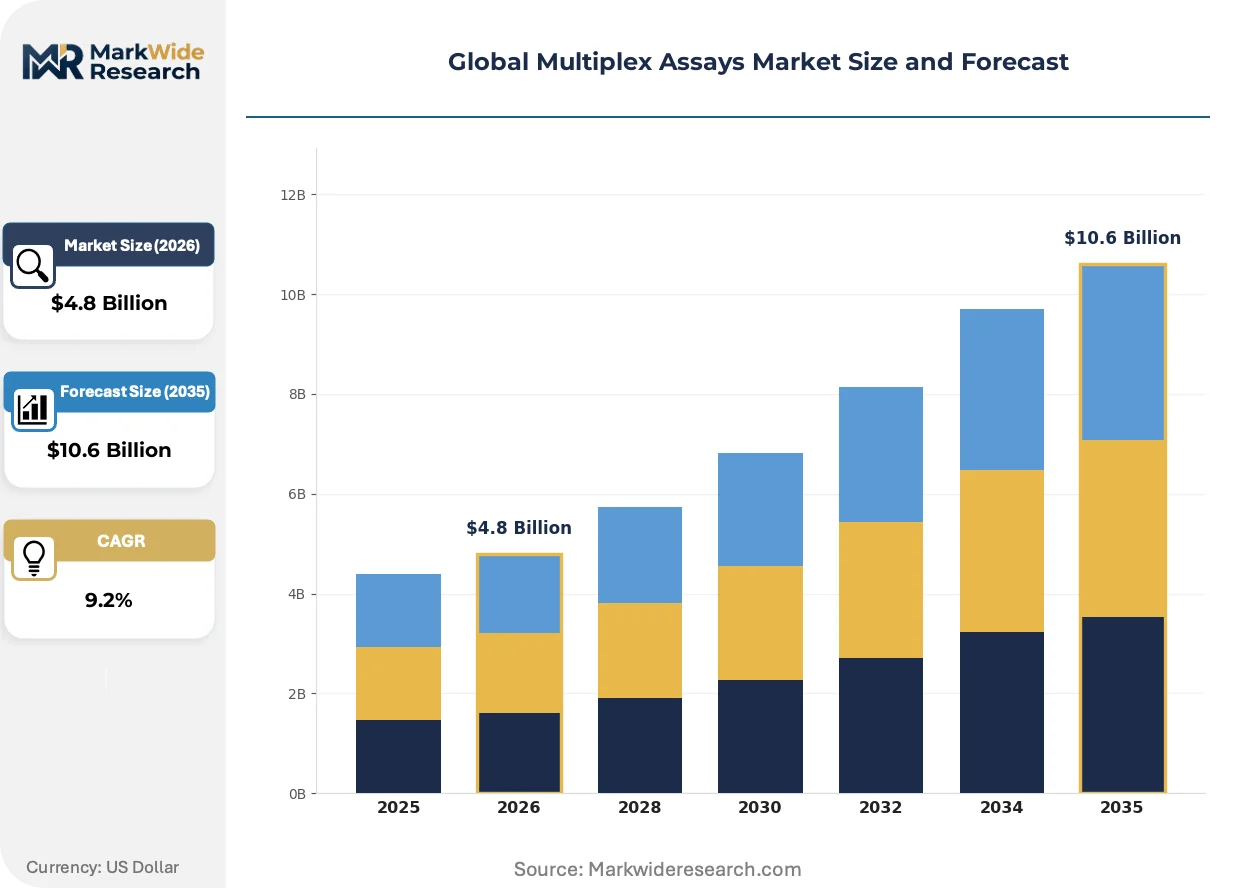
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bead-based Assays, Microarray-based Assays, Enzyme-linked Immunosorbent Assays, DNA Microarrays, Protein Microarrays Application: Biomarker Discovery, Drug Development, Genetic Testing, Clinical Diagnostics, Environmental Testing End User: Biotechnology Firms, Pharmaceutical Corporations, Academic Research Centers, Contract Research Organizations, Forensic Laboratories Technology: Fluorescence Detection, Chemiluminescence, Electrochemiluminescence, Surface Plasmon Resonance, Mass Spectrometry |
| Companies Covered | Thermo Fisher Scientific Inc., Illumina Inc., Bio-Rad Laboratories Inc., Luminex Corporation, Becton Dickinson and Company, QIAGEN NV, Agilent Technologies Inc., Abcam PLC, Meso Scale Diagnostics LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multiplex Assays Market Shifts & Advancements
Multiplex assay architectures are converging with microfluidic engineering and computational biology, compressing reaction volumes while expanding analyte density. These shifts are redrawing competitive boundaries between instrument manufacturers and reagent suppliers.
Digital microfluidic platforms are miniaturizing reaction volumes to nanoliter scales while preserving detection sensitivity through electrowetting-based droplet manipulation. Pharmaceutical toxicology groups at contract research organizations are adopting these systems for high-content safety screening. The technology is miniaturizing capital footprints for multiplex workflows, enabling distributed deployment beyond centralized reference laboratories.
EMA's qualification program for novel methodologies is creating accelerated pathways for multiplex biomarker panels in drug development, provided sponsors submit prospectively designed analytical validation packages. This regulatory architecture favors manufacturers with dedicated clinical affairs teams capable of managing parallel FDA and EMA submission strategies. Oncology therapeutic areas are responding with the most structured qualification investments.
Consolidated procurement by multi-hospital health systems is displacing individual laboratory purchasing autonomy, favoring vendors offering enterprise-wide service contracts with predictable per-test pricing. Integrated delivery networks in the United States are negotiating multi-year sole-source agreements that bundle instruments, reagents, and informatics support. This concentration is most pronounced in states with dominant regional health systems such as California and Texas.
Global Multiplex Assays Market Segmentation
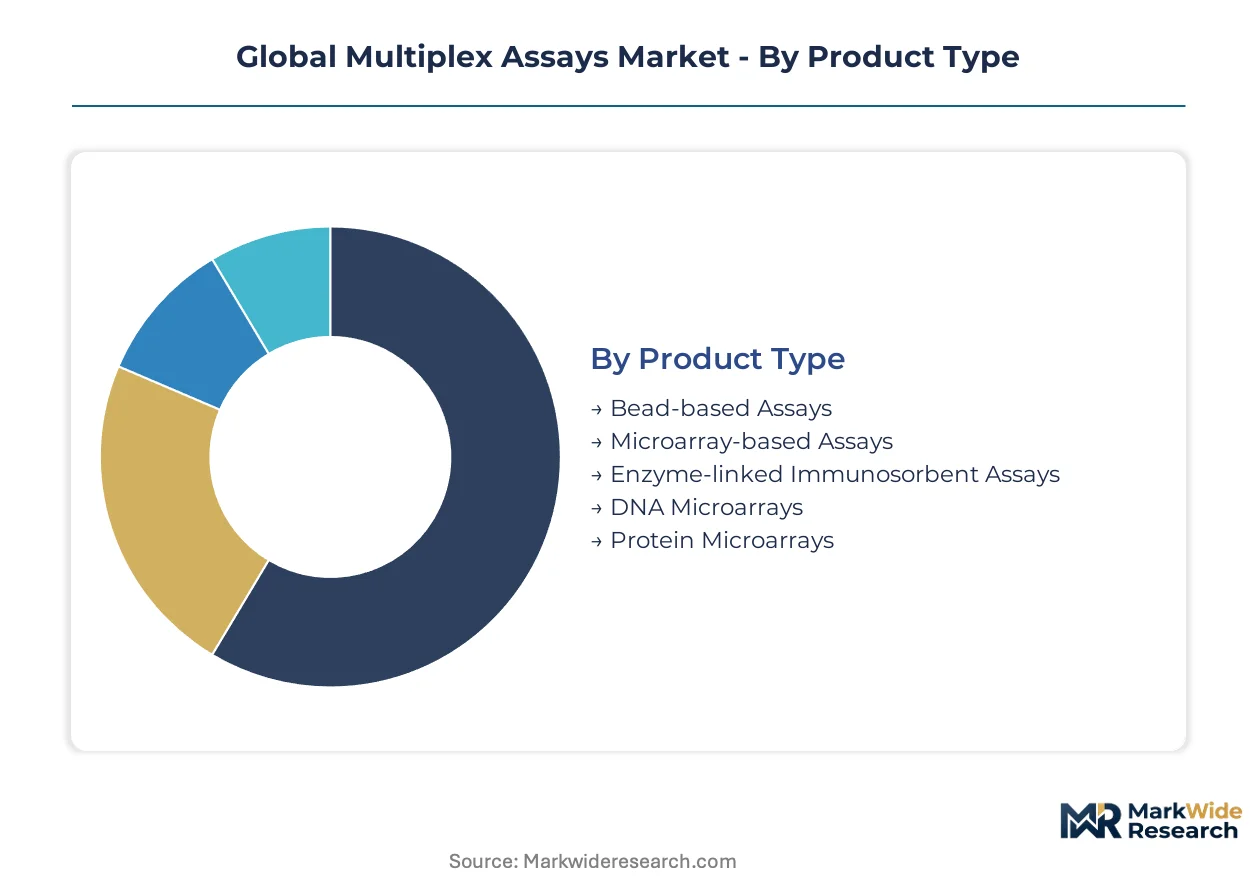
Segmentation in the multiplex assays market reveals how substitution pressures and technology transitions reshape competitive boundaries across product architectures and detection modalities. Understanding these fault lines guides portfolio positioning against both established platforms and emerging alternatives.
Product Type:
Bead-based platforms face intensifying substitution pressure from label-free mass spectrometry methods in proteomics workflows, while microarray systems confront digital PCR displacement in rare variant detection.
- Bead-based Assays:Suspension arrays using fluorescent-coded microspheres enable simultaneous quantification of up to 500 analytes per well with standardized workflow protocols. Demand concentrates in United States clinical reference laboratories where FDA-cleared panels for cytokine profiling and infectious disease serology anchor routine testing menus. IVDR technical documentation requirements are compressing European commercial timelines for novel bead-based kits.
- Microarray-based Assays:Solid-phase spatial encoding on glass or silicon substrates delivers highest-density analyte mapping for genome-wide association studies. Academic research centers in Germany and China represent the strongest demand concentration as national precision medicine initiatives fund population-scale genotyping infrastructure. The segment confronts pricing pressure from next-generation sequencing substitution in expression profiling applications.
- Enzyme-linked Immunosorbent Assays:Traditional colorimetric sandwich formats retain cost advantages for low-plex cytokine panels in resource-limited settings.
- DNA Microarrays:Oligonucleotide tiling designs support copy number variation detection in constitutional cytogenetics laboratories.
- Protein Microarrays:Functional protein printing enables autoantibody profiling for rheumatology diagnostic development.
Bead-based assays anchor the volume base while mass spectrometry convergence drives the steepest share gains in research settings.
Application:
Margin structures diverge sharply across applications, with pharmaceutical development commanding premium pricing for customized validation support versus standardized clinical diagnostics.
- Drug Development:Safety pharmacology and toxicokinetic screening require bespoke multiplex panels with extensive analytical validation documentation. Contract research organizations in United States and China represent concentrated demand as FDA and NMPA mandate biomarker-stratified enrollment in oncology trials. Sponsors pay substantial premiums for companion diagnostic co-development partnerships.
- Biomarker Discovery:Untargeted proteomic and transcriptomic profiling demands highest-plex platforms with minimal sample consumption. Academic medical centers in Germany lead European adoption through BMBF-funded systems medicine consortia. The segment exhibits longest sales cycles due to publication-driven purchasing decisions.
- Genetic Testing:Carrier screening and pharmacogenomic panels target mid-plex density with CLIA laboratory workflow integration.
- Clinical Diagnostics:Infectious disease syndromic panels and autoimmune profiling concentrate in hospital laboratory networks seeking operational efficiency.
- Environmental Testing:EPA and OECD harmonized water quality panels create standardized demand from municipal utilities and industrial compliance laboratories.
Clinical diagnostics generates the largest installed base while drug development applications expand most quickly through companion diagnostic mandates.
End User:
Procurement authority is shifting from individual principal investigators to centralized core facilities and enterprise purchasing functions across user categories.
- Pharmaceutical Corporations:Integrated discovery-to-development workflows demand vendor partnerships spanning reagent supply, instrument placement, and regulatory submission support. United States-based oncology therapeutic area teams represent the deepest contract values for multiplex biomarker programs. Procurement consolidation under global category management is compressing supplier margins.
- Contract Research Organizations:Toxicology service providers require high-throughput platforms with 24-hour turnaround capabilities for safety screening studies. Chinese CROs are expanding capacity most aggressively under domestic pharmaceutical innovation policies. Equipment leasing models predominate over capital purchase.
- Biotechnology Firms:Venture-backed discovery platforms prioritize flexibility over throughput in early-stage target validation.
- Academic Research Centers:Core facility centralization is displacing departmental instrument ownership in United States and European institutions.
- Forensic Laboratories:STR multiplex kits for human identification follow rigid FBI Quality Assurance Standards compliance requirements.
Pharmaceutical corporations anchor the revenue base while contract research organizations are climbing the fastest as outsourcing penetration deepens.
Technology:
Detection modality selection determines capital intensity, reagent ecosystem lock-in, and compatibility with emerging sample types including single-cell suspensions.
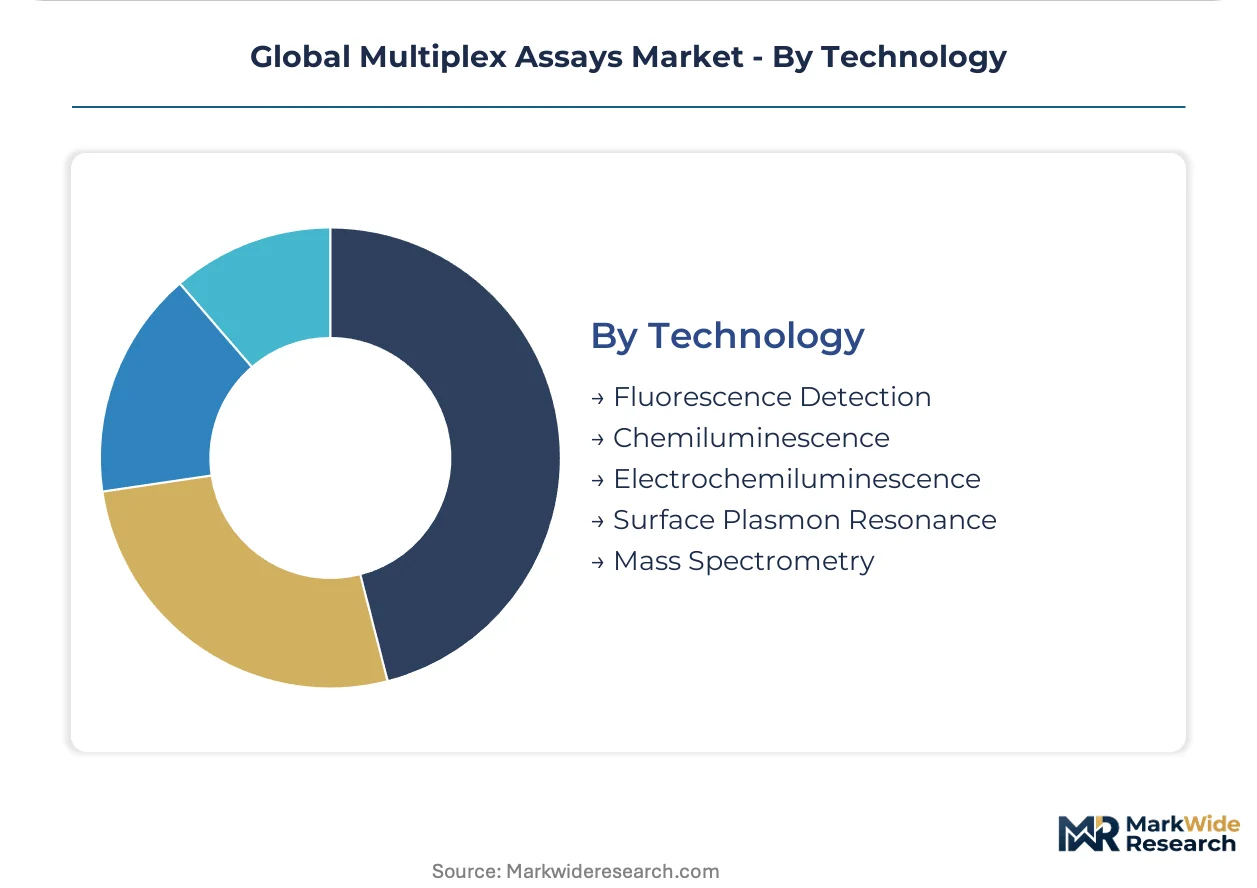
- Mass Spectrometry:Label-free quantification via multiple reaction monitoring or data-independent acquisition eliminates antibody dependence and extends dynamic range across four orders of magnitude. Proteomics core facilities in Germany and United States are displacing fluorescent bead systems for biomarker verification workflows. Instrument vendors are bundling informatics pipelines to reduce bioinformatics talent barriers.
- Fluorescence Detection:Spectral unmixing of organic dye signatures remains the dominant clinical modality due to regulatory precedent and workflow familiarity. Centralized laboratory networks in China are standardizing on fluorescence-based platforms under Hospital Future Act modernization funding. The technology confronts autofluorescence interference in complex matrices.
- Chemiluminescence:Enzymatic signal amplification delivers femtomolar sensitivity for low-abundance analyte detection in immunodiagnostics.
- Electrochemiluminescence:Meso Scale Discovery platforms dominate immunogenicity testing for biologic drug development.
- Surface Plasmon Resonance:Label-free binding kinetics support antibody screening in early discovery without reporter conjugation requirements.
Fluorescence detection anchors the installed base while mass spectrometry gains share at the steepest rate through proteomics laboratory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains the deepest installed base of high-throughput clinical multiplexing infrastructure, anchored by the Boston-Cambridge biotech corridor and San Diego's precision medicine cluster. Germany's dense network of university hospital laboratories and the Rhine-Main biotechnology hub concentrate European demand for automated sample-to-insight workflows.
United States
FDA companion diagnostic mandates for oncology trials pull multiplex panels into pharmaceutical development pipelines. The Hospital Future Act and NIH precision medicine initiatives fund centralized laboratory modernization. Boston's Kendall Square biotech cluster anchors contract research organization demand for biomarker validation services.
Germany
BMBF-funded systems medicine consortia drive academic adoption of high-plex proteomic platforms. IVDR 2017/746 technical documentation requirements compress commercial timelines for novel assay kits. The Rhine-Main region's university hospital network standardizes on automated molecular multiplexing workflows.
China
NMPA biomarker-stratified enrollment requirements expand pharmaceutical multiplex adoption. The Hospital Future Act modernization program embeds high-throughput capacity into tertiary hospital networks. Shanghai's Zhangjiang Hi-Tech Park concentrates domestic instrument manufacturing and CRO toxicology services.
India
CDSCO manufacturing localization requirements under the PLI scheme for medical devices create first-mover incentives. The National Health Mission expands diagnostic network infrastructure into tier-2 cities. Hyderabad's Genome Valley anchors contract research capacity for multiplex biomarker programs.
United Kingdom
NIHR biomedical research center funding sustains academic multiplex adoption for translational studies. MHRA post-Brexit regulatory divergence from EMA creates parallel submission pathways for assay manufacturers. The Cambridge-London life sciences corridor concentrates precision medicine infrastructure investment.
Global Multiplex Assays Market Competitive Landscape
Listed life sciences conglomerates compete with private specialists across platform integration depth and regulatory submission bandwidth. Market structure tilts toward consolidated procurement power as multi-hospital health systems negotiate enterprise-wide service contracts. Three archetypes dominate: end-to-end platform integrators, automated workflow specialists, and detection modality purists. Competitive moves concentrate on strategic partnerships for companion diagnostic co-development and geographic expansion into CDSCO-compliant manufacturing jurisdictions.
Among detection modality specialists, Bio-Rad Laboratories Inc. and Meso Scale Diagnostics LLC exemplify technology-specific positioning strategies. Thermo Fisher Scientific Inc. anchors the platform integration archetype through instrument-reagent-informatics bundling. These three entities occupy positions spanning the competitive spectrum from specialized rare mutation detection to comprehensive clinical laboratory outsourcing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Illumina Inc. |
| Bio-Rad Laboratories Inc. |
| Luminex Corporation |
| Becton Dickinson and Company |
| QIAGEN NV |
| Agilent Technologies Inc. |
| Abcam PLC |
| Meso Scale Diagnostics LLC |
| Others |
Supply & Pricing Matrix
Mass spectrometry displacement of fluorescent bead systems simultaneously redraws supply geography toward German and United States proteomics clusters while compressing reagent pricing power for traditional polymerase-dependent kit manufacturers facing label-free competition.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus research-use-only) creates the primary spread across multiplex assay tiers, with IVDR 2017/746 CE-marked products commanding intermediate positioning. Three-tier pricing structure separates premium companion diagnostic co-development contracts from standard clinical reference laboratory panels and economy-grade research screening kits. Pricing pressure stems from consolidated procurement by United States multi-hospital health systems negotiating enterprise-wide per-test contracts. Academic research centers exhibit highest price sensitivity, while pharmaceutical development teams prioritize analytical validation depth over unit cost.
Supply Chain Analysis
Inventory cycles for fluorescent dyes and polymerase enzymes extend lead times for assay kit producers sourcing from concentrated East Asian contract manufacturers. Polymerase production clusters in China and South Korea, while high-purity fluorescent dye synthesis concentrates in Japan and Germany. Single-source vulnerability pervades rare earth-dependent bead chemistries essential for Luminex-compatible suspension arrays. Distribution runs through specialized life sciences distributors serving hospital networks and CRO toxicology facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multiplex assays market sits at a technology inflection where mass spectrometry convergence and IVDR regulatory compression favor platform-integrated incumbents with parallel FDA-EMA submission bandwidth.
For Market Incumbents: Consolidate regulatory affairs capabilities to manage simultaneous FDA premarket notification and IVDR technical documentation pathways, compressing launch sequencing gaps. Deepen backward integration into proprietary bead chemistries and fluidic architectures to defend against reagent ecosystem fragmentation. Prioritize companion diagnostic co-development partnerships with oncology therapeutic area teams as the deepest margin pool. For New Entrants and Emerging Players: Lead with AI-integrated pattern recognition software for multiplex data interpretation, targeting bioinformatics talent scarcity as the unmet need. Penetrate India's tier-2 diagnostic network expansion under CDSCO manufacturing localization requirements. Position through equipment-leasing models rather than capital sales to match CRO procurement preferences. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automated workflow specialists with installed base density. Long-term viability hinges on regulatory submission bandwidth across FDA and EMA jurisdictions. Target acquisition profiles center on mid-cap platform manufacturers with validated IVDR documentation packages. Watch EMA-FDA biomarker qualification program harmonization efforts as the signal for global product development cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | CE marking timelines compress by 18-36 months without expanded clinical evidence portfolios. |
| Companion Diagnostic Co-Development Partnership | FDA oncology trial mandates pull multiplex panels into pharmaceutical sponsor workflows. |
| Mass Spectrometry Platform Integration | Label-free proteomics displacement of bead systems opens instrument placement cycles. |
| CDSCO-Compliant Manufacturing Localization | India's PLI scheme creates first-mover positioning in tier-2 diagnostic network expansion. |
| AI-Assisted Multiplex Data Interpretation | Machine learning compression of analysis time addresses bioinformatics talent scarcity. |
Research Methodology
Operator-level perspectives from clinical laboratory directors, regulatory affairs specialists at assay manufacturers, pharmaceutical biomarker program leads, and hospital procurement managers anchored the qualitative base. Primary intelligence combined with secondary validation against FDA 510(k) clearances, EMA qualification program submissions, IVDR notified body documentation, and ClinicalTrials.gov biomarker-stratified enrollment records. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down pharmaceutical R&D spending allocations.
Sensitivity analysis tested forecast robustness across regulatory approval timeline scenarios and technology substitution rates. Segmentation modeling spanned product architecture, detection modality, application purpose, end-user category, and geographic regulatory cluster. CAGRs derived from weighted average of historical placement cycles, replacement demand patterns, and precision medicine infrastructure investment trajectories. Companion diagnostic mandate intensity and mass spectrometry convergence velocity served as key forecast inputs.
Forecasts assume regulatory continuity in FDA premarket notification and IVDR 2017/746 frameworks; material policy shifts would require re-modeling. Outputs reflect assumptions of stable polymerase supply chains and continued pharmaceutical outsourcing penetration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Rapid Coagulation Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Toxicology Testing Services Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Medical Device Analytical Testing Outsourcing Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Zika Virus Testing Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Urodynamic Testing Market
Testing Services
Global GMP Testing Service Market
Testing Services
Autoimmune Disease Testing Market