
 Global Terminal Sterilization Services Market | 2026-2036
Global Terminal Sterilization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Terminal Sterilization Services Market Foresight
Ethylene oxide is decoupling from high-volume medical device sterilization as gamma irradiation and electron beam alternatives achieve pharmacopeial equivalence at lower per-cycle cost. STERIS leverages its integrated ethylene oxide abatement infrastructure to sustain contracted relationships with legacy device portfolios. Sotera Health anchors North American gamma capacity through cobalt-60 sourcing agreements and multi-site redundancy. Getinge competes on steam sterilization scale for reusable surgical instrument sets across European hospital networks.
Terminal sterilization services encompass validated microbial elimination processes applied to finished pharmaceutical products, medical devices, and biologics after final packaging, typically achieving a sterility assurance level of 10^-6 through radiation, gas, or thermal modalities. Autoclaving dominates parenteral drug applications where steam penetration validates lethality against Geobacillus stearothermophilus spores. Ethylene oxide retains structural importance for heat-sensitive polymer devices, though gamma irradiation captures fastest growth in single-use bioprocessing assemblies where polymer compatibility has advanced. Outsourced services concentrate margin pools as Contract Manufacturing Organizations seek dedicated capacity without capital-intensive in-house electron beam installations.
FDA sterilization guidance, EMA Good Manufacturing Practice Annex 1 revisions, and ISO 11137 radiation standards collectively tighten validation documentation and environmental release thresholds for commercial sterilization operations. The EPA's ethylene oxide emissions oversight in the United States and REACH chemical restrictions in Europe are reshaping facility siting decisions and driving capital allocation toward lower-residue modalities. Stakeholders must monitor regulatory divergence between cobalt-60 supply constraints and accelerator-based electron beam scalability when committing to multi-year sterilization partnerships.
Market Dynamics
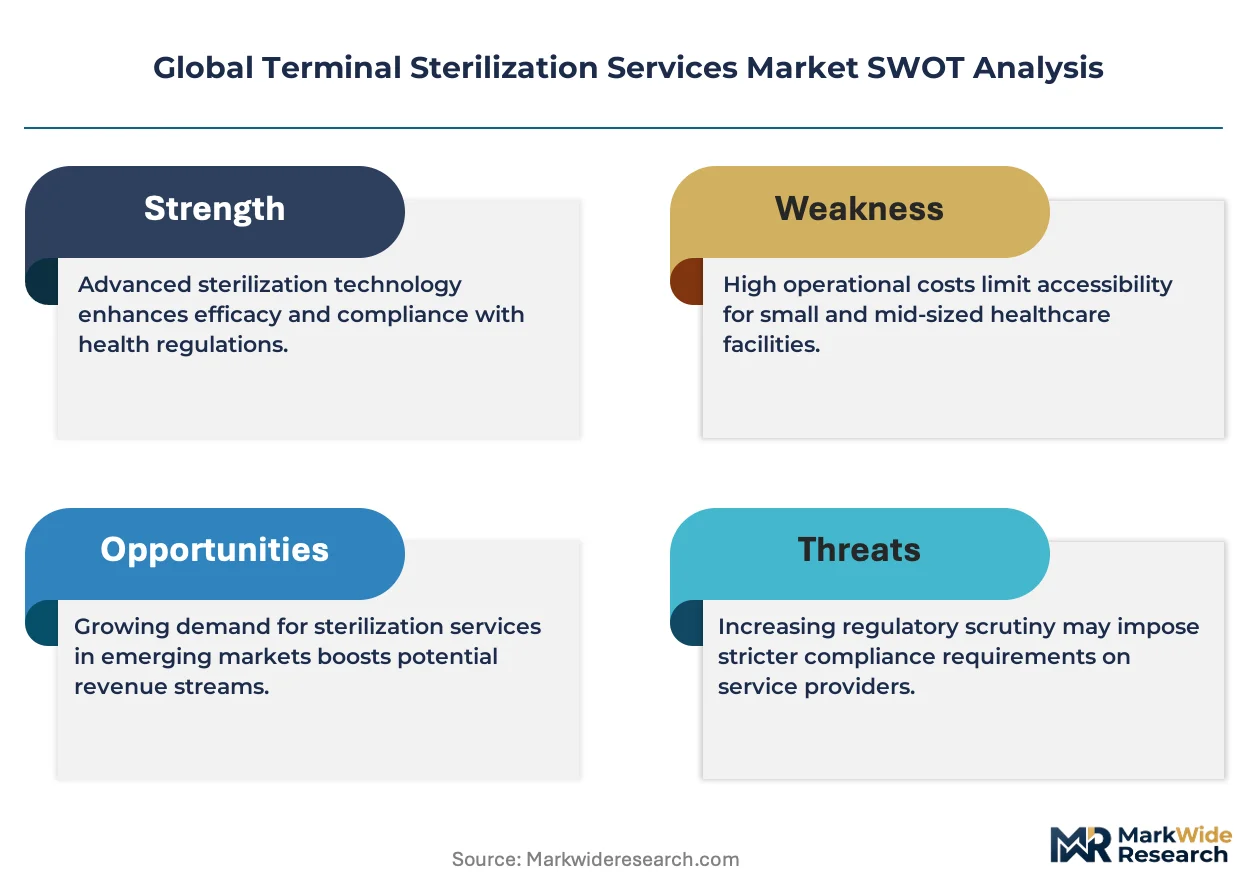
Ethylene oxide abatement costs and cobalt-60 supply constraints are compressing margin structures while forcing modality diversification across contract sterilization networks.
Growth Catalysts
- EMA Good Manufacturing Practice Annex 1:The revised sterile manufacturing requirements mandate terminal sterilization for an expanded range of parenteral formulations, pulling demand toward validated service providers.
- Cell and gene therapy biologics:Autologous and allogeneic cell therapy manufacturing requires specialized gamma and electron beam validation protocols that outsourced specialists alone can provision.
- Rhine corridor pharmaceutical clusters:Centralized sterilization hubs in Ludwigshafen, Basel, and Amsterdam capture economies of scale across contiguous biopharma manufacturing zones.
Market Restraints
- Cobalt-60 supply concentration:Canadian and Russian isotope production facilities control over 80% of global gamma irradiation source material, creating single-point vulnerability for radiation-dependent sterilizers.
- EPA ethylene oxide emissions thresholds:The agency's National Emission Standards for Hazardous Air Pollutants impose retrofit costs exceeding $15 million per legacy chamber facility in the United States.
- Electron beam polymer compatibility limits:Polypropylene and polycarbonate medical devices experience chain scission and yellowing at standard e-beam doses, restricting modality substitution.
Strategic Opportunities
- X-ray sterilization convergence:High-power linear accelerator technology paired with robotic handling systems enables pharmaceutical-grade throughput without radioactive source dependency.
- India pharmaceutical manufacturing:CDSCO's phased implementation of Schedule M(III) sterile facility requirements creates first-mover advantage for contract sterilizers establishing Mumbai-Pune corridor presence.
- Reusable surgical instrument circularity mandates:EU Green Deal packaging and waste directives accelerate hospital network demand for validated steam sterilization of metal instrument sets versus single-use polymer alternatives.
Industry Challenges
- Process validation specialist scarcity:Qualified personnel capable of executing ISO 11137 dose mapping and biological indicator studies command premium compensation across North American and European labor markets.
- Legacy ethylene oxide chamber integration:Retrofitting 1980s-era sterilization infrastructure with catalytic oxidation abatement requires extended facility shutdowns and parallel validation of temporary capacity arrangements.
- Multi-modal sterility assurance equivalence documentation:Demonstrating SAL 10^-6 parity across gamma, e-beam, and X-ray modalities demands redundant biological indicator testing protocols that extend commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Terminal Sterilization Services Market |
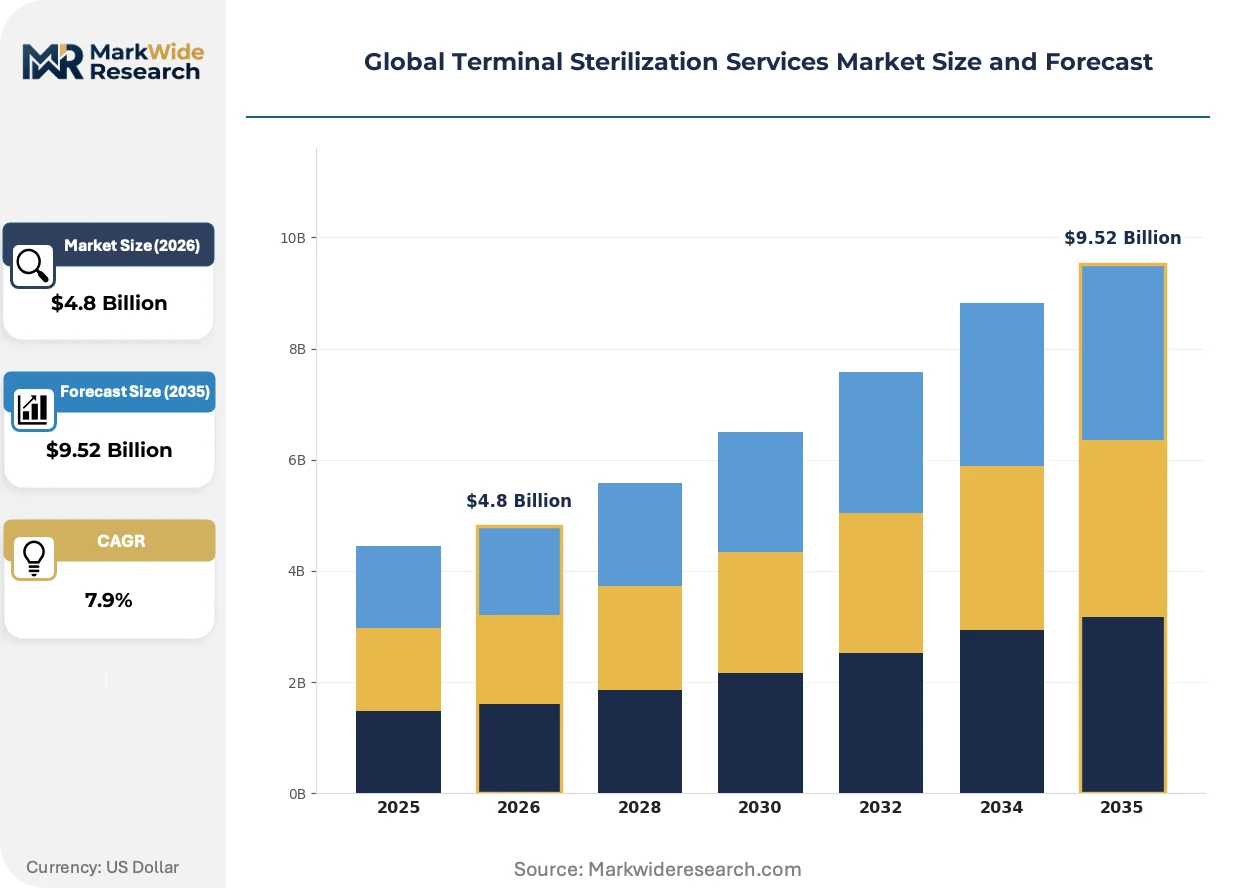
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Autoclaving, Gamma Irradiation, Electron Beam, Ethylene Oxide, Dry Heat Application: Pharmaceuticals, Medical Devices, Biologics, Surgical Instruments, Cosmetics End User: Contract Manufacturing Organizations, Biotechnology Firms, Medical Suppliers, Research Laboratories Delivery Model: On-Premise Services, Outsourced Services, Mobile Sterilization Units, Hybrid Models |
| Companies Covered | STERIS, Sotera Health, Getinge, Advanced Sterilization Products, 3M, Matachana, Belimed, Steelco, Tuttnauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Terminal Sterilization Services Market Shifts & Advancements
Validation automation and real-time release testing are compressing sterilization cycle documentation from weeks to days, reshaping competitive differentiation around speed-to-certificate rather than per-unit cost alone.
Electron beam sterilization is decentralizing pharmaceutical supply chains by enabling in-house accelerator installations at high-volume parenteral manufacturing sites. Pfizer, Novartis, and Roche have commissioned 10 MeV linear accelerators at fill-finish facilities in Ireland, Switzerland, and Singapore respectively. This modality shift reduces finished goods inventory holding periods and eliminates cold chain vulnerabilities associated with centralized gamma facility logistics.
REACH chemical restrictions on ethylene oxide residues are tightening maximum allowable limits for implantable cardiovascular devices and drug-device combination products. The European Chemicals Agency's 2023 update to Annex XVII imposes detection thresholds of 0.5 micrograms per device for permanent implants, forcing manufacturers toward alternative modalities or extended aeration protocols. German sterilization providers in the Baden-Württemberg medical technology cluster have invested in nitrogen-based aeration systems to achieve compliance without facility relocation.
Hospital procurement consortia are consolidating sterilization contracts across regional health system networks, displacing fragmented vendor relationships with single-source agreements spanning reusable instruments, implantable devices, and biologic tissue products. The NHS Supply Chain in England and the Vizient cooperative in the United States have both issued multi-year sterilization tenders covering 200-plus acute care facilities, concentrating volume with providers capable of modality flexibility and geographic redundancy.
Global Terminal Sterilization Services Market Segmentation
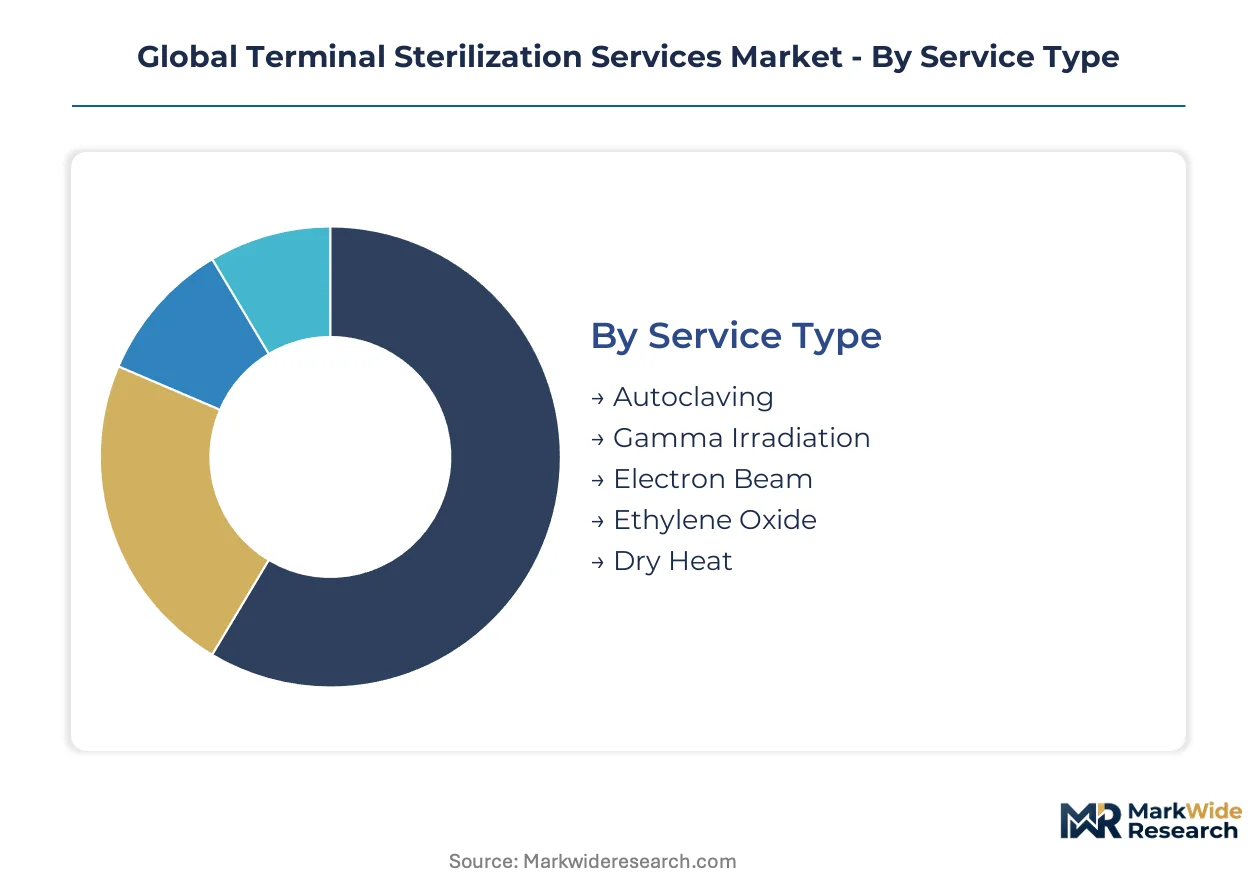
Terminal sterilization services fragment across four intersecting dimensions that determine capital intensity, regulatory burden, and customer lock-in. Service modality dictates facility infrastructure and source material dependency. Application verticals impose divergent sterility assurance level requirements. End-user procurement sophistication ranges from multinational CMO tender processes to single-site biotech validation protocols. Delivery model selection reflects inventory velocity constraints and geographic proximity to manufacturing clusters.
Service Type:
Customization intensity spans from standardized steam cycles to client-specific dose mapping protocols, with modality choice driven by product thermal tolerance and polymer compatibility requirements.
- Autoclaving:Saturated steam sterilization at 121°C achieves SAL 10^-6 lethality against Geobacillus stearothermophilus spores for parenteral drug containers and aqueous formulations. Demand concentrates at fill-finish facilities in Germany's Rhine corridor, where centralized steam capacity serves contiguous pharmaceutical clusters under EMA Annex 1 sterile manufacturing mandates.
- Gamma Irradiation:Cobalt-60 decay emission penetrates dense packaging and frozen biologics without thermal stress, enabling terminal sterilization of pre-filled syringes and cell therapy media. Canadian and Russian isotope production facilities control source material supply, creating single-point vulnerability for radiation-dependent sterilizers serving North American biologics manufacturers.
- Electron Beam:10 MeV linear accelerator technology enables in-house pharmaceutical installations with real-time release testing capability, reducing finished goods inventory holding periods at high-volume parenteral sites.
- Ethylene Oxide:Low-temperature gas diffusion retains polymer integrity for heat-sensitive cardiovascular devices and drug-eluting stents, though EPA NESHAP emissions thresholds impose $15 million retrofit costs per legacy US facility.
- Dry Heat:Depyrogenation at 160-170°C eliminates endotoxins from glass vials and metal surgical instruments, serving European hospital networks under EU Green Deal circularity mandates for reusable instrument sets.
Leading the category by volume: Autoclaving. Growing fastest: Electron Beam.
Application:
Regulatory stringency escalates from cosmetic topical formulations to implantable cardiovascular devices, with validation documentation requirements multiplying across the application hierarchy.
- Pharmaceuticals:Terminal sterilization of finished parenteral products demands ISO 11137 dose mapping and biological indicator studies with redundant SAL 10^-6 documentation. Demand clusters at fill-finish facilities in Ireland and Switzerland where Pfizer, Novartis, and Roche have commissioned electron beam accelerators.
- Medical Devices:Polymer compatibility constraints drive modality selection for single-use surgical instruments and implantable hardware, with REACH Annex XVII residue limits tightening to 0.5 micrograms per device for permanent implants.
- Biologics:Autologous and allogeneic cell therapies require specialized gamma and electron beam validation protocols that outsourced specialists alone can provision.
- Surgical Instruments:Reusable metal instrument sets dominate European hospital procurement under circular economy directives, displacing single-use polymer alternatives.
- Cosmetics:Non-sterile topical formulations occupy lower validation tiers, though preservative-free ampoules increasingly require terminal sterilization for premium positioning.
Dominant by revenue: Pharmaceuticals. Expanding most quickly: Biologics.
End User:
Procurement scale ranges from enterprise CMO multi-year tenders to biotech milestone-dependent validation engagements, with contract duration and modality flexibility as primary selection criteria.
- Contract Manufacturing Organizations:Multi-site pharmaceutical service providers seek dedicated sterilization capacity without capital-intensive in-house electron beam installations, consolidating volume with modality-flexible partners.
- Biotechnology Firms:Cell and gene therapy developers require specialized validation protocols for autologous products, creating premium pricing power for sterilizers with biological indicator study expertise.
- Medical Suppliers:Hospital procurement consortia issue multi-year tenders spanning reusable instruments, implantable devices, and biologic tissue products, concentrating volume with geographically redundant providers.
- Research Laboratories:Small-batch sterilization for clinical trial materials and investigational products demands rapid turnaround and flexible scheduling at lower throughput scale.
Highest volume concentration: Contract Manufacturing Organizations. Fastest procurement expansion: Biotechnology Firms.
Delivery Model:
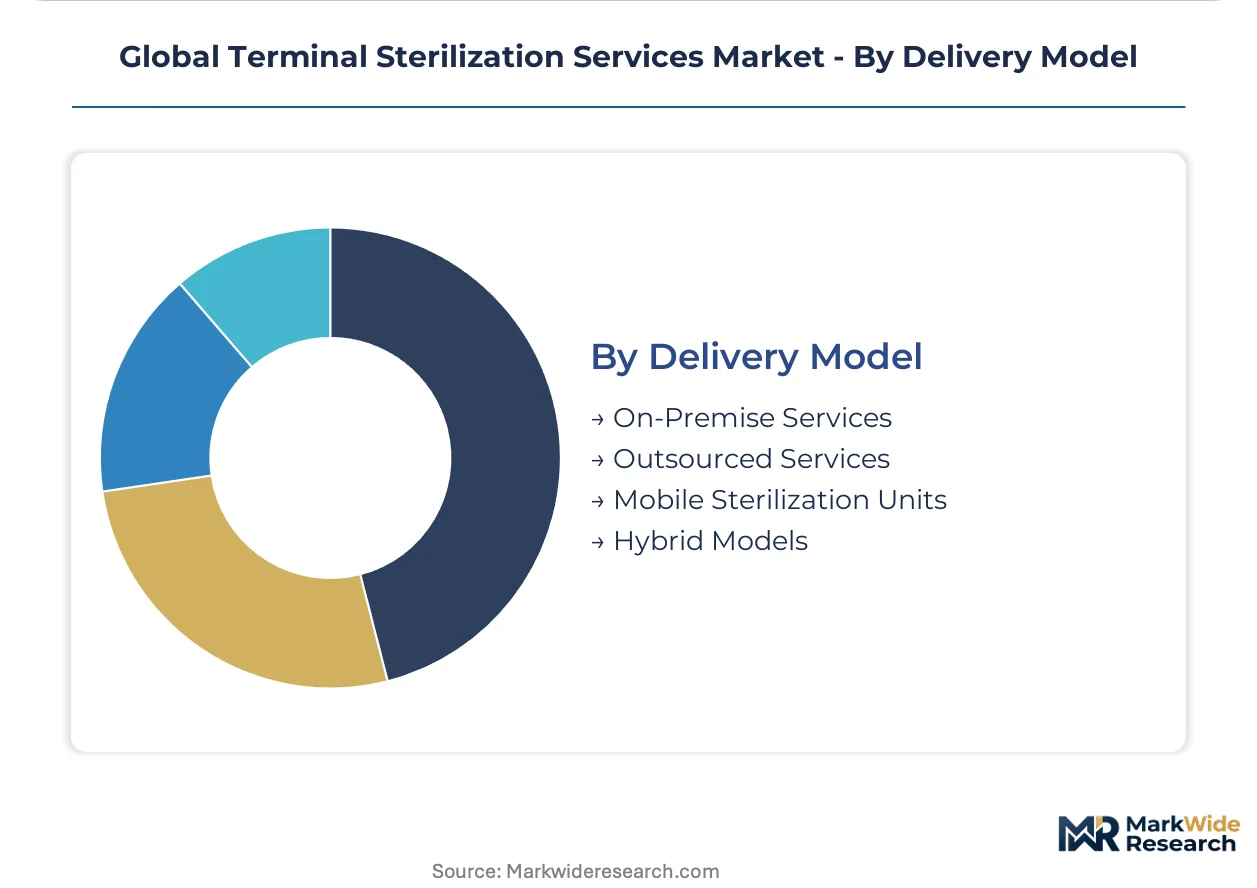
Asset deployment intensity varies from captive on-premise installations to third-party network access, with hybrid arrangements emerging to balance validation control against capital efficiency.
- On-Premise Services:Captive sterilization infrastructure at pharmaceutical manufacturing sites enables real-time release testing and eliminates cold chain logistics vulnerabilities, though requires dedicated validation personnel and maintenance overhead.
- Outsourced Services:Third-party contract sterilizers concentrate margin pools through multi-modal capacity and geographic redundancy, serving CMOs seeking dedicated throughput without capital commitment.
- Mobile Sterilization Units:Containerized electron beam and ethylene oxide systems deploy to remote manufacturing sites or disaster response zones, addressing temporary capacity constraints without permanent facility investment.
- Hybrid Models:Combination arrangements pair on-premise steam sterilization for routine production with outsourced gamma capacity for specialized biologics, optimizing capital allocation across product portfolios.
Prevailing by throughput: Outsourced Services. Gaining share fastest: Hybrid Models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for terminal sterilization services concentrates in pharmaceutical manufacturing corridors where fill-finish capacity and regulatory stringency intersect. Germany, the United States, Switzerland, India, and Singapore collectively anchor validated sterilization infrastructure across three continents.
United States
FDA enforcement of ethylene oxide residue limits and EPA NESHAP emissions thresholds drives facility retrofit investments exceeding $15 million per legacy chamber site. The agency's updated guidance on medical device sterilization accelerates modality diversification toward gamma and electron beam alternatives. Sterilization hubs in Minnesota and Ohio serve concentrated medical device manufacturing clusters.
Germany
EMA Annex 1 sterile manufacturing mandates pull demand toward centralized steam and gamma capacity serving Rhine corridor pharmaceutical clusters. The EU Green Deal circularity directives accelerate hospital network procurement of validated reusable surgical instrument sterilization. Ludwigshafen, Basel, and Amsterdam form a contiguous sterilization service zone.
Switzerland
Novartis and Roche commissioning of in-house electron beam accelerators at Swiss fill-finish sites demonstrates pharmaceutical vertical integration into terminal sterilization. Swissmedic oversight of biologics manufacturing maintains stringent validation documentation requirements. The Basel pharmaceutical cluster sustains demand for specialized gamma protocols.
India
CDSCO phased implementation of Schedule M(III) sterile facility requirements creates contract sterilization opportunity in the Mumbai-Pune corridor. Domestic pharmaceutical manufacturing expansion drives demand for outsourced gamma and ethylene oxide capacity. Regulatory convergence toward international GMP standards attracts multi-modal service providers.
Singapore
Roche's 10 MeV linear accelerator commissioning at Singapore fill-finish facilities exemplifies pharmaceutical electron beam adoption in Asia-Pacific manufacturing nodes. The city-state's biologics manufacturing incentives concentrate cell and gene therapy production requiring specialized sterilization validation. Regional hub status attracts modality-flexible contract sterilizers.
Global Terminal Sterilization Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers commanding premium positioning in biologics validation while regional steam operators compete on hospital instrument throughput. The vendor base organizes around three archetypes: multi-modal global networks with cobalt-60 sourcing advantages, European hospital-centric steam sterilizers, and pharmaceutical-integrated electron beam specialists. Consolidation pressure intensifies as EPA compliance costs and isotope supply constraints force smaller ethylene oxide operators toward acquisition or exit. Capacity expansion and modality diversification represent the dominant competitive vectors.
Among North American radiation-dependent networks, STERIS and Sotera Health exemplify multi-modal scale archetypes with integrated abatement infrastructure and cobalt-60 redundancy arrangements. Getinge occupies a position within the European hospital-centric tier, anchoring reusable surgical instrument sterilization contracts across health system networks. These three entities collectively represent the structural segmentation between global radiation networks and regional steam operators.
| Leading Market Players |
|---|
| STERIS |
| Sotera Health |
| Getinge |
| Advanced Sterilization Products |
| 3M |
| Matachana |
| Belimed |
| Steelco |
| Tuttnauer |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up contract sterilization networks anchor supply-side discipline through leveraged buyout structures that demand rapid EBITDA expansion, compressing procurement timelines and enforcing strict per-cycle pricing floors across gamma and ethylene oxide modalities. This ownership pattern concentrates pricing power with multi-modal operators capable of cobalt-60 sourcing redundancy while forcing smaller steam-only competitors into margin-eroding spot-market competition for hospital instrument contracts.
Pricing Analysis
High-volume medical device sterilization runs on thin per-unit margins while specialized biologics validation commands premium pricing tiers. Three-tier pricing structure across premium, standard, and economy levels separates cell therapy dose-mapping protocols from commodity steam cycles and emergency expedited turnaround services. Cost compression in standard gamma capacity is intensifying because Canadian and Russian isotope supply constraints limit source material availability. Contract Manufacturing Organizations exhibit highest price sensitivity due to tender-driven procurement, while cell and gene therapy developers accept premium rates for biological indicator study expertise.
Supply Chain Analysis
ISO 11137 certification and FDA validation protocol compliance gate entry for cobalt-60 source material suppliers and accelerator component manufacturers. Canada, Russia, and Belgium concentrate isotope production for gamma irradiation, while Germany, Switzerland, and the United States anchor electron beam accelerator assembly. The supply chain draws from specialized radiation source mining, precision accelerator engineering, and biological indicator manufacturing. Single-source vulnerability in cobalt-60 supply creates structural risk for radiation-dependent sterilizers. Distribution runs through validated cold-chain logistics networks serving pharmaceutical fill-finish clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal sterilization capacity operates under cobalt-60 supply constraints and EPA emissions compliance bottlenecks that prop pricing power for validated multi-modal operators across the analysis window.
For Market Incumbents: Lock in long-term cobalt-60 sourcing agreements with Canadian and Russian isotope producers before contract renewal cycles intensify competition. Secure EMA Annex 1 validation documentation superiority to defend against emerging electron beam specialists threatening gamma-dependent biologics contracts. Add redundant capacity in the Mumbai-Pune corridor to capture CDSCO Schedule M(III) implementation demand. For New Entrants and Emerging Players: Digital validation automation platforms offer lower-friction entry into small-batch biotech sterilization contracts currently underserved by legacy operators. Target India pharmaceutical manufacturing expansion as the most penetrable geography given regulatory convergence toward international GMP standards. Deploy mobile electron beam units for temporary capacity arrangements during competitor facility retrofits. For Investors and Strategic Acquirers: Distressed-cycle entries favor ethylene oxide abatement-compliant mid-cap specialists in the United States facing EPA NESHAP retrofit cost burdens. Five-to-ten year viability hinges on modality diversification beyond gamma-dependent revenue streams. Watch cobalt-60 spot pricing as the inflection signal for radiation sterilization margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modal Capacity Expansion | STERIS and Sotera Health investments in X-ray sterilization reduce cobalt-60 dependency for biologics manufacturers. |
| EMA Annex 1 Validation Investment | German sterilization hubs capture Rhine corridor pharmaceutical demand through compliant steam and gamma documentation. |
| Electron Beam In-House Installation | Pfizer and Novartis commissioning of 10 MeV accelerators eliminates cold chain logistics vulnerabilities at fill-finish sites. |
| Ethylene Oxide Abatement Retrofit | EPA NESHAP compliance investments exceed $15 million per legacy US facility, forcing smaller operator consolidation. |
| India Corridor Presence Establishment | CDSCO Schedule M(III) phased implementation creates first-mover advantage for contract sterilizers in Mumbai-Pune. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with sterilization operations directors, pharmaceutical quality assurance leads, hospital procurement managers, and biological indicator study specialists provided operational validation. FDA 483 inspection records, EMA GMP inspection databases, and ISO certification registries supplied compliance benchmarking. Bottom-up facility capacity modeling triangulated against top-down pharmaceutical manufacturing output estimates.
Data-stream reconciliation across cobalt-60 source material supply tracking, accelerator installation permits, and sterilization service contract announcements informed the analytical framework over the projection horizon. Segmentation dimensions modeled include service modality, application vertical, end-user procurement scale, and delivery model configuration alongside regional regulatory cluster differentiation. CAGRs derived from sterilization cycle volume trajectories and per-unit pricing trends across gamma, electron beam, and ethylene oxide modalities.
The model holds under stable cobalt-60 supply and EPA enforcement continuity; deviation in isotope production disruptions or REACH residue limit tightening would shift capacity allocation forecasts. A model refresh is warranted upon material change in FDA sterilization guidance or CDSCO regulatory implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Addison Disease Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Allergy Tester Market
Testing Services
Nipah Virus Testing Market
Testing Services
West Nile Virus Testing Market
Testing Services
Home Menopause Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Arbovirus Testing Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
Prothrombin Time Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Bioprocess Integrity Testing Systems Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Drug Testing Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Faecal Calprotectin Testing Market