
 Tablet Hardness Testers Market | 2026-2036
Tablet Hardness Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet Hardness Testers Market Analytics
US FDA's updated Process Analytical Technology guidelines is decoupling instrument validation from legacy batch-testing protocols. ERWEKA GmbH leverages its German engineering heritage to sustain premium positioning in high-throughput automatic tester lines. SOTAX AG anchors European demand through integrated tablet testing workstations that combine hardness with thickness and weight modules. Copley Scientific Limited competes on service density across British and Irish pharmaceutical contract manufacturers.
Tablet hardness testers measure the breaking force of compressed tablets using load cell or mechanical strain gauge mechanisms, typically reporting values in kiloponds or newtons to predict coating durability and shipping survivability. Automatic testers now dominate new capital expenditure as pharmaceutical companies replace manual bench units to meet data integrity requirements under 21 CFR Part 11. Quality Assurance applications absorb the largest share of installed base, though Production Monitoring represents the fastest-growing segment as continuous manufacturing lines demand real-time hardness feedback loops rather than offline sampling.
EMA's Annex 15 qualification standards and US FDA's Current Good Manufacturing Practice enforcement both elevate calibration traceability requirements for hardness instrumentation sold into regulated markets. India's CDSCO Schedule M revisions and China's NMPA pharmaceutical equipment registration rules create parallel compliance pathways that shape regional product specifications. Stakeholders must monitor divergence between FDA's PAT initiative and EMA's GMP Annex updates when configuring instrument software for multi-jurisdictional deployments.
Market Dynamics
Pharmaceutical manufacturers are retiring manual bench-top hardness testers in favor of automated systems that embed directly into continuous manufacturing lines, a shift driven by FDA's Process Analytical Technology initiative and the collapse of batch-based quality control economics.
Growth Catalysts
- Schedule M Compliance Mandates:India's CDSCO now requires documented hardness testing for all commercial tablet batches, forcing domestic generic manufacturers to upgrade from visual inspection to calibrated instrumentation.
- Continuous Manufacturing Integration:Real-time release testing architectures demand inline hardness sensors that feed data directly into process control loops, eliminating offline sampling delays.
- Load Cell Precision Advances:Strain gauge mechanisms now achieve sub-newton resolution at production speeds, enabling accurate measurement of fragile orally disintegrating tablets previously deemed untestable at line rates.
Market Restraints
- Calibration Traceability Costs:EMA's Annex 15 qualification standards and FDA's 21 CFR Part 11 enforcement require annual third-party calibration with documented uncertainty budgets, adding recurring operational overhead.
- Stainless Steel Supply Concentration:Pharmaceutical-grade 316L stainless steel for instrument chassis concentrates among German and Swiss specialty metal suppliers, exposing lead times to European energy cost volatility.
- Mechanical Tester Obsolescence:Spring-based manual testers face substitution pressure from electromechanical systems, stranding existing installed bases and compressing resale values for legacy equipment.
Strategic Opportunities
- Brazilian ANVISA Pre-Qualification Pathway:The regulator's accelerated pharmaceutical equipment registration program creates first-mover advantage for automated testers that demonstrate compliance with both USP <1217> and local dissolution correlation protocols.
- Bi-layer Tablet Testing Workstations:Converging hardness and friability modules into single-platform architectures addresses the complexity of combination products where each layer requires distinct breaking force characterization.
- Contract Research Organization Channel Expansion:Indian CROs in Hyderabad and Bengaluru are building dedicated solid-dose testing facilities, creating demand for high-throughput systems with multi-user data access controls.
Industry Challenges
- Metrology Technician Scarcity:Pharmaceutical manufacturers report difficulty recruiting personnel capable of executing IQ/OQ/PQ protocols for automated hardness systems, particularly in emerging manufacturing clusters.
- Legacy LIMS Integration Complexity:Older laboratory information management systems lack native APIs for real-time hardness data ingestion, forcing middleware development or costly platform upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet Hardness Testers Market |
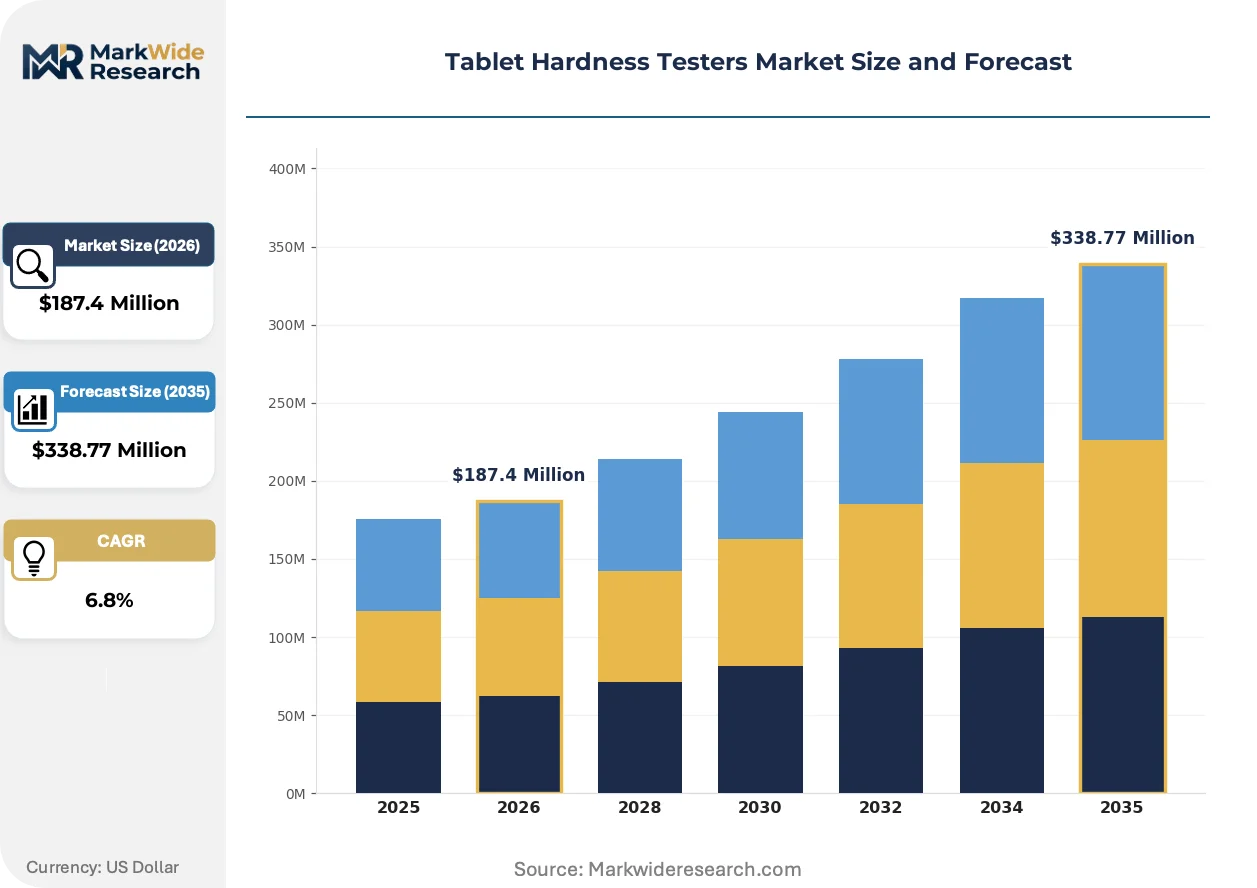
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Testers, Automatic Testers, Digital Testers, Analog Testers End User: Pharmaceutical Companies, Laboratories, Educational Institutions, Quality Control Units Technology: Load Cell, Ultrasonic, Optical, Mechanical Application: Quality Assurance, Research & Development, Production Monitoring, Compliance Testing |
| Companies Covered | Charles Ischi AG, SaintyCo., Natoli Engineering Company, Labtron Equipment Ltd., Copley Scientific Limited, ERWEKA GmbH, Teledyne LABS, CCS GROUP, SOTAX AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet Hardness Testers Market Evolving Landscape
Instrument architectures are pivoting from standalone measurement devices to networked nodes within pharmaceutical manufacturing execution systems, with software capabilities now determining competitive differentiation more than mechanical precision.
Electromechanical load cell systems are absorbing the functionality previously distributed across separate hardness, thickness, and diameter instruments. Generic manufacturers in India and Southeast Asia are adopting these consolidated workstations fastest, compressing capital expenditure timelines from three discrete purchases to single-platform deployment. This convergence is absorbing mid-tier mechanical gauge suppliers into the service ecosystems of integrated platform vendors.
REACH restrictions on hexavalent chromium plating are forcing redesigns of tablet compression contact surfaces, with instrument manufacturers migrating to ceramic-coated or PVD-treated alloys. European pharmaceutical equipment vendors face the tightest compliance timelines, driving accelerated qualification of alternative surface treatments. German and Swiss suppliers are responding with modular contact-point designs that simplify material certification for multi-jurisdictional sales.
After-sales service contracts are unbundling from hardware sales as buyers seek flexible calibration and qualification support. Indian generic manufacturers now procure instruments and service separately, often selecting local metrology providers for annual calibration rather than OEM service networks. This fragmentation is most visible in Maharashtra's Pune-Ahmednagar cluster, where CROs and contract manufacturers negotiate service autonomy as a procurement condition.
Tablet Hardness Testers Market Segmentation
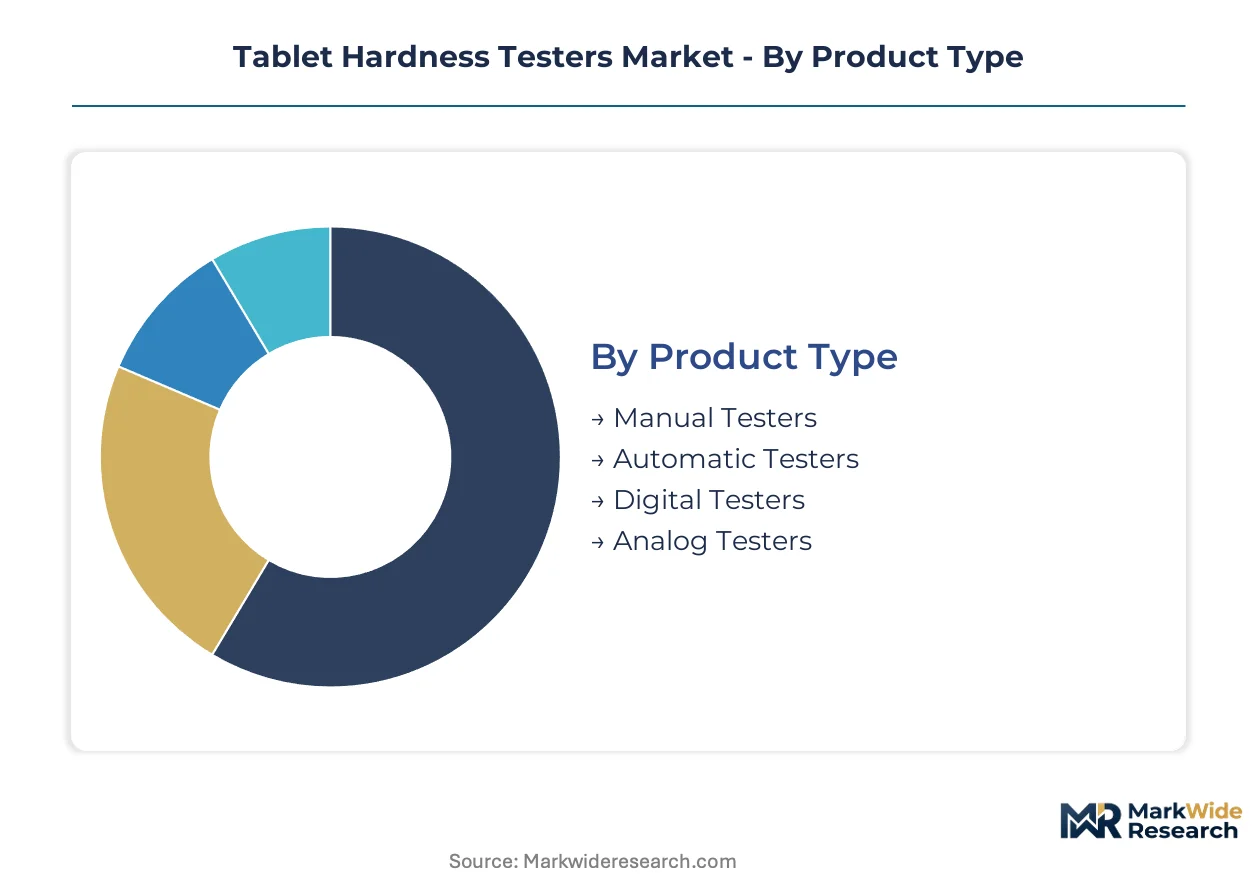
Tablet hardness testers segment across four distinct dimensions that shape procurement patterns and vendor positioning. Product type determines capital expenditure tiers, while end-user concentration in India's generic pharmaceutical clusters drives regional demand patterns. Technology selection hinges on calibration traceability requirements under FDA and EMA enforcement.
Product Type:
Capital expenditure thresholds and data integrity requirements drive buyer selection across instrument categories.
- Automatic Testers:Electromechanical systems with integrated load cells feed real-time data into manufacturing execution systems for continuous production lines. Indian generic manufacturers in Maharashtra's Pune-Ahmednagar cluster prioritize these systems to satisfy CDSCO Schedule M documentation mandates.
- Manual Testers:Spring-based or mechanical strain gauge units require operator intervention for each measurement, limiting throughput to batch sampling protocols. Legacy installed bases in European contract manufacturing organizations face replacement pressure as EMA Annex 15 qualification standards tighten calibration audit trails.
- Digital Testers:Standalone electronic units with local data storage bridge the gap between manual operation and full automation. Small-scale laboratories in Hyderabad and Bengaluru deploy these for intermediate throughput without enterprise system integration costs.
- Analog Testers:Dial-gauge mechanical instruments with minimal electronic components serve educational and basic research applications where 21 CFR Part 11 compliance is not required.
Automatic testers lead on scale; digital testers lead on momentum.
End User:
Regulatory exposure and batch volume determine instrumentation sophistication across buyer categories.
- Pharmaceutical Companies:Integrated tablet testing workstations combining hardness, thickness, and diameter modules dominate capital budgets. German and Swiss engineering heritage carries premium positioning for high-throughput lines serving US and European export markets.
- Quality Control Units:Standalone automatic testers with multi-user access controls support shift-based operations in contract research organizations. Indian CROs in Hyderabad and Bengaluru specify separate procurement of hardware and local calibration services to reduce total cost of ownership.
- Laboratories:Consolidated electromechanical platforms absorb functionality previously distributed across discrete instruments, compressing procurement timelines from three purchases to single-platform deployment.
- Educational Institutions:Basic mechanical or analog testers suffice for training purposes where regulatory submission requirements do not apply.
Pharmaceutical companies anchor procurement volume; quality control units are climbing the fastest.
Technology:
Measurement precision and production speed requirements determine mechanism selection.
- Load Cell:Strain gauge mechanisms achieve sub-newton resolution at line speeds, enabling accurate measurement of fragile orally disintegrating tablets previously deemed untestable during production. REACH restrictions on hexavalent chromium plating force redesigns of compression contact surfaces toward ceramic-coated or PVD-treated alloys.
- Mechanical:Spring-based systems face obsolescence pressure from electromechanical alternatives, stranding existing installed bases and compressing resale values for legacy equipment in secondary markets.
- Ultrasonic:Non-contact measurement approaches under development for bi-layer tablet applications where each layer requires distinct breaking force characterization.
- Optical:Vision-based systems supplement mechanical testing with dimensional verification in integrated workstation architectures.
Load cell technology commands the installed base; ultrasonic methods show steepest expansion trajectory.
Application:
Integration depth with manufacturing execution systems separates quality assurance from production monitoring deployments.
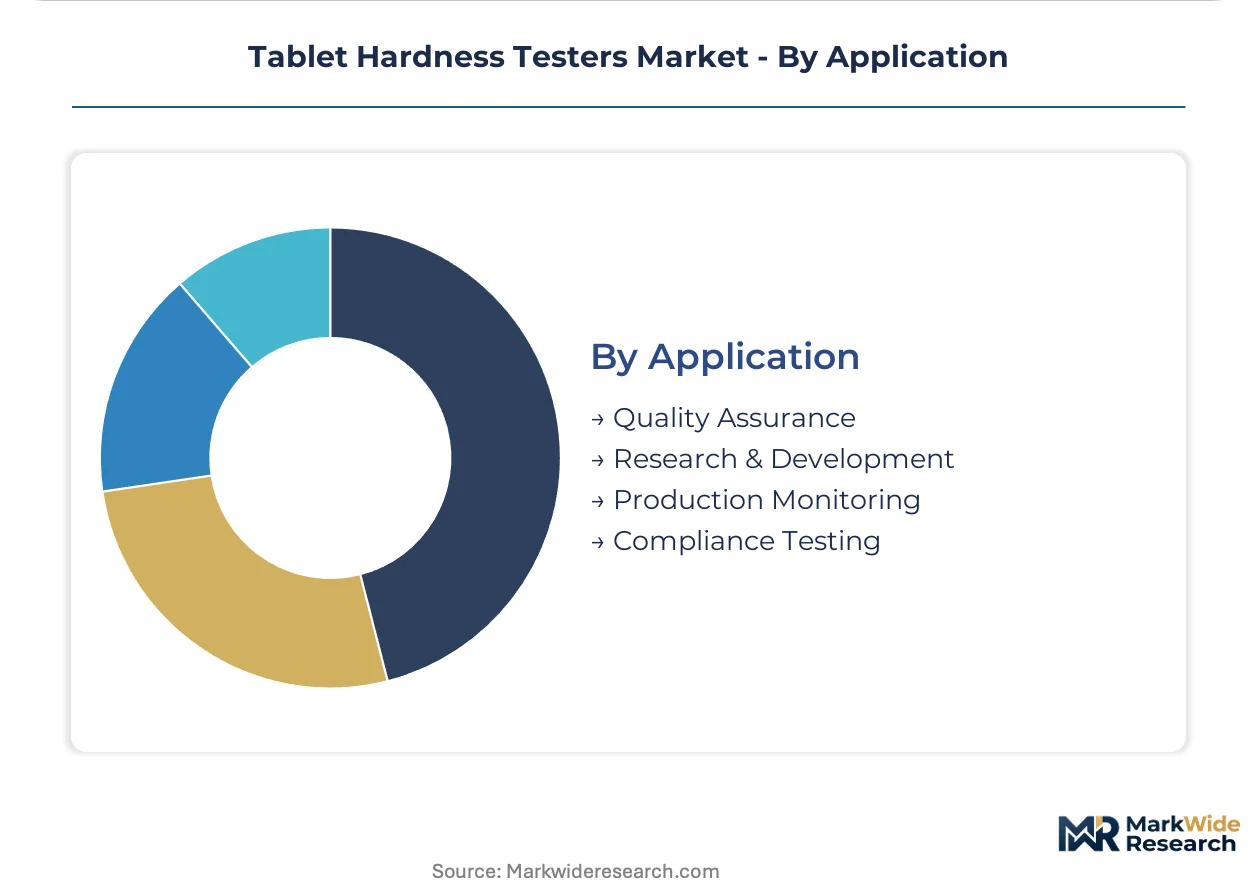
- Quality Assurance:Offline sampling protocols with documented uncertainty budgets support regulatory submission packages. EMA Annex 15 and FDA 21 CFR Part 11 enforcement elevate calibration traceability requirements for instruments deployed in this function.
- Production Monitoring:Inline hardness sensors feed data directly into process control loops, eliminating sampling delays for continuous manufacturing architectures. FDA's Process Analytical Technology initiative accelerates adoption of real-time release testing configurations.
- Research & Development:Flexible instrument configurations support formulation development where tablet geometry and compression parameters vary across experimental batches.
- Compliance Testing:Dedicated systems with locked method parameters ensure USP <1217> adherence for regulatory audit purposes.
Quality assurance holds the largest installed base; production monitoring gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulation scientists and metrology technicians concentrate in manufacturing clusters where regulatory enforcement is tightest. Their expertise anchors regional demand for calibrated hardness instrumentation.
United States
FDA's Process Analytical Technology initiative drives pharmaceutical manufacturers toward inline hardness sensors for continuous manufacturing lines. 21 CFR Part 11 enforcement elevates data integrity requirements, forcing upgrades from manual bench units. The New Jersey-Pennsylvania pharmaceutical corridor hosts the densest concentration of automated tester deployments.
Germany
Precision engineering heritage sustains premium positioning for high-throughput automatic tester lines serving export markets. REACH restrictions on hexavalent chromium plating accelerate redesigns of tablet compression contact surfaces. The Baden-Württemberg and Bavaria industrial regions concentrate instrument manufacturing and pharmaceutical R&D facilities.
India
Generic pharmaceutical manufacturers in Maharashtra's Pune-Ahmednagar cluster upgrade QC capacity to meet CDSCO Schedule M documentation mandates. Contract research organizations in Hyderabad and Bengaluru build dedicated solid-dose testing facilities with multi-user access controls. Domestic generic producers now separate hardware procurement from local calibration services.
Switzerland
Specialty metal suppliers for pharmaceutical-grade 316L stainless steel instrument chassis face tightening energy cost pressures. Swissmedic enforcement of calibration traceability aligns with EMA Annex 15 qualification standards. The Basel-Zurich corridor anchors integrated tablet testing workstation development.
China
NMPA pharmaceutical equipment registration rules create parallel compliance pathways shaping regional product specifications. Domestic tablet press manufacturers expand downstream into hardness testing instrumentation. The Yangtze River Delta pharmaceutical manufacturing belt concentrates demand for electromechanical load cell systems.
Tablet Hardness Testers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument tiers. The vendor base organizes around three strategic archetypes: German-Swiss precision engineering houses, British service-intensive distributors, and Asian scale fabricators. Consolidation pressure favors integrated platform vendors absorbing mid-tier mechanical gauge suppliers. Dominant competitive moves include geographic expansion into Indian CRO channels and portfolio diversification toward bi-layer tablet testing workstations.
Among German precision engineering specialists, ERWEKA GmbH and SOTAX AG exemplify the heritage-driven premium tier. Copley Scientific Limited represents the British service-density model competing across contract manufacturing networks. These three anchors illustrate how competitive positioning splits between mechanical engineering credibility and calibration service reach.
| Leading Market Players |
|---|
| Charles Ischi AG |
| SaintyCo. |
| Natoli Engineering Company |
| Labtron Equipment Ltd. |
| Copley Scientific Limited |
| ERWEKA GmbH |
| Teledyne LABS |
| CCS GROUP |
| SOTAX AG |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between 21 CFR Part 11-compliant electromechanical systems and basic mechanical units manifests in both pricing power and sourcing complexity. Premium automatic testers command service-bundled premiums while commodity manual instruments face cost compression from Indian generic manufacturers separating hardware procurement from local calibration contracts.
Pricing Analysis
Service unbundling now dominates procurement negotiations as Indian CROs in Hyderabad and Bengaluru separate instrument purchases from annual calibration contracts. Three-tier pricing structure across premium German-Swiss engineering, mid-tier British service-integrated platforms, and economy Asian fabricators reflects certification depth and traceability documentation. Pricing pressure stems from CDSCO Schedule M compliance mandates forcing domestic manufacturers toward calibrated instrumentation without corresponding budget expansion. Quality control units in contract research organizations exhibit highest price sensitivity, while pharmaceutical companies serving US export markets absorb premium positioning for integrated workstation architectures.
Supply Chain Analysis
Domestic-content requirements in India's pharmaceutical equipment sector reshape sourcing patterns toward local assembly partnerships. Pharmaceutical-grade 316L stainless steel concentrates among German and Swiss specialty metal suppliers, with electromechanical load cells and strain gauge mechanisms drawing from precision engineering clusters in Baden-Württemberg and Bavaria. REACH restrictions on hexavalent chromium plating expose lead times to European regulatory compliance timelines. Single-source vulnerability concentrates in ceramic-coated contact surface treatments still qualifying under EMA Annex 15 standards. Distribution runs through OEM direct sales for premium tiers and regional distributor networks for standard-economy segments across Maharashtra's Pune-Ahmednagar cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tablet hardness testers function as a stable compounder anchored by irreversible regulatory documentation mandates across FDA, EMA, and CDSCO jurisdictions. Compliance enforcement creates replacement demand cycles resistant to pharmaceutical capital expenditure volatility.
For Market Incumbents: Deepen backward integration into pharmaceutical-grade 316L stainless steel supply through captive partnerships with German-Swiss specialty metal suppliers. Anchor service contract density in Indian CRO channels before local metrology providers consolidate calibration autonomy. Defend against mid-tier mechanical gauge supplier absorption by accelerating integrated workstation development for bi-layer tablet applications.
For New Entrants and Emerging Players: Ultrasonic non-contact measurement technology offers entry into bi-layer tablet characterization where incumbent electromechanical platforms lack layer-specific resolution. Target Brazilian ANVISA pre-qualification pathway for automated testers demonstrating USP <1217> correlation before established vendors localize documentation. Pursue CRO channel partnerships in Hyderabad and Bengaluru with hardware-only positioning that undercuts bundled service premiums.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier mechanical gauge suppliers face stranded installed bases from electromechanical substitution. The 5-10 year viability window favors integrated platform vendors with multi-jurisdictional software certification capabilities. Monitor CDSCO Schedule M enforcement intensity across Maharashtra's generic manufacturing clusters as demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Bi-layer Tablet Testing Workstation Development | Addresses combination product complexity where each layer requires distinct breaking force characterization under USP <1217>. |
| Local Calibration Service Unbundling | Captures procurement autonomy demands from Indian CROs in Hyderabad and Bengaluru reducing total cost of ownership. |
| Ceramic-Coated Contact Surface Qualification | Responds to REACH hexavalent chromium restrictions with EMA Annex 15-compliant alternative treatments. |
| ANVISA Pre-Qualification Pathway Investment | Secures first-mover advantage in Brazilian pharmaceutical equipment registration with USP dissolution correlation. |
| Inline Hardness Sensor Integration | Aligns with FDA Process Analytical Technology initiative for continuous manufacturing real-time release testing. |
Research Methodology
Bottom-up pharmaceutical manufacturer modeling reconciled against top-down instrument shipment tracking forms the analytical core of this study. Primary interviews with quality assurance directors, metrology technicians, regulatory affairs leads at CDSCO, and CRO procurement managers combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA Annex 15 qualification standards, USP <1217> monographs, and CDSCO Schedule M revisions. Trade data from pharmaceutical equipment customs classifications and SEC filings from diversified instrumentation conglomerates enabled cross-referencing of regional demand patterns against vendor revenue disclosures.
Historical trendline analysis of electromechanical load cell adoption rates informed projection modeling across the analysis window. Segmentation dimensions include product type, end-user category, technology mechanism, and application depth with manufacturing execution systems. CAGRs were derived from instrument replacement cycle analysis, regulatory compliance deadline clustering, and continuous manufacturing line deployment trajectories. Forecast inputs incorporated CDSCO enforcement intensity assumptions and REACH alternative surface treatment qualification timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA PAT initiative adoption pace and EMA GMP Annex divergence from US protocols. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and stainless steel supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Fungal Testing Kits Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Pharmaceutical Quality Control Market
Testing Services
Global Urinalysis Test Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Test Strips Market
Testing Services
Friability Tester Market
Testing Services
Global Lipid Panel Testing Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Cannabis Testing Services Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Active B12 Test Market
Testing Services
Bimetallic Thermometer Market