
 Malaria Ag Rapid Testing Market | 2026-2036
Malaria Ag Rapid Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Malaria Ag Rapid Testing Market Foresight
Immunochromatographic assay miniaturization is tilting manufacturing toward cartridge-based and microfluidic platforms that reduce sample volume and reader dependence. Abbott Laboratories leverages its established diagnostic distribution networks across endemic regions to sustain volume leadership. Access Bio, Inc. anchors its competitive stance through vertically controlled membrane sourcing and strip assembly operations in Asia.
Malaria antigen rapid testing employs lateral-flow immunochromatographic strips or cartridges coated with monoclonal antibodies that detect Plasmodium falciparum histidine-rich protein II or Plasmodium lactate dehydrogenase in whole blood, delivering qualitative results within 15–20 minutes without laboratory infrastructure. The technology serves endemic-country health systems, NGOs, and private clinicians requiring immediate parasitological confirmation before treatment. Cassette formats command the dominant share among product types due to superior stability in tropical climates and ease of use by low-literacy health workers. Hospitals and diagnostic laboratories represent the largest end-user pool, though home-care channels are expanding fastest as self-test kits gain regulatory clearance in select markets.
WHO prequalification and the EU In Vitro Diagnostic Regulation shape market access, with prequalified products securing bulk procurement through Global Fund and PMI supply chains while non-compliant manufacturers face exclusion from tender programs. FDA enforcement of design-control requirements under 21 CFR Part 820 raises barriers for new entrants seeking US market entry. Stakeholders must monitor evolving WHO target product profiles for next-generation ultra-sensitive detection thresholds and multiplex malaria-dengue formats.
Market Dynamics
Immunochromatographic miniaturization is compressing manufacturing economics while WHO prequalification requirements are hardening procurement barriers, forcing manufacturers to choose between volume scale and regulatory compliance investment.
Growth Catalysts
- Point-of-care expansion in sub-Saharan Africa:Rural clinics in Nigeria, Kenya, and the Democratic Republic of Congo are replacing microscopy with rapid diagnostic tests, driven by Plasmodium falciparum prevalence and healthcare worker shortages.
- WHO prequalification pathways:Bulk procurement through Global Fund and PMI supply chains now mandates prequalified status, creating guaranteed demand pools for compliant manufacturers.
- Microfluidic cartridge platforms:Reduced sample volume requirements and reader-independent operation are extending testing access to community health worker programs in low-literacy settings.
Market Restraints
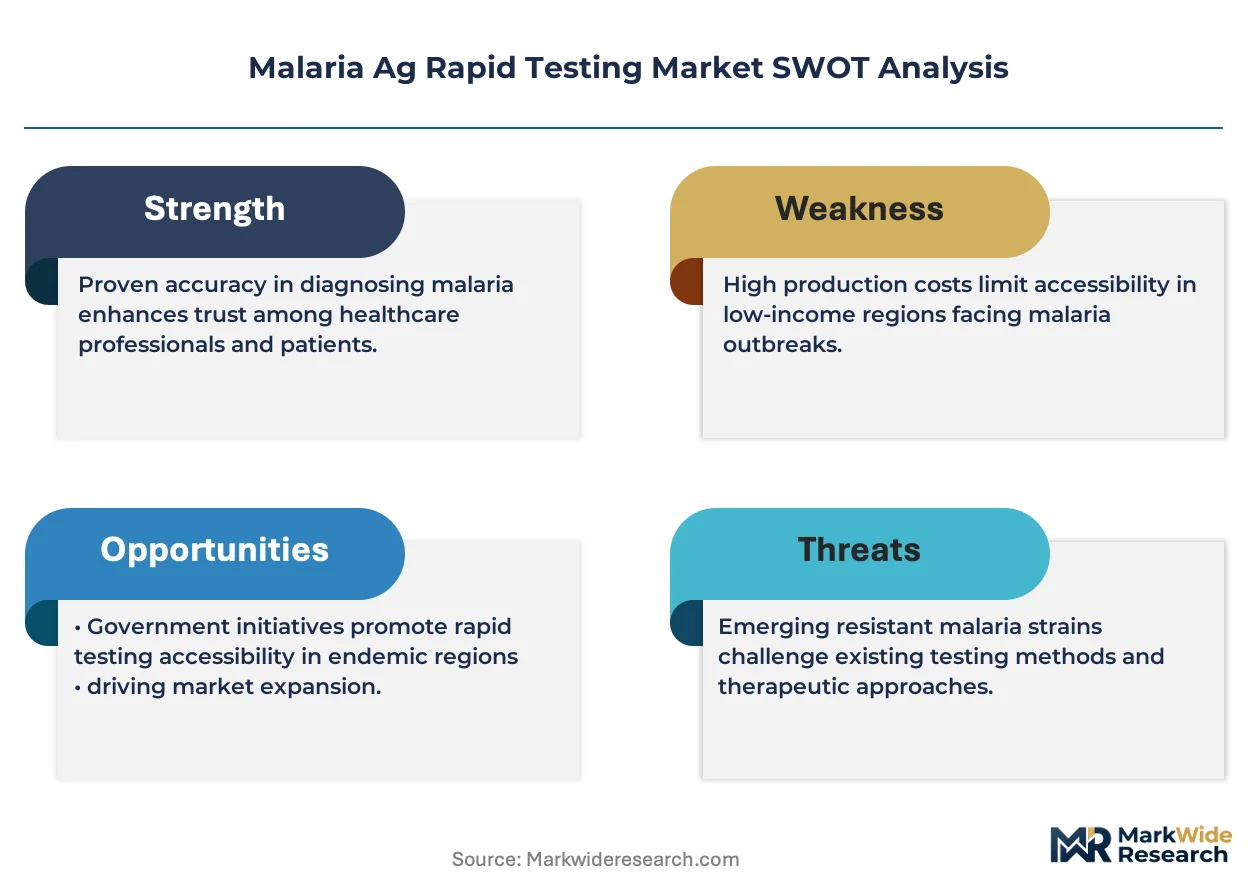
- Nitrocellulose membrane supply concentration:Asian suppliers control critical membrane substrate production, exposing manufacturers to input cost volatility and geographic supply disruption risks.
- EU In Vitro Diagnostic Regulation compliance costs:MDR technical documentation and notified body review timelines are extending market entry cycles for non-CE-marked products.
- Microscopy and PCR substitution:Reference laboratory networks in urban centers retain parasitological confirmation capacity, limiting rapid test penetration in tertiary care settings.
Strategic Opportunities
- Self-test kit regulatory clearance:Home-care channel expansion in Southeast Asian markets is creating new consumer-facing revenue streams beyond institutional procurement.
- Multiplex malaria-dengue formats:Convergent detection platforms addressing overlapping fever syndromes are aligning with WHO target product profiles for next-generation diagnostics.
- India's PLI scheme for diagnostics:Production-linked incentives for domestic manufacturing are attracting membrane casting and strip assembly investments to reduce import dependence.
Industry Challenges
- Monoclonal antibody characterization expertise:Histidine-rich protein II and lactate dehydrogenase specificity validation requires specialized immunoassay development talent that concentrates in established diagnostic hubs.
- Tropical stability certification timelines:Accelerated aging studies for cassette format shelf-life claims extend product development cycles by 12-18 months.
- Legacy health information system integration:Paper-based result reporting in rural clinics creates data capture gaps that digital reader platforms must bridge without infrastructure overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaria Ag Rapid Testing Market |
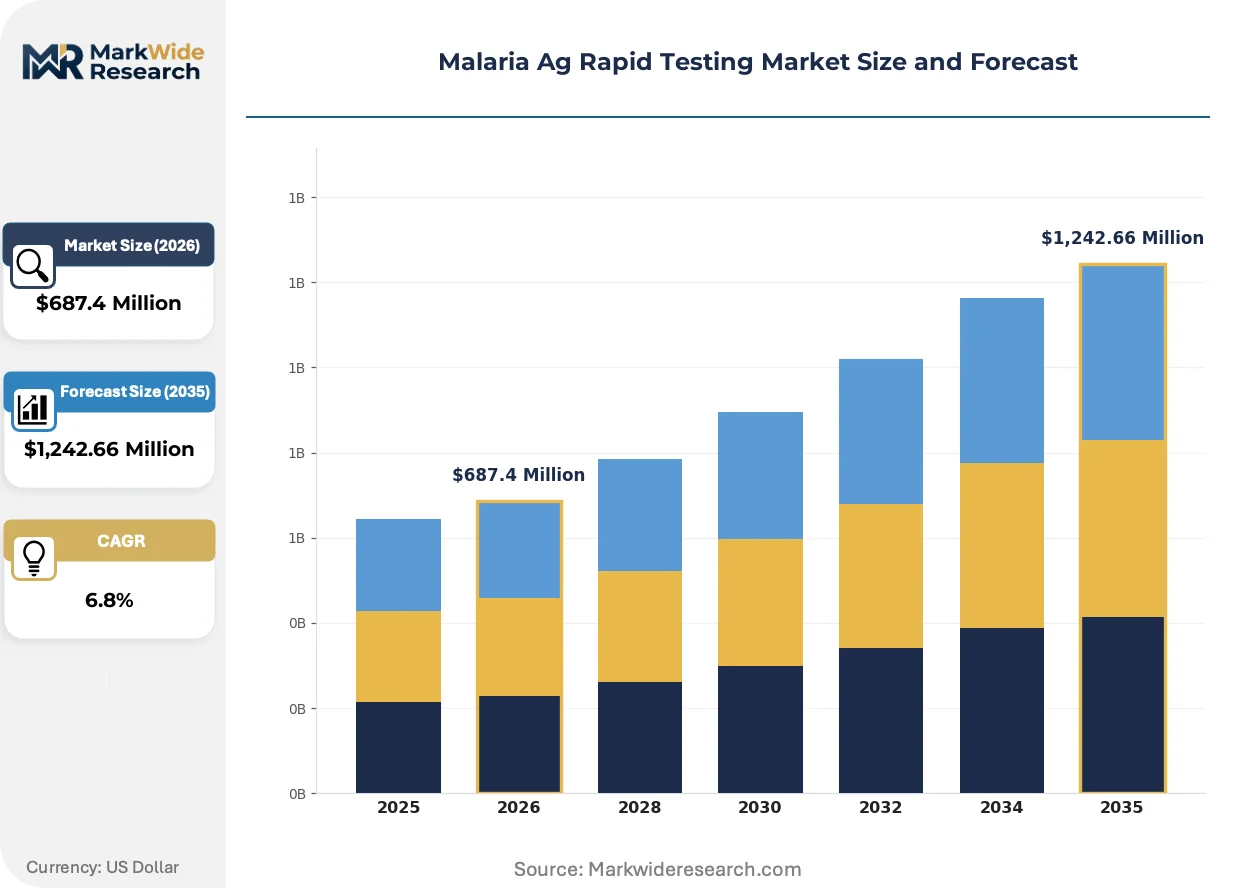
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,242.66 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dipstick, Cassette, Cartridge, Microfluidic End User: Hospitals, Diagnostic Laboratories, Clinics, Home Care Distribution Channel: Direct Sales, Distributors, Online Retail, Pharmacies Technology: Immunochromatographic, Lateral Flow, ELISA, PCR |
| Companies Covered | Abbott Laboratories, Access Bio, Inc., CTK Biotech, Inc., Premier Medical Corporation Pvt. Ltd., SD Biosensor, Inc., Bio-Rad Laboratories, Inc., Alere, Inc., Rapigen Inc., Meril Life Sciences Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaria Ag Rapid Testing Market Shifts & Advancements
Diagnostic platform digitization is converging with regulatory data requirements and procurement consolidation, reshaping how manufacturers capture value across endemic country supply chains.
Smartphone-interpreted lateral flow assays are digitizing result capture and transmission for remote supervision and epidemiological surveillance. District health management teams in Kenya and Nigeria are piloting these systems to replace manual registry entries. The technology is digitizing quality assurance workflows while compressing the feedback loop between field testing and central stock management.
WHO target product profile updates are tightening analytical sensitivity thresholds for ultra-sensitive detection of low-density parasitemia. The revised specifications are disqualifying legacy strip formats from prequalification renewal cycles. Manufacturers with membrane casting and conjugate pad optimization capabilities are accelerating reformulation programs to meet the new performance benchmarks.
NGO procurement consolidation through the Global Fund and PMI is concentrating purchasing power among fewer suppliers with full vertical control over membrane sourcing and strip assembly. Tender specifications now bundle volume commitments with post-market surveillance obligations. This buyer concentration is most visible in West African markets where national malaria control programs have centralized diagnostic commodity procurement at federal level.
Malaria Ag Rapid Testing Market Segmentation
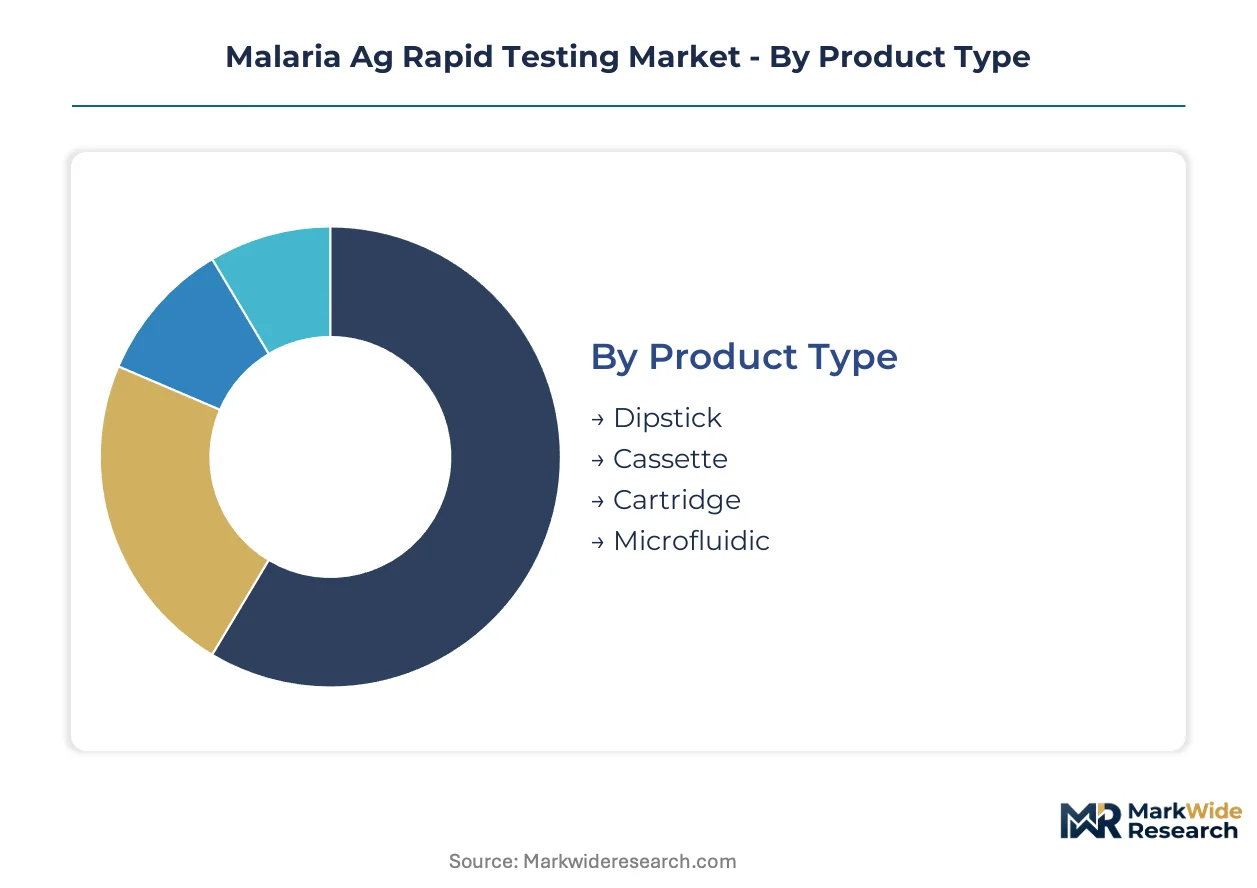
Segmentation in malaria rapid diagnostics reveals how procurement economics, clinical workflow requirements, and regulatory pathways fragment demand across institutional and consumer channels. Understanding these divides helps manufacturers align product formats with specific access constraints and margin structures.
Product Type:
Cassette and cartridge formats turn over inventory fastest in high-throughput clinic settings, while microfluidic platforms cycle slowly through regulatory validation and tender qualification stages.
- Cassette:Plastic-housed lateral-flow strips with built-in sample pad and result window deliver superior thermal stability in tropical storage conditions. Demand concentrates in Nigerian and Kenyan public health clinics where heat exposure degrades unprotected dipstick performance.
- Cartridge:Self-contained units with integrated buffer reservoirs and waste chambers reduce handling steps for low-literacy health workers. Procurement through Global Fund supply chains in the Democratic Republic of Congo favors this format for community health worker deployment.
- Dipstick:Bare strip format requiring external buffer addition serves cost-constrained microscopy replacement programs in rural Ethiopia and Tanzania.
- Microfluidic:Capillary-driven channel architectures with on-board reagent storage target next-generation WHO target product profile compliance for ultra-sensitive detection thresholds.
Cassette anchors the volume base while microfluidic gains share at the steepest rate.
End User:
Cost tiers separate institutional buyers with tender-negotiated pricing from emerging consumer segments paying retail premiums.
- Hospitals:Tertiary care facilities in urban Nigeria and Kenya maintain parallel microscopy confirmation capacity, using rapid tests primarily for emergency department triage where turnaround time outweighs sensitivity requirements.
- Diagnostic Laboratories:Reference networks in South Africa and Ghana perform quality control validation and prevalence surveys, driving demand for reader-compatible formats with digital result capture.
- Clinics:Primary health centers across sub-Saharan Africa represent the dominant procurement channel, with national malaria control programs centralizing diagnostic commodity purchasing at federal level in West African markets.
- Home Care:Self-test kits cleared by regulators in Thailand and Cambodia are expanding fastest among returning travelers and private consumers seeking pre-treatment confirmation.
Clinics anchor the volume base while home care climbs the fastest.
Distribution Channel:
Volume scale concentrates through direct sales to national programs, while margin capture shifts toward specialized distributor networks handling cold chain and regulatory documentation.
- Distributors:Regional logistics specialists with WHO prequalification expertise manage customs clearance and in-country warehousing for Global Fund and PMI deliveries across Francophone West Africa.
- Direct Sales:Manufacturer relationships with Nigeria's Federal Ministry of Health and Kenya's National Malaria Control Program bypass intermediaries for bulk tender fulfillment.
- Pharmacies:Retail channels in urban Southeast Asian markets serve private clinicians and self-paying patients outside public procurement systems.
- Online Retail:E-commerce platforms in India and Brazil target research institutions and NGOs with small-volume, multi-product orders requiring rapid delivery flexibility.
Distributors anchor the volume base while online retail expands most quickly.
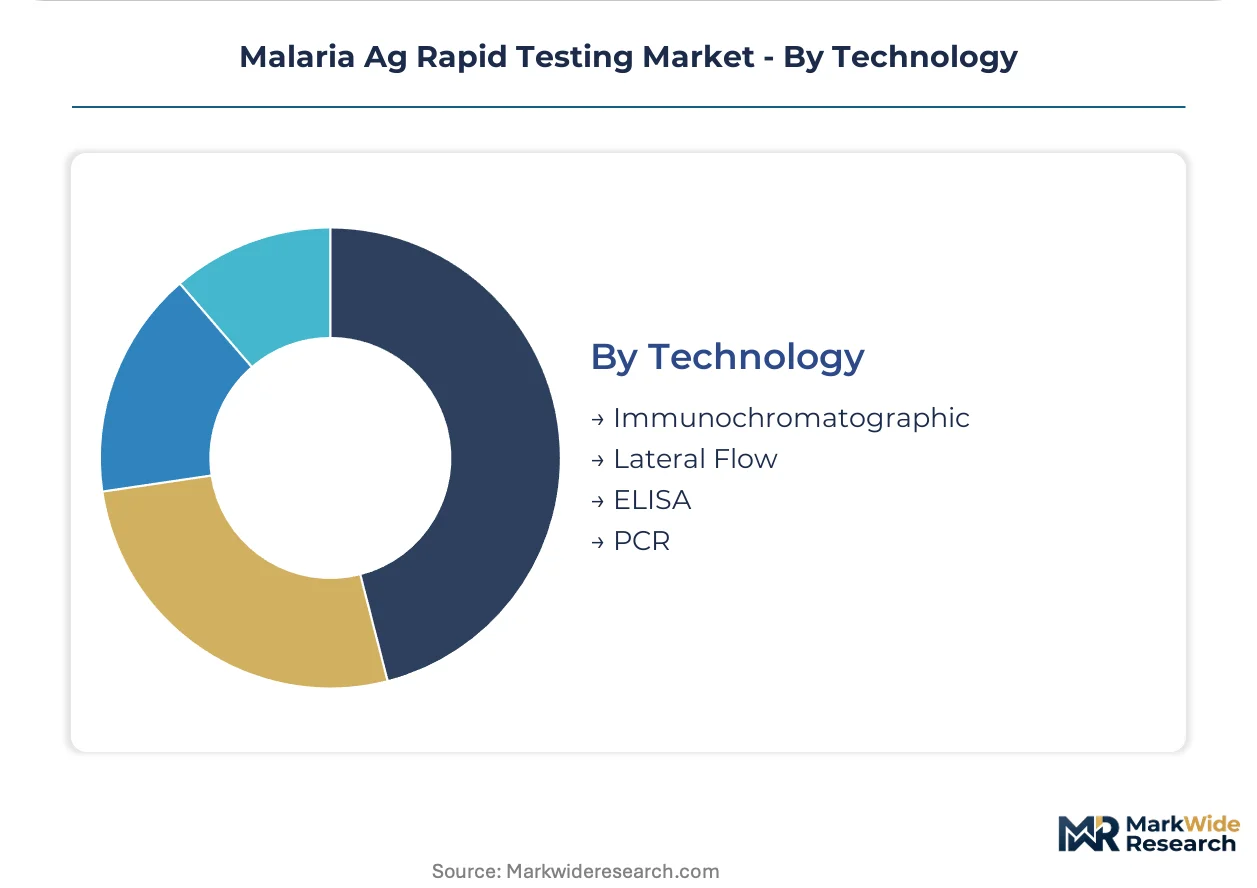
Technology:
Maturity curves separate field-proven immunochromatographic platforms from emerging molecular methods still scaling manufacturing economics.
- Immunochromatographic:Nitrocellulose membrane-based capture of Plasmodium falciparum histidine-rich protein II dominates WHO prequalified product lists and bulk procurement tenders.
- Lateral Flow:Reader-independent strip formats with visual line interpretation serve community health worker programs in low-literacy settings across rural Uganda and Mozambique.
- ELISA:Plate-based enzyme-linked assays with quantitative readout retain niche demand in research and epidemiological surveillance applications requiring parasitemia quantification.
- PCR:Nucleic acid amplification platforms with species differentiation capability serve reference laboratory confirmation and drug resistance monitoring networks in South Africa and Thailand.
Immunochromatographic anchors the volume base while PCR shows the steepest expansion trajectory among confirmation-tier applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian membrane manufacturers supply nitrocellulose substrates to diagnostic assemblers in Nigeria, Kenya, and the Democratic Republic of Congo, forming the backbone of sub-Saharan Africa's point-of-care testing infrastructure.
Nigeria
Federal Ministry of Health tenders drive cassette format procurement for 10,000 primary health centers. WHO prequalification status determines eligibility for Global Fund disbursements. Lagos and Abuja host distribution hubs where regional logistics specialists manage customs clearance for bulk diagnostic deliveries.
Kenya
National Malaria Control Program centralizes purchasing for 5,000 rural clinics replacing microscopy with rapid tests. District health management teams in Nairobi and Kisumu pilot smartphone-interpreted assays for remote supervision. KEMSA warehouses buffer inventory against supply disruptions.
Democratic Republic of Congo
Community health worker programs in Kinshasa and Lubumbashi favor cartridge formats with integrated buffer reservoirs. PMI supply chains mandate prequalified products for provincial procurement. Tropical stability requirements exclude unprotected dipstick formats from eastern region tenders.
India
PLI scheme incentives attract membrane casting investments to Tamil Nadu and Karnataka. CDSCO regulatory pathways clear self-test kits for Southeast Asian export markets. Mumbai and Delhi serve as procurement coordination centers for NGO bulk orders.
Thailand
FDA Thailand clearance for home-care self-tests opens private consumer channels in Bangkok and Chiang Mai. Border malaria programs in Mae Sot deploy reader-compatible formats for epidemiological surveillance. Reference laboratories in Bangkok retain PCR confirmation capacity for drug resistance monitoring.
Malaria Ag Rapid Testing Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated membrane-to-device manufacturers and strip assemblers dependent on external substrate sourcing. Three strategic archetypes dominate: vertically controlled Asian producers with captive nitrocellulose supply, multinational diagnostic divisions leveraging established distribution networks, and regional specialists targeting tender-specific procurement channels. Competitive moves center on backward integration into membrane casting and strategic partnerships with national malaria control programs for tender pre-qualification.
Among U.S.-based diversified diagnostic manufacturers, Abbott Laboratories and Bio-Rad Laboratories occupy positions spanning institutional and research channels. SD Biosensor, Inc. and Rapigen Inc. represent Korean specialists with concentrated presence in prequalified product lists. Access Bio, Inc. anchors the vertically integrated tier with in-house membrane production capabilities.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Access Bio, Inc. |
| CTK Biotech, Inc. |
| Premier Medical Corporation Pvt. Ltd. |
| SD Biosensor, Inc. |
| Bio-Rad Laboratories, Inc. |
| Alere, Inc. |
| Rapigen Inc. |
| Meril Life Sciences Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Tamil Nadu's membrane casting clusters determine downstream pricing power for diagnostic assemblers across sub-Saharan Africa, with capacity utilization swings in Indian substrate production transmitting directly to tender pricing in Nigerian and Kenyan procurement cycles. WHO prequalification status creates a bifurcated cost structure where compliant manufacturers command premium positioning against non-certified competitors excluded from Global Fund disbursements.
Pricing Analysis
Next-generation microfluidic cartridge formats extract 40-60% premiums over legacy dipstick products, while reader-independent cassette formats occupy the mid-tier procurement channel for community health worker programs. Price differentiation centers on WHO prequalification tier and tropical stability certification grade, with heat-stabilized formats commanding measurable premiums in Kinshasa and Lagos storage conditions. Cost compression in the dipstick segment is intensifying as Indian PLI scheme subsidies attract new membrane casting entrants. National malaria control programs in West Africa exhibit the highest price sensitivity, while reference laboratories in South Africa and Thailand show lowest sensitivity due to performance-specification procurement.
Supply Chain Analysis
Nitrocellulose polymer feedstock draws from specialized cellulose ester producers in India, China, and Germany, with membrane casting and conjugate pad finishing concentrating in Tamil Nadu and Karnataka manufacturing zones. Critical dependencies include monoclonal antibody cell lines from Korean and US bioreactor facilities, plus plastic cassette molding from Guangdong injection specialists. Single-source vulnerability in histidine-rich protein II antibody supply creates exposure to batch-to-batch variability disruptions. Distribution runs through WHO-prequalified regional logistics specialists managing Francophone West African customs clearance and in-country warehousing for PMI and Global Fund deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO target product profile updates for ultra-sensitive detection thresholds constitute a regulatory inflection disrupting legacy strip formats and compressing development timelines for next-generation platforms. This technological disruption favors manufacturers with captive membrane casting and accelerated aging certification capabilities.
For Market Incumbents: Harden membrane supply security through backward integration into nitrocellulose casting or long-term offtake agreements with Tamil Nadu substrate specialists, insulating against Asian supplier concentration risks. Accelerate reformulation programs to meet revised WHO sensitivity benchmarks before prequalification renewal cycles disqualify legacy formats. Channel control through direct national program relationships in Nigeria and Kenya remains critical as procurement consolidates at federal level.
For New Entrants and Emerging Players: Build out regulatory capabilities targeting India's CDSCO self-test kit pathway for Southeast Asian export markets, where home-care channels escape tender-based price compression. The most penetrable white-space sits in multiplex malaria-dengue formats aligning with WHO target product profiles for convergent fever syndrome diagnostics. A go-to-market angle through NGO procurement specialists with established Global Fund access bypasses direct national program relationship barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated membrane-to-device manufacturers with demonstrated tropical stability certification timelines and prequalified product lists. Long-term viability over the next decade rests on WHO compliance durability rather than volume scale alone. The acquisition target archetype combines captive nitrocellulose supply with district-level distribution relationships in Francophone Africa. The signal to watch is prequalification renewal success rates as revised target product profiles filter non-compliant legacy formats from tender eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Renewal | Secures continued Global Fund and PMI tender eligibility for compliant manufacturers. |
| Backward Integration into Membrane Casting | Reduces nitrocellulose supply concentration risk from Asian substrate specialists. |
| Microfluidic Platform Development | Aligns with WHO ultra-sensitive detection thresholds for next-generation product profiles. |
| Multiplex Format Expansion | Captures convergent malaria-dengue diagnostic demand in overlapping fever syndrome markets. |
| Self-Test Kit Regulatory Clearance | Opens private consumer channels in Thailand and Cambodia beyond institutional procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with malaria control program procurement officers, diagnostic laboratory directors, community health worker supervisors, membrane casting facility managers, and monoclonal antibody development scientists. Secondary validation drew from WHO prequalification product lists, Global Fund procurement databases, CDSCO regulatory filings, and PMI supply chain disclosures. Bottom-up volume modeling across product formats and end-user segments was triangulated against top-down macroeconomic indicators for endemic country health expenditure.
Calibration against historical tender award volumes and price realization data anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format stability tier, end-user institutional category, distribution channel type, and regional regulatory cluster. CAGRs were derived from slope analysis of adoption curves and procurement commitment trajectories. Industry-specific forecast inputs incorporated WHO target product profile revision timelines and PLI scheme capacity addition schedules in Indian manufacturing zones.
Stress conditions across nitrocellulose supply disruption, prequalification renewal failure rates, and microscopy replacement pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway stability and endemic country health financing continuity. Cross-checking against WHO Global Malaria Programme incidence trend data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Pregnancy Point of Care Testing Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
Friability Tester Market
Testing Services
Drug Testing Market
Testing Services
Dengue Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Global Bioburden Testing Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Calprotectin Testing Market