
 Breath Biopsy Testing Market | 2026-2036
Breath Biopsy Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Breath Biopsy Testing Market Insights
Buyer concentration among hospital networks is recalibrating procurement standards for breath biopsy platforms. Owlstone Medical leverages its ReCIVA sampling device to anchor clinical partnerships with large integrated delivery networks. Menssana Research Inc. competes through its BreathLink system, which specializes in rapid metabolic screening for emergency departments. Biodesix Inc. differentiates by extending its lung cancer blood-testing franchise into complementary breath-based biomarker discovery.
Breath biopsy testing captures volatile organic compounds and other biomarkers from exhaled breath using specialized collection devices coupled with analytical instruments such as gas chromatography or mass spectrometry, enabling non-invasive disease detection at parts-per-billion sensitivity. The technology serves primary commercial purpose in early-stage cancer screening and metabolic monitoring where repeated blood draws impose patient burden or infection risk. Mass spectrometry dominates current instrument revenue due to its analytical precision, while sensor technology occupies the fastest-expansion trajectory as semiconductor miniaturization reduces unit costs for point-of-care deployment. Cancer detection anchors application demand, though gastrointestinal disorder screening via hydrogen breath testing sustains higher test volumes in primary care settings.
FDA regulates breath biopsy devices through its in vitro diagnostic and 510(k) pathways, requiring clinical validation of volatile organic compound panels before commercial claims. EMA's In Vitro Diagnostic Regulation mandates performance studies and post-market surveillance for European market access, lengthening certification timelines but elevating clinical evidence standards. ISO 13485 quality management certification shapes supplier qualification for contract manufacturers serving device developers. Stakeholders must monitor evolving payer coverage determinations for multi-cancer early detection, as reimbursement decisions will determine whether breath biopsy platforms achieve routine clinical utility or remain confined to research and wellness applications.
Market Dynamics
Hospital procurement consolidation is compressing vendor qualification timelines for breath biopsy platforms, forcing device manufacturers to demonstrate interoperable data architectures and capitated cost structures before contract approval.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated review timelines for volatile organic compound biomarker panels are shortening clinical validation cycles and expanding reimbursable test menus.
- Integrated delivery networks:Large hospital systems in the United States are consolidating laboratory purchasing into centralized agreements that favor multi-site breath biopsy deployments.
- Silicon photonics miniaturization:Semiconductor foundries are driving down sensor unit costs for point-of-care breath analyzers, enabling primary care penetration.
Market Restraints
- Mass spectrometer supply concentration:Precision instrument manufacturing clusters in Germany and Japan create procurement bottlenecks for chromatography-mass spectrometry systems.
- EMA In Vitro Diagnostic Regulation compliance costs:Extended performance study requirements and post-market surveillance obligations are elevating European market entry capital requirements.
- Multi-cancer screening substitution:Liquid biopsy blood tests with established CPT reimbursement codes are capturing oncology screening budgets ahead of breath-based alternatives.
Strategic Opportunities
- Japan's metabolic disease screening mandate:METI-supported preventive health programs are creating pilot procurement channels for hydrogen breath testing in gastrointestinal diagnostics.
- Sensor-software convergence:Machine learning pattern recognition layered onto metal-oxide semiconductor arrays is enabling real-time biomarker identification without laboratory infrastructure.
- Direct-to-employer contracting:Self-insured corporations in the United States are bypassing traditional payer networks to fund workplace cancer screening programs.
Industry Challenges
- Cross-functional talent scarcity:Device developers struggle to recruit specialists combining clinical metabolomics expertise with regulatory affairs certification for FDA in vitro diagnostic submissions.
- Interoperability integration complexity:Hospital IT departments face extended implementation timelines connecting proprietary breath biopsy data formats to existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breath Biopsy Testing Market |
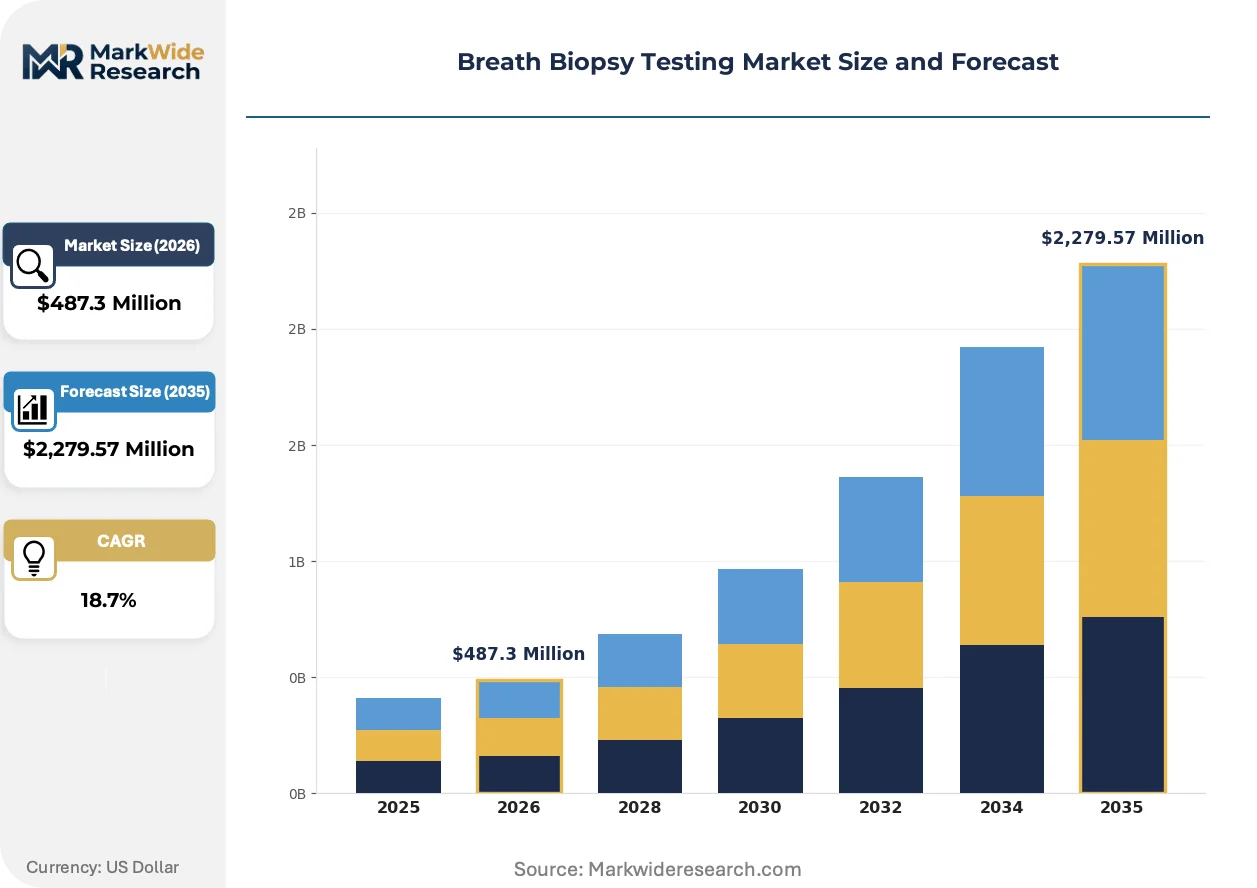
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,279.57 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Chromatography, Mass Spectrometry, Sensor Technology, Hydrogen Breath Test End User: Hospitals, Diagnostic Laboratories, Research Institutions, Homecare Settings Application: Cancer Detection, Metabolic Disorders, Gastrointestinal Disorders, Infection Diagnosis Technology: Non-invasive Testing, Point of Care Testing, Wearable Devices, Cloud-based Solutions |
| Companies Covered | Owlstone Medical, Breath Biopsy, Menssana Research Inc., GSK, Biodesix Inc., Philips Healthcare, Bedfont Scientific Ltd., IONICON, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breath Biopsy Testing Market Trends and Innovations
Artificial intelligence pattern recognition is reshaping how volatile organic compound signatures translate into diagnostic outputs, compressing the gap between raw sensor data and clinical decision support.
Metal-oxide semiconductor sensor arrays are electrifying point-of-care deployment by replacing laboratory-bound mass spectrometry with handheld devices capable of parts-per-billion sensitivity. Emergency departments in Germany are piloting these systems for rapid metabolic screening. The technology is electrifying competitive positioning by enabling same-shift diagnostic workflows that blood draws cannot match.
REACH regulation amendments governing chemical exposure biomonitoring are creating compliance-driven demand for standardized breath collection protocols across European occupational health programs. Industrial hygiene departments must now document volatile organic compound absorption through validated biological monitoring methods. Pharmaceutical manufacturing sites in Switzerland and the Netherlands are adopting breath biopsy platforms to satisfy ECHA reporting requirements for worker solvent exposure.
Hospital laboratory directors are unbundling after-sales service contracts from capital equipment purchases, negotiating separate agreements for preventive maintenance, software updates, and biomarker panel expansions. This purchasing behavior is fragmenting vendor revenue streams and compressing upfront equipment margins. The pattern is most visible in United States integrated delivery networks where procurement committees now mandate multi-year total cost of ownership analyses.
Breath Biopsy Testing Market Segmentation
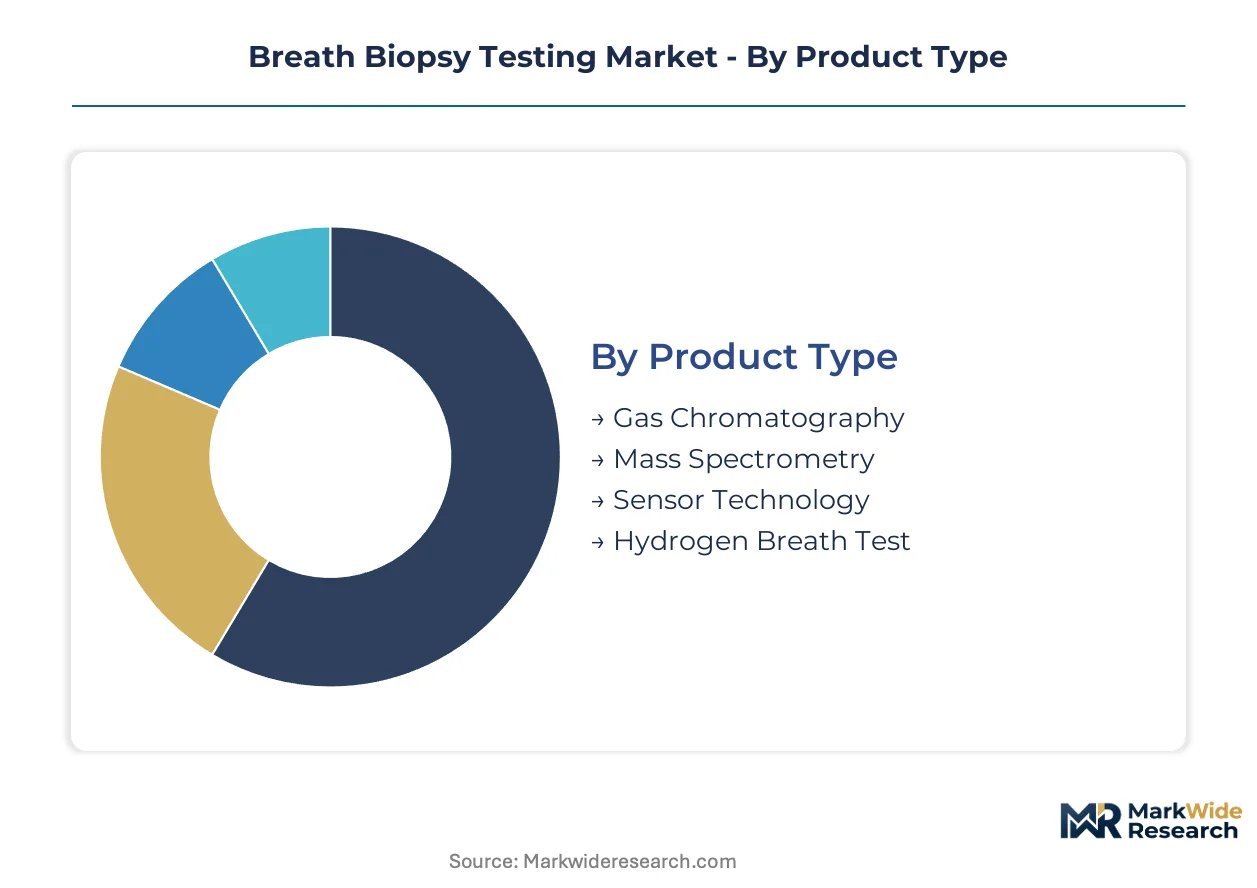
Breath biopsy platforms serve divergent clinical workflows ranging from centralized laboratory validation to decentralized point-of-care screening. Segmentation reveals how technology maturity, reimbursement pathways, and patient access requirements reshape procurement decisions across care settings.
Product Type:
Mass spectrometry commands premium pricing through analytical precision, while sensor technology penetrates high-volume primary care channels on cost efficiency.
- Mass Spectrometry:Laboratory-grade instrumentation achieves parts-per-billion sensitivity for volatile organic compound quantification. United States integrated delivery networks concentrate procurement for oncology biomarker validation programs.
- Sensor Technology:Metal-oxide semiconductor arrays miniaturize detection into handheld form factors. German emergency departments pilot same-shift metabolic screening where rapid turnaround displaces laboratory-dependent workflows.
- Gas Chromatography:Established separation technique paired with flame ionization or thermal conductivity detection for standardized breath panels.
- Hydrogen Breath Test:Dedicated lactulose and glucose substrates for small intestinal bacterial overgrowth diagnosis in gastroenterology clinics.
Mature deployment sits with mass spectrometry in tertiary oncology centers. Newer deployment is concentrated in sensor technology for ambulatory and workplace screening programs.
End User:
Hospital procurement committees consolidate capital equipment purchasing, fragmenting vendor revenue through unbundled service contracts.
- Hospitals:Centralized laboratory infrastructure anchors high-complexity testing for cancer detection and metabolic monitoring. United States payer negotiations for multi-cancer early detection reimbursement determine test menu expansion timelines.
- Diagnostic Laboratories:Independent reference labs aggregate specimens from dispersed physician practices, requiring interoperable data formats for electronic health record integration.
- Research Institutions:Academic medical centers conduct biomarker discovery and clinical validation studies under FDA investigational device exemption protocols.
- Homecare Settings:Direct-to-consumer and remote patient monitoring applications where simplified collection devices enable longitudinal metabolic tracking.
Revenue concentration favors hospitals for high-margin oncology panels. Steepest expansion trajectory appears in homecare settings as wearable form factors achieve regulatory clearance.
Application:
Cancer detection attracts venture funding and regulatory priority review, while gastrointestinal disorder screening sustains higher absolute test volumes.
- Cancer Detection:Volatile organic compound panels target lung, colorectal, and gastric malignancies through non-invasive screening. Japan's METI-supported preventive health programs create pilot procurement channels for workplace deployment.
- Gastrointestinal Disorders:Hydrogen and methane breath testing for carbohydrate malabsorption and small intestinal bacterial overgrowth dominates primary care test volumes.
- Metabolic Disorders:Diabetes monitoring and ketone detection applications leverage real-time sensor feedback for patient self-management.
- Infection Diagnosis:Pathogen-specific volatile biomarker signatures for respiratory and systemic infections under early clinical validation.
Clinical evidence maturity concentrates in gastrointestinal disorders with established CPT reimbursement. Biomarker discovery investment flows fastest into cancer detection pipelines.
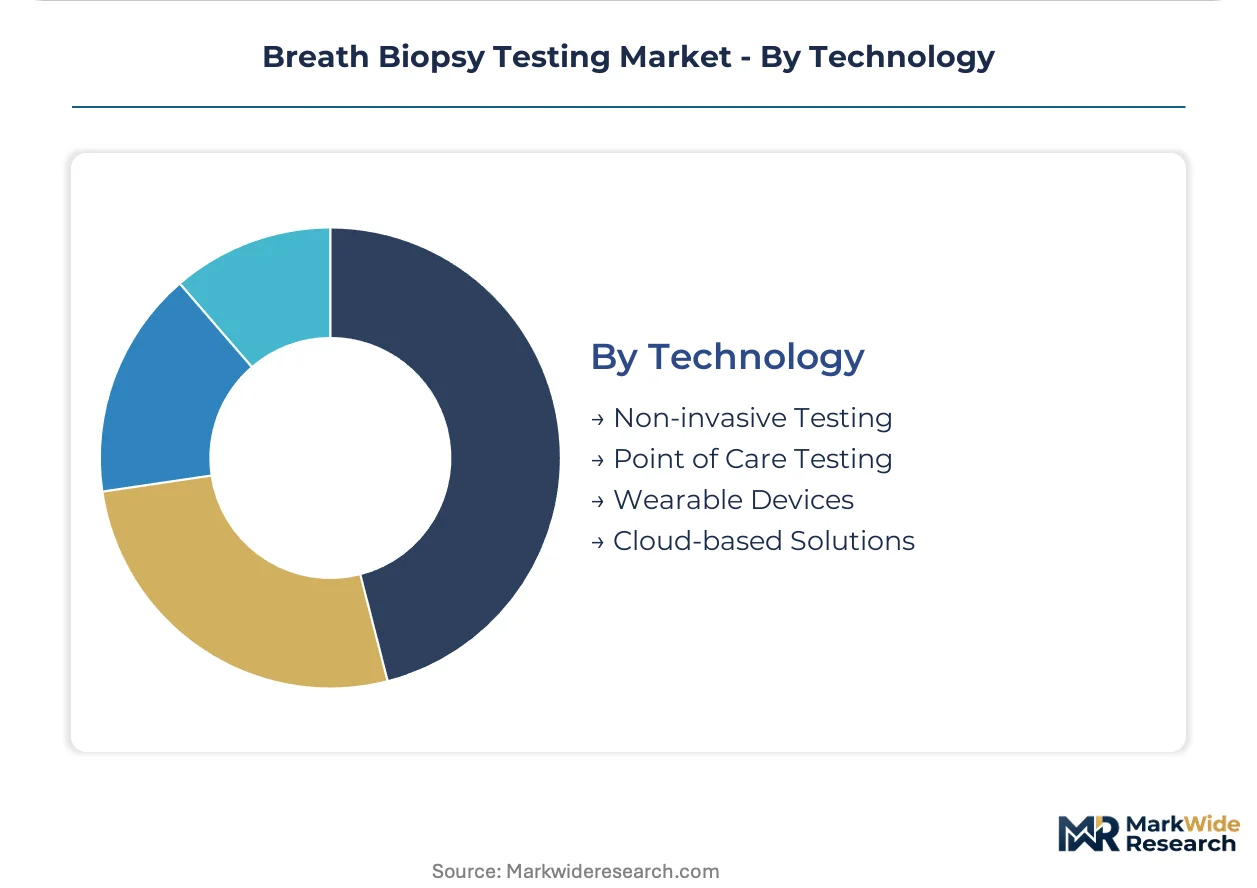
Technology:
Non-invasive sampling underpins commercial differentiation, while cloud architecture determines enterprise scalability for multi-site health systems.
- Non-invasive Testing:Exhaled breath collection eliminates phlebotomy requirements, reducing infection risk and patient burden for serial monitoring.
- Point of Care Testing:Decentralized deployment in ambulatory clinics and emergency departments where same-visit results drive clinical workflow efficiency.
- Wearable Devices:Continuous monitoring form factors integrate breath sampling with activity tracking for metabolic disease management.
- Cloud-based Solutions:Centralized algorithm updates and biomarker panel expansion enable software-as-a-service revenue models for device manufacturers.
Regulatory clearance density clusters in non-invasive testing and point-of-care platforms. Wearable devices face the longest validation pathway for clinical-grade accuracy claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan are negotiating payer reimbursement frameworks for breath-based oncology screening. Payer decisions in these markets will determine whether breath biopsy platforms achieve routine clinical utility or remain confined to research applications.
United States
Integrated delivery networks in Texas and the Northeast Corridor are consolidating laboratory purchasing into centralized agreements that favor multi-site breath biopsy deployments. FDA 510(k) pathway streamlining for volatile organic compound biomarker panels is shortening clinical validation cycles. The Greater Boston cluster anchors biomarker discovery pipelines under investigational device exemption protocols.
Germany
Emergency departments in Bavaria and North Rhine-Westphalia are piloting metal-oxide semiconductor sensor arrays for same-shift metabolic screening. EMA In Vitro Diagnostic Regulation compliance costs are elevating European market entry capital requirements for device manufacturers. Precision instrument manufacturing clusters around Munich and Stuttgart create procurement bottlenecks for chromatography-mass spectrometry systems.
Japan
METI-supported preventive health programs are creating pilot procurement channels for hydrogen breath testing in gastrointestinal diagnostics. PMDA regulatory frameworks are adapting to accommodate real-world evidence submissions for wearable breath monitoring devices. The Kanto region around Tokyo concentrates venture funding for cancer detection biomarker discovery.
Switzerland
Pharmaceutical manufacturing sites in Basel and Zurich are adopting breath biopsy platforms to satisfy ECHA reporting requirements for worker solvent exposure under REACH regulation amendments. Swissmedic certification timelines for point-of-care devices are shorter than EMA pathways, attracting early-stage device developers. The Lake Geneva corridor hosts contract research organizations conducting multi-center validation studies.
United Kingdom
NHS England's accelerated access collaborative is evaluating breath biopsy technologies for lung cancer screening pathway integration. MHRA post-Brexit regulatory autonomy is enabling faster approval timelines for devices with existing FDA clearance. The Oxford-Cambridge arc anchors academic medical centers conducting volatile organic compound panel validation research.
Breath Biopsy Testing Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in precision instrumentation and regulatory compliance services. The vendor base organizes around three strategic archetypes: integrated diagnostic platform developers, component specialists for sampling devices and sensors, and contract research organizations managing clinical validation. Competitive moves concentrate on strategic partnerships with hospital networks and technology licensing agreements for semiconductor sensor arrays.
Within the integrated platform tier, Owlstone Medical and Menssana Research Inc. exemplify device developers anchoring clinical partnerships through proprietary sampling systems. Biodesix Inc. occupies a position bridging blood-based and breath-based diagnostic modalities. These three companies represent contrasting approaches to market entry: one through emergency department workflow integration, another through metabolic screening specialization, and the third through franchise extension from established oncology testing.
| Leading Market Players |
|---|
| Owlstone Medical |
| Breath Biopsy |
| Menssana Research Inc. |
| GSK |
| Biodesix Inc. |
| Philips Healthcare |
| Bedfont Scientific Ltd. |
| IONICON |
| Drägerwerk AG & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
Mass spectrometry-to-sensor technology bifurcation creates divergent margin profiles across the breath biopsy testing value chain, with laboratory-grade precision instruments commanding premium pricing tethered to German and Japanese component sourcing while semiconductor-miniaturized point-of-care devices compress unit economics through Taiwanese foundry partnerships.
Pricing Analysis
Volume concentration in gastrointestinal hydrogen breath testing generates commodity-margin pressure, while oncology biomarker panels sustain premium positioning through FDA 510(k) certification tiers and unbundled service contracts. Three-tier pricing structure across premium, standard, and economy levels reflects analytical precision gradations and after-sales bundling complexity. Cost compression in sensor arrays is intensifying because Taiwanese semiconductor foundries are driving silicon photonics unit costs downward. Primary care networks exhibit highest price sensitivity, whereas United States integrated delivery networks prioritize total cost-of-ownership over per-unit acquisition.
Supply Chain Analysis
Single-source vulnerability sits with precision mass spectrometer manufacturing clusters in Germany and Japan, where chromatography-mass spectrometry subsystem production anchors analytical instrument supply. Device assembly draws from semiconductor sensor inputs out of Taiwan, specialized breath collection polymers from Switzerland, and precision machining from South Korea. Tariff exposure on precision optics creates procurement risk for United States device developers. Distribution runs through hospital procurement committees and group purchasing organizations that consolidate multi-site laboratory agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation functions as a consolidation play, with integrated delivery network vendor qualification timelines forcing capital-constrained device developers toward strategic exits or acquisition.
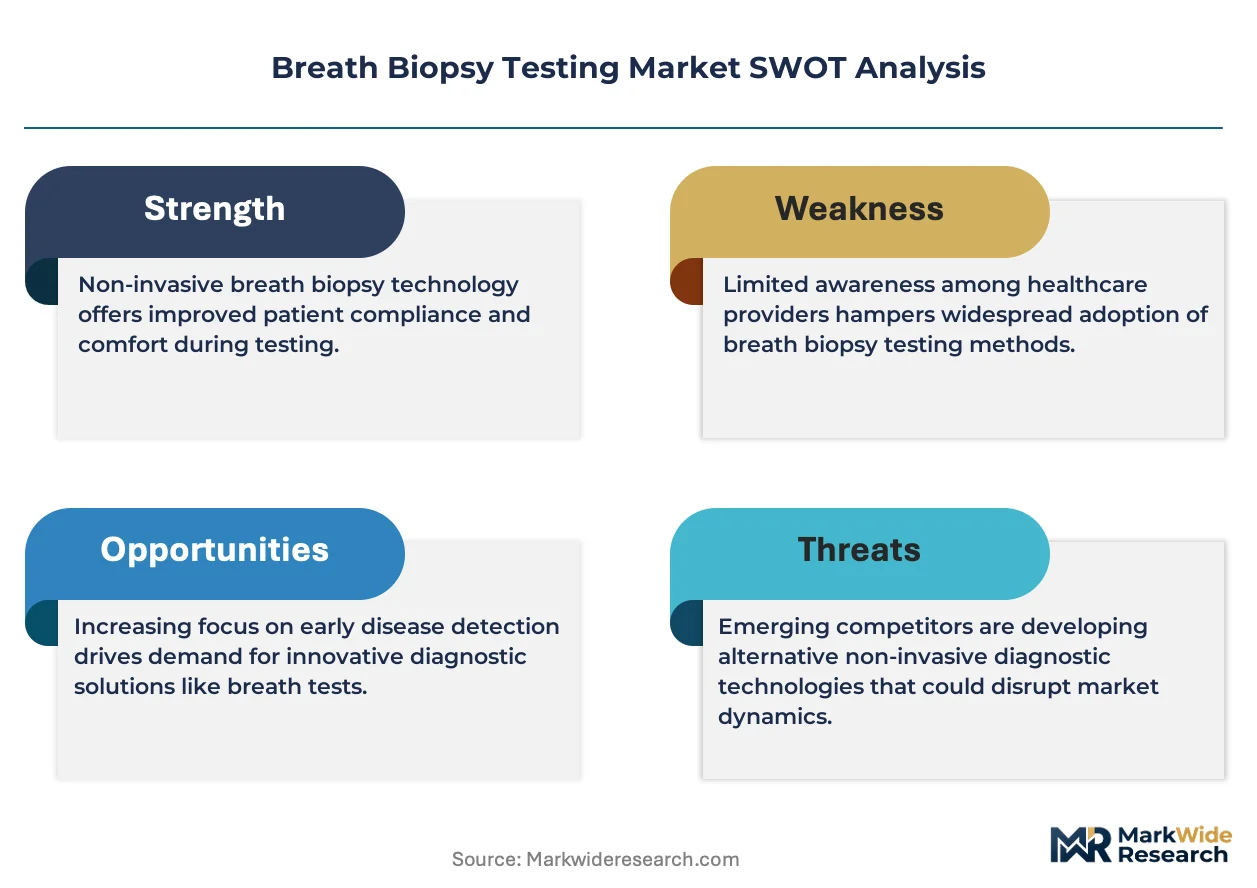
For Market Incumbents: To counter liquid biopsy blood-test substitution in oncology screening budgets, anchor multi-year service contracts with United States hospital networks and deepen backward integration into semiconductor sensor design. FDA 510(k) pathway expertise functions as a defendable moat against emerging entrants lacking regulatory affairs certification.
For New Entrants and Emerging Players: Launch via direct-to-employer contracting channels that bypass traditional payer reimbursement negotiations, targeting self-insured corporations for workplace cancer screening programs. Japan's METI-supported preventive health programs represent the most penetrable geography given pilot procurement channel availability and PMDA real-world evidence accommodation.
For Investors and Strategic Acquirers: Re-rating potential sits with sensor-software convergence specialists given machine learning pattern recognition catalysts enabling laboratory-free diagnostic workflows. Long-term viability hinges on cloud-based biomarker panel expansion capabilities and recurring software-as-a-service revenue attachment. Watch for FDA multi-cancer early detection reimbursement determinations as the definitive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-site deployment agreements with United States integrated delivery networks lock in recurring service revenue streams. |
| FDA 510(k) Submission | Accelerated review timelines for volatile organic compound panels shorten clinical validation cycles and expand reimbursable test menus. |
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation compliance elevates European market entry barriers but validates premium pricing claims. |
| Software Companion Development | Machine learning algorithms layered onto metal-oxide semiconductor arrays enable real-time biomarker identification without laboratory infrastructure. |
| Reimbursement Strategy | Payer coverage determinations for multi-cancer early detection will determine whether platforms achieve routine clinical utility. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, hospital procurement contract structures, and payer reimbursement negotiations anchored the trend analysis, supplemented by interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists. Secondary validation drew from FDA filings, CMS Medicare coverage determinations, hospital procurement databases, and EMA In Vitro Diagnostic Regulation guidance documents. Bottom-up test volume modeling and top-down market sizing triangulated segment-level outputs.
Segment-weighting across product type, end user, application, and technology dimensions informed the analytical framework over the projection horizon. CAGRs were derived from installed base expansion rates, test menu adoption curves, and pricing trajectory assumptions. Forecast inputs incorporated semiconductor sensor cost decline curves and integrated delivery network consolidation patterns.
Payer reimbursement denial, regulatory validation failure, and liquid biopsy technology substitution are the dominant revision risks that could compress addressable market assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Drug Tester Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Vials Leak Testing Market
Testing Services
Adenovirus Testing Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Americas Sterility Testing Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Ovulation Test Kit Market
Testing Services
Biological Indicator Vials Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
Lab Screening Test Kit Market
Testing Services
Global Rapid Test Market