
 Fertility and Pregnancy Rapid Test Kits Market | 2026-2036
Fertility and Pregnancy Rapid Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Fertility and Pregnancy Rapid Test Kits Market Analysis
Digital integration into lateral flow assay architecture is fragmenting traditional kit design paradigms across the competitive landscape. Abbott Laboratories leverages connected reader technology to sustain premium positioning in multi-parameter fertility tracking. Swiss Precision Diagnostics GmbH anchors European private-label supply through manufacturing scale and channel control. Church & Dwight Co., Inc. competes aggressively in North American retail pharmacy placement with streamlined urine-based formats.
Fertility and pregnancy rapid test kits are immunoassay-based diagnostic devices that detect human chorionic gonadotropin (hCG), luteinizing hormone (LH), or follicle-stimulating hormone (FSH) in biological specimens within minutes through antibody-antigen binding on nitrocellulose membranes. Urine test kits dominate volume due to non-invasive collection and shelf-stable chemistry, while blood test kits command higher analytical sensitivity for early detection windows. Online retail channels are capturing fastest-growing share as subscription-based fertility programs bypass traditional pharmacy stocking, and CE Marked certification remains the baseline threshold for European commercial access.
FDA premarket clearance under 21 CFR 862.1155 governs over-the-counter pregnancy test marketing in the United States, while the EU Medical Device Regulation (MDR) reclassifies self-test devices under stricter conformity assessment procedures. Health Canada and the Therapeutic Goods Administration (TGA) in Australia impose parallel clinical evidence requirements that shape multinational registration sequencing. Stakeholders must monitor evolving software-as-medical-device rulings that could reclassify app-integrated fertility trackers.
Market Dynamics
Digital connectivity integration is fragmenting traditional lateral flow assay architectures as manufacturers race to capture recurring revenue from app-integrated fertility tracking ecosystems rather than one-time disposable sales.
Growth Catalysts
- Self-Monitoring Consumer Behavior:Home-based diagnostic adoption accelerates among women seeking ovulation precision without clinic visits, particularly in markets with high smartphone penetration and pharmacy retail density.
- FDA 21 CFR 862.1155 Pathway:The premarket notification framework for over-the-counter diagnostics enables faster commercial entry compared to prescription device routes, compressing time-to-revenue for novel assay formats.
- Nitrocellulose Membrane Chemistry:Advances in antibody immobilization techniques extend shelf stability and reduce false-positive rates, expanding addressable use cases to early pregnancy detection windows.
Market Restraints
- Antibody Raw Material Concentration:Monoclonal antibody production concentrates among specialized biologics suppliers in the United States and Western Europe, exposing manufacturers to batch variability and qualification delays.
- EU MDR Conformity Assessment:The Medical Device Regulation reclassifies self-test devices under stricter notified body oversight, extending certification timelines and documentation burdens for European market access.
- Digital-Only Fertility Apps:Smartphone-based ovulation prediction algorithms without physical assay components threaten to commoditize the tracking segment among price-sensitive younger demographics.
Strategic Opportunities
- Subscription-Based Fertility Programs:Direct-to-consumer channels bypass traditional pharmacy stocking economics, enabling recurring revenue models that bundle test kits with telehealth consultations and cycle analytics.
- Menopausal Hormone Monitoring:Follicle-stimulating hormone detection for perimenopause tracking represents an underdeveloped application with aging population tailwinds in Japan and Western European markets.
- Health Canada Parallel Review:Alignment with FDA clearance pathways creates streamlined multinational registration sequencing for North American market entry with reduced duplicative clinical evidence requirements.
Industry Challenges
- Software-as-Medical-Device Classification:Evolving rulings on app-integrated fertility trackers threaten to reclassify connected reader technologies under more stringent quality management and cybersecurity standards.
- Lateral Flow Assembly Automation:Precision dispensing of reagent lines onto nitrocellulose membranes requires capital-intensive manufacturing equipment that mid-scale manufacturers struggle to justify at current volume thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertility and Pregnancy Rapid Test Kits Market |
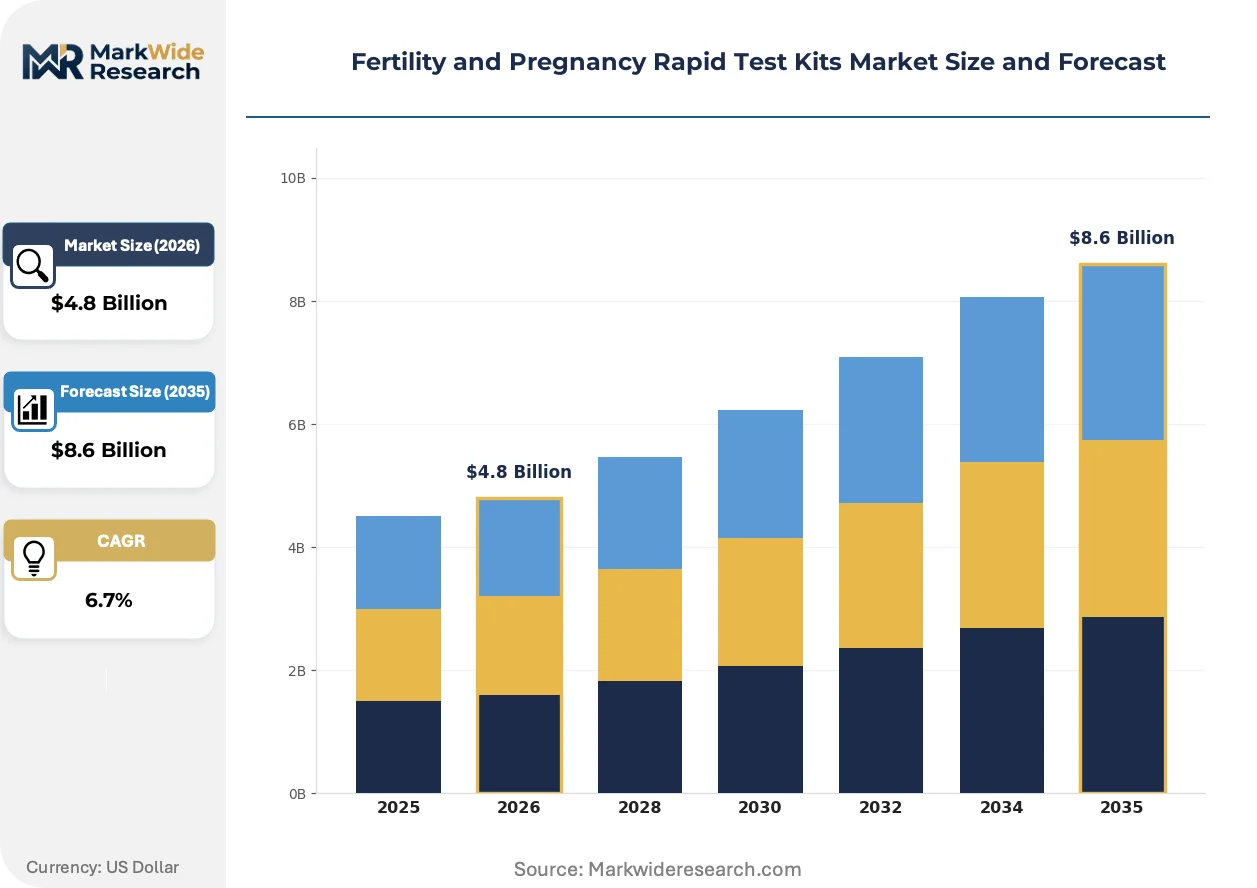
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Test Kits, Saliva Test Kits, Blood Test Kits, Multi-Parameter Test Kits End User: Hospitals, Clinics, Pharmacies, Home Users Distribution Channel: Online Retail, Offline Retail, Medical Distributors, E-commerce Platforms Certification: FDA Approved, CE Marked, ISO Certified, Health Canada Approved |
| Companies Covered | QuidelOrtho Corporation, Prestige Consumer Healthcare Inc., Abbott Laboratories, bioMérieux SA, Geratherm Medical AG, Procter & Gamble Co, Swiss Precision Diagnostics GmbH, Cardinal Health Inc, Church & Dwight Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertility and Pregnancy Rapid Test Kits Market Emerging Trajectories
Assay architecture is converging with consumer electronics as manufacturers embed Bluetooth connectivity and cloud analytics into disposable test formats, transforming single-use products into data collection nodes for longitudinal health monitoring.
Quantitative hCG measurement is migrating from laboratory immunoassay systems to home-based connected readers, enabling precise gestational dating and early pregnancy monitoring without venous blood draws. Fertility clinics and telehealth platforms are piloting these devices for remote patient management. This capability compression is collapsing the traditional boundary between clinical-grade and over-the-counter diagnostic performance tiers.
The EU Medical Device Regulation is forcing manufacturers to rebuild technical documentation and quality management systems for self-test device classifications that previously operated under lighter conformity assessment procedures. Notified body capacity constraints are creating bottlenecks that delay European launches by twelve to eighteen months. Smaller manufacturers without dedicated regulatory affairs functions are exiting the market or seeking private-label partnerships with established certificate holders.
Direct-to-consumer subscription models are displacing retail pharmacy stocking as the primary growth channel, with fertility programs bundling multi-parameter test kits with algorithmic cycle prediction and telehealth access. This channel shift concentrates customer relationships with digital-native brands rather than traditional retail distributors. The United States and United Kingdom markets exhibit the fastest migration toward this consumption pattern, driven by insurance reimbursement gaps for fertility services.
Fertility and Pregnancy Rapid Test Kits Market Segmentation
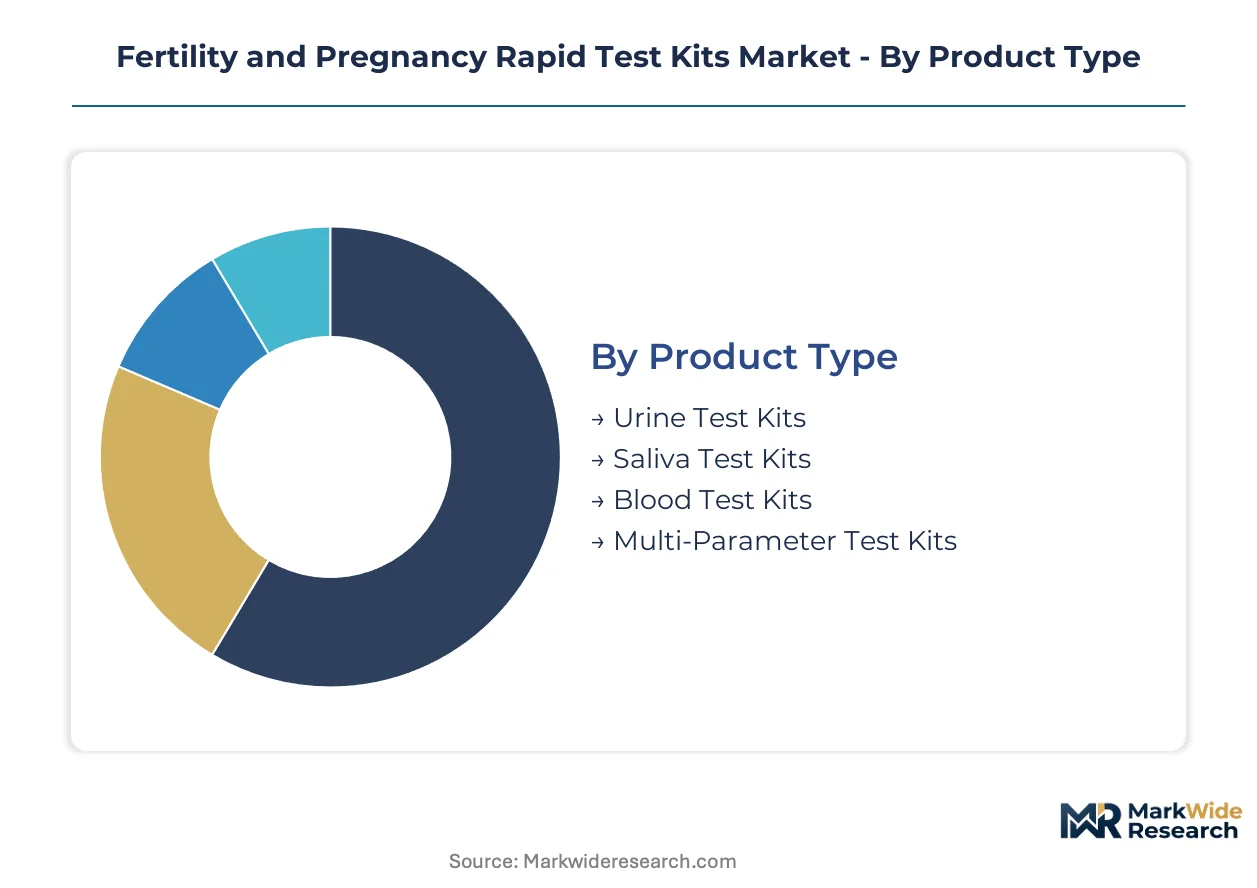
Segmentation in fertility and pregnancy rapid test kits reveals divergent margin structures and service intensity requirements across product formats and channels. Manufacturers calibrate R&D allocation and regulatory sequencing based on which segments promise recurring revenue versus one-time transactions.
Product Type:
After-sales service intensity varies sharply across formats, with connected devices demanding firmware updates and calibration support while disposable strips require minimal ongoing engagement.
- Urine Test Kits:Lateral flow immunoassay strips detect hCG through antibody-antigen binding on nitrocellulose membranes with visual or digital readout. Home users in the United States drive volume through retail pharmacy and subscription channels, constrained by shelf-stability requirements and batch-to-batch antibody consistency.
- Blood Test Kits:Quantitative hCG measurement via finger-prick capillary blood achieves higher analytical sensitivity for early detection windows. Fertility clinics and telehealth platforms in Germany and the United Kingdom pilot these for remote patient monitoring, though venous draw aversion limits home adoption.
- Saliva Test Kits:Electrochemical biosensors measure estrogen and progesterone metabolites in oral fluid samples. European wellness retailers stock these for hormone tracking without urine collection.
- Multi-Parameter Test Kits:Combined LH, FSH, and estrogen detection enables comprehensive cycle mapping through single-device architectures. Japanese consumers show strongest uptake for perimenopause applications.
Urine test kits hold the largest share; momentum sits with multi-parameter formats integrating Bluetooth connectivity.
End User:
Volume concentration tilts toward direct-to-consumer channels, yet clinical settings sustain premium pricing for quantitative readouts and professional interpretation.
- Home Users:Self-monitoring consumers purchase through subscription programs bundling test kits with algorithmic cycle prediction and telehealth access. Smartphone penetration and pharmacy retail density in the United States and United Kingdom accelerate this channel shift.
- Hospitals:Emergency departments and obstetrics units deploy quantitative hCG readers for rapid pregnancy confirmation and ectopic pregnancy screening. Reimbursement coding in France and Spain shapes procurement specifications.
- Clinics:Fertility specialists utilize connected readers for longitudinal hormone monitoring between in-person visits. Australian fertility networks integrate these into remote patient management protocols.
- Pharmacies:Retail pharmacy placement remains deepest in North American markets, though shelf space competition from generic brands compresses margins for branded suppliers.
Home users command the largest share; clinics represent the steepest expansion trajectory as telehealth platforms standardize remote fertility management.
Distribution Channel:
Channel economics fragment between inventory-heavy retail partnerships and capital-light direct relationships with algorithmic health platforms.
- Online Retail:Subscription-based fertility programs bypass traditional pharmacy stocking economics, concentrating customer relationships with digital-native brands. The United States and United Kingdom exhibit fastest migration toward this pattern.
- Offline Retail:Brick-and-mortar pharmacies and supermarkets sustain volume in markets with lower e-commerce penetration, particularly in rural Canada and Australia.
- E-commerce Platforms:Marketplace aggregators enable price comparison and bulk purchasing for cost-sensitive demographics, though counterfeit detection challenges persist.
- Medical Distributors:Hospital and clinic procurement runs through specialized distributors with cold-chain capabilities for temperature-sensitive reagent shipments.
Online retail holds the largest share; medical distributors are gaining share fastest as fertility clinics consolidate purchasing through group purchasing organizations.
Certification:
Regulatory pathway selection determines timeline-to-revenue and addressable market scope, with multi-jurisdiction clearance commanding premium positioning.
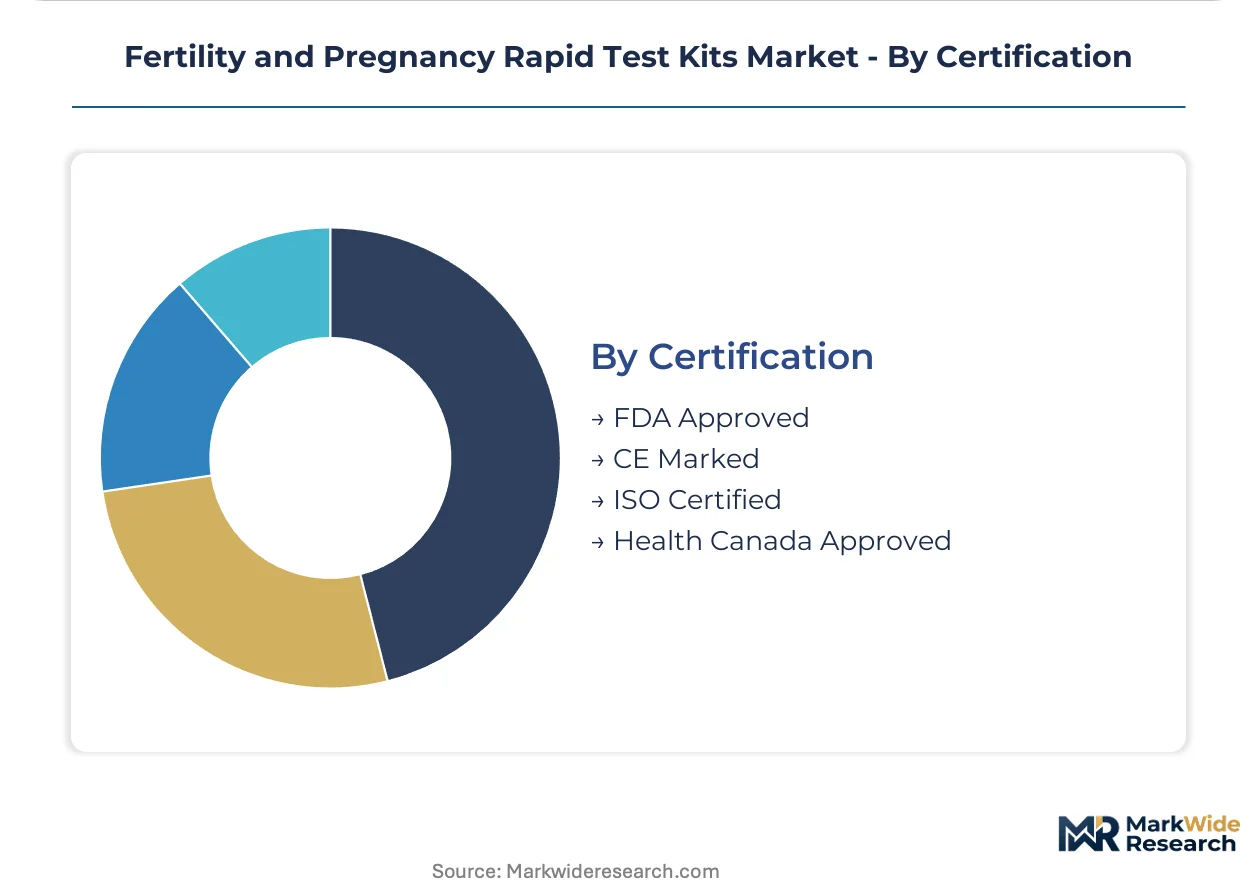
- FDA Approved:Premarket notification under 21 CFR 862.1155 enables over-the-counter marketing in the United States with clinical evidence requirements focused on sensitivity and specificity benchmarks.
- CE Marked:EU Medical Device Regulation conformity assessment reclassifies self-test devices under stricter notified body oversight, extending documentation burdens for European access.
- Health Canada Approved:Parallel review alignment with FDA pathways streamlines North American registration sequencing for manufacturers targeting both markets.
- ISO Certified:Quality management system certification supports private-label manufacturing relationships and tenders in markets without mandatory national approval requirements.
CE Marked certification holds the largest share; FDA approval is expanding most quickly as manufacturers prioritize the United States market for initial commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Self-monitoring consumers concentrate in high-income markets with dense pharmacy retail networks and established direct-to-consumer infrastructure. Regulatory pathway efficiency and reimbursement gaps for clinical fertility services shape geographic expansion sequencing for kit manufacturers.
United States
Retail pharmacy penetration and subscription-based fertility programs drive volume concentration among smartphone-enabled home users. FDA premarket notification under 21 CFR 862.1155 enables faster commercial entry than prescription routes, compressing time-to-revenue. The Boston-Cambridge corridor hosts telehealth platforms piloting quantitative hCG readers for remote patient management between clinic visits.
Germany
Fertility clinics and telehealth platforms pilot quantitative blood-based formats for longitudinal hormone monitoring with higher analytical sensitivity. EU MDR conformity assessment reclassifies self-test devices under stricter notified body oversight, extending certification timelines by twelve to eighteen months. The Rhine-Ruhr industrial basin concentrates private-label manufacturing partnerships as smaller manufacturers exit or seek certificate-holder alliances.
United Kingdom
Digital-native brands capture fastest-growing share through subscription models bundling test kits with algorithmic cycle prediction and telehealth access. MHRA alignment with FDA clearance pathways streamlines multinational registration sequencing for North American market entry. London anchors direct-to-consumer channel development as insurance reimbursement gaps for fertility services accelerate home-based diagnostic adoption.
Japan
Perimenopause tracking applications for follicle-stimulating hormone detection show strongest uptake among aging demographics seeking hormone monitoring without clinic visits. PMDA clinical evidence requirements parallel FDA benchmarks, enabling streamlined registration for manufacturers with existing United States clearance. The Osaka-Kobe industrial zone concentrates electrochemical biosensor development for saliva-based estrogen and progesterone metabolite measurement.
Australia
Fertility networks integrate connected readers into remote patient management protocols between in-person specialist visits. TGA clinical evidence requirements align with FDA and Health Canada pathways, reducing duplicative documentation for multinational manufacturers. Sydney and Melbourne anchor telehealth platform consolidation as group purchasing organizations centralize clinic procurement through specialized medical distributors.
Fertility and Pregnancy Rapid Test Kits Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers defined by manufacturing scale and regulatory certificate breadth. The vendor base separates into three strategic archetypes: multinational diagnostics conglomerates with connected reader ecosystems, European private-label manufacturers with notified body certificate depth, and North American retail pharmacy placement specialists with streamlined urine-based formats. Dominant competitive moves include private-label partnerships to bypass MDR certification bottlenecks and subscription-based bundling to capture recurring revenue from algorithmic health platforms.
Among multinational diagnostics conglomerates, Abbott Laboratories and QuidelOrtho Corporation represent the connected-technology archetype with premium positioning in multi-parameter fertility tracking. Swiss Precision Diagnostics GmbH exemplifies the European private-label manufacturing tier with scale-driven supply relationships and channel control across continental retail networks. Church & Dwight Co., Inc. anchors the North American retail pharmacy placement specialist tier with streamlined formats optimized for brick-and-mortar shelf economics. These three occupy positions that reflect divergent bets on digital integration versus manufacturing scale versus distribution density as the primary competitive moat.
| Leading Market Players |
|---|
| QuidelOrtho Corporation |
| Prestige Consumer Healthcare Inc. |
| Abbott Laboratories |
| bioMérieux SA |
| Geratherm Medical AG |
| Procter & Gamble Co |
| Swiss Precision Diagnostics GmbH |
| Cardinal Health Inc |
| Church & Dwight Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Antibody raw material concentration among specialized biologics suppliers in the United States and Western Europe determines both the spread between premium quantitative readers and economy strip formats and the geographic clustering of contract manufacturing capacity. Manufacturers pass batch variability costs through to buyers while qualifying alternative suppliers extends lead times for mid-tier producers.
Pricing Analysis
Cost-plus contracts with monoclonal antibody suppliers index to biologics manufacturing benchmarks, creating pricing stratification across premium connected readers, standard lateral flow strips, and economy private-label formats. FDA and CE Mark certification tiers separate pricing bands by approximately one standard deviation in unit economics. Cost compression in the economy tier intensifies as Chinese contract manufacturers enter European private-label supply. Home users through subscription channels show lowest price sensitivity; retail pharmacy bulk purchasers exhibit highest.
Supply Chain Analysis
Contract manufacturing concentrates with Swiss Precision Diagnostics GmbH in Switzerland, Geratherm Medical AG in Germany, and select Chinese EMS providers serving private-label demand. Nitrocellulose membrane production draws from the United States and Japan; monoclonal antibody supply rests on bioreactor capacity in Massachusetts and Bavaria. Single-source vulnerability in antibody qualification creates bottlenecks during batch changeover. Distribution runs through medical distributors with cold-chain capabilities for temperature-sensitive reagent shipments to fertility clinics and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fertility and pregnancy rapid test kits market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. Certificate holder status under EU MDR and FDA 510(k) clearance pathways erects structural barriers that protect incumbent returns.
For Market Incumbents: Build regulatory entrenchment through parallel FDA-Health Canada registration sequencing to compress multinational time-to-revenue. Deepen backward integration into nitrocellulose membrane casting to insulate margin from antibody supplier concentration. Defend against digital-only fertility apps by bundling connected readers with telehealth consultation credits that algorithmic competitors cannot replicate. For New Entrants and Emerging Players: Establish a beachhead in perimenopause FSH tracking for Japanese and Western European aging demographics where incumbent coverage remains thin. Target saliva-based electrochemical biosensors for wellness retail channels in Germany and the United Kingdom. Pursue white-label partnerships with established CE Mark certificate holders to bypass MDR conformity assessment bottlenecks while building proprietary clinical evidence. For Investors and Strategic Acquirers: European private-label manufacturers with notified body certificate depth and scale-driven supply relationships represent the most defensible acquisition profile. Long-term viability hinges on recurring revenue capture from app-integrated fertility ecosystems rather than disposable test economics. Monitor FDA software-as-medical-device rulings as the critical inflection signal that could reclassify connected reader margins.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | EU MDR reclassification under stricter notified body oversight compresses competitive field to certificate holders. |
| Subscription Model Launch | Direct-to-consumer bundling with algorithmic cycle prediction captures recurring revenue from telehealth platforms. |
| Connected Reader Firmware Development | Bluetooth-enabled quantitative hCG measurement collapses clinical-grade and over-the-counter performance tiers. |
| Hospital System Partnership | Emergency department procurement contracts for quantitative readers secure volume through GPO consolidation. |
| Perimenopause Application Extension | FSH detection for aging demographics in Japan and Western Europe opens underdeveloped hormone monitoring segment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fertility clinic directors, biomedical engineers at connected reader manufacturers, regulatory affairs leads navigating FDA 510(k) and EU MDR pathways, and procurement managers at hospital group purchasing organizations. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, Health Canada device licensing records, and GPO contract award disclosures. Bottom-up test kit volume estimates triangulated against top-down market sizing from customs trade data and distributor shipment records.
Calibration against historical sensitivity benchmarks and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format (urine strip, blood quantitative, saliva biosensor, multi-parameter), end-user setting (home, hospital, clinic, pharmacy), distribution channel (subscription, retail, medical distributor), and certification tier (FDA approved, CE Marked, Health Canada cleared, ISO certified). CAGRs were derived from regression analysis of adoption curve penetration rates and smartphone-enabled self-monitoring behavioral indices.
Stress conditions across antibody supplier concentration, EU MDR notified body capacity constraints, and digital-only fertility app substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway efficiency and telehealth reimbursement gaps. Quarterly review of FDA software-as-medical-device guidance evolution and EU MDR certificate holder exit rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
India GMP Testing Service Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Self-Testing Market
Testing Services
Allergy Skin Test Market
Testing Services
Blood Borne Testing Market
Testing Services
IVD Quality Control Market
Testing Services
Fungal Testing Kits Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Fertility Testing Market
Testing Services
STD Testing Devices Market
Testing Services
Global Virology Testing Market
Testing Services
Candida Vaginitis Rapid Testing Market
Testing Services
Ferritin Testing Market