
 Minimal Residual Disease Testing Market | 2026-2036
Minimal Residual Disease Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Minimal Residual Disease Testing Market Intelligence
Buyer concentration among large hospital networks and academic medical centers is hardening as institutions consolidate oncology testing under single molecular pathology platforms. F. Hoffmann-La Roche Ltd leverages its installed base of sequencing and PCR instrumentation to sustain recurring consumable revenue across major cancer centers. Adaptive Biotechnologies anchors its position through clonoSEQ assay exclusivity in lymphoid MRD monitoring, while Guardant Health competes via circulating tumor DNA approaches in solid tumor surveillance.
Minimal residual disease testing encompasses highly sensitive molecular and immunophenotypic methods that detect malignant cells persisting below the threshold of conventional morphologic assessment, typically achieving sensitivities of one tumor cell per 100,000 to one million normal cells. Its primary purpose lies in guiding treatment escalation or de-escalation decisions, predicting relapse risk, and stratifying patients for clinical trial enrollment in hematologic and solid malignancies. NGS-based platforms command premium positioning due to their clonal resolution and expanding reimbursement, while flow cytometry retains cost advantages in acute leukemia monitoring where rapid turnaround matters. Digital PCR occupies a growing niche for targeted mutation tracking with simplified workflow requirements.
FDA oversight of companion diagnostic claims shapes product development priorities, while EMA's evolving MDR framework and Health Canada's regulatory alignment with ICH guidelines influence market access timelines across North America and Europe. The EU AI Act introduces new conformity obligations for algorithm-driven variant interpretation pipelines, adding compliance layers for NGS-based MRD software. Stakeholders must weigh platform standardization against assay flexibility as payer evidence requirements tighten for ctDNA-based surveillance indications.
Market Dynamics
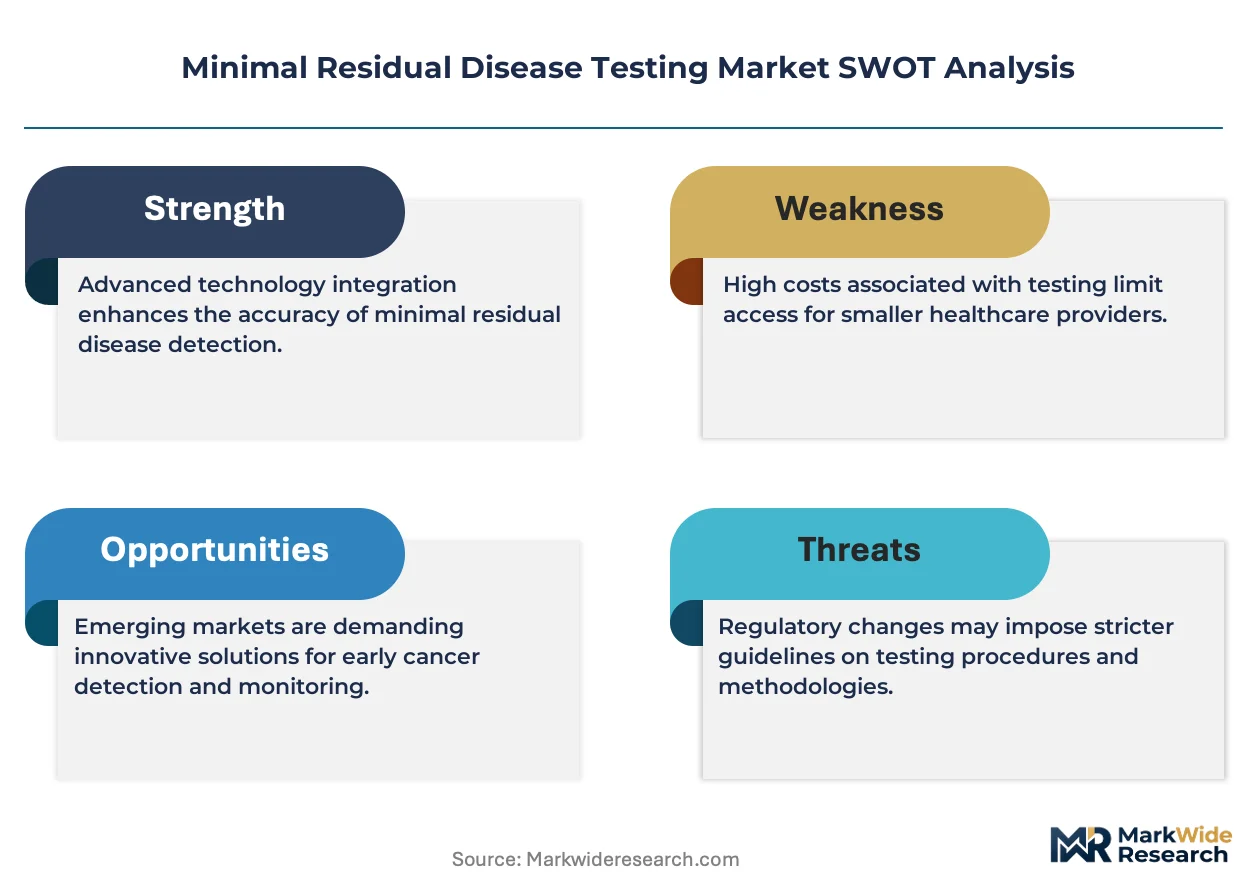
Centralization of oncology testing portfolios within academic medical centers and large hospital networks is compressing vendor relationships toward single-platform contracts, privileging integrated NGS workflows over fragmented point solutions.
Growth Catalysts
- EMA MDR Framework Expansion:The evolving Medical Device Regulation in Europe accelerates clinical validation requirements for MRD assays, driving investment in standardized NGS platforms that satisfy pre-market approval pathways.
- ctDNA Payer Coverage Broadening:United States commercial insurers and Medicare Advantage plans are expanding reimbursement policies for circulating tumor DNA surveillance in solid tumors, reducing out-of-pocket barriers for longitudinal monitoring.
- Lymphoid MRD Standardization:Consensus guidelines from the European Society for Medical Oncology and National Comprehensive Cancer Network now recommend molecular MRD assessment as a response criterion in multiple myeloma and acute lymphoblastic leukemia clinical trials.
Market Restraints
- Reagent Supply Concentration:Specialty enzymes and indexed adapter oligonucleotides for NGS-based MRD workflows depend on a limited supplier base concentrated in California and Massachusetts, creating vulnerability to allocation disruptions.
- Technical Sensitivity Floor:Current droplet digital PCR platforms face inherent detection limits around 0.01% variant allele frequency in low-input cfDNA samples, constraining utility in early-stage solid tumor surveillance.
- FDA Companion Diagnostic Friction:The requirement for co-development with therapeutic sponsors extends regulatory timelines for novel MRD indications, delaying commercial launch by 18-36 months compared to laboratory-developed test pathways.
Strategic Opportunities
- Japan PMDA Streamlined Review:The Pharmaceuticals and Medical Devices Agency's Sakigake designation system offers accelerated assessment for innovative MRD technologies, creating first-mover advantage for NGS platforms with demonstrated analytical validity.
- Artificial Intelligence Variant Interpretation:Machine learning algorithms trained on clonal evolution patterns are converging with cloud-based bioinformatics pipelines to automate MRD positivity calls, reducing manual review burden in high-volume reference laboratories.
- Community Oncology Network Penetration:Underpenetrated outpatient infusion centers and regional cancer clinics represent whitespace for decentralized MRD testing through hub-and-spoke sample logistics models.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of computational biologists with dual expertise in immunogenetics and clinical regulatory requirements constrains assay development velocity at mid-scale diagnostic firms.
- Legacy LIMS Integration Complexity:Enterprise laboratory information management systems at established cancer centers require custom API development to ingest NGS MRD data streams, prolonging implementation timelines.
- Inter-laboratory Harmonization Delays:Absence of standardized reference materials for ultra-low frequency variant detection complicates cross-site analytical validation for multi-center clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimal Residual Disease Testing Market |
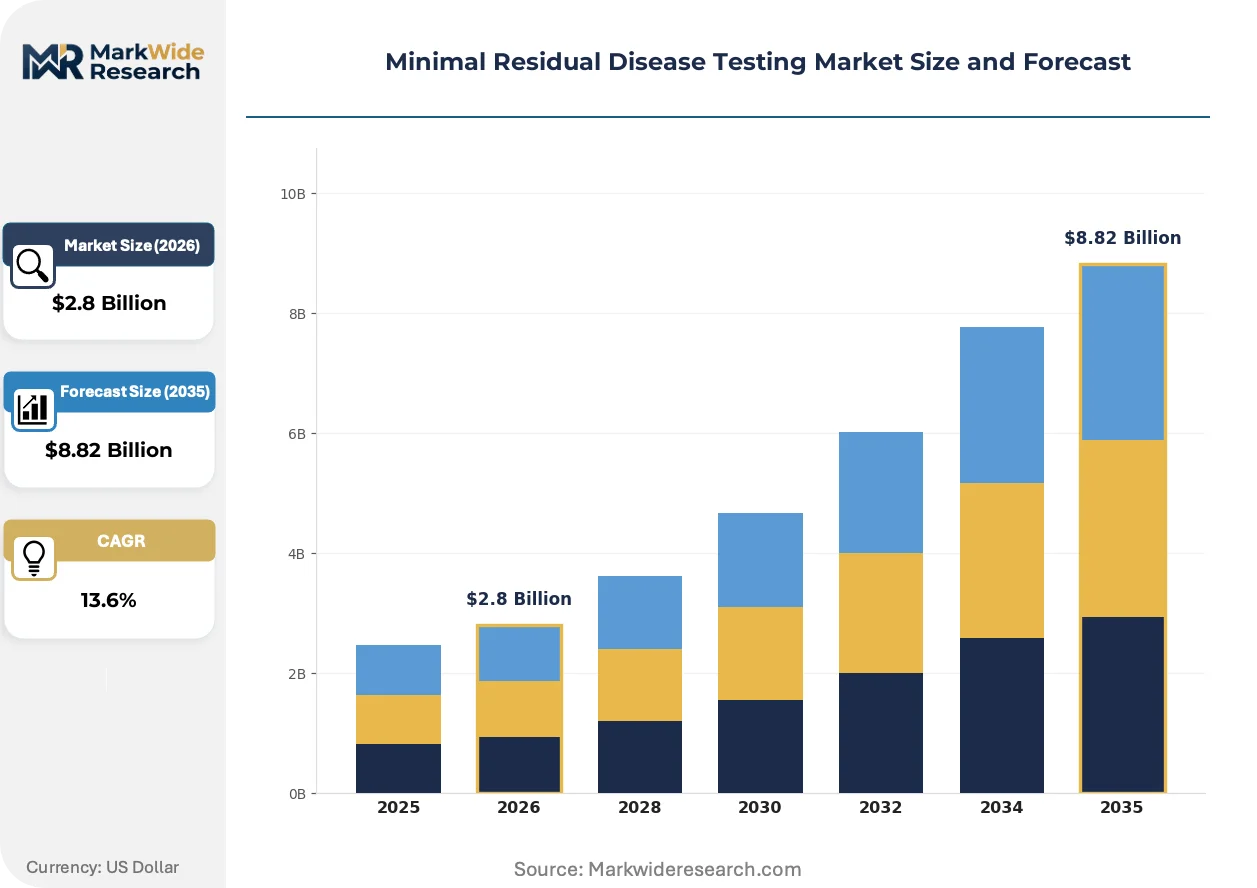
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, NGS, Flow Cytometry, Digital PCR Technology: Fluorescence, Bioluminescence, Microarray, Enzyme-Linked Immunosorbent Assay Application: Hematologic Malignancies, Solid Tumors, Autoimmune Disorders, Transplant Monitoring End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies |
| Companies Covered | F. Hoffmann-La Roche Ltd, Labcorp Inc, Guardant Health, Sysmex Corporation, Adaptive Biotechnologies, Natera, Inc., QIAGEN, Exact Sciences Corporation, NeoGenomics Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimal Residual Disease Testing Market Strategic Shifts & Innovations
Next-generation sequencing platforms are actively displacing incumbent methodologies across both hematologic and solid tumor MRD applications, driven by superior clonal resolution and expanding regulatory clearances for companion diagnostic claims.
Error-corrected NGS library preparation methods incorporating unique molecular identifiers are consolidating market share in high-sensitivity MRD detection. Academic medical centers in Boston, Heidelberg, and Tokyo are standardizing on these workflows for lymphoid malignancy monitoring. The technology is consolidating vendor relationships by bundling sequencing instruments, consumables, and bioinformatics into multi-year enterprise agreements that lock out competing flow cytometry and digital PCR suppliers.
The EU AI Act introduces conformity obligations for algorithm-driven variant interpretation pipelines used in NGS-based MRD software. Manufacturers must now document training data provenance and establish human oversight protocols for automated positivity calls. European reference laboratories are responding by segregating EU-deployed analysis modules from global codebases to satisfy jurisdiction-specific audit requirements.
Hospital procurement committees are consolidating molecular pathology vendor panels under sole-source or dual-source arrangements, displacing the prior model of best-of-breed instrument selection. Integrated platform contracts now span sequencing, liquid handling automation, and enterprise bioinformatics. This concentration is most visible in United States National Cancer Institute-designated comprehensive cancer centers, where total cost-of-ownership analyses favor consolidated supplier relationships over point solution optimization.
Minimal Residual Disease Testing Market Segmentation
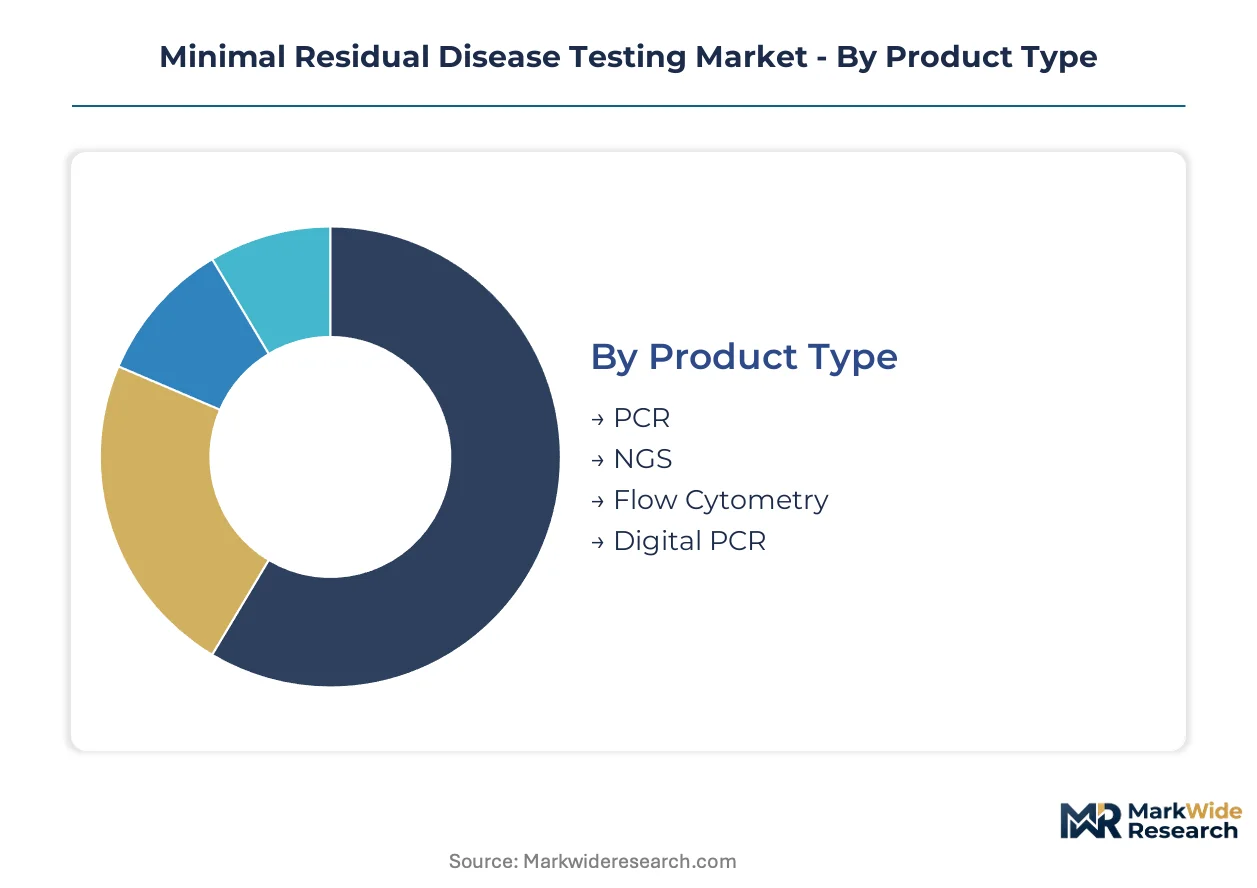
Technology selection in MRD testing directly determines sensitivity thresholds, turnaround times, and reimbursement eligibility. Platform choices cascade through laboratory infrastructure decisions, bioinformatics requirements, and clinical utility claims.
Product Type:
NGS platforms command premium positioning against higher-volume PCR alternatives, with flow cytometry defending cost-sensitive acute leukemia segments.
- NGS:Clonotype-resolved detection achieves sensitivities below 0.001% variant allele frequency through unique molecular identifier error correction. United States academic medical centers concentrate demand here, driven by EMA MDR pre-market approval pathways that favor standardized NGS workflows over laboratory-developed alternatives.
- PCR:Quantitative amplification methods retain dominance in community hospital settings where rapid turnaround and lower capital burden outweigh clonal resolution requirements. Germany's hospital procurement consolidation favors established PCR instrumentation for routine BCR-ABL monitoring in chronic myeloid leukemia.
- Flow Cytometry:Multiparameter immunophenotyping offers same-day results in acute leukemia MRD assessment.
- Digital PCR:Partitioned amplification enables absolute quantification without standard curves.
Today's leader: NGS. Tomorrow's challenger: Digital PCR.
Technology:
Detection modality selection hinges on throughput requirements and automation compatibility rather than raw sensitivity alone.
- Fluorescence:Fluorophore-conjugated probe detection underpins quantitative PCR and flow cytometry workflows across installed instrument bases. Japan's PMDA Sakigake designation system accelerates fluorescence-based assay approvals, concentrating demand in Tokyo-Osaka reference laboratory corridors.
- Bioluminescence:Luciferase reporter systems enable ultra-sensitive detection in low-input sample scenarios.
- Microarray:Solid-phase hybridization supports high-plex mutation profiling.
- Enzyme-Linked Immunosorbent Assay:Colorimetric detection retains niche applications in research settings.
Fluorescence anchors current volume. Bioluminescence gains share in sensitivity-critical applications.
Application:
Hematologic indications retain reimbursement clarity against emerging solid tumor surveillance categories.
- Hematologic Malignancies:Lymphoid and myeloid neoplasm monitoring commands established CPT codes and NCCN guideline inclusion. United States commercial payers and Medicare Advantage plans now cover longitudinal ctDNA surveillance, reducing patient cost barriers.
- Solid Tumors:Circulating tumor DNA MRD detection in colorectal, lung, and breast cancer represents the steepest expansion trajectory. ESMO consensus guidelines increasingly incorporate molecular response criteria, though FDA companion diagnostic co-development requirements extend regulatory timelines.
- Autoimmune Disorders:Measurable residual autoreactive cell tracking remains investigational.
- Transplant Monitoring:Chimerism assessment quantifies donor versus recipient cell populations.
Hematologic Malignancies defend revenue concentration. Solid Tumors offer the fastest volume expansion.
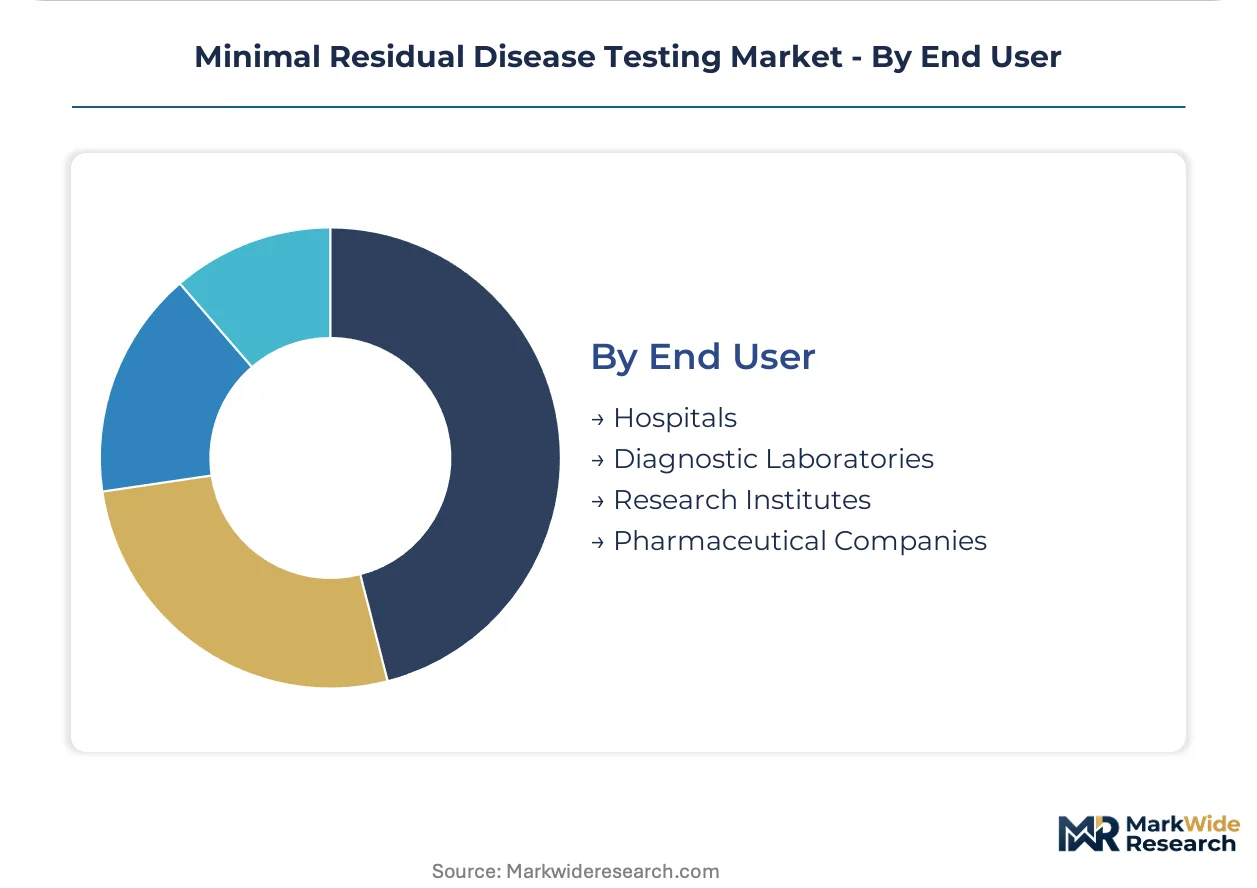
End User:
Customer scale determines platform sophistication, with centralized molecular pathology operations displacing distributed testing.
- Hospitals:NCI-designated comprehensive cancer centers consolidate oncology testing under single-platform enterprise agreements. United States procurement committees now favor total cost-of-ownership analyses that privilege integrated sequencing, automation, and bioinformatics over point solutions.
- Diagnostic Laboratories:Reference laboratories process high-throughput sample volumes for hospital network clients.
- Research Institutes:Academic centers drive assay innovation and clinical validation studies.
- Pharmaceutical Companies:Biopharma sponsors deploy MRD endpoints in registrational trials.
Hospitals concentrate purchasing power. Diagnostic Laboratories capture outsourcing volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital procurement consolidation favors standardized NGS workflows, while Japan accelerates innovative MRD technologies through regulatory fast-tracks. Demand concentrates where payer coverage for molecular surveillance has achieved clarity.
United States
NCI-designated comprehensive cancer centers in Boston and Houston drive enterprise platform consolidation under single-vendor contracts. FDA companion diagnostic requirements shape product development timelines for novel MRD indications. The Greater Boston corridor anchors clonoSEQ standardization in lymphoid malignancy monitoring.
Germany
Academic medical centers in Heidelberg and Munich centralize oncology testing portfolios toward integrated molecular pathology platforms. EMA MDR framework expansion accelerates clinical validation requirements for standardized NGS workflows. The Rhine-Main cluster concentrates reference laboratory capacity for BCR-ABL monitoring in chronic myeloid leukemia.
Japan
Tokyo-Osaka reference laboratory corridors concentrate demand for fluorescence-based assay approvals under PMDA Sakigake designation. METI industrial policy supports domestic sequencing instrumentation development. The Kanto region anchors first-mover adoption of error-corrected NGS library preparation methods.
United Kingdom
London and Cambridge academic networks drive assay innovation and multi-center clinical validation studies. MHRA alignment with ICH guidelines influences market access timelines for ctDNA-based surveillance. The Oxford-Cambridge arc concentrates biopharma-sponsored MRD endpoint deployment in registrational trials.
Switzerland
Basel and Zurich hospital networks leverage proximity to pharmaceutical R&D for companion diagnostic co-development partnerships. Swissmedic regulatory frameworks emphasize analytical validity documentation for algorithm-driven variant interpretation. The Lake Geneva region concentrates precision oncology platform integration across cantonal health systems.
Minimal Residual Disease Testing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across instrument, consumable, and bioinformatics layers. The market structure tilts toward consolidation as hospital procurement committees favor total cost-of-ownership analyses over point solution optimization. Three archetypes dominate: integrated diagnostics conglomerates with sequencing hardware installed bases, ctDNA-focused liquid biopsy specialists, and clonotype-resolved immune repertoire profiling firms. Competitive moves concentrate on multi-year enterprise agreements locking in consumable revenue and regulatory co-development partnerships with therapeutic sponsors.
Within the integrated diagnostics tier, F. Hoffmann-La Roche Ltd and Sysmex Corporation exemplify conglomerate positioning through sequencing and PCR instrumentation ecosystems. Among pure-play specialists, Adaptive Biotechnologies and Guardant Health occupy complementary positions—one anchored in lymphoid MRD clonotype resolution, the other in solid tumor circulating DNA surveillance. QIAGEN represents the sample-to-insight workflow archetype with automation and bioinformatics bundling.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Labcorp Inc |
| Guardant Health |
| Sysmex Corporation |
| Adaptive Biotechnologies |
| Natera, Inc. |
| QIAGEN |
| Exact Sciences Corporation |
| NeoGenomics Laboratories |
| Others |
Cost & Logistics Intelligence
Platform-performance bifurcation between error-corrected NGS workflows and conventional flow cytometry manifests in divergent pricing power and supply chain configurations across the United States, Germany, and Japan. Premium NGS instrumentation commands enterprise-level contract structures with multi-year consumable commitments, while cost-sensitive acute leukemia monitoring segments retain spot-market reagent purchasing patterns.
Pricing Analysis
Capacity additions in California and Massachusetts are reshaping price floors for specialty enzymes and indexed adapter oligonucleotides. Pricing stratifies across premium, standard, and economy tiers based on analytical sensitivity thresholds and FDA companion diagnostic certification status. Cost compression in flow cytometry reagents is intensifying because hospital procurement committees favor total cost-of-ownership analyses. Community hospital laboratories exhibit highest price sensitivity, while NCI-designated comprehensive cancer centers prioritize performance metrics over unit economics.
Supply Chain Analysis
Freight costs for temperature-controlled oligonucleotide shipments from California and Massachusetts to European and Japanese reference laboratories add material landed cost premiums. Manufacturing concentrates in the United States, Germany, and Japan, with specialty polymerase enzymes drawing from fermentation facilities in the San Francisco Bay Area and Boston corridor. Single-source vulnerability characterizes indexed adapter suppliers, with allocation disruptions posing continuity risk. Distribution runs through authorized distributor networks serving hospital networks and academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Minimal Residual Disease Testing Market functions as a stable compounder, with longitudinal reimbursement expansion for ctDNA-based surveillance providing durable revenue visibility across the analysis window.
For Market Incumbents: Acquire bioinformatics talent pools with dual expertise in immunogenetics and clinical regulatory requirements. Consolidate reagent supply agreements through backward integration into specialty enzyme manufacturing or exclusive long-term offtake contracts with California and Massachusetts suppliers. Digital PCR platform entrants threaten NGS market share in community hospital settings, necessitating defensive bundling of sequencing instrumentation with simplified workflow automation. For New Entrants and Emerging Players: Capture underpenetrated community oncology networks in the United States Midwest and Southern regions through hub-and-spoke sample logistics models. Target decentralized MRD testing whitespace at regional cancer clinics where rapid turnaround requirements favor digital PCR platforms over comprehensive NGS workflows. Partner with existing reference laboratories for analytical validation rather than building captive CLIA capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with ctDNA-focused liquid biopsy specialists possessing FDA companion diagnostic co-development partnerships. Long-term viability hinges on regulatory moat depth and payer coverage breadth rather than technological differentiation alone. Monitor EMA MDR pre-market approval pathway progress as inflection indicator for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA submission timelines for novel MRD indications compress competitive windows for therapeutic sponsors. |
| Error-Corrected NGS Library Preparation Scale-Up | United States academic medical centers in Boston standardize on UMI workflows for lymphoid malignancy monitoring. |
| Cloud-Based Bioinformatics Platform Integration | EU AI Act conformity obligations for algorithm-driven variant interpretation pipelines require segregated codebases. |
| Community Oncology Network Logistics Partnership | Hub-and-spoke sample collection models penetrate regional cancer clinics in underpenetrated United States markets. |
| PMDA Sakigake Designation Pathway Pursuit | Japan's accelerated review system creates first-mover advantage for NGS platforms with demonstrated analytical validity. |
Research Approach
Coverage spans the United States, Germany, Japan, the United Kingdom, and Switzerland, with primary inputs from each regional cluster. The analysis combines structured interviews with molecular pathology laboratory directors, hospital procurement committee members, GPO contracts managers, and regulatory affairs specialists at diagnostic manufacturers with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up instrument installation base modeling and top-down payer coverage expansion analysis were triangulated for cross-verification.
Granularity extends to technology-platform-level demand modeling across NGS, PCR, flow cytometry, and digital PCR modalities, with sensitivity-threshold segmentation and end-user archetype differentiation. CAGRs were derived from installed base expansion curves, consumable pull-through assumptions, and reimbursement policy trajectory analysis. Forecast inputs incorporate EMA MDR implementation pace, PMDA Sakigake designation awards, and United States commercial payer coverage expansion for solid tumor ctDNA surveillance.
Underlying measurement precision varies by segment; hematologic malignancy MRD testing carries tighter precision than emerging solid tumor surveillance categories due to established CPT coding and NCCN guideline inclusion. Forecasts reflect assumptions regarding regulatory approval timelines, payer coverage expansion velocity, and reagent supply continuity. Stakeholders should weight assumptions against their own operating context and regional reimbursement landscapes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Platelet Function Test Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Global Urinalysis Test Market
Testing Services
Global Biological Safety Testing Market
Testing Services
STD Testing Devices Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Ovulation Testing Kits Market
Testing Services
Global Thyroid Function Test Market
Testing Services
Anti-Asthma TDM Assay Kits Market
Testing Services
Medical Device Testing Services Market
Testing Services
Leukocyte Count Testing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market