
 Healthcare Analytical Testing Services Market | 2026-2036
Healthcare Analytical Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Analytical Testing Services Market Intelligence
ISO/IEC 17025 accreditation is unwinding the competitive landscape by filtering out laboratories lacking validated analytical methods. Eurofins Scientific leverages its pan-European laboratory network to sustain high-throughput stability programs. WuXi AppTec anchors its position through integrated biologics testing from cell-line characterization to lot-release. Charles River Laboratories differentiates with specialized virology and adventitious-agent testing for gene-therapy vectors.
Healthcare analytical testing services encompass laboratory-based evaluation of pharmaceutical substances, biologics, and medical materials using chromatographic separation, spectroscopic detection, and mass-spectrometric identification to determine purity, potency, identity, and safety profile. These services primarily assure that drug candidates and commercial products meet predetermined release specifications before human administration or market distribution. Biologics testing commands premium pricing due to complex molecular heterogeneity and stringent host-cell protein clearance thresholds. Mass spectrometry represents the fastest-growing technology segment as high-resolution accurate-mass instruments displace older methods for impurity profiling and peptide mapping. Contract research organizations now absorb the largest volume of outsourced analytical work as virtual biotechs lack captive laboratory infrastructure.
FDA enforces current Good Manufacturing Practice through its Center for Drug Evaluation and Research, mandating that analytical methods demonstrate specificity, linearity, and robustness prior to commercial filing. EMA's ICH Q2(R1) guideline harmonizes validation expectations across European member states, while China's NMPA requires local language method documentation and on-site inspectorate audits for imported drug approvals. Regulatory stringency directly expands demand for third-party validation and method-transfer services as sponsors seek audit-ready documentation packages. Stakeholders must monitor evolving biosimilar analytical comparability guidelines and position their capability investments ahead of anticipated guidance revisions on complex generics and cell therapies.
Market Dynamics
Regulatory convergence around ICH Q2(R1) validation standards is compressing method-transfer timelines while simultaneously elevating the technical barrier for laboratory entry, forcing consolidation among mid-tier analytical service providers.
Growth Catalysts
- Biologics Pipeline Expansion:Complex monoclonal antibodies and gene-therapy vectors require specialized host-cell protein clearance assays that captive pharma laboratories cannot scale internally.
- FDA Biosimilar Comparability Guidance:The 2025 draft guidance on analytical similarity assessments mandates orthogonal characterization methods, expanding outsourcing to third-party validation specialists.
- Mass Spectrometry Platform Upgrades:High-resolution accurate-mass instruments enable peptide mapping and impurity profiling at sensitivities unattainable with legacy chromatographic systems.
Market Restraints
- Reference Standard Supply Concentration:Certified impurity reference materials originate from fewer than twelve qualified suppliers globally, creating single-source vulnerability for validation studies.
- Skilled Analyst Scarcity:Mass spectrometry method development requires hybrid chemist-engineer profiles that university programs produce at insufficient volumes.
- Capital Equipment Intensity:Orbitrap and Q-TOF platforms demand seven-figure capital commitments with five-year depreciation cycles that strain independent laboratory balance sheets.
Strategic Opportunities
- Cell Therapy Analytical Gap:CAR-T potency assays and vector copy-number determination lack standardized methods, creating first-mover advantage for laboratories developing platform approaches.
- China NMPA Localization Requirements:Mandatory on-site inspectorate audits for imported drug approvals position domestic Chinese laboratories for method-transfer partnerships with Western sponsors.
- Real-Time Release Testing:Process analytical technology integration enables continuous verification, shifting revenue from batch-release testing to embedded process development contracts.
Industry Challenges
- ISO/IEC 17025 Accreditation Timelines:Full scope accreditation for biologics methods requires eighteen to twenty-four months of proficiency testing and on-site assessments, delaying market entry.
- Legacy LIMS Integration:Sponsor quality systems built on decade-old laboratory information management platforms resist API connectivity with modern cloud-based analytical data systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Analytical Testing Services Market |
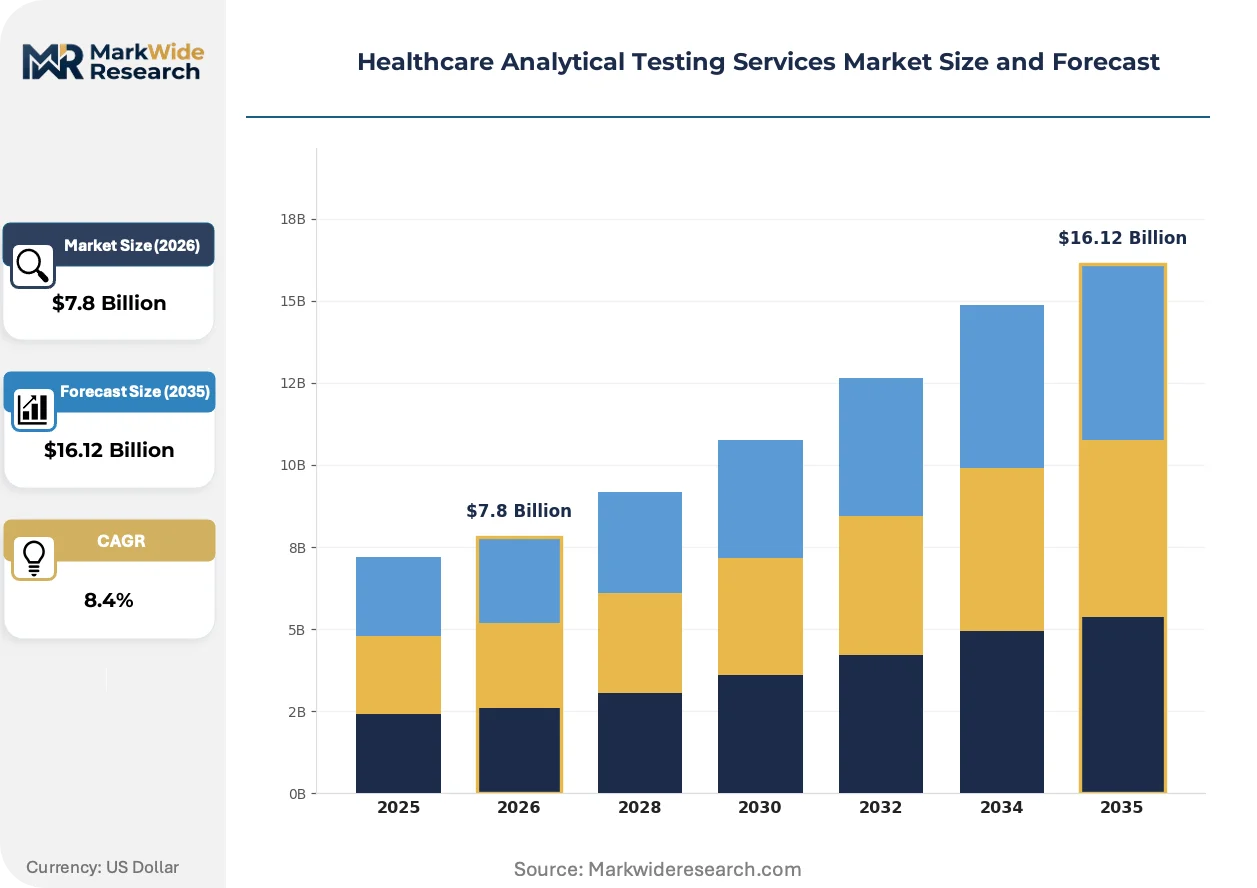
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Biologics Testing, Stability Testing, Microbiology Testing, Chemical Analysis End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Hospitals Technology: Chromatography, Spectroscopy, Mass Spectrometry, Electrophoresis Application: Quality Control, Drug Development, Regulatory Compliance, Research Studies |
| Companies Covered | Labcorp Drug Development, WuXi AppTec, Eurofins Scientific, Pace Analytical Services, Intertek Group, SGS SA, Thermo Fisher Scientific, ICON plc, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Analytical Testing Services Market Strategic Shifts & Innovations
Artificial intelligence is penetrating analytical method development, compressing design-of-experiment cycles while simultaneously raising questions about algorithmic validation under GxP frameworks.
High-resolution mass spectrometry is bifurcating the competitive landscape. Orbitrap platforms deliver sub-ppm mass accuracy for intact protein analysis and glycan profiling. Large pharmaceutical sponsors now mandate these capabilities for biosimilar comparability packages. Mid-tier contract laboratories without accurate-mass instrumentation face exclusion from premium biologics programs.
EMA's revised ICH Q5A(R2) guideline on viral safety evaluation expands next-generation sequencing requirements for adventitious-agent detection. Cell-therapy and gene-therapy manufacturers must now submit NGS-based contamination assessments alongside traditional in vitro and in vivo methods. European contract research organizations are accelerating platform investments to capture this expanded testing mandate.
Virtual biotechnology companies now represent the fastest-growing buyer segment for integrated analytical packages. These asset-light sponsors outsource entire development-phase testing programs rather than building captive capabilities. The United States concentrates this demand, with Boston and San Diego clusters driving consolidated contracts spanning cell-line characterization through commercial lot-release.
Healthcare Analytical Testing Services Market Segmentation
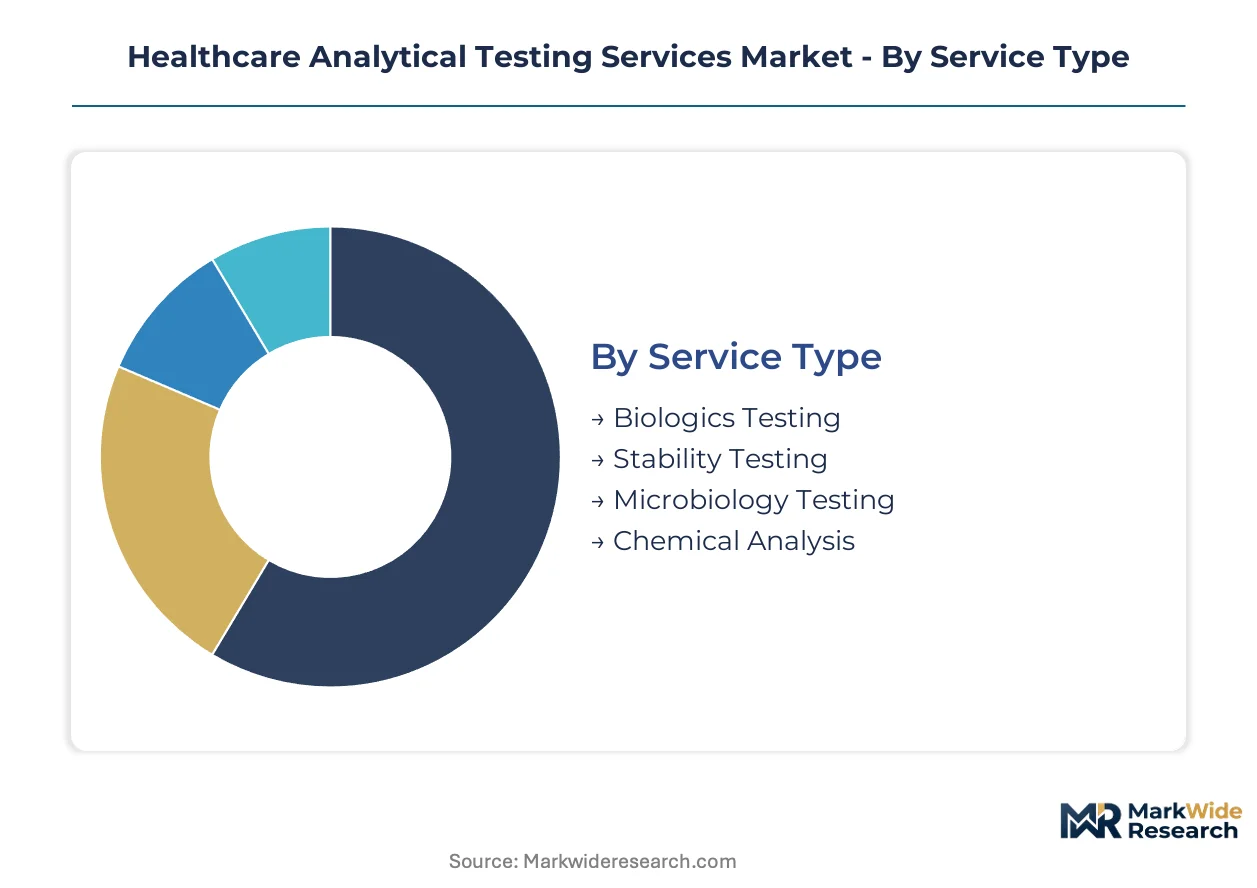
Segmentation in healthcare analytical testing reveals how specialized capabilities map to distinct buyer workflows. Service type determines capital intensity and regulatory burden. End-user structure shows where outsourcing pressure concentrates.
Service Type:
Channel flow varies sharply across service categories, with biologics and stability testing dominating direct sponsor relationships while chemical analysis routes through procurement aggregators.
- Biologics Testing:Host-cell protein clearance assays and glycan profiling for monoclonal antibodies and gene-therapy vectors. United States sponsors drive premium demand for orthogonal characterization packages supporting FDA biosimilar filings.
- Stability Testing:Long-term and accelerated storage studies establishing shelf-life specifications under ICH Q1A(R2) guidelines. Pharmaceutical companies in Germany outsource high-throughput programs to pan-European laboratory networks.
- Microbiology Testing:Sterility assurance and endotoxin detection for parenteral products.
- Chemical Analysis:Impurity profiling and elemental identification for small-molecule APIs.
By volume, chemical analysis leads. By growth pace, biologics testing is climbing the fastest.
End User:
Cost tier segmentation separates integrated buyers seeking full development-phase packages from transactional purchasers running discrete lot-release tests.
- Pharmaceutical Companies:Large sponsors with captive laboratories still outsource overflow capacity and specialized assays. Boston and San Diego clusters drive consolidated contracts spanning cell-line characterization through commercial release.
- Biotechnology Firms:Virtual biotechs without infrastructure absorb the fastest-growing outsourcing volume. These asset-light sponsors purchase integrated analytical packages rather than building internal capabilities.
- Contract Research Organizations:Mid-tier CROs subcontract reference standard-limited assays to accredited specialists.
- Hospitals:Clinical trial sites and academic medical centers demand point-of-care compatibility testing.
Pharmaceutical companies anchor revenue concentration. Biotechnology firms are expanding most quickly.
Technology:
Application intensity separates high-resolution platforms commanding premium pricing from legacy methods facing displacement.
- Mass Spectrometry:High-resolution accurate-mass instruments enable peptide mapping and impurity profiling at sensitivities unattainable with chromatographic systems. Orbitrap and Q-TOF platforms now dominate biologics comparability studies.
- Chromatography:HPLC and UHPLC systems remain workhorses for routine purity assessment and method transfer validation across sponsor quality systems.
- Spectroscopy:UV-Vis and FTIR techniques support rapid identity confirmation and raw material qualification.
- Electrophoresis:Capillary and gel-based separation methods persist for protein molecular weight determination.
Chromatography handles the highest test volumes. Mass spectrometry shows the steepest expansion trajectory.
Application:
Maturity differentiation separates standardized quality control workflows from exploratory research studies lacking regulatory precedent.
- Quality Control:Batch-release testing and in-process verification against predetermined specifications. FDA enforces current Good Manufacturing Practice through method validation requirements prior to commercial filing.
- Drug Development:Characterization studies supporting IND-enabling toxicology batches and formulation optimization. China's NMPA requires local language documentation for imported drug approvals.
- Regulatory Compliance:Method transfer and validation documentation packages for audit-ready submissions.
- Research Studies:Investigational assays without immediate commercial pathway.
Quality control commands the largest revenue share. Drug development is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors European distribution networks for temperature-sensitive reference standards and biologics samples. This logistics backbone underwrites the region's analytical testing density alongside direct air links between Boston Logan and Frankfurt am Main cargo terminals.
United States
FDA's Center for Drug Evaluation and Research processes over 4,500 IND applications annually, generating continuous demand for method validation and stability protocols. The 2025 draft biosimilar comparability guidance mandates orthogonal characterization approaches, expanding outsourcing to specialized laboratories. Boston and San Diego biotechnology clusters drive consolidated contracts spanning cell-line characterization through commercial lot-release testing.
Germany
EMA headquarters in Amsterdam coordinates ICH Q2(R1) validation standards that German laboratories implement across pan-European sponsor networks. The country's national pharmaceutical regulator enforces strict method-transfer documentation requirements for imported drug approvals. Frankfurt and Munich host high-throughput stability programs serving mid-sized European pharmaceutical sponsors lacking captive analytical infrastructure.
China
NMPA requires local language method documentation and on-site inspectorate audits for all imported drug approvals, positioning domestic laboratories for Western partnership opportunities. The country's dual carbon goals accelerate green chemistry analytical method adoption for environmental impurity detection. Shanghai and Suzhou biotech parks concentrate demand for integrated biologics testing from IND-enabling toxicology through commercial release.
Switzerland
Swissmedic maintains alignment with EMA guidelines while offering streamlined pathways for innovative biologics characterization methods. The regulator's pragmatic approach to biosimilar analytical comparability attracts sponsor submissions requiring rapid validation timelines. Basel's pharmaceutical corridor anchors specialized host-cell protein clearance and glycan profiling capabilities serving European and North American sponsors.
India
CDSCO's revised Schedule M requirements expand method validation documentation for export-oriented API manufacturers. The country's national pharmaceutical regulator intensifies inspection frequency for facilities supplying regulated markets. Hyderabad and Bangalore contract research organizations absorb overflow stability testing from European sponsors seeking cost-optimized ICH Q1A(R2) compliance programs.
Healthcare Analytical Testing Services Market Key Industry Players
Listed leaders compete with private specialists across accreditation depth and technology platform breadth. The market structure concentrates around three tiers: pan-regional networks with ISO/IEC 17025 scope across multiple geographies, mid-tier laboratories with single-country dominance, and boutique specialists in emerging modalities like cell therapy potency assays. Strategic moves center on M&A-driven geographic expansion and high-resolution mass spectrometry platform licensing to secure biosimilar comparability contracts.
Within the integrated service tier, WuXi AppTec exemplifies vertical integration from cell-line characterization through lot-release, while Eurofins Scientific occupies a position defined by pan-European laboratory density. Charles River Laboratories anchors the specialized virology segment. These three entities represent distinct archetypes: the full-stack Asian contractor, the European network consolidator, and the North American niche specialist.
| Leading Market Players |
|---|
| Labcorp Drug Development |
| WuXi AppTec |
| Eurofins Scientific |
| Pace Analytical Services |
| Intertek Group |
| SGS SA |
| Thermo Fisher Scientific |
| ICON plc |
| Charles River Laboratories |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with accredited laboratories lock in both Orbitrap platform access and multi-year price visibility for sponsors filing biosimilar comparability packages. These arrangements concentrate pricing power with ISO/IEC 17025-certified providers in the United States, Germany, and China while forcing virtual biotechs into premium spot-rate arrangements.
Pricing Analysis
Volume-discount tiering structures separate enterprise sponsors running high-throughput stability programs from virtual biotechs purchasing discrete lot-release tests. Three-tier pricing stratifies across premium orthogonal characterization, standard method validation, and economy impurity screening tiers, with FDA biosimilar filing requirements driving sponsors toward premium tiers regardless of scale. Price differentiation hinges on accreditation depth and mass spectrometry platform generation, with Orbitrap-equipped laboratories commanding substantial premiums over legacy Q-TOF operators. Cost compression in the economy tier is intensifying as mid-tier laboratories without accurate-mass instrumentation compete for overflow chemical analysis work. Virtual biotechnology firms show highest price sensitivity, while large pharmaceutical sponsors prioritize audit-ready documentation over unit cost.
Supply Chain Analysis
Reference standard supply concentration in the United States, Germany, and Switzerland underwrites validation study timelines for biologics manufacturers globally. Certified impurity reference materials and host-cell protein clearance kits draw from fewer than twelve qualified suppliers, creating single-source vulnerability that propagates through sponsor quality systems. Supply chain risk centers on tariff exposure for Chinese-sourced analytical consumables and European-manufactured high-resolution detectors. Distribution runs through cold-chain logistics networks anchored at Rotterdam and Frankfurt, with temperature-controlled air freight connecting Boston and San Diego clusters to European laboratory hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare analytical testing services represent a service-attach opportunity where method development contracts expand faster than capital equipment sales, with recurring validation and stability programs generating predictable revenue streams across development cycles.
For Market Incumbents: Compound accreditation scope across multiple regulatory jurisdictions to defend against emerging platform-technology specialists. Prioritize Orbitrap and next-generation sequencing platform investments ahead of anticipated EMA viral safety guideline revisions. Deepen backward integration into reference standard production to reduce single-source supplier vulnerability. For New Entrants and Emerging Players: Differentiate on cell therapy analytical capabilities where CAR-T potency assays and vector copy-number determination lack standardized methods. Target virtual biotechnology clusters in Boston and San Diego with integrated packages spanning cell-line characterization through commercial release. Pursue NMPA partnership structures to capture method-transfer demand from Western sponsors seeking China market access. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier laboratories with ISO/IEC 17025 accreditation gaps that strategic buyers can close through platform licensing and personnel investment. Long-term viability favors specialists with defensible positions in high-resolution mass spectrometry and viral safety testing. Watch FDA biosimilar comparability guidance finalization as the signal for accelerated outsourcing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Scope Expansion | ISO/IEC 17025 multi-geography coverage unlocks pan-regional sponsor contracts and audit-ready documentation packages. |
| High-Resolution Platform Investment | Orbitrap and Q-TOF instrumentation secures biosimilar comparability work from sponsors requiring orthogonal characterization. |
| Cell Therapy Capability Buildout | CAR-T potency assay development captures first-mover advantage in standardized methods for gene-therapy vectors. |
| China NMPA Partnership Structure | Domestic laboratory alliances enable Western sponsors to satisfy mandatory on-site inspectorate audit requirements. |
| Real-Time Release Testing Integration | Process analytical technology contracts shift revenue from batch-release testing to embedded process development engagements. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and GPO contracts managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up test volume estimates and top-down sponsor spending patterns were triangulated to converge on market sizing.
Segmentation dimensions modeled include service type, end-user structure, technology platform, and application maturity across the projection horizon. Treatment line, dosage form, and regional regulatory cluster variations were incorporated as industry-specific forecast inputs. CAGRs were derived from sponsor pipeline analysis and outsourcing penetration assumptions rather than extrapolated historical trends.
Material uncertainties — regulatory guidance revisions, reference standard supply disruptions, and platform technology substitution — sit outside the modeled envelope. Forecasts reflect assumptions about accreditation timeline stability and sponsor outsourcing preference continuity. Practitioners should keep alternative scenarios live as FDA biosimilar comparability guidance and EMA viral safety requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Global Virology Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Home DNA Testing Market
Testing Services
United States Esoteric Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Platelet Function Testing Market
Testing Services
Blood Sugar Tester Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
At-Home Testing Market
Testing Services
Drug Testing Equipment Market
Testing Services
Dengue Testing Market