
 Global Hot and Cold Therapy Packs Market | 2026-2036
Global Hot and Cold Therapy Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hot and Cold Therapy Packs Market Foresight
The premium medical-grade segment is decoupling from commodity consumer wraps in both pricing and distribution access. 3M leverages its materials science heritage to sustain hospital contracts with reusable thermal systems that withstand autoclave cycles. Cardinal Health anchors its position through direct-to-clinic logistics networks, while Medline Industries differentiates via private-label manufacturing scale across rehabilitation SKUs.
Hot and cold therapy packs are sealed, thermally conductive containers—typically employing gel, clay, or hydrocolloid fillings within polymer or fabric shells—engineered to retain and release thermal energy across specified temperature ranges for therapeutic tissue modulation. Gel packs dominate institutional procurement due to conformability and freeze-thaw durability, while bead packs capture fastest growth in fitness-center channels where microwave-safe portability matters. Application demand concentrates in post-surgery care and arthritis management, where reimbursement codes support recurring purchase patterns.
FDA 510(k) requirements govern medical-device classification in the United States, while the EU MDR and REACH frameworks constrain polymer and additive specifications for European distribution. The ISO 13485 quality management standard shapes supplier qualification thresholds for OEM partnerships. Stakeholders must monitor evolving home-health reimbursement policies and biocompatibility testing costs as these determine which product tiers achieve profitable scale.
Market Dynamics
FDA 510(k) clearance timelines and EU MDR biocompatibility testing costs are bifurcating the vendor base into validated medical-grade suppliers and commodity consumer-wrap manufacturers. This regulatory pressure concentrates procurement authority among hospital systems and rehabilitation chains that demand ISO 13485-certified supply chains.
Growth Catalysts
- Post-operative rehabilitation protocols:Sports medicine clinics in Germany and the United States are tightening procurement standards for reusable thermal packs that withstand repeated autoclave cycles.
- REACH polymer constraints:European distributors now require gel formulation disclosures and additive-free shell materials, accelerating substitution toward validated biocompatible alternatives.
- Home healthcare channel expansion:Aging populations in Japan and Italy self-manage osteoarthritis without clinical supervision, creating recurring purchase patterns through retail pharmacy networks.
Market Restraints
- Propylene glycol price volatility:Primary gel constituent costs fluctuate with petrochemical feedstock markets, compressing margin on mid-tier consumer packs.
- Chinese mold-injection equipment concentration:Polymer shell fabrication relies on tooling sourced from Zhejiang and Guangdong provinces, creating single-source vulnerability.
- Medical-device reimbursement compression:Medicare and commercial payers are narrowing durable medical equipment codes that cover thermal therapy systems.
Strategic Opportunities
- Brazilian outpatient rehabilitation expansion:ANVISA is streamlining Class II medical device registrations, opening private clinic procurement to imported thermal systems.
- Microwave-safe bead pack convergence:Fitness-center channels in Australia are adopting hybrid clay-bead formulations that bridge institutional durability with consumer convenience.
- Direct-to-patient subscription models:Chronic pain management platforms in Canada are bundling thermal therapy packs with telehealth consultations, bypassing traditional distributor markups.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face 14-18 month queues at accredited laboratories, delaying product launches.
- Legacy ERP integration:Hospital procurement systems require EDI connectivity and lot-level traceability that smaller manufacturers lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hot and Cold Therapy Packs Market |
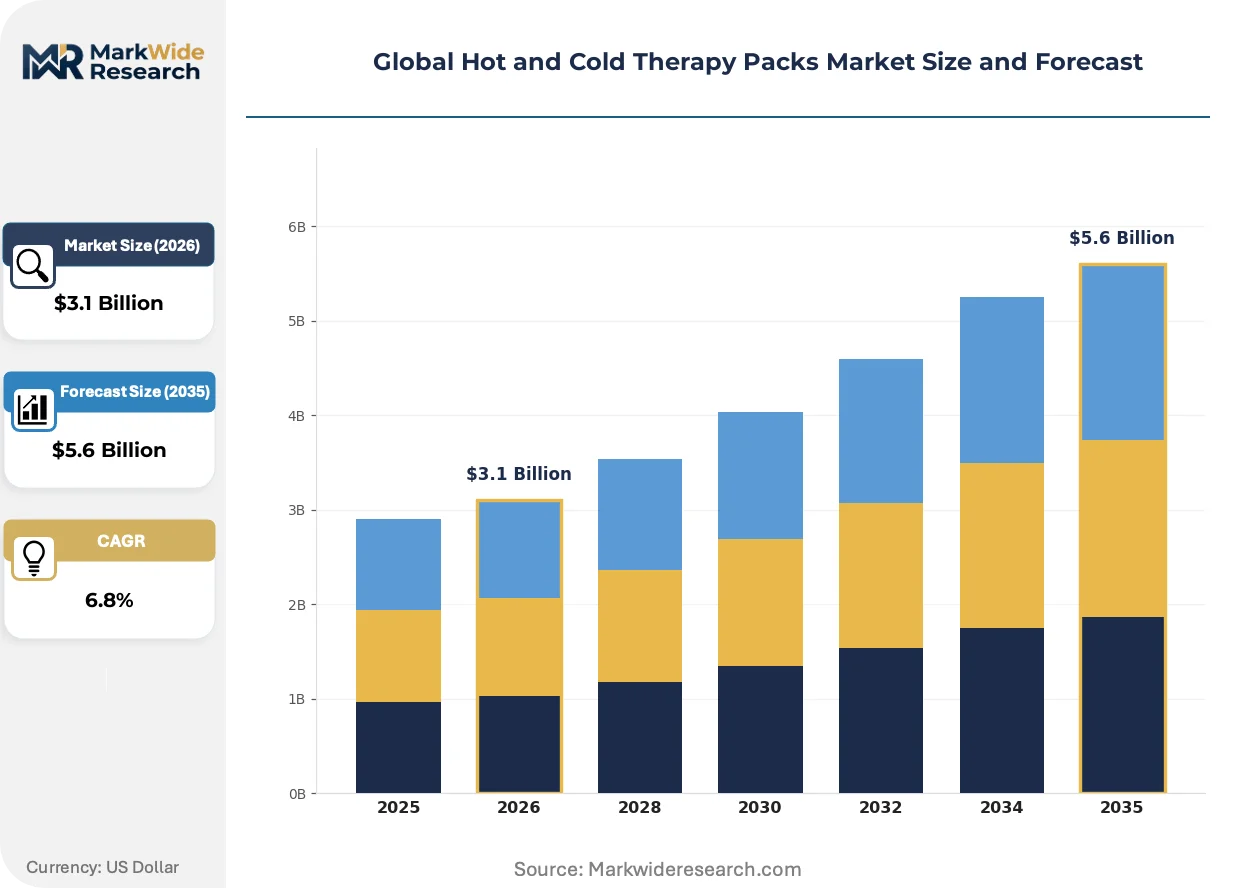
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel Packs, Wheat Bags, Bead Packs, Clay Packs, Crystallized Packs Application: Sports Injury Relief, Post-surgery Care, Chronic Pain, Arthritis Management, Muscle Relaxation End User: Physical Therapists, Fitness Centers, Chiropractic Clinics, Home Users, Rehabilitation Facilities Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Specialty Shops, Wellness Centers |
| Companies Covered | 3M, Cardinal Health, Medline Industries, Breg, Caldera International, Chattanooga International, Bruder Healthcare Company, Kobayashi Pharmaceutical, Core Products International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hot and Cold Therapy Packs Market Shifts & Advancements
Phase-change material formulations and connected temperature-monitoring systems are redefining performance benchmarks across institutional and home-use segments. These innovations compress the gap between clinical-grade efficacy and consumer accessibility.
Microencapsulated paraffin wax composites with tunable melting points are absorbing thermal energy more efficiently than traditional gel matrices. Outpatient surgery centers in South Korea are adopting these packs for same-day discharge protocols. The technology is absorbing market share from hydrocolloid alternatives by delivering consistent 20-minute therapeutic windows without temperature spikes.
EU MDR Article 10 technical documentation requirements now mandate clinical evaluation reports for thermal therapy devices claiming pain management indications. German notified bodies are rejecting legacy 510(k) equivalency arguments for gel formulations lacking new biocompatibility data. Rehabilitation equipment distributors are responding by segregating inventory into MDR-compliant and non-compliant SKUs with divergent pricing.
Chronic pain patients are consolidating purchasing decisions through specialty pharmacy benefit managers rather than retail impulse buys. Hospital-affiliated home health agencies are displacing standalone durable medical equipment suppliers as the primary channel for post-discharge thermal therapy. This concentration is most visible in United States Medicare Advantage networks where vertical integration between payer and provider controls device formularies.
Global Hot and Cold Therapy Packs Market Segmentation
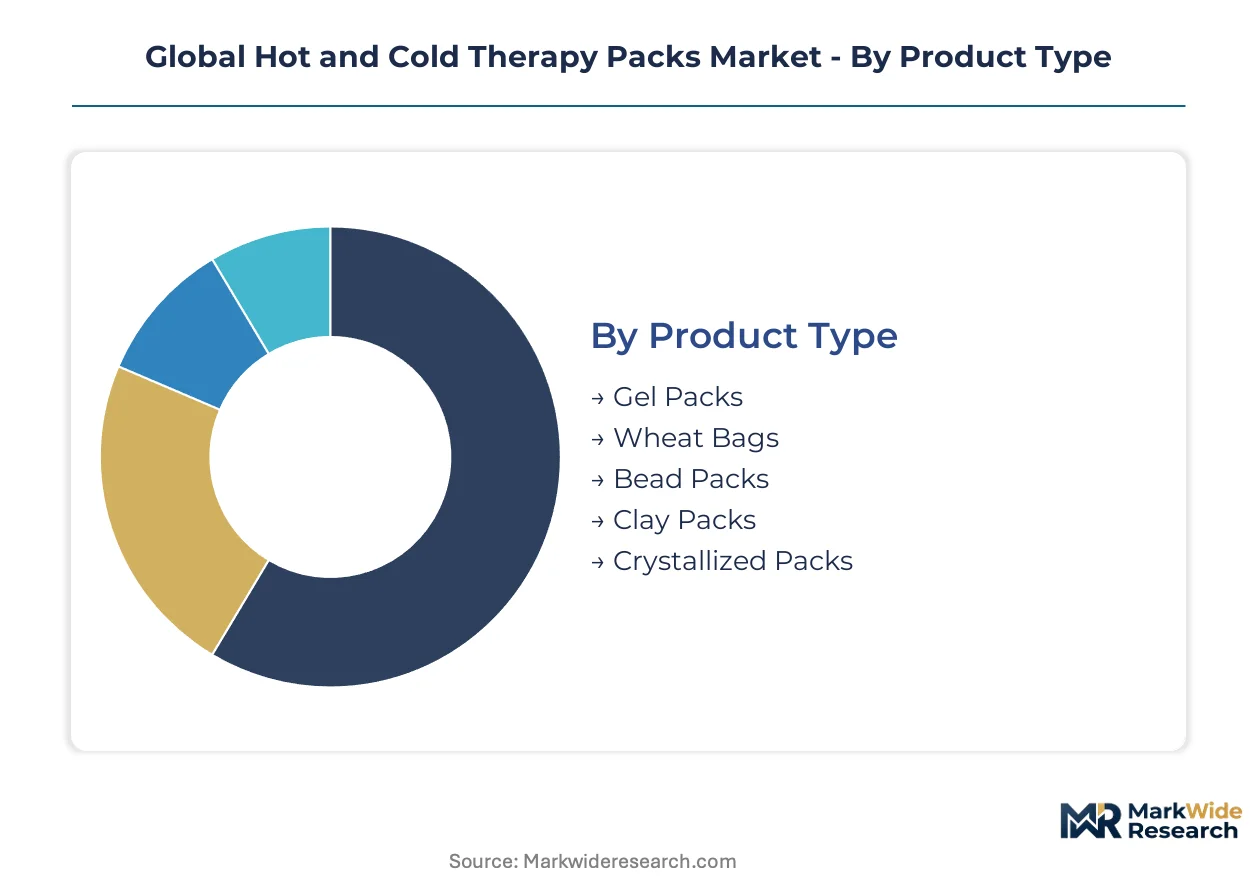
Thermal therapy pack manufacturers configure product portfolios around four distinct axes: material physics determine performance specifications, clinical versus consumer use cases dictate regulatory pathways, procurement authority varies by care setting, and channel economics shape margin structures. Understanding how these dimensions intersect clarifies why gel formulations dominate hospital contracts while bead packs penetrate fitness subscriptions.
Product Type:
Material composition dictates thermal retention curves, conformability to anatomical contours, and durability through sterilization cycles.
- Gel Packs:Polymer matrices suspended in aqueous solutions deliver pliable cold therapy that maintains shape through repeated freeze-thaw cycles. Demand concentrates in German and United States sports medicine clinics where autoclave compatibility is mandatory under tightened post-operative rehabilitation protocols.
- Bead Packs:Silica or ceramic microspheres enable microwave-safe reheating without phase separation, capturing fitness-center channels in Australia where portability between gym and home matters. These formulations bridge institutional durability with consumer convenience, accelerating substitution from traditional gel alternatives.
- Wheat Bags:Natural grain fillings provide moist heat penetration favored in home settings, though organic content limits institutional adoption due to microbial contamination risks.
- Clay Packs:Bentonite-based composites offer extended thermal mass for chronic pain sessions, prevalent in Japanese home healthcare where aging populations self-manage osteoarthritis.
- Crystallized Packs:Sodium acetate phase-change systems activate via metal disc triggers, serving emergency medical kits and outdoor sports where electricity access is unreliable.
Gel packs lead volumes today; bead packs are gaining share fastest.
Application:
Reimbursement coding and clinical evidence requirements fragment demand between acute intervention and chronic maintenance use cases.
- Post-surgery Care:Hospital discharge protocols in South Korea mandate thermal therapy for same-day orthopedic procedures, driving procurement of reusable systems with lot-level traceability. Medicare and commercial payer compression on durable medical equipment codes is narrowing coverage for these systems in United States networks.
- Chronic Pain:Canadian telehealth platforms bundle thermal packs with virtual consultations, bypassing traditional distributor markups through direct-to-patient subscription models. This channel expansion responds to patients consolidating purchasing decisions through specialty pharmacy benefit managers.
- Sports Injury Relief:Acute trauma management in athletic settings prioritizes rapid temperature modulation over durability, favoring disposable instant-cold chemistries.
- Arthritis Management:Italian and Japanese retail pharmacy networks serve aging demographics with over-the-counter heat wraps, creating recurring purchase patterns without clinical supervision.
- Muscle Relaxation:Wellness-oriented consumers in Brazilian private clinics drive demand for aromatherapy-infused thermal systems as ANVISA streamlines Class II medical device registrations.
Post-surgery care commands the largest revenue pool; chronic pain applications are climbing the fastest.
End User:
Procurement sophistication varies from institutional tender processes to individual impulse purchases.
- Rehabilitation Facilities:United States hospital-affiliated home health agencies displace standalone durable medical equipment suppliers through vertical integration with Medicare Advantage networks, controlling device formularies via payer-provider alignment.
- Fitness Centers:Australian gym chains adopt hybrid clay-bead formulations for member amenity programs, prioritizing microwave-safe convenience over clinical-grade specifications.
- Physical Therapists:Outpatient practices in Germany require ISO 13485-certified supply chains with EDI connectivity for procurement system integration.
- Chiropractic Clinics:Smaller practices lack capital for legacy ERP implementation, creating vulnerability to distributor consolidation.
- Home Users:Direct-to-consumer channels in Canada and Italy bypass traditional retail through chronic pain management platforms.
Rehabilitation facilities dominate institutional procurement; fitness centers are expanding most quickly.
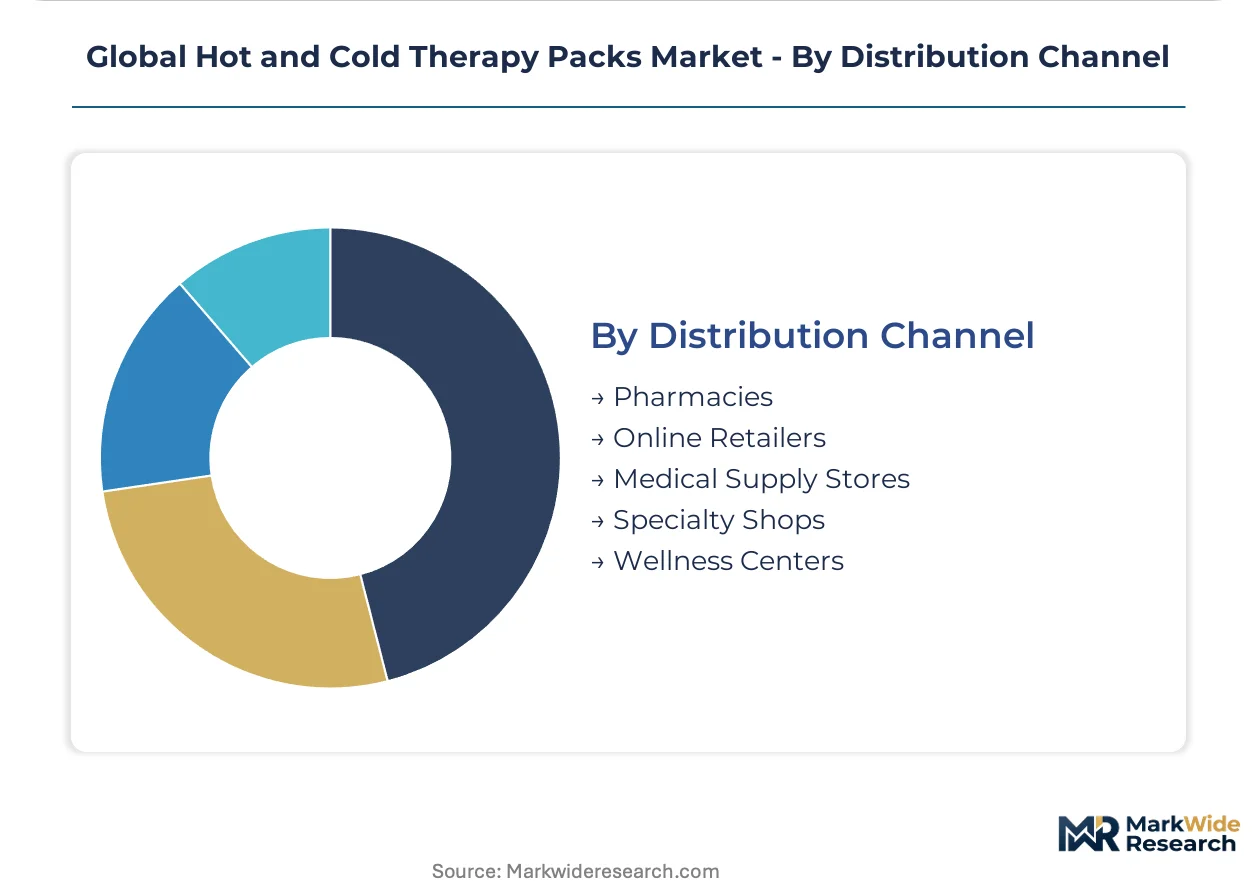
Distribution Channel:
Channel selection determines regulatory exposure, working capital requirements, and customer acquisition economics.
- Online Retailers:Amazon and specialized health platforms capture Canadian subscription bundling and Australian fitness-center procurement, compressing distributor margins through price transparency.
- Pharmacies:Italian and Japanese retail chains serve aging populations with over-the-counter thermal wraps, leveraging pharmacist trust for chronic condition management.
- Medical Supply Stores:United States durable medical equipment suppliers face displacement as hospital-affiliated home health agencies capture post-discharge thermal therapy volumes.
- Specialty Shops:Sports-focused retailers in Germany cater to athletic consumers with performance-oriented thermal systems.
- Wellness Centers:Brazilian private clinics access imported thermal systems through streamlined ANVISA registration pathways.
Pharmacies lead current volume; online retailers are expanding at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer chemists and medical device engineers cluster in Germany, the United States, and Japan, anchoring the industry's validated manufacturing base. These workforce concentrations support ISO 13485-certified production networks that supply hospital systems and rehabilitation chains worldwide.
United States
Sports medicine clinics in Texas and California are tightening procurement standards for reusable thermal packs that withstand autoclave sterilization cycles. FDA 510(k) clearance timelines are bifurcating the vendor base into medical-grade suppliers and commodity manufacturers. Hospital-affiliated home health agencies in the Midwest are displacing standalone durable medical equipment suppliers through vertical integration with Medicare Advantage networks.
Germany
Outpatient rehabilitation facilities in Bavaria and North Rhine-Westphalia demand gel formulations with complete additive disclosures under REACH polymer constraints. EU MDR Article 10 technical documentation requirements are rejecting legacy 510(k) equivalency arguments for thermal therapy devices. German notified bodies in Berlin are mandating new biocompatibility data for pain management indications, segregating inventory into compliant and non-compliant SKUs.
Japan
Aging populations in Tokyo and Osaka self-manage osteoarthritis through retail pharmacy networks, creating recurring purchase patterns without clinical supervision. METI standards for medical device quality management shape supplier qualification thresholds for OEM partnerships. Clay pack manufacturers in the Kansai region are expanding production to serve chronic pain management demand from home healthcare channels.
Australia
Fitness-center chains in New South Wales and Victoria are adopting hybrid clay-bead formulations that bridge institutional durability with consumer microwave-safe convenience. TGA oversight of therapeutic goods classification determines which thermal systems qualify for private health insurance rebates. Australian distributors are capturing procurement from gym amenity programs that prioritize portability between training facilities and residential settings.
Brazil
Private clinic networks in São Paulo and Rio de Janeiro are expanding outpatient rehabilitation capacity as ANVISA streamlines Class II medical device registrations. Wellness-oriented consumers drive demand for aromatherapy-infused thermal systems in Brazilian private healthcare settings. Imported thermal therapy systems are penetrating the market through simplified registration pathways that reduce time-to-market for foreign manufacturers.
Global Hot and Cold Therapy Packs Market Competitive Landscape
Top-tier vendors anchor hospital and rehabilitation chain contracts, while mid-tier manufacturers serve fitness centers and retail pharmacy channels. The vendor base stratifies across three tiers: multinational healthcare conglomerates with materials science heritage, specialized medical device firms with ISO 13485 certification, and regional consumer goods producers. Two strategic archetypes dominate: suppliers leveraging direct-to-clinic logistics networks, and manufacturers differentiating through private-label scale across rehabilitation SKUs. Competitive moves concentrate on backward integration into gel formulation production and geographic expansion into streamlined regulatory jurisdictions.
Within the multinational healthcare tier, 3M and Cardinal Health exemplify divergent positioning strategies. 3M represents the materials science heritage archetype, sustaining institutional contracts through reusable thermal systems engineered for sterilization durability. Cardinal Health occupies a position anchored in direct-to-clinic logistics networks that bypass traditional distributor markups. Medline Industries sits within the private-label manufacturing archetype, leveraging scale across multiple rehabilitation SKUs to serve hospital procurement systems requiring EDI connectivity and lot-level traceability.
| Leading Market Players |
|---|
| 3M |
| Cardinal Health |
| Medline Industries |
| Breg |
| Caldera International |
| Chattanooga International |
| Bruder Healthcare Company |
| Kobayashi Pharmaceutical |
| Core Products International |
| Others |
Supply & Pricing Matrix
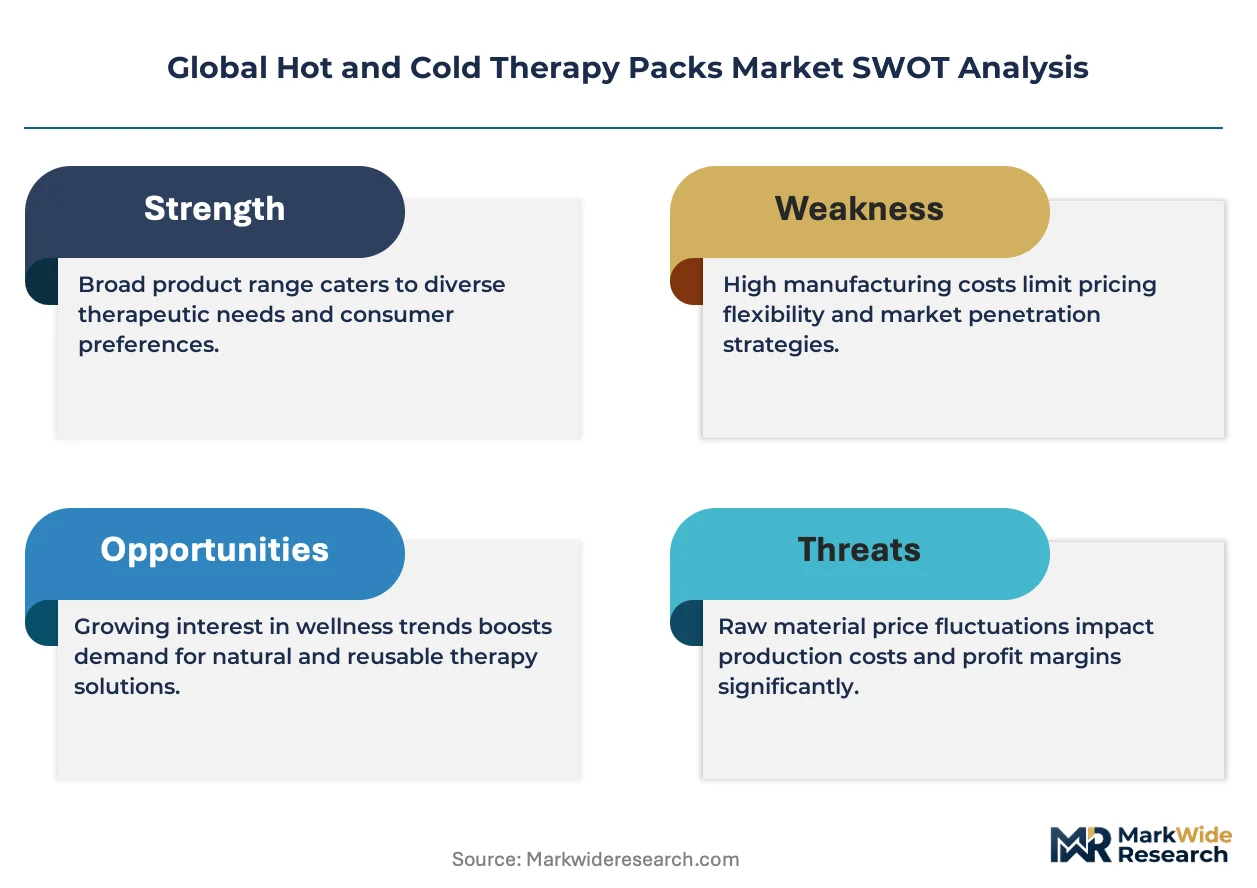
Propylene glycol feedstock costs transmit directly from Zhejiang petrochemical complexes through polymer shell fabricators to mid-tier consumer pack margins, with REACH-compliant biocompatible alternatives commanding premium spreads at hospital procurement desks.
Pricing Analysis
Bundled service contracts with autoclave-cycle guarantees separate institutional procurement from unbundled retail transactions. Three-tier pricing structure across premium medical-grade, validated standard, and commodity consumer levels reflects ISO 13485 certification status and freeze-thaw durability specifications. Cost compression in mid-tier consumer packs intensifies because propylene glycol price volatility tracks naphtha feedstock markets. Hospital systems exhibit lowest price sensitivity due to reimbursement code coverage, while fitness-center channels demonstrate highest elasticity to unit cost fluctuations.
Supply Chain Analysis
Direct-to-clinic channels handle hospital system demand through EDI-integrated logistics networks, while retail pharmacy and online platforms serve home healthcare segments. Gel formulation production clusters in Germany, the United States, and Japan, with polymer shell fabrication drawing from Zhejiang and Guangdong injection-molding capacity. Raw material dependencies span propylene glycol, medical-grade PVC, and bentonite clay reserves. Single-source vulnerability in Chinese tooling equipment creates supply chain risk. Distribution runs through Cardinal Health direct networks, Medline private-label channels, and Amazon marketplace aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on backward integration into gel formulation production and the accelerating premium-tier shift toward MDR-compliant medical-grade systems.
For Market Incumbents: Anchor hospital contracts through ISO 10993 biocompatibility data investments that satisfy German notified body requirements. Deepen captive supply of polymer matrices to offset propylene glycol cost volatility. Defend against commodity consumer-wrap erosion by tightening autoclave-cycle performance guarantees in sports medicine clinic tenders. For New Entrants and Emerging Players: Begin with ANVISA-streamlined Class II registrations in Brazilian private clinic networks where outpatient rehabilitation capacity is expanding. Target Australian fitness-center channels with hybrid clay-bead microwave-safe formulations. Pursue direct-to-patient subscription bundling through Canadian telehealth platforms to bypass distributor markups. For Investors and Strategic Acquirers: Roll-up economics work for regional ISO 13485-certified manufacturers because hospital procurement consolidation demands EDI connectivity and lot-level traceability that smaller players cannot self-fund. Long-term viability favors platforms with validated gel chemistry capabilities and MDR technical documentation expertise. Watch ANVISA registration queue lengths as inflection indicator for Brazilian market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gel Formulation | Captive propylene glycol sourcing insulates margins from petrochemical feedstock volatility. |
| MDR Technical Documentation Investment | German notified bodies mandate new biocompatibility data for pain management indications. |
| Direct-to-Clinic Logistics Expansion | Cardinal Health networks bypass distributor markups in United States hospital systems. |
| ANVISA Registration Streamlining | Brazilian Class II pathways reduce time-to-market for imported thermal therapy systems. |
| Phase-Change Material R&D | Microencapsulated paraffin wax composites absorb market share from hydrocolloid alternatives. |
Research Methodology
Bottom-up rehabilitation facility and home healthcare channel modeling reconciled against top-down gel pack and bead pack production tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sports medicine clinic procurement officers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and REACH polymer disclosure registries. Triangulation across these sources ensures segment-level volume and value estimates reflect actual procurement patterns rather than manufacturer shipment claims.
Historical trendline analysis of thermal therapy pack adoption across post-surgery care, chronic pain management, and sports injury relief applications informed the projection framework. Segmentation dimensions modeled include material composition, clinical versus consumer use case, procurement authority by care setting, and channel economics. CAGRs derive from curve-fitting against documented reimbursement code expansions and contraction patterns, with propylene glycol price elasticity and biocompatibility testing queue lengths serving as industry-specific forecast inputs across the analysis window.
Several conditions sit outside the modeled scope, including sudden REACH polymer ban expansions, Medicare durable medical equipment code eliminations, and Chinese mold-injection equipment export restrictions. Forecasts reflect assumptions about regulatory pathway stability and feedstock market continuity. Periodic stress-testing of base assumptions is recommended against ANVISA registration velocity, ISO 10993 laboratory capacity, and hospital vertical integration trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Safety Needles Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
Specimen Transport Bags Market