
 Europe Endotoxin and Pyrogen Testing Market | 2026-2036
Europe Endotoxin and Pyrogen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Endotoxin and Pyrogen Testing Market Foresight
Aftermarket service revenue from instrument calibration and reagent supply contracts is rewriting how testing vendors capture lifetime value from installed LAL and recombinant Factor C platforms. Eurofins Scientific leverages its pan-European laboratory network to anchor long-term service agreements with pharmaceutical quality control departments. Charles River Laboratories sustains its position through specialized endotoxin detection kits that dominate high-throughput drug release testing. Lonza competes by extending its footprint in automated endotoxin monitoring systems for continuous bioprocessing lines.
Endotoxin and pyrogen testing encompasses analytical methods that detect lipopolysaccharide contaminants from Gram-negative bacteria and non-endotoxin fever-inducing substances in pharmaceuticals, medical devices, and biological products. The Limulus amebocyte lysate (LAL) assay measures coagulation cascade activation with picogram-level sensitivity, while recombinant Factor C assays eliminate horseshoe crab dependency through synthetic reagents. Automated testing systems lead the technology landscape by reducing manual pipetting errors and compressing batch release timelines for sterile injectable manufacturers. Recombinant Factor C assays represent the fastest-growing product category as EMA pharmacopeial alignment and ethical sourcing mandates displace traditional LAL methods in European facilities.
The European Medicines Agency (EMA) harmonizes endotoxin limits through the European Pharmacopoeia, while REACH and EU Green Deal frameworks pressure manufacturers to abandon horseshoe crab-derived reagents in favor of synthetic alternatives. Germany's national pharmaceutical regulator enforces batch-release testing protocols that directly shape laboratory procurement decisions for pyrogen detection platforms. Stakeholders must monitor how the EU AI Act's validation requirements for automated decision-making systems will reshape algorithmic endotoxin detection software compliance pathways.
Market Dynamics
The EMA's pharmacopeial alignment with recombinant Factor C assays is collapsing traditional LAL dominance across European sterile injectable facilities. This regulatory pivot is redrawing competitive positioning among testing platform vendors and reconfiguring laboratory procurement priorities.
Growth Catalysts
- EMA Pharmacopeial Harmonization:The European Pharmacopoeia's acceptance of recombinant Factor C methods is accelerating displacement of horseshoe crab-derived reagents in batch-release protocols.
- Rhine-Main Biotech Corridor Expansion:Contract manufacturing organizations and Big Pharma co-location in Germany is concentrating demand for high-throughput endotoxin detection systems.
- Continuous Bioprocessing Adoption:Real-time endotoxin monitoring integration into automated production lines is creating pull for inline testing platforms.
Market Restraints
- Recombinant Reagent Cost Premium:Synthetic Factor C assays carry 40-60% higher per-test costs than traditional LAL methods, constraining adoption at mid-cap pharmaceutical facilities.
- Horseshoe Crab Supply Concentration:Coastal harvesting operations in the United States and Asia control 90% of wild Limulus polyphemus populations, creating geopolitical exposure for LAL-dependent laboratories.
- Cross-Reactivity Limitations:Recombinant assays demonstrate variable sensitivity to certain lipopolysaccharide serotypes, requiring parallel validation studies that extend implementation timelines.
Strategic Opportunities
- Eastern European CMO Penetration:Poland and Hungary's emerging sterile injectable manufacturing bases remain underpenetrated by automated endotoxin platforms, offering first-mover positioning.
- Cell and Gene Therapy Testing:Advanced therapy medicinal products require modified pyrogen detection protocols, creating specialized service revenue streams for contract testing laboratories.
- EU Green Deal Alignment:REACH framework incentives for animal-free testing methods are generating procurement preference for synthetic reagent suppliers in sustainability-focused pharmaceutical companies.
Industry Challenges
- Validation Specialist Scarcity:The shortage of technicians trained in recombinant assay validation and equivalency studies against pharmacopeial standards is extending implementation cycles at quality control departments.
- Legacy LAL Infrastructure Stranding:Laboratories with depreciated endotoxin detection systems face capital intensity conflicts when migrating to automated recombinant platforms, particularly at facilities with multi-year reagent supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Endotoxin and Pyrogen Testing Market |
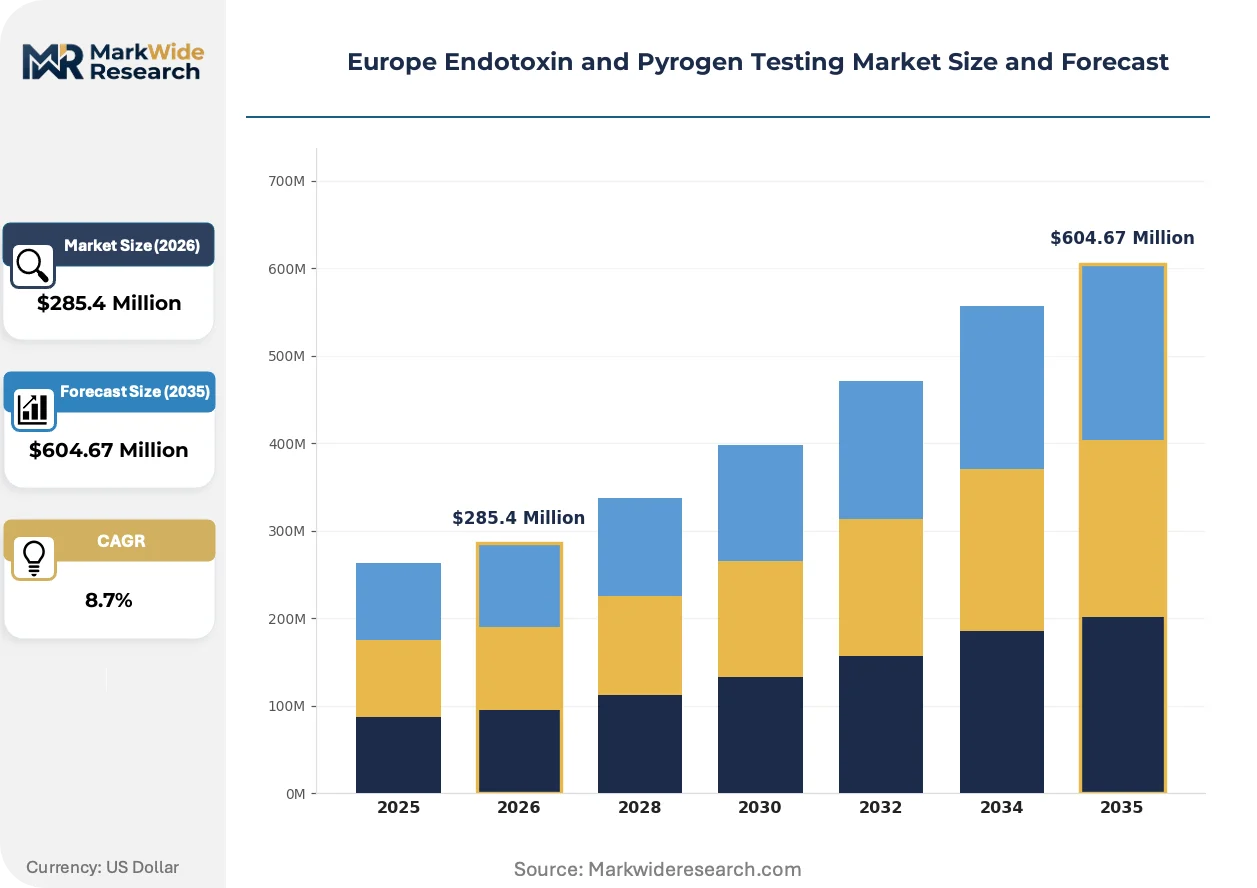
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel Clot Method, LAL Test, Recombinant Factor C Assay, PCR Methods End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Hospitals Technology: Automated Testing Systems, Traditional Methods, Microbial Detection Systems, Molecular Techniques Application: Drug Development, Quality Control, Clinical Trials, Environmental Testing |
| Companies Covered | Eurofins Scientific, Thermo Fisher Scientific Inc., Charles River Laboratories, Lonza, Merck KGaA, SGS SA, Sartorius AG, bioMérieux, Pall Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Endotoxin and Pyrogen Testing Market Shifts & Advancements
Digital integration and synthetic biology are converging to compress testing timelines and eliminate biological supply dependencies. These forces are restructuring how European pharmaceutical quality control departments procure and operate endotoxin detection capabilities.
Microfluidic cartridge-based endotoxin detection is virtualizing laboratory workflows by embedding LAL and recombinant reagents in single-use disposable formats. Biopharmaceutical quality control departments in Germany and Switzerland are adopting these platforms to eliminate manual pipetting steps and reduce analyst-to-analyst variability. This technology is virtualizing the traditional central laboratory model by enabling distributed testing nodes at manufacturing sites.
REACH regulation amendments targeting animal-derived raw materials in pharmaceutical manufacturing are mandating substitution pathways for horseshoe crab hemolymph. The European Chemicals Agency's enforcement timeline is compelling contract manufacturers to accelerate recombinant Factor C validation before 2027 compliance deadlines. Sterile injectable facilities in France and Italy are responding by consolidating reagent procurement under long-term synthetic supply agreements.
Service unbundling is fragmenting traditional instrument-reagent bundled contracts into separate hardware, consumable, and validation service lines. Pharmaceutical quality control departments now negotiate calibration and maintenance agreements independently from reagent supply, compressing vendor switching costs. This behavioral shift is most visible in the United Kingdom's CMO sector, where multi-vendor testing strategies are becoming standard procurement practice.
Europe Endotoxin and Pyrogen Testing Market Segmentation
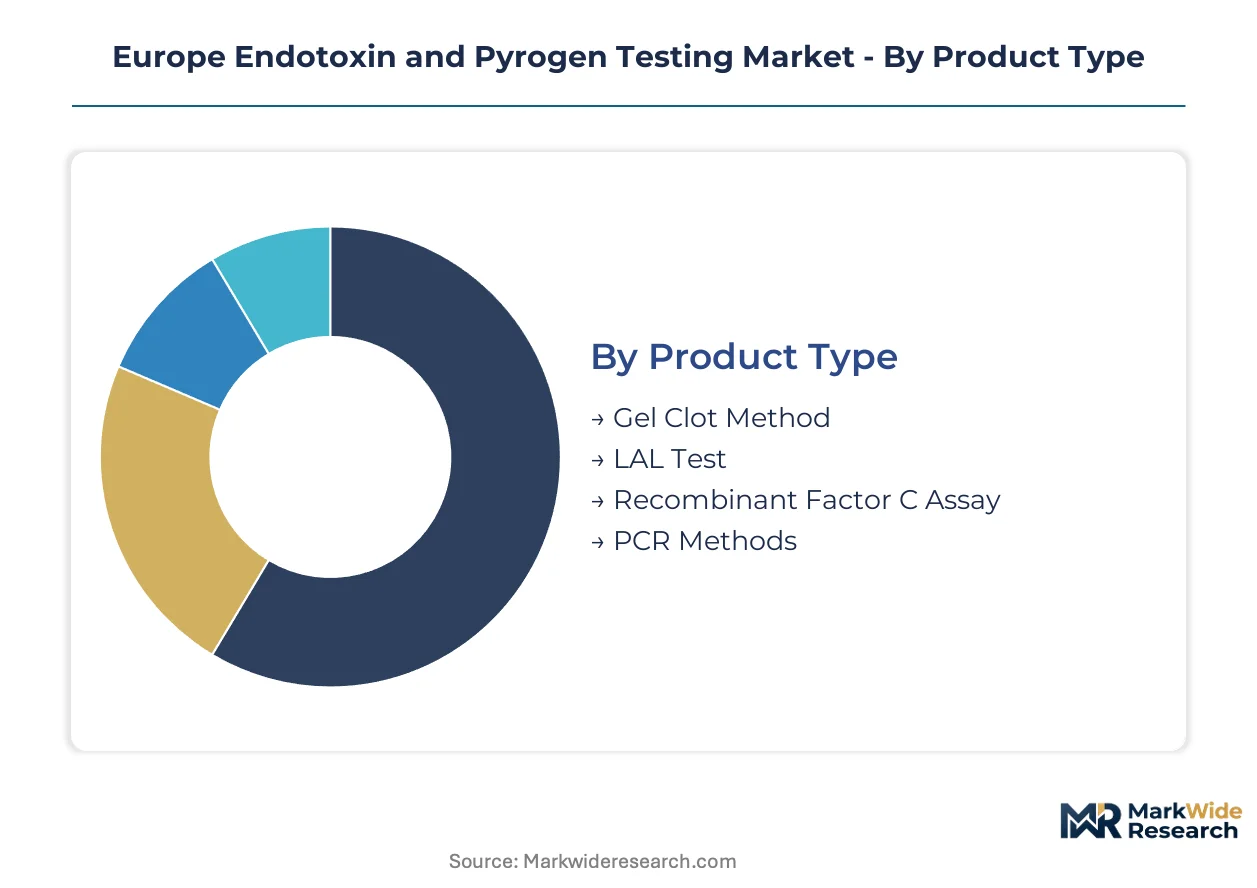
Endotoxin and pyrogen testing segments diverge sharply across technology maturity, regulatory acceptance, and automation intensity. Pharmaceutical procurement teams in Europe weight these dimensions differently based on batch volume, therapeutic class, and EMA pharmacopeial alignment status.
Product Type:
Testing methodologies span a spectrum from established animal-derived reagents to synthetic biology-engineered alternatives, with cost sensitivity and ethical sourcing mandates driving portfolio decisions.
- LAL Test:Horseshoe crab hemolymph-based coagulation cascade detection delivers picogram-level sensitivity for lipopolysaccharide quantification. Demand persists among legacy facilities in France and Italy with validated pharmacopeial protocols and multi-year reagent supply contracts, though EMA pressure on animal-derived materials is constraining expansion.
- Recombinant Factor C Assay:Synthetic reagents replicate the Factor C enzymatic pathway without biological harvesting, eliminating supply chain exposure to wild Limulus populations. German and Swiss sterile injectable manufacturers are consolidating procurement under long-term synthetic agreements ahead of REACH compliance deadlines.
- Gel Clot Method:Qualitative endpoint detection using LAL reagent gel formation provides pass-fail simplicity for low-volume screening.
- PCR Methods:Nucleic acid amplification targets bacterial DNA signatures as orthogonal confirmation to protein-based endotoxin detection.
The dominant share belongs to LAL Test, while Recombinant Factor C Assay is gaining share fastest.
End User:
Customer archetypes distribute across the value chain from discovery-stage research through commercial batch release, with automation requirements and validation burdens scaling accordingly.
- Pharmaceutical Companies:Big Pharma quality control departments operate high-throughput endotoxin detection for parenteral drug release, with Germany's Rhine-Main corridor concentrating the densest demand. These facilities prioritize automated platforms with 21 CFR Part 11 compliant data integrity and inline bioprocessing integration.
- Biotechnology Firms:Cell and gene therapy developers require modified pyrogen detection protocols for complex matrices including viral vectors and lipid nanoparticles. Facilities in Cambridge, UK and Leiden, Netherlands are driving specialized service revenue for contract testing laboratories.
- Research Institutions:Academic and government laboratories employ lower-throughput methods for preclinical toxicology and method development studies.
- Hospitals:Compounding pharmacies and clinical laboratories perform point-of-release testing for radiopharmaceuticals and personalized medicine preparations.
Pharmaceutical Companies command the largest procurement volumes, though Biotechnology Firms are expanding most quickly.
Technology:
Automation intensity separates capital-intensive platform investments from labor-dependent manual workflows, with digital integration reshaping total cost of ownership calculations.
- Automated Testing Systems:Robotic liquid handling and microplate readers compress batch release timelines while eliminating analyst-to-analyst variability. CMOs across Germany and the United Kingdom are unbundling instrument-reagent contracts to negotiate calibration services independently.
- Traditional Methods:Manual pipetting and visual endpoint determination persist at mid-cap facilities with constrained capital budgets and lower throughput requirements.
- Microbial Detection Systems:Culture-based alternatives to LAL methods target non-endotoxin pyrogen detection for complete fever-inducing substance coverage.
- Molecular Techniques:PCR and sequencing-based orthogonal confirmation methods address specificity limitations in protein-based assays.
Automated Testing Systems hold the installed base majority, while Microbial Detection Systems are climbing the fastest on ATMP testing demand.
Application:
Use cases trace the pharmaceutical lifecycle from candidate selection through commercial manufacturing, with regulatory scrutiny intensifying at each progression stage.
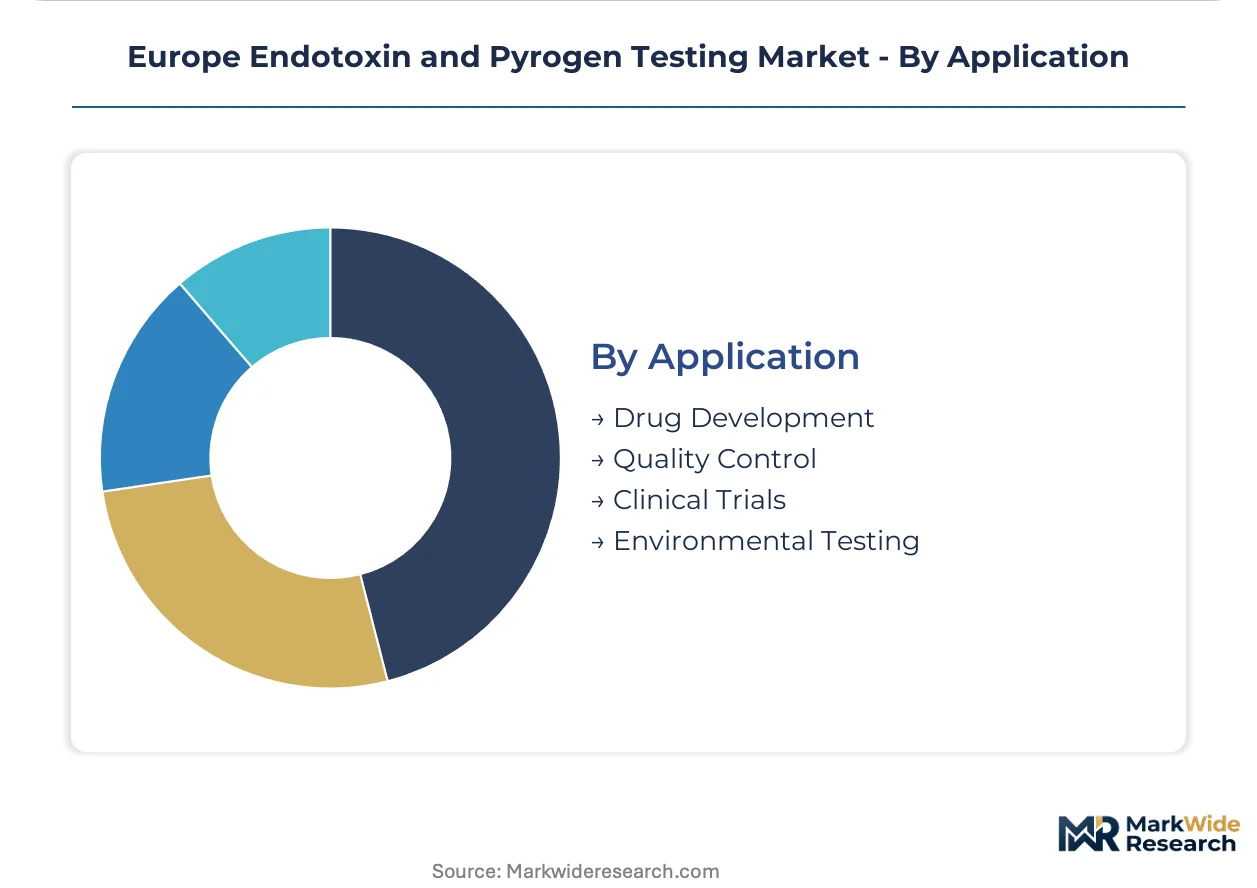
- Quality Control:Batch-release testing for sterile injectables represents the most stringent application, with EMA pharmacopeial limits enforced through validated LAL or recombinant methods. German national pharmaceutical regulator protocols directly shape laboratory procurement for commercial parenteral production.
- Drug Development:Preclinical and clinical-phase testing supports IND and NDA filings, with method validation requirements scaling toward commercial transfer.
- Clinical Trials:Investigational medicinal product release requires GMP-compliant endotoxin documentation for multi-site study consistency.
- Environmental Testing:Cleanroom and water system monitoring extends pyrogen detection beyond drug product to manufacturing infrastructure.
Quality Control absorbs the dominant procurement spend, while Drug Development shows the steepest expansion trajectory on pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-cap pharmaceutical facilities in Eastern Europe exhibit acute price sensitivity to recombinant reagent premiums, while German and Swiss sterile injectable manufacturers absorb higher per-test costs to secure supply chain resilience and EMA pharmacopeial alignment.
Germany
The Rhine-Main biotech corridor concentrates Europe's densest demand for automated endotoxin detection systems as CMOs and Big Pharma co-locate sterile injectable operations. Germany's national pharmaceutical regulator enforces batch-release testing protocols that directly shape laboratory procurement decisions for pyrogen detection platforms. Facilities in Frankfurt and Mainz are consolidating reagent procurement under long-term synthetic agreements ahead of REACH compliance deadlines.
United Kingdom
Biotechnology firms in Cambridge and contract manufacturers across the UK are driving specialized service revenue for modified pyrogen detection protocols in cell and gene therapy applications. The Medicines and Healthcare products Regulatory Agency maintains alignment with EMA pharmacopeial standards while adapting post-Brexit validation requirements. Service unbundling is most visible here, with multi-vendor testing strategies becoming standard procurement practice among CMOs.
France
ANSM enforcement of pharmacopeial standards is accelerating displacement of horseshoe crab-derived reagents in batch-release protocols across Paris and Lyon manufacturing clusters. Legacy facilities with validated LAL protocols and multi-year reagent supply contracts persist, though EMA pressure on animal-derived materials is constraining expansion. Sterile injectable facilities are responding by consolidating reagent procurement under long-term synthetic supply agreements.
Switzerland
Swissmedic's rigorous quality standards and proximity to German supply chains position Basel and Zurich facilities as early adopters of recombinant Factor C validation. Biopharmaceutical quality control departments are adopting microfluidic cartridge-based platforms to eliminate manual pipetting steps and reduce analyst-to-analyst variability. The country's pharmaceutical concentration creates pull for inline bioprocessing integration of real-time endotoxin monitoring.
Poland
Emerging sterile injectable manufacturing bases in Warsaw and Krakow remain underpenetrated by automated endotoxin platforms, offering first-mover positioning for testing vendors. Mid-cap facilities here exhibit pronounced cost sensitivity to the 40-60% premium carried by synthetic Factor C assays. EU structural funds and CMO investment incentives are accelerating facility upgrades that will reshape procurement priorities over the forecast window.
Europe Endotoxin and Pyrogen Testing Market Competitive Landscape
Pan-European laboratory networks and specialized testing kit suppliers split the market into service-anchored and product-centric competitive spheres. The vendor base concentrates around three strategic archetypes: integrated contract research organizations with calibration service capabilities, dedicated endotoxin detection platform manufacturers, and diversified life science conglomerates with reagent portfolios. Competitive dynamics center on long-term service agreement capture and automated platform placement in continuous bioprocessing lines.
Within the integrated service tier, Eurofins Scientific leverages its laboratory network to anchor agreements with pharmaceutical quality control departments. Charles River Laboratories and Lonza occupy positions as specialized platform vendors, with the former exemplifying high-throughput detection kit supply and the latter representing automated monitoring system integration. These three entities collectively illustrate how aftermarket service revenue and synthetic reagent transitions are restructuring competitive positioning across European sterile injectable facilities.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Thermo Fisher Scientific Inc. |
| Charles River Laboratories |
| Lonza |
| Merck KGaA |
| SGS SA |
| Sartorius AG |
| bioMérieux |
| Pall Corporation |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container cost dynamics amplify supply concentration effects for recombinant Factor C reagents, compressing margins for mid-cap Polish facilities while German buyers absorb premiums for supply chain resilience. This logistics chokepoint reinforces price stratification between automated platform adopters and legacy LAL-dependent laboratories.
Pricing Analysis
Aftermarket service revenue from multi-year calibration and reagent supply contracts drives lifetime value capture for endotoxin testing vendors. Three-tier pricing structure across premium automated platforms, standard benchtop systems, and economy manual methods stratifies the installed base. Cost compression in economy tiers intensifies as Eastern European CMOs negotiate unbundled hardware and consumable contracts. Mid-cap facilities in Poland and Hungary exhibit acute price sensitivity, while Swiss and German sterile injectable manufacturers prioritize supply security over per-test economics.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities anchor procurement relationships for recombinant reagent suppliers serving cash-constrained mid-cap laboratories. Manufacturing concentration in Germany, Switzerland, and the United States feeds European distribution networks for synthetic Factor C enzymes and LAL alternatives. The supply chain rests on hemolymph harvesting operations in the United States and Asia for traditional reagents, creating single-source vulnerability amid REACH-driven substitution mandates. Distribution runs through pan-European laboratory networks and direct pharmaceutical procurement channels, with consolidated reagent agreements displacing spot purchasing in the Rhine-Main corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and Swiss sterile injectable manufacturers as CMO consolidation in the Rhine-Main corridor compresses vendor switching costs through unbundled procurement strategies.
For Market Incumbents: Entrench position by securing exclusive multi-year service agreements with automated platform installations ahead of REACH compliance deadlines, while accelerating backward integration into recombinant reagent production to capture margin from synthetic substitution. The EMA's pharmacopeial alignment with Factor C methods threatens LAL-dependent revenue streams; incumbents must validate equivalency studies rapidly to retain batch-release testing contracts. For New Entrants and Emerging Players: Eastern European CMO facilities in Warsaw and Krakow represent the most penetrable entry point for economy-tier automated platforms, given pronounced price sensitivity and EU structural fund availability for facility upgrades. Cell and gene therapy developers in Cambridge and Leiden offer specialized service revenue through modified pyrogen detection protocols for complex ATMP matrices. A validation-specialist hiring surge combined with localized technical support accelerates first-mover positioning. For Investors and Strategic Acquirers: REACH amendment enforcement reshapes the acquisition landscape by elevating synthetic reagent capabilities above legacy LAL infrastructure value. Long-term viability centers on automated platform vendors with installed base density in continuous bioprocessing lines. Acquisition targets should demonstrate equivalency study completion against European Pharmacopoeia standards. The signal to watch is EMA guidance publication timing on AI Act validation requirements for algorithmic detection software.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Factor C Validation Completion | EMA pharmacopeial alignment secures batch-release testing contracts against LAL displacement. |
| Automated Platform Installation Surge | Rhine-Main corridor CMOs compress release timelines through robotic liquid handling integration. |
| Service Contract Unbundling | UK CMOs negotiate calibration and reagent supply independently, fragmenting vendor lock-in. |
| Microfluidic Cartridge Development | Swiss facilities eliminate pipetting variability through single-use distributed testing nodes. |
| Eastern European CMO Penetration | Polish and Hungarian facility upgrades reshape procurement priorities for economy-tier systems. |
Research Methodology
Initial hypotheses were tested against primary input from quality control directors at sterile injectable facilities, regulatory affairs specialists at EMA-aligned laboratories, procurement managers at German CMOs, and validation technicians overseeing recombinant assay implementation, and refined through secondary validation against European Pharmacopoeia submissions, EMA inspection reports, REACH regulatory filings, and trade data on reagent imports. Bottom-up triangulation across installed platform counts and reagent consumption patterns converged with top-down pharmaceutical production value estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product type, end user archetype, automation intensity, and application stage from drug development through commercial release. CAGRs derived from regression analysis of historical procurement patterns and forward projection of regulatory compliance deadlines incorporated EMA pharmacopeial adoption curves and continuous bioprocessing penetration rates as industry-specific forecast inputs.
Practitioners should monitor REACH enforcement timeline acceleration and EMA AI Act guidance publication for early signals of compliance-driven procurement shifts. Forecasts reflect assumptions regarding regulatory alignment pace and synthetic reagent cost convergence. Macroeconomic contraction affecting pharmaceutical capital expenditure, regulatory delay in pharmacopeial method acceptance, or technological breakthrough in alternative pyrogen detection would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Fecal Occult Testing Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Tablet Hardness Testers Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Vestibular Testing System Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Osmometer Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Self-Testing Market