
 US Patient Positioning Systems Market | 2026-2036
US Patient Positioning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Patient Positioning Systems Market Intelligence
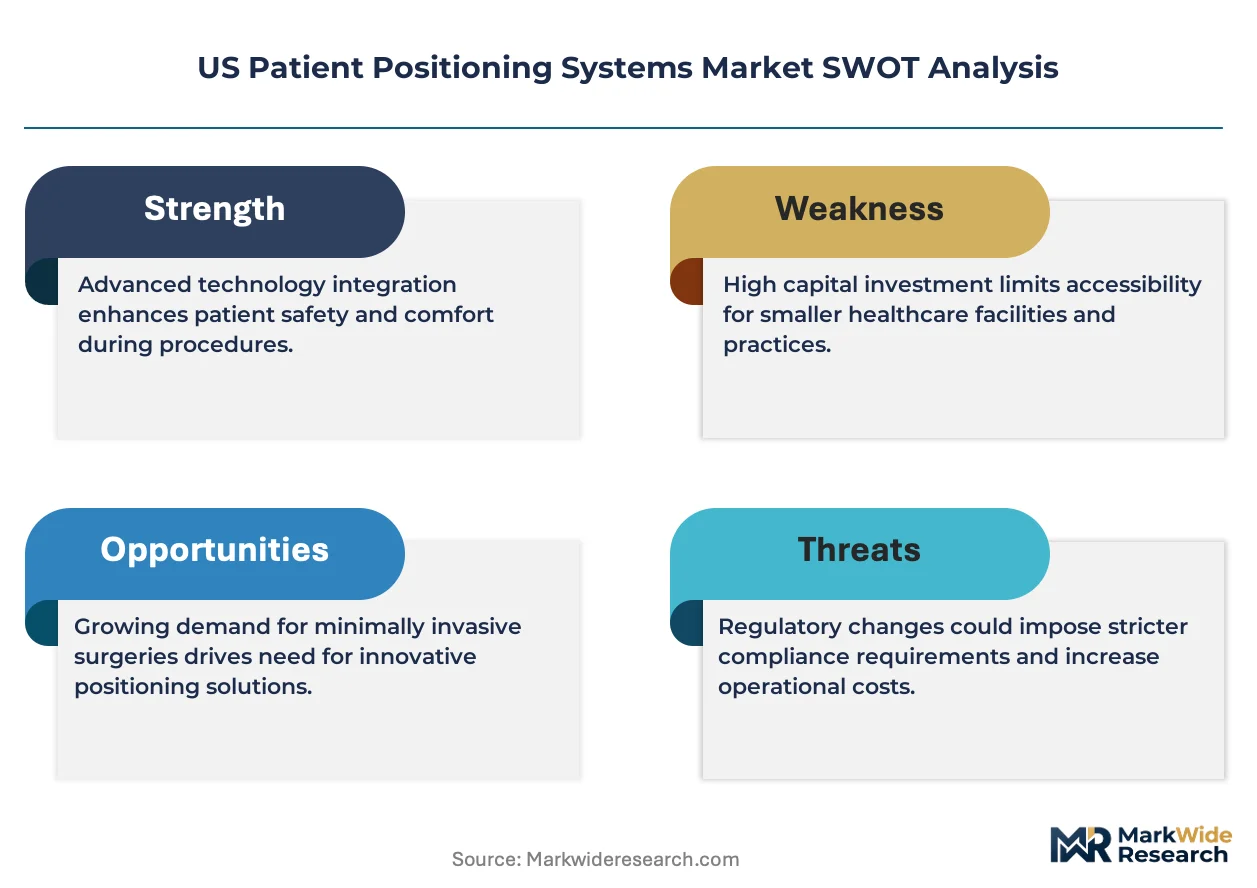
Ambulatory surgical centers is rebalancing toward higher-acuity procedures requiring powered positioning equipment. Stryker Corporation leverages its integrated surgical technologies portfolio to dominate premium table segments. Hill-Rom Holdings, Inc. anchors its position through extensive hospital service contracts across integrated delivery networks. Medtronic competes by specializing in neurosurgical and spinal positioning accessories with precision control systems.
Patient positioning systems encompass powered and manually operated tables, supports, and accessories engineered to stabilize patients during surgical, diagnostic, or therapeutic procedures, typically featuring load capacities exceeding 500 pounds and radiolucent surfaces for intraoperative imaging compatibility. Their primary commercial purpose centers on preventing nerve injury, pressure ulcers, and respiratory compromise while enabling surgeon access. Surgical tables command the largest revenue share among product types due to capital intensity and replacement cycles tied to operating room renovations. Electric technology segments are expanding fastest as hospitals phase out manual crank systems to reduce staff musculoskeletal injuries and improve turnover efficiency.
FDA 510(k) premarket notification requirements govern powered positioning system approvals, while OSHA workplace ergonomics standards drive electric system adoption to reduce clinical staff injury rates. The Centers for Medicare & Medicaid Services reimbursement policies for outpatient surgical procedures indirectly influence capital allocation decisions across health systems. Stakeholders must monitor evolving FDA guidance on software-enabled positioning controls and cybersecurity requirements for networked surgical equipment.
Market Dynamics
Outpatient surgical migration is compressing replacement cycles for powered positioning equipment as ambulatory surgical centers upgrade infrastructure to handle higher-acuity procedures previously confined to hospital operating rooms.
Growth Catalysts
- OSHA Ergonomics Enforcement:Workplace injury reduction mandates accelerate electric table adoption across hospital systems replacing manual crank systems.
- Southeast Capital Concentration:Health system infrastructure spending in this region exceeds national averages, driving concentrated demand for surgical table replacements.
- Radiolucent Surface Engineering:Intraoperative imaging compatibility requirements pull demand toward premium tables supporting fluoroscopy and C-arm integration.
Market Restraints
- FDA 510(k) Timeline Friction:Premarket notification requirements for powered controls extend product development cycles by 12-18 months.
- Stainless Steel Input Volatility:Surgical table frame manufacturing faces cost pressure from commodity metal price swings.
- Manual Table Substitution:Budget-constrained rural hospitals delay electric upgrades, extending legacy equipment lifecycles.
Strategic Opportunities
- Software-Enabled Positioning Controls:Networked surgical equipment with predictive maintenance capabilities opens service revenue streams.
- Neurosurgical Accessory Specialization:Precision head fixation and spinal navigation integration address unmet needs in high-margin subspecialties.
- CMS Outpatient Reimbursement Expansion:Medicare payment policy shifts indirectly fund ASC capital equipment purchases.
Industry Challenges
- Cybersecurity Certification Burden:FDA guidance on networked medical device security adds compliance layers for software-enabled systems.
- Biomedical Engineering Talent Scarcity:Shortage of technicians trained on integrated electromechanical surgical tables prolongs service response times.
- Legacy OR Integration Complexity:New powered tables require electrical infrastructure upgrades incompatible with aging hospital facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Patient Positioning Systems Market |
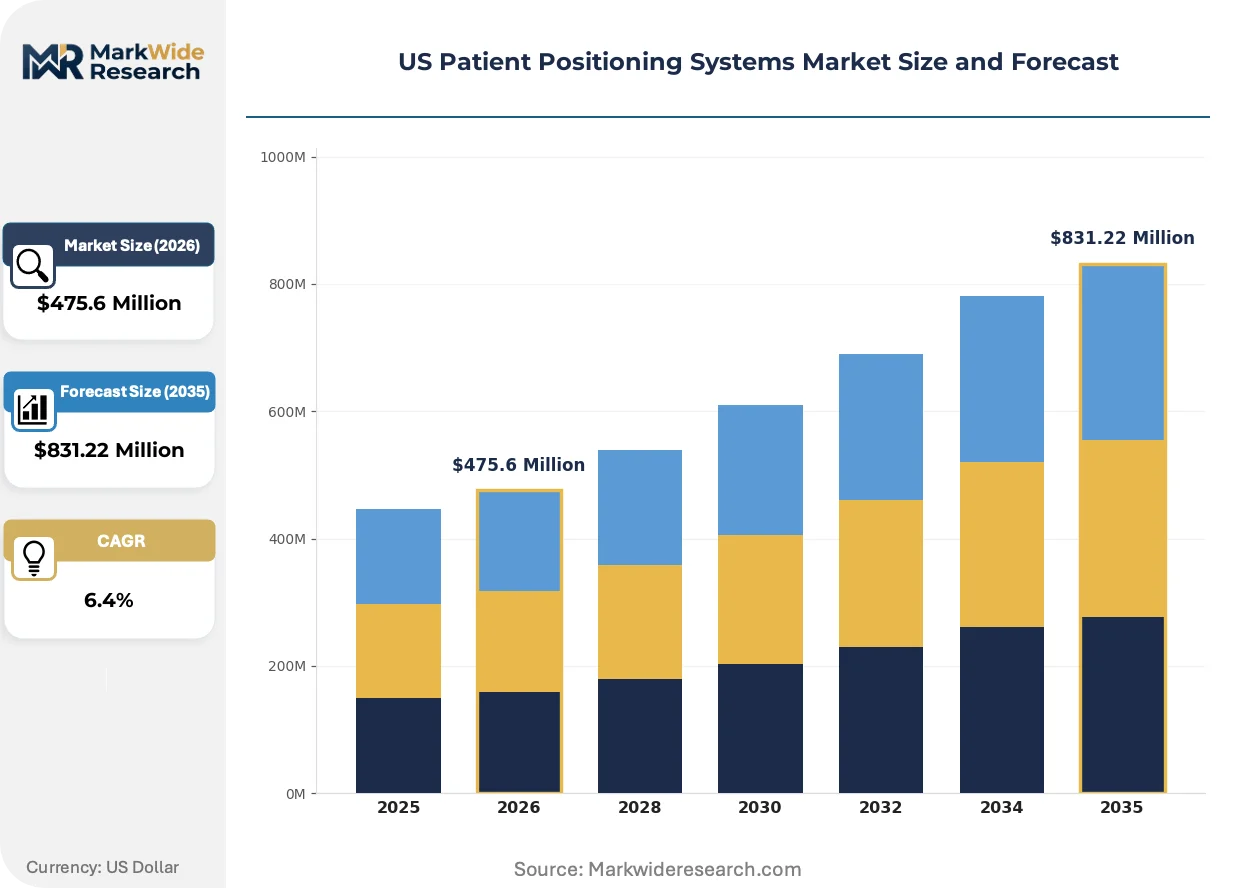
| Market Size in 2026 | $475.6 Million |
| Market Size in 2035 | $831.22 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Supports, Surgical Tables, Cushions, Slings End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Technology: Electric, Manual, Adjustable, Fixed Application: Surgery, Diagnostics, Physical Therapy, Emergency Care |
| Companies Covered | Stryker Corporation, Hill-Rom Holdings, Inc., STERIS plc, Medtronic, Medline Industries, Skytron, LLC, Mizuho OSI, SchureMed, Span-America Medical Systems, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Patient Positioning Systems Market Strategic Shifts & Innovations
Electromechanical integration and software control layers are redefining competitive differentiation in patient positioning, shifting value capture from hardware durability to intraoperative workflow optimization.
Integrated pressure mapping and automated position feedback is unifying patient safety monitoring with table control systems. Academic medical centers and high-volume orthopedic centers are adopting these systems fastest. This convergence is compressing the market for standalone pressure ulcer prevention devices.
FDA draft guidance on cybersecurity for networked medical devices is forcing manufacturers to embed security-by-design into positioning control software. The industrial consequence is extended validation timelines and third-party penetration testing requirements. Powered surgical table segments with wireless connectivity face the steepest compliance ramps.
Hospital procurement departments are consolidating vendor relationships through integrated delivery network master agreements. Independent distributors and regional equipment dealers are losing access as health systems centralize capital purchases. This concentration is most visible in the Southeast and Midwest where IDN consolidation has advanced furthest.
US Patient Positioning Systems Market Segmentation
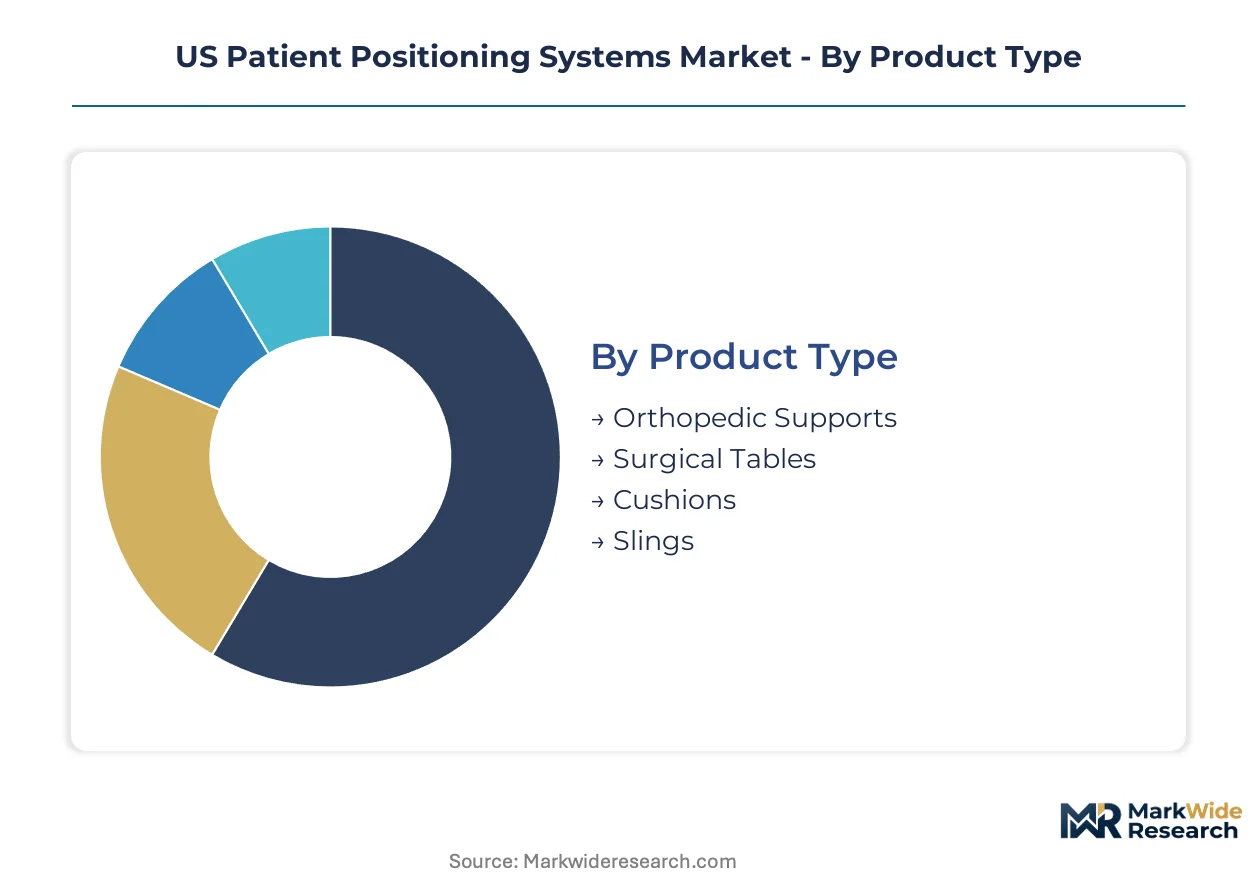
Positioning system procurement varies sharply by clinical setting and procedure intensity. Capital allocation patterns diverge between high-volume surgical infrastructure and distributed rehabilitation networks. Understanding these segment boundaries clarifies where technology premiums command pricing power versus where cost minimization dominates purchasing decisions.
Product Type:
Surgical tables absorb the highest upfront capital outlays, with powered configurations requiring electrical infrastructure investment beyond the unit purchase price. Accessory segments carry lower entry costs but higher lifetime replacement frequency.
- Surgical Tables:Electromechanical platforms with radiolucent surfaces and integrated imaging compatibility anchor operating room infrastructure. Demand concentrates in ambulatory surgical centers across the Southeast as these facilities expand into higher-acuity procedures requiring C-arm integration.
- Orthopedic Supports:Limb positioning devices and traction apparatus engineered for joint replacement and fracture repair. Hospital systems in Texas and Florida are standardizing these purchases through integrated delivery network master agreements to reduce per-procedure setup variability.
- Cushions:Pressure redistribution surfaces for intraoperative and postoperative use.
- Slings:Patient transfer and suspension equipment for lateral positioning and lifting.
Most installed capacity flows through Surgical Tables. Expansion is steepest in Orthopedic Supports.
End User:
Procurement authority and budget scale create distinct purchasing behaviors across care settings. Hospital systems leverage volume consolidation while smaller facilities prioritize flexibility and lease arrangements.
- Hospitals:Academic medical centers and community hospitals drive demand for premium powered tables with software-enabled positioning controls. Replacement cycles accelerate in the Southeast where health system capital spending on surgical infrastructure exceeds national averages.
- Clinics:Outpatient facilities prioritize compact electric tables with rapid turnover capabilities. Freestanding ambulatory surgical centers in Florida and Georgia are upgrading manual equipment to meet OSHA ergonomics enforcement and reduce staff injury claims.
- Rehabilitation Centers:Long-term therapy facilities require adjustable positioning for progressive mobility protocols.
- Home Care:Distributed settings favor lightweight manual equipment with simplified operation.
Hospital procurement channels capture the majority of premium system revenue. Clinic segment growth is climbing fastest as outpatient migration continues.
Technology:
Power source and adjustability determine both unit economics and operational workflow impact. Electric systems command price premiums justified by staff injury reduction and turnover efficiency gains.
- Electric:Motorized height, tilt, and lateral adjustment with programmable position memory. Hospital systems in North Carolina and Tennessee are phasing out manual crank systems to comply with OSHA workplace ergonomics standards and reduce musculoskeletal injury rates among nursing staff.
- Manual:Hand-crank or hydraulic mechanisms with lower acquisition cost but higher operational labor burden. Rural hospitals in Appalachia and the Mississippi Delta delay electric upgrades due to budget constraints and electrical infrastructure limitations.
- Adjustable:Modular configurations allowing component reconfiguration across procedure types.
- Fixed:Static positioning platforms for dedicated procedure rooms with minimal variation.
Electric systems account for the dominant share of new capital deployment. Manual technology retains position in budget-constrained settings.
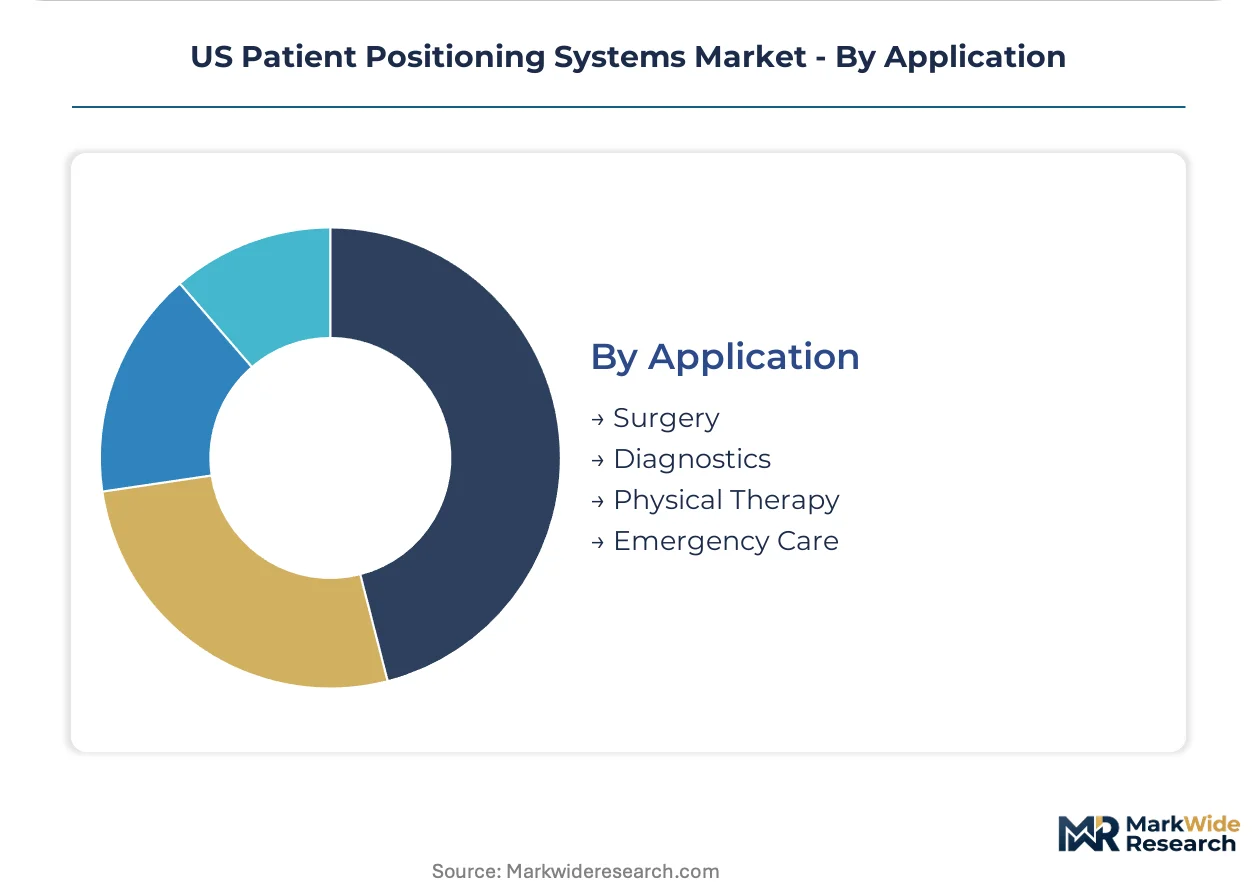
Application:
Procedure complexity and reimbursement levels shape equipment specification requirements. Surgical applications justify the highest technology investment while diagnostic and therapeutic uses prioritize throughput.
- Surgery:Precision positioning for open and minimally invasive procedures with sterile field requirements. Ambulatory surgical centers in Texas and Florida are expanding powered table purchases as outpatient procedure volumes rise and case mix shifts toward higher-acuity interventions.
- Diagnostics:Imaging-compatible positioning for radiology and interventional suites. Demand pulls toward tables with radiolucent surface engineering supporting fluoroscopy and C-arm integration without patient repositioning.
- Physical Therapy:Progressive positioning for mobility restoration and strength training.
- Emergency Care:Rapid-deployment tables for trauma stabilization and resuscitation.
Surgical applications absorb the largest equipment investment. Diagnostic positioning systems are gaining share fastest as imaging procedure volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast health system capital spending concentrates surgical table demand across Florida, Georgia, and the Carolinas, where ambulatory surgical center expansion outpaces national infrastructure investment rates.
Southeast
Florida and Georgia ambulatory surgical centers are upgrading powered positioning equipment to handle higher-acuity outpatient procedures previously confined to hospital operating rooms. CMS outpatient reimbursement expansion for ASC-eligible procedures indirectly funds capital equipment purchases across these states. Tampa and Atlanta metropolitan clusters anchor the nation's steepest surgical infrastructure investment curves.
Southwest
Texas health systems are standardizing orthopedic support purchases through integrated delivery network master agreements to reduce per-procedure setup variability. OSHA workplace ergonomics enforcement accelerates electric table adoption to reduce nursing staff musculoskeletal injury claims. Houston and Dallas-Fort Worth medical centers drive premium powered table procurement.
Midwest
Illinois and Michigan hospital systems are phasing out manual crank systems under OSHA compliance mandates while navigating legacy operating room electrical infrastructure limitations. FDA 510(k) clearance timelines shape product development cycles for manufacturers serving these replacement markets. Chicago and Detroit health networks anchor regional capital deployment.
Northeast
New York and Massachusetts academic medical centers are adopting software-enabled positioning controls with integrated pressure mapping fastest. Cybersecurity certification burdens from FDA draft guidance on networked medical devices extend validation timelines for equipment suppliers. Boston and New York City metropolitan clusters concentrate precision neurosurgical and spinal positioning demand.
Appalachia and Mississippi Delta
Rural hospitals across Kentucky, Tennessee, and Mississippi delay electric table upgrades due to budget constraints and electrical infrastructure limitations. Manual table substitution extends legacy equipment lifecycles in these budget-constrained settings. Regional biomedical engineering talent scarcity prolongs service response times for existing powered equipment.
US Patient Positioning Systems Market Key Industry Players
Portfolio diversification dominates the current landscape as established surgical equipment manufacturers extend positioning system offerings through adjacent technology integration. The market structure consolidates around integrated surgical technologies portfolios rather than standalone positioning specialists. Three strategic archetypes prevail: diversified surgical equipment conglomerates, hospital service contract anchors, and precision subspecialty accessory specialists. M&A activity and strategic partnerships represent the dominant competitive moves reshaping vendor relationships with integrated delivery networks.
Within the diversified surgical equipment tier, Stryker Corporation and STERIS plc occupy positions exemplifying portfolio breadth across operating room infrastructure. Hill-Rom Holdings, Inc. anchors the hospital service contract archetype through extensive integrated delivery network relationships. Medtronic represents the precision subspecialty vector, with its positioning in neurosurgical and spinal accessories reflecting narrower but deeper clinical focus.
| Leading Market Players |
|---|
| Stryker Corporation |
| Hill-Rom Holdings, Inc. |
| STERIS plc |
| Medtronic |
| Medline Industries |
| Skytron, LLC |
| Mizuho OSI |
| SchureMed |
| Span-America Medical Systems, Inc. |
| Others |
Cost & Logistics Intelligence
Integrated delivery network procurement consolidation concentrates purchasing power among fewer buyers, compressing distributor margins and forcing manufacturers toward direct contracting models with volume-tiered pricing structures.
Pricing Analysis
Distributor margins face sustained compression as hospital systems centralize capital equipment purchases through GPO and IDN master agreements. Pricing stratifies across premium, standard, and economy tiers based on software-enabled control sophistication and radiolucent surface certification grades. Cost compression in mid-tier electric tables is intensifying because stainless steel input volatility and extended FDA 510(k) timelines inflate fixed development costs. Rural hospitals and budget-constrained ASCs exhibit highest price sensitivity, while academic medical centers prioritize clinical workflow integration over unit cost.
Supply Chain Analysis
Domestic-content requirements under Buy American provisions for federally funded health infrastructure are reshaping sourcing patterns for surgical table frame manufacturing and electromechanical actuator assembly. Component supply draws from the United States, Germany, and Japan for precision motors and control systems; stainless steel tubing and aluminum castings anchor raw material dependencies. Single-source vulnerability concentrates in specialized radiolucent carbon-fiber surface suppliers. Distribution runs through manufacturer-direct sales organizations serving IDNs, with independent dealers retaining residual access in non-consolidated rural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Patient Positioning Systems Market functions as a stable compounder, with outpatient surgical migration and OSHA ergonomics mandates generating predictable replacement demand across hospital and ambulatory settings.
For Market Incumbents: Anticipate margin pressure from software-enabled positioning controls by deepening service contract penetration and embedding predictive maintenance capabilities. Consolidate position through backward integration into electromechanical actuator production to reduce exposure to German and Japanese component suppliers. Counter emerging entrants specializing in neurosurgical accessories by accelerating FDA submissions for precision head fixation systems.
For New Entrants and Emerging Players: Digital direct-to-ASC sales channels bypass entrenched distributor relationships and enable rapid penetration of Florida and Georgia ambulatory surgical center clusters. White-space opportunities concentrate in cybersecurity-certified software layers for networked surgical tables and disposable pressure-mapping sensor overlays. Target rural hospital manual-to-electric conversion programs with lease-based financing structures addressing capital constraint barriers.
For Investors and Strategic Acquirers: Diversified surgical equipment conglomerates represent the most active acquirer category in this space, seeking positioning system capabilities to complete integrated operating room portfolios. Long-term viability rests on software-enabled service revenue streams rather than hardware replacement cycles. Monitor FDA draft guidance finalization on networked medical device cybersecurity as the critical inflection signal for compliance cost trajectories and competitive consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated submissions for powered controls with software-enabled positioning reduce competitive lag against Stryker and Hill-Rom. |
| Hospital System Partnership | IDN master service agreements with Southeast health systems lock in multi-year replacement cycles and block distributor intermediaries. |
| Software Companion Development | Predictive maintenance platforms for electromechanical tables generate recurring revenue and deepen clinical workflow integration. |
| Backward Integration | In-house production of radiolucent carbon-fiber surfaces mitigates single-source supplier risk and captures margin from premium table tiers. |
| Reimbursement Strategy | CMS outpatient procedure code alignment positions ASC customers for capital equipment purchase funding through expanded Medicare payment. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and ASC operations directors with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and OSHA workplace injury statistics. Bottom-up unit demand modeling and top-down health system capital expenditure analysis triangulated market sizing across product type, technology, and end-user segments.
Segment-weighting approaches distributed forecast growth across surgical tables, orthopedic supports, and accessories by procedure volume intensity and replacement cycle timing. Technology adoption curves for electric versus manual systems incorporated OSHA enforcement patterns and IDN standardization mandates. CAGRs derived from regression analysis of historical capital equipment purchasing correlated with outpatient surgical migration rates and health system infrastructure spending indices.
The model assumes a particular technology adoption path; alternative pathways for software-enabled positioning controls with integrated pressure mapping would alter the outlook if FDA cybersecurity guidance accelerates compliance timelines. Forecasts reflect assumptions about CMS reimbursement stability and stainless steel commodity price normalization. A small set of named triggers—FDA guidance finalization, IDN consolidation pace, and ASC case-mix shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Middle Ear Implants Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
Venturi Mask Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Steam Inhaler Devices Market