
 Stethoscope Hygiene Devices Market | 2026-2036
Stethoscope Hygiene Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Stethoscope Hygiene Devices Market Analytics
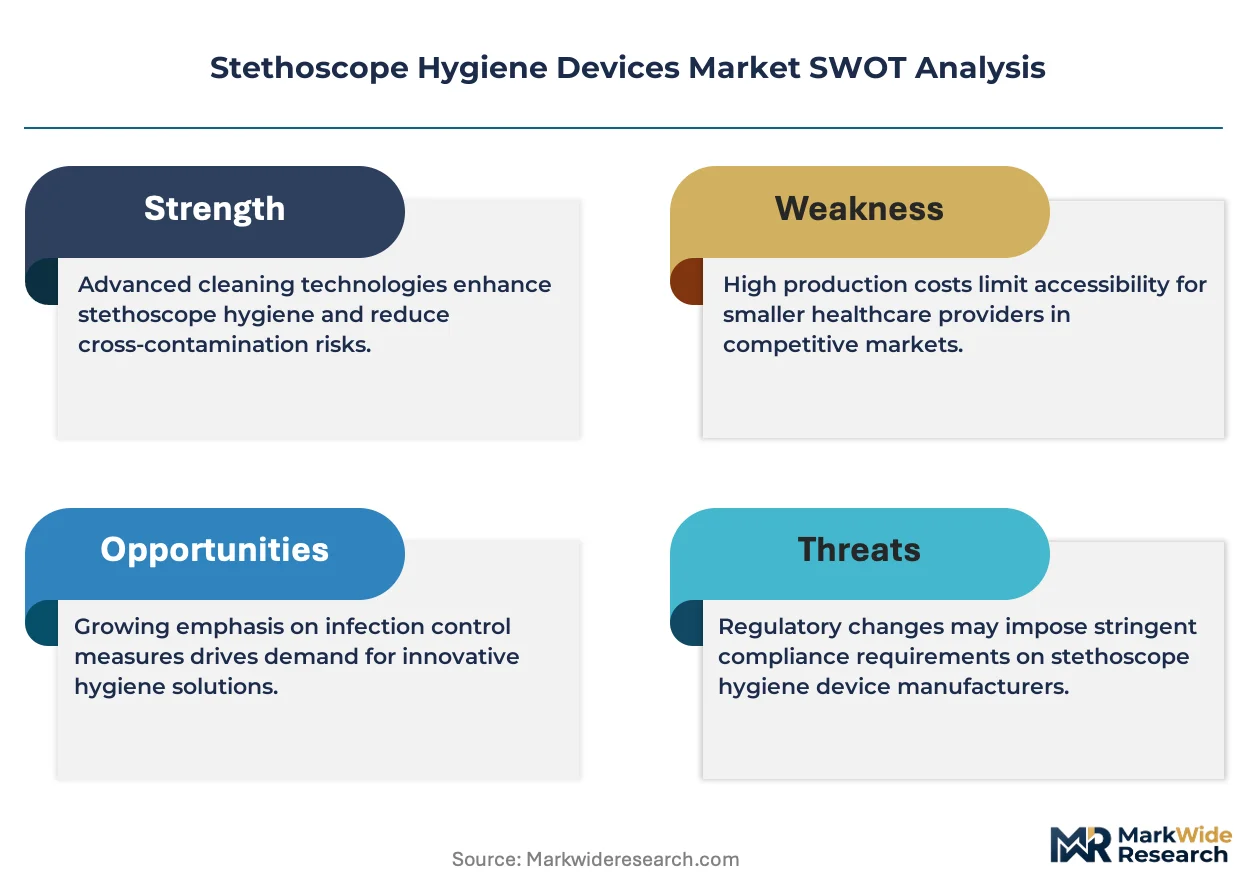
Hospital-grade specification tiers is bifurcating the competitive landscape as acute care facilities demand validated 5-log reduction protocols. UV Smart leverages its ultraviolet sterilizer specialization to anchor European hospital procurement channels. Tangshan UMG Medical Instrument Co., Ltd. sustains manufacturing scale advantages across portable disinfection units. Vioguard differentiates through channel control of automated UV-C cabinet systems in US outpatient clinics.
Stethoscope hygiene devices encompass equipment engineered to eliminate pathogenic contamination from stethoscope diaphragms and binaurals, typically achieving bacterial reduction through UV-C irradiation at 254 nanometers or EPA-registered chemical formulations. These systems serve infection prevention programs seeking to break fomite transmission vectors between clinical encounters. Ultraviolet sterilizers command the dominant revenue position given their reusable architecture and elimination of consumable costs, while antimicrobial covers represent the fastest-expanding segment as nursing homes prioritize single-patient assignment protocols. Portable devices concentrate margin pools where battery-powered units enable bedside deployment without infrastructure retrofit.
FDA enforcement of medical device cleaning validation, EPA registration requirements for surface disinfectants, and Joint Commission infection control standards collectively elevate compliance costs for market entrants lacking established regulatory dossiers. These frameworks compel manufacturers to maintain quality management systems aligned with ISO 13485 while documenting efficacy against clinically relevant organisms including MRSA and VRE. Stakeholders must monitor evolving CMS reimbursement linkages to hospital-acquired infection rates as these metrics increasingly influence capital allocation toward preventive technologies.
Market Dynamics
Hospital procurement teams are consolidating vendor relationships around validated 5-log reduction protocols, compressing the competitive field to manufacturers with ISO 13485-aligned quality systems and documented efficacy against MRSA and VRE.
Growth Catalysts
- FDA medical device cleaning validation:Tightened guidance on reusable device disinfection is compelling acute care facilities to upgrade from manual wipes to automated UV-C systems, accelerating replacement cycles in emergency departments.
- Single-patient assignment protocols:Nursing homes are expanding antimicrobial cover deployment to break fomite transmission between residents, creating pull-through demand for disposable hygiene consumables.
- CMS reimbursement linkages:Hospital-acquired infection rate metrics are increasingly influencing capital allocation decisions, redirecting budgets toward preventive technologies in intensive care units.
Market Restraints
- UV-C lamp supply concentration:Specialized 254-nanometer bulb manufacturing clusters in East Asia create input vulnerability for sterilizer producers outside the region.
- EPA registration timelines:Surface disinfectant approval processes extend 18-24 months, delaying market entry for novel chemical formulations.
- Manual disinfection persistence:Alcohol wipe protocols remain entrenched in outpatient clinics due to low upfront cost, constraining automated system penetration.
Strategic Opportunities
- Battery-powered portable units:Bedside deployment without infrastructure retrofit opens margin pools in older hospital wings lacking dedicated disinfection stations.
- Joint Commission infection control standards:Accreditation requirements are elevating compliance budgets, favoring vendors with established regulatory dossiers over new entrants.
- UV-C and hydrogen peroxide vapor convergence:Hybrid sterilization architectures are emerging for high-throughput settings requiring sub-60-second cycle times.
Industry Challenges
- ISO 13485 quality management implementation:Documentation demands for design controls and risk management strain mid-tier engineering teams without prior medical device experience.
- Legacy stethoscope compatibility:Variable diaphragm diameters across installed bases complicate universal fit designs for automated cabinet systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stethoscope Hygiene Devices Market |
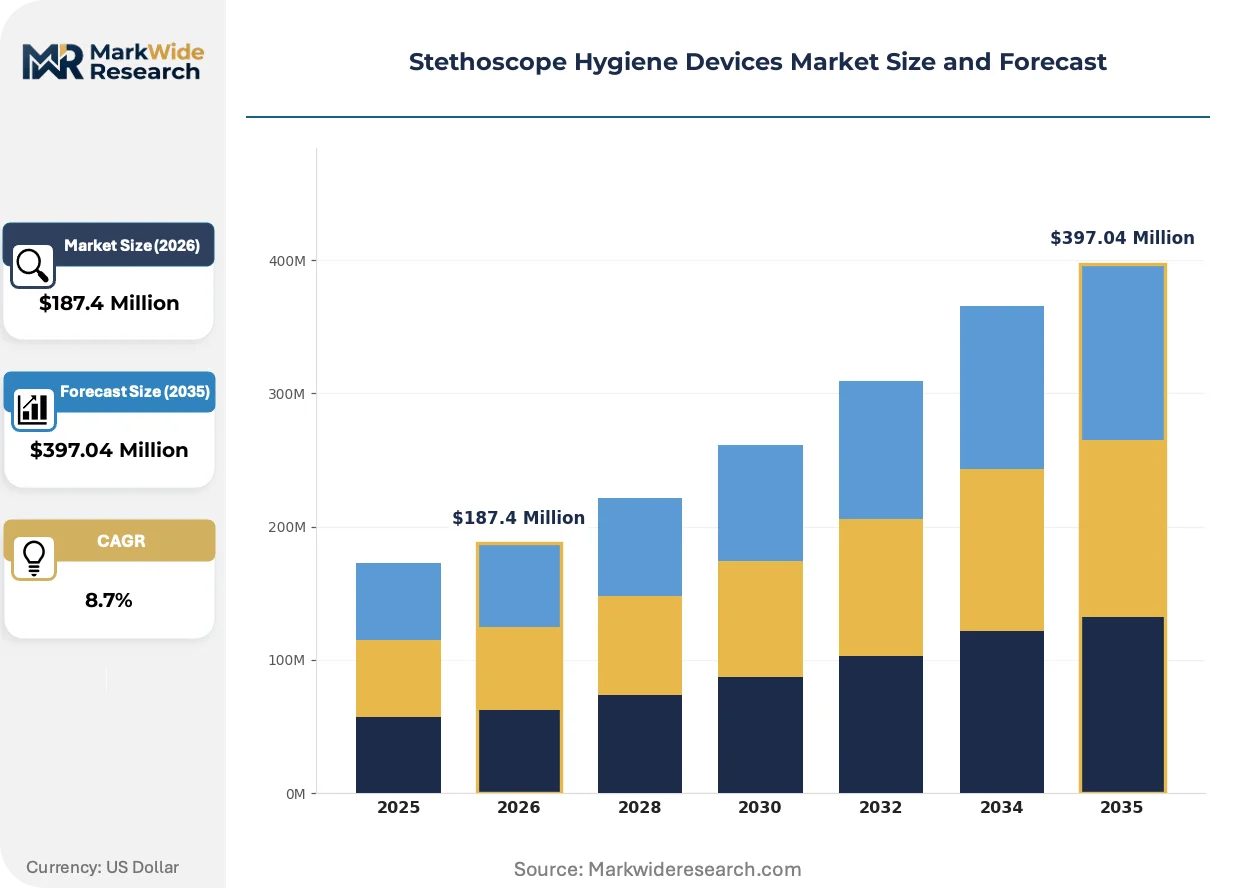
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultraviolet Sterilizers, Antimicrobial Covers, Cleaning Wipes, Disinfectant Sprays End User: Hospitals, Clinics, Nursing Homes, Home Care Providers Form Factor: Portable Devices, Stationary Units, Disposable Products, Reusable Items Technology: UV-C Light, Chemical Disinfection, Nanotechnology, Electromagnetic Fields |
| Companies Covered | Your First Services Inc., Edmund Optics, Xech, UV Smart, Parsons, LightProgress, Vioguard, Tangshan UMG Medical Instrument Co., Ltd., egoHealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stethoscope Hygiene Devices Market Evolving Landscape
Active innovation is compressing disinfection cycle times while expanding deployment flexibility beyond fixed infrastructure, reshaping how infection prevention programs integrate hygiene devices into clinical workflows.
UV-C LED arrays operating at 265-280 nanometers are supplanting mercury vapor lamps in next-generation sterilizers, achieving comparable log-reduction efficacy without warm-up latency or hazardous material disposal requirements. Emergency departments in large US health systems are piloting these solid-state units for 30-second turnaround between patient encounters. The technology is supplanting legacy cabinet architectures that required 5-10 minute cycles, enabling point-of-care deployment without throughput bottlenecks.
REACH restrictions on mercury-containing products are accelerating lamp technology transitions across European hospital procurement channels, with ECHA substance authorization timelines forcing manufacturers to redesign optical engines before 2027 compliance deadlines. German and French infection control committees are prioritizing LED-based systems in revised technical specifications. Nordic health systems are responding fastest, with Stockholm and Copenhagen hospital clusters completing fleet conversions ahead of continental adoption curves.
Health system buying consortia are consolidating vendor panels around outcome guarantees rather than equipment procurement, unbundling hardware from service contracts and demanding validated compliance reporting. Group purchasing organizations are displacing individual hospital negotiations, compressing price realization for manufacturers without scale. This concentration is most visible in the United States, where multi-state systems like Kaiser Permanente and CommonSpirit Health are standardizing single-source agreements across 100-plus facility networks.
Stethoscope Hygiene Devices Market Segmentation
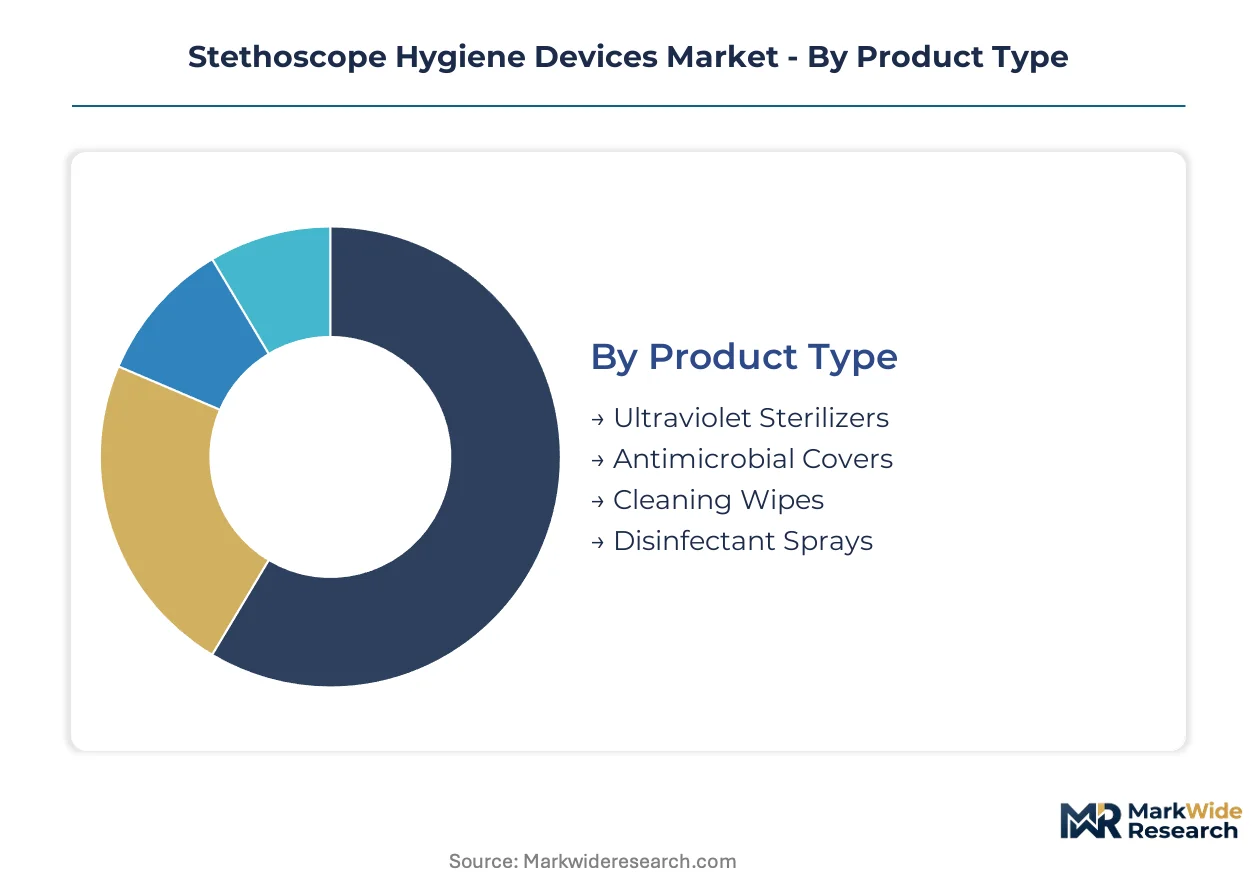
Product architecture and deployment context create divergent substitution pressures across the stethoscope hygiene devices market. Technology maturity, consumable versus capital expenditure models, and regulatory validation requirements fragment competitive positioning across each dimension.
Product Type:
Antimicrobial covers face the most acute substitution threat from automated sterilizers as health systems consolidate around reusable infrastructure and reduce disposable waste streams.
- Ultraviolet Sterilizers:Systems employing 254-nanometer mercury vapor or 265-280 nanometer LED arrays achieve validated 5-log bacterial reduction without consumable costs. Large US health systems including Kaiser Permanente are standardizing these across emergency departments and intensive care units to satisfy Joint Commission infection control standards.
- Antimicrobial Covers:Single-use polymer barriers impregnated with silver ion or triclosan formulations provide immediate physical isolation between patient encounters. Nursing homes in the United States prioritize these for single-patient assignment protocols where equipment turnover frequency exceeds automated cycle capacity.
- Cleaning Wipes:EPA-registered alcohol or quaternary ammonium formulations remain entrenched in outpatient clinics due to minimal capital requirements and established clinical workflows.
- Disinfectant Sprays:Aerosolized chemical formulations targeting rapid surface coverage compete primarily on per-application cost in resource-constrained settings.
Ultraviolet sterilizers anchor the volume base while antimicrobial covers gain share at the steepest rate among consumable categories.
End User:
Capital allocation authority and infection control liability exposure stratify demand intensity across care settings.
- Hospitals:Acute care facilities with dedicated infection prevention programs command premium pricing for validated 5-log reduction protocols and automated compliance documentation. CMS reimbursement linkages to hospital-acquired infection rates redirect capital budgets toward preventive technologies in emergency departments and intensive care units.
- Clinics:Outpatient settings with lower patient acuity and throughput constraints favor manual disinfection protocols and portable battery-powered units requiring no infrastructure retrofit.
- Nursing Homes:Long-term care facilities prioritize single-patient assignment protocols and disposable consumables to break fomite transmission between immunocompromised residents.
- Home Care Providers:Distributed care models with limited equipment standardization drive demand for low-cost chemical formulations and individual protective barriers.
Hospitals concentrate margin pools through outcome-based procurement while nursing homes expand volume fastest as regulatory scrutiny intensifies.
Form Factor:
Deployment flexibility versus throughput capacity shapes infrastructure investment decisions across facility vintages.
- Portable Devices:Battery-powered UV-C or chemical applicators enable bedside deployment in older hospital wings lacking dedicated disinfection stations. These units capture margin premiums where infrastructure retrofit costs exceed equipment acquisition.
- Stationary Units:Fixed cabinet architectures with automated cycle documentation serve high-throughput settings requiring validated compliance reporting for accreditation surveys.
- Disposable Products:Single-use covers and wipes eliminate cross-contamination risk without maintenance overhead or training requirements.
- Reusable Items:Durable sterilizer components and launderable barriers reduce per-use cost for high-frequency clinical environments.
Stationary units dominate installed base value while portable devices expand most quickly as fleet retrofit priorities shift toward point-of-care deployment.
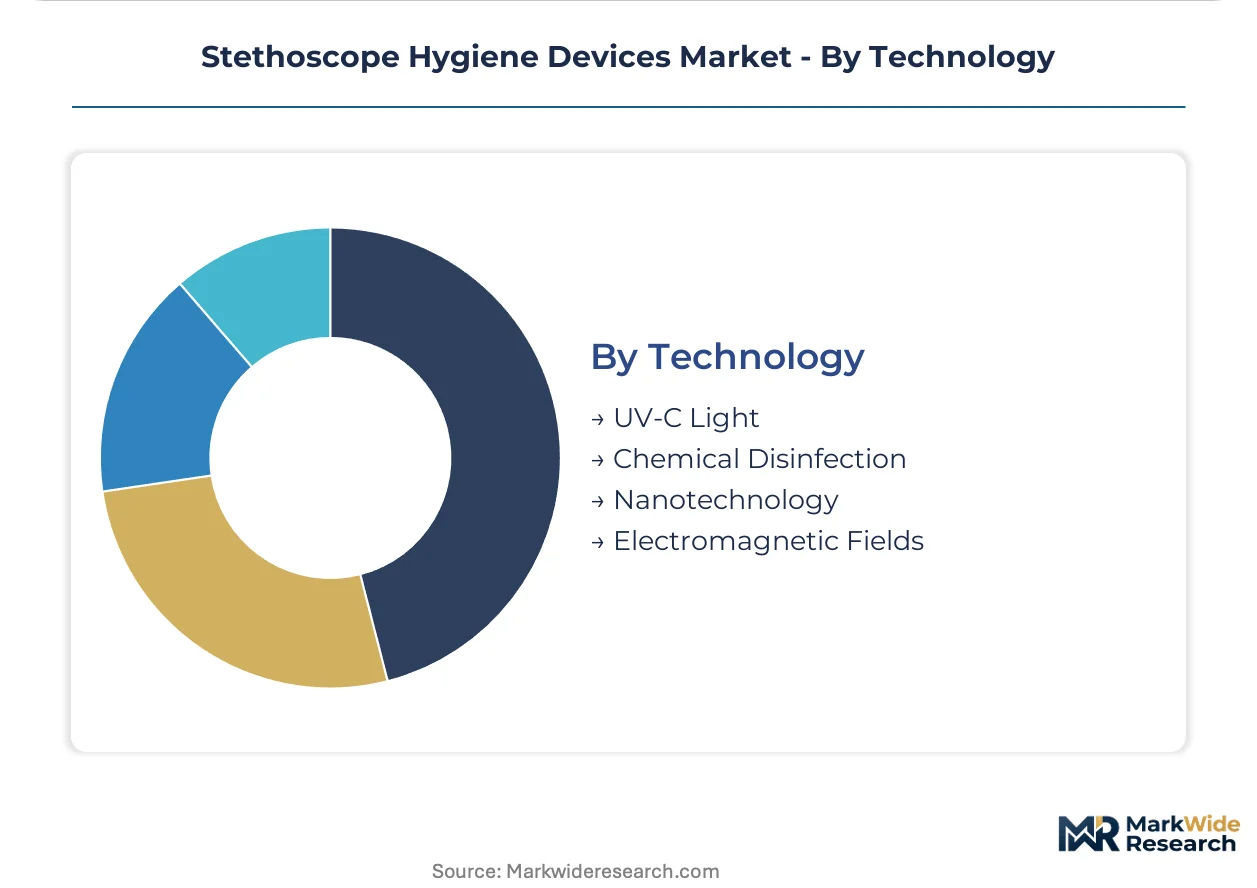
Technology:
Regulatory validation burden and material compatibility constraints segment competitive moats across disinfection modalities.
- UV-C Light:Mercury vapor lamps at 254 nanometers and emerging LED arrays at 265-280 nanometers achieve photolytic DNA damage without chemical residue. REACH restrictions on mercury-containing products are accelerating LED transitions across European hospital procurement channels ahead of 2027 compliance deadlines.
- Chemical Disinfection:EPA-registered formulations including alcohols, quaternary ammonium compounds, and hydrogen peroxide vapor require surface contact time validation and material compatibility testing.
- Nanotechnology:Silver ion and photocatalytic coatings provide persistent antimicrobial surfaces with reduced reapplication frequency.
- Electromagnetic Fields:Emerging non-thermal plasma and pulsed electric field technologies target rapid microbial inactivation without consumable chemistry.
UV-C light commands dominant revenue share while nanotechnology climbs the fastest as coating integration into disposable products accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UV-C lamp manufacturing clusters in East Asia create input vulnerability for sterilizer producers elsewhere. Demand concentrates in acute care facilities with dedicated infection prevention programs. Regulatory divergence across jurisdictions fragments compliance requirements for multinational vendors.
United States
Kaiser Permanente and CommonSpirit Health are standardizing single-source agreements across 100-plus facility networks. FDA enforcement of medical device cleaning validation tightens compliance timelines for reusable device manufacturers. Boston and New York hospital clusters pilot UV-C LED arrays for 30-second turnaround between patient encounters.
Germany
REACH restrictions on mercury-containing products accelerate lamp technology transitions ahead of 2027 deadlines. ECHA substance authorization timelines force manufacturers to redesign optical engines. Berlin and Munich infection control committees prioritize LED-based systems in revised technical specifications.
China
Domestic health system consolidation drives standardization of automated disinfection protocols in tertiary hospitals. NMPA medical device registration requirements elevate documentation burdens for imported sterilizers. Shanghai and Beijing medical device manufacturing zones expand production of 254-nanometer bulb components.
France
ANSM guidance on reusable medical device hygiene tightens validation requirements for hospital procurement. Paris hospital clusters complete fleet conversions to solid-state UV-C systems ahead of continental adoption curves. Lyon and Marseille emergency departments expand automated cabinet deployments.
Japan
METI initiatives on healthcare-associated infection reduction redirect capital budgets toward preventive technologies. PMDA quality management system inspections strain mid-tier engineering teams without prior medical device experience. Tokyo and Osaka hospital networks consolidate vendor relationships around validated 5-log reduction protocols.
Stethoscope Hygiene Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the stethoscope hygiene devices market. UV-C sterilizer specialists with ISO 13485-aligned quality systems command premium positioning in acute care procurement channels. Portable disinfection unit manufacturers compete on manufacturing scale and battery-powered deployment flexibility. Strategic moves concentrate on regulatory dossier expansion and geographic channel control rather than price-based competition.
Among ultraviolet sterilizer specialists, UV Smart and Vioguard exemplify divergent geographic anchoring strategies within the premium tier. Tangshan UMG Medical Instrument Co., Ltd. occupies a position representing manufacturing scale advantages in portable disinfection units. Edmund Optics and Xech sit within adjacent optical technology domains that inform sterilizer component supply relationships. Parsons and LightProgress represent European engineering heritage in UV-C system architecture.
| Leading Market Players |
|---|
| Your First Services Inc. |
| Edmund Optics |
| Xech |
| UV Smart |
| Parsons |
| LightProgress |
| Vioguard |
| Tangshan UMG Medical Instrument Co., Ltd. |
| egoHealth |
| Others |
Value Network & Pricing Analysis
Three-week lead times for 254-nanometer mercury vapor lamps from East Asian suppliers concentrate pricing power among sterilizer manufacturers with established inventory buffers, while buyers without long-term offtake agreements face spot-market volatility that compresses margin capture in the portable device tier.
Pricing Analysis
FDA medical device cleaning validation dictates the pricing tier structure across the stethoscope hygiene devices market. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified systems with documented MRSA efficacy from unvalidated chemical formulations. Cost compression in the economy tier is intensifying because outpatient clinics resist capital expenditure for automated infrastructure. Nursing homes exhibit highest price sensitivity due to disposable consumable volumes, while acute care hospitals prioritize compliance documentation over per-unit cost.
Supply Chain Analysis
China and Japan anchor 254-nanometer bulb manufacturing and UV-C LED component fabrication for stethoscope sterilizer producers. Supply chains draw from specialized glass envelope foundries, mercury amalgam processing facilities, and gallium nitride substrate growers. Single-source vulnerability concentrates in mercury lamp filament winding operations located in coastal Chinese manufacturing zones. Distribution runs through medical device distributors with GPO contracting relationships, hospital procurement consortia, and direct sales teams serving large health system accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stethoscope hygiene devices sit in early-cycle expansion as FDA enforcement tightens cleaning validation requirements and acute care facilities accelerate automated protocol adoption beyond manual wipe baselines.
For Market Incumbents: Secure regulatory dossier expansion into antimicrobial cover categories and battery-powered portable architectures before REACH mercury restrictions reshape lamp sourcing economics. Threat of UV-C LED substitution demands backward integration into solid-state optical engine design or captive supply agreements with gallium nitride foundries. Channel control through GPO sole-source contracts represents the critical defensive lever against price compression from manufacturing-scale competitors. For New Entrants and Emerging Players: EPA registration fast-track for novel quaternary ammonium formulations opens white-space penetration in nursing home disposable segments where automated cycle capacity constraints persist. Target home care provider networks with individual protective barrier products requiring minimal training overhead. Go-to-market execution through regional medical supply distributors with existing long-term care relationships accelerates shelf placement without direct hospital procurement committee navigation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory tailwind play because infection control liability exposure and CMS reimbursement linkages to hospital-acquired infection rates create durable budget allocation toward preventive technologies. Acquisition targets should display ISO 13485-aligned quality systems with established 5-log reduction validation dossiers rather than unproven technology platforms. Signal to monitor: Joint Commission survey citation frequency for stethoscope hygiene protocol deficiencies as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | REACH mercury restrictions accelerate LED-based system approvals ahead of ECHA deadlines. |
| Hospital System Partnership | Kaiser Permanente and CommonSpirit standardization creates reference account leverage for GPO expansion. |
| Software Companion Development | Automated compliance documentation satisfies Joint Commission survey requirements for accreditation maintenance. |
| FDA Submission | 510(k) clearance for UV-C LED arrays enables emergency department point-of-care deployment claims. |
| Reimbursement Strategy | CMS quality metric linkages to infection rates redirect capital budgets toward validated preventive technologies. |
Research Methodology
Desk research of FDA 510(k) filings, EPA disinfectant registration databases, and hospital GPO contract disclosures preceded structured interviews with infection prevention officers, biomedical engineering directors, and procurement committee members at large US health systems. Secondary validation drew from Joint Commission survey citation records, CMS hospital-acquired infection rate publications, and ECHA substance authorization timelines. Bottom-up unit demand modeling and top-down health system capital expenditure triangulation anchored volume estimates.
Variance decomposition across product type, end user facility tier, form factor deployment context, and technology modality shaped the analytical framework over the projection horizon. CAGRs derived from replacement cycle analysis of installed base aging, regulatory compliance deadline clustering, and health system consolidation patterns. Forecast inputs incorporated UV-C LED cost curve trajectories and REACH mercury restriction implementation phasing.
The analysis sits within stated boundaries; outcomes outside FDA enforcement continuity, EPA registration timeline stability, or CMS reimbursement metric persistence would require recalibration. Forecasts reflect documented assumptions regarding health system capital allocation prioritization and infection control liability exposure trends. Recalibration cycles align with material shifts in regulatory enforcement intensity, lamp technology substitution rates, and GPO vendor panel consolidation dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Treatment Pumps Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Gum Grafting Market
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Pectus Bar Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Global Wheelchair Market
Medical Devices
Digital Stethoscope Market
Medical Devices
China Diabetes Devices Market