
 Spinal Fusion Bone Graft Substitutes Market | 2026-2036
Spinal Fusion Bone Graft Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Fusion Bone Graft Substitutes Market Insights
Recurring software-defined surgical planning modules bundled with implant systems is shifting how vendors monetize spinal fusion workflows. Medtronic leverages its integrated navigation and biologics portfolio to lock in hospital system contracts. Stryker anchors its position through scale manufacturing of synthetic ceramic matrices. NuVasive differentiates via specialized expandable interbody devices paired with proprietary graft delivery systems.
Spinal fusion bone graft substitutes are osteoconductive, osteoinductive, or osteogenic materials—encompassing demineralized bone matrix, synthetic hydroxyapatite, beta-tricalcium phosphate, and recombinant human bone morphogenetic protein-2—engineered to promote vertebral arthrodesis when autograft supply proves insufficient. These materials must demonstrate compression resistance exceeding host bone remodeling rates and integrate within 12-24 month fusion windows validated by CT-based bridging criteria. Biologic grafts, particularly BMP-2 formulations, command premium positioning despite cost scrutiny, while ceramic segments compete on unit economics in high-volume hospital purchasing. Composite matrices combining mineral scaffold with collagen carrier represent the fastest-expanding category as surgeons seek handling properties absent in pure synthetics.
The FDA's 510(k) clearance framework and ongoing postmarket surveillance requirements under the Medical Device Reporting regulation govern product entry and sustain clinical evidence investment. The EU Medical Device Regulation imposes stricter notified body scrutiny on biologic-device combination products, compressing margin pools for European market participants. Stakeholders must monitor evolving CMS coverage determinations for bone morphogenetic proteins and synthetic grafts, as reimbursement granularity increasingly dictates site-of-service selection and product mix across hospital and ambulatory settings.
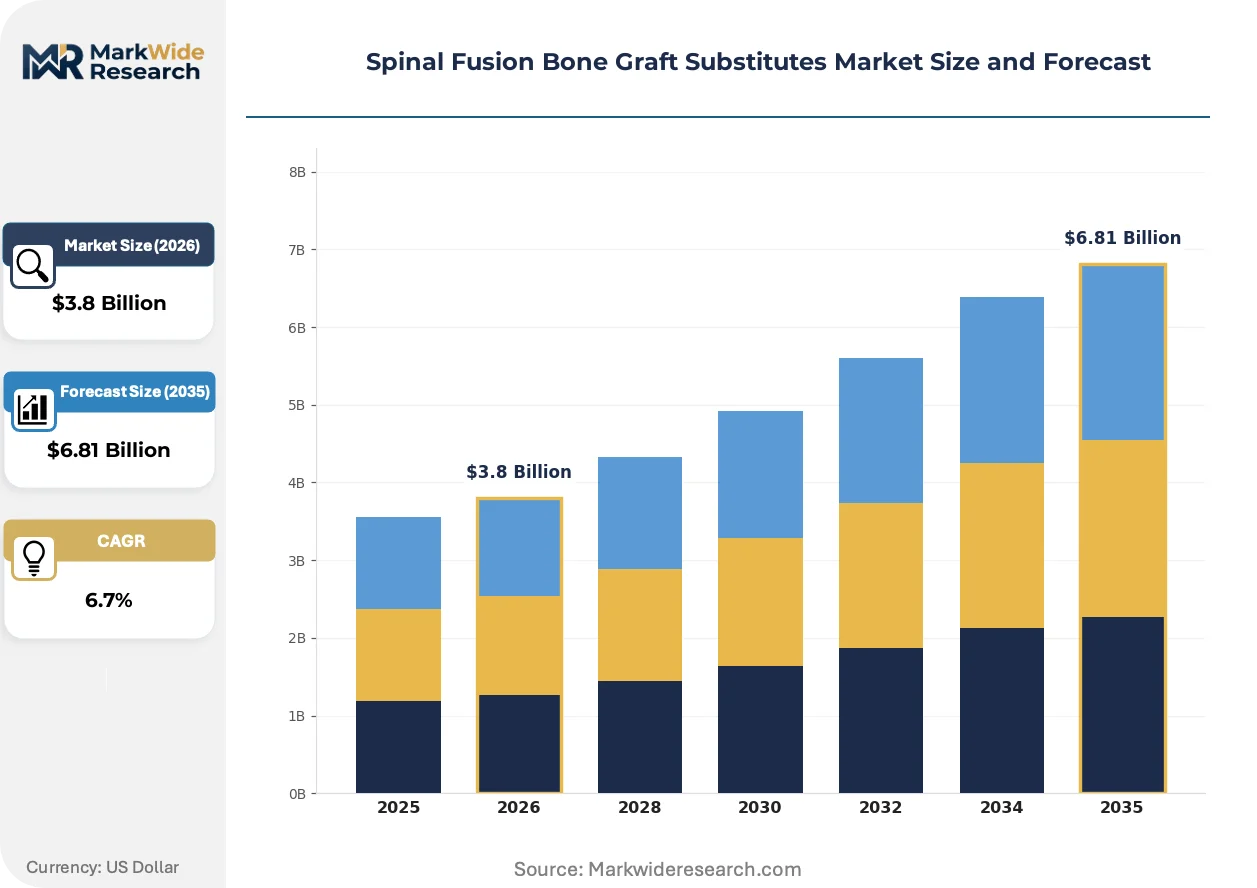
Market Dynamics
The spinal fusion bone graft substitutes market is being fundamentally restructured by the migration of procedures from inpatient hospital settings to ambulatory surgical centers, compressing pricing power while expanding addressable procedure volumes.
Growth Catalysts
- Aging demographics:The United States population over 65 years drives sustained demand for degenerative disc disease interventions requiring vertebral arthrodesis.
- 510(k) pathway efficiency:FDA premarket notification requirements enable faster synthetic ceramic and demineralized bone matrix clearances compared to biologics PMA routes.
- Minimally invasive technique diffusion:Surgeons in tertiary hospitals increasingly adopt expandable interbody devices that reduce autograft harvest morbidity.
Market Restraints
- BMP-2 cost containment:Commercial payers and CMS impose prior authorization requirements that limit recombinant protein utilization to complex deformity cases.
- Supply concentration:Beta-tricalcium phosphate precursor manufacturing clusters in China create raw material vulnerability for Western synthetic graft producers.
- Technical limitation:Pure hydroxyapatite scaffolds lack the handling characteristics surgeons require for posterior lumbar interbody fusion approaches.
Strategic Opportunities
- ASC site-of-service expansion:Outpatient cervical fusion procedures in United States ambulatory centers create demand for pre-packaged graft delivery systems.
- Composite matrix innovation:Mineral-collagen hybrid scaffolds address the handling gap between ceramics and allografts.
- EU MDR compliance leverage:Stricter notified body scrutiny on biologic-device combinations creates first-mover advantage for firms with established quality management systems.
Industry Challenges
- Fusion assessment standardization:Variability in CT-based bridging criteria across clinical sites complicates postmarket surveillance and evidence generation.
- Biologics manufacturing scale-up:BMP-2 production requires substantial capital investment in cell culture capacity to meet demand without batch failure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Fusion Bone Graft Substitutes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Metal, Biologic, Composite Application: Spinal Surgery, Orthopedic Surgery, Trauma Surgery, Revision Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Form: Paste, Putty, Block, Granules |
| Companies Covered | Medtronic, DePuy Synthes, Stryker, Zimmer Biomet, NuVasive, Baxter International, Smith & Nephew, AlloSource, Orthofix Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Fusion Bone Graft Substitutes Market Trends and Innovations
Software-defined surgical planning is collapsing the traditional separation between implant selection and graft material specification, forcing vendors to integrate biologics portfolios with navigation platforms.
Patient-specific 3D-printed titanium cages with integrated porous architectures are rewriting how surgeons approach multilevel fusions. Academic medical centers in the United States and Germany are adopting these constructs for complex deformity corrections. The technology is rewriting procurement patterns by bundling graft containment and structural support into single-use sterile devices that command premium reimbursement.
EU Medical Device Regulation notified body capacity constraints are extending biologic-device combination product review timelines. European manufacturers face compressed margin pools as conformity assessment costs rise. Synthetic graft categories with simpler classification routes are capturing share from demineralized bone matrix formulations in Germany and France.
Hospital value analysis committees now mandate head-to-head fusion rate data before approving bone morphogenetic protein contracts. Integrated delivery networks in Texas and Florida are consolidating vendor lists to three suppliers maximum. Site-of-service economics favor ceramic matrices in high-volume ASC settings where reimbursement granularity dictates product selection.
Spinal Fusion Bone Graft Substitutes Market Segmentation
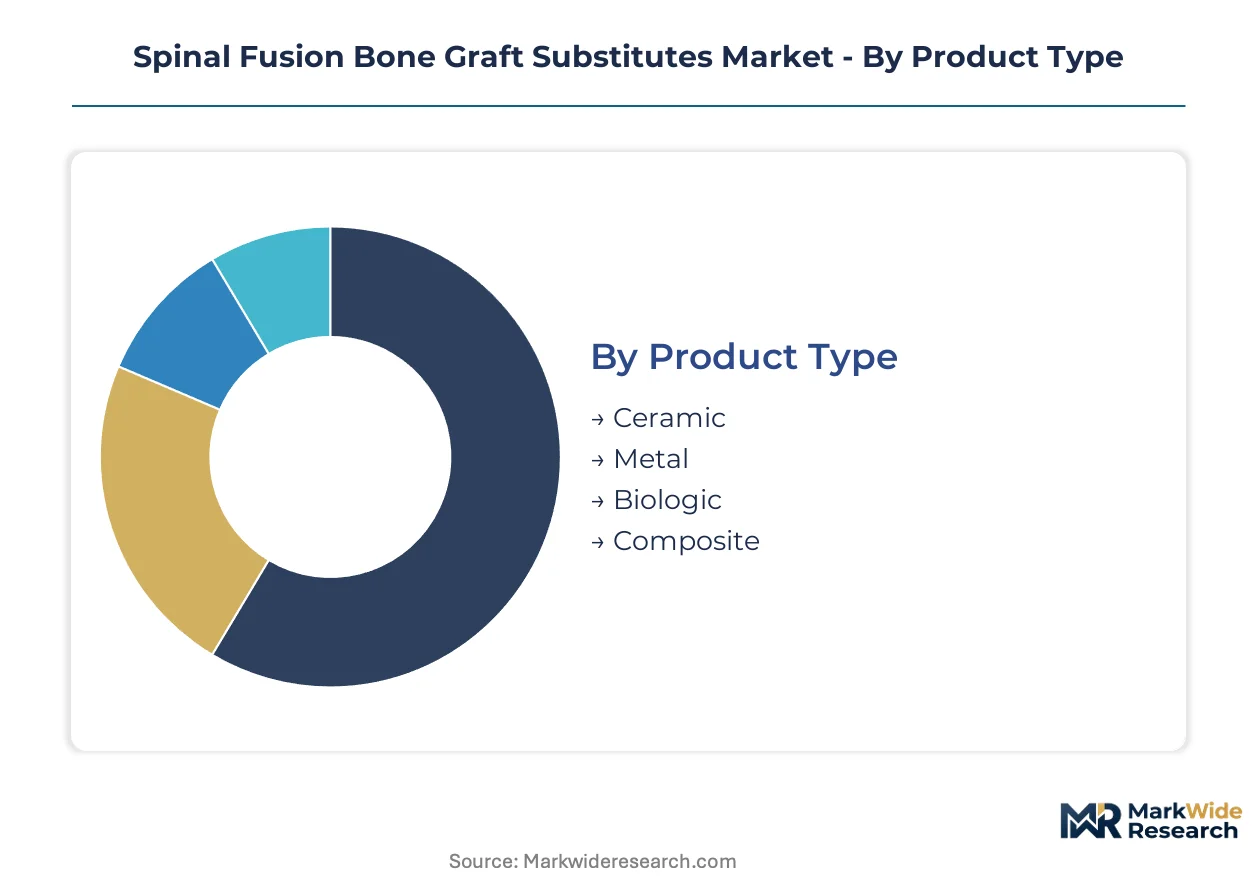
Segmentation in spinal fusion bone graft substitutes reveals how procurement committees, surgeons, and facility administrators prioritize distinct performance attributes. Product selection hinges on handling characteristics, fusion timelines, and site-of-service economics rather than unit cost alone.
Product Type:
Surgeon preference for handling properties and compression resistance drives category selection across anterior and posterior approaches.
- Ceramic:Synthetic hydroxyapatite and beta-tricalcium phosphate scaffolds provide osteoconductive lattice structures with tunable resorption rates. Demand concentrates in United States ambulatory surgical centers where reimbursement granularity favors cost-controlled synthetic options over biologics.
- Biologic:Demineralized bone matrix and recombinant human bone morphogenetic protein-2 deliver osteoinductive signaling proteins that accelerate fusion in osteoporotic bone. Complex deformity cases in tertiary United States hospitals sustain demand despite prior authorization requirements from commercial payers and CMS.
- Metal:Porous titanium and tantalum constructs serve as structural cages with integrated graft containment chambers.
- Composite:Mineral-collagen hybrid matrices combine ceramic compression resistance with allograft-like handling properties.
Volume sits with Ceramic; growth tilts toward Composite.
Application:
Procedure complexity and anatomical site dictate graft material specifications and reimbursement pathways.
- Spinal Surgery:Cervical and lumbar fusion procedures require materials demonstrating compression resistance exceeding host bone remodeling rates. United States hospital purchasing favors pre-packaged delivery systems for posterior lumbar interbody fusion where handling precision affects operative time.
- Revision Surgery:Pseudarthrosis corrections demand osteoinductive biologics to overcome compromised vascular beds and prior radiation exposure. Academic medical centers in Germany and the United States drive adoption of BMP-2 formulations for salvage fusions.
- Orthopedic Surgery:Long bone nonunions and joint arthrodesis procedures utilize ceramic granules and demineralized bone matrix.
- Trauma Surgery:Acute vertebral fractures and spinal column injuries require rapid-deployment graft options.
Spinal Surgery commands procedure volume; Revision Surgery shows the steepest expansion trajectory as aging hardware requires explantation.
End User:
Site-of-service migration is restructuring procurement authority and product mix across care settings.
- Hospitals:Tertiary centers maintain broad formulary access spanning biologics, ceramics, and composite matrices. Integrated delivery networks in Texas and Florida consolidate vendor lists to three suppliers maximum, demanding head-to-head fusion rate data before contract approval.
- Ambulatory Surgical Centers:Outpatient cervical fusion procedures create demand for pre-packaged graft delivery systems with simplified inventory management. United States ASC reimbursement granularity favors ceramic matrices and demineralized bone matrix over premium biologics.
- Specialty Clinics:Orthopedic spine practices with in-office procedure suites require small-format putty and paste options.
- Rehabilitation Centers:Post-acute facilities influence graft selection indirectly through readmission risk contracts.
Hospitals retain biologics volume; ASCs are gaining share fastest as outpatient cervical fusions expand.
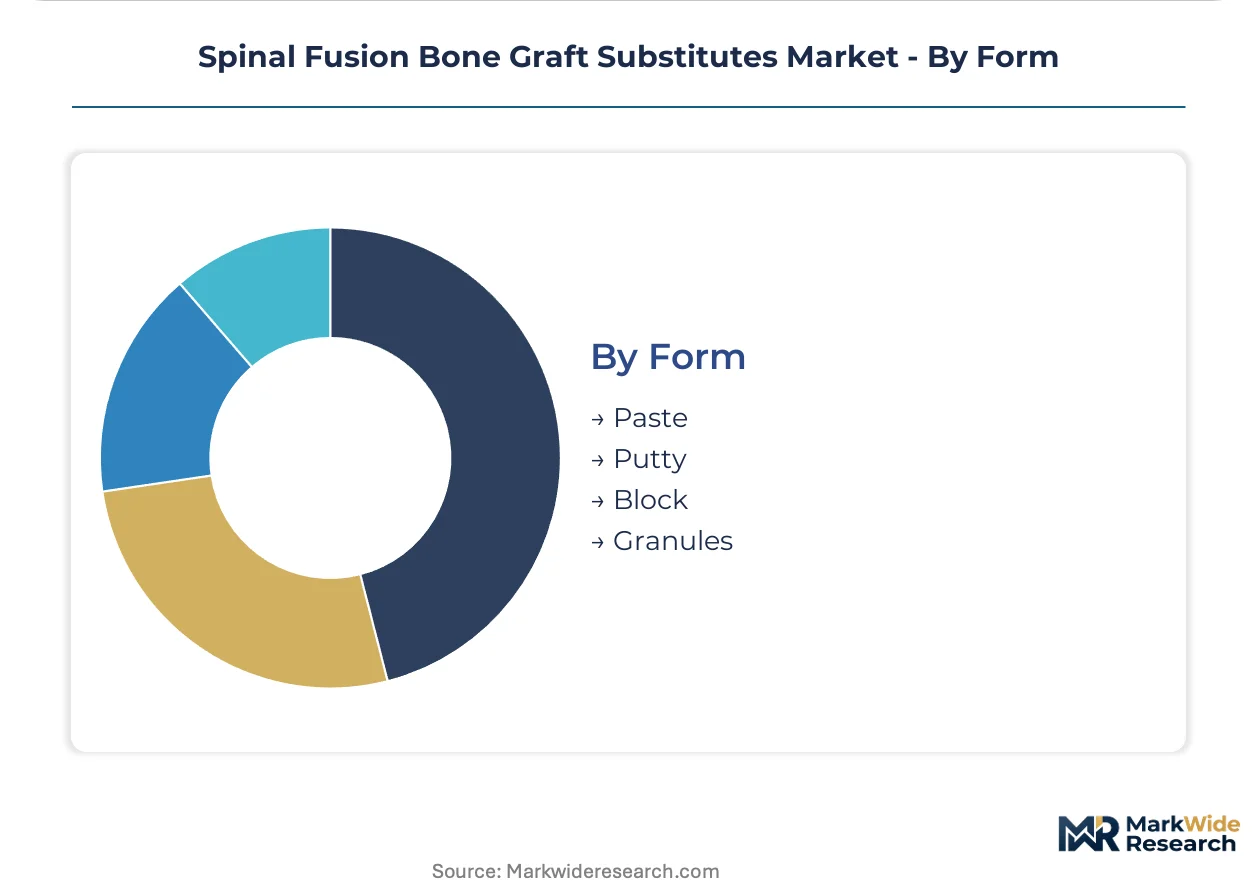
Form:
Handling characteristics and delivery method compatibility determine form selection by surgical approach.
- Putty:Moldable consistency suits posterior cervical and lumbar interbody fusion cages requiring precise contouring. Surgeons in United States academic centers prefer putty formulations for multilevel constructs where graft distribution uniformity affects fusion mass quality.
- Granules:Flowable particles enable minimally invasive delivery through expandable interbody device ports. Ambulatory surgical centers in Florida and Texas specify granule formats for reduced operative time and simplified sterilization workflows.
- Paste:Injectable consistency facilitates percutaneous vertebral augmentation and kyphoplasty adjunct procedures.
- Block:Pre-formed shapes provide structural support in corpectomy defects and multilevel anterior approaches.
Granules dominate high-volume throughput; Putty maintains premium positioning in deformity correction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of beta-tricalcium phosphate precursors concentrates in Chinese industrial zones, while consumption tilts toward United States tertiary hospitals and ambulatory surgical centers where reimbursement granularity shapes procurement. Germany and Japan anchor European and Asian demand through aging demographics and established spinal surgery infrastructure. Supply chain vulnerabilities emerge from this geographic split.
United States
Commercial payer coverage for minimally invasive spinal fusion and CMS reimbursement determinations for bone morphogenetic proteins sustain procedure volumes. FDA 510(k) premarket notification requirements enable faster synthetic ceramic clearances than biologics PMA routes. Integrated delivery networks in Texas and Florida consolidate vendor lists to three suppliers maximum, demanding head-to-head fusion rate data.
Germany
Academic medical centers in Bavaria and Baden-Württemberg drive adoption of BMP-2 formulations for complex deformity corrections and salvage fusions. EU Medical Device Regulation notified body scrutiny compresses margin pools for biologic-device combination products. Synthetic graft categories with simpler classification routes capture share from demineralized bone matrix formulations.
China
Domestic production of hydroxyapatite and beta-tricalcium phosphate precursors supplies Western manufacturers while local consumption rises with expanding hospital infrastructure. NMPA medical device registration requirements impose clinical evidence standards that extend product development timelines. Manufacturing clusters in Jiangsu and Zhejiang provinces face raw material vulnerability scrutiny from Western procurement committees.
Japan
PMDA regulatory frameworks and aging population demographics sustain demand for ceramic matrices in lumbar fusion procedures. METI industrial policy supports domestic production of synthetic bone graft substitutes. Tokyo and Osaka medical centers prioritize handling characteristics in posterior lumbar interbody fusion approaches.
Switzerland
Swissmedic oversight of biologic-device combinations maintains stringent quality management requirements for European market entry. Precision manufacturing capabilities in Basel and Zurich regions support specialized composite matrix production. Swiss orthopedic research institutions influence EU MDR implementation practices for spinal fusion products.
Spinal Fusion Bone Graft Substitutes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the spinal fusion bone graft substitutes market. Vertically integrated medical technology conglomerates with captive biologics manufacturing anchor the premium tier, while specialized ceramic producers and allograft processors occupy mid-market positions. Three archetypes dominate: diversified implant-biologics integrators, synthetic scaffold specialists, and tissue bank-derived matrix suppliers. Competitive moves concentrate on M&A to secure cell culture capacity and strategic partnerships to bundle graft delivery with navigation platforms.
Within the diversified integrator tier, Medtronic exemplifies the implant-biologics convergence model, while Stryker occupies a position emphasizing scale manufacturing of synthetic matrices. NuVasive represents the specialized interbody device category paired with proprietary graft delivery systems. These three anchors demonstrate how vendor consolidation around integrated surgical workflows is restructuring procurement authority in United States hospital systems and ambulatory surgical centers.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes |
| Stryker |
| Zimmer Biomet |
| NuVasive |
| Baxter International |
| Smith & Nephew |
| AlloSource |
| Orthofix Holdings |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery networks in Texas and Florida anchor procurement authority through three-supplier vendor consolidation, forcing contract-based long-term offtake pricing with head-to-head fusion rate data requirements. This buyer concentration shifts pricing power toward ceramic matrices in ambulatory surgical centers while biologics command premium positioning in tertiary hospital systems.
Pricing Analysis
Margin tightening in synthetic ceramic tiers reflects ASC reimbursement granularity favoring cost-controlled options over premium biologics. Three-tier pricing structure across premium BMP-2 formulations, standard demineralized bone matrix, and economy hydroxyapatite granules stratifies by osteoinductive potency and handling characteristics. Cost-down pressure on composite matrices accelerates because hospital value analysis committees mandate outcome documentation. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers in Germany and the United States show lowest sensitivity due to complex deformity case requirements.
Supply Chain Analysis
Direct-to-hospital channels handle biologics demand from integrated delivery networks, while distributor-mediated routes serve fragmented ambulatory surgical centers. Manufacturing of beta-tricalcium phosphate precursors concentrates in Jiangsu and Zhejiang provinces of China, with ceramic scaffold finishing in the United States and Germany. Raw material dependencies include recombinant cell culture media, collagen carriers from bovine sources, and mineral precursors. Single-source vulnerability in Chinese precursor supply creates exposure for Western synthetic graft producers. Distribution runs through specialized orthopedic distributors with cold-chain capabilities for biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
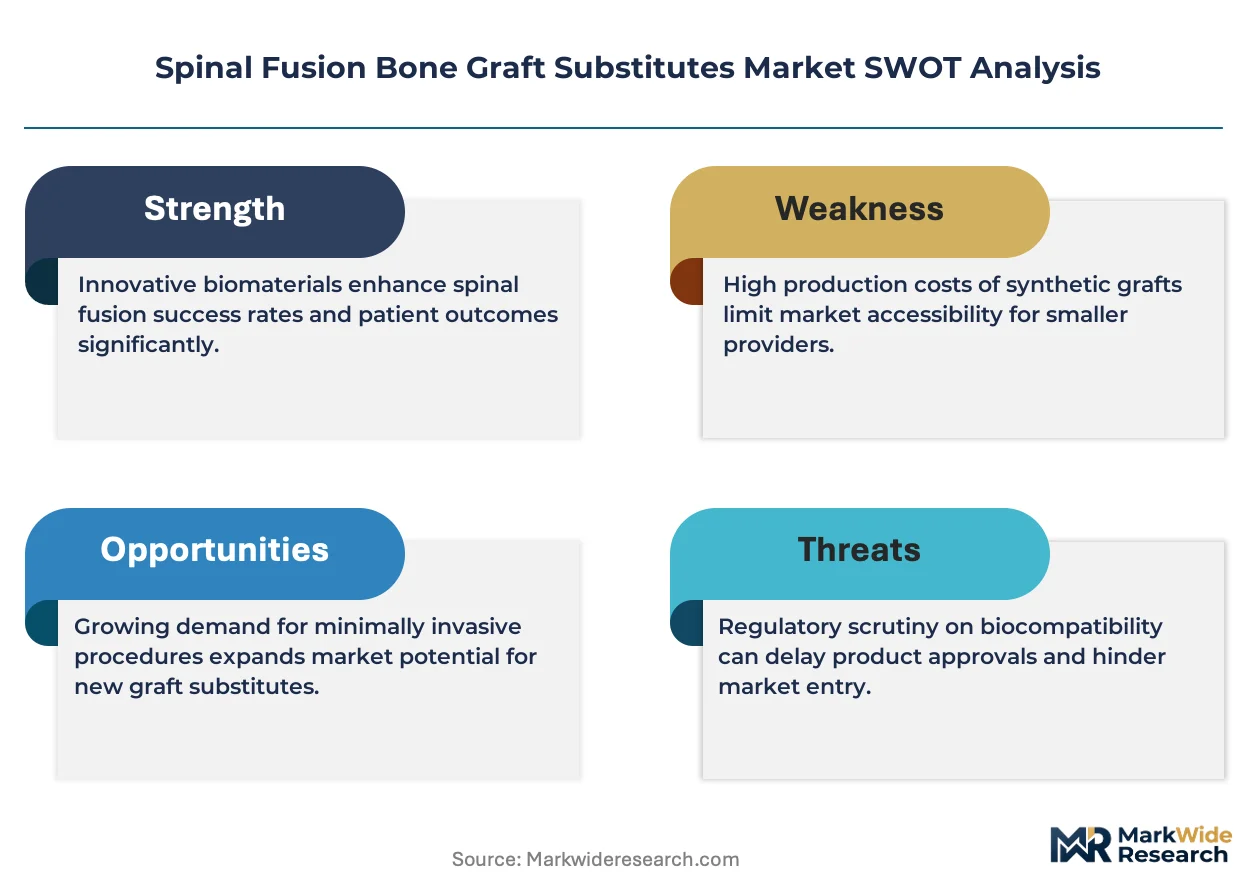
The spinal fusion bone graft substitutes market operates as a cost-of-compliance story where FDA 510(k) premarket notification requirements and EU MDR notified body scrutiny erect substantial barrier-to-entry moats favoring established quality management systems.
For Market Incumbents: Acquire cell culture manufacturing capacity to secure BMP-2 production without batch failure risk. Consolidate navigation platform partnerships to bundle graft delivery with surgical planning software, defending against specialized interbody device competitors. Prioritize backward integration into beta-tricalcium phosphate precursor supply to mitigate raw material vulnerability from Chinese manufacturing clusters.
For New Entrants and Emerging Players: Digital health platform partnerships offer de novo market access without capital-intensive biologics manufacturing. Target ambulatory surgical center procurement committees in Florida and Texas with pre-packaged ceramic granule delivery systems. Pursue white-space positioning in mineral-collagen composite matrices where handling gaps between pure ceramics and allografts remain unaddressed.
For Investors and Strategic Acquirers: The window for entry favors synthetic scaffold specialists with established FDA 510(k) clearance track records and EU MDR technical documentation capabilities. Long-term viability hinges on reimbursement strategy execution across CMS coverage determinations and commercial payer prior authorization pathways. Monitor hospital value analysis committee vendor consolidation velocity as inflection indicator for pricing power compression.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Stricter notified body scrutiny compresses margin pools for unprepared European market participants. |
| ASC-Specific Product Format Development | Pre-packaged graft delivery systems align with outpatient cervical fusion reimbursement granularity in United States ambulatory centers. |
| Navigation Platform Partnership | Software-defined surgical planning bundles collapse traditional separation between implant selection and graft material specification. |
| Cell Culture Capacity Expansion | BMP-2 production scale-up requires substantial capital investment to meet demand without batch failure. |
| Composite Matrix R&D Pipeline | Mineral-collagen hybrid scaffolds address handling gaps that limit pure ceramic adoption in posterior lumbar interbody fusion. |
Research Methodology
FDA 510(k) clearance databases, CMS coverage determination records, and EU MDR notified body guidance documents formed the secondary backbone for regulatory pathway analysis. Primary interviews with spine surgeons, hospital purchasing committee members, GPO contracts managers, and biologics manufacturing executives validated procurement pattern assumptions. Bottom-up and top-down triangulation reconciled procedure volume estimates with product-level pricing intelligence across ceramic, biologic, and composite matrix categories.
Bottom-up modeling anchored volume projections to ambulatory surgical center expansion rates and minimally invasive technique diffusion curves across the analysis window. Segmentation dimensions included product type, application complexity, end-user site-of-service, and surgical approach form factor. CAGRs were derived from regression analysis against aging demographic drivers and reimbursement policy trajectories. Forecast inputs incorporated hospital value analysis committee vendor consolidation velocity and EU MDR conformity assessment timeline extensions.
The model holds under stable FDA 510(k) pathway efficiency and CMS reimbursement continuity; deviation in prior authorization stringency or raw material trade restrictions would shift synthetic versus biologics mix assumptions. Periodic stress-testing of base assumptions is recommended given supply chain concentration in Chinese precursor manufacturing and evolving commercial payer coverage policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Global Angiography Devices Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Inversion Table Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Cervical Dilators Market