
 Non-Invasive Pulse Oximeter Market | 2026-2036
Non-Invasive Pulse Oximeter Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Pulse Oximeter Market Insights
ISO 80601-2-61 certification for pulse oximeter basic safety and essential performance is bifurcating the competitive landscape between established manufacturers and new entrants. Masimo leverages proprietary signal extraction technology to sustain premium positioning in hospital-critical care segments. Nonin Medical anchors its presence in ruggedized and veterinary-adjacent applications where durability standards exceed consumer-grade requirements. CONTEC MEDICAL SYSTEMS CO., LTD competes aggressively on manufacturing scale, dominating cost-sensitive procurement channels across emerging markets.
A non-invasive pulse oximeter measures arterial oxygen saturation and pulse rate through light absorption at specific wavelengths, typically employing dual LEDs at approximately 660 nm (red) and 940 nm (infrared) with a photodiode detector to compute the ratio of oxygenated to deoxygenated hemoglobin. The device serves continuous patient monitoring in clinical triage, perioperative care, chronic disease management, and athletic performance assessment without requiring arterial puncture. Finger pulse oximeters occupy the largest volume tier due to portability and low unit cost, though wrist pulse oximeters are capturing expanded sleep apnea and overnight monitoring applications. Tabletop pulse oximeters retain the highest margin pools in surgical suites and neonatal intensive care units where multi-parameter integration commands premium pricing.
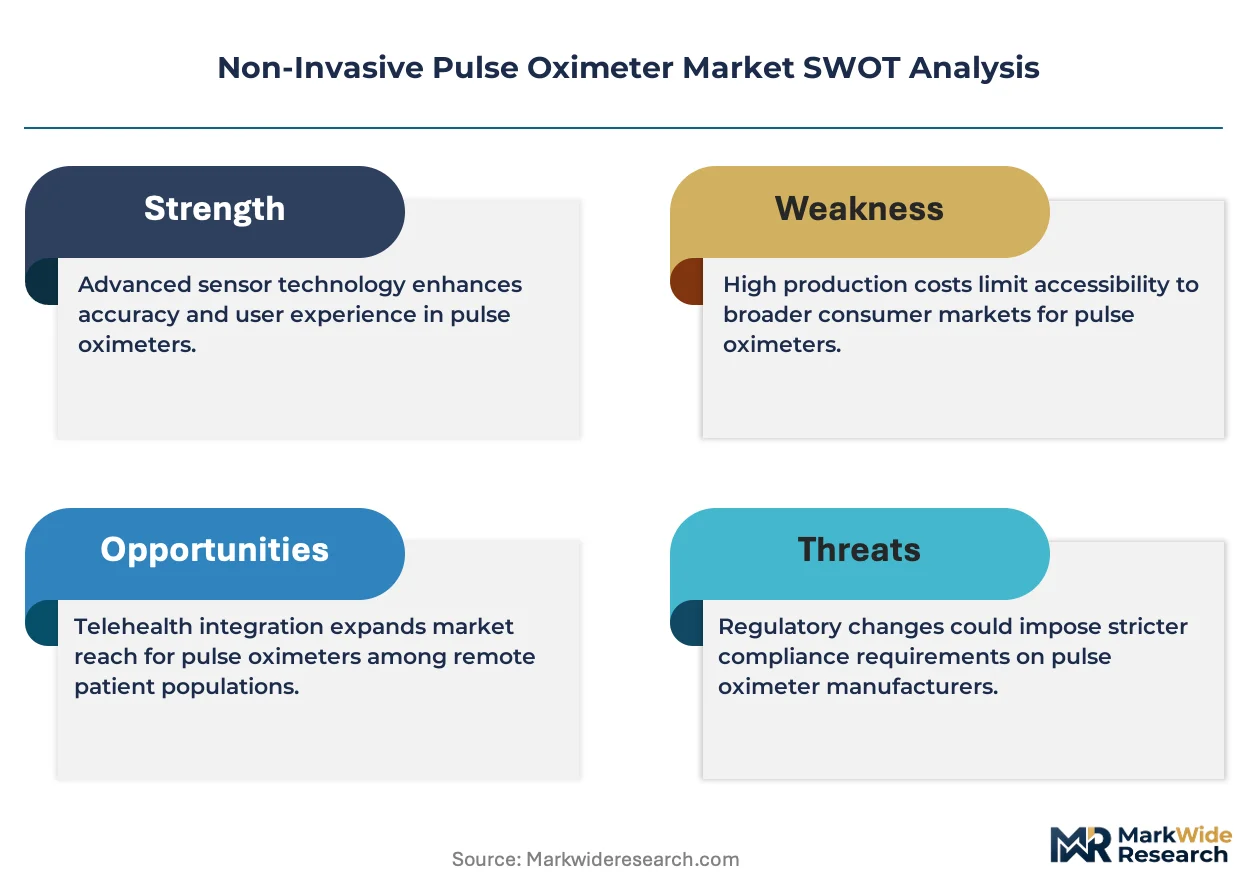
The FDA governs 510(k) clearance pathways for pulse oximeter market entry in the United States, while the EU Medical Device Regulation mandates updated clinical evidence and post-market surveillance for CE marking continuity in European markets. Japan's PMDA enforces JIS T 0601-1 collateral standards that create additional conformance burdens for manufacturers targeting hospital procurement in that geography. Stakeholders must monitor regulatory divergence between accuracy validation requirements and emerging skin pigmentation correction mandates that could necessitate hardware redesigns or algorithmic updates across product portfolios.
Market Dynamics
ISO 80601-2-61 certification requirements are compressing development timelines while bifurcating competitive positioning between established manufacturers with validated quality systems and new entrants facing capital-intensive conformance burdens.
Growth Catalysts
- Home Care Migration:Chronic respiratory patients in the United States seek continuous monitoring outside institutional settings, expanding addressable demand beyond acute care facilities.
- Reimbursement Clarity:CMS coding specificity for remote patient monitoring creates predictable procurement economics for durable medical equipment suppliers.
- Signal Processing Advances:Proprietary motion artifact rejection algorithms enable reliable readings during ambulatory use cases previously requiring stationary monitoring.
Market Restraints
- Component Concentration:Photodiode and LED supply chains concentrate in East Asian semiconductor foundries, exposing manufacturers to single-source vulnerability.
- Accuracy Limitations:Perfusion index dependency and motion sensitivity constrain clinical utility in low-perfusion states and pediatric populations.
- Regulatory Divergence:JIS T 0601-1 collateral standards in Japan impose additional conformance testing not harmonized with IEC 60601-2-61 baselines.
Strategic Opportunities
- Sleep Apnea Expansion:Overnight oxygen desaturation monitoring in Germany and France creates demand for wrist-worn form factors with extended battery life.
- Veterinary Adjacencies:Ruggedized designs developed for equine and companion animal applications command premium pricing in specialty veterinary clinics.
- Algorithmic Differentiation:Skin pigmentation correction mandates under FDA premarket guidance create first-mover advantage for validated multi-wavelength systems.
Industry Challenges
- Biomedical Engineering Scarcity:Signal processing and optical sensor design expertise concentrates in legacy patient monitoring firms, constraining startup hiring pipelines.
- 510(k) Timeline Compression:FDA substantive review periods for Class II pulse oximeters extend unpredictably when predicate device equivalence is contested.
- Legacy System Interoperability:HL7 FHIR integration requirements for hospital information systems demand software engineering capacity absent in hardware-centric manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Pulse Oximeter Market |
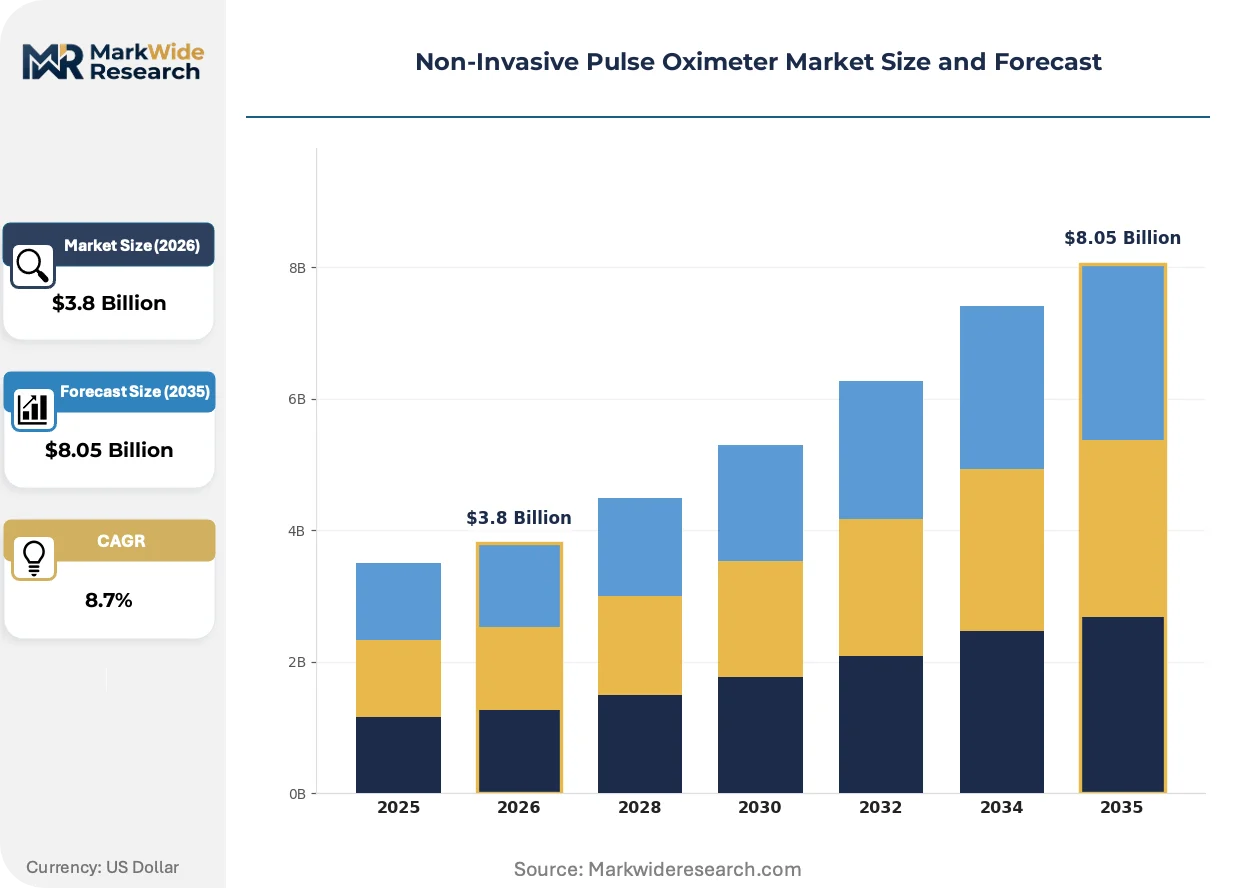
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Finger Pulse Oximeters, Handheld Pulse Oximeters, Tabletop Pulse Oximeters, Wrist Pulse Oximeters Technology: Infrared, Red Light, Dual Wave, Reflectance End User: Hospitals, Home Care, Clinics, Sports Facilities Distribution Channel: Online Retail, Offline Retail, Medical Supply Stores, Distributors |
| Companies Covered | Medtronic, Masimo, Koninklijke Philips N.V., Nonin Medical, GE HealthCare, Nihon Kohden Corporation, Drägerwerk AG & Co. KGaA, ICU Medical, CONTEC MEDICAL SYSTEMS CO., LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Pulse Oximeter Market Trends and Innovations
Multi-parameter integration and algorithmic personalization are compressing the distinction between consumer wellness devices and clinical-grade monitors, forcing strategic repositioning across the value chain.
Reflectance-mode pulse oximetry is decomposing the historical monopoly of transmissive finger-clip designs in neonatal intensive care. Manufacturers serving premature infant populations adopt forehead and foot sensors to circumvent poor peripheral perfusion. This shift is decomposing established form factor standards and opening margin pools previously captured by invasive arterial line monitoring.
The EU Medical Device Regulation's updated clinical evidence requirements for CE marking continuity are extending post-market surveillance obligations across European markets. Manufacturers must maintain proactive vigilance systems rather than reactive complaint handling. Class IIa pulse oximeter portfolios face the steepest compliance cost escalation as notified body capacity constrains review throughput.
Direct-to-consumer distribution through pharmacy retail chains and telehealth platforms is compressing traditional durable medical equipment dealer networks. Sleep apnea screening programs in the United States increasingly bypass respiratory therapy suppliers. This channel rotation is most visible in Medicare Advantage populations where remote monitoring incentives align with home delivery logistics.
Non-Invasive Pulse Oximeter Market Segmentation
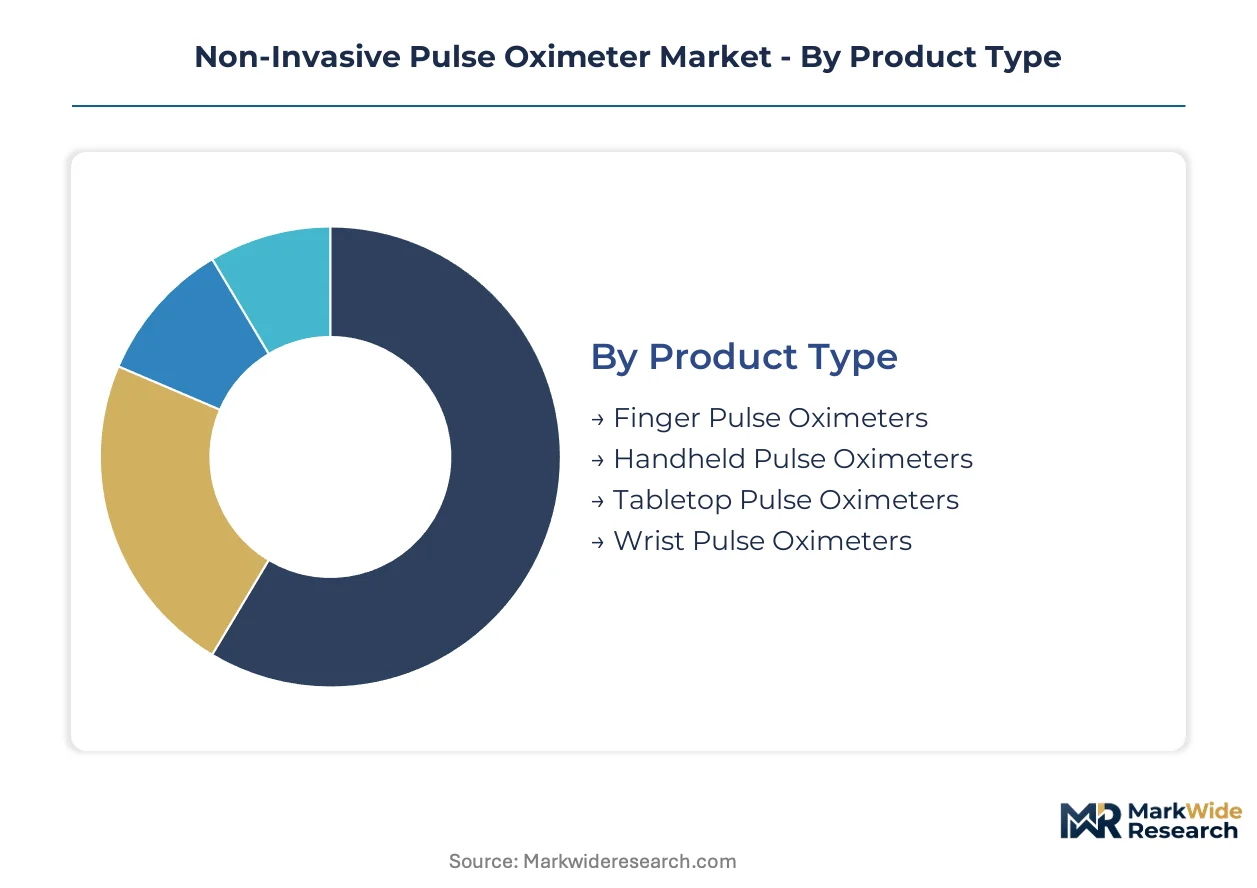
Non-invasive pulse oximeter purchasing decisions fragment across clinical certification tiers, patient mobility requirements, and reimbursement eligibility. Each segment carries distinct margin profiles and regulatory conformance burdens that reshape manufacturer portfolio priorities.
Product Type:
FDA 510(k) clearance pathways diverge sharply between consumer-grade finger clips and multi-parameter tabletop systems requiring IEC 60601-2-61 validation.
- Finger Pulse Oximeters:Compact transmissive devices employing dual LEDs at 660 nm and 940 nm wavelengths dominate home care procurement in the United States. CMS remote patient monitoring reimbursement codes sustain volume economics for durable medical equipment suppliers serving chronic respiratory populations.
- Tabletop Pulse Oximeters:Multi-parameter integration with ECG and capnography capabilities commands premium positioning in surgical suites and neonatal intensive care units. JIS T 0601-1 collateral standards in Japan impose additional conformance testing that filters out consumer-grade competitors.
- Handheld Pulse Oximeters:Battery-operated portable units bridge emergency medical services and clinic triage workflows.
- Wrist Pulse Oximeters:Reflectance-mode sensors capture overnight oxygen desaturation patterns for sleep apnea screening programs.
Finger pulse oximeters handle the majority of throughput; wrist pulse oximeters are climbing the fastest on share.
Technology:
Optical wavelength selection determines clinical accuracy validation requirements and algorithmic patent positioning.
- Dual Wave:Simultaneous 660 nm red and 940 nm infrared emission enables ratio-of-ratios computation for arterial oxygen saturation. ISO 80601-2-61 certification mandates for this configuration bifurcate the competitive landscape between established manufacturers and capital-constrained entrants.
- Reflectance:Forehead and foot sensor placements circumvent poor peripheral perfusion in neonatal and low-flow states. PMDA enforcement of JIS standards in Japanese hospital procurement creates first-mover advantage for validated reflectance systems.
- Infrared:Single-wavelength systems target cost-sensitive consumer wellness applications with reduced clinical claims.
- Red Light:Narrowband emission supports specialized veterinary and research applications.
Dual wave configurations anchor hospital-critical care procurement; reflectance technology is expanding most quickly into neonatal segments.
End User:
Reimbursement clarity and clinical liability exposure segment demand across institutional and non-institutional settings.
- Hospitals:Acute care facilities require IEC 60601-1-11 compliance for electromagnetic immunity and alarm systems integration. FDA premarket notification timelines extend unpredictably when predicate device equivalence is contested for multi-parameter systems.
- Home Care:Chronic respiratory patients in the United States seek continuous monitoring outside institutional environments. Medicare Advantage remote monitoring incentives align with direct-to-consumer distribution through pharmacy retail chains.
- Clinics:Outpatient facilities balance portability requirements against diagnostic accuracy standards.
- Sports Facilities:Athletic performance assessment applications prioritize motion artifact rejection over clinical-grade precision.
Hospitals concentrate the highest-margin procurement; home care is gaining share fastest among end user categories.
Distribution Channel:
Channel configuration determines warranty liability, technical support obligations, and price transparency exposure.
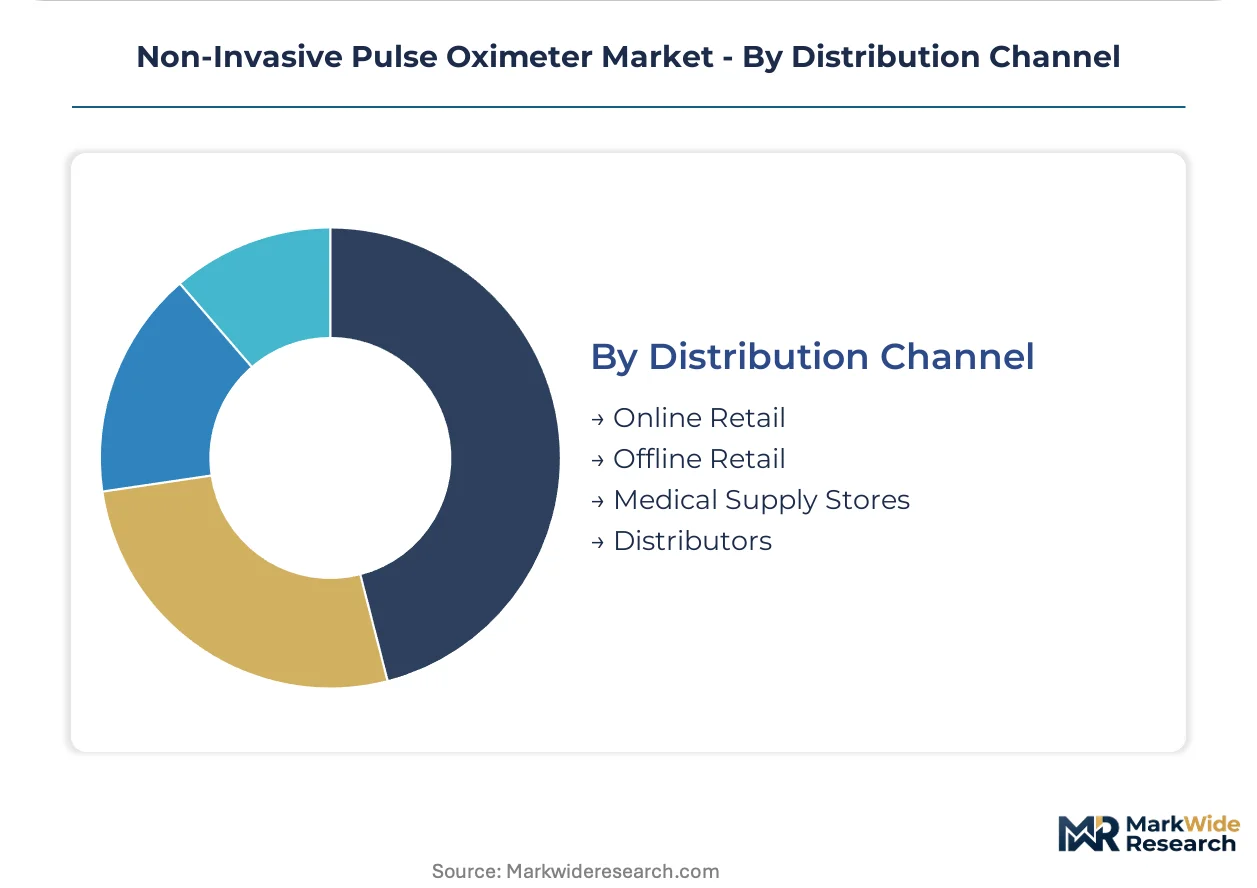
- Medical Supply Stores:Specialized durable medical equipment dealers maintain technical staff for device calibration and patient education. Reimbursement documentation requirements in the United States sustain this channel's relevance despite direct-to-consumer compression.
- Online Retail:Pharmacy retail chains and telehealth platforms bypass traditional dealer networks. Sleep apnea screening programs increasingly leverage home delivery logistics aligned with remote monitoring incentives.
- Offline Retail:General merchandise and electronics retailers serve wellness-oriented consumers with limited clinical accuracy expectations.
- Distributors:Multi-line medical device wholesalers aggregate procurement for hospital systems and integrated delivery networks.
Medical supply stores retain the highest service-margin capture; online retail is expanding most quickly on volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific semiconductor and photodiode supply chains that feed pulse oximeter manufacturing clusters across North America and Asia.
United States
Chronic respiratory disease prevalence and Medicare Advantage remote monitoring incentives drive procurement volume. FDA 510(k) clearance pathways govern Class II device market entry with evolving premarket notification requirements. Minneapolis-St. Paul hosts durable medical equipment distribution networks serving home care migration trends.
Germany
Sleep apnea screening programs and overnight oxygen desaturation monitoring expand wrist-worn device demand. EU Medical Device Regulation mandates updated clinical evidence and post-market surveillance for CE marking continuity. Munich medical technology clusters concentrate multi-parameter system development for surgical suite applications.
Japan
Hospital procurement standards and aging demographics sustain premium device demand. PMDA enforces JIS T 0601-1 collateral standards creating additional conformance burdens for foreign manufacturers. Tokyo-Osaka industrial corridors host neonatal intensive care equipment specialists developing reflectance-mode sensors.
China
Manufacturing scale advantages and cost-sensitive procurement channels dominate emerging market supply. NMPA medical device registration requirements filter market entry for imported systems. Shenzhen semiconductor foundries concentrate photodiode and LED component production with single-source vulnerability exposure.
India
Expanding chronic disease management infrastructure and pharmacy retail chain growth enable direct-to-consumer distribution expansion. CDSCO medical device rules govern import licensing and quality standards enforcement. Bangalore medical device clusters develop signal processing algorithms for motion artifact rejection in ambulatory use cases.
Non-Invasive Pulse Oximeter Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and geographic reach. The competitive structure concentrates around three to five dominant platforms with ISO 80601-2-61 validated quality systems, while mid-scale manufacturers occupy cost-sensitive procurement channels. Strategic archetypes include proprietary signal extraction technology holders, ruggedized durability specialists, and manufacturing scale-driven commodity suppliers. Capacity expansion and algorithmic differentiation represent the dominant competitive moves reshaping positioning.
Among technology-differentiated specialists, Masimo occupies a position exemplifying proprietary signal extraction architecture, while Nonin Medical represents ruggedized design archetypes serving veterinary-adjacent applications. CONTEC MEDICAL SYSTEMS CO., LTD anchors the manufacturing scale tier, competing aggressively on production volume across emerging market procurement channels.
| Leading Market Players |
|---|
| Medtronic |
| Masimo |
| Koninklijke Philips N.V. |
| Nonin Medical |
| GE HealthCare |
| Nihon Kohden Corporation |
| Drägerwerk AG & Co. KGaA |
| ICU Medical |
| CONTEC MEDICAL SYSTEMS CO., LTD |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day photodiode lead times from Shenzhen semiconductor foundries concentrate procurement leverage among manufacturers with validated ISO 80601-2-61 quality systems, compressing margin pools for entrants lacking volume-commitment contracts with East Asian LED suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multi-parameter tabletop systems from IEC-validated handheld units and unregulated consumer finger clips. Price differentiation hinges on certification grade and after-sales calibration service bundling. Cost compression in the economy tier is intensifying because CONTEC MEDICAL SYSTEMS CO., LTD and manufacturing-scale competitors flood emerging market channels. Hospital procurement committees demonstrate lowest price sensitivity; direct-to-consumer pharmacy retail buyers exhibit highest elasticity.
Supply Chain Analysis
Inventory buffers of 45-60 days for infrared LEDs and silicon photodiodes reflect single-source vulnerability concentrated in China, Taiwan, and South Korea. Component sourcing draws from Shenzhen semiconductor foundries, Taoyuan optoelectronics fabs, and Seoul LED packaging houses. Tariff exposure on photodiode imports threatens margin stability for US-assembled devices. Distribution runs through multi-line medical device wholesalers serving hospital systems and integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomedical engineering talent scarcity—particularly signal processing and optical sensor design expertise—constrains competitive entry and sustains premium positioning for incumbents with captive R&D pipelines.
For Market Incumbents: Shield margin pools in hospital-critical care segments by deepening backward integration into photodiode specification control and accelerating FDA premarket notification submissions for multi-wavelength skin pigmentation correction algorithms. Motion artifact rejection patent portfolios represent the critical defensive asset against consumer-grade entrants. For New Entrants and Emerging Players: Algorithmic personalization services for sleep apnea screening programs in Germany and France expose incumbent under-service in overnight monitoring data analytics. Telehealth platform partnerships offer the most penetrable go-to-market angle, bypassing entrenched durable medical equipment dealer networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded pulse oximeter divisions lacking ISO 80601-2-61 certification investment discipline. Long-term viability favors specialists with validated reflectance-mode neonatal portfolios and software engineering capacity for HL7 FHIR integration. Watch FDA premarket guidance on skin pigmentation correction as the inflection signal for hardware redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification timelines compress competitive windows for algorithmic differentiation. |
| CE Marking Pathway Investment | EU Medical Device Regulation clinical evidence requirements filter out undercapitalized entrants. |
| Hospital System Partnership | GPO contracts with integrated delivery networks lock in multi-parameter system procurement. |
| Software Companion Development | HL7 FHIR integration capabilities satisfy hospital information system interoperability mandates. |
| Reimbursement Strategy | CMS remote patient monitoring coding specificity creates predictable procurement economics. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and durable medical equipment procurement leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, CMS reimbursement coding records, and EU notified body CE marking registries. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product type, technology configuration, end-user setting, and distribution channel throughout the forecast period. CAGRs derived from logistic curve fitting to historical penetration data, calibrated against chronic respiratory disease prevalence trajectories and Medicare Advantage remote monitoring incentive expansion. Forecast inputs incorporated ISO 80601-2-61 certification adoption curves and photodiode supply chain lead-time volatility.
Material uncertainties—regulatory divergence on skin pigmentation correction mandates, single-source photodiode supply disruption, and FDA substantive review period extension—sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Medical Loupes Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Inversion Table Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
North America Laser Hair Removal Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Patient Warming Devices Market
Medical Devices
EEG Amplifiers Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Global Automated Suturing Devices Market