
 India Drug Delivery Devices Market | 2026-2036
India Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Drug Delivery Devices Market Foresight
Domestic contract manufacturers in Gujarat and Maharashtra is pivoting toward higher-value injection systems and wearable pumps. Becton, Dickinson and Company leverages its global catheter expertise to sustain leadership in vascular access devices across Indian hospitals. Cipla Ltd anchors the respiratory segment through specialized inhaler production tailored to local asthma prevalence. Novo Nordisk India Pvt Ltd dominates insulin pen supply with manufacturing operations positioned for diabetes care expansion.
Drug delivery devices encompass engineered systems that administer therapeutic agents through controlled release mechanisms, incorporating specifications such as 0.5-3 mL dose accuracy for injectors and 1-5 μm particle size for pulmonary deposition in inhalers. These devices serve to optimize bioavailability, ensure patient compliance, and enable self-administration across chronic disease management. Injectable pumps and smart drug delivery systems capture expanding margin pools as hospitals upgrade infusion technology, while inhalers retain volume leadership through respiratory disease burden. Transdermal patches and microneedle platforms represent faster-growing niches driven by pediatric and geriatric adherence requirements.
CDSCO enforces Medical Device Rules 2017 with risk-based classification, while BIS mandates IS 13485 alignment for quality management systems and the PLI scheme incentivizes domestic manufacturing scale-up. These frameworks elevate compliance costs for importers while creating protected demand channels for certified local producers. Stakeholders must monitor CDSCO's transition to full medical device regulation from the current phased implementation to anticipate licensing timelines and competitive positioning shifts.
Market Dynamics
CDSCO's phased transition to full medical device regulation under the Medical Device Rules 2017 is compressing licensing timelines and forcing domestic manufacturers to accelerate quality system upgrades ahead of importers losing grandfathered status.
Growth Catalysts
- Homecare settings:Chronic disease patients in Tier-2 and Tier-3 cities are adopting self-injection devices and portable inhalers as hospital capacity constraints persist.
- PLI scheme incentives:The Production Linked Incentive scheme for medical devices is channeling capital toward high-value injection systems and wearable pump manufacturing in Gujarat.
- Respiratory disease burden:Asthma and COPD prevalence in urban Maharashtra and Karnataka is sustaining inhaler volume demand through specialized local production.
Market Restraints
- Polymer import dependency:Medical-grade polycarbonate and specialized elastomers for pen injectors face volatile landed costs and forex exposure.
- Single-source component risk:Precision microneedle arrays and microfluidic chips concentrate with Taiwanese and German suppliers, creating vulnerability.
- CDSCO classification friction:Risk-based device categorization under Medical Device Rules 2017 delays novel transdermal patch approvals versus legacy injectables.
Strategic Opportunities
- Kerala and Tamil Nadu homecare penetration:Geriatric diabetes populations in southern states remain underserved by insulin pen distribution networks.
- Smart connectivity convergence:Bluetooth-enabled dose trackers paired with disposable injectors is opening adherence-data monetization channels.
- BIS certification acceleration:IS 13485 quality management alignment creates protected procurement channels for certified domestic producers in government hospital tenders.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993-compliant toxicology and sterilization validation facilities in India face 6-9 month queues, throttling product launches.
- Legacy hospital procurement inertia:Public sector tendering systems favor established catheter and infusion pump suppliers, complicating novel device vendor onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Drug Delivery Devices Market |
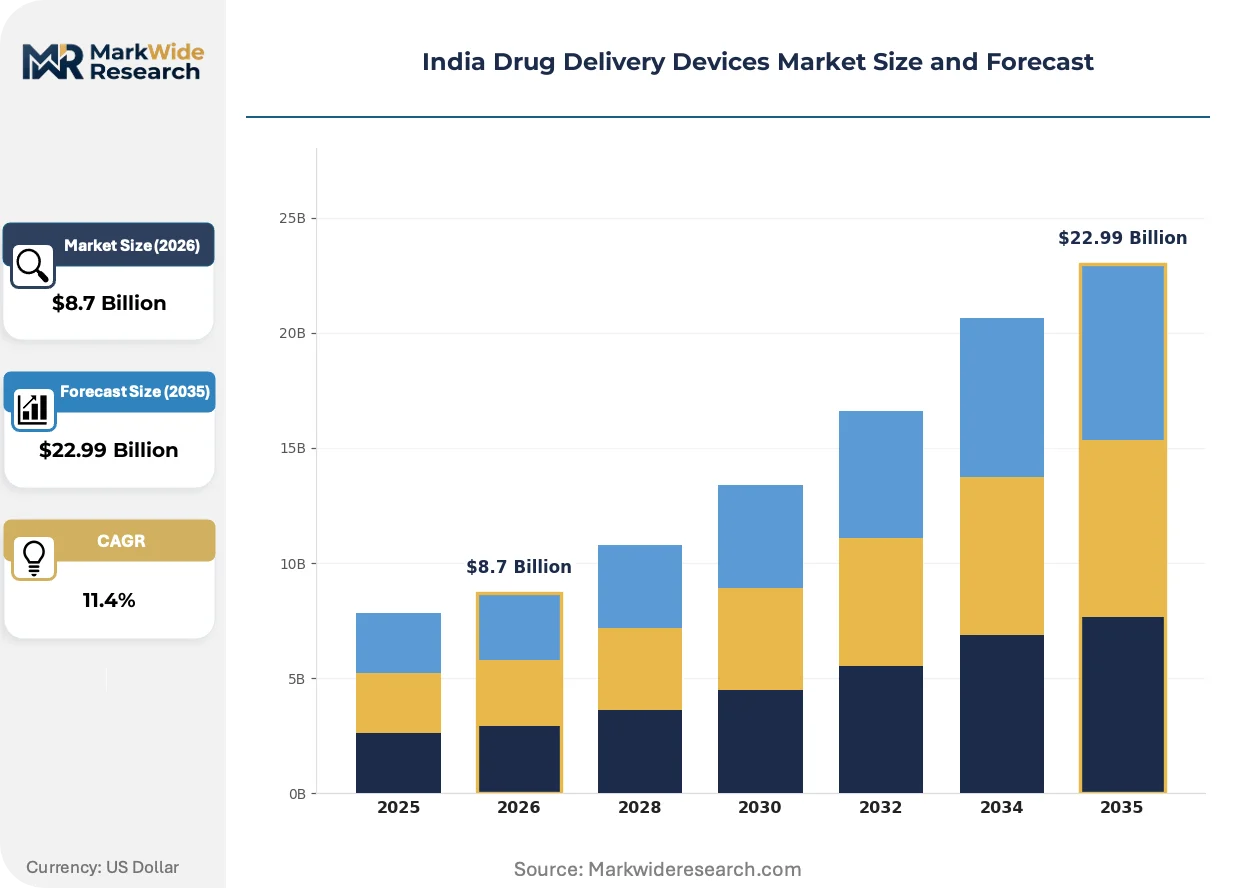
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Inhalers, Injectors, Transdermal Patches End User: Hospitals, Clinics, Homecare, Pharmacies Technology: Microneedles, Smart Drug Delivery, Biodegradable Systems, Nanotechnology Application: Chronic Diseases, Pain Management, Vaccination, Diabetes Care |
| Companies Covered | Medtronic Plc, Cipla Ltd, Becton, Dickinson and Company, Sun Pharmaceutical Industries Ltd, Novo Nordisk India Pvt Ltd, Stryker Corp, Johnson & Johnson Services, Inc, F. Hoffmann-La Roche Ltd, Novartis AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Drug Delivery Devices Market Shifts & Advancements
Microneedle platforms and connected injection systems are displacing conventional hypodermic delivery in chronic care, while regulatory data requirements and procurement digitization reshape competitive entry paths.
Wearable bolus injectors with pre-filled drug cartridges is expanding into oncology and autoimmune therapy administration previously confined to clinical settings. Large hospital chains in Delhi-NCR and Mumbai are piloting these devices for chemotherapy regimens. This shift is expanding into ambulatory care cost structures and compressing infusion center utilization rates.
CDSCO's 2024 guidance on software-as-medical-device classification is forcing connected inhaler and pump manufacturers to submit cybersecurity documentation alongside biocompatibility dossiers. Domestic developers in Bengaluru and Hyderabad are restructuring quality management systems to accommodate this dual validation burden. The respiratory and diabetes device segments face the steepest compliance cost escalation as they integrate dose-tracking applications.
Hospital buying committees are unbundling device procurement from pharmaceutical supply contracts that historically bundled inhalers and insulin pens with drug volume commitments. Standalone device tenders now dominate Maharashtra and Karnataka public health procurement, enabling specialized manufacturers to compete without molecule alliances. This pattern is most visible in government medical college hospitals transitioning to e-tendering platforms under central procurement mandates.
India Drug Delivery Devices Market Segmentation
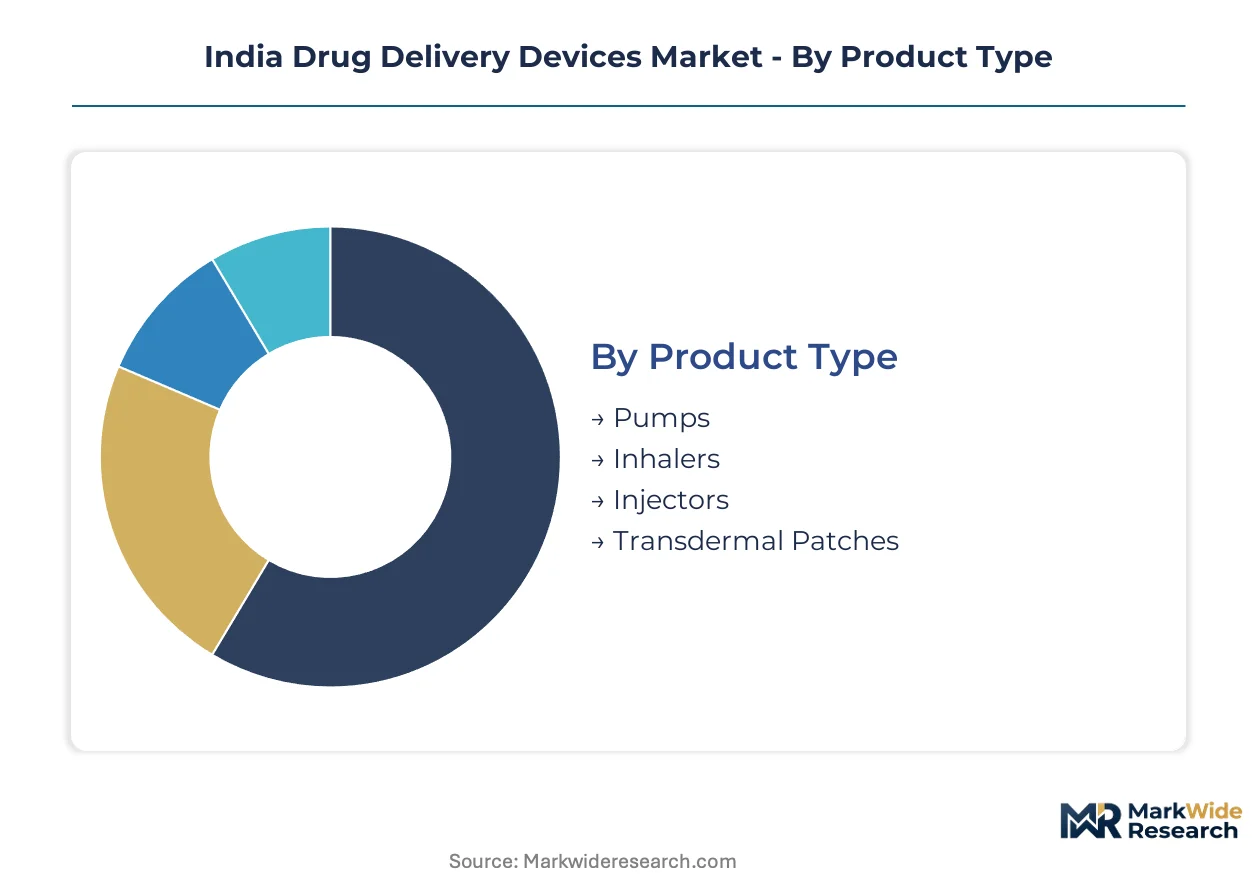
Device architecture determines integration depth across India's healthcare infrastructure. Pumps and inhalers anchor hospital procurement, while portable formats penetrate homecare settings where CDSCO's risk-based classification shapes approval pathways.
Product Type:
Standalone devices dominate acute care workflows, whereas embedded systems with pre-filled cartridges are penetrating ambulatory oncology and autoimmune therapy administration.
- Inhalers:Metered-dose and dry-powder configurations deliver 1-5 μm particle sizes for pulmonary deposition. Maharashtra and Karnataka hospitals sustain volume demand through specialized local production aligned with asthma prevalence in urban clusters.
- Injectors:Pen injectors and autoinjectors achieve 0.5-3 mL dose accuracy for insulin and biologic administration. Tier-2 and Tier-3 cities are adopting self-injection formats as hospital capacity constraints persist and homecare expands.
- Pumps:Infusion and wearable bolus systems administer controlled therapeutic release in oncology regimens.
- Transdermal Patches:Matrix and reservoir designs enable passive drug absorption for chronic pain and motion sickness management.
Inhalers lead volumes today; injectors are gaining share fastest.
End User:
Procurement authority concentrates with institutional buyers, though patient-directed purchasing is rising in diabetes and respiratory segments.
- Hospitals:Large chains in Delhi-NCR and Mumbai drive infusion pump and smart device adoption through centralized technology committees. CDSCO's Medical Device Rules 2017 compliance requirements filter vendor pools in government medical college tenders.
- Homecare:Geriatric diabetes populations in Kerala and Tamil Nadu remain underserved by insulin pen distribution networks. Portable inhalers and disposable injectors penetrate this channel as self-administration training programs expand.
- Clinics:Specialist outpatient settings in Gujarat and Maharashtra administer vaccination and pain management devices.
- Pharmacies:Retail channels distribute over-the-counter transdermal patches and basic inhaler formats.
Hospitals capture the dominant procurement value; homecare demonstrates the steepest expansion trajectory.
Technology:
Cost tiers separate mature platforms from emerging modalities facing biocompatibility validation queues.
- Smart Drug Delivery:Bluetooth-enabled dose trackers paired with disposable injectors open adherence-data monetization channels. CDSCO's 2024 software-as-medical-device guidance forces cybersecurity documentation alongside biocompatibility dossiers, escalating compliance costs for respiratory and diabetes segments.
- Microneedles:Dissolvable and hydrogel-forming arrays enable painless transdermal administration for pediatric and geriatric populations. ISO 10993-compliant toxicology facilities in India face 6-9 month validation queues, throttling product launches.
- Biodegradable Systems:PLGA and chitosan-based carriers eliminate retrieval procedures in implantable applications.
- Nanotechnology:Liposomal and polymeric nanoparticles enhance bioavailability for oncology and central nervous system targeting.
Smart connectivity leads current revenue concentration; microneedle platforms are climbing the fastest.
Application:
Volume distribution aligns with chronic disease burden geography and reimbursement policy coverage.
- Diabetes Care:Insulin pen and pump demand concentrates in southern states with aging demographics. Novo Nordisk's India manufacturing operations position for care expansion as PLI scheme incentives channel capital toward high-value injection systems.
- Chronic Diseases:Asthma and COPD inhaler requirements sustain production in pharmaceutical clusters. Cipla's specialized manufacturing anchors this segment through local formulation expertise.
- Pain Management:Transdermal opioid and non-opioid patches serve palliative and post-operative protocols.
- Vaccination:Prefilled syringes and needle-free injectors support immunization program scale-up.
Diabetes care leads installed base value; chronic disease applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing manufacturing capacity toward states with streamlined CDSCO licensing and PLI scheme disbursement timelines, compressing the cost-of-compliance gap between established pharmaceutical clusters and emerging production zones.
Maharashtra
Mumbai-Pune pharmaceutical corridors sustain inhaler and infusion pump production through concentrated formulation expertise. CDSCO's Medical Device Rules 2017 implementation in this zone accelerates quality system certifications for export-oriented manufacturers. Nashik and Aurangabad industrial estates are absorbing capacity spillover as Mumbai land costs escalate.
Gujarat
Ahmedabad-Vadodara chemical processing infrastructure supports medical-grade polymer compounding for pen injectors and autoinjectors. The state's PLI scheme administrative efficiency channels capital toward high-value injection systems faster than competing jurisdictions. Sanand and Vapi special economic zones concentrate contract manufacturing for multinational device licensors.
Karnataka
Bengaluru's medical technology engineering pool enables smart drug delivery firmware development alongside hardware production. CDSCO's software-as-medical-device guidance forces local developers to restructure quality management systems for dual validation. Mysuru and Mangaluru host secondary manufacturing for precision-molded components serving the Bengaluru design ecosystem.
Tamil Nadu
Chennai's automotive plastics suppliers are retooling for medical-grade polycarbonate molding to serve insulin pen housing demand. The state's geriatric diabetes population remains underserved by distribution networks, creating procurement channel opportunities. Coimbatore precision engineering clusters are entering microneedle array tooling subcontracting.
Delhi-NCR
Gurugram and Noida host headquarters functions for multinational device marketers while relying on external manufacturing. Central government hospital procurement mandates under e-tendering platforms concentrate buying authority here, influencing vendor qualification standards. Faridabad metalworking capabilities support surgical instrument integration with drug delivery systems.
India Drug Delivery Devices Market Competitive Landscape
Western India producers anchor the contract manufacturing tier; European and North American specialists hold premium branded device positions through technology licensing arrangements. The market structures around three participant layers: multinational marketers with India-registered subsidiaries, domestic pharmaceutical companies with device divisions, and pure-play contract manufacturers serving both categories. Consolidation pressure operates through CDSCO licensing cost escalation favoring scaled quality system investments over fragmented local assembly.
Within the multinational marketer tier, Becton, Dickinson and Company and Novo Nordisk India Pvt Ltd occupy positions defined by vascular access and diabetes care specialization respectively. Cipla Ltd represents the domestic pharmaceutical-integrated archetype, leveraging respiratory formulation expertise into device co-development. These three anchors exemplify how molecule-device bundling is unbundling under standalone tender rules, forcing strategic repositioning across procurement channels.
| Leading Market Players |
|---|
| Medtronic Plc |
| Cipla Ltd |
| Becton, Dickinson and Company |
| Sun Pharmaceutical Industries Ltd |
| Novo Nordisk India Pvt Ltd |
| Stryker Corp |
| Johnson & Johnson Services, Inc |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Standalone device tenders under CDSCO's unbundled procurement mandates are compressing distributor margins and forcing manufacturers to absorb certification cost escalations directly. This channel shift rewards domestic producers with BIS IS 13485 alignment while squeezing import-dependent vendors facing polymer cost volatility.
Pricing Analysis
Distributor margins in government medical college procurement have compressed from traditional pharma-device bundled structures to standalone device tenders. Pricing stratifies across IS 13485-certified premium tiers, BIS-compliant standard tiers, and uncertified economy imports. Cost compression in the economy tier is intensifying because polymer import dependency exposes landed cost volatility. Government hospital buying committees demonstrate highest price sensitivity; large private hospital chains in Delhi-NCR show lowest sensitivity due to technology committee preference for smart connectivity features.
Supply Chain Analysis
CDSCO's risk-based classification and BIS certification gating concentrates component sourcing with Taiwan, Germany, and South Korea for precision microneedle arrays and microfluidic chips. Medical-grade polycarbonate and specialized elastomers for pen injectors draw from petrochemical hubs in Saudi Arabia, Singapore, and Belgium. Single-source vulnerability concentrates in Taiwanese semiconductor foundries supplying dose-tracking firmware. Distribution runs through Gujarat and Maharashtra contract manufacturing clusters before final assembly in Bengaluru and Chennai medical technology zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on PLI scheme absorption of quality system upgrade costs and the premium-tier shift toward Bluetooth-enabled adherence trackers. Domestic certification acceleration creates protected procurement channels that sustain pricing power against import competition.
For Market Incumbents: Cement leadership in vascular access and diabetes care segments through backward integration into medical-grade polymer compounding in Gujarat. Acquire ISO 10993-compliant toxicology capacity to bypass 6-9 month biocompatibility validation queues throttling competitor launches. Defend against emerging smart connectivity entrants by locking hospital system partnerships before CDSCO's software-as-medical-device guidance fully phases in.
For New Entrants and Emerging Players: Launch via Kerala and Tamil Nadu insulin pen distribution networks where geriatric diabetes populations remain underserved by existing channels. Target microneedle platform development for pediatric and geriatric adherence requirements as the fastest-climbing technology tier. Pursue contract manufacturing relationships with Ahmedabad-Vadodara chemical processing infrastructure to access PLI scheme capital efficiency.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic contract manufacturers pivoting toward high-value injection systems and wearable pumps. The 5-10 year viability window favors scaled quality system investments over fragmented local assembly as CDSCO licensing cost escalation accelerates consolidation. Watch CDSCO's transition to full medical device regulation from phased implementation as the inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Medical Device Rules Compliance Acceleration | IS 13485 alignment creates protected government tender channels against import competition. |
| PLI Scheme Capital Absorption | Gujarat's administrative efficiency channels investment toward high-value injection systems faster than rival states. |
| Smart Connectivity Firmware Development | Bengaluru engineering pools enable Bluetooth dose trackers that open adherence-data monetization channels. |
| Biocompatibility Testing Capacity Acquisition | ISO 10993-compliant toxicology facilities bypass 6-9 month queues throttling competitor product launches. |
| Kerala-Tamil Nadu Distribution Network Buildout | Geriatric diabetes populations in southern states remain underserved by existing insulin pen channels. |
Research Methodology
Bottom-up hospital and homecare demand modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, CDSCO regulatory affairs specialists, and GPO contracts managers combined with secondary validation from CDSCO Medical Device Rules filings, BIS certification databases, PLI scheme disbursement records, and hospital procurement tender platforms. Cross-referencing bottom-up patient population projections with top-down device production estimates ensures segmentation integrity.
Historical trendline analysis across inhaler, injector, pump, and transdermal patch shipment patterns established baseline growth trajectories. The analytical framework models product type, end user channel, technology tier, and application segmentation dimensions across the analysis window. CAGRs derive from regression-adjusted trend extrapolation incorporating PLI scheme incentive absorption rates and CDSCO licensing timeline compression. Forecast inputs include respiratory disease burden projections in Maharashtra-Karnataka clusters and diabetes prevalence demographics in southern states.
Several conditions sit outside the modeled scope, including unforeseen CDSCO classification guidance revisions, polymer commodity price shocks, and geopolitical disruption to Taiwanese semiconductor supply. Forecasts reflect documented assumptions about regulatory implementation pacing and reimbursement policy stability. A model refresh is warranted upon material change in CDSCO's phased transition timeline to full medical device regulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Monopolar Electrosurgery Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Global Pulmonary Drug Delivery Systems Market
Medical Devices
Intubation Accessories Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Global Pregnancy Detection Kits Market