
 Global Medical Rehabilitation Services Market | 2026-2036
Global Medical Rehabilitation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Rehabilitation Services Market Foresight
Hospital referral networks is tilting toward outpatient and home-based rehabilitation pathways as payers push for lower-cost alternatives to inpatient stays. Select Medical Holdings Corp. leverages its national network of specialty hospitals to sustain high-acuity rehabilitation volumes. Encompass Health Corporation anchors its position through integrated inpatient facilities paired with home health extensions. Shirley Ryan AbilityLab differentiates via research-intensive neurorehabilitation programs that attract complex cases from across the United States.
Medical rehabilitation services encompass therapeutic interventions delivered by licensed clinicians to restore functional capacity following injury, surgery, or disease onset, typically involving prescribed exercise protocols, assistive device training, and neuromuscular re-education administered across 30-90 day episodes. These services reduce long-term disability costs and accelerate return-to-work timelines for working-age populations. Physical therapy occupies the largest share of service revenue due to its applicability across orthopedic and post-surgical populations, while neurorehabilitation represents the fastest-expanding category as stroke incidence rises and robotic-assisted gait training gains clinical acceptance. Outpatient rehabilitation settings capture growing volume as telehealth-enabled remote monitoring allows clinicians to supervise home exercise programs without facility-based encounters.
The FDA oversees medical device clearance for rehabilitation robotics and electrotherapy equipment, while CMS reimbursement rules determine which services qualify for Medicare and Medicaid payment, directly constraining provider revenue models. State-level occupational licensing boards govern therapist scope-of-practice, creating fragmented market access conditions that favor multi-state operators with compliance infrastructure. Stakeholders must monitor evolving value-based payment demonstrations that bundle rehabilitation into total episode costs, as these models will reshape which care settings and service intensities prove economically viable.
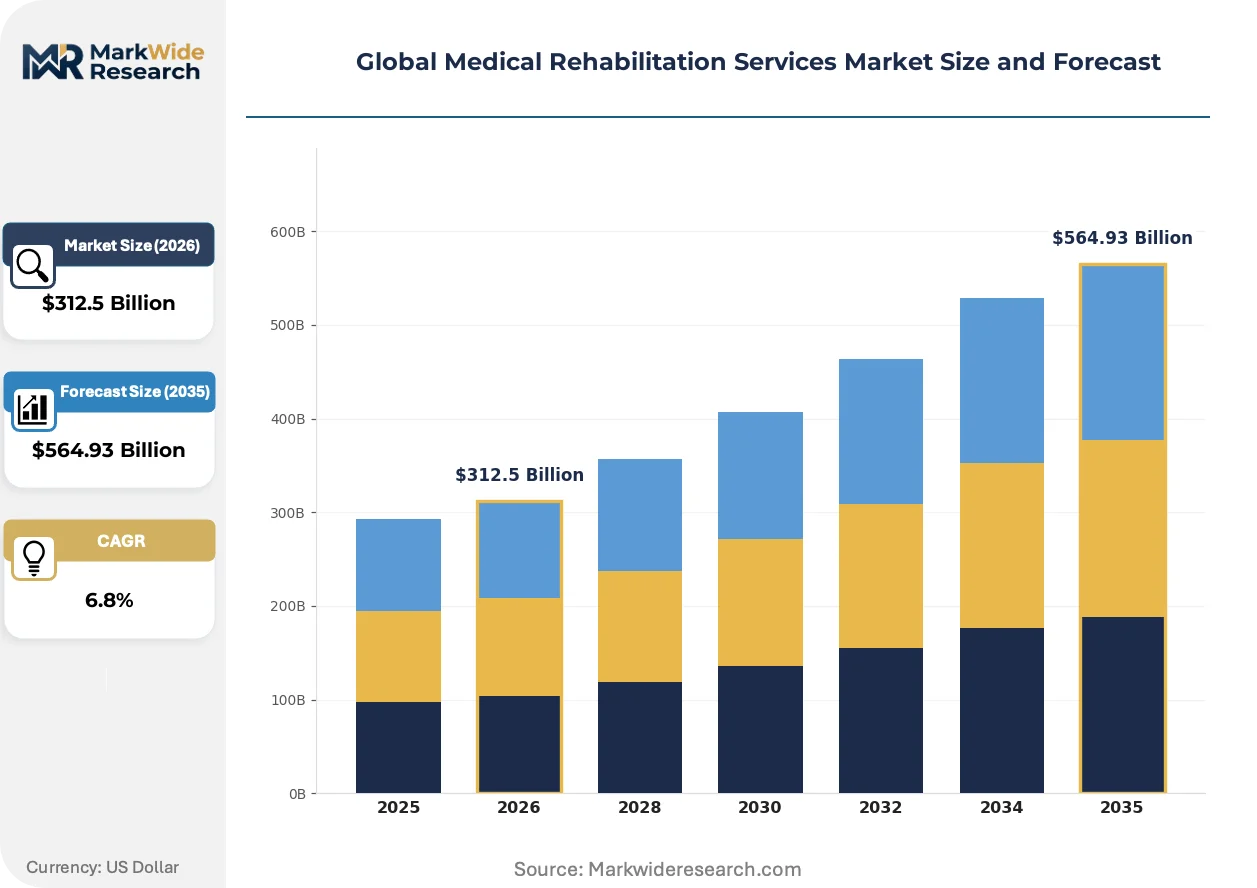
Market Dynamics
CMS reimbursement compression is forcing rehabilitation providers to migrate high-margin services toward outpatient settings while maintaining clinical intensity through remote monitoring infrastructure.
Growth Catalysts
- Aging demographics:Japan, Italy, and Germany face acute post-surgical rehabilitation demand as median ages exceed 45 years, expanding eligible patient pools for joint replacement and cardiac recovery programs.
- MDR certification pathways:The European Union's Medical Device Regulation streamlines market entry for robotic exoskeletons and electrotherapy systems, accelerating clinical adoption of CE-marked rehabilitation equipment.
- Telehealth integration:Remote patient monitoring platforms enable licensed therapists to supervise home exercise protocols, extending service reach into rural catchment areas previously underserved by facility-based care.
Market Restraints
- Reimbursement volatility:Medicare's annual Physician Fee Schedule adjustments create revenue uncertainty for US outpatient clinics dependent on CMS payment rates for physical therapy encounters.
- Equipment capital intensity:Lokomat and Armeo robotic systems require $250,000-$500,000 upfront investment, constraining independent practice acquisition of gait-training technology.
- Workforce pipeline constraints:Accredited physical therapy doctoral programs produce insufficient graduates to match vacancy rates in neurorehabilitation and geriatric specialty settings.
Strategic Opportunities
- Home-based care expansion:India's tier-2 and tier-3 cities present untapped demand for post-stroke rehabilitation as hospital networks extend home health divisions beyond metropolitan centers.
- AI-driven personalization:Machine learning algorithms analyzing kinematic data from wearable sensors enable adaptive exercise prescription, converging biomechanical assessment with predictive analytics.
- Value-based payment pilots:CMS Bundled Payments for Care Improvement initiative rewards providers achieving functional outcome targets, creating margin upside for high-performance rehabilitation networks.
Industry Challenges
- Interoperability fragmentation:Electronic health record systems from Epic, Cerner, and MEDITECH lack standardized APIs for rehabilitation-specific outcome metrics, complicating longitudinal patient tracking across care transitions.
- Specialized therapist scarcity:Certified neurodevelopmental treatment and vestibular rehabilitation competencies require 200+ hour post-graduate training, limiting supply of clinicians qualified for complex neurological cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Rehabilitation Services Market |
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $564.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Physical Therapy, Occupational Therapy, Speech Therapy, Neurorehabilitation, Prosthetic Services, Cognitive Rehabilitation Application: Post-Surgical Recovery, Stroke Recovery, Sports Injury, Orthopedic Rehabilitation, Neurological Disorders, Chronic Pain Management Care Setting: Inpatient Rehabilitation, Outpatient Rehabilitation, Home Care, Skilled Nursing Facilities, Day Rehabilitation Centers, Long-Term Care End User: Geriatric Patients, Pediatric Patients, Veterans, Accident Victims, Orthopedic Patients, Neurological Patients |
| Companies Covered | Select Medical Holdings Corp., Encompass Health Corporation, Kindred Rehabilitation Services, Shirley Ryan AbilityLab, Athletico Physical Therapy, Kessler Institute for Rehabilitation, U.S. Physical Therapy, Inc., Lifepoint Rehabilitation, Prism Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Rehabilitation Services Market Shifts & Advancements
Sensor-embedded wearable systems are compressing the boundary between clinical supervision and autonomous home exercise, enabling continuous kinematic feedback without facility-based encounters.
Exoskeleton-assisted gait training is digitizing stroke rehabilitation protocols by capturing real-time ground reaction forces and joint angle data. Academic medical centers and Veterans Affairs facilities deploy these systems for high-acuity neurorehabilitation. The technology is digitizing documentation workflows, replacing manual six-minute walk tests with automated spatiotemporal gait analysis.
Japan's PMDA has accelerated approval pathways for software-as-a-medical-device rehabilitation applications, reducing time-to-market for AI-powered movement assessment tools. Domestic manufacturers gain competitive positioning against European and North American equipment suppliers. Japanese hospital chains now specify PMDA-cleared digital therapeutics in procurement tenders for post-surgical orthopedic programs.
Episode-based purchasing contracts are displacing fee-for-service arrangements in commercial payer networks. Large self-insured employers negotiate direct contracts with rehabilitation providers for bundled musculoskeletal care. This shift concentrates procurement authority among benefits managers at Fortune 500 headquarters, particularly visible in manufacturing-heavy Midwestern US states seeking workers' compensation cost containment.
Global Medical Rehabilitation Services Market Segmentation
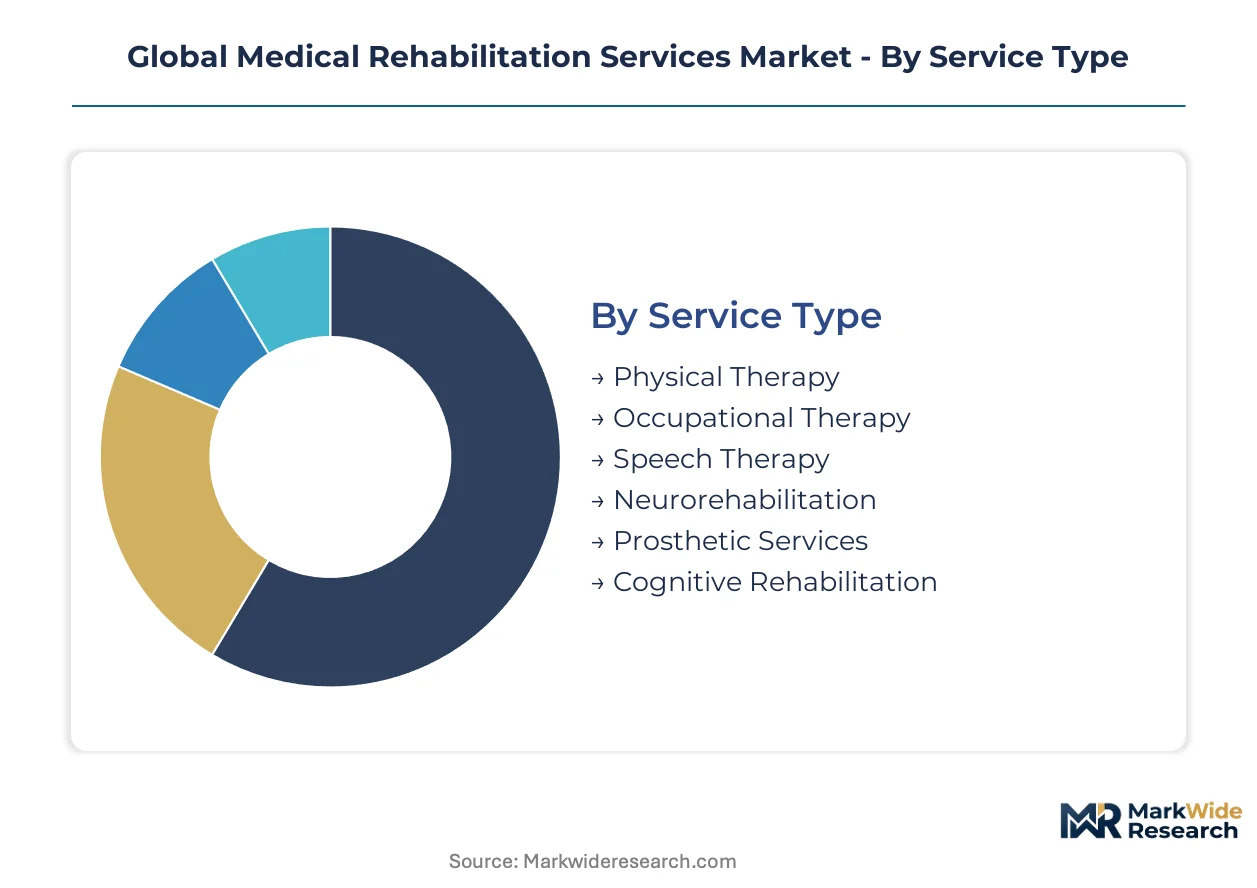
Medical rehabilitation services fragment across four intersecting dimensions that determine reimbursement rates, capital requirements, and clinician specialization. Service type and care setting combinations dictate Medicare billing codes, while application and end-user pairings shape referral patterns from acute-care discharge planners.
Service Type:
Cycle times vary dramatically across therapeutic modalities, with orthopedic-focused services turning patients every 4-6 weeks while neurorehabilitation extends 12-24 months for stroke survivors.
- Physical Therapy:Therapeutic exercise, manual therapy, and electrophysical agents restore musculoskeletal function following joint replacement or sports trauma. Demand clusters in United States outpatient clinics where CMS reimbursement for post-surgical protocols drives volume. Workforce constraints limit expansion in rural catchment areas despite telehealth-enabled remote supervision.
- Neurorehabilitation:Robotic-assisted gait training, constraint-induced movement therapy, and virtual reality balance systems address stroke, traumatic brain injury, and spinal cord pathology. Academic medical centers in Germany and Japan deploy Lokomat and Armeo systems for high-acuity cases. PMDA accelerated approval pathways in Japan compress regulatory timelines for software-as-a-medical-device movement assessment tools.
- Occupational Therapy:Activities of daily living retraining and adaptive equipment prescription target functional independence.
- Speech Therapy:Swallowing assessment and cognitive-linguistic intervention address post-stroke aphasia and Parkinson's-related dysarthria.
- Prosthetic Services:Socket fitting, gait training, and myoelectric control calibration follow amputation.
- Cognitive Rehabilitation:Compensatory strategy training and computer-based attention exercises target traumatic brain injury sequelae.
Physical Therapy dominates installed base. Neurorehabilitation is where expansion concentrates.
Application:
Cost tiers separate episodic conditions with defined recovery endpoints from chronic conditions requiring indefinite maintenance.
- Post-Surgical Recovery:Structured protocols following joint arthroplasty, cardiac bypass, or spinal fusion emphasize progressive mobilization and wound care. Hospital networks in Italy and Germany embed these services in bundled payment contracts with commercial insurers. CMS reimbursement compression accelerates migration from inpatient to outpatient settings.
- Stroke Recovery:Intensive multidisciplinary programs address hemiparesis, aphasia, and spatial neglect through task-specific training. Demand concentrates in Japan where aging demographics expand eligible patient pools. Veterans Affairs facilities in the United States deploy robotic exoskeletons for high-acuity neurorehabilitation.
- Sports Injury:Accelerated return-to-play protocols target anterior cruciate ligament reconstruction and rotator cuff repair.
- Orthopedic Rehabilitation:Fracture healing and degenerative joint disease management emphasize joint protection strategies.
- Neurological Disorders:Progressive conditions including Parkinson's disease and multiple sclerosis require adaptive equipment and caregiver training.
- Chronic Pain Management:Multimodal approaches combining physical modalities with behavioral intervention target fibromyalgia and low back pain.
Post-Surgical Recovery commands highest per-episode revenue. Stroke Recovery represents the steepest expansion trajectory.
Care Setting:
Volume distribution shifts as remote monitoring platforms enable licensed supervision without facility-based encounters.
- Outpatient Rehabilitation:Clinic-based encounters with prescribed home exercise programs capture growing share as telehealth integration extends reach. Independent practices in the United States face Medicare reimbursement volatility from annual Physician Fee Schedule adjustments. Large multi-state operators absorb regulatory compliance costs that constrain smaller competitors.
- Inpatient Rehabilitation:Hospital-based units deliver intensive daily therapy for medically complex patients requiring nursing oversight. Select Medical Holdings Corp. and Encompass Health Corporation sustain high-acuity volumes through national specialty hospital networks. CMS prospective payment systems determine length-of-stay incentives.
- Home Care:Licensed therapists supervise exercise protocols in patient residences with wearable sensor feedback.
- Skilled Nursing Facilities:Subacute programs bridge acute hospital discharge and community reintegration.
- Day Rehabilitation Centers:Structured programs provide intensive therapy without overnight admission.
- Long-Term Care:Maintenance therapy preserves function in residential settings for permanent disability.
Inpatient Rehabilitation retains highest clinical intensity. Outpatient Rehabilitation captures volume growth fastest.
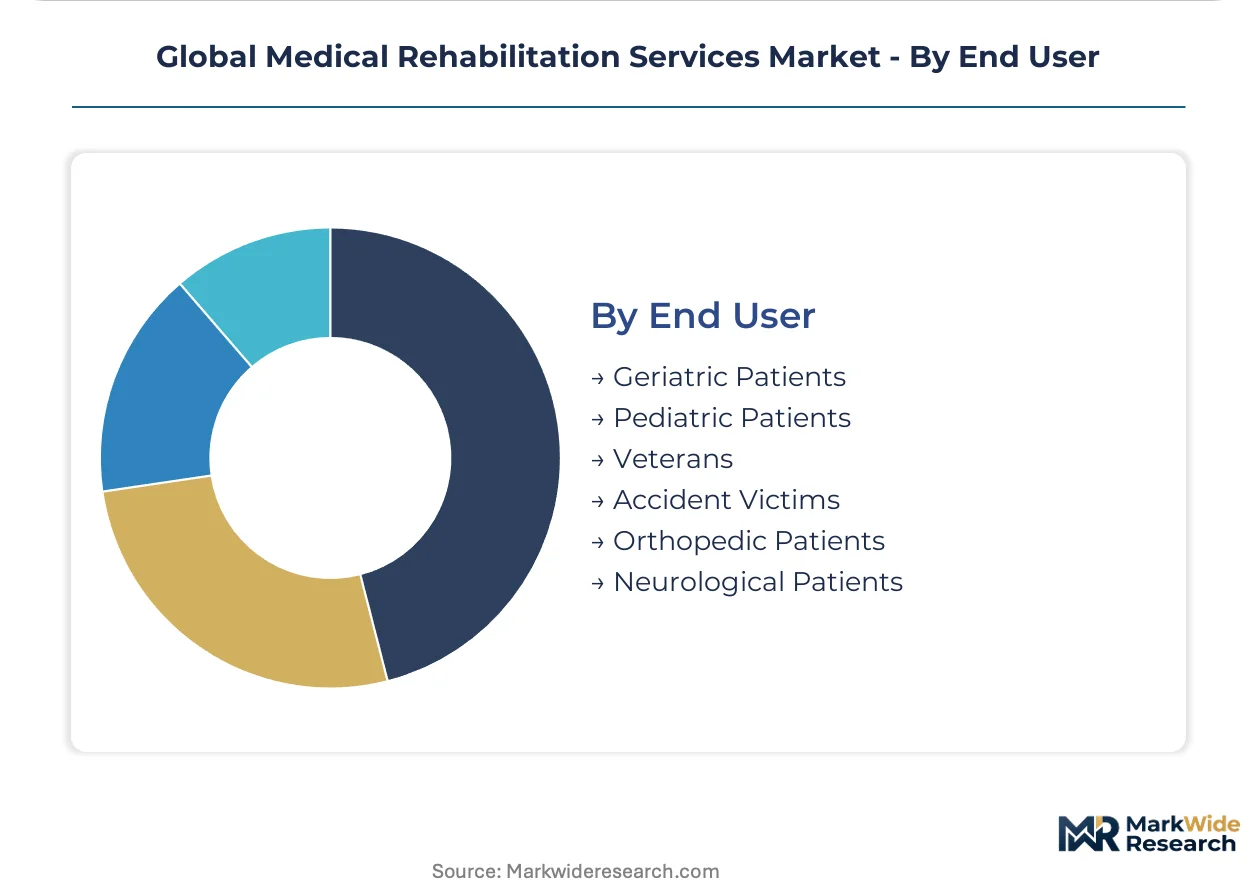
End User:
Customer type determines payer mix, with geriatric populations concentrated in Medicare-funded programs and working-age populations tied to commercial insurance or workers' compensation.
- Geriatric Patients:Joint replacement recovery, fall prevention, and cardiac rehabilitation dominate service utilization. Aging demographics in Japan, Italy, and Germany expand eligible pools for post-surgical programs. Medicare reimbursement policies in the United States directly shape service availability and facility expansion decisions.
- Accident Victims:Trauma-related orthopedic and neurological rehabilitation follows motor vehicle collisions and workplace injuries. Workers' compensation systems in Midwestern United States manufacturing states concentrate procurement authority among Fortune 500 benefits managers.
- Pediatric Patients:Early intervention and school-based services address developmental disabilities.
- Veterans:Traumatic brain injury and polytrauma programs operate through dedicated federal facilities.
- Orthopedic Patients:Sports medicine and degenerative joint conditions span working-age and elderly populations.
- Neurological Patients:Stroke, multiple sclerosis, and Parkinson's disease require specialized therapist competencies.
Geriatric Patients anchor installed base. Accident Victims concentrate expansion in commercial payer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Medicare reimbursement infrastructure underwrites North American rehabilitation service capacity, while Japan's PMDA regulatory pathways and Germany's MDR-certified equipment clusters anchor regional specialization elsewhere.
United States
Medicare's annual Physician Fee Schedule adjustments directly constrain outpatient clinic revenue models, while CMS prospective payment systems govern inpatient rehabilitation facility economics. The FDA oversees clearance pathways for robotic exoskeletons and electrotherapy devices used in neurorehabilitation. Hospital networks in Florida and Arizona sustain high geriatric rehabilitation volumes through bundled payment contracts with commercial insurers.
Japan
Aging demographics expand eligible pools for post-stroke and joint replacement recovery programs beyond metropolitan hospital catchments. METI coordinates industrial policy supporting domestic rehabilitation robotics manufacturers against European competitors. Tokyo medical centers deploy PMDA-cleared software-as-a-medical-device applications for movement assessment in orthopedic rehabilitation procurement.
Germany
The European Union's Medical Device Regulation streamlines CE-marking for Lokomat and Armeo robotic systems, accelerating clinical adoption in academic medical centers. Germany's statutory health insurance system reimburses extended neurorehabilitation episodes spanning 12-24 months for stroke survivors. Industrial clusters in Bavaria and Baden-Württemberg concentrate rehabilitation equipment manufacturing alongside automotive supplier networks.
India
Tier-2 and tier-3 cities present untapped demand for home-based post-stroke rehabilitation as hospital networks extend beyond Delhi and Mumbai. The country's national pharmaceutical regulator oversees medical device quality standards for imported rehabilitation equipment. Maharashtra and Karnataka anchor telehealth-enabled remote monitoring pilots connecting urban specialists to rural patient populations.
United Kingdom
NHS England's integrated care systems reshape referral patterns from acute hospital discharge toward community-based rehabilitation pathways. The Medicines and Healthcare products Regulatory Agency governs clearance for AI-powered movement assessment tools entering clinical use. London and Southeast England concentrate private rehabilitation capacity serving commercial insurance and self-pay segments alongside NHS provision.
Global Medical Rehabilitation Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete therapeutic technologies to multi-site operators. The vendor base concentrates around national specialty hospital networks, outpatient clinic chains, and research-intensive academic medical centers. Three archetypes dominate: scale-driven multi-state operators absorbing compliance costs, research-anchored institutions attracting complex neurological referrals, and technology-forward platforms integrating remote monitoring infrastructure. Competitive positioning depends on Medicare network participation and robotic equipment certification rather than price differentiation alone.
Within the scale-driven operator tier, Select Medical Holdings Corp. and Encompass Health Corporation exemplify national network strategies built around inpatient facility density paired with home health extensions. Shirley Ryan AbilityLab occupies a distinct position as a research-intensive academic medical center anchoring competitive differentiation through neurorehabilitation specialization and complex case attraction from across the United States.
| Leading Market Players |
|---|
| Select Medical Holdings Corp. |
| Encompass Health Corporation |
| Kindred Rehabilitation Services |
| Shirley Ryan AbilityLab |
| Athletico Physical Therapy |
| Kessler Institute for Rehabilitation |
| U.S. Physical Therapy, Inc. |
| Lifepoint Rehabilitation |
| Prism Medical |
| Others |
Supply & Pricing Matrix
The Asia-Europe maritime corridor carries robotic rehabilitation equipment from German and Japanese manufacturing clusters to hospital networks in India and Southeast Asia, with freight cost volatility compressing margins for independent outpatient clinics while concentrating procurement leverage among multi-state operators with volume-contracted logistics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared robotic systems from CE-marked equipment and uncertified electrotherapy devices. Price differentiation rests on certification grade and after-sales service bundling, with CMS reimbursement volatility intensifying cost compression in the standard tier. Independent practices in rural United States catchments exhibit highest price sensitivity, while academic medical centers absorb premium-tier premiums for research-intensive neurorehabilitation programs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electrotherapy component sourcing. Equipment manufacturing concentrates in Germany, Japan, and the United States, with precision servo motors and sensor arrays drawing from Taiwanese semiconductor foundries. Single-source vulnerability around robotic exoskeleton control systems feeds from concentrated Japanese mechatronics suppliers. Distribution runs through GPO-negotiated contracts with hospital networks and direct procurement by national specialty hospital operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global Medical Rehabilitation Services Market dynamics track Medicare reimbursement cycles, with post-acute care spending recovering from prior-year compression as aging demographics expand eligible patient pools for joint replacement and stroke recovery programs.
For Market Incumbents: Entrench network density through home health division expansion into tier-2 and tier-3 cities, absorbing compliance costs that constrain independent competitors. Deepen backward integration into remote monitoring platform development to offset CMS reimbursement compression. Prioritize FDA clearance for AI-driven gait assessment tools before PMDA-accelerated Japanese competitors capture procurement tenders.
For New Entrants and Emerging Players: Establish a beachhead in India's home-based post-stroke rehabilitation segment, where hospital network extension beyond metropolitan centers creates white-space demand. Target telehealth-enabled remote supervision contracts with Maharashtra and Karnataka state health systems. Lead with wearable sensor partnerships that bypass capital-intensive robotic equipment procurement.
For Investors and Strategic Acquirers: CMS Bundled Payments for Care Improvement initiative reshapes the acquisition landscape toward rehabilitation networks with proven functional outcome metrics. Five-to-ten-year viability hinges on value-based payment participation rates. Monitor neurorehabilitation therapist vacancy rates as the inflection signal for workforce-constrained market access.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR certification accelerates European market entry for Lokomat and Armeo robotic systems. |
| Hospital System Partnership | Bundled payment contracts with Florida and Arizona networks secure high geriatric volumes. |
| Software Companion Development | PMDA-cleared AI movement assessment tools differentiate Japanese procurement tenders. |
| Reimbursement Strategy | Medicare network participation determines outpatient clinic revenue model sustainability. |
| Geographic Expansion | India's tier-2 and tier-3 cities present untapped home-based rehabilitation demand. |
Research Methodology
Initial hypotheses were tested against primary input from rehabilitation hospital executives, biomedical engineering directors, CMS policy specialists, and GPO contracts managers and refined through secondary validation across FDA 510(k) filings, CMS Medicare cost reports, hospital procurement databases, and EU MDR certification registries. Bottom-up patient volume modeling triangulated against top-down healthcare expenditure forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, care setting, application, and end-user age cohort. CAGRs derived from historical Medicare utilization trends and robotic equipment adoption curves, incorporating stroke incidence projections and joint replacement surgery volumes as industry-specific forecast inputs.
Sensitivities concentrate around CMS Physician Fee Schedule adjustments, FDA clearance timelines for rehabilitation robotics, and neurorehabilitation therapist graduate pipeline constraints. Forecasts reflect documented assumptions regarding telehealth reimbursement permanence and value-based payment pilot expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
Motion Stimulation Therapy Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
Brachial Plexus Injury Market
Rehabilitation Services
US Physical Therapy Services Market