
 Global Assistive Listening Device Market | 2026-2036
Global Assistive Listening Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Assistive Listening Device Market Foresight
Bluetooth Low Energy integration is reconfiguring how assistive listening devices pair with consumer electronics and public address infrastructure. GN Hearing A/S leverages its ReSound platform to anchor premium wireless connectivity across clinical and direct-to-consumer channels. Sonova Holding AG differentiates through Phonak's proprietary Roger digital radio protocol, which dominates large-venue installations. WS Audiology sustains manufacturing scale across its Bernafon and Widex brands, competing on programmable digital signal processing architectures.
Assistive listening devices are electroacoustic systems designed to transmit amplified sound directly to the user's ear, typically operating within frequency ranges of 20 Hz to 8 kHz with signal-to-noise ratios exceeding 20 dB for speech intelligibility in noisy environments. Their primary purpose is to overcome distance, reverberation, and background noise barriers for individuals with hearing loss in settings ranging from theaters to hospital wards. Hearing aids command the largest value pool within product type segmentation, while Bluetooth-enabled systems represent the fastest-expanding technology category as streaming protocols replace analog transmission. Public venues and schools are driving volume in end-user segmentation due to Americans with Disabilities Act compliance requirements and equivalent accessibility mandates across European and Asian jurisdictions.
The FDA's OTC hearing aid final rule reshapes demand by enabling direct retail access without audiologist gatekeeping, while the EU Medical Device Regulation imposes clinical evaluation and post-market surveillance obligations on manufacturers selling into European markets. Japan's Ministry of Health, Labour and Welfare maintains reimbursement schedules that influence product pricing and feature bundling for elderly beneficiaries. Stakeholders must monitor how regulatory divergence between permissive OTC frameworks and stringent medical device classifications alters competitive positioning and channel investment priorities.
Market Dynamics
The FDA's OTC hearing aid final rule is compressing the traditional audiology channel by enabling direct retail access, forcing manufacturers to rebuild distribution infrastructure around pharmacy chains and consumer electronics retailers rather than clinical gatekeepers.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States exhibit accelerating hearing loss prevalence among populations over 65, expanding the addressable user base for amplification devices in residential and institutional settings.
- Public Venue Mandates:ADA Title III compliance requirements in the United States and equivalent accessibility directives across European jurisdictions mandate assistive listening system installation in theaters, lecture halls, and worship facilities.
- Bluetooth Low Energy:The protocol enables seamless pairing between personal hearing devices and smartphones, televisions, and public address infrastructure, eliminating proprietary radio frequency compatibility barriers.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries fabricate the majority of digital signal processing chips, creating vulnerability to geopolitical disruption and allocation constraints during demand surges.
- EU Medical Device Regulation:MDR clinical evaluation requirements and notified body capacity bottlenecks extend certification timelines for new product introductions, compressing effective patent life.
- Smartphone Substitution:Consumer-grade earbuds with ambient sound amplification and transcription applications capture price-sensitive users seeking basic speech enhancement without medical device cost or stigma.
Strategic Opportunities
- Indian Market Expansion:The country's PLI scheme for electronics manufacturing and expanding private hospital networks create localized production and distribution footholds for mid-tier device categories.
- Remote Fitting Platforms:Tele-audiology services enable manufacturers to bypass brick-and-mortar clinical infrastructure, capturing rural and mobility-limited populations previously excluded from professional calibration.
- Classroom Audio Distribution:K-12 inclusion mandates in the United States and equivalent special education requirements in European school systems drive volume procurement of multi-receiver FM and infrared systems.
Industry Challenges
- Audiologist Workforce Constraints:Training program capacity limitations in the United States and European Union extend appointment wait times, creating friction for prescription-device fitting workflows.
- Interoperability Certification Complexity:FCC Part 15 compliance for radio frequency emissions, combined with Bluetooth SIG qualification and medical device clearance, multiplies pre-launch testing duration and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Assistive Listening Device Market |
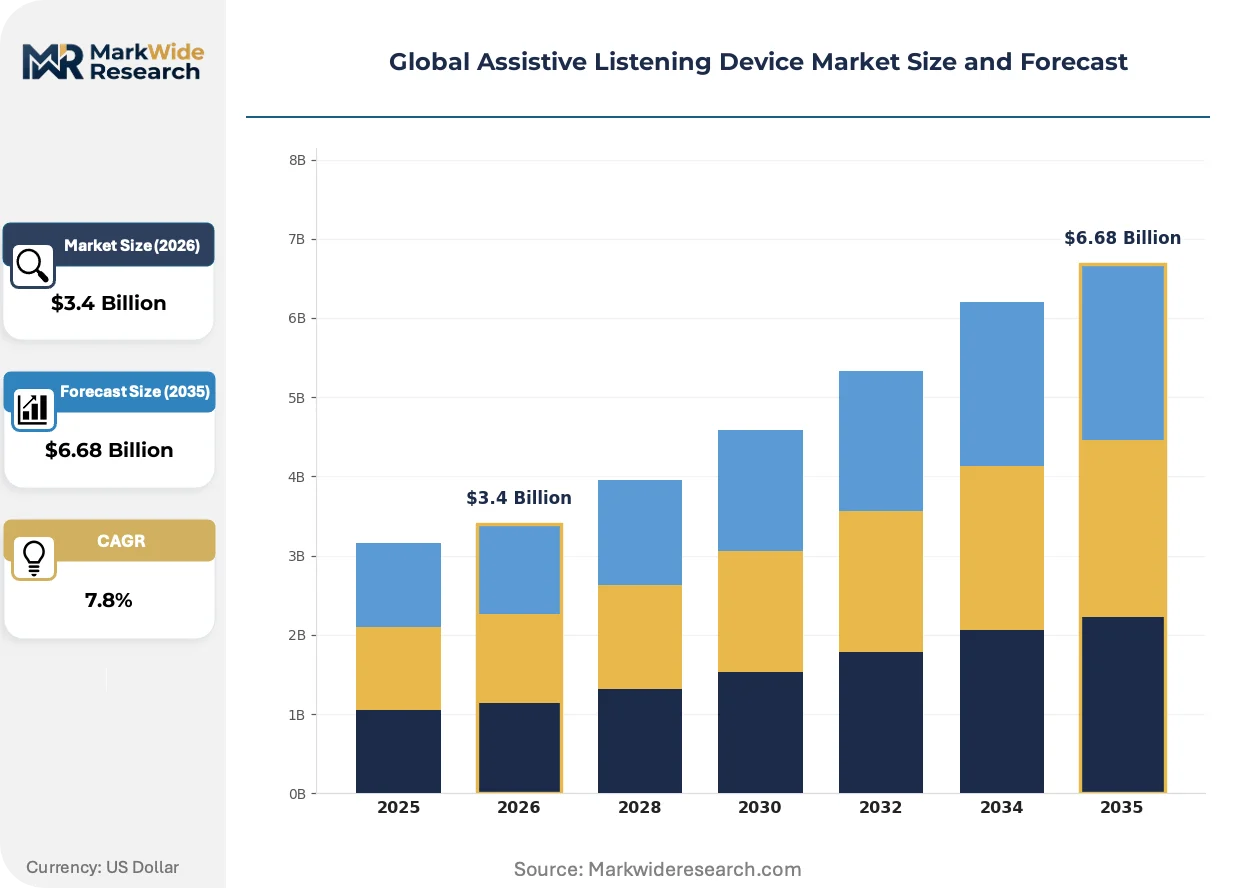
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hearing Aids, FM Systems, Infrared Systems, Induction Loop Systems Technology: Analog, Digital, Bluetooth, Wireless End User: Individuals, Schools, Healthcare Facilities, Public Venues Distribution Channel: Online Retail, Medical Stores, Audiology Clinics, Specialty Stores |
| Companies Covered | GN Hearing A/S, Cochlear Ltd., Sonova Holding AG, Williams AV, WS Audiology, Starkey Hearing Technologies, Oticon Inc., Sennheiser, Phonak AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Assistive Listening Device Market Shifts & Advancements
Wireless transmission protocols are displacing analog induction loop systems across public venue installations, while artificial intelligence architectures enable real-time environmental sound classification and adaptive amplification without manual user adjustment.
Beamforming microphone arrays with onboard machine learning inference are digitizing how directional sound capture occurs in noisy environments. Large-venue installers and premium hearing aid manufacturers deploy these systems to isolate speech from reverberant background noise. The technology is compressing the performance gap between professional hearing instruments and consumer audio devices.
REACH substance restrictions and RoHS hazardous material limits are reshaping European manufacturing footprints by prohibiting lead-based solders and restricted phthalates in device housings. Manufacturers serving EU markets reformulate acoustic tubing and circuit board assemblies to maintain market access. Hearing aid battery compartments and rechargeable lithium-ion cell enclosures undergo accelerated redesign cycles to satisfy evolving chemical compliance thresholds.
Direct-to-consumer subscription models are displacing traditional device ownership structures in North American and Western European markets. Retail pharmacy chains and telehealth platforms bundle hardware, remote tuning services, and loss replacement into monthly fee structures. The United States exhibits the fastest channel transformation as OTC regulatory clarity enables marketing campaigns previously restricted to licensed practitioners.
Global Assistive Listening Device Market Segmentation
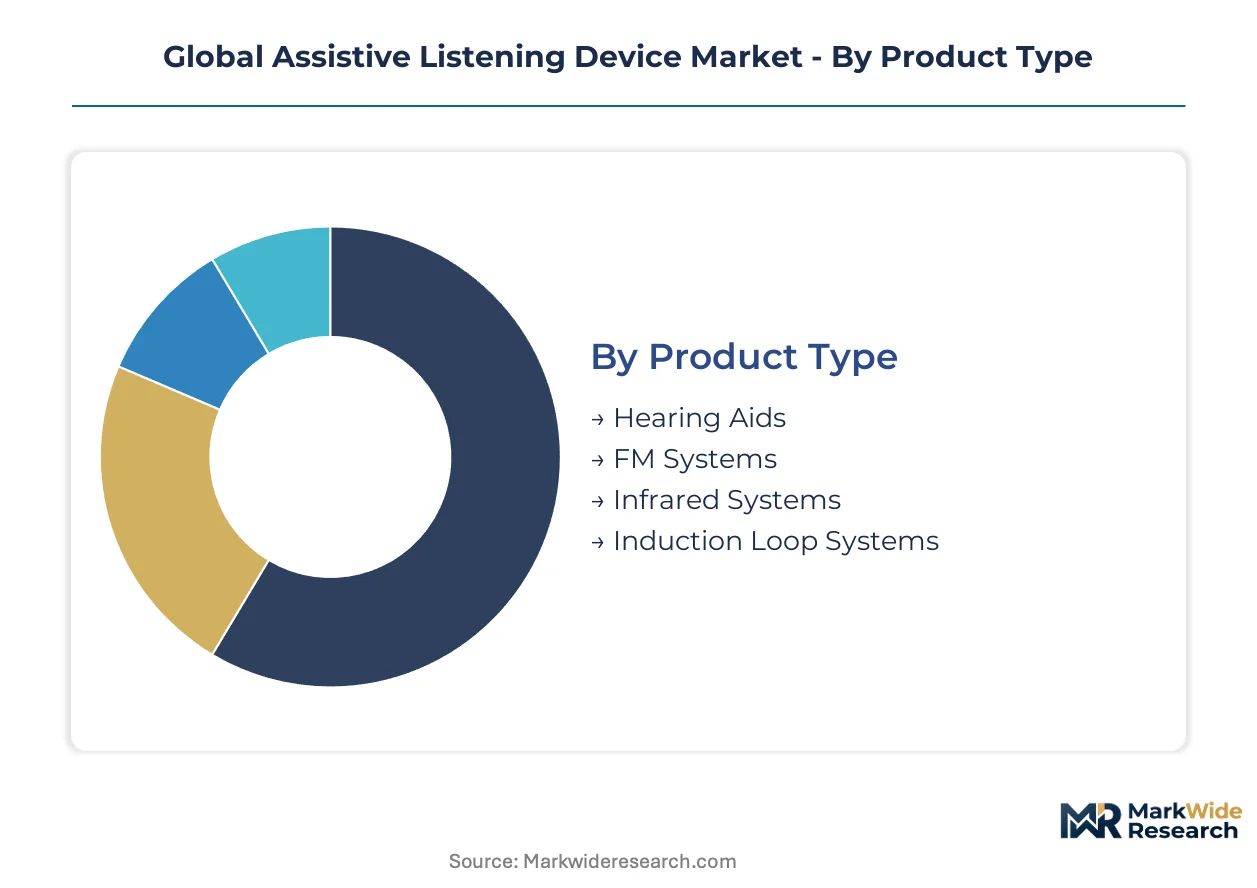
Assistive listening device segmentation reveals how technical specifications, procurement pathways, and user environments create distinct commercial battlegrounds. Manufacturers must align R&D investment and channel strategy against the specific performance thresholds and purchasing authority that each segment demands.
Product Type:
Devices span personal amplification worn on the body to venue-scale infrastructure requiring professional installation and compliance certification.
- Hearing Aids:Miniaturized electroacoustic devices with programmable digital signal processing, rechargeable lithium-ion or zinc-air power systems, and custom-molded or receiver-in-canal form factors. Demand concentrates in the United States and Germany where aging demographics intersect with reimbursement schedules and OTC regulatory pathways. FDA OTC rules are compressing traditional audiologist gatekeeping while expanding pharmacy and direct-to-consumer access.
- FM Systems:Radio frequency transmission architecture operating in 72-76 MHz or 216-217 MHz bands, pairing body-worn or desktop transmitters with personal receivers. Schools in the United States drive procurement volume through Individuals with Disabilities Education Act mandates for classroom audio distribution to hearing-impaired students.
- Infrared Systems:Line-of-sight light-based transmission immune to radio interference, requiring emitter panels and compatible receivers. Theaters and lecture halls in Japan deploy these for simultaneous multilingual interpretation and assistive listening compliance.
- Induction Loop Systems:Copper wire installations generating electromagnetic fields for telecoil-equipped hearing aids, prevalent in European worship facilities and transport terminals. RoHS substance restrictions and REACH phthalate limits are accelerating replacement of legacy lead-soldered installations.
Established volume favors Hearing Aids; emerging adoption favors FM Systems.
Technology:
Signal processing architecture determines power consumption, environmental adaptability, and interoperability with consumer electronics ecosystems.
- Digital:Microprocessor-based sound processing with multi-channel compression, noise reduction algorithms, and feedback cancellation. Healthcare facilities in Germany specify digital platforms for patient communication systems where speech intelligibility in reverberant wards is critical.
- Bluetooth:Low Energy and Classic protocols enabling direct streaming from smartphones, televisions, and public address infrastructure. The United States exhibits steepest expansion trajectory as hearing aid manufacturers integrate Auracast broadcast audio for venue connectivity.
- Analog:Continuous signal amplification without digital conversion, surviving in cost-sensitive basic hearing aids and legacy venue installations. India's private hospital networks and PLI-supported electronics manufacturing are sustaining residual analog demand for price-constrained procurement.
- Wireless:Proprietary radio protocols including Roger digital systems for large-venue multi-receiver deployments. Theaters and conference centers in Japan specify these for simultaneous interpretation and assistive listening integration.
Bluetooth climbs the fastest; Analog retains residual share in emerging markets.
End User:
Purchasing authority ranges from individual consumers to institutional procurement offices with accessibility compliance obligations.
- Individuals:Personal acquisition for residential use, increasingly through direct-to-consumer channels following OTC regulatory clarity. The United States leads this transformation as pharmacy chains and telehealth platforms displace traditional audiology workflows.
- Public Venues:Theaters, worship facilities, and transport terminals mandated by ADA Title III and equivalent European accessibility directives to install assistive listening infrastructure. Compliance enforcement drives replacement cycles and technology upgrades.
- Schools:K-12 and higher education institutions procuring classroom audio distribution under IDEA and equivalent special education mandates. Multi-receiver FM and infrared systems dominate this specification-driven segment.
- Healthcare Facilities:Hospitals and long-term care institutions deploying wireless patient communication systems. Germany's hospital procurement networks and Japan's elderly care facilities are expanding digital platform adoption.
Individual purchasing is gaining share fastest; Public Venues sustain infrastructure replacement cycles.
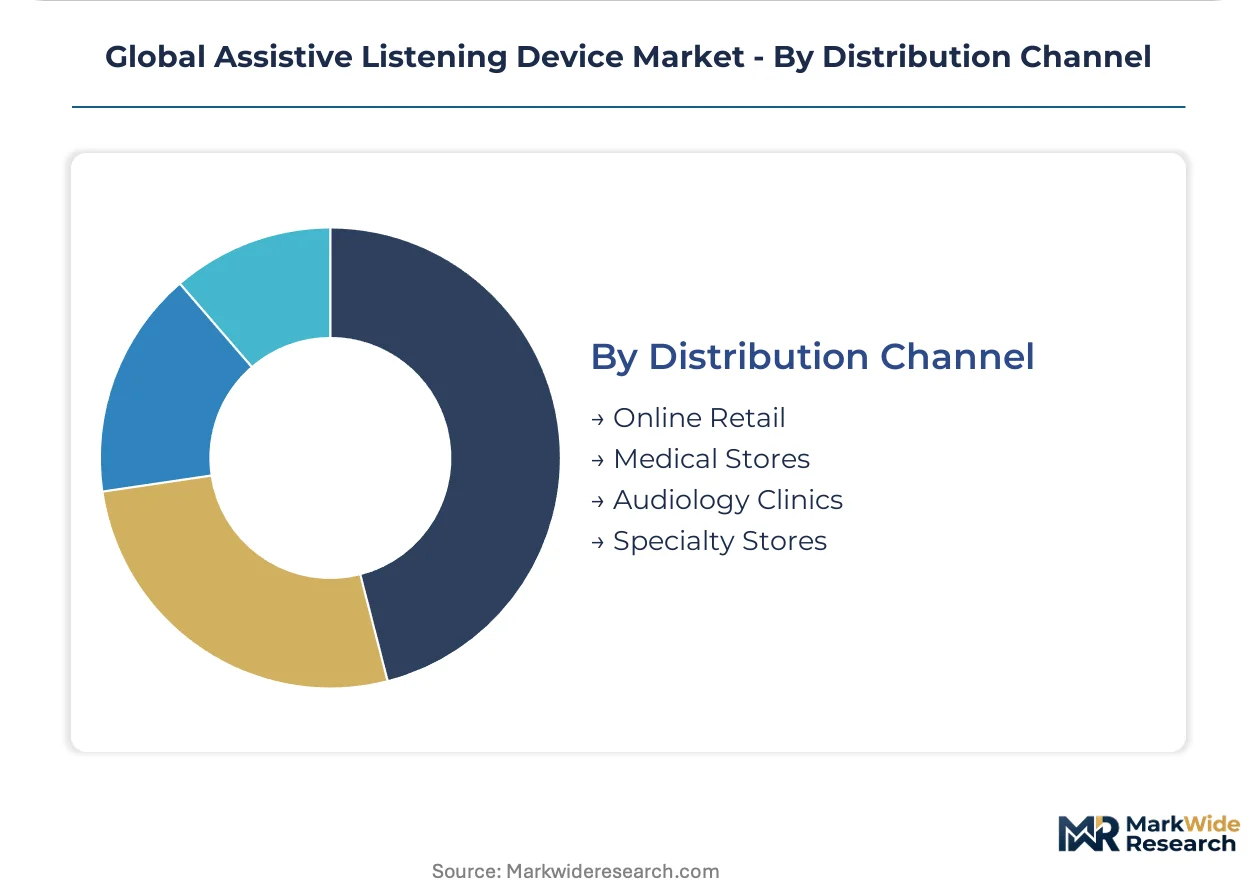
Distribution Channel:
Channel structure is fragmenting as regulatory changes enable non-clinical access points alongside traditional professional gatekeeping.
- Audiology Clinics:Licensed practitioner facilities providing diagnostic evaluation, device fitting, and ongoing calibration services. EU MDR clinical evaluation requirements and notified body capacity constraints are extending certification timelines for products distributed through this channel.
- Online Retail:Direct-to-consumer platforms and pharmacy chain e-commerce enabled by FDA OTC regulations in the United States. Subscription bundling of hardware, remote tuning, and loss replacement is displacing traditional ownership models.
- Medical Stores:Pharmacy and optical retail chains expanding into hearing devices as OTC classification reduces professional barrier requirements. Germany's Apotheken and Japan's drugstore networks are testing assisted self-selection models.
- Specialty Stores:Consumer electronics retailers and dedicated hearing device shops offering demonstration and basic fitting support. Best Buy and similar chains in the United States are building in-store audiology kiosks.
Audiology Clinics retain premium-device dominance; Online Retail captures volume in accessible price tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark exports precision audio components to Germany and the United States, anchoring transatlantic supply corridors for wireless transmission modules and digital signal processing chipsets.
United States
FDA OTC regulations enable pharmacy chains and consumer electronics retailers to bypass audiologist gatekeeping. ADA Title III mandates drive venue infrastructure replacement cycles in theaters and transport terminals. Austin and Minneapolis host emerging tele-audiology platform clusters serving rural beneficiary populations.
Germany
Hospital procurement networks specify digital patient communication systems for reverberant ward environments. EU MDR clinical evaluation requirements extend certification timelines for new product introductions. Berlin and Munich concentrate audiology clinic density alongside industrial hearing device manufacturing.
Japan
Ministry of Health, Labour and Welfare reimbursement schedules influence feature bundling for elderly beneficiaries. METI accessibility directives mandate assistive listening infrastructure in public venues and transport systems. Osaka and Nagoya anchor manufacturing clusters for infrared and FM transmission equipment.
India
PLI scheme incentives attract electronics manufacturing investment for mid-tier device categories. Expanding private hospital networks create localized distribution footholds outside metropolitan cores. Bengaluru and Hyderabad develop component assembly capacity for Bluetooth-enabled personal amplification systems.
United Kingdom
NHS procurement frameworks prioritize cost-effective digital hearing aid provision for age-related hearing loss. Equality Act accessibility requirements mandate venue compliance with induction loop and infrared installations. London and Manchester concentrate audiology service delivery alongside hearing device retail expansion.
Global Assistive Listening Device Market Competitive Landscape
On the supply side, the industry is consolidating around integrated hearing healthcare platforms with wireless connectivity expertise. Tiered competition separates premium audiology-dependent manufacturers from direct-to-consumer entrants exploiting OTC regulatory pathways. Two strategic archetypes dominate: full-stack hearing instrument developers controlling proprietary signal processing architectures, and venue infrastructure specialists capturing public compliance-driven replacement cycles. Competitive moves concentrate on M&A for tele-audiology capabilities and geographic expansion into Indian manufacturing corridors.
Within the integrated platform tier, GN Hearing A/S and Sonova Holding AG exemplify scale-driven consolidation combining clinical channel presence with consumer electronics interoperability. WS Audiology occupies a position spanning multiple brand architectures and programmable digital platforms. Williams AV represents the venue infrastructure specialization archetype, anchoring large-installation RF and infrared system deployment.
| Leading Market Players |
|---|
| GN Hearing A/S |
| Cochlear Ltd. |
| Sonova Holding AG |
| Williams AV |
| WS Audiology |
| Starkey Hearing Technologies |
| Oticon Inc. |
| Sennheiser |
| Phonak AG |
| Others |
Supply & Pricing Matrix
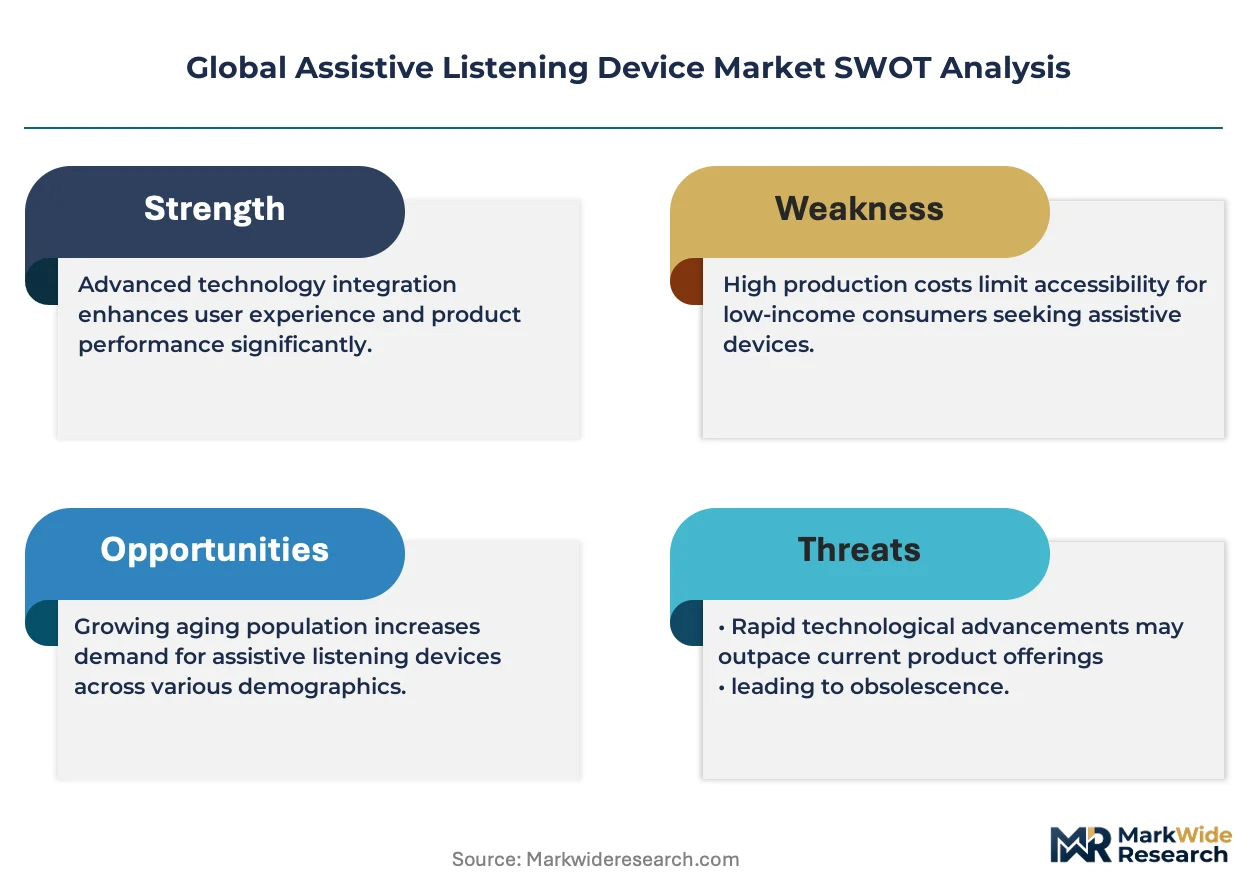
Overcapacity in Taiwan-based semiconductor foundries is compressing digital signal processing chip pricing while simultaneously constraining supplier willingness to expand legacy analog component lines, forcing assistive listening device manufacturers to absorb premium sourcing costs for Bluetooth-enabled architectures or retreat to margin-thinner analog alternatives.
Pricing Analysis
Current-generation Bluetooth Low Energy platforms command three-to-fivefold premiums over prior-generation FM transmission modules and tenfold spreads against basic analog amplification circuits. Pricing stratifies across premium, standard, and economy tiers based on FDA certification tier and programmable channel count, with FDA-cleared OTC devices facing cost compression from direct-to-consumer subscription bundling while prescription-grade audiology products retain pricing power through bundled fitting services. Price erosion runs through the economy tier as smartphone-amplified earbuds capture price-sensitive users seeking basic speech enhancement.
Supply Chain Analysis
Export-control restrictions on advanced lithography equipment to Chinese fabs are concentrating digital signal processing wafer sourcing in Taiwan, South Korea, and the United States, while rechargeable lithium-ion cell production draws from China, Japan, and South Korea. Supply chain vulnerability centers on single-source dependency for 40nm-class Bluetooth audio SoCs fabricated at TSMC Hsinchu facilities. Distribution runs through audiology clinic networks for prescription devices and pharmacy chain logistics for OTC products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of audiologist-calibrated telehealth platforms capable of remote real-ear measurement and algorithmic fitting is constraining market expansion into rural beneficiary populations, creating acquisition value for automated calibration technology stacks.
For Market Incumbents: Harden proprietary signal processing architectures against smartphone-amplified earbud substitution by deepening integration with Auracast broadcast audio infrastructure in public venues. Secure exclusive distribution partnerships with pharmacy chains exploiting FDA OTC regulatory clarity to preempt channel access for emerging competitors. Anchor manufacturing scale in India PLI corridors to offset Taiwan foundry concentration risk and capture mid-tier price point procurement in expanding private hospital networks. For New Entrants and Emerging Players: Build out tele-audiology platform capabilities targeting the United States rural beneficiary population excluded by brick-and-mortar audiology appointment wait times. White-space opportunity concentrates in classroom audio distribution for K-12 inclusion mandates under IDEA, where multi-receiver FM system procurement lacks dominant integrated platform vendors. Pursue hospital system partnerships in Germany specifying digital patient communication systems for reverberant ward environments. For Investors and Strategic Acquirers: Capital is best deployed toward tele-audiology software specialists with FDA-cleared remote fitting algorithms and automated real-ear measurement capabilities. Long-term viability favors platform plays bridging clinical prescription workflows and direct-to-consumer OTC access rather than single-product hardware vendors. Watch FDA enforcement discretion on OTC marketing claims as the inflection signal determining whether pharmacy channel expansion sustains or contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Tele-audiology Platform Acquisition | Captures rural United States populations excluded by brick-and-mortar clinical infrastructure constraints. |
| Auracast Infrastructure Partnership | Locks venue-scale Bluetooth broadcast audio specifications ahead of competing proprietary protocols. |
| India PLI Manufacturing Footprint | Localizes production for mid-tier devices targeting private hospital network procurement expansion. |
| FDA OTC Marketing Authorization | Enables pharmacy chain distribution bypassing traditional audiologist gatekeeping channel control. |
| Remote Fitting Algorithm Development | Automates calibration workflows to compress cost structure against subscription-model competitors. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR notified body certificates, and Bluetooth SIG qualification databases preceded structured interviews with audiology clinic directors, hospital biomedical engineers, GPO contracts managers, and pharmacy chain category buyers. Secondary validation drew from CMS Medicare hearing aid claims data, ADA Title III compliance inspection records, and customs trade statistics for audio electronic component flows. Bottom-up demand modeling triangulated against top-down manufacturer revenue segmentation across product type, technology, and end-user dimensions.
Assumptions held Taiwan foundry capacity utilization and FDA OTC regulatory enforcement patterns within observed ranges while varying Bluetooth Low Energy adoption curves and audiology workforce growth projections across the analysis window. The analytical framework modeled volume and value segmentation by product type, signal processing architecture, distribution channel, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to technology substitution patterns and reimbursement schedule elasticity estimates for elderly beneficiary populations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by consumer electronics platform vendors into hearing health verticals would shift outcomes. Material shifts in FDA enforcement discretion on OTC marketing claims or Taiwan semiconductor export control escalations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Global Medical Loupes Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Laser BPH Devices Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Injection Pen Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Cheek Implants Market