
 Chile Artificial Organs and Bionic Implants Market | 2026-2036
Chile Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Artificial Organs and Bionic Implants Market Outlook
Hospital procurement across Chile is pivoting toward consolidated purchasing agreements managed by regional health service administrations. Medtronic plc leverages its established cardiac rhythm management portfolio to sustain long-term supply relationships with these consolidated buyers. Boston Scientific Corporation anchors its position through deep specialization in interventional cardiology devices tailored to Chilean patient profiles. Zimmer Biomet competes aggressively in orthopedic reconstruction, extending its reach through distributor networks that control access to provincial surgical centers.
Artificial organs and bionic implants comprise electromechanical and biological substitute devices engineered to replace or augment native tissue function, typically incorporating biocompatible alloys, polymers, and sensor arrays that interface with neural or vascular systems. These devices restore physiological performance in patients with end-stage organ failure or traumatic limb loss, operating through integrated power systems and feedback control architectures. Cochlear implants lead installed base volumes due to mature surgical infrastructure and established reimbursement, while bionic limbs represent the fastest-expanding category as myoelectric control systems improve functional outcomes. Artificial intelligence integration across diagnostic and adaptive control modules is concentrating margin pools in technology-enabled segments that command premium positioning.
Chile's ISP national pharmaceutical regulator governs medical device registration under Decreto Supremo 825, enforcing clinical evidence standards that shape market access timelines for novel implantable technologies. ISO 13485 quality management certification serves as a de facto prerequisite for supplier qualification within public hospital tenders, filtering participant pools to established multinationals. The Ministry of Health's progressive incorporation of high-cost procedures into the AUGE guaranteed-benefit regime is expanding patient eligibility for advanced interventions. Stakeholders must monitor regulatory alignment between Chilean standards and MERCOSUR technical harmonization initiatives to anticipate future conformity assessment pathways.
Market Dynamics
Regional health service networks in Chile are consolidating hospital procurement under unified purchasing agreements, compressing vendor pools and elevating ISO 13485 certification to a non-negotiable entry threshold for implantable device suppliers.
Growth Catalysts
- AUGE Regime Expansion:The Ministry of Health's progressive incorporation of high-cost cardiac and orthopedic procedures into Chile's guaranteed-benefit system is widening patient eligibility for advanced implant therapies.
- ISP Streamlining:Chile's national pharmaceutical regulator is accelerating Class III medical device registration pathways, compressing time-to-market for innovative electromechanical implants.
- Santiago Cluster Concentration:Tertiary cardiac centers in the capital metropolitan region are generating disproportionate surgical volumes for complex organ replacement, creating concentrated demand nodes for specialized suppliers.
Market Restraints
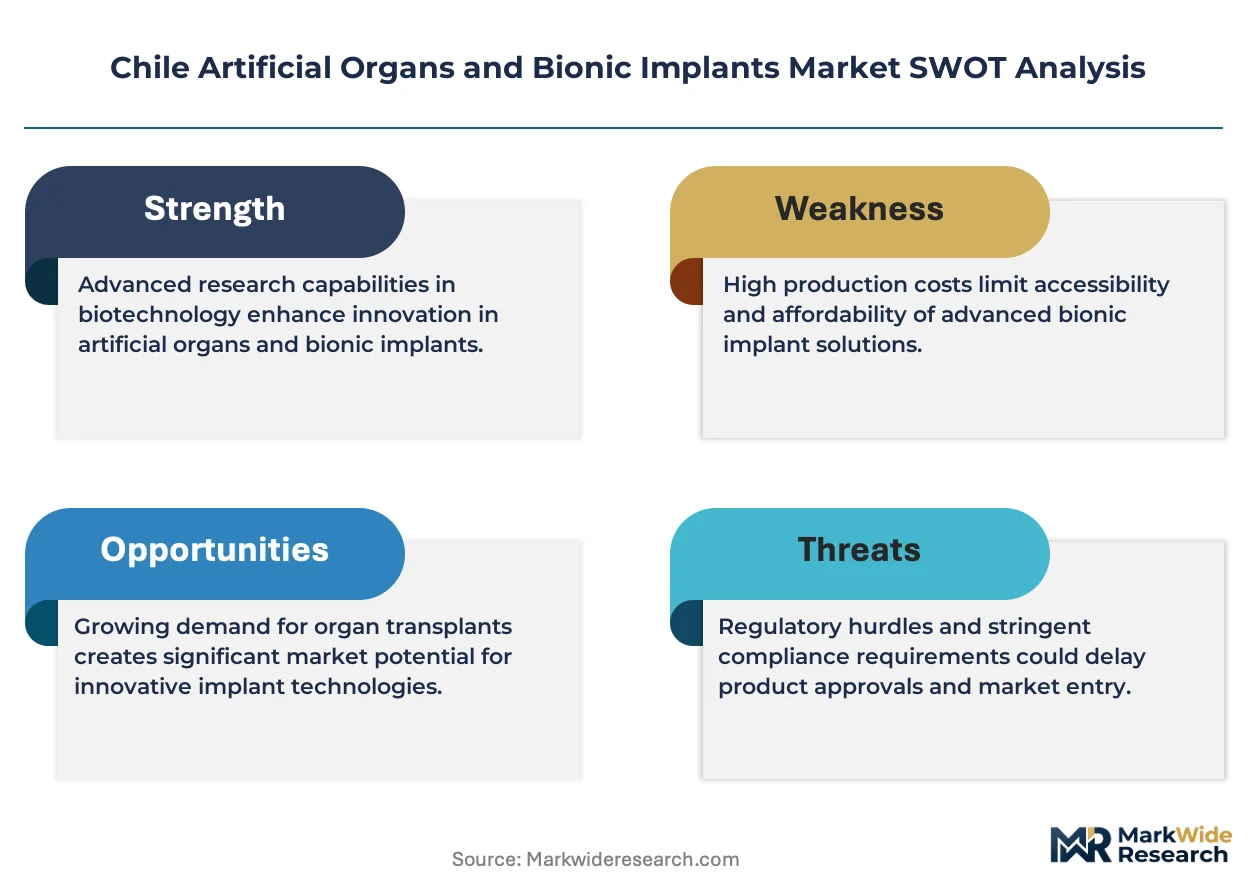
- Import Dependency:Chile's domestic manufacturing base for biocompatible alloys and sensor arrays remains underdeveloped, exposing procurement to currency fluctuation and international supply chain volatility.
- Specialized Surgical Infrastructure:Myoelectric limb implantation requires trained rehabilitation teams and prosthetic fitting centers that concentrate in Santiago, limiting provincial access.
- Reimbursement Lag:Novel bionic categories face delays in securing AUGE coverage codes, stretching payback periods for capital-intensive device investments.
Strategic Opportunities
- Provincial Surgical Networks:Underpenetrated regions such as Biobío and Valparaíso present expansion targets for distributors capable of training local orthopedic surgical teams in advanced reconstruction techniques.
- MERCOSUR Harmonization:Alignment between Chilean ISP standards and regional technical regulations is creating pathways for single-registration access across South American markets.
- AI-Enabled Adaptive Control:Convergence of machine learning with myoelectric signal processing is opening premium positioning for next-generation bionic limbs with self-calibrating neural interfaces.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Chilean universities produce limited graduates in implantable device design and neural interface engineering, forcing reliance on foreign-trained specialists.
- Multi-Site Validation Requirements:ISP clinical evidence standards mandate prospective data collection across multiple hospital systems, extending trial timelines for novel Class III submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Artificial Organs and Bionic Implants Market |
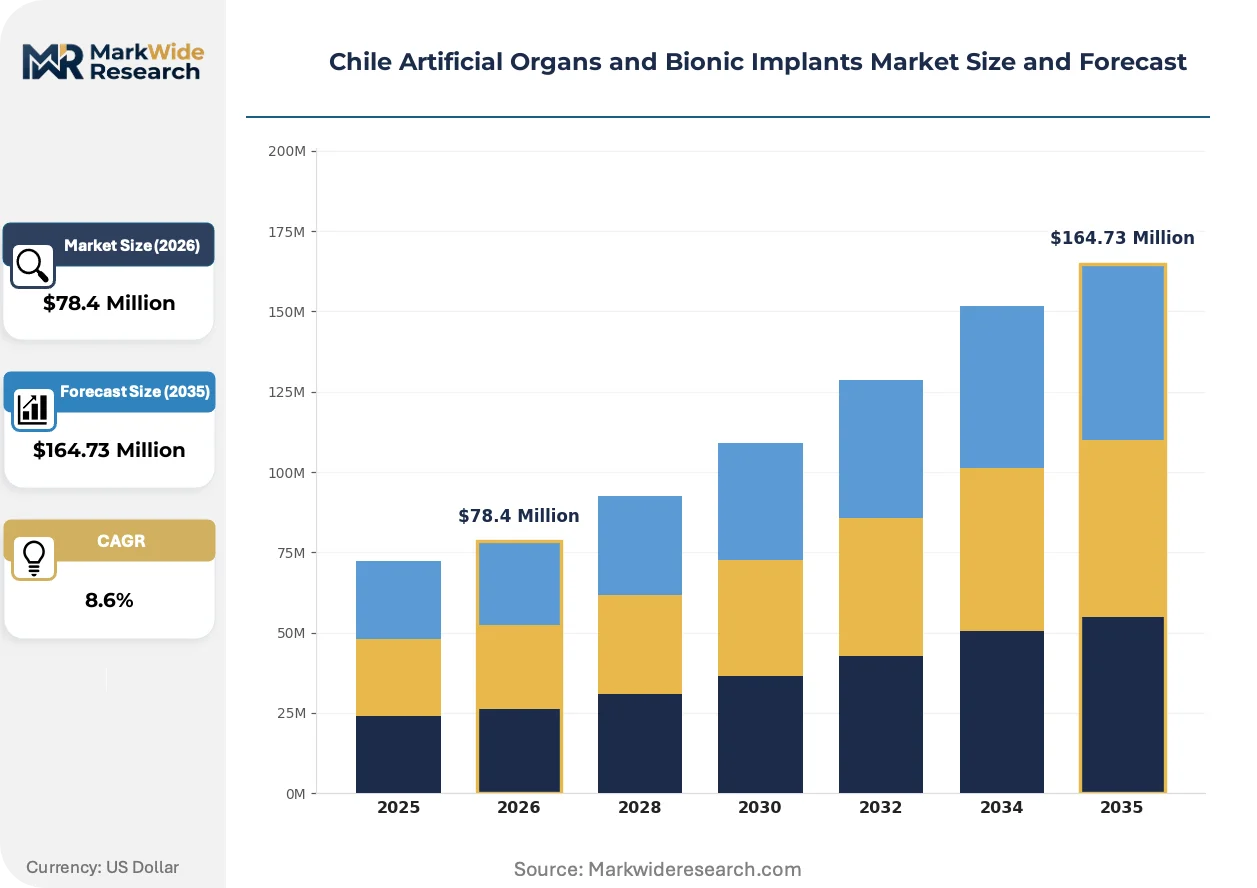
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $164.73 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Heart, Cochlear Implants, Bionic Limbs, Retinal Implants Technology: 3D Bioprinting, Bioelectronic, Artificial Intelligence, Nano-coating End User: Hospitals, Rehabilitation Centers, Research Institutes, Home Care Delivery Mode: Surgical, Outpatient, Remote Monitoring, Telemedicine |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Zimmer Biomet, Otto Bock Holding GmbH & Co. KG, Terumo Corporation, Sonova Holding AG (Advanced Bionics), Edwards Lifesciences Corporation, Cochlear Limited, Ekso Bionics Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Artificial Organs and Bionic Implants Market Strategic Shifts
Neural-signal processing architectures are compressing the functional gap between prosthetic and native limb control, while regulatory convergence and procurement rationalization are restructuring competitive access across Chilean healthcare networks.
Myoelectric control systems are expanding into Chilean orthopedic practice through improved signal-to-motion translation algorithms that reduce calibration time. Provincial rehabilitation centers are adopting these platforms as training protocols standardize. The technology is expanding into previously underserved patient segments by lowering the specialist skill threshold for device fitting.
Chile's ISP is aligning Class III device registration requirements with MERCOSUR technical harmonization initiatives, reducing redundant conformity assessments for multinational suppliers. This regulatory convergence is compressing administrative burdens for manufacturers already certified under Brazilian ANVISA or Argentine equivalent frameworks. Cardiac implant categories are responding fastest, with rhythm management device sponsors prioritizing synchronized dossier submissions.
Consolidated purchasing agreements administered by regional health service administrations are displacing hospital-level procurement autonomy across Chile's public system. Device vendors are restructuring sales organizations to interface directly with centralized technical evaluation committees rather than individual hospital material managers. The Valparaíso and Maule regional health services are furthest advanced in this transition, with Santiago metropolitan networks following.
Chile Artificial Organs and Bionic Implants Market Segmentation
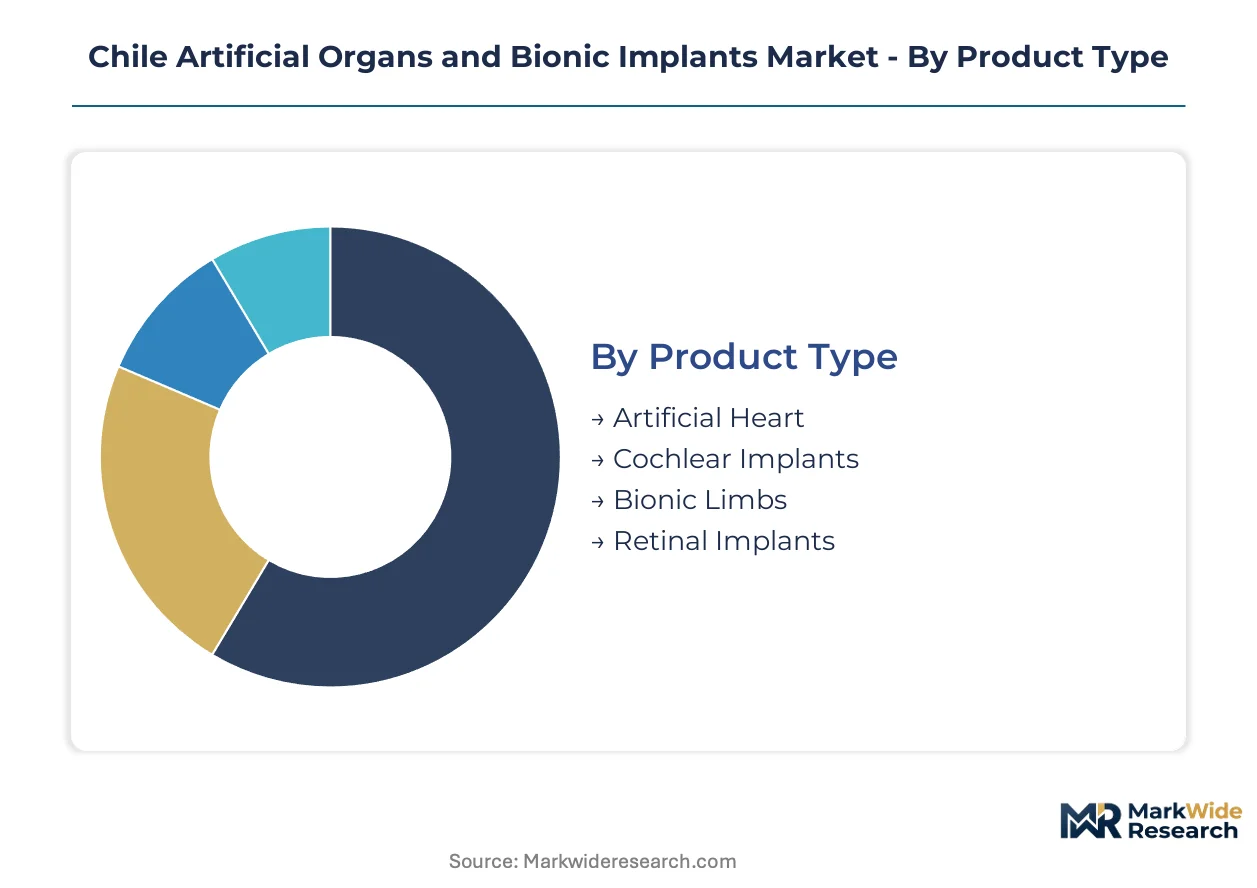
Segmentation in Chile's artificial organs and bionic implants market reveals how procurement consolidation, technology maturity, and reimbursement pathways concentrate demand across distinct product and delivery categories. Understanding these divisions exposes where vendor qualification thresholds and clinical evidence requirements create barriers or openings for market access.
Product Type:
Purchasing committees weigh long-term total cost of ownership against upfront device costs, with reimbursement status under AUGE heavily influencing selection criteria.
- Artificial Heart:These electromechanical circulatory support systems incorporate biocompatible alloys and transcutaneous power transfer. Santiago's tertiary cardiac centers generate concentrated demand as complex organ replacement volumes outpace provincial regions, though reimbursement lag stretches capital recovery timelines.
- Cochlear Implants:Mature neuroprosthetic devices with established surgical infrastructure and guaranteed AUGE coverage. Demand concentrates in pediatric and post-lingual deafness populations where Santiago's auditory rehabilitation networks dominate installed base volumes.
- Bionic Limbs:Myoelectric prosthetics with sensor-driven neural interfaces. Provincial expansion accelerates as standardized training protocols reduce specialist dependency.
- Retinal Implants:Subretinal and epiretinal electrode arrays for degenerative vision loss. Limited penetration reflects narrow eligible populations and restricted AUGE inclusion.
Cochlear implants lead on scale; bionic limbs lead on momentum.
Technology:
Margin pools concentrate in segments where regulatory pathways have stabilized and clinical evidence libraries support faster ISP registration.
- 3D Bioprinting:Additive manufacturing of patient-specific scaffolds and tissue constructs. Research institutes in Santiago pilot applications while commercial scale awaits GMP infrastructure.
- Bioelectronic:Implantable devices interfacing with neural or muscular tissue through biocompatible electrodes. Cardiac rhythm management and cochlear applications dominate near-term revenue.
- Artificial Intelligence:Adaptive control algorithms and predictive diagnostics embedded in implantable systems. Self-calibrating neural interfaces command premium positioning as machine learning compresses prosthetic-native functional gaps.
- Nano-coating:Surface modification technologies enhancing biocompatibility and reducing fibrotic encapsulation. Orthopedic and cardiovascular implants adopt these layers to extend device longevity.
Bioelectronics dominates current revenue; artificial intelligence climbs the fastest.
End User:
Procurement authority and technical evaluation capabilities vary sharply across settings, shaping vendor sales organization design.
- Hospitals:Tertiary centers in Santiago perform complex implantations requiring specialized surgical teams and intensive care infrastructure. Regional health service networks consolidate purchasing agreements, elevating ISO 13485 to entry threshold.
- Rehabilitation Centers:Provincial facilities in Biobío and Valparaíso expand prosthetic fitting capacity as training protocols standardize myoelectric limb calibration.
- Research Institutes:Clinical trial sites generate ISP-mandated multi-site validation data for Class III device registrations.
- Home Care:Remote device monitoring and patient self-management platforms. Limited penetration reflects infrastructure gaps outside metropolitan regions.
Hospitals command procurement volume; rehabilitation centers gain share fastest.
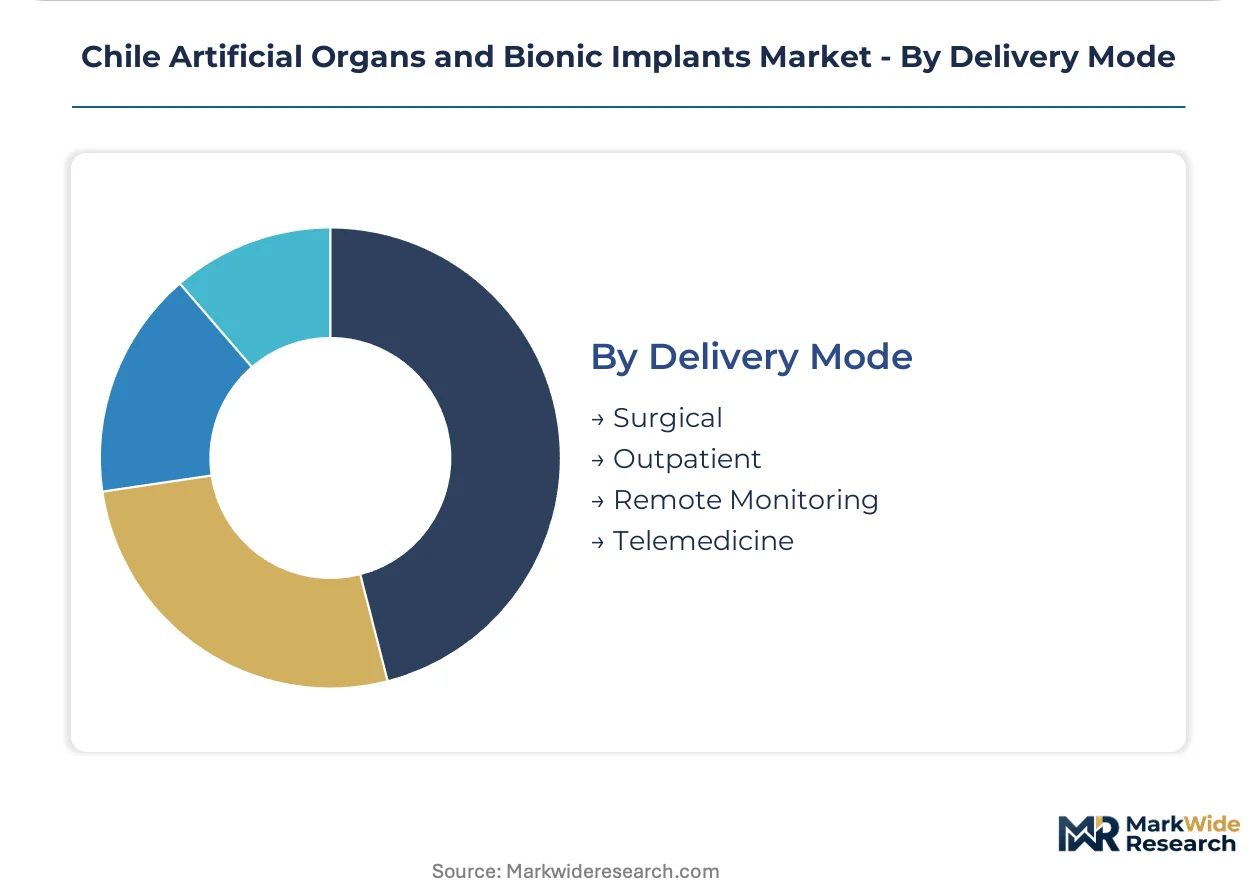
Delivery Mode:
Reimbursement coding and facility accreditation requirements determine which delivery channels can sustain commercial viability.
- Surgical:Inpatient implantation procedures requiring operating theater capacity and anesthesia support. Complex cardiac and neural implants depend on this pathway.
- Outpatient:Same-day discharge protocols for established implant categories with streamlined recovery profiles. Cost pressure favors migration where clinically appropriate.
- Remote Monitoring:Telemetry-enabled implants transmitting physiological data to clinical teams. Cardiac rhythm management devices lead adoption.
- Telemedicine:Virtual consultation and rehabilitation guidance reducing geographic access barriers. Provincial expansion accelerates post-implant follow-up coverage.
Surgical delivery anchors revenue; telemedicine expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's cardiac implant volumes outpace Chile's by a factor of four, yet Chile's per-capita penetration of cochlear devices exceeds that of its larger neighbor, reflecting divergent healthcare infrastructure priorities across Latin America.
Brazil
ANVISA's streamlined registration pathways for Class III cardiac devices accelerate market entry for rhythm management manufacturers. São Paulo's Instituto do Coração anchors complex implant volumes, while Minas Gerais expands provincial access through telemedicine-linked follow-up protocols. The government's RENEM registry mandates device traceability, elevating compliance costs for entrants.
Argentina
Economic volatility compresses procurement cycles for high-value bionic implants, forcing vendors toward leasing structures. ANMAT's alignment with MERCOSUR technical standards reduces redundant conformity assessments for multinationals already certified in Brazil. Buenos Aires clusters dominate demand, with Córdoba emerging as a secondary cardiac surgery hub through public-private partnerships.
Mexico
COFEPRIS's 2023 equivalence agreements with FDA compress review timelines for pre-approved US devices. Mexico City's Instituto Nacional de Cardiología generates concentrated demand for ventricular assist devices, while Monterrey's private hospital networks drive orthopedic bionic adoption. The INSABI public insurance expansion widens patient eligibility for cochlear interventions.
Colombia
INVIMA's risk-based classification system prioritizes review resources toward novel neural interface technologies. Bogotá's Fundación Cardioinfantil performs the majority of complex pediatric cardiac implants, with Medellín's rehabilitation institutes advancing myoelectric limb fitting capacity. The POS mandatory insurance regime's technology inclusion committee determines reimbursement velocity for emerging categories.
Peru
DIGEMID's decentralized regional offices extend registration support to Andean provinces, reducing Lima-centric bottlenecks. The capital's Instituto Nacional Cardiovascular remains the sole site for total artificial heart implantation, while Arequipa builds orthopedic reconstruction capacity through Ministry of Health training programs. SUNSIS insurance expansion lags regional peers, constraining private market development.
Chile Artificial Organs and Bionic Implants Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Chile's procurement landscape, creating a tiered structure where scale advantages meet clinical depth. The vendor base concentrates around cardiac rhythm management, interventional cardiology, and orthopedic reconstruction, with neural prosthetic categories showing greater fragmentation. Three archetypes dominate: integrated multinationals with broad cardiovascular portfolios, limb-focused specialists with distributor-heavy models, and auditory device pure-plays with established rehabilitation networks. Competitive moves center on ISO 13485 certification maintenance for public tender eligibility and direct engagement with consolidated regional health service purchasing committees.
Among the integrated cardiovascular-focused multinationals, Medtronic plc and Boston Scientific Corporation exemplify the scale-driven archetype, anchoring long-term supply relationships through comprehensive device portfolios and clinical training infrastructure. Zimmer Biomet occupies a distinct position within orthopedic reconstruction, leveraging distributor networks to extend reach beyond Santiago's tertiary centers into provincial surgical markets. These three entities collectively represent the consolidation-resistant core of Chile's implantable device procurement landscape, with each embedding differently across public hospital networks and private clinic chains.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Zimmer Biomet |
| Otto Bock Holding GmbH & Co. KG |
| Terumo Corporation |
| Sonova Holding AG (Advanced Bionics) |
| Edwards Lifesciences Corporation |
| Cochlear Limited |
| Ekso Bionics Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up distributors controlling provincial surgical access in Chile are compressing procurement timelines while simultaneously extracting margin concessions from implant manufacturers, linking supply chain gatekeeping power directly to pricing discipline across public hospital networks.
Pricing Analysis
Capacity additions in Brazilian orthopedic component manufacturing are reshaping price floors for myoelectric limb systems entering Chile through MERCOSUR trade corridors. Contract-based long-term offtake agreements dominate cardiac implant procurement, with ISO 13485 certification tier and volume scale driving price differentiation between established multinationals and qualified second-tier suppliers. Cost compression in standard-grade orthopedic reconstruction is intensifying because regional health service networks are consolidating purchasing committees. Provincial surgical centers exhibit the highest price sensitivity due to constrained AUGE reimbursement bandwidth, while Santiago's tertiary cardiac centers prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Freight costs for temperature-controlled biocompatible alloy shipments from Germany, Switzerland, and the United States constitute a persistent cost layer for Chilean distributors serving Andean provincial markets. Raw material dependencies center on titanium alloys, platinum-iridium electrodes, and medical-grade silicone polymers sourced from established European and North American foundries. Single-source vulnerability concentrates in sensor array microfabrication, where Taiwanese and South Korean foundries anchor global capacity. Distribution runs through ISO 13485-certified medical device distributors that maintain direct contractual relationships with regional health service procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's artificial organs and bionic implants market functions as a geographic-arbitrage play where regulatory alignment with MERCOSUR standards enables Brazilian-manufactured components to access Chilean procurement at lower conformity assessment cost than US or EU-origin alternatives.
For Market Incumbents: Anchor long-term supply relationships by embedding clinical training infrastructure within Santiago's tertiary cardiac centers, defending against emerging pure-play neural prosthetic specialists. Prioritize backward integration into sensor array sourcing to mitigate single-foundry exposure from Taiwanese suppliers. Deepen ISO 13485 certification maintenance investments to preserve eligibility for consolidated regional health service tenders.
For New Entrants and Emerging Players: The premium-to-economy price gap in myoelectric limb systems creates entry space for mid-tier suppliers capable of standardized fitting protocols. Provincial rehabilitation networks in Biobío and Valparaíso represent the most penetrable geography given underdeveloped specialist infrastructure. Pursue direct partnerships with regional health service technical evaluation committees rather than distributor intermediation.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap limb-focused specialists with established Chilean distributor relationships but limited R&D depth. Long-term viability hinges on AI-enabled adaptive control differentiation compressing functional gaps with native limb performance. Monitor ISP Class III registration velocity for myoelectric categories as the inflection signal indicating regulatory pathway maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| ISP Class III Registration Pathway | Accelerates market entry for novel electromechanical implants through streamlined clinical evidence review. |
| Regional Health Service Partnership | Secures preferred vendor status within consolidated procurement frameworks governing public hospital purchasing. |
| AI Companion Software Development | Enables premium positioning for self-calibrating neural interfaces in next-generation bionic limb systems. |
| MERCOSUR Harmonization Alignment | Reduces redundant conformity assessments for manufacturers certified under Brazilian ANVISA frameworks. |
| Provincial Surgical Training Program | Expands addressable market by reducing specialist dependency for myoelectric limb fitting in underserved regions. |
Study Parameters
Multiple input streams — primary interviews with cardiac surgeons and biomedical engineers, hospital procurement database analysis, and ISP regulatory filing review — were reconciled to construct demand estimates. Stakeholder consultations encompassed GPO contracts managers, regional health service technical evaluators, and distributor operations heads across Santiago, Valparaíso, and Biobío. Secondary validation drew from ANVISA registration databases, MERCOSUR technical regulation harmonization documents, and Chilean Ministry of Health AUGE procedure inclusion records. Bottom-up surgical volume modeling and top-down healthcare expenditure allocation were cross-referenced for triangulation.
Historical implant procedure volumes were cross-referenced against panel input from procurement executives to establish baseline demand patterns across the projection horizon. Segmentation dimensions encompassed product type, technology maturity tier, end-user facility category, and delivery mode complexity. CAGRs were derived from surgical volume growth trajectories weighted against reimbursement expansion schedules. Forecast inputs incorporated AUGE coverage code inclusion velocity and ISP registration pathway efficiency metrics specific to Class III device categories.
Caveats apply where reimbursement lag for novel bionic categories or currency fluctuation impacting import-dependent supply chains could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Catheters Market
Medical Devices
Bathroom and Toilet Assist Devices Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Neurotechnology Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Global Biliary Stents Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Global Pacemakers Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Ocular Adhesive Market
Medical Devices
Global Medical Sensor Market