
 Disposable Needle Guides Market | 2026-2036
Disposable Needle Guides Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Needle Guides Market Outlook
MDR Article 52 reclassification of certain needle guidance accessories is repositioning the competitive landscape toward disposable formats. CIVCO Medical Solutions leverages its ultrasound probe integration expertise to dominate hospital procurement channels. Aspen Surgical sustains manufacturing scale across standard and biopsy needle guide portfolios. Siemens Healthineers anchors its position through bundled imaging system contracts that incorporate proprietary guide compatibility.
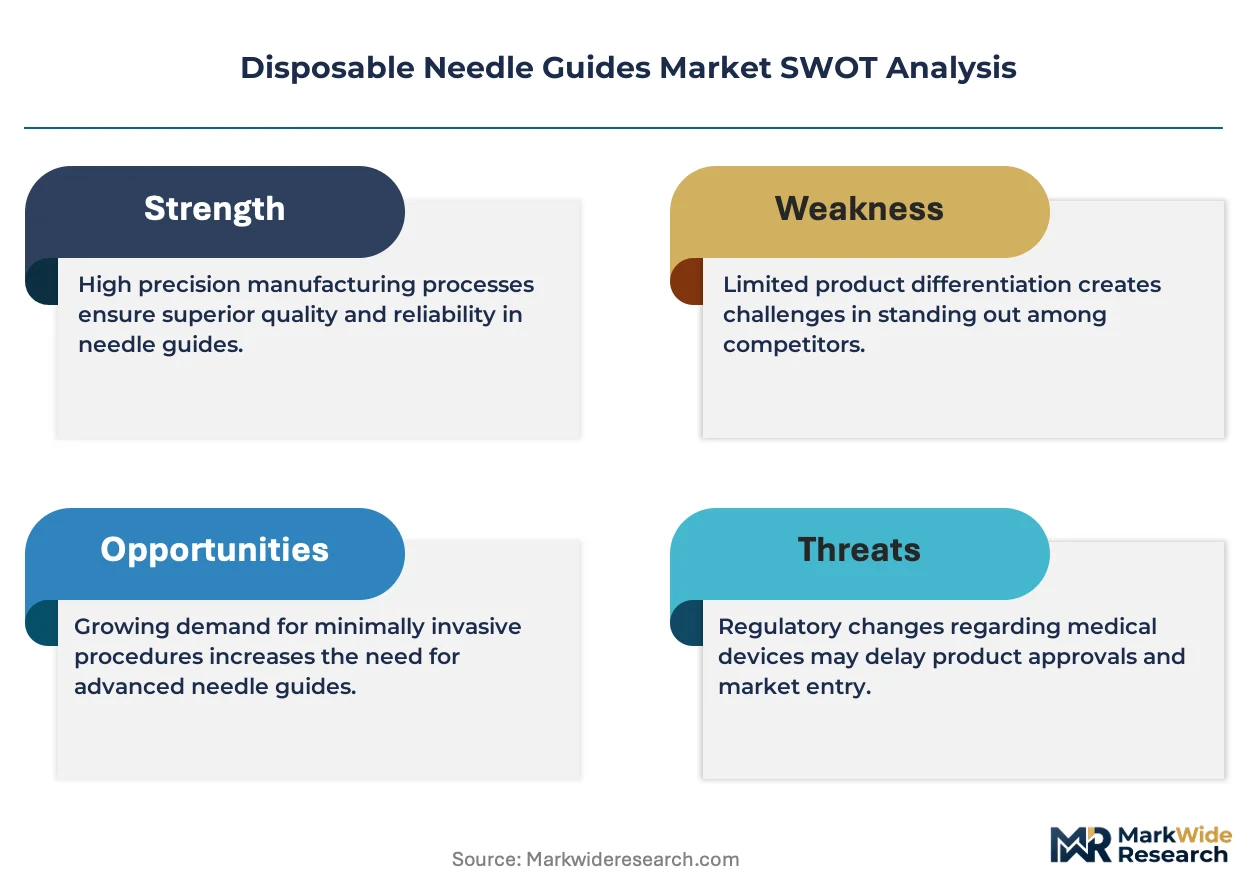
Disposable needle guides are sterile, single-use instruments typically molded from medical-grade polymers such as polycarbonate or ABS, designed to attach to ultrasound transducers or operate freehand for precise needle trajectory alignment during percutaneous procedures. Their primary purpose is to eliminate cross-contamination risk while improving procedural accuracy in biopsy, drainage, and regional anesthesia applications. Ultrasound needle guides command the largest revenue share due to their integration with high-frequency linear and curvilinear probes used in vascular access and musculoskeletal interventions. Biopsy needle guides represent the fastest-expanding product category as image-guided tissue sampling displaces open surgical diagnostic methods. Within end users, ambulatory surgical centers are capturing disproportionate growth as outpatient interventional volumes shift away from traditional hospital settings.
FDA enforcement of 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements are compelling manufacturers to maintain exhaustive sterilization validation and clinical performance data. ISO 13485 certification has become a baseline qualification for distributor access rather than a differentiator. Health Canada and Japan's PMDA maintain aligned but distinct biocompatibility testing protocols that fragment regulatory submission strategies. Stakeholders must monitor evolving single-use plastic reduction mandates in European jurisdictions, as these sustainability frameworks could impose material substitution timelines that disrupt existing supply chains and force reformulation investments.
Market Dynamics
EU MDR Article 52 reclassification is forcing manufacturers to abandon reusable needle guide formats entirely, compressing product development cycles and redistributing procurement power toward sterile single-use suppliers with validated sterilization infrastructure.
Growth Catalysts
- FDA 21 CFR Part 820 enforcement:Quality system mandates elevate barriers for reusable device competitors, channeling hospital procurement toward pre-validated disposable formats with established sterilization documentation.
- Ambulatory surgical center expansion:Outpatient interventional volume migration creates addressable demand for single-use accessories that eliminate reprocessing infrastructure requirements.
- Polycarbonate material advances:Medical-grade polymer formulation improvements enable thinner-wall guide geometries that maintain structural integrity during high-gauge needle insertions.
Market Restraints
- Medical-grade polymer cost volatility:Polycarbonate and ABS resin prices fluctuate with petrochemical feedstock markets, compressing margin structures for molded component manufacturers.
- Asian mold fabrication concentration:Precision injection tooling capacity clusters in Dongguan and Shenzhen, creating geographic supply risk for Western brands without captive mold assets.
- Reusable guide residual demand:Some cost-constrained health systems in Eastern Europe and Latin America continue reprocessing metal guides despite infection control guidelines.
Strategic Opportunities
- India imaging infrastructure buildout:Government hospital ultrasound deployment programs create first-mover advantage for disposable guide suppliers establishing distribution through domestic medical device distributors.
- Point-of-care ultrasound integration:Handheld wireless probe proliferation enables guide formats designed for compact transducers without traditional bracket mounting systems.
- EU single-use plastic reduction carve-outs:Medical device exemptions from SUP directives position sterile guides as compliant alternatives to reusable formats facing sustainability scrutiny.
Industry Challenges
- ISO 13485 certification timeline compression:Accelerated EU MDR compliance deadlines strain quality management system implementation capacity across mid-tier manufacturers.
- Legacy probe compatibility mapping:Ultrasound transducer form factor fragmentation across GE, Philips, and Siemens installed bases forces SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Needle Guides Market |
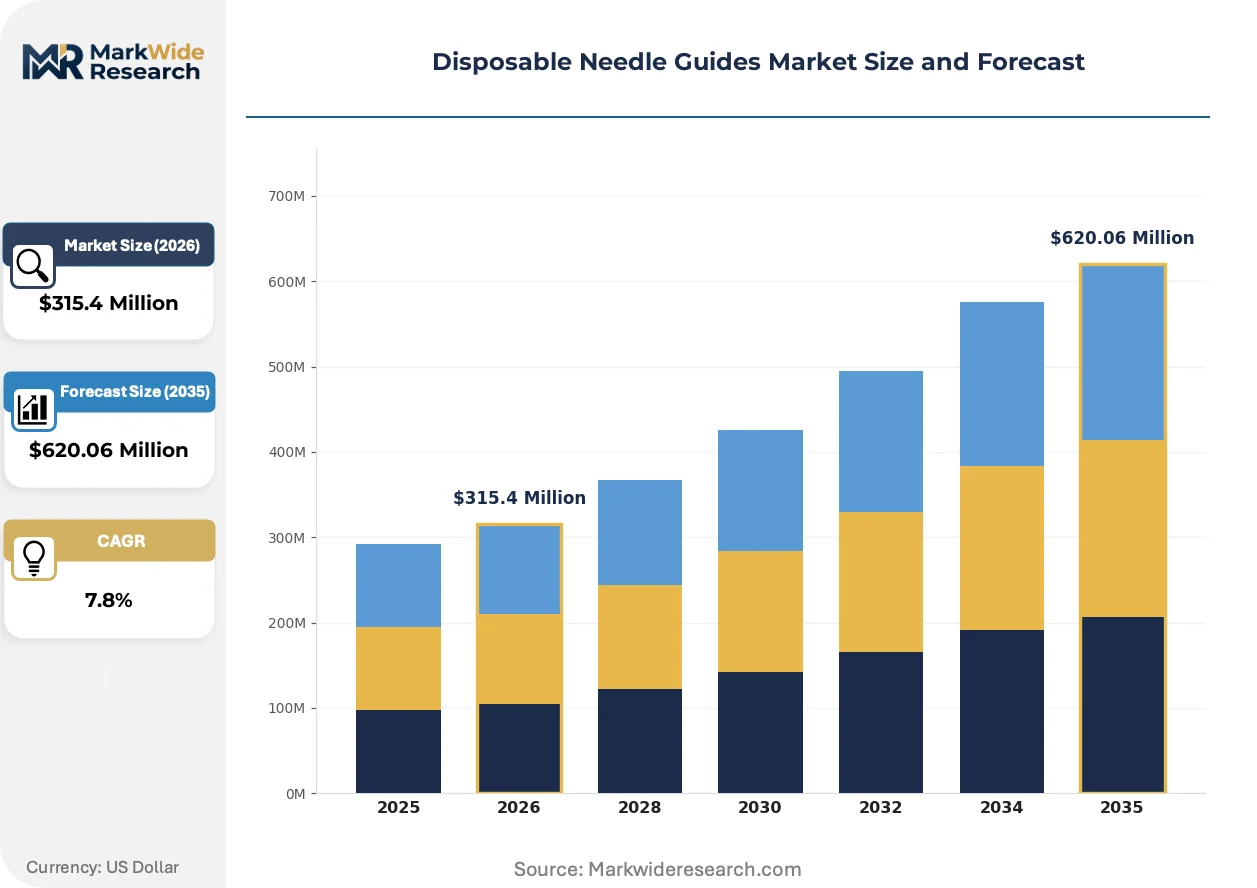
| Market Size in 2026 | $315.4 Million |
| Market Size in 2035 | $620.06 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Needle Guides, Standard Needle Guides, Biopsy Needle Guides, Spinal Needle Guides Application: Diagnostic Procedures, Surgical Procedures, Interventional Procedures, Pain Management End User: Hospitals, Clinics, Ambulatory Surgical Centers, Imaging Centers Distribution Channel: Online Retail, Direct Sales, Medical Distributors, Wholesalers |
| Companies Covered | CIVCO Medical Solutions, Aspen Surgical, FUJIFILM Sonosite, Becton Dickinson and Company, Argon Medical Devices, Siemens Healthineers, GE Healthcare, Hologic, Rocket Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Needle Guides Market Strategic Shifts
Disposable needle guide evolution centers on three intersecting vectors: material science enabling geometric miniaturization, regulatory pressure eliminating reusable alternatives, and procurement centralization favoring suppliers with integrated sterilization validation.
3D-printed polycarbonate lattice structures are electrifying biopsy guide design by enabling patient-specific needle trajectory channels with integrated depth stops. Academic medical centers in Germany and the United States are piloting these formats for complex musculoskeletal interventions. This customization capability is compressing the addressable market for standard-angle guides in high-complexity procedures.
EU MDR technical documentation requirements are reshaping competitive access by mandating clinical performance data for all needle guidance accessories reclassified as Class IIa devices. Manufacturers must now maintain post-market surveillance systems and periodic safety update reports. Smaller reusable guide suppliers in Italy and Spain are exiting rather than absorbing compliance infrastructure costs.
Hospital procurement consolidation is consolidating vendor panels around suppliers offering comprehensive ultrasound accessory portfolios. Integrated delivery networks in the United States now mandate single-source contracts covering probes, guides, and disposable covers. This behavior is most visible in Texas and Florida health systems where ambulatory surgery center rollups have concentrated purchasing authority.
Disposable Needle Guides Market Segmentation
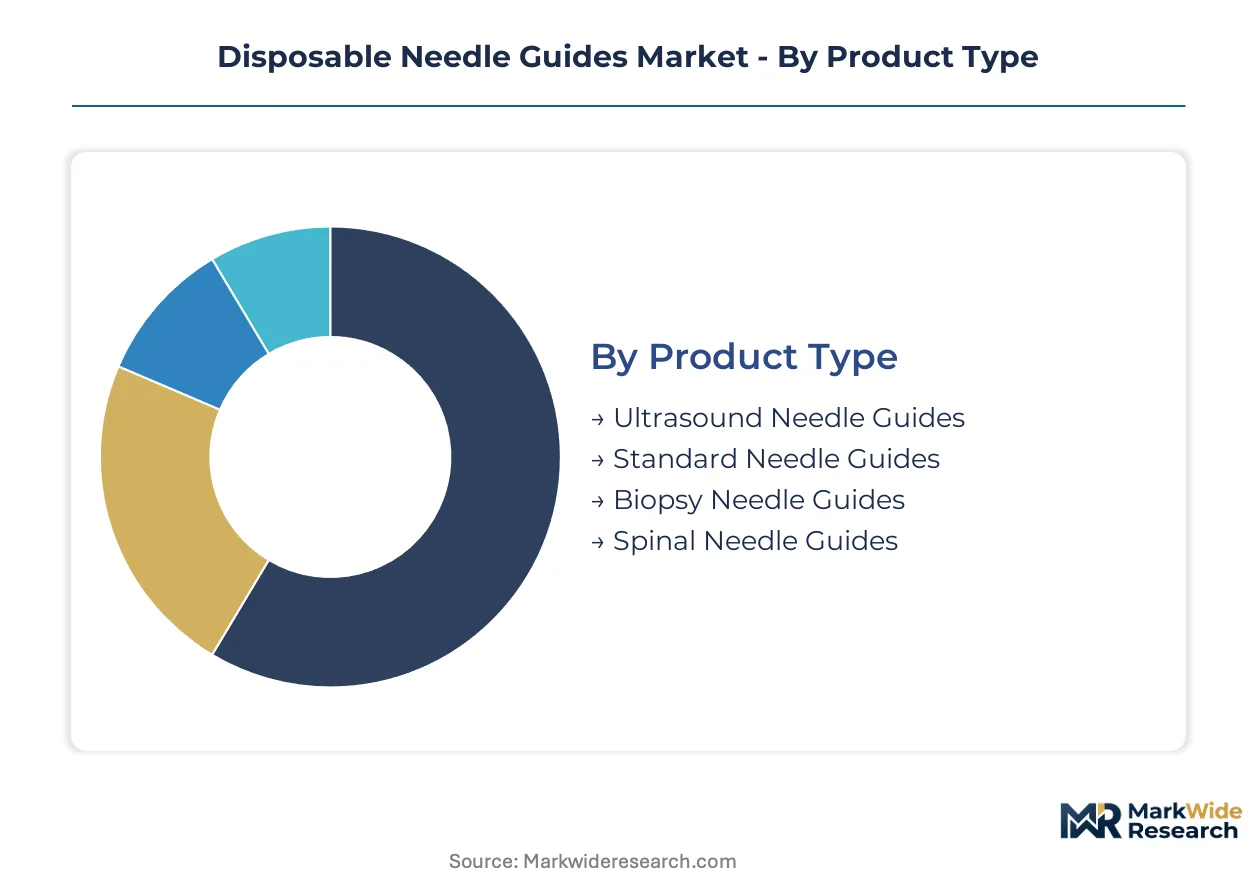
Segmentation in disposable needle guides reflects divergent sterilization requirements across procedure types and procurement centralization pressures reshaping channel economics. Manufacturers must align polymer formulation capabilities with specific imaging modalities while navigating distribution consolidation in integrated health networks.
Product Type:
Standardization dominates high-volume disposable formats while customization gains traction in complex interventional applications requiring patient-specific trajectory alignment.
- Ultrasound Needle Guides:Molded polycarbonate brackets interface with linear and curvilinear transducers for vascular access and musculoskeletal procedures. Demand concentrates in United States hospital systems where FDA 21 CFR Part 820 compliance elevates procurement toward pre-validated sterile formats. These guides eliminate cross-contamination risk in high-frequency ultrasound-guided interventions.
- Biopsy Needle Guides:Precision-molded channels with integrated depth stops enable percutaneous tissue sampling under image guidance. Germany and China drive expansion as image-guided diagnostic methods displace open surgical biopsies in oncology workflows. 3D-printed lattice variants are piloting in academic medical centers for complex anatomical access.
- Standard Needle Guides:General-purpose single-use instruments serve routine injection and aspiration procedures across primary care settings.
- Spinal Needle Guides:Specialized geometries align with neuraxial anesthesia applications requiring exact midline trajectory control.
Most installed capacity flows through Ultrasound Needle Guides. Expansion is steepest in Biopsy Needle Guides.
Application:
Procedure reimbursement tiers and infection control stringency create divergent margin profiles across clinical use cases.
- Interventional Procedures:Real-time image-guided catheter placement, drainage, and ablation demand sterile single-use guides with validated compatibility across transducer portfolios. United States ambulatory surgical centers are capturing disproportionate volume as outpatient interventional migration accelerates.
- Diagnostic Procedures:Image-guided tissue sampling and fluid aspiration require precise needle trajectory control for specimen adequacy. China government hospital ultrasound deployment programs are expanding addressable demand for disposable formats in provincial diagnostic networks.
- Surgical Procedures:Intraoperative needle localization and marker placement utilize sterile guides in operating room environments.
- Pain Management:Regional anesthesia and neurolytic blocks employ single-use guides for neuraxial and peripheral nerve access.
Interventional Procedures command the dominant revenue share. Diagnostic Procedures are climbing the fastest as early-stage cancer screening protocols expand.
End User:
Capital intensity and reprocessing infrastructure availability determine facility-level adoption of disposable versus reusable formats.
- Ambulatory Surgical Centers:Outpatient facilities lacking central sterile processing departments favor single-use guides eliminating reprocessing capital expenditure. United States ASC rollups in Texas and Florida have concentrated purchasing authority around comprehensive ultrasound accessory contracts.
- Hospitals:Acute care institutions with integrated imaging departments maintain bulk procurement of sterile guides across radiology, anesthesiology, and interventional suites. Germany university hospitals lead EU MDR compliance-driven transitions from reusable metal guides.
- Clinics:Primary and specialty care offices utilize standard guides for routine injection procedures.
- Imaging Centers:Dedicated diagnostic facilities employ biopsy-specific guides for outpatient tissue sampling workflows.
Hospitals retain the largest installed base. Ambulatory Surgical Centers are gaining share fastest as procedural volume shifts to outpatient settings.
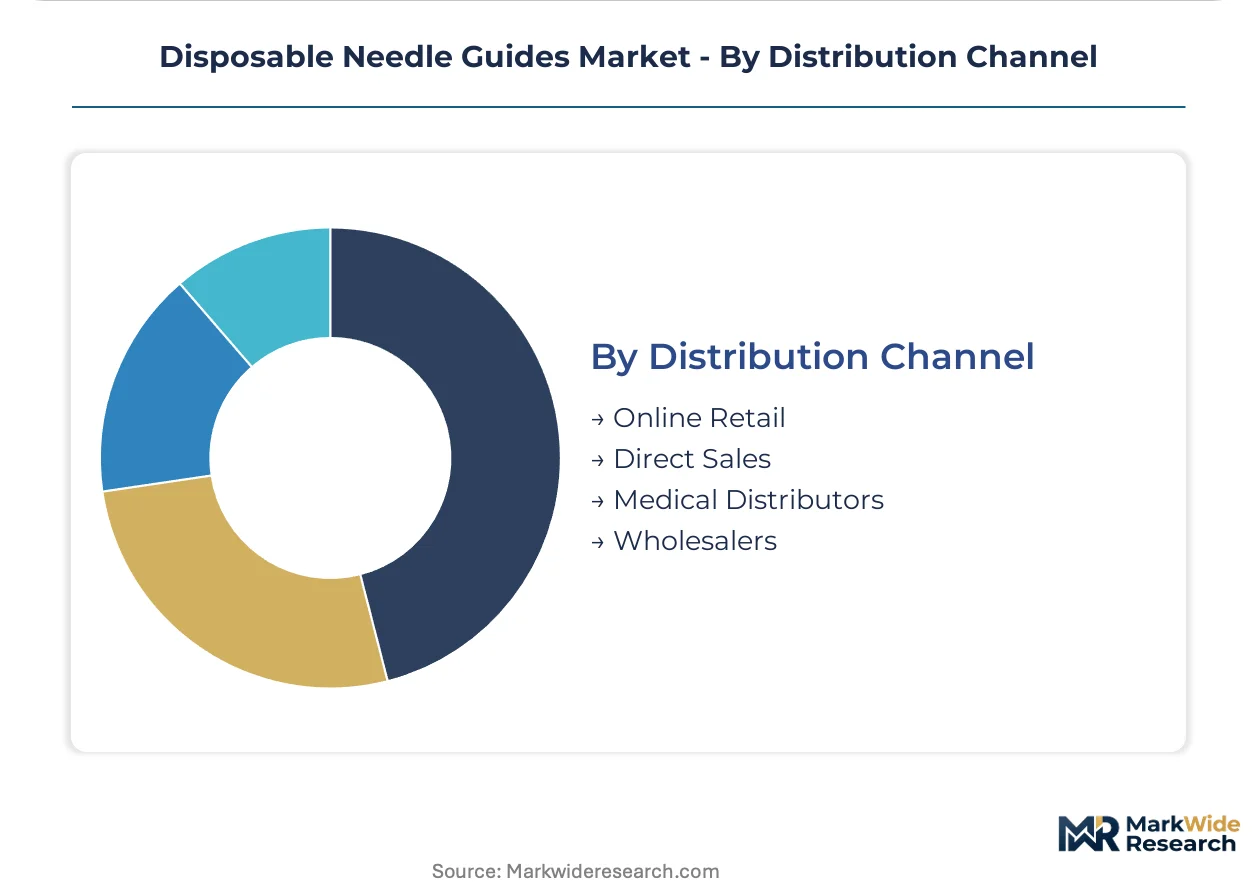
Distribution Channel:
Channel selection reflects order fragmentation versus procurement centralization tensions across health system configurations.
- Medical Distributors:Specialized device distributors with ISO 13485-certified warehousing dominate hospital and ASC procurement in mature markets. CIVCO Medical Solutions and Aspen Surgical leverage established distributor relationships for probe-compatible guide portfolios.
- Direct Sales:Bundled imaging system contracts through manufacturers like Siemens Healthineers incorporate proprietary guide compatibility as a lock-in mechanism. Direct channels capture high-volume health system accounts with consolidated purchasing authority.
- Online Retail:E-commerce platforms serve small clinic and individual practitioner segments with standard guide formats.
- Wholesalers:General medical supply wholesalers handle commodity-grade guides for cost-constrained settings.
Medical Distributors handle the majority of transaction volume. Direct Sales are expanding most quickly as imaging OEMs consolidate accessory bundling strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional radiologists and anesthesiologists concentrate in urban medical centers across Germany, the United States, China, India, and Japan, anchoring procedural demand for sterile single-use needle guidance accessories.
United States
Ambulatory surgical center rollups in Texas and Florida concentrate purchasing authority around comprehensive ultrasound accessory contracts. FDA enforcement of 21 CFR Part 820 quality system regulations elevates procurement toward pre-validated disposable formats. Boston and Minneapolis medical device clusters house sterilization validation laboratories serving domestic manufacturers.
Germany
University hospitals in Munich and Heidelberg lead EU MDR compliance-driven transitions from reusable metal guides to sterile single-use formats. EMA coordination with notified bodies accelerates technical documentation reviews for Class IIa needle guidance accessories. The Baden-Württemberg precision molding corridor supplies medical-grade polycarbonate components to Western European device assemblers.
China
Government hospital ultrasound deployment programs in provincial diagnostic networks expand addressable demand for disposable biopsy guides. NMPA biocompatibility testing protocols for medical-grade polymers streamline domestic manufacturer market access. Dongguan and Shenzhen injection molding clusters concentrate precision tooling capacity for polycarbonate guide fabrication.
India
Government hospital imaging infrastructure buildout creates first-mover advantage for disposable guide suppliers establishing distribution through CDSCO-registered domestic medical device distributors. PLI scheme incentives for medical device manufacturing attract molding capacity to Gujarat and Maharashtra industrial corridors. Hyderabad and Bangalore diagnostic center clusters drive outpatient interventional volume growth.
Japan
Academic medical centers in Tokyo and Osaka pilot 3D-printed patient-specific biopsy guide formats for complex musculoskeletal interventions. PMDA alignment with ISO 13485 quality management standards streamlines regulatory submission pathways for polymer-based single-use devices. The Nagoya medical device manufacturing belt supplies precision-molded components to domestic ultrasound OEMs.
Disposable Needle Guides Market Competitive Environment
The competitive structure tilts toward imaging system integrators with probe compatibility expertise. Hospital procurement consolidation and bundled equipment contracts favor suppliers offering comprehensive ultrasound accessory portfolios alongside validated sterilization documentation. Three archetypes dominate: imaging OEMs with proprietary guide lock-in strategies, specialized disposable device manufacturers with distributor channel depth, and contract molders supplying white-label components. Dominant competitive moves include strategic partnerships for probe compatibility certification and geographic expansion through ISO 13485-certified distributor networks.
Among imaging-integrated suppliers, CIVCO Medical Solutions and Siemens Healthineers exemplify the equipment-bundling archetype, anchoring hospital procurement through transducer compatibility ecosystems. Aspen Surgical occupies a position within the specialized disposable device tier, representing manufacturing scale across standard and biopsy needle guide portfolios. These three entities collectively illustrate how probe integration expertise and sterilization validation infrastructure determine competitive access in procurement-centralized health systems.
| Leading Market Players |
|---|
| CIVCO Medical Solutions |
| Aspen Surgical |
| FUJIFILM Sonosite |
| Becton Dickinson and Company |
| Argon Medical Devices |
| Siemens Healthineers |
| GE Healthcare |
| Hologic |
| Rocket Medical |
| Others |
Value Chain & Pricing Dynamics
Precision mold fabrication engineers concentrated in Dongguan and Shenzhen command wage premiums that compress margin structures for Western brands lacking captive tooling assets, widening spreads between premium validated-sterile formats and economy-tier unbranded alternatives.
Pricing Analysis
Bundled imaging system contracts versus unbundled accessory procurement splits the market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated sterile guides with exhaustive technical documentation from CE-marked mid-tier formats and unbranded economy alternatives. Price differentiation hinges on ISO 13485 certification grade and sterilization validation completeness. Pricing pressure stems from polycarbonate resin cost volatility tied to petrochemical feedstock markets. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while integrated delivery networks prioritize compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for reusable metal guide refurbishment are contracting as EU MDR Article 52 reclassification eliminates viable reprocessing pathways, redirecting volume toward single-use polymer formats. Manufacturing gravity centers on China, Germany, and the United States. Medical-grade polycarbonate, precision injection molds, and sterilization validation services constitute critical input dependencies. Single-source vulnerability concentrates in Dongguan tooling clusters where Western brands lack captive mold assets. Distribution runs through ISO 13485-certified medical device distributors serving hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through polycarbonate formulation advances enabling thinner-wall geometries that command premium positioning while reducing material input costs per unit.
For Market Incumbents: To counter mid-tier manufacturers in Italy and Spain exiting under EU MDR compliance cost pressure, deepen sterilization validation infrastructure and secure probe compatibility certifications with GE, Philips, and Siemens installed bases. Capacity addition in Baden-Württemberg precision molding corridors anchors Western supply security. For New Entrants and Emerging Players: Launch via CDSCO-registered domestic distributors targeting India government hospital ultrasound deployment programs in provincial diagnostic networks. Unpenetrated imaging infrastructure buildout in Gujarat and Maharashtra industrial corridors offers first-mover positioning ahead of entrenched Western brands. For Investors and Strategic Acquirers: Imaging OEMs with bundled equipment contract capabilities are the most active acquirer in this space, seeking sterilization-validated disposable guide portfolios to complete ultrasound accessory ecosystems. Target contract molders with validated polycarbonate lattice fabrication expertise. Monitor FDA 21 CFR Part 820 enforcement intensity as inflection indicator for procurement channel consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 52 reclassification mandates Class IIa technical documentation for market access. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida consolidate vendor panels around comprehensive ultrasound contracts. |
| Backward Integration into Mold Fabrication | Captive precision tooling capacity in Dongguan mitigates geographic supply risk for Western brands. |
| Software Companion Development | 3D-printed patient-specific biopsy guide design platforms enable complex musculoskeletal intervention customization. |
| Reimbursement Strategy | Outpatient interventional procedure coding alignment accelerates ambulatory surgical center volume capture. |
Study Parameters
Bottom-up ambulatory surgical center and hospital procurement modeling reconciled against top-down polycarbonate resin consumption and precision molding capacity tracking forms the analytical core. Primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and medical-grade polymer trade flow data.
Historical procedural volume trendlines across ultrasound-guided biopsy, drainage, and regional anesthesia applications anchor projection frameworks. Segmentation dimensions span product type, application, end-user facility tier, and distribution channel structure. CAGRs derive from installed base erosion rates for reusable formats and outpatient procedural volume migration patterns. Forecast inputs incorporate EU MDR compliance deadline phasing and NMPA biocompatibility testing protocol streamlining.
Forecast precision tightens around the base case; tail outcomes carry wider variance under single-use plastic reduction mandate escalation or polycarbonate supply disruption scenarios. Practitioners should monitor FDA enforcement intensity, EU MDR notified body backlog duration, and India PLI scheme medical device manufacturing incentive uptake for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Pectus Bar System Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Pericardial Patches Market
Medical Devices
Global Medical Dynamometer Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Transient Elastography Device Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Vascular Boot Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Lyophilized Injectable Market
Medical Devices
Drug Delivery Devices Market