
 Prostate Biopsy Devices Market | 2026-2036
Prostate Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Prostate Biopsy Devices Market Outlook
Hospital procurement committees is collapsing as the dominant buyer archetype for prostate biopsy devices, while cancer clinics and specialized diagnostic centers capture expanded purchasing authority. Boston Scientific Corporation leverages its integrated urology portfolio to sustain channel presence across outpatient settings. Medtronic anchors its position through R&D intensity in image-guided navigation platforms. Hologic competes on manufacturing scale in vacuum-assisted biopsy systems.
Prostate biopsy devices are instruments designed to extract tissue specimens from the prostate gland for histopathological examination, typically employing hollow-core needles ranging from 14 to 18 gauge with spring-loaded or vacuum-assisted mechanisms to obtain cylindrical tissue cores. These devices serve the primary commercial purpose of enabling definitive cancer diagnosis while minimizing procedural morbidity through precise targeting and reduced needle passes. Ultrasound-guided systems still occupy the largest installed base, though MRI-guided and robot-assisted platforms represent the fastest-growing technology categories where margin pools concentrate due to premium pricing and disposable consumables. Transperineal approaches are gaining structural share over transrectal routes in infection-sensitive protocols, while core needle biopsy dominates procedure type volume against fine needle aspiration in urological practice.
The FDA governs Class II device clearances for prostate biopsy systems under 510(k) pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for software-guided and robot-assisted platforms entering European markets. ISO 13485 quality management standards and IEC 62304 software lifecycle protocols shape manufacturer compliance burdens and product development timelines. Stakeholders must monitor how reimbursement coding for fusion biopsy procedures evolves against standard transrectal ultrasound guidance, as payor decisions will determine whether capital-intensive platforms achieve sustainable utilization rates.
Market Dynamics
The migration from transrectal to transperineal biopsy protocols is redistributing procedural volume across outpatient surgical centers and specialized urology clinics, compressing traditional hospital-based diagnostic workflows while elevating infection control as a procurement criterion.
Growth Catalysts
- Fusion biopsy platforms:MRI-ultrasound fusion technology enables targeted sampling of suspicious lesions, reducing false-negative rates in men with elevated PSA and prior negative biopsies. Cancer clinics in the United States are prioritizing capital allocation toward these systems.
- EU Medical Device Regulation:Stricter clinical evidence requirements for software-guided instruments are accelerating consolidation among manufacturers capable of funding extensive validation studies, favoring established players with regulatory infrastructure.
- Transperineal route adoption:Sepsis risk reduction protocols are driving urologists toward perineal approaches, stimulating demand for specialized needle guides and disposable drapes designed for this access trajectory.
Market Restraints
- Reimbursement compression:Medicare and commercial payors in the United States maintain differential coding between standard ultrasound-guided and fusion biopsy procedures, constraining utilization of capital-intensive platforms despite clinical efficacy.
- Single-use consumable costs:Vacuum-assisted biopsy systems require proprietary needle sets and specimen collection devices, locking facilities into recurring expenditure streams that strain outpatient clinic operating budgets.
- Training pathway bottlenecks:Proficiency in MRI interpretation and fusion software navigation demands specialized fellowship exposure, limiting deployable operator pools and elongating technology adoption cycles.
Strategic Opportunities
- Artificial intelligence integration:Machine learning algorithms for real-time lesion detection and needle trajectory optimization represent unclaimed white space, with regulatory pathways under development at the FDA for Class II software-as-medical-device clearances.
- Ambulatory surgery center expansion:Freestanding facilities in the United States are securing prostate biopsy service line licenses, creating new channel entry points for disposable-heavy product portfolios.
- Transperineal template mapping:Systematic saturation biopsy techniques using brachytherapy-style grids enable comprehensive gland sampling, addressing diagnostic uncertainty in active surveillance candidates.
Industry Challenges
- Interoperability fragmentation:Proprietary data formats between MRI workstations, fusion software, and pathology information systems force manual data translation, degrading workflow efficiency and inviting transcription errors.
- Supply chain reconfiguration:Reliance on specialized needle alloys and precision-machined components from concentrated Asian manufacturing hubs exposes distributors to extended lead times and quality variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prostate Biopsy Devices Market |
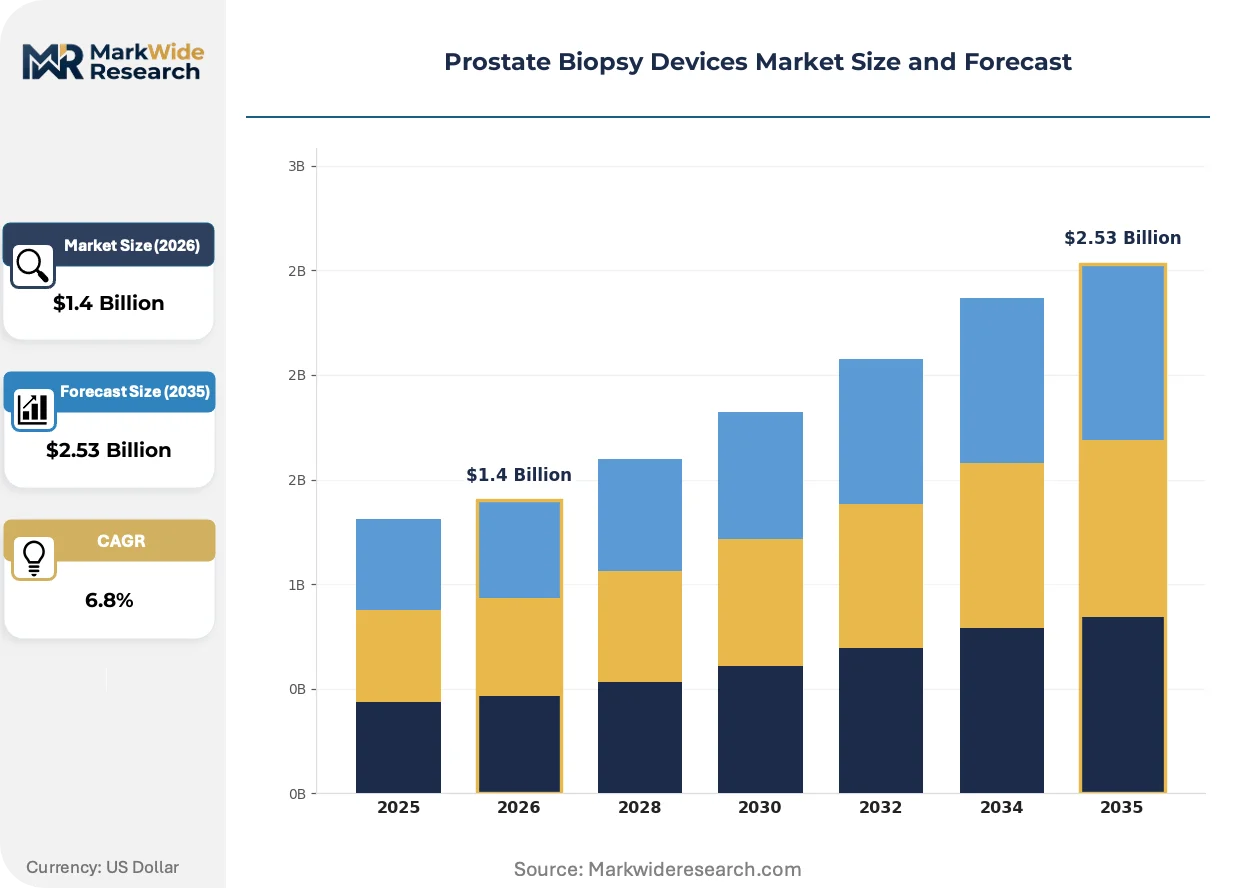
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Core Needle, Vacuum-Assisted, Transrectal, Transperineal Technology: Ultrasound-Guided, MRI-Guided, Stereotactic, Robot-Assisted End User: Hospitals, Cancer Clinics, Diagnostic Centers, Research Institutions Procedure Type: Needle Biopsy, Fine Needle Aspiration, Surgical Biopsy, Image-Guided Biopsy |
| Companies Covered | Boston Scientific Corporation, Medtronic, Olympus Corporation, Argon Medical Devices, Cook Medical, Becton Dickinson and Company, Cardinal Health, Hologic, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prostate Biopsy Devices Market Strategic Shifts
Software-guided targeting systems are compressing the diagnostic pathway from imaging suspicion to histopathological confirmation, while disposable component innovation and service model restructuring reshape commercial relationships between manufacturers and clinical sites.
Robot-assisted biopsy platforms are displacing manual freehand techniques in high-volume academic medical centers, where urology departments deploy these systems to standardize needle placement accuracy across operators with varying experience levels. The technology compresses training curves while enabling remote proctoring capabilities that extend specialist reach into community settings.
The FDA's ongoing refinement of 510(k) pathways for software-guided instruments is extending clearance timelines for manufacturers submitting predicate devices with novel algorithmic components. This regulatory friction concentrates development resources among entities with established quality management systems and clinical affairs infrastructure, compressing the competitive field for next-generation platforms.
Hospital procurement committees are ceding purchasing authority to specialized diagnostic centers and integrated urology networks that consolidate biopsy service lines across multiple sites. These networks negotiate enterprise-level pricing for disposable consumables while demanding outcome guarantees on diagnostic yield, shifting vendor relationships from transactional supply toward performance-linked partnerships visible in the United States.
Prostate Biopsy Devices Market Segmentation
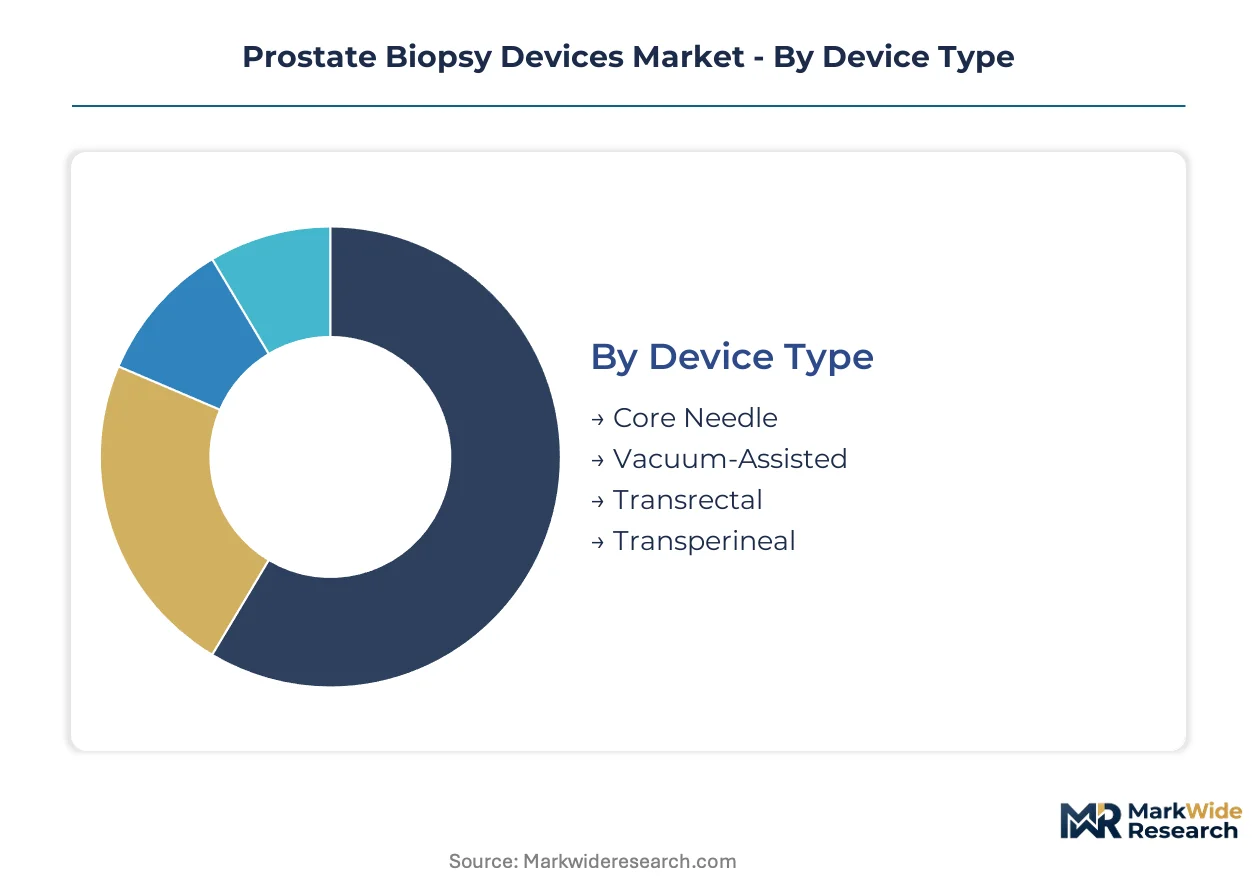
Prostate biopsy device segmentation reveals distinct margin pools and substitution pressures across hardware categories, imaging modalities, and care delivery settings. Procurement patterns diverge sharply between capital-intensive platform purchases and disposable consumable flows.
Device Type:
Substitution pressure concentrates in transperineal and vacuum-assisted formats as infection control protocols and diagnostic yield demands reshape needle selection criteria.
- Core Needle:Spring-loaded mechanisms deliver 14-18 gauge cylindrical tissue specimens through single-trigger deployment. Hospitals in the United States maintain the largest installed base of these systems despite slower growth curves.
- Vacuum-Assisted:Continuous suction mechanisms enable larger tissue volumes per pass, reducing sampling error rates in active surveillance protocols. Cancer clinics prioritize these devices where specimen adequacy directly influences treatment pathway decisions.
- Transrectal:Standard ultrasound-guided access dominates procedural volume through established operator familiarity and lower capital requirements.
- Transperineal:Perineal template approaches eliminate rectal flora exposure, commanding premium positioning in sepsis-sensitive patient populations.
Core needle systems retain volume leadership; transperineal configurations hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium navigation platforms from commodity ultrasound guidance, with reimbursement differentials determining viable price points across clinical settings.
- Ultrasound-Guided:Real-time B-mode imaging with transrectal probes represents the lowest capital entry point for biopsy service lines. Diagnostic centers in community settings depend on these systems where procedure volume does not justify fusion platform investment.
- MRI-Guided:Direct in-bore biopsy within magnetic resonance suites enables lesion-targeted sampling without fusion software intermediation. Academic medical centers deploy these configurations for research protocols and complex diagnostic cases.
- Stereotactic:Frame-based coordinate targeting systems bridge precision and accessibility for mid-tier urology practices.
- Robot-Assisted:Articulated needle drivers standardize trajectory accuracy across operator experience levels, concentrating in high-volume centers with fellowship training pipelines.
Ultrasound-guided technology anchors installed base volume; robot-assisted platforms are climbing the fastest.
End User:
Customer type fragmentation redistributes purchasing authority from centralized hospital procurement toward specialized outpatient operators with distinct technical requirements.
- Hospitals:Integrated health systems negotiate enterprise contracts spanning multiple sites, leveraging volume commitments for disposable pricing concessions.
- Cancer Clinics:Dedicated oncology facilities prioritize diagnostic throughput and rapid pathology turnaround, driving demand for integrated specimen handling workflows.
- Diagnostic Centers:Freestanding imaging and pathology operations concentrate on cost-per-procedure efficiency with streamlined device portfolios.
- Research Institutions:Academic medical centers with NIH funding access sustain demand for experimental navigation platforms and protocol development tools.
Hospitals maintain procurement scale leadership; cancer clinics are gaining share fastest.
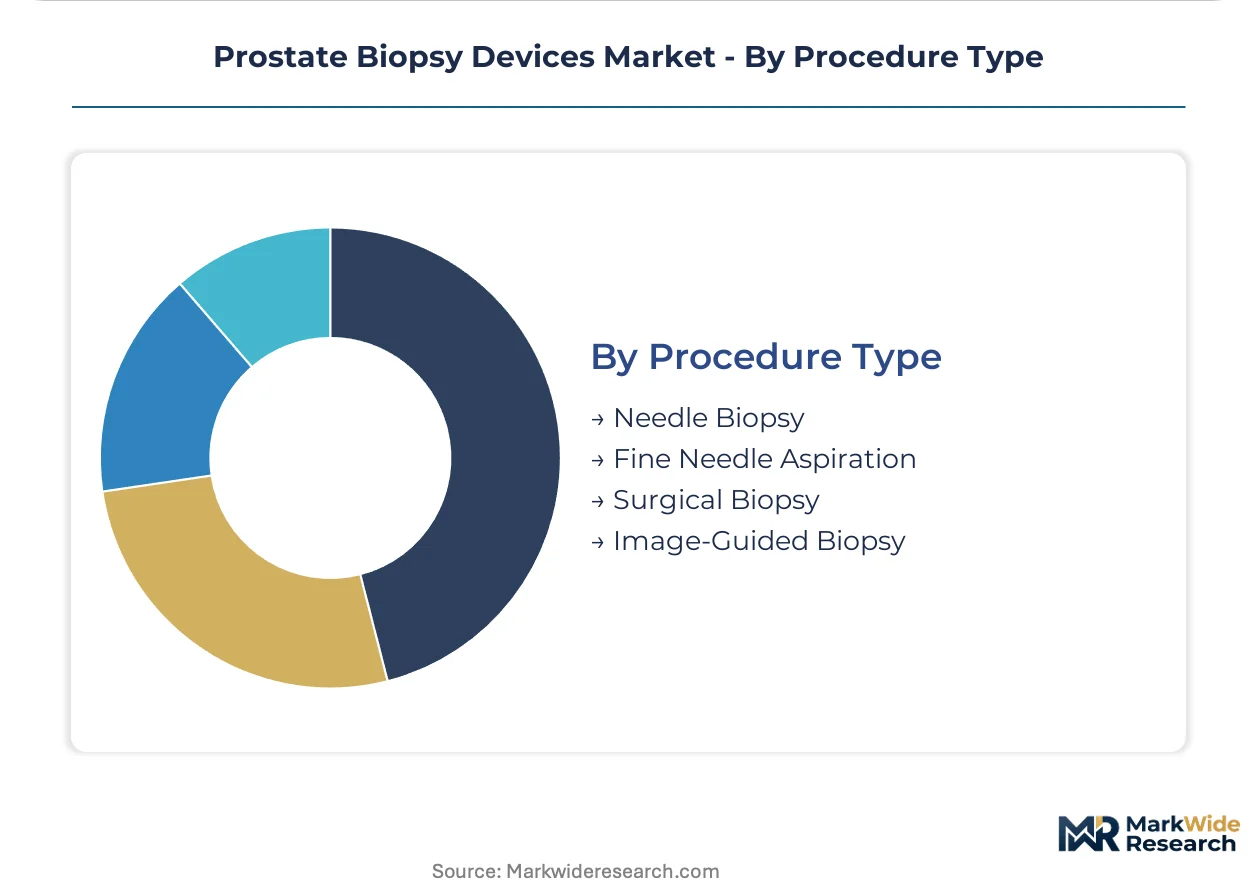
Procedure Type:
Application maturity separates established needle biopsy protocols from emerging image-guided approaches with distinct training and infrastructure requirements.
- Needle Biopsy:Standard core sampling techniques dominate urological practice with established CPT coding and reimbursement pathways.
- Fine Needle Aspiration:Cytology-focused sampling sees limited prostate application outside of metastatic staging scenarios.
- Surgical Biopsy:Open or laparoscopic gland sampling retains niche indication for cases requiring immediate therapeutic intervention.
- Image-Guided Biopsy:Fusion and direct MRI targeting represent the expanding frontier where diagnostic accuracy improvements justify capital expenditure.
Needle biopsy retains procedural volume leadership; image-guided biopsy holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-95 corridor's dense concentration of academic medical centers underwrites the United States' dominance in fusion biopsy platform deployment. Germany's Rhine-Ruhr logistics network enables rapid distribution of precision-machined needle components across European urology networks. Japan's Shinkansen-linked metropolitan corridors concentrate MRI-guided system installations in Tokyo-Osaka medical clusters.
United States
Integrated urology networks in Texas and Florida drive enterprise contracting for disposable consumables. The FDA's 510(k) pathway refinements for software-guided instruments extend clearance timelines for algorithm-heavy submissions. Boston Scientific Corporation anchors channel presence across outpatient settings in the Northeast and Southeast corridors.
Germany
Baden-Württemberg's precision engineering clusters supply vacuum-assisted biopsy needle sets to EU cancer clinics. The EU Medical Device Regulation imposes stricter clinical evidence requirements for robot-assisted platforms entering European markets. Munich's university hospital network validates next-generation navigation protocols for transperineal approaches.
Japan
Tokyo's aging demographic concentrates demand for repeat biopsy procedures in active surveillance protocols. PMDA reviews of MRI-ultrasound fusion software compress product launch windows against US benchmarks. Osaka's medical device manufacturing belt produces specialized needle guides for perineal template mapping systems.
United Kingdom
NHS England's specialized commissioning frameworks restrict fusion biopsy reimbursement to designated cancer centers in London and Manchester. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance tracks for software-guided instruments. Cambridge's biomedical cluster hosts validation studies for AI-enhanced lesion detection algorithms.
Australia
Melbourne and Sydney urology practices adopt transperineal protocols to reduce sepsis admissions in antibiotic-resistant populations. TGA's streamlined Class II device reviews attract manufacturers seeking early clinical validation outside US-EU pathways. Queensland's regional diagnostic networks pilot satellite fusion biopsy services via teleradiology links.
Prostate Biopsy Devices Market Competitive Environment
Listed leaders compete with private specialists across regulatory infrastructure and disposable scale. The vendor base concentrates around three tiers: diversified medtech conglomerates with integrated urology portfolios, dedicated biopsy device specialists with manufacturing depth, and emerging navigation platform developers seeking FDA clearance. Archetypal competitive moves include backward integration into precision needle production and outcome-based contracting with integrated delivery networks.
Within the diversified conglomerate tier, Boston Scientific Corporation, Medtronic, and Olympus Corporation exemplify scale-driven positions. These entities anchor enterprise relationships across hospital procurement and outpatient clinic channels. Hologic occupies a specialist position in vacuum-assisted systems manufacturing. Private and regional players concentrate on transperineal needle guide accessories and disposable drapes for infection-sensitive protocols.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Olympus Corporation |
| Argon Medical Devices |
| Cook Medical |
| Becton Dickinson and Company |
| Cardinal Health |
| Hologic |
| Koninklijke Philips |
| Others |
Value Chain & Pricing Dynamics
Transperineal needle guide substitution for transrectal consumables simultaneously redraws supplier geography toward precision-machining clusters in Germany and Japan while compressing per-procedure pricing economics for disposable-heavy portfolios. This input shift elevates infection-control premiums in procurement negotiations while exposing distributors to alloy sourcing bottlenecks.
Pricing Analysis
Volume-discount tiering structures dominate enterprise contracting between integrated urology networks and disposable manufacturers, with pricing stratifying across premium navigation platforms, standard ultrasound-guided systems, and economy core needle configurations. Price differentiation rests on FDA clearance tier and disposable bundling depth. Cost compression in standard transrectal consumables is intensifying because cancer clinics are consolidating purchasing authority. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with NIH funding access show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites just-in-time delivery of precision-machined needle alloys from South Korean and Japanese metallurgical suppliers to German and US device assemblers. Raw material dependencies center on surgical-grade stainless steel, shape-memory nickel-titanium alloys, and medical-grade polymers. Single-source vulnerability concentrates in specialized needle tip grinding equipment sourced from Swiss precision toolmakers. Distribution runs through regional specialty distributors with GPO contracting authority in the United States and direct hospital service agreements in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is underway as proprietary MRI-fusion software ecosystems lock clinical sites into interoperable hardware-consumable bundles, with data format standardization emerging as the decisive control point.
For Market Incumbents: Shield installed base positions by deepening backward integration into precision needle production and securing exclusive GPO contracts with cancer clinic networks before reimbursement coding shifts favor fusion platforms. Regulatory infrastructure investment in FDA 510(k) algorithmic device pathways serves as the priority defensive lever against navigation software entrants. For New Entrants and Emerging Players: AI-enhanced lesion detection training data services represent a service-layer gap where incumbents under-serve community urology practices lacking fellowship-trained MRI interpreters. Target ambulatory surgery centers in Texas and Florida with teleradiology-linked fusion biopsy platforms. Go-to-market angle: outcome-guaranteed diagnostic yield contracts with integrated delivery networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed transperineal needle guide specialists with manufacturing depth but limited software capabilities. Five-to-ten year viability hinges on navigation platform consolidation. Acquisition target archetype: disposable-heavy firms with captive hospital relationships but aging R&D pipelines. Signal to watch: CMS reimbursement parity decisions between standard ultrasound-guided and fusion biopsy CPT codes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Pathway Investment | Accelerates clearance timelines for algorithm-heavy fusion navigation platforms against EU MDR benchmarks. |
| Transperineal Disposable Portfolio Expansion | Captures procedural volume migrating from hospital-based transrectal workflows to infection-sensitive outpatient protocols. |
| GPO Contract Consolidation | Locks enterprise pricing for vacuum-assisted consumables across multi-site urology networks in the United States. |
| AI Lesion Detection Development | Addresses training pathway bottlenecks limiting deployable operator pools for MRI-guided platforms. |
| Reimbursement Strategy Alignment | Positions fusion biopsy platforms for sustainable utilization rates as payor coding evolves. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and hospital GPO contract disclosures. Primary interviews engaged urology department chairs, cancer clinic procurement directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from ISO 13485 audit records, EU MDR technical documentation, and pathology information system vendor disclosures. Bottom-up procedure volume modeling triangulates against top-down capital expenditure tracking across the analysis window.
Segmentation dimensions modeled span device type, technology platform, end-user facility category, and procedural approach across the projection horizon. CAGRs derive from installed base replacement cycles, technology substitution elasticities, and reimbursement scenario weighting. Industry-specific forecast inputs incorporate MRI scanner penetration rates in urology practices and active surveillance protocol adoption curves.
Forecasts assume regulatory continuity in FDA Class II device pathways and EU MDR software-guided instrument requirements; material policy shifts would require re-modeling. Supply chain disruption from concentrated Asian manufacturing hubs and reimbursement compression from Medicare coding revisions represent specific revision risks. Practitioners should keep alternative scenarios live as interoperability standardization and transperineal protocol diffusion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Wheelchair Market
Medical Devices
Global Pessary Market
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Bone Power Tools Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Infusion Management Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Antimicrobial Coated Medical Devices Market