
 Mobile Operating Rooms Market | 2026-2036
Mobile Operating Rooms Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Operating Rooms Market Foresight
ISO 13485 certification is unwinding the competitive landscape for mobile surgical platform manufacturers. Kentucky Trailer leverages its chassis engineering heritage to dominate trailer-based system fabrication. Odulair LLC specializes in containerized configurations for military and humanitarian deployments. Stryker Corporation anchors the high-technology tier through its integrated surgical instrument and imaging ecosystems.
Mobile operating rooms are self-contained, transportable surgical environments built on reinforced vehicle platforms or standardized shipping containers, typically incorporating HEPA filtration, laminar airflow systems, and dedicated anesthesia gas scavenging to maintain ISO 5-7 cleanroom equivalence during active procedures. Their primary purpose is to deliver sterile surgical capability at locations lacking fixed infrastructure, including conflict zones, disaster sites, and remote civilian populations. Trailer-based systems currently occupy the largest installed base due to faster deployment logistics, while containerized solutions represent the fastest-growing category as military end users prioritize air-transportable platforms. Among end users, military facilities command premium pricing for hardened specifications, whereas ambulance services drive volume demand for compact emergency intervention units.
The US FDA regulates mobile surgical platforms as Class II medical devices under 510(k) premarket notification requirements, while the EU MDR imposes stricter clinical evidence standards for sterile field validation in transportable settings. Germany's KBA enforces vehicle safety compliance for road-mobile units, adding a dual-certification burden that filters out smaller fabricators. Stakeholders must monitor how divergent transatlantic regulatory timelines reshape competitive access across NATO procurement channels.
Market Dynamics
NATO defense ministries are consolidating procurement around air-transportable surgical platforms, compressing vendor qualification timelines and privileging fabricators with dual ISO 13485 and military hardening certifications. This concentration dynamic is restructuring competitive access across transatlantic emergency medical infrastructure markets.
Growth Catalysts
- EU MDR sterile field validation:Transportable surgical environments meeting EU MDR clinical evidence standards gain automatic preferential access to German federal disaster preparedness tenders.
- Containerized platform engineering:Standardized shipping container conversions enable rapid airlift deployment, attracting military end users prioritizing strategic medical mobility.
- Kentucky Trailer chassis heritage:Road-mobile surgical units leveraging established trailer fabrication expertise achieve faster KBA vehicle safety certification turnaround.
Market Restraints
- Aluminum alloy price volatility:Reinforced vehicle platforms depend on aerospace-grade aluminum, exposing fabricators to London Metal Exchange commodity swings.
- HEPA filtration supply concentration:Critical laminar airflow components concentrate among three German and Swiss specialty filter manufacturers, creating single-source vulnerability.
- FDA 510(k) clinical evidence requirements:Premarket notification pathways for mobile surgical devices demand extensive sterile field validation studies, extending time-to-revenue for new entrants.
Strategic Opportunities
- Indian remote healthcare infrastructure:CDSCO regulatory harmonization with ISO 13485 creates pathway for containerized surgical platforms addressing rural surgical access gaps.
- Ambulance service compact emergency units:Emergency medical services seek downsized mobile intervention capabilities for urban rapid response, distinct from full surgical suites.
- Japan METI disaster resilience mandates:Post-disaster medical preparedness regulations explicitly fund mobile surgical assets, opening procurement channels for hardened platform suppliers.
Industry Challenges
- Cleanroom technician scarcity:Mobile platform commissioning requires specialists certified in ISO 5-7 laminar airflow validation, a skill pool concentrated among fixed-facility contractors.
- Dual-certification timeline compression:Simultaneous FDA 510(k) and EU MDR sterile field submissions demand parallel clinical study designs, straining regulatory affairs capacity.
- Anesthesia gas scavenging integration:Legacy fixed-hospital evacuation systems use incompatible connectors, forcing custom engineering for each mobile deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Operating Rooms Market |
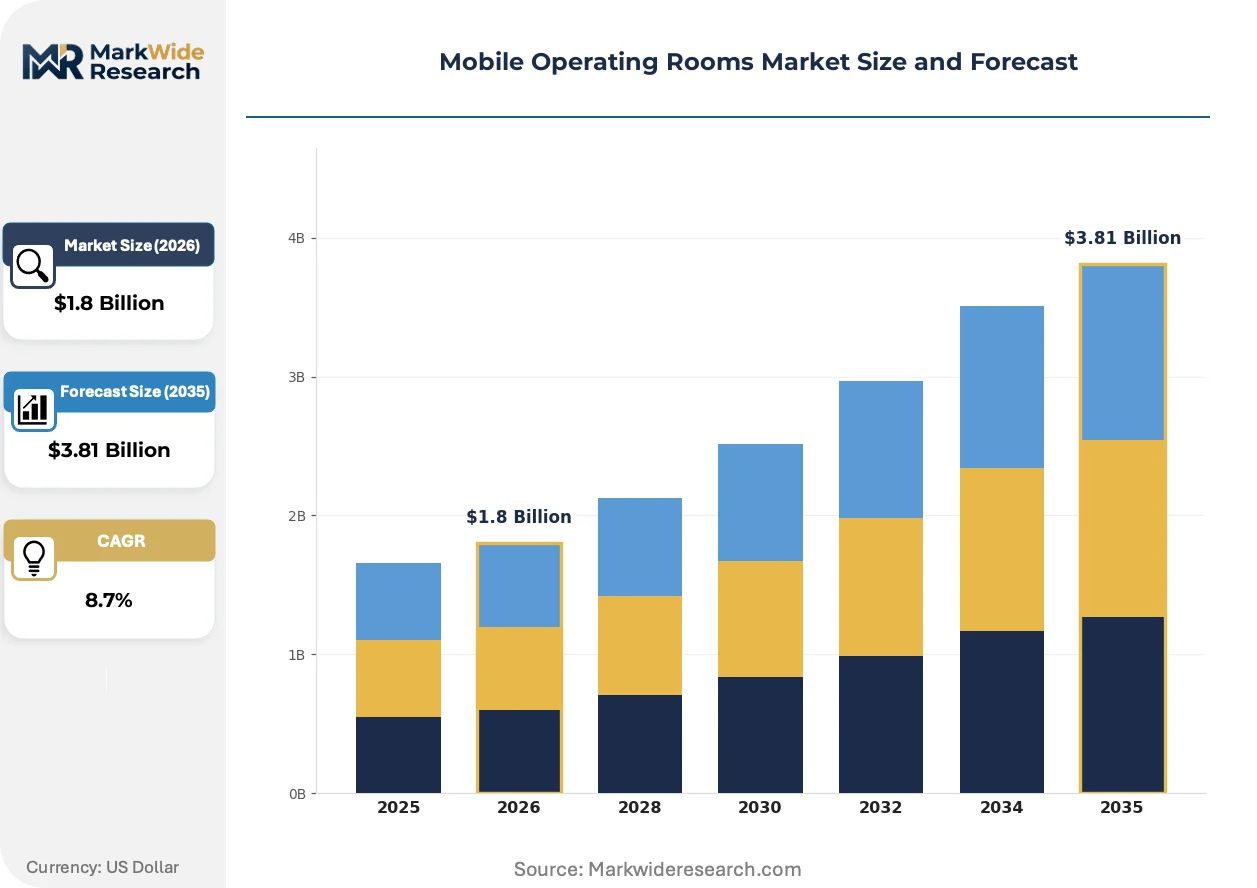
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Units, Trailer-Based Systems, Containerized Solutions, Mobile Surgical Suites Application: Emergency Care, Military Operations, Disaster Relief, Patient Transport End User: Hospitals, Ambulance Services, Military Facilities, Private Clinics Technology: Telemedicine, Anesthesia Systems, Surgical Instruments, Imaging Equipment |
| Companies Covered | Kentucky Trailer, AmbulanceMed, Infinity Chassis Units, Odulair LLC, EpiGuard AS, EMS Healthcare Ltd., Expandable Healthcare B.V., Stryker Corporation, MHC Americas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Operating Rooms Market Shifts & Advancements
Surgical platform architecture is bifurcating between hardened military specifications and civilian emergency medical services configurations, with divergent engineering priorities reshaping vendor specialization patterns across NATO procurement channels.
Carbon fiber reinforced polymer chassis construction is supplanting traditional steel framing in next-generation trailer-based systems. Military medical corps buyers in Germany and Poland are specifying CFRP platforms for payload reduction without structural compromise. This materials transition is compressing deployment logistics timelines while elevating fabrication capital requirements, filtering out mid-tier metalworking suppliers.
EU MDR Annex XVI sterile field validation protocols are extending clinical evidence requirements to transportable surgical environments previously exempt under transitional provisions. German notified bodies are interpreting transport vibration stress as a novel clinical factor requiring dedicated stability studies. Containerized platform manufacturers serving Bundeswehr medical units are responding by embedding continuous environmental monitoring systems to generate real-world performance datasets.
Outcome-based service contracting is displacing capital purchase models among Scandinavian ambulance services. Danish and Swedish regional health authorities now specify guaranteed surgical availability per platform rather than equipment ownership, transferring operational risk to fabricators. This procurement evolution concentrates demand among vertically integrated suppliers capable of field maintenance networks across dispersed geographies.
Mobile Operating Rooms Market Segmentation
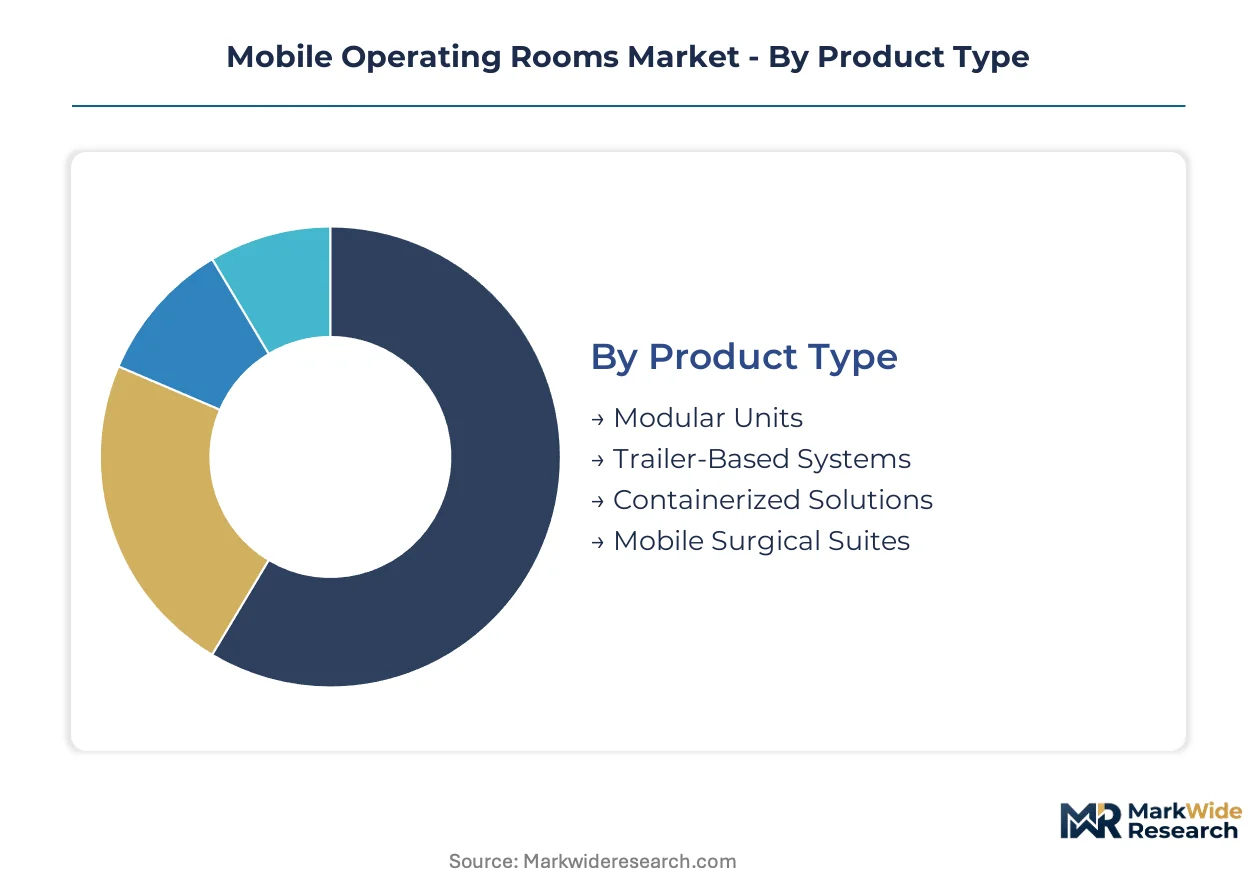
Mobile operating room procurement channels diverge sharply by deployment velocity and certification burden. Trailer-based systems flow through commercial vehicle distributors, while containerized platforms move via defense procurement frameworks with distinct hardening specifications.
Product Type:
Channel access varies dramatically across fabrication formats, with road-mobile units leveraging established trailer dealer networks and air-transportable solutions requiring direct military contracting relationships.
- Trailer-Based Systems:Reinforced vehicle platforms mounted on commercial chassis enable rapid highway deployment to disaster sites. Kentucky's fabrication clusters supply ambulance services across the Midwest with KBA-certified road-mobile units.
- Containerized Solutions:Standardized shipping container conversions incorporate ISO 5-7 laminar airflow and anesthesia gas scavenging for sterile field maintenance. NATO medical corps in Germany and Poland specify these for strategic airlift compatibility.
- Modular Units:Expandable structural components assemble into temporary surgical facilities.
- Mobile Surgical Suites:Fully integrated operating environments with pre-installed imaging and instrumentation.
By volume, Trailer-Based Systems lead. By growth pace, Containerized Solutions is climbing the fastest.
Application:
End-use economics separate emergency civilian deployment from hardened military specifications, with disaster relief occupying a hybrid procurement space between federal preparedness budgets and humanitarian NGO funding.
- Military Operations:Hardened platforms withstand ballistic threats and electromagnetic interference while maintaining sterile fields under combat conditions. Bundeswehr medical units in Germany drive specification standards across NATO procurement channels.
- Emergency Care:Compact intervention units deploy to mass casualty incidents and urban trauma scenes. Danish ambulance services specify guaranteed availability contracts rather than capital purchase for these deployments.
- Disaster Relief:Rapidly deployable surgical capacity addresses infrastructure collapse following seismic or weather events.
- Patient Transport:En-route surgical intervention during critical care transfer.
Emergency Care dominates current installed base. Military Operations shows steepest expansion trajectory as NATO defense budgets prioritize medical mobility.
End User:
Customer procurement sophistication ranges from outcome-based service contracting among Scandinavian ambulance authorities to capital-intensive military specification programs with decade-long vendor qualification cycles.
- Military Facilities:Defense medical corps command premium pricing for dual-certified platforms meeting both ISO 13485 and military hardening standards. German and Polish procurement offices consolidate vendor lists around air-transportable surgical capabilities.
- Ambulance Services:Regional emergency medical authorities in Denmark and Sweden drive volume demand through performance-based contracts. These stakeholders transfer operational risk to fabricators capable of dispersed field maintenance networks.
- Hospitals:Fixed-facility operators acquire mobile assets for surge capacity and renovation backup.
- Private Clinics:Independent surgical providers seek compact mobile units for procedure volume flexibility.
Ambulance Services generate highest unit volume. Military Facilities capture largest revenue per platform.
Technology:
Component integration intensity separates basic mobile intervention platforms from comprehensive surgical ecosystems, with imaging and telemedicine subsystems commanding disproportionate value share.
- Imaging Equipment:Mobile C-arms, portable CT, and intraoperative MRI systems require vibration isolation engineering for transportable deployment. Stryker's integrated ecosystems anchor the high-technology tier through proprietary instrument and imaging combinations.
- Telemedicine:Real-time surgical consultation and remote procedural guidance connect field teams with specialist expertise. EU MDR Annex XVI validation protocols now extend to transportable telemedicine environments.
- Anesthesia Systems:Gas delivery and scavenging for mobile sterile field maintenance.
- Surgical Instruments:Sterilizable tool sets compatible with mobile autoclave configurations.
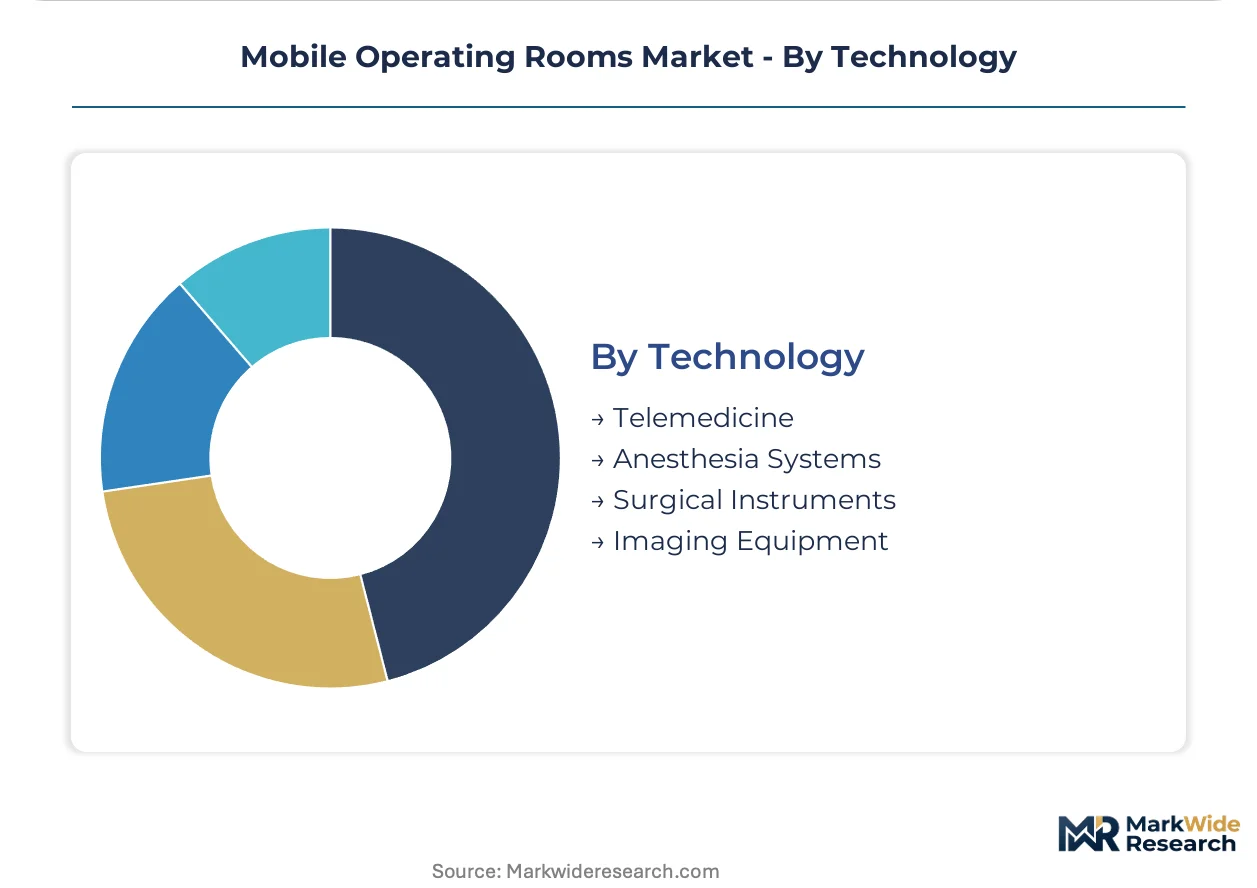
Imaging Equipment represents the highest value-add tier. Telemedicine is gaining share fastest as remote surgical consultation becomes standard in military and humanitarian deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Military medical corps in Germany command premium procurement budgets for hardened surgical platforms, while ambulance authorities in Scandinavia drive volume demand through outcome-based contracting. Containerized systems find their fastest growth corridors where air-transportable infrastructure meets federal disaster preparedness mandates.
United States
Defense Health Agency procurement channels prioritize air-transportable surgical capabilities for expeditionary medical support. The FDA's 510(k) premarket notification framework governs mobile surgical platform classification, compressing deployment timelines for emergency use authorizations. Kentucky-based chassis fabricators supply trailer-based systems to Midwest ambulance services and military medical units at Fort Sam Houston.
Germany
Bundeswehr medical corps consolidate vendor qualification around dual-certified platforms meeting ISO 13485 and military hardening specifications. The KBA enforces vehicle safety compliance for road-mobile units, creating a dual-certification burden that filters fabricators. Containerized surgical platform production clusters in Bavaria serve NATO procurement channels with air-transportable configurations.
Poland
Ministry of National Defence procurement offices expand mobile surgical infrastructure under NATO interoperability commitments. EU MDR Annex XVI sterile field validation protocols extend to transportable environments, requiring dedicated stability studies for vibration stress. Polish medical corps coordinate with German suppliers for hardened platform specifications aligned with Bundeswehr standards.
Denmark
Regional health authorities specify guaranteed surgical availability per platform rather than capital equipment ownership. Outcome-based service contracting transfers operational risk to fabricators capable of dispersed field maintenance networks. Danish ambulance services drive compact emergency intervention unit demand across Scandinavian procurement channels.
Japan
METI disaster resilience mandates explicitly fund mobile surgical assets for post-disaster medical preparedness. PMDA regulatory frameworks align with ISO 13485 certification pathways for containerized platform importation. Tokyo-based emergency medical authorities evaluate hardened surgical platforms for seismic response infrastructure.
Mobile Operating Rooms Market Competitive Landscape
Player mix skews toward specialized fabricators with dual military-civilian certification capabilities. Tiered competitive structure separates chassis engineering specialists, containerized platform converters, and integrated medical technology suppliers. Three archetypes dominate: trailer-based system fabricators leveraging commercial vehicle heritage, military-hardened container specialists, and diversified medical device conglomerates with surgical ecosystem integration. Competitive dynamics center on dual-certification timeline compression and field maintenance network geographic coverage.
Among chassis engineering specialists, Kentucky Trailer exemplifies the trailer-based fabrication archetype through its commercial vehicle heritage. Odulair LLC occupies a position within the military-hardened container specialist tier. Stryker Corporation anchors the integrated medical technology supplier category. These three fabricators represent distinct competitive vectors: road-mobile deployment velocity, air-transportable strategic mobility, and comprehensive surgical ecosystem integration.
| Leading Market Players |
|---|
| Kentucky Trailer |
| AmbulanceMed |
| Infinity Chassis Units |
| Odulair LLC |
| EpiGuard AS |
| EMS Healthcare Ltd. |
| Expandable Healthcare B.V. |
| Stryker Corporation |
| MHC Americas |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between NATO defense ministries and hardened platform fabricators lock in multi-year aluminum alloy supply at London Metal Exchange-indexed pricing, compressing margin volatility while anchoring cost visibility for air-transportable surgical system procurement.
Pricing Analysis
Cost-plus contracts with aluminum alloy indexation dominate military procurement channels, passing commodity volatility to defense budgets while preserving fabricator margins. Pricing stratifies across ISO 13485-certified premium tiers, KBA-compliant road-mobile standards, and economy-grade disaster relief configurations without military hardening. Cost compression in trailer-based civilian segments is intensifying because ambulance services consolidate purchasing through outcome-based contracts. Scandinavian regional health authorities exhibit highest price sensitivity through performance-guarantee structures, whereas Bundeswehr medical units accept premium pricing for dual-certified air-transportable platforms.
Supply Chain Analysis
Inventory cycles for HEPA filtration components stretch eighteen to twenty-four months due to concentration among German and Swiss specialty manufacturers. Aerospace-grade aluminum supply draws from US, German, and Chinese smelting capacity, while laminar airflow systems rest on Bavarian cleanroom engineering clusters. Single-source vulnerability in HEPA filtration creates structural exposure to plant disruption or export licensing shifts. Distribution runs through defense procurement frameworks for containerized platforms and commercial vehicle dealer networks for trailer-based systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where dual FDA 510(k) and EU MDR certification timelines create switching costs that freeze out opportunistic entrants.
For Market Incumbents: Compound certification depth by embedding continuous environmental monitoring systems that generate real-world sterile field datasets, preempting EU MDR Annex XVI validation extensions. Expand captive HEPA filtration supply through backward integration into German cleanroom component manufacturing, neutralizing single-source vulnerability before emerging Polish fabricators secure alternative supplier relationships. For New Entrants and Emerging Players: CDSCO-ISO 13485 harmonization pathways in India offer accelerated sterile field validation for containerized platforms targeting rural surgical access gaps. Penetrate Indian remote healthcare infrastructure through modular deployment partnerships with state-level disaster preparedness authorities, bypassing entrenched NATO vendor lists where qualification timelines span multiple years. For Investors and Strategic Acquirers: Chassis engineering specialists with dormant military hardening capabilities represent asymmetric acquisition targets as NATO procurement compresses vendor qualification windows. Long-term viability hinges on regulatory entrenchment depth rather than manufacturing scale alone. Monitor EU MDR notified body interpretation shifts on transport vibration stress as the decisive inflection signal for clinical evidence cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Fast-Track Investment | Parallel FDA 510(k) and EU MDR submissions compress time-to-revenue for NATO defense procurement channels. |
| Carbon Fiber Chassis Partnership | CFRP platform adoption by Bundeswehr medical units elevates capital barriers for mid-tier metalworking competitors. |
| Outcome-Based Service Contracting | Scandinavian ambulance authorities transfer operational risk to fabricators with dispersed field maintenance networks. |
| HEPA Filtration Backward Integration | Captive supply from Bavarian cleanroom engineering clusters neutralizes single-source vulnerability in laminar airflow components. |
| Indian Regulatory Harmonization Entry | CDSCO alignment with ISO 13485 creates pathway for containerized platforms addressing rural surgical access gaps. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and NATO defense procurement tender records preceded structured interviews with biomedical engineers, GPO contracts managers, Bundeswehr medical procurement officers, and cleanroom validation specialists. Secondary validation drew from hospital procurement databases, KBA vehicle safety certification registries, and aluminum alloy trade flow data. Bottom-up platform shipment analysis triangulated against top-down defense budget appropriation tracking.
Variance decomposition across product type, application, end user, and technology dimensions anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare infrastructure spending patterns. Modeled inputs incorporated NATO interoperability commitment timelines, EU MDR Annex XVI implementation trajectories, and carbon fiber reinforced polymer adoption curves in military medical corps specifications.
Decision-makers should treat outputs as directional under assumptions of sustained NATO defense medical mobility prioritization and stable aluminum alloy supply chains; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Ureteral Stent Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Self-Injections Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Blood Lancet Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market