
 Home Sleep Apnea Testing Devices Market | 2026-2036
Home Sleep Apnea Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Home Sleep Apnea Testing Devices Market Analysis
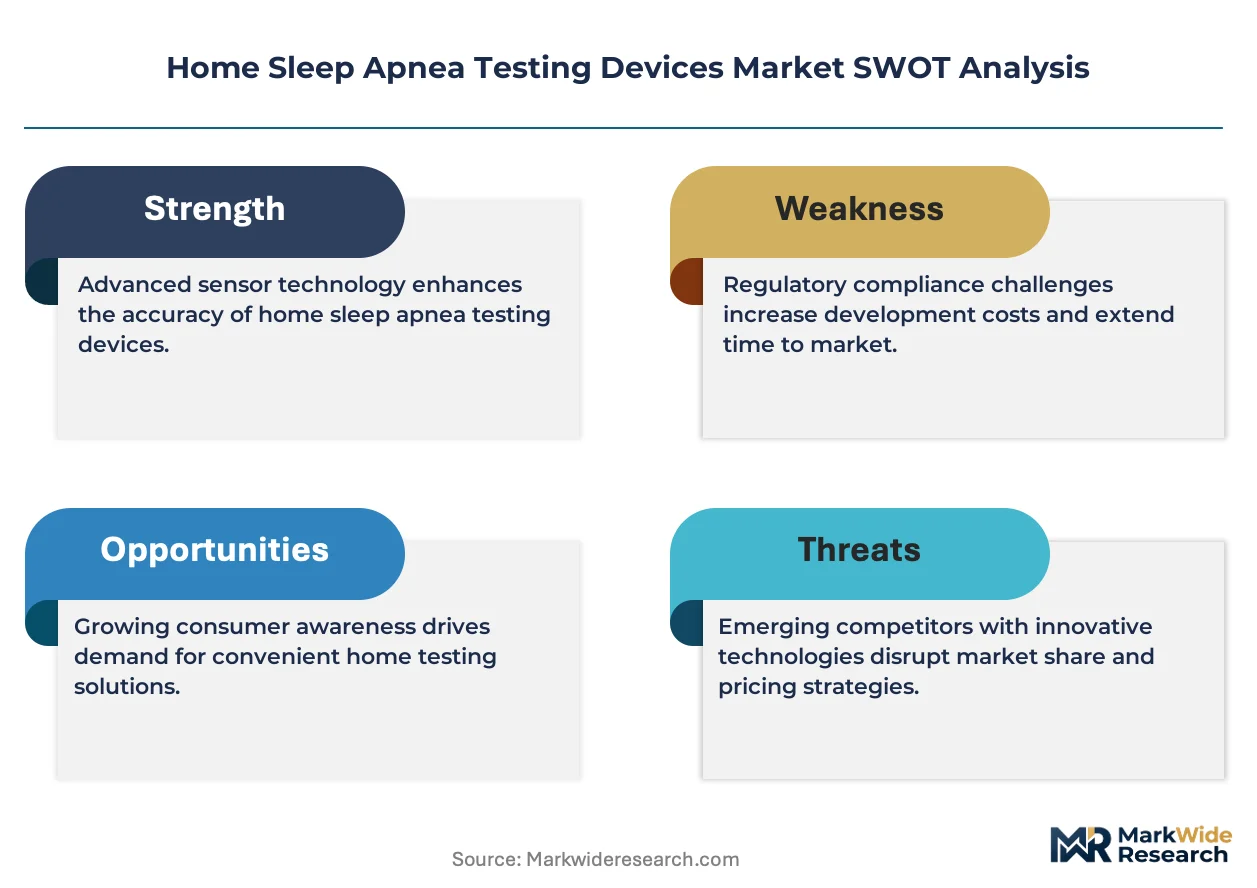
The gap between premium polysomnography-grade home systems and basic portable monitors is restructuring how manufacturers allocate engineering resources. ResMed leverages its cloud-connected platform architecture to dominate the premium tier. Philips sustains broad channel control across hospital and home care segments. ZOLL Itamar specializes in peripheral arterial tone technology, carving out a defensible niche in cardiology-integrated sleep testing.
Home sleep apnea testing devices are portable or wearable diagnostic instruments that record physiological parameters including airflow, blood oxygen saturation, respiratory effort, and heart rhythm during unattended sleep, typically employing pulse oximetry and respiratory inductance plethysmography to generate apnea-hypopnea indices for clinical interpretation. These devices serve the primary commercial purpose of enabling cost-effective obstructive sleep apnea diagnosis outside traditional sleep laboratory environments. Wearable devices represent the fastest-expanding product category as miniaturization improves patient compliance and expands addressable populations beyond severe cases. Pulse oximetry anchors the technology mix due to its low component cost and established reimbursement codes, while EEG monitoring commands premium positioning in hybrid home-lab protocols.
FDA 510(k) clearance requirements and the European Union's Medical Device Regulation shape product development timelines and clinical validation burdens for manufacturers seeking multi-regional market access. The Centers for Medicare and Medicaid Services maintain influential reimbursement policies that directly determine physician prescribing behavior and patient out-of-pocket exposure in the United States. Stakeholders must monitor evolving home-based diagnostic reimbursement parity against in-lab polysomnography, as payment policy shifts will determine whether volume growth concentrates in basic screening tools or advanced multi-parameter systems.
Market Dynamics
Reimbursement parity negotiations between CMS and private payers are compressing margins on basic pulse oximetry devices while expanding coverage for multi-parameter home systems, forcing manufacturers to reallocate R&D toward clinically differentiated sensor architectures.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage determinations for unattended home sleep testing under CPT codes 95806 and 95800 are expanding physician prescribing authority beyond traditional polysomnography referrals.
- Wearable form factor miniaturization:Advances in respiratory inductance plethysmography sensors are enabling finger-worn and chest-strap configurations that improve patient compliance in longitudinal screening programs.
- Germany:Ambulatory sleep diagnostics under the German Social Code Book V are gaining parity reimbursement status, accelerating procurement by statutory health insurance-authorized diagnostic networks.
Market Restraints
- Semiconductor component volatility:Supply constraints on specialized analog-to-digital converters for physiological signal processing are extending production lead times for multi-channel recording devices.
- FDA 510(k) clinical validation burdens:Predicate device requirements for novel sensor algorithms are creating multi-year regulatory timelines that disadvantage smaller manufacturers lacking existing cleared platforms.
- In-lab polysomnography substitution resistance:Academic medical centers with captive sleep laboratory infrastructure continue to prioritize attended diagnostics for complex comorbid cases, limiting pure-play home device penetration.
Strategic Opportunities
- Cardiology-integrated screening protocols:Peripheral arterial tone technology convergence with implantable cardiac monitor data streams is creating hybrid diagnostic workflows in electrophysiology clinics.
- Direct-to-consumer channel development:Pharmacy retail partnerships and telehealth platform integrations are bypassing traditional durable medical equipment distribution for initial screening tool access.
- EU MDR Article 120 transition extensions:Staggered compliance deadlines for legacy device recertification are creating temporary competitive windows for manufacturers with robust quality management systems.
Industry Challenges
- Clinical sleep technologist workforce constraints:Board-registered polysomnographic technologist shortages are limiting scalable home testing interpretation services and forcing automation investments in AI-assisted scoring algorithms.
- Interoperability standardization delays:Fragmented data exchange protocols between proprietary cloud platforms and electronic health record systems are complicating enterprise procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Sleep Apnea Testing Devices Market |
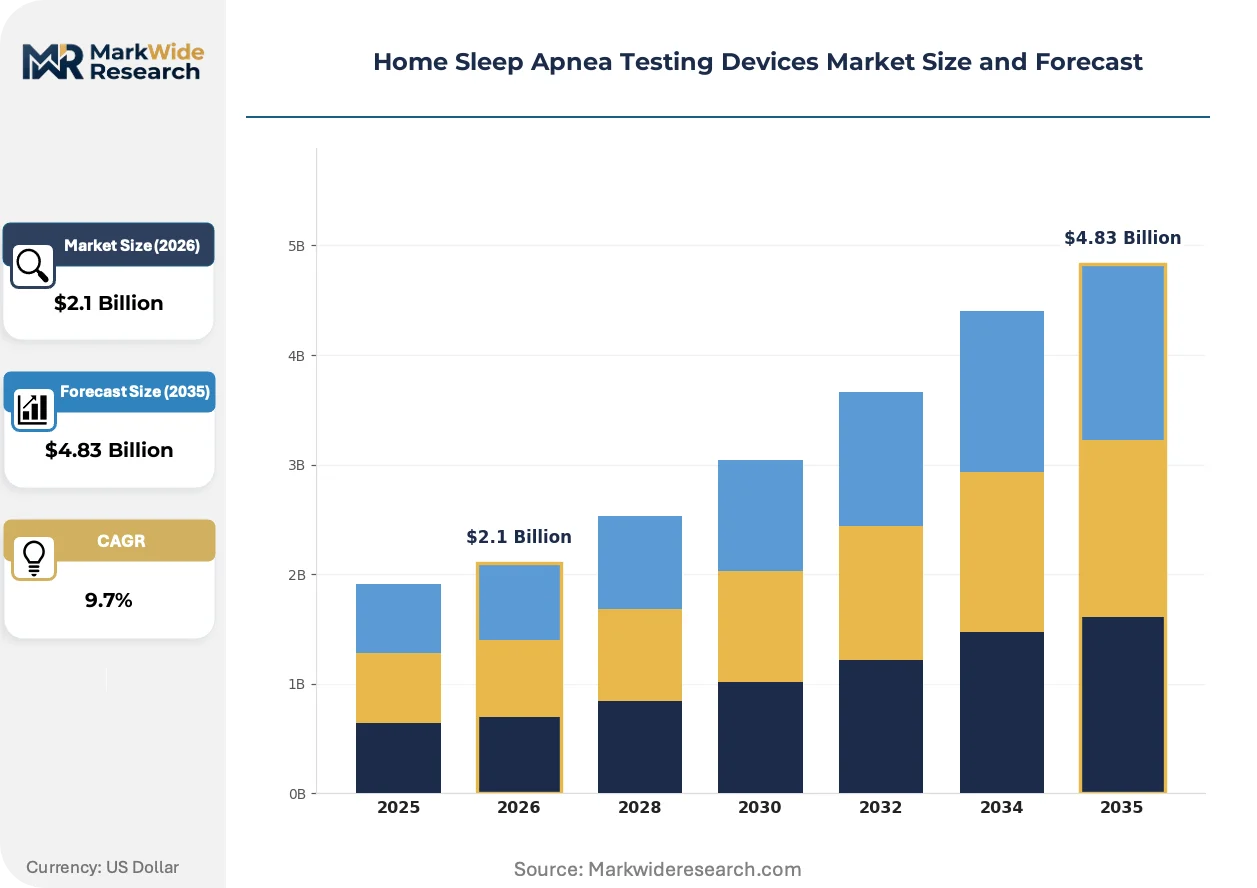
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Home Sleep Tests, Polysomnography Devices, Wearable Devices Technology: Pulse Oximetry, Actigraphy, Respiratory Inductance Plethysmography, EEG Monitoring End User: Home Care Settings, Diagnostic Labs, Sleep Clinics, Healthcare Providers Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Pharmacy Chains |
| Companies Covered | ResMed, Philips, Nihon Kohden, Natus Medical, ZOLL Itamar, Compumedics, Nox Medical, CleveMed, Onera Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Sleep Apnea Testing Devices Market Emerging Trajectories
Cloud-native platform architectures are displacing standalone device business models, with recurring revenue from remote monitoring subscriptions becoming the primary value capture mechanism rather than hardware margins alone.
Artificial intelligence-assisted respiratory event scoring is consolidating clinical validation workflows by automating apnea-hypopnea index calculations that previously required manual technologist review. Sleep medicine practices with high testing volumes are adopting FDA-cleared algorithms to reduce interpretation turnaround from days to hours. This compression of diagnostic latency is consolidating market share among vendors with integrated software-hardware ecosystems capable of end-to-end automation.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIa diagnostic devices are extending product development timelines and favoring manufacturers with established post-market surveillance infrastructures. Notified body capacity constraints in Germany and the Netherlands are creating bottlenecks for novel sensor modalities seeking CE marking. Device firms are responding by front-loading clinical validation studies and establishing European authorized representative offices in advance of submission deadlines.
Hospital procurement departments are unbundling after-sales technical support from capital equipment contracts, instead negotiating separate service level agreements with third-party biomedical engineering firms. This disintermediation of manufacturer service revenue is most pronounced in United States integrated delivery networks with centralized device management programs. Vendors are countering by embedding predictive maintenance capabilities into connected platforms to demonstrate ongoing value beyond initial hardware deployment.
Home Sleep Apnea Testing Devices Market Segmentation
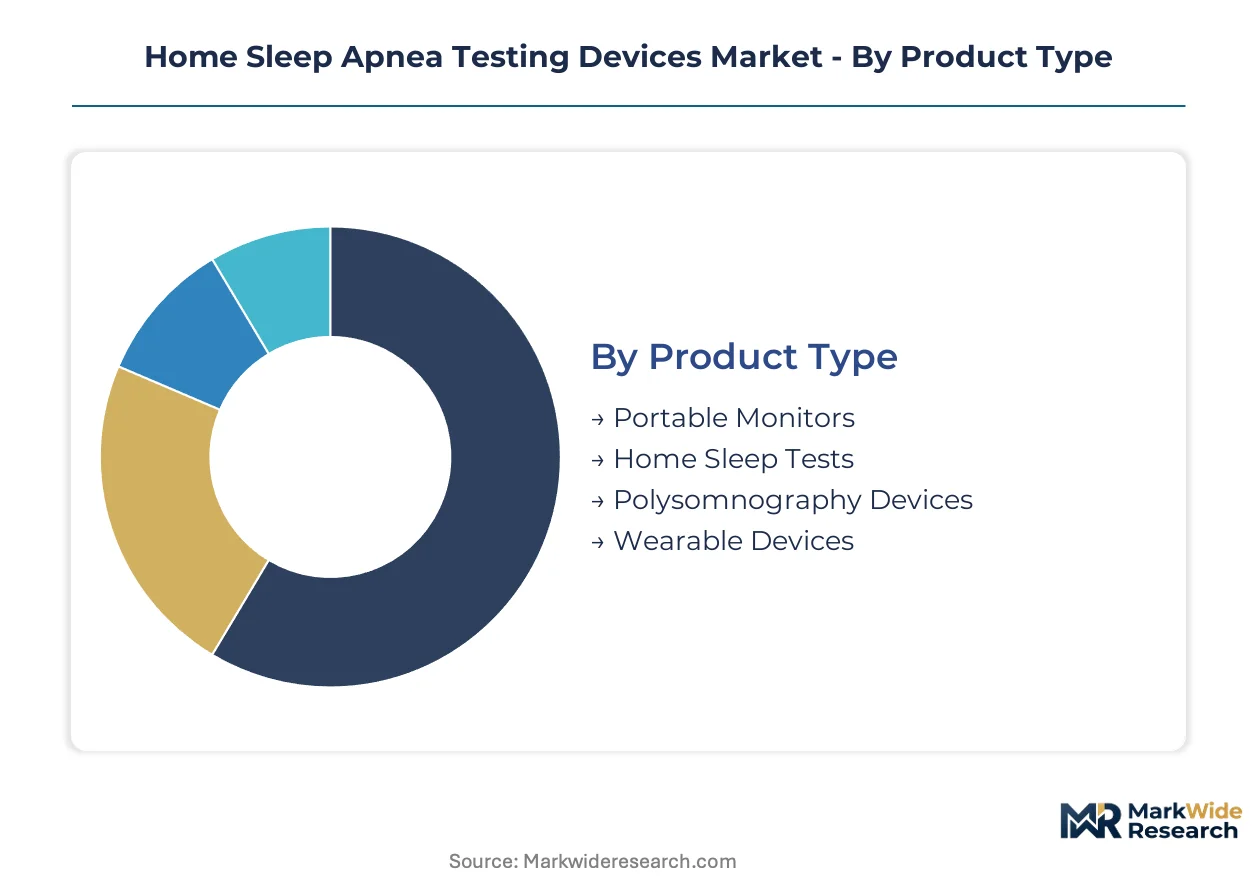
Home sleep apnea testing devices fragment across four critical dimensions that determine reimbursement pathways, clinical validation requirements, and channel economics. Product form factors and sensor technologies drive manufacturing complexity, while end-user settings and distribution channels shape pricing power and customer acquisition costs.
Product Type:
Standardization dominates at the economy tier with single-parameter screening tools, while premium configurations demand extensive customization for multi-channel physiological recording.
- Portable Monitors:Compact battery-operated units typically measuring three to five physiological channels including airflow, respiratory effort, and blood oxygen saturation. Demand concentrates in diagnostic labs across Germany and the United States where CMS reimbursement codes 95806 and 95800 validate clinical utility. Supply constraints on specialized analog-to-digital converters extend production lead times for multi-channel variants.
- Wearable Devices:Finger-worn rings, chest-strap monitors, and patch-based sensors employing miniaturized respiratory inductance plethysmography. Adoption accelerates in longitudinal screening programs and direct-to-consumer channels where compliance rates exceed traditional tethered systems. Philips and ResMed cloud platforms dominate data integration for these form factors.
- Home Sleep Tests:Pre-configured disposable or limited-use diagnostic kits designed for single-patient deployment. Pharmacy retail partnerships in North America drive volume for basic screening configurations.
- Polysomnography Devices:Full multi-parameter systems replicating in-lab diagnostic capability for unattended home deployment. Academic medical centers with captive sleep laboratory infrastructure sustain demand for complex comorbid case management.
Leading the category by volume: Portable Monitors. Growing fastest: Wearable Devices.
Technology:
Component cost tiers separate established optical sensors from emerging multi-modal architectures requiring extensive clinical validation.
- Pulse Oximetry:Photoplethysmography-based blood oxygen saturation measurement using red and infrared LED wavelengths. Reimbursement codes in the United States and Germany anchor demand for this lowest-cost modality. Semiconductor volatility for specialized photodetectors creates intermittent supply pressure.
- EEG Monitoring:Electroencephalography for sleep staging and arousal detection in hybrid home-lab protocols. Sleep clinics in tertiary care networks drive adoption where diagnostic specificity requirements exceed basic apnea-hypopnea index calculation. FDA 510(k) predicate device requirements extend development timelines for novel electrode configurations.
- Actigraphy:Accelerometer-based movement detection for sleep-wake pattern estimation. Home care settings employ these sensors as adjunctive rather than standalone diagnostic tools.
- Respiratory Inductance Plethysmography:Inductive belt sensors measuring thoracic and abdominal respiratory effort. Wearable form factor miniaturization concentrates engineering investment in this modality for next-generation devices.
Pulse Oximetry dominates unit economics. EEG Monitoring commands premium positioning and steepest expansion trajectory in reimbursement-advantaged segments.
End User:
Procurement authority and reimbursement access create distinct customer segments with diverging technical support requirements and contract structures.
- Diagnostic Labs:High-throughput facilities processing hundreds of tests monthly with automated scoring workflows. Germany's statutory health insurance-authorized networks and United States independent diagnostic testing facilities drive capital equipment procurement. AI-assisted interpretation algorithms reduce turnaround demands.
- Home Care Settings:Patient-direct deployment with remote clinical oversight via telehealth platforms. Direct-to-consumer channel development and pharmacy retail partnerships bypass traditional durable medical equipment distribution. Compliance monitoring and patient education burdens concentrate in this segment.
- Sleep Clinics:Physician-owned or hospital-affiliated practices with in-house interpretation capabilities. Board-registered polysomnographic technologist workforce constraints limit scalable testing volume.
- Healthcare Providers:Integrated delivery networks and accountable care organizations with centralized procurement. Third-party biomedical engineering service agreements disintermediate manufacturer technical support revenue.
Diagnostic Labs lead procurement volume. Home Care Settings gain share fastest as telehealth integration matures.
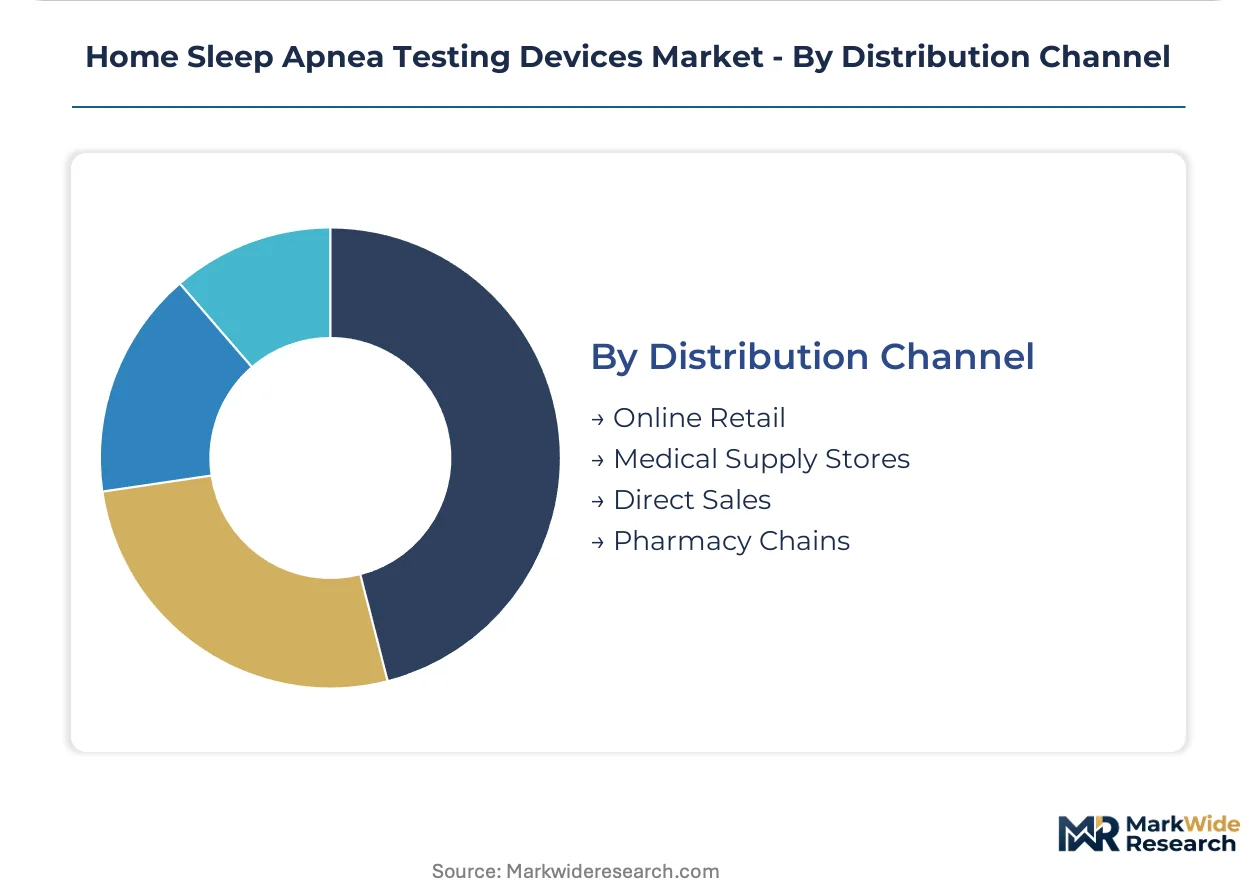
Distribution Channel:
Channel control separates manufacturers with direct sales infrastructure from those dependent on third-party intermediaries with margin compression effects.
- Direct Sales:Manufacturer-employed clinical specialists negotiating enterprise contracts with integrated delivery networks and diagnostic lab chains. United States hospital procurement departments favor this channel for capital equipment with service level agreement bundling.
- Online Retail:E-commerce platforms and telehealth-integrated direct-to-consumer pathways. Pharmacy retail partnerships expand initial screening tool access outside traditional prescription workflows. Regulatory compliance for medical device marketing varies across jurisdictions.
- Medical Supply Stores:Regional durable medical equipment distributors with local technical support capabilities. Established relationships with sleep medicine practices sustain this channel for replacement device procurement.
- Pharmacy Chains:Mass retail and specialty pharmacy networks with consumer health device sections. Over-the-counter availability for basic screening tools drives volume in markets with favorable medical device classification.
Direct Sales dominates contract value. Online Retail expands most quickly as platform integrations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors North American sleep technology development, with ResMed's headquarters driving cloud-connected platform innovation that shapes procurement standards across diagnostic networks.
United States
FDA 510(k) clearance pathways streamline market entry for portable monitors under CPT codes 95806 and 95800. Medicare coverage determinations expand physician prescribing authority beyond traditional polysomnography referrals. The Minneapolis diagnostic corridor concentrates high-throughput independent testing facilities processing hundreds of home sleep studies monthly.
Germany
Ambulatory sleep diagnostics under the German Social Code Book V gain parity reimbursement status. Statutory health insurance-authorized diagnostic networks accelerate procurement of multi-parameter home systems. The Munich-Stuttgart medical technology corridor hosts concentrated device distribution infrastructure serving Central European markets.
Japan
PMDA regulatory frameworks govern medical device approval timelines for home diagnostic equipment. METI industrial policy supports miniaturization R&D in wearable sensor technologies. The Tokyo-Osaka healthcare corridor concentrates sleep medicine practices adopting hybrid home-lab protocols.
Australia
TGA medical device regulations shape clinical validation requirements for export-oriented manufacturers. Compumedics anchors domestic sleep diagnostic technology development with established cloud platform infrastructure. The Melbourne biomedical research corridor concentrates AI-assisted scoring algorithm development for automated interpretation workflows.
United Kingdom
NICE technology appraisal guidelines influence NHS procurement criteria for home sleep testing devices. MHRA post-Brexit regulatory frameworks create parallel approval pathways distinct from EU MDR timelines. The Cambridge-London health technology corridor concentrates telehealth platform integrations bypassing traditional durable medical equipment distribution.
Home Sleep Apnea Testing Devices Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the home sleep apnea testing devices landscape. The market structure concentrates around integrated platform vendors with cloud-native architectures and specialized sensor technology developers serving cardiology-integrated niches. Three strategic archetypes dominate: full-stack platform providers bundling hardware-software-services, component specialists licensing miniaturized sensor modules, and regional distributors with localized technical support capabilities. M&A activity targets AI-assisted scoring algorithm developers, while strategic partnerships between telehealth platforms and device manufacturers disintermediate traditional durable medical equipment channels.
Within the full-stack platform tier, ResMed and Philips exemplify vertically integrated competitors with cloud-connected ecosystems spanning hardware deployment through remote monitoring subscriptions. ZOLL Itamar occupies a specialized position representing the cardiology-integrated diagnostic archetype, with peripheral arterial tone technology carving defensible positioning in electrophysiology clinic workflows. These three companies anchor the competitive structure, with ResMed's San Diego base and Philips' broad hospital channel control contrasting against ZOLL Itamar's focused clinical integration strategy.
| Leading Market Players |
|---|
| ResMed |
| Philips |
| Nihon Kohden |
| Natus Medical |
| ZOLL Itamar |
| Compumedics |
| Nox Medical |
| CleveMed |
| Onera Health |
| Others |
Supply Flow & Price Mechanics
Miniaturization of respiratory inductance plethysmography sensors is compressing component costs while concentrating procurement leverage among cloud-platform vendors with volume scale. This technology transition simultaneously erodes margins on standalone hardware and shifts value capture toward recurring software subscriptions.
Pricing Analysis
Throughput-based pricing anchors diagnostic lab procurement decisions, with automated scoring workflows commanding per-test fees that scale with interpretation volume. Three-tier pricing structure across premium, standard, and economy levels separates multi-parameter polysomnography-grade systems from basic pulse oximetry screening tools. Cost compression in economy-tier devices is intensifying because CMS reimbursement parity narrows margins on single-parameter monitors. Home care settings exhibit highest price sensitivity due to direct patient out-of-pocket exposure, while integrated delivery networks prioritize total cost of ownership over unit price.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for specialized analog-to-digital converters used in multi-channel physiological signal processing. Semiconductor fabrication for photoplethysmography photodetectors draws from China and Japan, with inductive sensor coils sourced from Germany's precision manufacturing base. Tariff exposure on Chinese electronic components creates intermittent cost volatility for wearable form factor producers. Distribution runs through manufacturer-direct sales for enterprise contracts and third-party durable medical equipment networks for regional sleep clinic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as FDA 510(k) clinical validation burdens and cloud-platform R&D requirements force capital-constrained competitors toward exit or acquisition.
For Market Incumbents: Extend cloud-native platform architectures to capture recurring remote monitoring revenue and defend against standalone hardware commoditization. Deepen backward integration into specialized sensor module production to secure supply continuity amid semiconductor volatility. Prioritize AI-assisted scoring algorithm FDA clearance to compress interpretation turnaround and lock in diagnostic lab switching costs. For New Entrants and Emerging Players: AI-first peripheral arterial tone technology convergence with implantable cardiac monitors offers entry into electrophysiology clinic workflows underserved by generalist sleep platforms. Direct-to-consumer pharmacy retail partnerships bypass entrenched durable medical equipment distribution and capture initial screening volume. Telehealth platform integration provides the essential go-to-market channel for compliance-focused patient populations. For Investors and Strategic Acquirers: Re-rating potential sits with AI-assisted scoring algorithm developers given CMS reimbursement expansion for automated interpretation workflows. Long-term viability favors targets with established post-market surveillance infrastructures capable of navigating EU MDR enhanced clinical evidence requirements. Watch for FDA 510(k) clearance acceleration as the inflection signal for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlines market entry for portable monitors under established predicate device frameworks. |
| CE Marking Pathway | EU MDR Article 120 transition extensions create temporary competitive windows for quality system-ready manufacturers. |
| Hospital System Partnership | Integrated delivery network procurement centralization favors vendors with service level agreement bundling capabilities. |
| Software Companion Development | AI-assisted scoring algorithms reduce diagnostic latency from days to hours for high-throughput sleep clinics. |
| Reimbursement Strategy | CPT codes 95806 and 95800 coverage determinations directly shape physician prescribing authority and patient access. |
Methodological Framework
Document review covered FDA 510(k) clearance databases, CMS Medicare coverage determinations, and EU MDR notified body guidance documents, complemented by interviews with sleep medicine clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, statutory health insurance reimbursement schedules, and medical device trade flow records. Bottom-up unit economics modeling triangulated against top-down market sizing from capital equipment deployment tracking.
Segment-level value outputs reflect product form factor, sensor technology modality, end-user setting, and distribution channel dimensions across the projection horizon. CAGRs were derived from regression analysis of reimbursement policy trajectories and technology adoption curves. Forecast inputs incorporated semiconductor lead time volatility and AI-assisted scoring algorithm regulatory clearance velocity.
Several conditions sit outside the modeled scope, including unannounced FDA guidance document revisions and unforeseen EU MDR notified body capacity constraints. Deviation in CMS reimbursement parity determinations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
UK Surgical Devices Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Dialysis Catheters Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
United Kingdom Minimally Invasive Surgery Devices Market
Medical Devices
EEG Electrodes Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Medical Coatings Market