
 Pacemaker/Defibrillator Lead Extraction Kits Market | 2026-2036
Pacemaker/Defibrillator Lead Extraction Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Pacemaker/Defibrillator Lead Extraction Kits Market Analytics
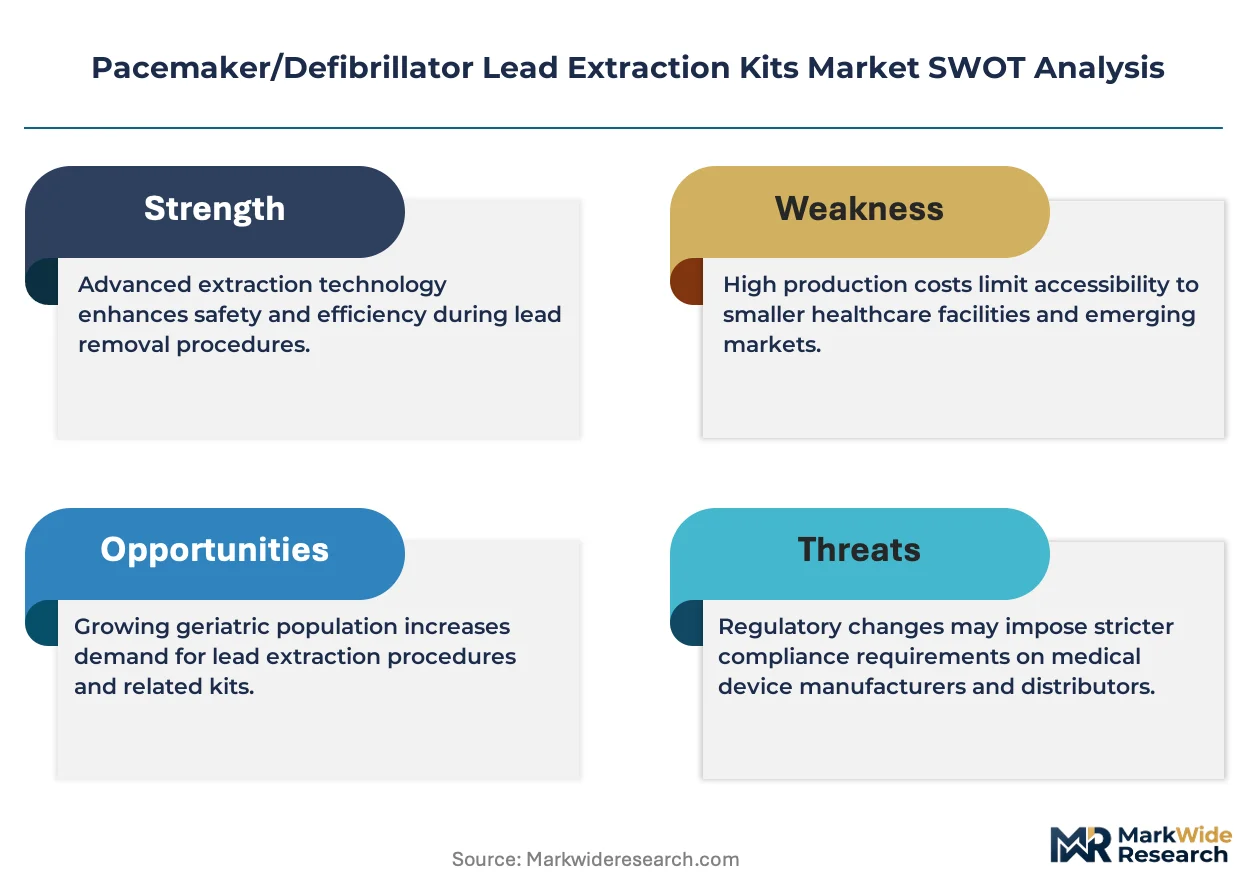
Equipment leasing and pay-per-procedure financing is fragmenting competitive access across the pacemaker/defibrillator lead extraction kits space. Abbott leverages its integrated vascular portfolio to sustain hospital contracting power. Cook Medical anchors its position through deep specialization in mechanical extraction sheaths. Spectranetics Corp differentiates via proprietary laser-based extraction platforms that command premium placement.
Pacemaker/defibrillator lead extraction kits comprise specialized tools—locking stylets, dilator sheaths, snares, and powered dissection systems—engineered to remove chronically implanted cardiac leads with controlled traction and counterpressure. These kits serve the essential purpose of enabling safe lead revision when device infection, lead fracture, or upgrade necessity arises. Mechanical extraction kits dominate procedural volume due to lower capital requirements and broader physician familiarity, while laser extraction kits capture concentrated margin pools in complex, long-dwelling lead cases. Electrosurgical extraction kits occupy a growing intermediate tier as operators seek precision between mechanical and laser approaches.
FDA 510(k) clearance pathways and EU MDR class III certification requirements shape product development timelines and commercialization costs for extraction kit manufacturers. The EPA regulates sterilization gas emissions from kit reprocessing facilities, adding compliance layers to domestic manufacturing. Japan's PMDA enforces stringent clinical evidence standards for powered extraction devices that filter market entrants. Stakeholders must monitor evolving reimbursement codes for lead extraction procedures as they determine whether hospital capital committees approve kit procurement.
Market Dynamics
Equipment leasing and pay-per-procedure financing is fragmenting competitive access across the pacemaker/defibrillator lead extraction kits space. Hospital cath labs now demand flexible capital deployment models that reduce upfront kit procurement burdens while preserving vendor accountability for procedural outcomes.
Growth Catalysts
- EU MDR Class III Device Rules:Elevated certification barriers filter marginal competitors and consolidate procurement decisions toward established kit manufacturers with full technical documentation capabilities.
- Hospital Cath Labs:Procedural volumes climb as aging implant populations require lead revision, creating dedicated extraction service lines that standardize kit consumption patterns.
- Laser-Based Extraction Platforms:Premium placement in complex, long-dwelling lead cases expands addressable procedure complexity and captures concentrated margin pools.
Market Restraints
- FDA 510(k) Clearance Pathways:Pre-market notification requirements extend product development timelines and elevate commercialization costs for novel extraction technologies.
- Japan PMDA Clinical Evidence Standards:Stringent powered device approval filters filter market entrants and delay geographic expansion for laser and electrosurgical kit categories.
- Mechanical Extraction Kit Commoditization:Lower capital requirements and broad physician familiarity compress pricing power in high-volume, straightforward extraction procedures.
Strategic Opportunities
- Germany:Aging implant populations and established cardiac device revision infrastructure create concentrated demand for advanced extraction kit portfolios.
- Electrosurgical Extraction Kits:Intermediate precision positioning between mechanical and laser approaches captures operators seeking controlled dissection without capital-intensive laser systems.
- EPA Sterilization Gas Emissions Rules:Compliance layers for kit reprocessing facilities favor manufacturers with integrated sterilization capabilities and captive supply chains.
Industry Challenges
- Lead Extraction Specialist Training:Limited fellowship programs and procedural volume requirements constrain qualified operator supply, capping procedural throughput expansion.
- Reimbursement Code Evolution:Hospital capital committees withhold kit procurement approvals until definitive procedure coding and payment parity stabilizes.
- Powered System Integration Complexity:Laser and electrosurgical platforms require specialized maintenance protocols and vendor field service networks that strain rural and community hospital adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pacemaker/Defibrillator Lead Extraction Kits Market |
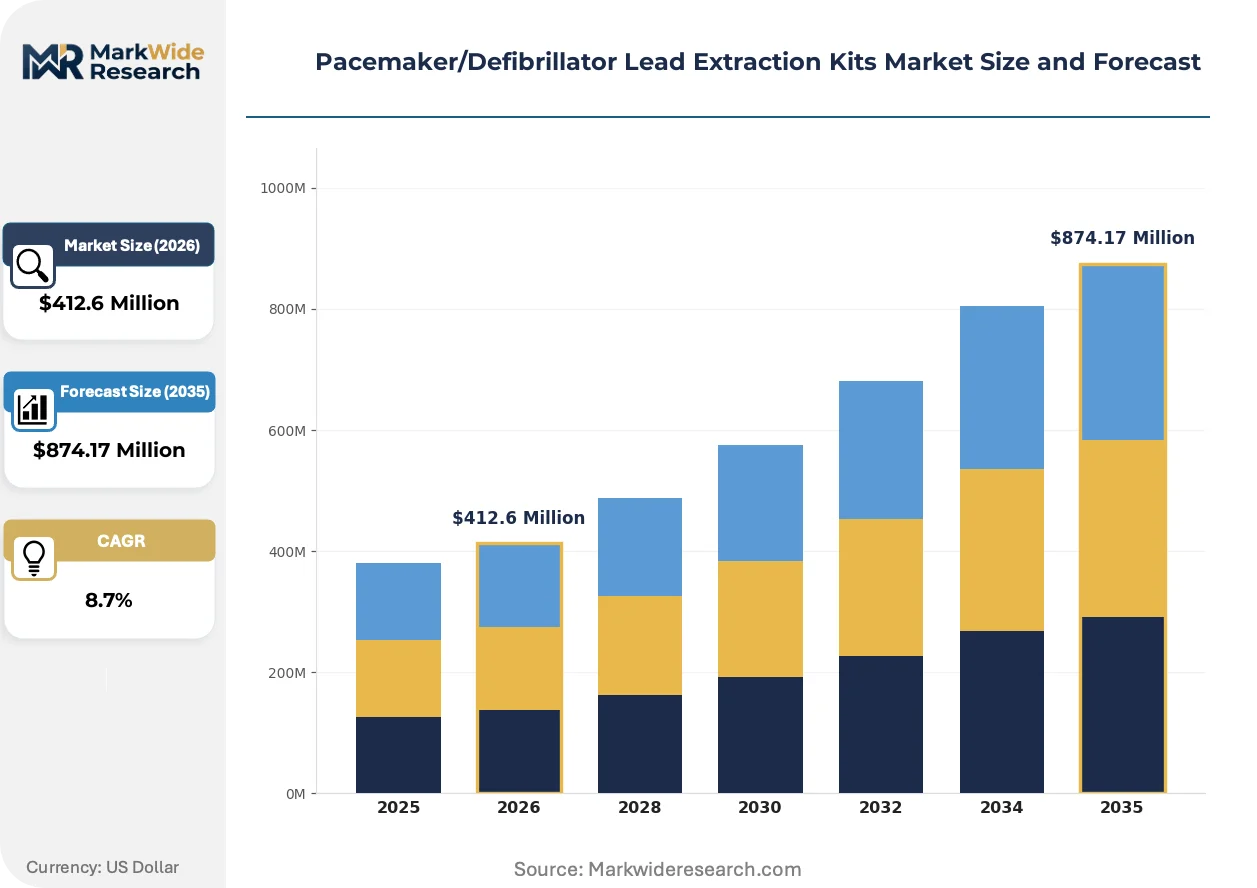
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Extraction Kits, Electrosurgical Extraction Kits, Laser Extraction Kits, Hybrid Extraction Kits End User: Hospitals, Cardiac Care Centers, Outpatient Clinics, Emergency Rooms Application: Lead Removal, Device Replacement, Cardiac Maintenance, Infection Control Distribution Channel: Direct Sales, Distributors, Online Retail, Healthcare Organizations |
| Companies Covered | Abbott, Philips Healthcare, Cook Medical, Eximo Medical, Vascomed, Spectranetics Corp, St Jude Medical Inc, Lepu Medical Technology Beijing Co Ltd, Idev Technologies Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pacemaker/Defibrillator Lead Extraction Kits Market Evolving Landscape
Active migration toward precision-controlled extraction modalities is compressing the historical dominance of purely mechanical approaches. This shift reconfigures kit portfolio architecture and vendor capability requirements across hospital procurement cycles.
Mechanical extraction sheaths are migrating from standard locking stylet configurations toward integrated dilator-snare systems that reduce procedural steps. Community hospital cath labs adopt these streamlined kits to compensate for lower annual extraction volumes and limited on-site specialist depth. The technology is migrating from high-volume academic centers into mid-tier facilities, expanding addressable market footprint while pressuring premium laser system placement.
EU MDR technical documentation requirements now mandate clinical performance data for Class III cardiac device accessories. Manufacturers must maintain post-market surveillance systems and periodic safety update reports that extend regulatory affairs staffing. Powered extraction kit categories face the steepest compliance burden, creating competitive separation between firms with established European notified body relationships and new market aspirants.
Leasing arrangements now displace outright capital purchase for laser extraction platforms in United States hospital systems. Financial risk transfers to vendors through per-procedure utilization guarantees that align kit supply with actual clinical throughput. This restructuring concentrates most visibly in integrated delivery networks seeking to standardize extraction capabilities across multi-site cardiac service lines without equipment redundancy.
Pacemaker/Defibrillator Lead Extraction Kits Market Segmentation
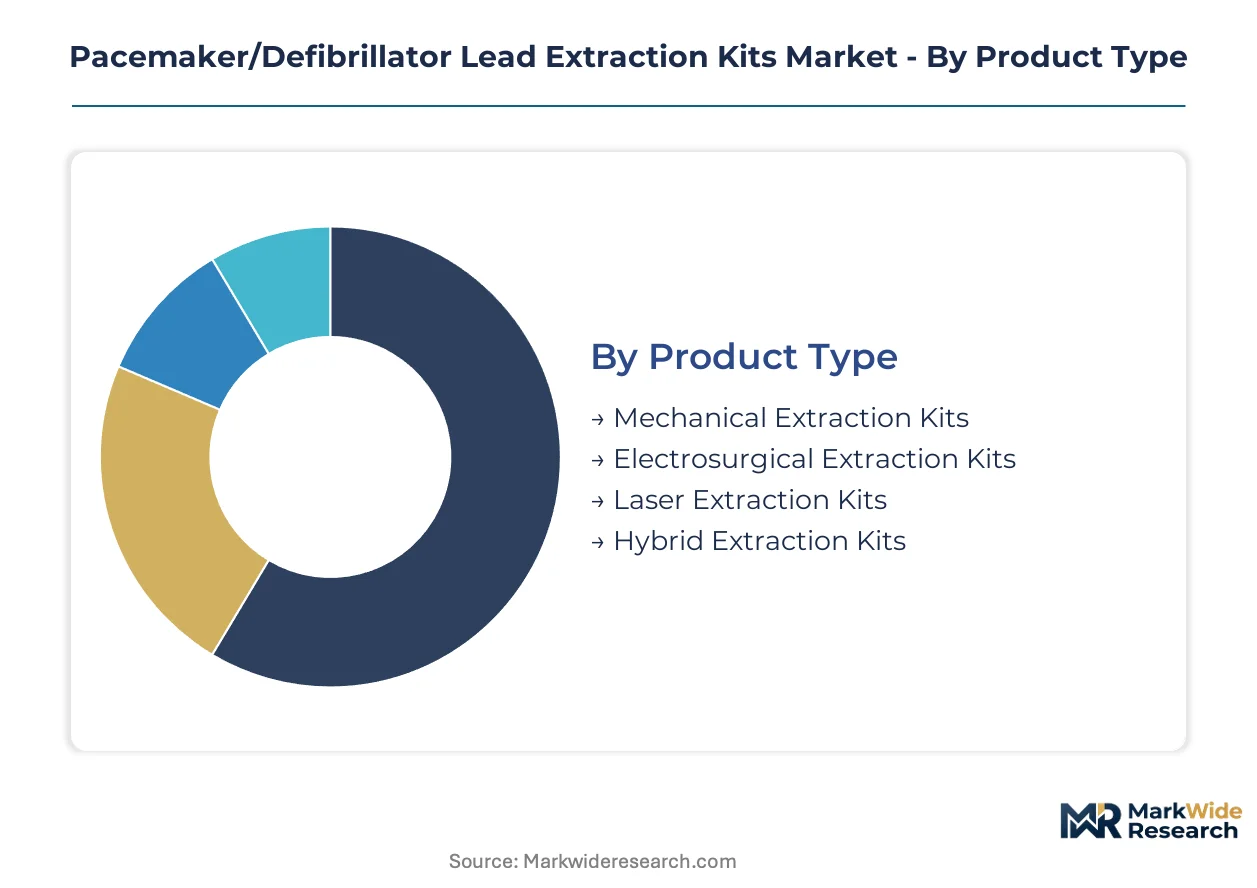
Segmentation in pacemaker/defibrillator lead extraction kits reveals how procedural complexity, capital constraints, and clinical settings reshape procurement patterns. Understanding these divisions exposes where mechanical familiarity yields to powered precision, and where hospital cath labs diverge from outpatient workflows.
Product Type:
Mature mechanical platforms anchor procedural volume while emerging powered modalities capture premium placement in complex cases.
- Mechanical Extraction Kits:Locking stylets, dilator sheaths, and snare systems enable controlled traction without capital-intensive powered equipment. Demand concentrates in community hospital cath labs across the United States and Germany where lower annual extraction volumes limit laser system justification.
- Laser Extraction Kits:Proprietary powered platforms employ excimer laser energy to ablate fibrotic encapsulation around chronically implanted leads. Academic medical centers in Japan and the United States deploy these systems for long-dwelling leads where mechanical extraction risks venous perforation.
- Electrosurgical Extraction Kits:Radiofrequency-based dissection offers intermediate precision between mechanical and laser approaches. Cardiac care centers adopt these to access powered extraction capabilities without full laser capital commitment.
- Hybrid Extraction Kits:Integrated mechanical-powered configurations allow procedural flexibility within single kit architecture. Operators in high-volume extraction service lines favor these for unpredictable lead adhesion patterns.
Mechanical extraction kits handle the majority of throughput; laser extraction kits are gaining share fastest in tertiary referral centers.
End User:
Customer type segmentation tracks how procedural volume thresholds and specialist availability determine kit specification and financing structure.
- Hospitals:Integrated cardiac service lines with dedicated electrophysiology labs standardize on multi-modal kit portfolios. Hospital cath labs in the United States, Germany, and Japan drive procurement of advanced extraction platforms through leasing arrangements that transfer capital risk to vendors.
- Cardiac Care Centers:Specialized facilities with concentrated device revision volumes achieve economies in kit consumption that justify premium powered system placement. These centers in Germany and the United States establish regional referral networks for complex extraction cases.
- Outpatient Clinics:Limited to straightforward lead revisions with minimal vascular adhesion. Mechanical kits dominate these settings where immediate surgical backup remains unavailable.
- Emergency Rooms:Occasional extraction demand for device infection or lead fracture emergencies. Stocking constraints favor compact mechanical kits with broad procedural applicability.
Hospital cath labs absorb the dominant share of kit value; cardiac care centers are expanding most quickly as dedicated extraction service lines proliferate.
Application:
Application segmentation separates scheduled revision workflows from urgent clinical scenarios with divergent kit performance requirements.
- Lead Removal:Primary extraction indication encompassing lead fracture, insulation breach, or upgrade necessity. United States hospital systems report highest procedural volumes as aging implant populations from the 1990s and 2000s require systematic revision.
- Infection Control:Device or lead-associated endocarditis mandates complete hardware explantation. These cases in Germany and Japan command premium kit specifications due to friable tissue and systemic sepsis risk.
- Device Replacement:Generator upgrade or battery depletion with existing lead retention. Straightforward procedures favor streamlined mechanical kits in high-throughput settings.
- Cardiac Maintenance:Prophylactic lead revision or lead abandonment management. Selective extraction decisions balance procedural risk against long-term hardware burden.
Lead removal applications command the largest procedure volume; infection control applications are climbing fastest as antimicrobial resistance elevates hardware explantation frequency.
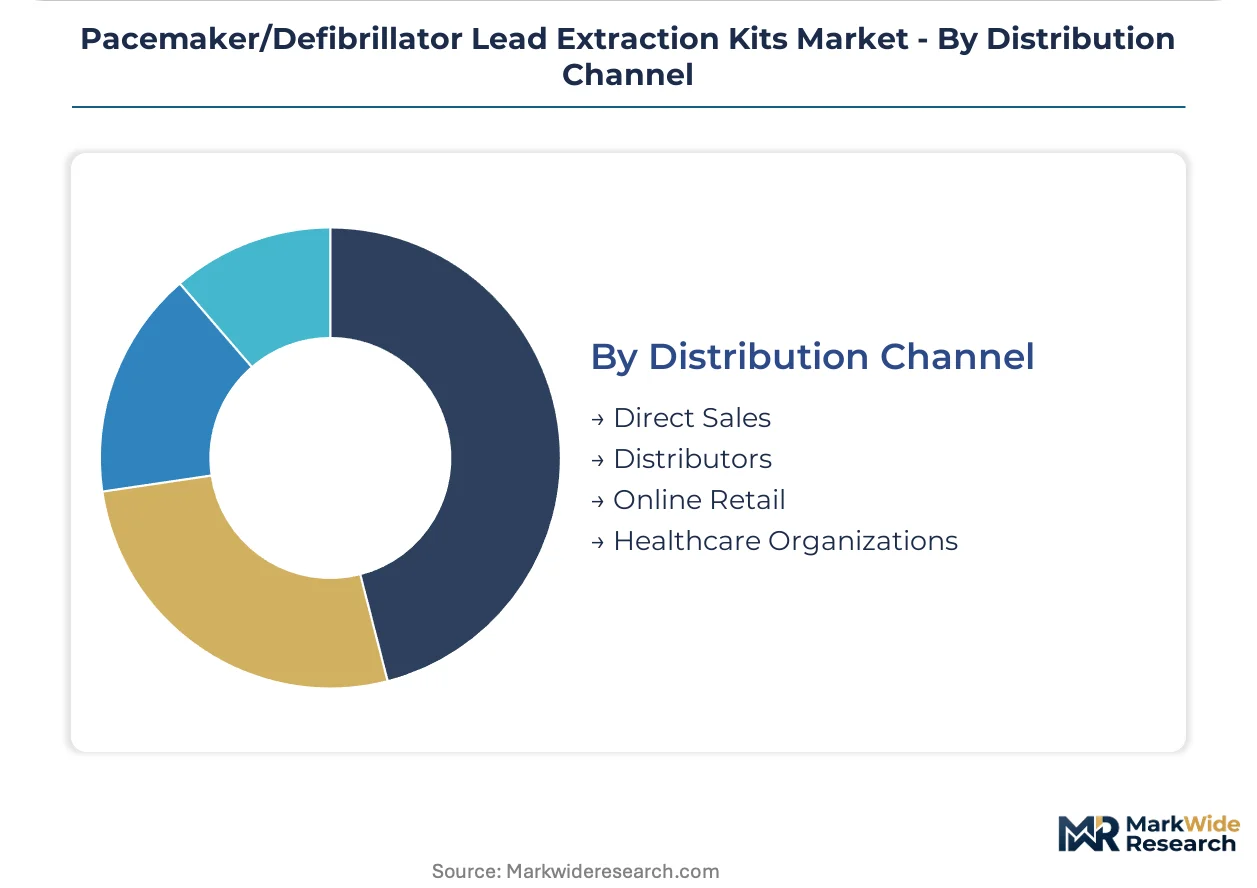
Distribution Channel:
Channel segmentation reflects how vendor control over technical support and training infrastructure shapes kit procurement patterns.
- Direct Sales:Manufacturer field service networks provide on-site laser system maintenance and operator training. United States integrated delivery networks negotiate enterprise-wide extraction platform standardization through direct vendor relationships.
- Distributors:Regional medical device distributors extend mechanical kit reach into mid-tier hospitals with limited specialist depth. German hospital procurement federations leverage distributor networks for consolidated mechanical kit purchasing.
- Online Retail:Limited to consumable components and replacement parts for established extraction systems. Regulatory constraints on Class III device traceability restrict full kit online distribution.
- Healthcare Organizations:Group purchasing organizations aggregate demand across multi-hospital systems. These entities in the United States increasingly specify outcome-based utilization guarantees for powered extraction platforms.
Direct sales channels capture the dominant share of powered system revenue; distributor channels are expanding most quickly for mechanical kit categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital cath labs in the United States, Germany, and Japan concentrate procurement authority for extraction kits. Aging implant populations from the 1990s and 2000s drive systematic lead revision demand across these markets. Regulatory complexity and reimbursement structures determine which kit modalities achieve placement.
United States
FDA 510(k) clearance pathways shape product development timelines for domestic manufacturers. Hospital systems in Cleveland Clinic and Mayo Clinic corridors establish dedicated extraction service lines that standardize kit consumption. Leasing arrangements displace capital purchase for laser platforms as integrated delivery networks seek equipment standardization.
Germany
EU MDR Class III device rules elevate certification barriers and consolidate procurement toward established manufacturers. The country's cardiac device revision infrastructure in Berlin and Munich corridors creates concentrated demand for advanced extraction portfolios. Hospital procurement federations leverage distributor networks for consolidated mechanical kit purchasing.
Japan
PMDA clinical evidence standards for powered extraction devices filter market entrants and delay category expansion. Academic medical centers in Tokyo and Osaka deploy laser systems for long-dwelling leads where mechanical extraction risks venous perforation. Aging implant populations from early pacemaker adoption waves now require systematic hardware revision.
United Kingdom
NHS procurement frameworks emphasize outcome-based utilization guarantees for powered extraction platforms. Specialist centers in London and Manchester establish regional referral networks for complex extraction cases. Post-Brexit regulatory divergence from EU MDR creates dual compliance burdens for kit manufacturers.
India
CDSCO medical device regulations are tightening for Class C and D cardiac accessories including extraction tools. Private hospital chains in Delhi-NCR and Mumbai corridors represent the primary addressable market for premium kit categories. Domestic manufacturers concentrate on mechanical kit production for cost-sensitive institutional procurement.
Pacemaker/Defibrillator Lead Extraction Kits Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base spans integrated cardiovascular conglomerates, dedicated extraction device specialists, and regional mechanical kit fabricators. Three archetypes dominate: diversified cardiovascular portfolio holders, laser-powered extraction platform specialists, and mechanical sheath pure-plays. Competitive moves concentrate on hospital system contracting consolidation and per-procedure financing innovation.
Among diversified portfolio holders, Abbott and Philips Healthcare occupy positions representing integrated vascular and cardiovascular imaging capabilities. Cook Medical exemplifies the mechanical extraction specialist archetype through concentrated sheath technology development. Spectranetics Corp anchors the powered platform specialist tier with proprietary laser-based systems commanding premium placement in complex cases.
| Leading Market Players |
|---|
| Abbott |
| Philips Healthcare |
| Cook Medical |
| Eximo Medical |
| Vascomed |
| Spectranetics Corp |
| St Jude Medical Inc |
| Lepu Medical Technology Beijing Co Ltd |
| Idev Technologies Inc |
| Others |
Value Network & Pricing Analysis
Minneapolis-St. Paul anchors North American mechanical extraction kit manufacturing, where concentrated polymer molding and sterilization capacity creates downstream pricing leverage for integrated producers against fragmented component suppliers. Laser system assembly clusters in Colorado and Massachusetts feed premium pricing power through captive optical engineering and field service networks that lock hospital systems into long-term utilization contracts.
Pricing Analysis
Cost-plus contracts with medical-grade polymer indexation dominate mechanical kit procurement between German hospital federations and regional distributors. Three-tier pricing structure across premium laser platforms, standard electrosurgical systems, and economy mechanical configurations separates academic medical centers from community hospitals and emergency settings. Pricing pressure stems from EU MDR compliance cost pass-through and sterilization gas emission controls that squeeze mid-tier manufacturers. Community hospital cath labs exhibit highest price sensitivity due to capital committee constraints, while integrated delivery networks prioritize outcome guarantees over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates with specialized medical device CMs in Ireland, Costa Rica, and Malaysia that hold validated Class III device assembly lines. Raw material dependencies center on medical-grade nitinol for locking stylets, excimer laser gas mixtures for powered platforms, and ethylene oxide sterilization services. Single-source vulnerability runs through sterilization capacity as EPA emission rules shutter domestic facilities. Distribution runs through manufacturer-direct field service for laser systems and regional distributors for mechanical kit categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pacemaker/defibrillator lead extraction kits market tracks a cyclical recovery anchored to aging implant populations from the 1990s and 2000s entering systematic revision windows. Hospital cath lab capital deployment cycles and reimbursement code stabilization will determine amplitude.
For Market Incumbents: Insulate laser platform margins through per-procedure leasing structures that transfer utilization risk and lock multi-site standardization. Deepen backward integration into excimer laser gas supply and sterilization capacity to offset EPA compliance cost volatility. Defend against mechanical kit commoditization by bundling procedural training and outcome guarantees that raise switching costs for hospital systems. For New Entrants and Emerging Players: India's private hospital chains in Delhi-NCR and Mumbai corridors offer the most penetrable geographic white space as CDSCO regulations tighten but premium kit adoption lags. Electrosurgical extraction kits represent the most accessible product tier, positioning between capital-intensive laser systems and commoditized mechanical approaches. Target GPO contract manager relationships with outcome-based utilization models that mimic incumbent leasing structures without full platform investment. For Investors and Strategic Acquirers: Long-term, this sits as a demographic tailwind play because aging cardiac device implant populations create non-discretionary revision demand with limited substitution alternatives. Acquisition targets should concentrate on electrosurgical platform specialists with FDA 510(k) clearance momentum and European notified body relationships. Monitor PMDA powered device approval timelines in Japan as the signal for category expansion feasibility across Asia-Pacific markets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for novel electrosurgical extraction technologies in United States hospital systems. |
| CE Marking Pathway | EU MDR Class III technical documentation requirements filter competitors and consolidate procurement toward established manufacturers. |
| Hospital System Partnership | Integrated delivery network standardization agreements lock multi-site laser platform placement through per-procedure financing. |
| Reimbursement Strategy | CMS coding parity for lead extraction procedures determines hospital capital committee approval velocity for kit procurement. |
| Software Companion Development | Procedural planning algorithms and extraction difficulty scoring enhance laser system differentiation in academic medical centers. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract records preceded structured interviews with electrophysiology lab directors, biomedical engineering managers, GPO contracts specialists, and cardiovascular device regulatory affairs leads. Secondary validation drew from CMS Medicare procedure data, Japanese PMDA approval registers, and German hospital federation purchasing reports. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Assumptions held fixed include regulatory pathway timelines for Class III device categories and reimbursement code stability for lead extraction procedures. Variable assumptions encompassed hospital cath lab capital deployment cycles and specialist operator training program expansion rates. The analytical framework modeled segmentation across product type, end user, application, and distribution channel dimensions. CAGRs derived from logistic diffusion curves fitted to aging implant population data and procedural volume elasticity estimates.
Practitioners should monitor EU MDR notified body capacity constraints and PMDA powered device approval decisions for early signals of supply-side compression or geographic expansion feasibility. Quarterly review of hospital GPO contract award announcements and CMS physician fee schedule updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nurse Call Systems Market
Medical Devices
UK Surgical Devices Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Laser BPH Devices Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Medical Electronics Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Absorbable Antibacterial Envelope Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Artificial Spine Discs Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Global Concussion Market
Medical Devices
3D Medical Imaging Devices Market