
 Neuro Critical Care Market | 2026-2036
Neuro Critical Care Market Size, Share, and Industry Trends Forecast 2026-2036
Neuro Critical Care Market Foresight
Market Context with Strategic Players
Hospital procurement channels for neuro critical care systems is narrowing around bundled service contracts that tie device placement to long-term monitoring subscriptions. GE Healthcare leverages its imaging-installed base to cross-sell ICU monitoring ecosystems, while Medtronic anchors its position through deep catheter and neuromodulation portfolios that feed into integrated critical care workflows. Philips N.V. competes by extending its patient monitoring architecture into cloud-native analytics platforms that span pre-hospital through ICU discharge.
Technical Definition and Structural Segments
Neuro critical care encompasses the specialized medical discipline and associated technologies for managing life-threatening neurological conditions, including traumatic brain injury, subarachnoid hemorrhage, and status epilepticus, through continuous multimodal monitoring of intracranial pressure, cerebral perfusion, and electrophysiological parameters to prevent secondary brain injury. The field deploys invasive and non-invasive systems that integrate hemodynamic, metabolic, and neuroimaging data streams to guide therapeutic interventions in real time. Monitoring Devices occupies the largest revenue pool as hospitals prioritize continuous ICP and EEG platforms, while Brain-Computer Interface technology represents the fastest-expanding segment as research translation accelerates toward clinical communication and control applications for locked-in patients. Therapeutic Equipment maintains mature margins in mechanical ventilation and temperature management, though margin pools increasingly shift toward software-enabled predictive analytics layered atop hardware foundations.
Regulatory Frame and Forward Outlook
The FDA breakthrough device program and EU MDR classification for active implantable neurological devices create divergent compliance burdens that shape market entry sequencing and clinical evidence requirements. Health Canada and TGA alignment with FDA predicate pathways streamlines parallel submissions for North American and Asia-Pacific commercialization. Stakeholders must monitor how FDA guidance on artificial intelligence-enabled neurodiagnostic devices redefines predicate equivalence standards and whether EU AI Act risk categorization captures closed-loop neurostimulation systems under high-risk obligations.
Market Dynamics
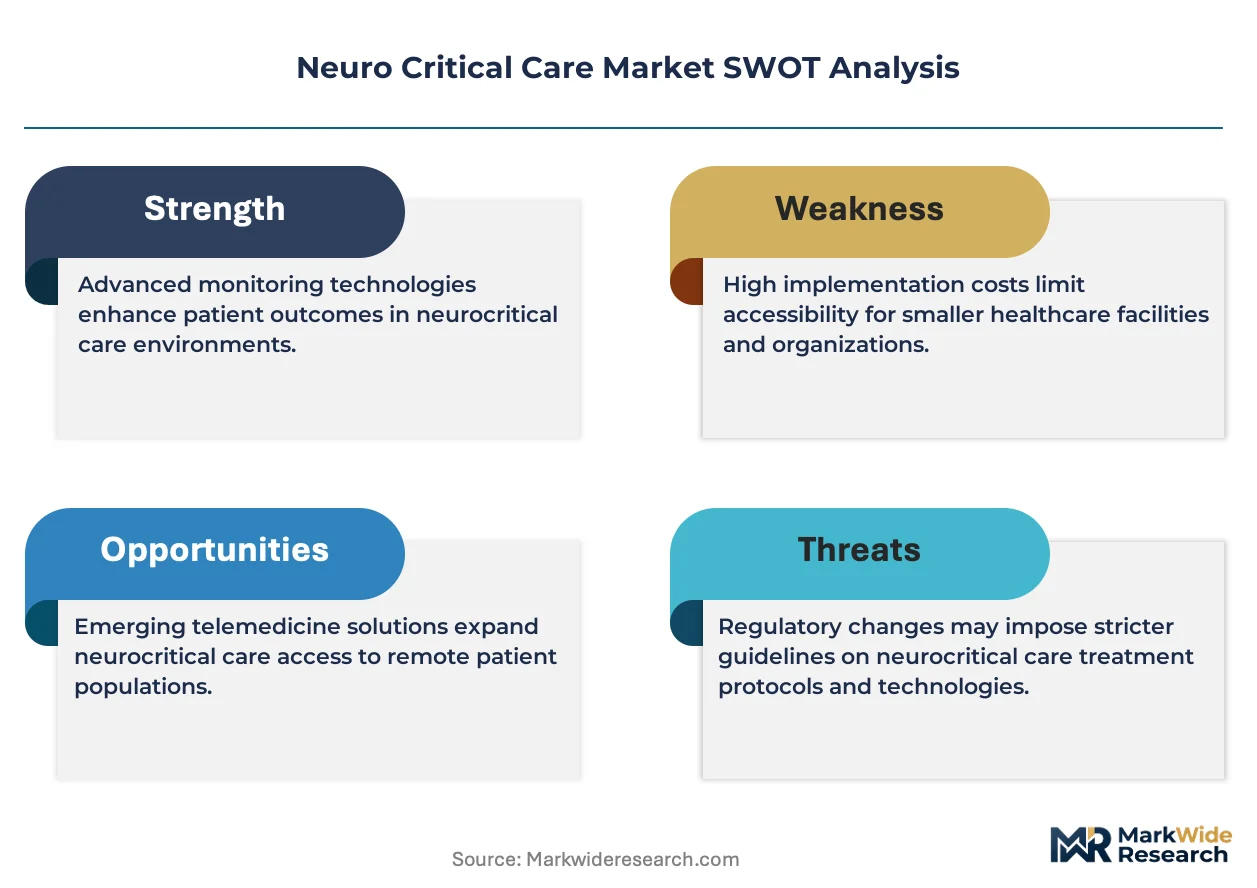
Hospital procurement consolidation around bundled monitoring subscriptions is compressing vendor margins while locking tertiary centers into multi-year platform commitments that favor integrated ecosystem providers over standalone device manufacturers.
Growth Catalysts
- FDA Breakthrough Device Pathway:Accelerated review timelines for neurological devices reduce commercialization cycles from 18-24 months to 8-12 months, enabling faster patient access to intracranial pressure monitoring innovations.
- Traumatic Brain Injury Protocol Standardization:Military and civilian trauma networks in the United States, Germany, and Australia now mandate continuous multimodal monitoring for severe TBI cases, creating institutional demand pull.
- Machine Learning Integration:Predictive algorithms layered atop EEG and ICP data streams enable preemptive intervention for secondary brain injury, converting reactive critical care into proactive management workflows.
Market Restraints
- Implantable Component Supply Concentration:Specialized pressure transducers and biocompatible catheter materials concentrate among three European suppliers, exposing device manufacturers to input volatility and allocation risk.
- EU MDR Clinical Evidence Burden:Reclassification of active implantable neurological devices under MDR Article 52 requires prospective clinical trials for legacy products, freezing some product lines in regulatory limbo.
- Non-Invasive Monitoring Substitution:Transcranial Doppler and near-infrared spectroscopy advances reduce invasive ICP monitor placement rates in select subarachnoid hemorrhage protocols, compressing addressable procedure volumes.
Strategic Opportunities
- India Tertiary Hospital Expansion:Government medical college upgrades and private hospital neuro-ICU investments in Mumbai, Delhi, and Chennai create first-mover advantage for monitoring platform vendors willing to localize service infrastructure.
- Brain-Computer Interface Clinical Translation:Locked-in syndrome communication and motor restoration applications move from research to reimbursable clinical utility, opening new revenue pools beyond traditional critical care monitoring.
- Pre-Hospital to ICU Data Continuity:Cloud-native platforms that ingest ambulance-based EEG and vital sign streams enable seamless handoffs, differentiating vendors who control the full temporal data chain.
Industry Challenges
- Neurocritical Care Specialist Shortage:Fellowship-trained intensivists capable of interpreting multimodal monitoring data remain concentrated at academic medical centers, limiting technology deployment to community hospitals.
- Legacy EMR Integration Complexity:Proprietary data formats from established monitoring systems require costly middleware development to achieve interoperability with Epic and Cerner installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuro Critical Care Market |
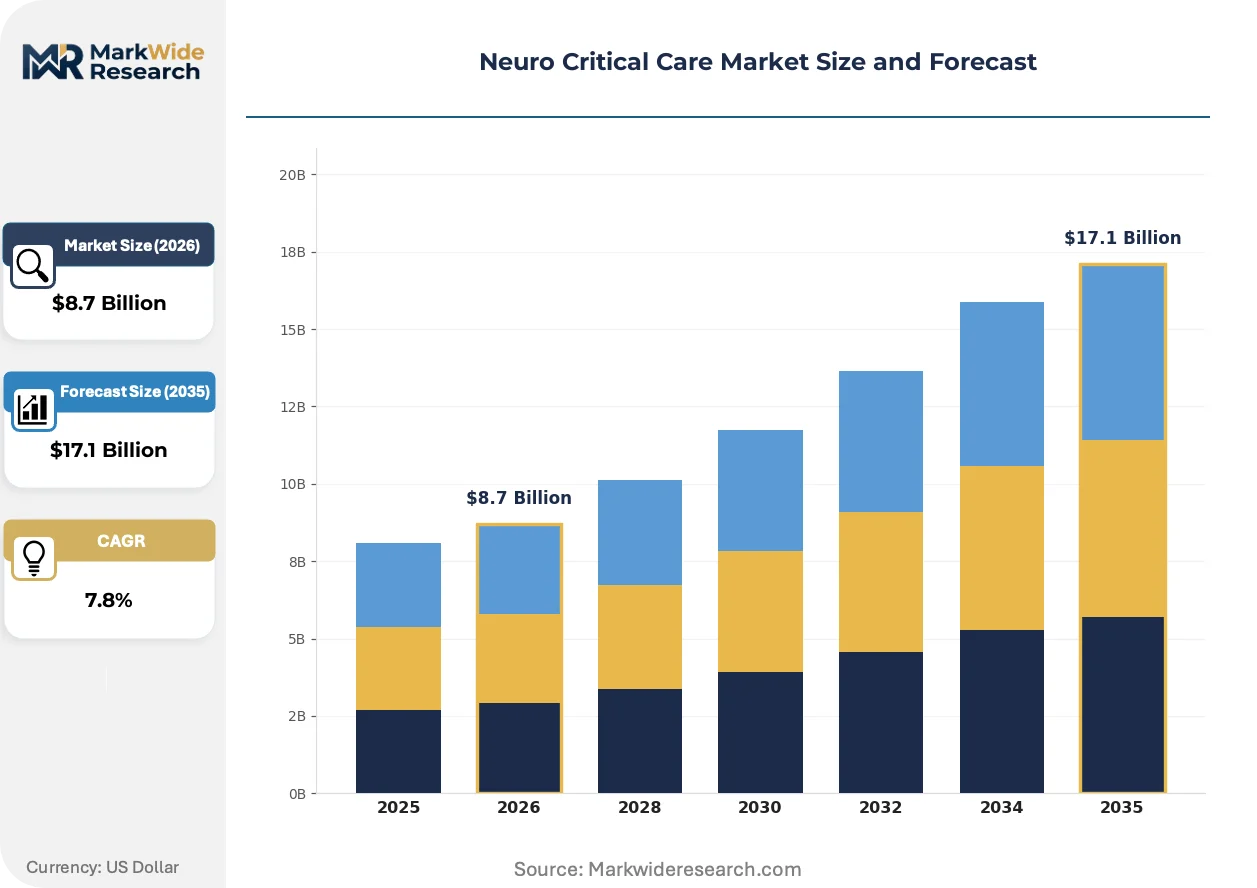
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Devices, Therapeutic Equipment, Diagnostic Tools, Supportive Technology Care Setting: Hospitals, Intensive Care Units, Neurology Centers, Rehabilitation Facilities End User: Neurosurgeons, Critical Care Physicians, Nurses, Allied Health Professionals Technology: Telemedicine, Advanced Imaging, Brain-Computer Interface, Neurostimulation |
| Companies Covered | GE Healthcare, Edwards Lifesciences Corporation, Medtronic, Drägerwerk AG & Co. KGaA, Integra LifeSciences Corporation, Abbott, Teleflex Incorporated, Nihon Kohden Corporation, Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuro Critical Care Market Shifts & Advancements
Artificial intelligence is compressing the interpretation bottleneck in neurophysiological monitoring while regulatory frameworks scramble to keep pace with closed-loop therapeutic systems that blur diagnostic and therapeutic device boundaries.
Continuous AI-enabled EEG pattern recognition is rendering obsolete the traditional model of delayed offline review by board-certified neurophysiologists. Tertiary referral centers in the United States and Germany now deploy real-time seizure detection and burst-suppression quantification at the bedside, enabling immediate therapeutic adjustment rather than waiting for specialist consultation windows.
EU AI Act risk classification for closed-loop neurostimulation systems is forcing manufacturers to restructure clinical evidence packages ahead of 2026 implementation. High-risk obligations for systems that autonomously modulate intracranial pressure or cerebral perfusion will require prospective safety studies and post-market surveillance protocols that add 12-18 months to development timelines, advantaging larger players with existing MDR infrastructure.
Service unbundling from hardware placement is disrupting traditional capital equipment sales models. Hospital systems in Texas, Florida, and California now negotiate monitoring subscriptions separately from device procurement, with per-patient-per-day pricing for algorithmic analysis and remote specialist oversight replacing lump-sum capital outlays and separate maintenance contracts.
Neuro Critical Care Market Segmentation
Neuro critical care segmentation reveals how technology specialization, care delivery location, and clinical workflow integration create distinct commercial entry points. Vendors must align product architecture with the specific monitoring intensity and therapeutic intervention requirements of each segment cluster.
Product Type:
Cost tier differentiation separates capital-intensive integrated platforms from discrete diagnostic instruments and consumable-supported technologies.
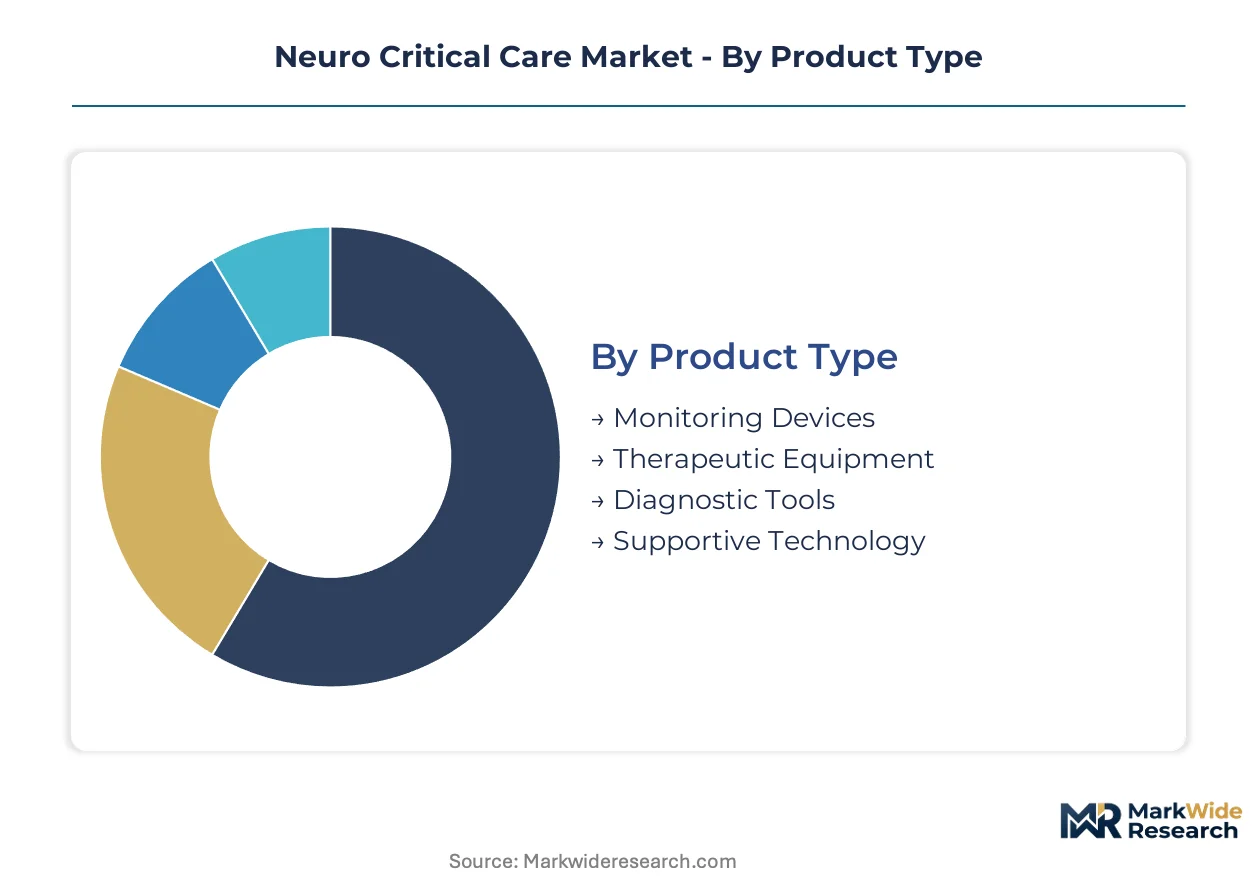
- Monitoring Devices:Continuous intracranial pressure, cerebral perfusion, and electrophysiological monitoring systems form the revenue foundation. Hospital neuro-ICUs in the United States and Germany prioritize multimodal platforms that consolidate ICP, EEG, and PbtO2 streams, though supply concentration in European pressure transducer manufacturers creates procurement vulnerability.
- Therapeutic Equipment:Mechanical ventilation, targeted temperature management, and cerebrospinal fluid drainage systems deliver mature margin profiles. Demand concentrates in tertiary referral centers managing status epilepticus and refractory intracranial hypertension, where device integration with monitoring platforms determines purchasing decisions.
- Diagnostic Tools:Portable CT, transcranial Doppler, and point-of-care biomarker assays enable rapid neurological assessment.
- Supportive Technology:Patient positioning systems, specialized bedding, and environmental controls reduce secondary injury risk.
Monitoring Devices holds installed capacity. Brain-Computer Interface applications within Supportive Technology are rotating up the share rankings.
Care Setting:
Application intensity varies dramatically across settings, from continuous invasive monitoring in dedicated units to intermittent assessment in step-down and recovery environments.
- Hospitals:General acute care facilities with neuro-ICU capabilities require scalable monitoring architectures that adapt to admission surges. Trauma centers in Australia and military treatment facilities in the United States now mandate continuous multimodal protocols for severe TBI, institutionalizing demand pull.
- Intensive Care Units:Dedicated neuro-ICUs represent the highest acuity deployment environment. These units in Mumbai, Delhi, and Chennai are expanding through government medical college upgrades and private hospital investments, creating first-mover opportunities for platform vendors with localized service infrastructure.
- Neurology Centers:Specialized outpatient and inpatient facilities focus on elective intervention and post-acute monitoring.
- Rehabilitation Facilities:Long-term recovery settings deploy lower-intensity monitoring for secondary prevention and functional restoration.
Intensive Care Units command premium pricing. Neurology Centers are climbing the fastest as ambulatory surgical expansion redirects lower-acuity cases.
End User:
Customer type determines purchasing authority, with surgeons driving device selection while critical care physicians influence monitoring protocol design and nursing staff determine usability adoption.
- Neurosurgeons:Invasive monitoring placement and therapeutic intervention decisions rest with surgical specialists. Their preference for catheter-based ICP systems and external ventricular drain integration shapes device form factor requirements.
- Critical Care Physicians:Multimodal data interpretation and therapeutic adjustment authority concentrates with fellowship-trained intensivists. Their scarcity at community hospitals limits technology deployment outside academic medical centers.
- Nurses:Bedside monitoring management and alarm response workflows depend on interface design.
- Allied Health Professionals:Rehabilitation therapists and neuropsychologists influence post-acute technology selection.
Critical Care Physicians control protocol standardization. Nurses are gaining purchasing influence as staffing shortages elevate retention technology to strategic priority.
Technology:
Maturity stage separates established imaging and telemedicine platforms from emerging neurostimulation and brain-computer interface modalities.
- Telemedicine:Remote specialist consultation and continuous monitoring oversight platforms extend neurocritical expertise to underserved regions. Cloud-native architectures that span pre-hospital through ICU discharge are differentiating vendor competitive position.
- Advanced Imaging:Portable CT, MRI-compatible monitoring, and quantitative EEG processing enable rapid diagnostic confirmation. These systems concentrate in tertiary centers with capital equipment budgets and specialized technical staffing.
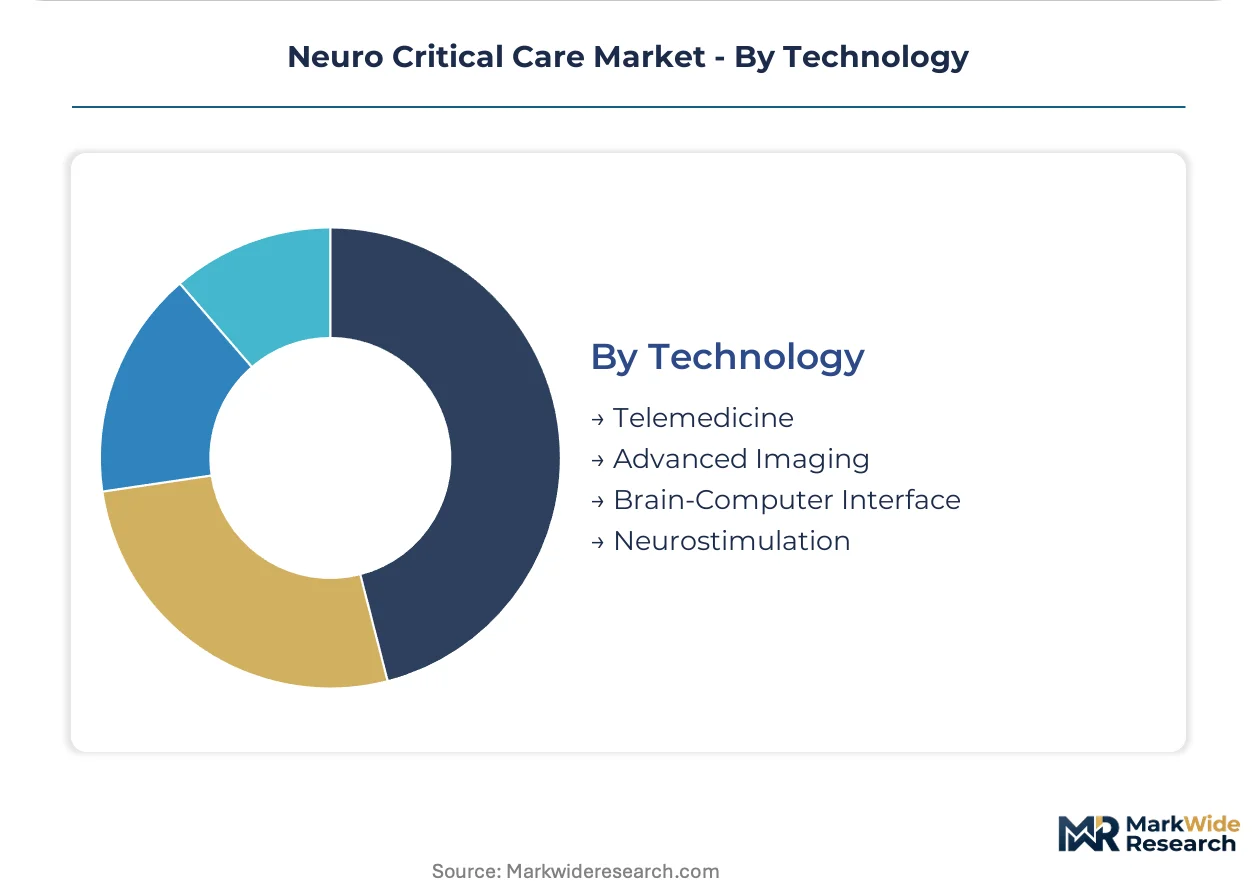
- Brain-Computer Interface:Locked-in syndrome communication and motor restoration applications are translating from research to reimbursable clinical utility. FDA breakthrough device designation is accelerating commercialization timelines for invasive and non-invasive neural signal acquisition systems.
- Neurostimulation:Closed-loop intracranial pressure modulation and cerebral perfusion optimization systems face EU AI Act high-risk classification requirements.
Advanced Imaging holds installed capacity. Brain-Computer Interface represents the steepest expansion trajectory as clinical translation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States neuro-ICU platforms command premium pricing against German equivalents, creating a structural asymmetry that channels vendor investment toward tertiary referral centers in Texas and California while European procurement consolidates around bundled service contracts.
United States
Trauma network standardization and military treatment facility protocols institutionalize demand for continuous multimodal monitoring. FDA breakthrough device designation accelerates commercialization timelines for intracranial pressure innovations. Houston and Dallas medical centers expand neuro-ICU capacity through private hospital investments and academic medical center consolidation.
Germany
Civilian trauma networks mandate continuous monitoring for severe traumatic brain injury, creating protocol-driven demand pull. EU MDR reclassification of active implantable neurological devices requires prospective clinical trials for legacy products. Munich and Berlin tertiary centers concentrate fellowship-trained intensivist expertise that shapes technology deployment decisions.
India
Government medical college upgrades and private hospital neuro-ICU investments generate first-mover opportunities for platform vendors. CDSCO alignment with FDA predicate pathways streamlines device registration for multinational manufacturers. Mumbai, Delhi, and Chennai clusters expand through localized service infrastructure commitments from monitoring ecosystem providers.
Australia
TGA alignment with FDA pathways enables parallel submission strategies for Asia-Pacific commercialization. Civilian trauma networks adopt continuous multimodal protocols for severe TBI cases. Sydney and Melbourne academic medical centers concentrate complex case volumes that justify capital-intensive platform investments.
Japan
PMDA regulatory frameworks for neurological devices create distinct evidence requirements that shape market entry sequencing. Aging demographics expand addressable patient populations for stroke and subarachnoid hemorrhage interventions. Tokyo and Osaka metropolitan hospital networks consolidate neurocritical care capabilities through regional referral system reforms.
Neuro Critical Care Market Competitive Landscape
Integrated monitoring ecosystem providers and standalone device manufacturers split the market along bundled subscription versus capital equipment fault lines. Hospital procurement consolidation favors vendors with cloud-native analytics platforms that span pre-hospital through ICU discharge. Three archetypes dominate: diversified medical technology conglomerates with imaging-installed bases, specialized neuromodulation and catheter portfolios, and emerging brain-computer interface specialists. Competitive moves concentrate on cross-selling ICU monitoring ecosystems and securing long-term algorithmic analysis subscriptions.
Among diversified medical technology conglomerates, GE Healthcare and Philips N.V. exemplify the imaging-to-monitoring cross-sell archetype, while Medtronic anchors the specialized neuromodulation portfolio position. These three occupy distinct competitive spaces within the integrated ecosystem tier, with each representing a different pathway to neuro-ICU platform dominance.
| Leading Market Players |
|---|
| GE Healthcare |
| Edwards Lifesciences Corporation |
| Medtronic |
| Drägerwerk AG & Co. KGaA |
| Integra LifeSciences Corporation |
| Abbott |
| Teleflex Incorporated |
| Nihon Kohden Corporation |
| Philips N.V. |
| Others |
Supply & Pricing Matrix
European pressure transducer manufacturers in Germany and Switzerland anchor upstream supply for invasive intracranial monitoring systems, concentrating margin capture in catheter materials and biocompatible sensors while downstream device assemblers face procurement volatility. This supply concentration shifts pricing power toward component specialists and forces original equipment manufacturers to absorb input cost fluctuations or renegotiate hospital contracts.
Pricing Analysis
Configured-to-order multimodal platforms command substantial premiums over standard ICP monitoring configurations due to EEG integration and cloud analytics modules. The dominant pricing structure is a hybrid model combining capital equipment placement with per-patient-per-day algorithmic analysis subscriptions. Price differentiation rests on FDA breakthrough designation status and local service infrastructure density. Pricing pressure stems from hospital procurement consolidation around bundled monitoring subscriptions that compress standalone device margins. Community hospitals exhibit highest price sensitivity due to limited neuro-ICU case volumes, while military treatment facilities and academic medical centers prioritize capability over cost.
Supply Chain Analysis
Tariff exposure between United States and European Union jurisdictions dominates supply chain risk planning for catheter-based monitoring systems. Manufacturing concentrates in Germany, Switzerland, and Ireland for specialized pressure transducers, biocompatible polymers, and implantable electronics. Raw material dependencies include medical-grade silicone, platinum-iridium electrodes, and ceramic substrate materials. Single-source vulnerability in European pressure sensor foundries creates allocation risk during demand surges. Distribution runs through hospital procurement consortia and group purchasing organizations that consolidate neuro-ICU capital budgets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic analysis and remote specialist oversight subscriptions are expanding faster than hardware placement revenue, converting capital equipment vendors into recurring-revenue service platforms. This service-attach dynamic rewards vendors who control cloud-native data architectures spanning pre-hospital through ICU discharge.
For Market Incumbents: Insulate installed base positions through backward integration into European pressure transducer supply and exclusive cloud analytics partnerships with Epic and Cerner. Deepen catheter portfolio differentiation against emerging non-invasive monitoring substitutes. Prioritize MDR infrastructure investment to maintain EU market access as AI Act high-risk obligations take effect. For New Entrants and Emerging Players: Pursue brain-computer interface applications for locked-in syndrome communication as the most penetrable white-space segment, where FDA breakthrough designation accelerates commercialization timelines. Target private hospital neuro-ICU investments in Mumbai, Delhi, and Chennai with localized service infrastructure. Lead with algorithmic seizure detection software that layers atop existing EEG hardware rather than competing on capital equipment. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native monitoring platform specialists with demonstrated hospital system partnerships and recurring revenue traction. The five-to-ten-year viability window favors vendors who control full temporal data chains from ambulance to discharge. Watch for EU AI Act implementation as the inflection signal that separates MDR-compliant platform providers from regulatory laggards.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress commercialization cycles for intracranial pressure innovations. |
| Hospital System Partnership | Bundled subscription contracts with Texas and California medical centers lock multi-year platform commitments. |
| Software Companion Development | Real-time seizure detection algorithms differentiate monitoring ecosystems beyond hardware specifications. |
| CE Marking Pathway | MDR compliance for active implantable neurological devices preserves European market access. |
| Reimbursement Strategy | CPT code alignment for brain-computer interface applications unlocks payer coverage for locked-in patients. |
Research Methodology
A spread of perspectives from neurocritical care physicians, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions for demand modeling. Primary interviews combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation. Bottom-up equipment shipment analysis and top-down healthcare expenditure triangulation anchored market sizing.
Demand-supply-balance framing structured the analytical framework across the analysis window, with segmentation dimensions spanning monitoring intensity tier, care setting acuity, end-user specialty, and regional regulatory cluster. CAGRs derived from procedure volume growth trajectories and technology substitution curves. Forecast inputs incorporated trauma protocol standardization mandates and EU AI Act implementation timelines.
Sensitivities concentrate around EU MDR clinical evidence requirements and non-invasive monitoring substitution rates. Forecasts reflect documented assumptions on hospital procurement consolidation velocity and neurocritical care specialist availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Transcranial Doppler Market
Neurology
Brazil Neurology Devices Market
Neurology
AIDS Related Primary CNS Lymphoma Market
Neurology
Cerebral Aneurysm Management Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
Netherlands Neurology Devices Market
Neurology
United States Neurology Devices Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
India Neurology Devices Market
Neurology
Coma Diagnosis and Treatment Market
Neurology
Spain Neurology Devices Market
Neurology
Optic Neuritis Treatment Market
Neurology
Cluster Headache Syndrome Market
Neurology
US Optic Neuritis Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Frontotemporal Disorders Treatment Market