
 North America Antimicrobial Susceptibility Testing Market | 2026-2036
North America Antimicrobial Susceptibility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Antimicrobial Susceptibility Testing Market Analytics
Next-generation polymer substrates are restructuring reagent manufacturing economics in antimicrobial susceptibility testing. Thermo Fisher Scientific leverages its Fisher Scientific distribution arm to control channel access across hospital networks. BioMérieux SA anchors its position through specialized automated blood culture-to-AST workflow integration. Danaher Corporation sustains R&D intensity across its Beckman Coulter and Cepheid operating units.
Antimicrobial susceptibility testing measures pathogen response to antimicrobial agents through quantitative minimum inhibitory concentration determination and qualitative resistance phenotype classification, employing calibrated antibiotic-impregnated disks, gradient strips, or broth microdilution panels to guide therapeutic selection. Automated systems dominate capital expenditure budgets while broth dilution retains reference-laboratory anchoring for definitive resistance mechanism confirmation. Reagent and consumable sales generate recurring revenue streams that software-enabled instrument platforms increasingly capture through locked consumable protocols.
FDA breakpoint updates and CLSI M100 standards directly shape product validation requirements and market access timelines for new AST panels. Health Canada and the CDC's Antibiotic Resistance Threats Report collectively elevate institutional procurement standards for rapid phenotypic testing. Stakeholders must monitor reimbursement alignment between laboratory procedure codes and instrument platform capabilities.
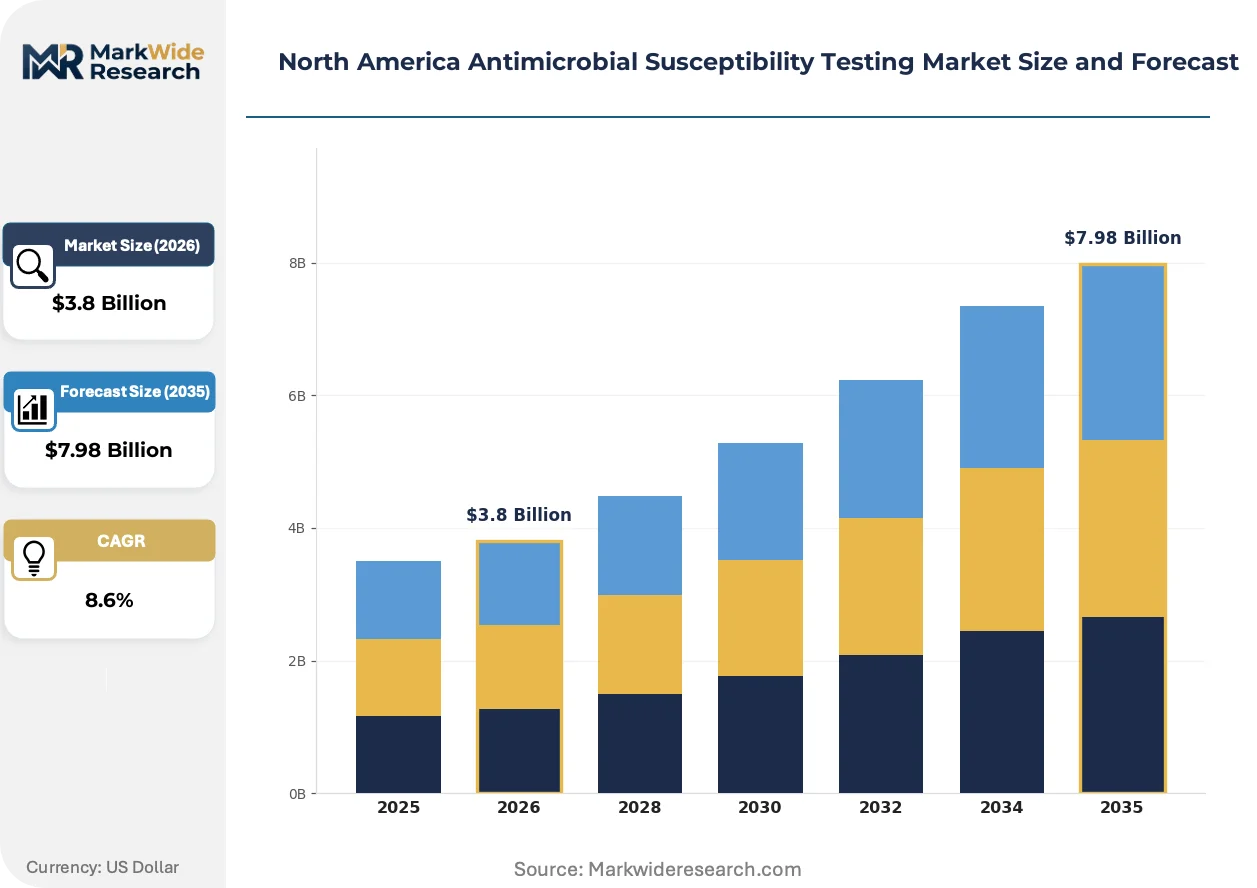
Market Dynamics
Breakpoint harmonization between FDA and CLSI is compressing validation timelines for new AST panels while forcing manufacturers to synchronize product roadmaps with evolving resistance definitions.
Growth Catalysts
- FDA breakpoint updates:Accelerated standardization of susceptibility testing protocols drives instrument replacement cycles in hospital laboratories across the northeastern United States.
- Multidrug-resistant pathogen surveillance:CDC Antibiotic Resistance Threats Report elevates institutional procurement standards for rapid phenotypic testing in academic medical centers.
- Automated blood culture-to-AST workflow integration:Specialized platform convergence reduces turnaround time from positive culture to susceptibility result.
Market Restraints
- Capital intensity of automated systems:Broth microdilution panels and gradient strip methods require substantial upfront instrument expenditure that constrains mid-tier hospital adoption.
- Locked consumable protocols:Software-enabled instrument platforms capture recurring revenue through proprietary reagent formats that limit third-party supplier access.
- Reference laboratory anchoring:Definitive resistance mechanism confirmation remains concentrated in specialized facilities with extended turnaround times.
Strategic Opportunities
- Underpenetrated outpatient settings:Urgent care clinics and physician office laboratories in the southeastern United States lack automated AST capacity for point-of-care resistance screening.
- Next-generation polymer substrates:Novel reagent manufacturing economics enable cost reduction in disk and strip production for high-volume reference laboratories.
- Health Canada alignment with FDA breakpoints:Cross-border regulatory convergence creates unified product validation pathways for manufacturers serving both markets.
Industry Challenges
- Microbiology technologist shortage:Specialized training requirements for phenotypic interpretation limit laboratory staffing capacity in community hospital settings.
- Legacy system integration complexity:Hospital laboratory information systems require customized middleware development to connect new AST platforms with existing electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Antimicrobial Susceptibility Testing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Disk Diffusion, Automated Systems, E-Test, Broth Dilution End User: Hospitals, Diagnostics Laboratories, Research Institutions, Pharmaceutical Companies Product Type: Instruments, Reagents, Software, Consumables Application: Clinical Microbiology, Infection Control, Pharmaceutical Development, Epidemiological Studies |
| Companies Covered | Thermo Fisher Scientific Inc, Becton, Dickinson and Company, Danaher Corporation, Bio-Rad Laboratories Inc, BioMérieux SA, Merck & Co Inc, Bruker Corporation, Roche Diagnostics, Creative Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Antimicrobial Susceptibility Testing Market Evolving Landscape
Rapid phenotypic methods are compressing the traditional 24-48 hour susceptibility reporting window, reshaping therapeutic decision timelines and antimicrobial stewardship program design across acute care networks.
Matrix-assisted laser desorption ionization-time of flight mass spectrometry is overtaking biochemical identification as the front-end technology for AST workflows. Hospital laboratories in the northeastern United States are adopting MALDI-TOF platforms at accelerated replacement cycles. This technology is overtaking conventional methods by enabling same-day species identification that feeds directly into automated susceptibility testing algorithms.
CLSI M100 standards revisions now require annual panel updates for resistance mechanism coverage, forcing manufacturers to revalidate product configurations against evolving carbapenemase and extended-spectrum beta-lactamase definitions. Industrial consequence includes shortened product lifecycles and compressed R&D amortization periods. Automated system vendors serving the United States market are responding by modularizing instrument hardware to accommodate firmware-updatable detection protocols.
Consolidated procurement through integrated delivery networks is displacing standalone laboratory purchasing autonomy in the United States. Multi-hospital systems now centralize AST platform selection through capital committees that standardize across affiliated facilities. This concentration is most visible in the Midwest, where regional health systems negotiate enterprise-wide reagent contracts that lock in multi-year consumable commitments.
North America Antimicrobial Susceptibility Testing Market Segmentation
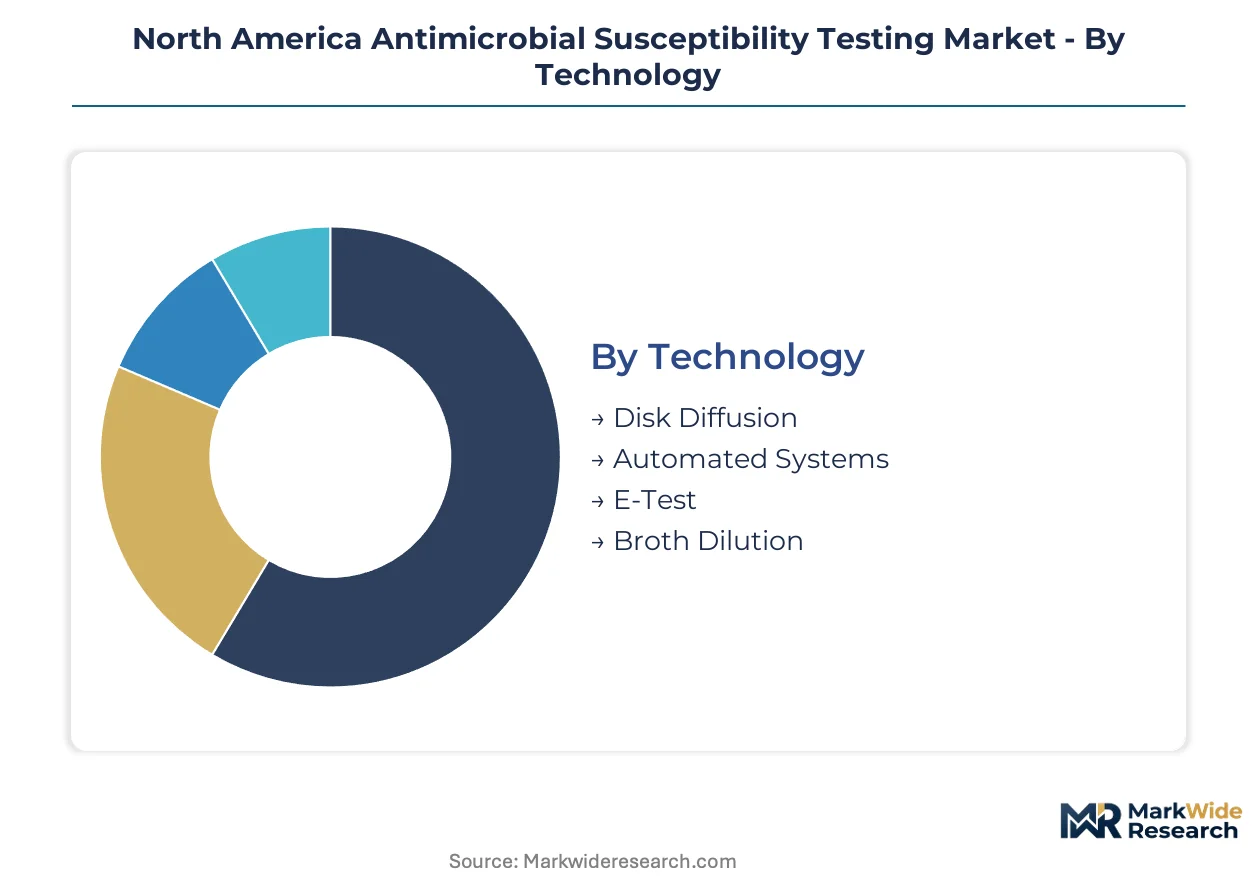
Technology choices in antimicrobial susceptibility testing directly determine capital allocation cycles and recurring revenue capture across hospital networks. Product configurations must align with FDA breakpoint updates and CLSI M100 validation requirements to maintain market access.
Technology:
Upgrade cycles accelerate where breakpoint harmonization forces instrument replacement to maintain compliance with evolving resistance definitions.
- Automated Systems:Platforms integrate blood culture-to-AST workflows with firmware-updatable detection protocols. Academic medical centers in the northeastern United States drive replacement demand as FDA breakpoint updates compress validation timelines for new panels.
- Broth Dilution:Reference laboratories anchor definitive resistance mechanism confirmation through quantitative minimum inhibitory concentration determination. Extended turnaround times constrain adoption outside specialized facilities despite superior accuracy for novel resistance patterns.
- Disk Diffusion:Calibrated antibiotic-impregnated disks serve high-volume screening with lower capital requirements.
- E-Test:Gradient strips provide quantitative MIC determination for organisms with unpredictable growth characteristics.
Automated systems sit at the top of the volume ranking, with broth dilution climbing the fastest among reference laboratories expanding resistance mechanism confirmation capacity.
End User:
Procurement concentration through integrated delivery networks reshapes purchasing autonomy across multi-hospital systems.
- Hospitals:Hospital laboratories dominate capital expenditure budgets for AST platforms, with microbiology technologist shortages constraining staffing capacity in community settings. The CDC Antibiotic Resistance Threats Report elevates procurement standards for rapid phenotypic testing in acute care networks.
- Diagnostics Laboratories:Reference laboratories anchor definitive resistance mechanism confirmation with extended turnaround times. MALDI-TOF mass spectrometry adoption accelerates species identification throughput before AST workflow initiation.
- Research Institutions:Academic medical centers drive instrument replacement cycles through specialized automated workflow integration.
- Pharmaceutical Companies:Drug development pipelines require resistance surveillance for antimicrobial stewardship program design.
Hospitals capture the largest share of instrument placements, with diagnostics laboratories expanding most quickly as regional health systems centralize confirmatory testing.
Product Type:
Margin structures diverge sharply between locked consumable protocols and modular hardware platforms.
- Reagents:Next-generation polymer substrates restructure manufacturing economics for disk and strip production. Recurring revenue streams concentrate through proprietary formats that limit third-party supplier access across hospital networks.
- Instruments:Capital intensity constrains mid-tier hospital adoption, with modular hardware designs accommodating firmware-updatable detection protocols. Beckman Coulter and Cepheid operating units sustain R&D intensity across Danaher Corporation's portfolio.
- Consumables:Broth microdilution panels and gradient strips generate recurring revenue through standardized formats.
- Software:Middleware development connects AST platforms with existing electronic health records in hospital laboratory information systems.
Reagents command the steepest expansion trajectory as locked consumable protocols capture recurring revenue, with instruments facing replacement pressure from breakpoint harmonization requirements.
Application:
Turnaround time compression reshapes therapeutic decision timelines across acute care networks.
- Clinical Microbiology:Rapid phenotypic methods compress the traditional susceptibility reporting window to guide therapeutic selection. MALDI-TOF platforms enable same-day species identification feeding directly into automated susceptibility testing algorithms.
- Infection Control:Multidrug-resistant pathogen surveillance demands point-of-care resistance screening capacity in urgent care clinics and physician office laboratories.
- Pharmaceutical Development:Antimicrobial stewardship program design requires resistance surveillance integration across drug development pipelines.
- Epidemiological Studies:Carbapenemase and extended-spectrum beta-lactamase definitions require annual panel updates for resistance mechanism coverage.
Clinical microbiology leads application volume, with infection control gaining share fastest as underpenetrated outpatient settings in the southeastern United States expand screening capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The northeastern United States anchors North American antimicrobial susceptibility testing demand through concentrated academic medical center clusters.
United States Northeast
Academic medical centers in Massachusetts and New York drive instrument replacement cycles for automated blood culture-to-AST platforms. FDA breakpoint updates accelerate standardization protocols across hospital laboratory networks. Boston's Longwood Medical Area concentrates specialized workflow integration deployments.
United States Southeast
Urgent care clinics and physician office laboratories lack automated AST capacity for point-of-care resistance screening. CDC Antibiotic Resistance Threats Report elevates procurement standards for rapid phenotypic testing. Atlanta's healthcare corridor expands multidrug-resistant pathogen surveillance infrastructure.
United States Midwest
Regional health systems centralize AST platform selection through capital committees standardizing across affiliated facilities. Integrated delivery networks negotiate enterprise-wide reagent contracts locking in multi-year consumable commitments. Chicago's hospital consortiums concentrate procurement decision-making authority.
Canada
Health Canada alignment with FDA breakpoints creates unified product validation pathways for manufacturers serving both markets. Reference laboratories anchor definitive resistance mechanism confirmation with extended turnaround times. Toronto's diagnostic hub expands MALDI-TOF mass spectrometry adoption for species identification throughput.
North America Antimicrobial Susceptibility Testing Market Competitive Landscape
Strategic partnerships dominate the current landscape as instrument manufacturers secure locked consumable protocols across hospital networks. The vendor base concentrates around automated system specialists and reference laboratory equipment providers. Two archetypes prevail: diversified life science conglomerates controlling distribution channels, and specialized diagnostic firms integrating blood culture-to-AST workflows. M&A activity and firmware-updatable hardware modularization represent the dominant competitive vectors.
Among diversified conglomerates, Thermo Fisher Scientific Inc and Danaher Corporation exemplify scale-driven channel control archetypes. Thermo Fisher leverages its Fisher Scientific distribution arm to govern hospital network access. Danaher sustains R&D intensity across operating units including Beckman Coulter and Cepheid. BioMérieux SA occupies the specialized integration tier, anchoring automated workflow convergence from positive culture to susceptibility result. These three entities represent distinct strategic positions without implying specific market share claims.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Becton, Dickinson and Company |
| Danaher Corporation |
| Bio-Rad Laboratories Inc |
| BioMérieux SA |
| Merck & Co Inc |
| Bruker Corporation |
| Roche Diagnostics |
| Creative Diagnostics |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in the United States Midwest anchor procurement concentration for antimicrobial susceptibility testing platforms, locking in multi-year consumable commitments that sustain premium pricing for automated system vendors. This buyer concentration enables firmware-updatable hardware suppliers to capture recurring revenue through proprietary reagent formats while constraining price competition from third-party disk and strip manufacturers.
Pricing Analysis
Input-cost pass-through from next-generation polymer substrates partially offsets margin compression in reagent manufacturing, though capital intensity of automated instruments limits price elasticity for mid-tier hospitals. Pricing stratifies across premium automated blood culture-to-AST platforms, standard broth microdilution panel systems, and economy disk diffusion methods, with FDA breakpoint update frequency serving as the primary tier separator. Price erosion runs through standard-tier instruments as breakpoint harmonization accelerates replacement cycles. Community hospitals exhibit highest price sensitivity due to microbiology technologist shortage constraints, while academic medical centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for antibiotic-impregnated disks and gradient strips mandate multi-supplier qualification across United States, Germany, and Japan manufacturing facilities. Raw material dependencies center on specialized polymer substrates, calibrated antibiotic matrices, and precision-manufactured detection substrates. Single-source vulnerability concentrates in firmware-updatable instrument platforms where locked consumable protocols tether hospitals to original equipment manufacturers. Distribution runs through Fisher Scientific's hospital network arm and specialized diagnostic distributors serving reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America antimicrobial susceptibility testing market represents a late-cycle quality story as FDA breakpoint updates and CLSI M100 annual panel revision requirements shift procurement criteria toward firmware-updatable detection protocols and rapid phenotypic testing accuracy.
For Market Incumbents: Acquire firmware-updatable instrument platform portfolios to consolidate position against emerging molecular diagnostic substitutes. Integrate backward into next-generation polymer substrate manufacturing to defend margin position from reagent cost compression. Lock in multi-year consumable contracts with integrated delivery networks before Health Canada-FDA breakpoint alignment expands competitive access. For New Entrants and Emerging Players: FDA breakpoint updates in the United States open a window for specialized rapid phenotypic testing platforms targeting underpenetrated urgent care clinics and physician office laboratories in the southeastern United States. Pursue white-space capture in point-of-care resistance screening through portable disk diffusion systems with lower capital requirements. Go-to-market through regional health system capital committees rather than standalone laboratory purchasing channels. For Investors and Strategic Acquirers: Diversified life science conglomerates are the most active acquirer in this space, seeking automated workflow integration capabilities. Long-term viability hinges on recurring revenue capture through locked consumable protocols rather than instrument placement volume. Target acquisition archetypes include specialized blood culture-to-AST workflow integrators and next-generation polymer substrate developers. Watch for Health Canada alignment with FDA breakpoints as inflection signal for cross-border market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Updatable Hardware Modularization | Beckman Coulter and Cepheid operating units sustain R&D intensity to compress validation timelines for evolving resistance definitions. |
| Locked Consumable Protocol Expansion | Proprietary reagent formats limit third-party supplier access and capture recurring revenue across hospital network contracts. |
| Reference Laboratory Partnership | Definitive resistance mechanism confirmation capacity anchors high-margin broth microdilution panel demand in specialized facilities. |
| Health Canada Regulatory Alignment | Cross-border breakpoint convergence creates unified product validation pathways for manufacturers serving both United States and Canadian markets. |
| MALDI-TOF Platform Integration | Mass spectrometry species identification throughput accelerates same-day AST workflow initiation in northeastern academic medical centers. |
Research Methodology
Direct dialogue with hospital laboratory directors, microbiology technologists, GPO contracts managers, and biomedical engineers grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) filings, CLSI M100 standards documentation, hospital procurement databases, and CDC Antibiotic Resistance Threats Report series. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down market sizing derived from capital expenditure disclosures across integrated delivery networks.
Segment-level outputs across technology, end user, product type, and application dimensions were generated through the projection horizon. CAGRs were derived from instrument replacement cycle analysis, breakpoint update frequency modeling, and recurring revenue capture rates in locked consumable protocols. Industry-specific inputs included FDA breakpoint harmonization timelines, Health Canada regulatory alignment probability, and MALDI-TOF platform adoption curves in academic medical center clusters.
Revisions become necessary when FDA breakpoint update schedules accelerate beyond modeled timelines, Health Canada alignment delays materialize, or molecular diagnostic substitutes achieve equivalent turnaround times for resistance mechanism confirmation. Deviation in integrated delivery network procurement concentration or microbiology technologist shortage severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
At-Home Celiac Testing Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Global Ovulation Test Market
Testing Services
Global Newborn Screening Market
Testing Services
Global Endocrine Testing Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Global Sterility Testing Market
Testing Services
Test Strips Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Urodynamic Testing Market
Testing Services
At-Home Testing Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Specific Protein Testing Market
Testing Services
Asia-Pacific Viral Clearance Market