
 Next Generation Wound Closure Device Market | 2026-2036
Next Generation Wound Closure Device Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Wound Closure Device Market Foresight
Premium antimicrobial-coated suture tiers is unwinding commoditization pressures across the wound closure landscape. Ethicon leverages vertical integration from fiber extrusion to sterile packaging to sustain margin control in advanced absorbable segments. Medtronic anchors North American hospital contracting through ultrasonic closure platforms that reduce operative time. Baxter differentiates via hemostatic adjuncts bundled with staple delivery systems.
Next generation wound closure devices encompass sutures, adhesives, clips, and staples engineered with smart materials or biodegradable polymers, typically featuring tensile strength retention profiles matched to tissue healing timelines of seven to twenty-one days, designed to minimize foreign body reaction while eliminating removal procedures. The primary purpose spans operative site approximation across trauma, surgical, cosmetic, and chronic wound applications where infection prevention and scar optimization drive clinical selection. Sutures retain the largest revenue footprint due to universal surgical applicability, though adhesives represent the fastest-expanding margin pool as outpatient procedural volumes shift toward minimally invasive techniques. Biodegradable polymer technology is displacing traditional synthetic platforms in pediatric and cosmetic segments where suture removal trauma conflicts with patient compliance requirements.
FDA 510(k) pathways and EU MDR conformity assessments shape product development timelines, with the former accelerating market entry for laser-assisted closure devices and the latter imposing clinical evidence requirements that favor established players with post-market surveillance infrastructure. ISO 10993 biocompatibility testing standards filter out undercapitalized entrants attempting polymer formulation innovations without validated toxicology profiles. Stakeholders must weigh regulatory capital intensity against the contracting leverage of integrated delivery networks consolidating procurement across hospital and ambulatory surgical center footprints.
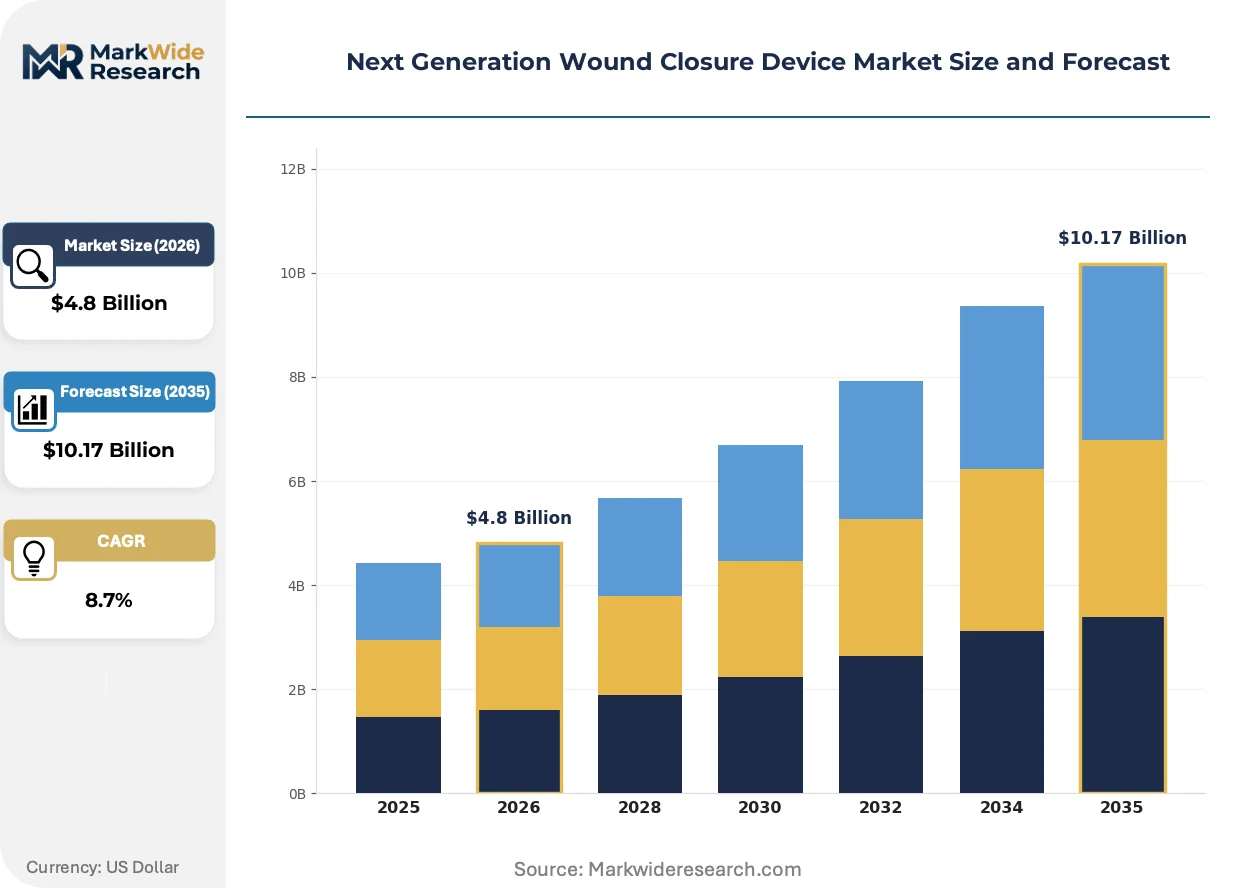
Market Dynamics
Biodegradable polymer platforms are decomposing traditional synthetic suture market positions as FDA 510(k) review compression accelerates time-to-market for absorbable alternatives. Hospital procurement consortiums in Germany and ambulatory surgical center networks across the United States are consolidating vendor selection around smart material integration capabilities.
Growth Catalysts
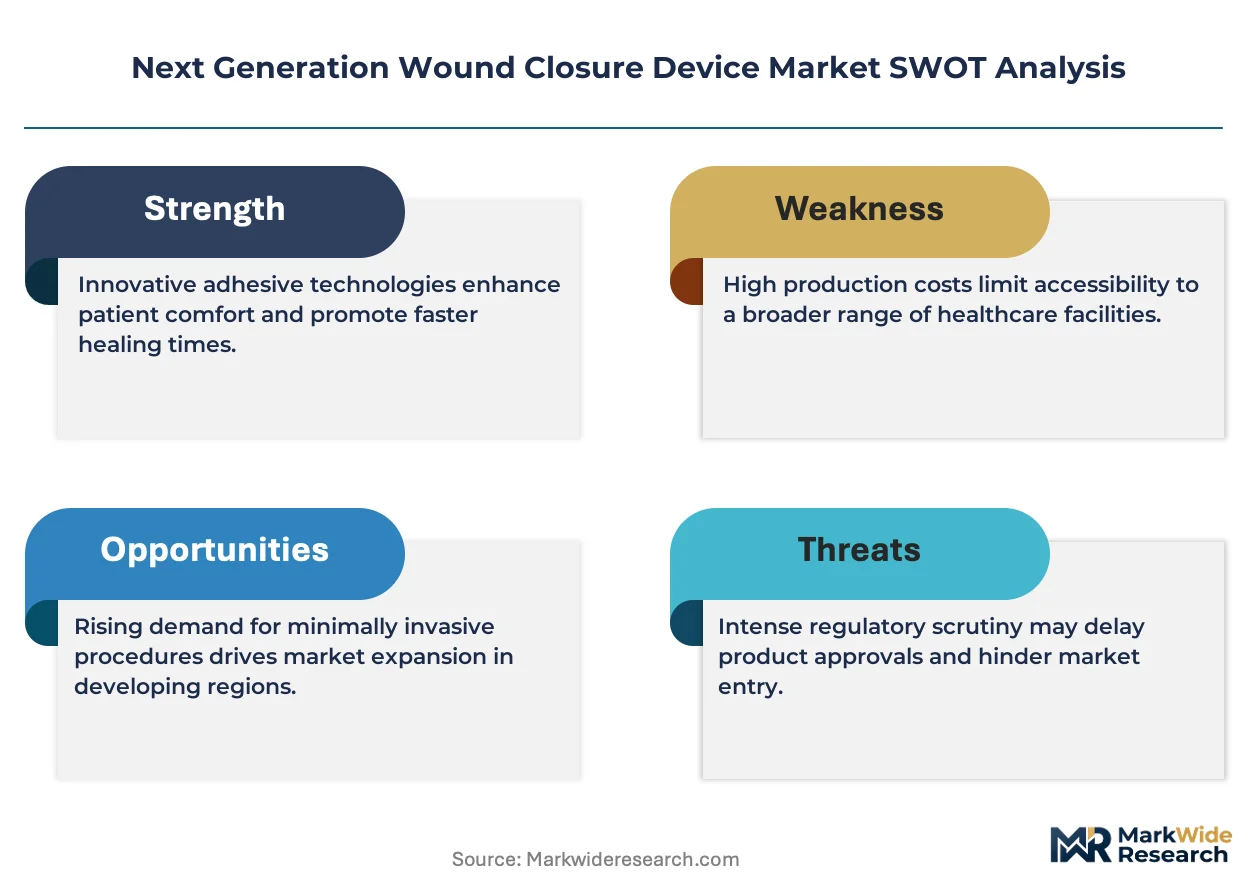
- FDA Class II review pathway compression:The updated 510(k) framework for laser-assisted closure devices reduces regulatory lag, enabling faster commercialization of biodegradable platforms targeting pediatric and cosmetic segments.
- Ambulatory surgical center expansion:Outpatient procedural volume concentration in United States and German networks creates pull for minimally invasive closure systems that eliminate follow-up removal visits.
- Antimicrobial coating chemistry:Silver-ion and triclosan-impregnated suture tiers are unwinding commoditization pressures across premium hospital procurement tiers.
Market Restraints
- Polymer raw material concentration:Caprolactone and glycolide monomer supply concentrates among three specialty chemical producers, exposing device manufacturers to input cost volatility.
- EU MDR clinical evidence requirements:The Medical Device Regulation imposes post-market surveillance infrastructure burdens that favor established players with validated toxicology databases.
- Tissue adhesive substitution threat:Cyanoacrylate formulations for superficial lacerations are capturing low-acuity emergency department volume previously served by synthetic non-absorbable sutures.
Strategic Opportunities
- India surgical infrastructure buildout:Government hospital modernization programs under the Ayushman Bharat scheme create entry points for absorbable polymer platforms in tier-2 and tier-3 cities.
- Ultrasonic closure-convergent robotics:Integration of Medtronic's energy-based vessel sealing algorithms with laparoscopic stapling systems opens robotic surgery compatibility.
- Japan PMDA fast-track designation:The Sakigake framework for breakthrough medical devices offers accelerated approval for smart sutures with integrated tensile strength sensors.
Industry Challenges
- ISO 10993 biocompatibility certification timeline:Polymer formulation innovations require 18-24 month toxicology validation cycles that strain R&D capitalization for mid-tier entrants.
- Legacy sterilization infrastructure retrofit:Ethylene oxide and gamma sterilization facilities require capital-intensive revalidation when transitioning to novel biodegradable packaging formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Wound Closure Device Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Adhesives, Clips, Staples Technology: Smart Materials, Biodegradable Polymers, Laser-assisted, Ultrasonic End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Care Application: Trauma, Surgical, Cosmetic, Chronic Wounds |
| Companies Covered | Ethicon (Johnson & Johnson Services, Inc.), Medtronic, 3M, Baxter, Smith+Nephew, Stryker, Corza Medical, Solventum, Riverpoint Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Wound Closure Device Market Shifts & Advancements
Smart material integration and energy-based closure modalities are fragmenting traditional suture-centric procurement patterns. Device manufacturers must now compete across polymer chemistry, sensor embedding, and ultrasonic energy delivery simultaneously.
Shape-memory alloy sutures incorporating nitinol wire cores are decomposing conventional tension-control limitations in orthopedic and cardiovascular applications. German hospital consortiums are piloting these systems in trauma reconstruction cases where dynamic wound approximation exceeds static suture performance. The technology is decomposing the historical trade-off between immediate tensile strength and long-term biocompatibility.
REACH regulation amendments on microplastic release are compelling European manufacturers to reformulate synthetic absorbable sutures with accelerated hydrolysis profiles. The ECHA restriction proposal targets polymer fragments below 5mm that persist in tissue beyond resorption timelines. German and French surgical device distributors are now requiring biodegradation certification documentation for all new polymer platform introductions.
Integrated delivery networks in the United States are unbundling closure device procurement from staple and suture tray contracts previously locked to single-source vendors. Hospital purchasing coalitions in Texas and California are conducting parallel price negotiations for adhesives, clips, and energy-based systems. This disintermediation is most visible in ambulatory surgical centers where procedure-specific kitting replaces standardized operating room supply agreements.
Next Generation Wound Closure Device Market Segmentation
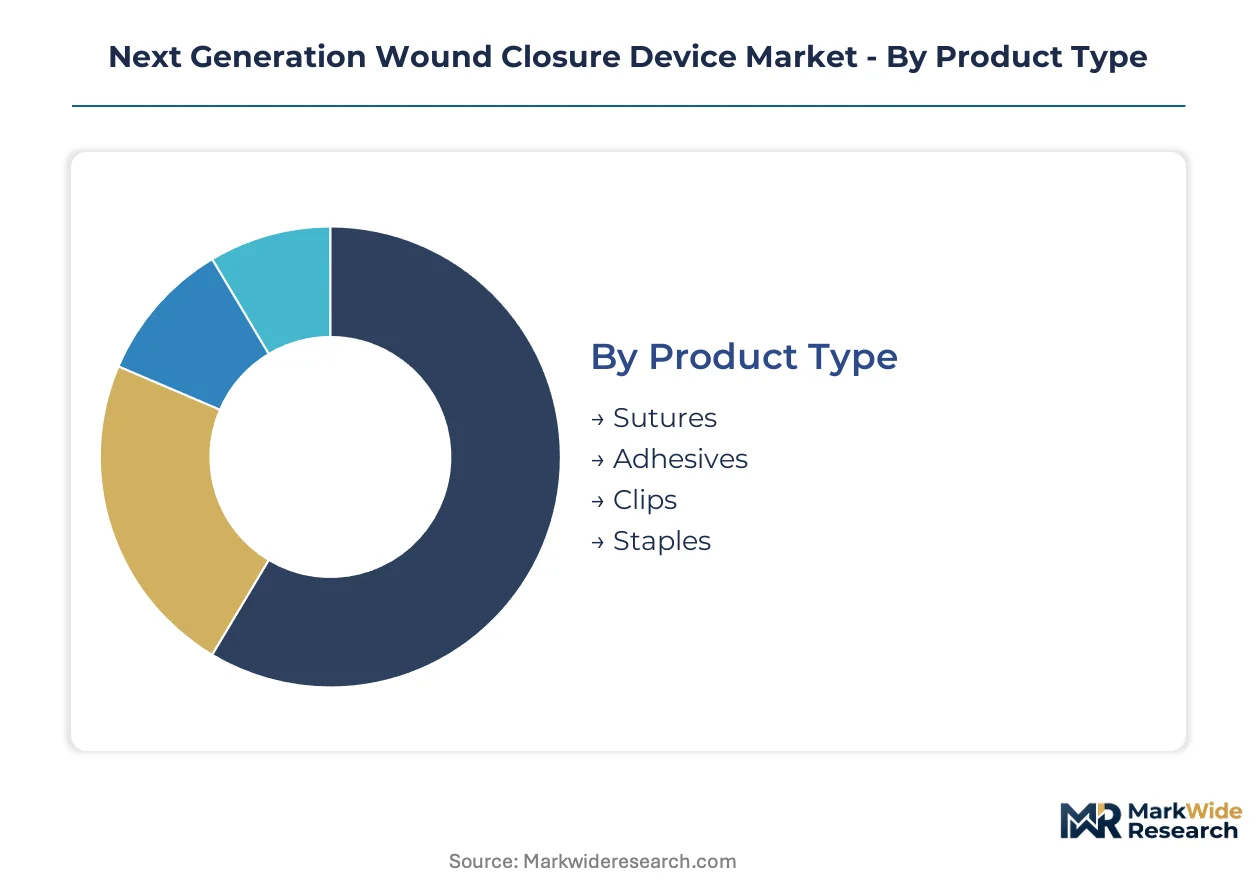
Segmentation in wound closure devices tracks how procurement authority shifts between hospital systems and outpatient networks. Technology choices here determine whether manufacturers compete on polymer chemistry, energy delivery, or smart material integration.
Product Type:
Margin pools concentrate in absorbable platforms where material science differentiation sustains pricing power against commodity synthetics.
- Sutures:Absorbable and non-absorbable fiber platforms dominate operative site approximation across open and minimally invasive procedures. Hospital procurement consortiums in Germany prioritize sutures with integrated antimicrobial coatings and smart tensile indicators. The dominant share belongs to Sutures, while Adhesives is closing the gap fastest.
- Adhesives:Cyanoacrylate and protein-based tissue bonding agents eliminate suture removal visits in superficial laceration and cosmetic closure applications. Ambulatory surgical centers in the United States are expanding adhesive formulary inclusion for outpatient dermatologic and ophthalmic procedures.
- Clips:Metallic and absorbable polymer clips provide rapid vessel and tissue approximation in laparoscopic and robotic-assisted surgeries.
- Staples:Stainless steel and titanium staple lines secure gastrointestinal and thoracic anastomoses where mechanical strength exceeds suture performance.
Sutures retain the largest revenue footprint, though adhesive volumes are climbing fastest as outpatient procedural mix shifts.
Technology:
Technology selection determines regulatory pathway complexity and time-to-market velocity for new platform introductions.
- Smart Materials:Sensor-embedded sutures with real-time tensile strength monitoring and pH-based infection indicators. Japan's PMDA Sakigake fast-track designation is accelerating approval timelines for these breakthrough devices.
- Biodegradable Polymers:Polyglycolic acid, polylactic acid, and polycaprolactone formulations hydrolyze within tissue healing windows. FDA 510(k) pathway compression is reducing commercialization lag for pediatric and cosmetic segment entrants.
- Laser-assisted:Photothermal tissue welding systems for microvascular and neural approximation.
- Ultrasonic:Energy-based vessel sealing and tissue coaptation platforms integrated with laparoscopic stapling systems.
Biodegradable Polymers command the dominant technology investment share, with Smart Materials gaining regulatory momentum fastest.
End User:
End user structure tracks the decentralization of surgical services from inpatient towers to outpatient facilities and home settings.
- Hospitals:Integrated delivery networks consolidate procurement across cardiac, orthopedic, and general surgery service lines. Texas and California purchasing coalitions are unbundling closure device contracts from traditional single-source vendor agreements.
- Ambulatory Surgical Centers:Freestanding outpatient facilities performing same-day procedures drive demand for elimination of follow-up removal visits. United States network expansion is concentrating volume in ophthalmic, orthopedic, and cosmetic applications.
- Clinics:Office-based procedure rooms in dermatology and emergency medicine settings.
- Home Care:Self-application adhesive platforms for chronic wound management and post-discharge incision monitoring.
Hospitals retain the dominant procurement volume, though Ambulatory Surgical Centers are expanding their share most aggressively.
Application:
Application segmentation reveals how reimbursement and outcome requirements reshape device selection across acute and chronic care pathways.
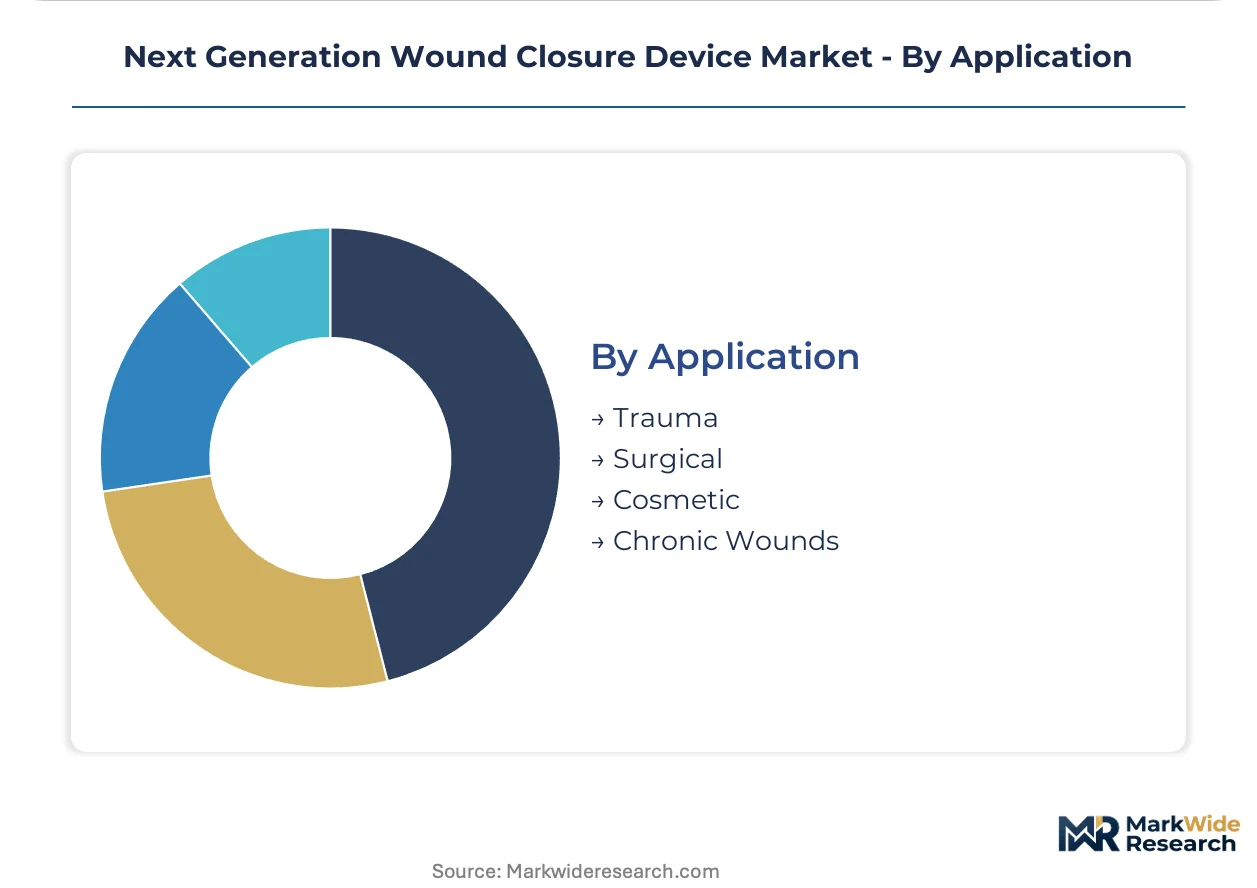
- Trauma:Emergency department and field stabilization closures requiring immediate tensile strength and infection resistance. Shape-memory alloy sutures with nitinol cores are decomposing static tension limitations in German trauma reconstruction pilots.
- Surgical:Planned operative procedures across general, cardiac, orthopedic, and gynecologic specialties. Antimicrobial-coated tiers are unwinding commoditization pressures in premium hospital procurement brackets.
- Cosmetic:Scar-minimizing closures in plastic and dermatologic surgery where patient compliance conflicts with suture removal requirements.
- Chronic Wounds:Pressure ulcer, diabetic foot, and venous stasis management in long-term care settings.
Surgical applications dominate procedure volume, while Cosmetic segments are expanding most quickly on outpatient procedural shift and patient compliance demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital procurement coalitions exhibit the lowest price elasticity, prioritizing smart material integration and antimicrobial coatings over cost minimization. Indian tier-2 city expansion shows the highest elasticity, where government tenders drive absorbable polymer adoption based on unit economics. German consortiums occupy the middle ground, balancing biodegradation certification requirements with total cost-of-ownership frameworks.
United States
Ambulatory surgical center networks in Texas and California are unbundling closure device contracts from traditional single-source vendor agreements. FDA's updated 510(k) Class II review pathways compress regulatory lag for laser-assisted and biodegradable platforms. The Dallas-Fort Worth metroplex anchors procurement concentration for ultrasonic closure systems integrated with robotic surgery compatibility.
Germany
Hospital procurement consortiums prioritize suture technologies with smart material integration and REACH-compliant biodegradation profiles. ECHA restrictions on microplastic release below 5mm accelerate hydrolysis profile reformulation requirements. The Baden-Württemberg cluster around Tübingen and Stuttgart pilots shape-memory alloy sutures with nitinol cores for trauma reconstruction applications.
Japan
PMDA's Sakigake fast-track designation for breakthrough medical devices accelerates approval timelines for sensor-embedded sutures with real-time tensile monitoring. METI funding for surgical robotics integration creates demand for ultrasonic closure-convergent platforms. The Kansai region surrounding Osaka anchors manufacturing concentration for smart material sutures targeting domestic and export markets.
India
Ayushman Bharat government hospital modernization programs create entry points for absorbable polymer platforms in tier-2 and tier-3 cities. CDSCO regulatory harmonization with ISO 10993 biocompatibility standards streamlines import substitution pathways. The Maharashtra-Gujarat industrial corridor concentrates contract manufacturing for biodegradable sutures serving price-sensitive public health procurement.
China
NMPA medical device innovation fast-track channels accelerate domestic smart suture approvals while import substitution policies favor local biodegradable polymer production. Dual carbon goals drive reformulation away from persistent synthetic platforms toward accelerated hydrolysis profiles. The Yangtze River Delta cluster around Shanghai and Suzhou anchors R&D concentration for laser-assisted closure device commercialization.
Next Generation Wound Closure Device Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure rather than consolidated dominance. Vertically integrated multinational conglomerates with captive fiber extrusion capabilities anchor premium antimicrobial-coated and smart material segments. Mid-scale polymer specialists compete on biodegradable platform customization for regional procurement specifications. Strategic moves concentrate on backward integration into caprolactone and glycolide monomer supply, alongside sterile packaging infrastructure revalidation for novel biodegradable formats.
Within the integrated multinational tier, Ethicon and Medtronic exemplify archetypes combining upstream polymer chemistry control with hospital contracting leverage. Baxter occupies a distinct position bundling hemostatic adjuncts with staple delivery systems. These three entities represent the dominant competitive anchors against which mid-tier biodegradable specialists and regional contract manufacturers position their portfolio differentiation.
| Leading Market Players |
|---|
| Ethicon (Johnson & Johnson Services, Inc.) |
| Medtronic |
| 3M |
| Baxter |
| Smith+Nephew |
| Stryker |
| Corza Medical |
| Solventum |
| Riverpoint Medical |
| Others |
Supply & Pricing Matrix
Scale economies in sterile packaging infrastructure anchor price floors for biodegradable polymer platforms, concentrating margin control among manufacturers with captive extrusion-to-sterilization footprints. Hospital procurement consortiums in Germany and ambulatory surgical center networks in the United States leverage this concentration to negotiate tiered access based on volume commitment and smart material integration capabilities.
Pricing Analysis
EU MDR clinical evidence requirements dictate the pricing tier structure across European hospital procurement, separating premium antimicrobial-coated sutures with validated post-market surveillance databases from standard absorbable tiers lacking comprehensive toxicology profiles. Price differentiation rests on ISO 10993 biocompatibility certification grade and vertical integration depth into caprolactone monomer supply. Cost compression in standard synthetic segments is intensifying because cyanoacrylate adhesives capture superficial laceration volume. Ambulatory surgical centers in the United States exhibit the highest price sensitivity, while German hospital consortiums prioritize biodegradation certification over unit cost.
Supply Chain Analysis
Strategic stockpiling of glycolide and caprolactone monomers dominates inventory strategy among device manufacturers hedging against specialty chemical supply volatility. Raw material concentration in Germany, the United States, and Japan shapes polymer platform availability, with downstream distribution running through hospital group purchasing organizations and ambulatory surgical center networks. Single-source vulnerability in ethylene oxide sterilization infrastructure poses structural risk as facilities face capital-intensive revalidation cycles for novel biodegradable packaging formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated delivery network consolidation across Texas and California has shifted procurement leverage toward buyers capable of unbundling closure device contracts from traditional single-source vendor agreements.
For Market Incumbents: Secure backward integration into caprolactone and glycolide monomer supply to insulate margin structures from specialty chemical input volatility. Anchor hospital contracting through ultrasonic closure platform compatibility with robotic surgery systems, defending against biodegradable polymer specialists targeting pediatric and cosmetic segments with FDA 510(k) pathway compression advantages. For New Entrants and Emerging Players: Post-discharge incision monitoring and self-application adhesive platforms represent service-layer gaps where incumbents under-serve chronic wound management pathways. Target tier-2 and tier-3 Indian cities under Ayushman Bharat modernization programs, deploying absorbable polymer platforms through government tender structures with CDSCO harmonization as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biodegradable polymer specialists with validated ISO 10993 toxicology databases and sterile packaging infrastructure revalidation capabilities. Long-term viability hinges on regulatory capital intensity advantages across EU MDR and FDA 510(k) pathways. The signal to watch is Japan PMDA Sakigake fast-track designation velocity for sensor-embedded sutures with real-time tensile monitoring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive caprolactone production insulates margin structures from specialty chemical price volatility in Germany and the United States. |
| Hospital System Partnership | Ultrasonic closure platform integration with robotic surgery compatibility anchors contracting leverage in Texas and California purchasing coalitions. |
| FDA 510(k) Submission | Class II review pathway compression accelerates commercialization timelines for biodegradable platforms targeting pediatric and cosmetic segments. |
| CE Marking Pathway | EU MDR conformity assessment completion enables access to German hospital procurement consortiums prioritizing REACH-compliant biodegradation certification. |
| Software Companion Development | Sensor-embedded sutures with real-time tensile strength monitoring align with Japan PMDA Sakigake fast-track designation criteria. |
Research Methodology
A spread of perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement contract records, and ISO 10993 biocompatibility certification registries. Bottom-up volume modeling across product type, technology, and end user segments triangulated against top-down market sizing from trade flow and customs data.
Segmentation dimensions modeled include product type, technology platform, end user facility type, and application across trauma, surgical, cosmetic, and chronic wound pathways over the projection horizon. CAGRs derive from procedure volume elasticity analysis, technology substitution rate modeling, and procurement pattern shifts in ambulatory surgical center networks. Forecast inputs incorporate biodegradable polymer hydrolysis profile adoption curves and antimicrobial coating chemistry penetration rates.
Forecasts assume regulatory continuity in FDA 510(k) Class II review pathways and EU MDR post-market surveillance frameworks; material policy shifts would require re-modeling. Revision becomes warranted when laser-assisted closure device approval velocity or REACH microplastic restriction enforcement intensity crosses thresholds altering competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Vascular Dressings Market
Wound Care
Biopatches Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Advanced Wound Management Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
North America Advanced Wound Care Market
Wound Care
Wound Healing Supplement Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Wound Drainage Devices Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
France Wound Care Market
Wound Care
Liquid Bandages Market