
 Active Humidifier Devices Market | 2026-2036
Active Humidifier Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Active Humidifier Devices Market Outlook
China is narrowing its reliance on imported active humidifier components through expanded domestic manufacturing zones in Guangdong and Jiangsu provinces. Honeywell International Inc. leverages its building automation ecosystem to bundle humidification with HVAC controls in commercial installations. ResMed anchors its position in clinical-grade devices through FDA-cleared platforms for sleep apnea therapy settings. Fisher & Paykel Healthcare differentiates via integrated humidification circuits designed for neonatal intensive care applications.
Active humidifier devices are electromechanical systems that add moisture to air streams through thermal evaporation, ultrasonic piezoelectric vibration, or impeller-driven aerosolization, typically maintaining relative humidity between 30% and 60% in controlled environments. These devices serve critical functions in healthcare respiratory therapy, semiconductor cleanrooms, and precision manufacturing where static control and material stability depend on tight humidity bands. Ultrasonic technology commands the premium tier due to silent operation and energy efficiency in residential and clinical deployments. Healthcare end users represent the fastest-expanding demand pool as hospitals prioritize infection control and patient comfort protocols. Steam vaporizers retain share in industrial segments where mineral-free output and rapid moisture loading justify higher energy consumption.
The FDA maintains stringent biocompatibility and electrical safety standards for humidifiers marketed as medical devices, while the EPA regulates antimicrobial claims and ozone emission thresholds for consumer units. ISO 80601-2-74 establishes international performance benchmarks for respiratory humidifiers, creating compliance costs that favor scaled manufacturers with dedicated regulatory affairs teams. Stakeholders must weigh the pace of hospital capital expenditure cycles against the shift toward home-based respiratory care when allocating product development resources.
Market Dynamics
Hospital capital expenditure cycles are compressing as healthcare systems prioritize infection control infrastructure, while semiconductor fabs in Taiwan and South Korea demand sub-5% relative humidity variance for advanced node production. This dual-track demand pull is fragmenting manufacturer R&D allocation between clinical-grade precision and industrial-scale throughput.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance timelines for humidifiers with predicate device claims accelerate hospital procurement decisions in the United States.
- Neonatal intensive care expansion:Rising NICU bed counts across tertiary hospitals drive demand for integrated heated-wire breathing circuits with precise temperature control.
- Ultrasonic transducer miniaturization:Piezoelectric element advances enable portable device formats for home respiratory therapy applications.
Market Restraints
- Piezoelectric ceramic supply concentration:Rare-earth element processing for high-frequency transducers clusters in Jiangxi province, creating single-source vulnerability.
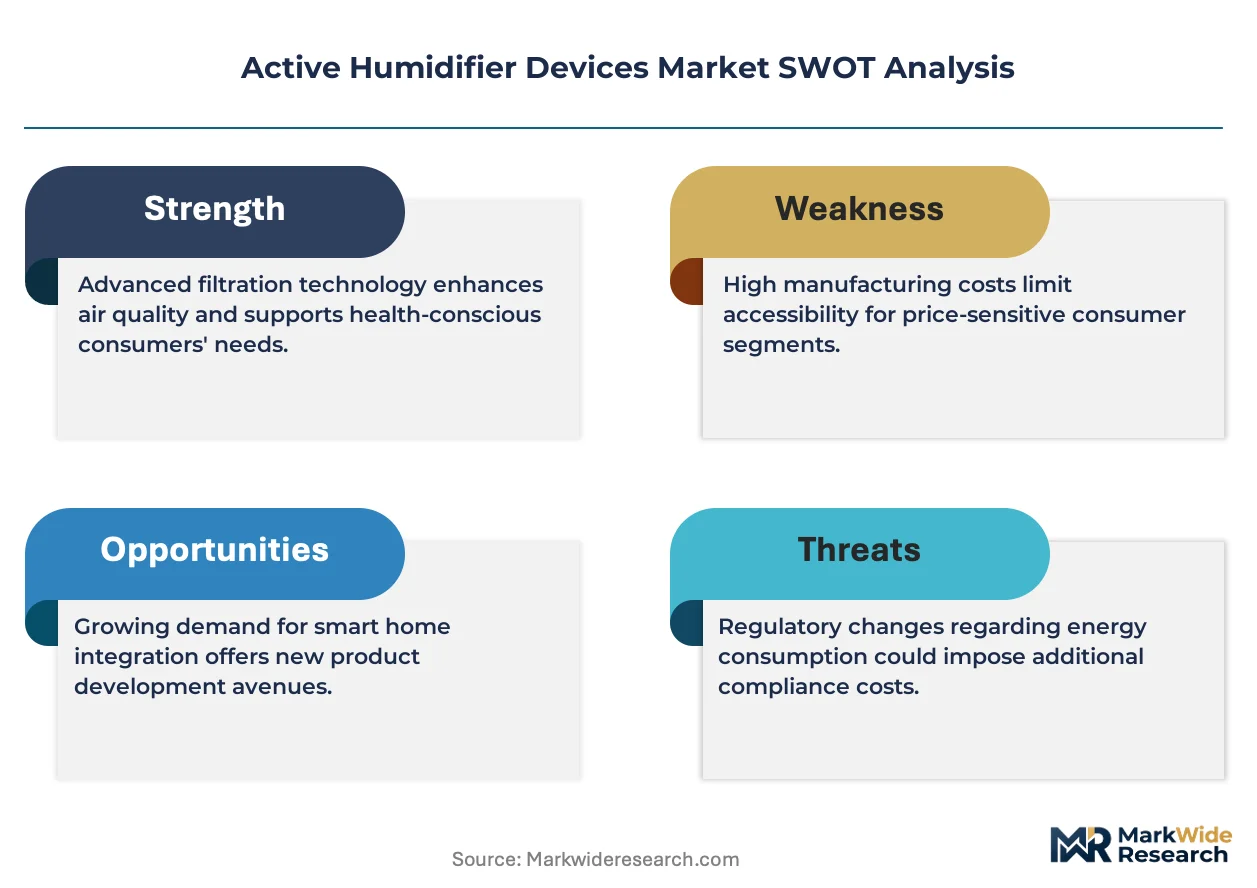
- ISO 80601-2-74 compliance costs:Third-party testing for respiratory humidifier electrical safety imposes six-figure certification burdens on smaller manufacturers.
- Passive humidifier substitution:Heat-and-moisture exchangers retain cost advantage in short-duration anesthesia settings, limiting active device penetration.
Strategic Opportunities
- India PLI scheme for medical devices:Production-linked incentives for domestic manufacturing of respiratory equipment reduce import dependence for hospital chains.
- Home-based respiratory care expansion:Sleep apnea patient migration from clinical to residential settings creates demand for whisper-quiet ultrasonic platforms.
- CE marking MDR transition:Stricter European medical device regulation creates first-mover advantage for manufacturers with established notified body relationships.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face 14-18 month queue times at accredited laboratories.
- Legacy HVAC integration complexity:Building management system protocol fragmentation forces custom middleware development for commercial installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Humidifier Devices Market |
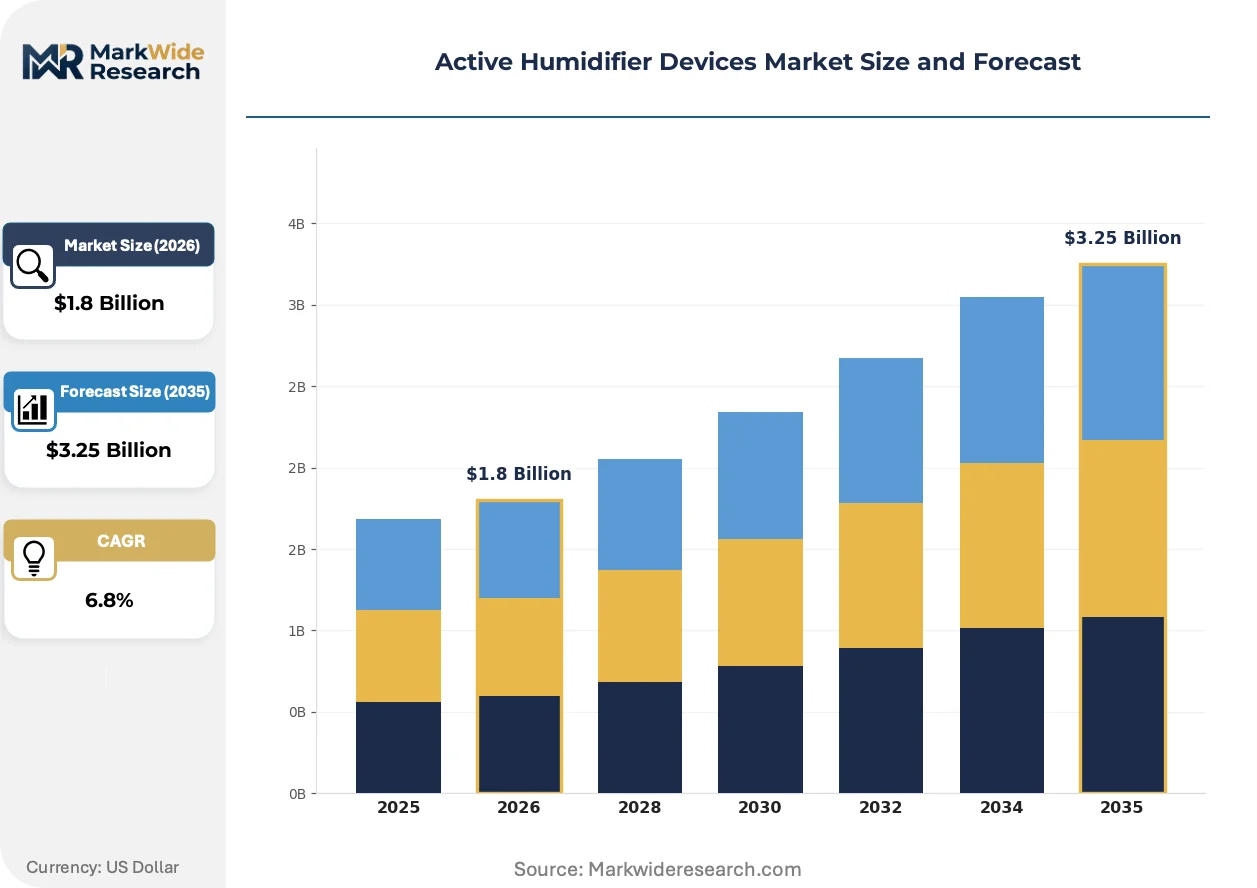
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Evaporative, Steam Vaporizers, Ultrasonic, Impeller Technology: Warm Mist, Cool Mist, Hybrid, Ionic End User: Residential, Commercial, Industrial, Healthcare Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Honeywell International Inc., Dyson Ltd., BONECO AG, Aprilaire, Philips Respironics, ResMed, Fisher & Paykel Healthcare, Vapotherm, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Humidifier Devices Market Strategic Shifts
Electromechanical humidification systems are converging with digital control architectures and predictive maintenance platforms, compressing the traditional separation between hardware OEMs and software service providers.
Ultrasonic nebulization technology is hybridizing with heated-wire feedback loops to eliminate rainout in long-duration ventilation circuits. Adult intensive care units in German university hospitals are piloting these dual-mode systems for ARDS patients requiring 72-hour continuous support. The convergence is compressing the addressable market for standalone steam vaporizers in acute care settings.
The EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants is forcing industrial humidifier manufacturers to redesign thermal evaporator heat pump circuits. Equipment destined for pharmaceutical cleanrooms in Belgium and the Netherlands faces 2027 compliance deadlines for alternative refrigerant adoption. Semiconductor fabs in Ireland are accelerating equipment refresh cycles to preempt regulatory obsolescence.
Hospital procurement committees are consolidating vendor relationships through multi-year managed service agreements that bundle device supply with preventive maintenance and consumable replenishment. This model is displacing traditional capital purchase cycles for respiratory humidifiers in National Health Service trusts across England. The shift concentrates purchasing authority at integrated care system level, marginalizing individual hospital autonomy.
Active Humidifier Devices Market Segmentation
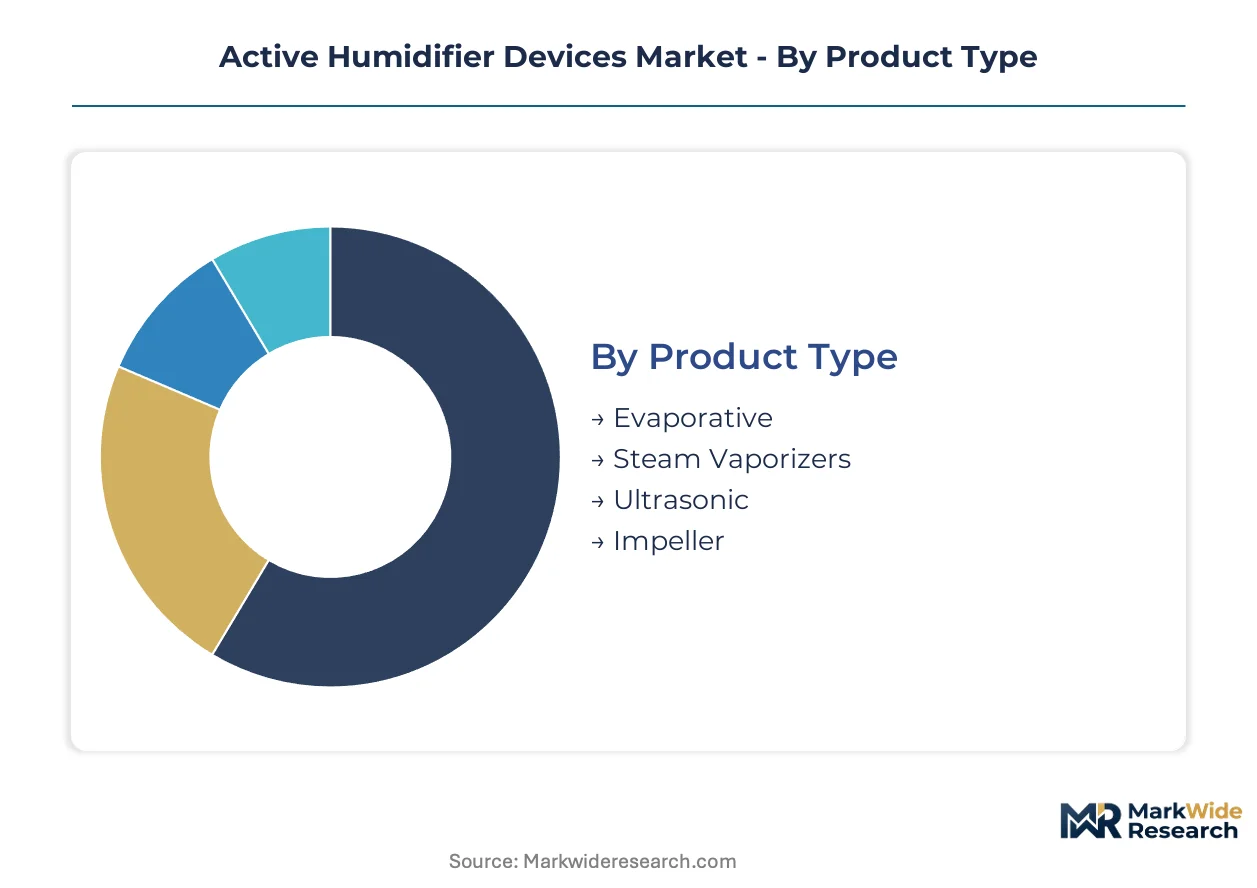
Active humidifier devices fragment across four critical dimensions that shape procurement patterns and margin structures. Product type and technology configurations determine capital intensity and regulatory pathway, while end-user concentration and channel mix dictate pricing power and service bundling potential.
Product Type:
Mature thermal evaporation platforms coexist with emerging ultrasonic miniaturization, creating divergent investment horizons across manufacturer portfolios.
- Evaporative:Wick-based systems draw water through porous media while fans accelerate ambient evaporation, achieving 30-50% relative humidity without mineral dust emission. Demand clusters in German hospital infrastructure modernization programs where precise climate control specifications favor low-maintenance mechanical designs.
- Steam Vaporizers:Electric heating elements boil water to produce mineral-free vapor, consuming 300-500 watts but delivering rapid moisture loading for acute respiratory therapy. NICU bed expansion across US tertiary hospitals sustains procurement despite energy penalties.
- Ultrasonic:Piezoelectric transducers operating at 1.7 MHz generate micro-droplet aerosols with silent operation.
- Impeller:Rotating disks fling water against diffuser screens for coarse humidification in industrial settings.
Steam vaporizers retain volume leadership in clinical acute care; ultrasonic platforms hold the steepest expansion curve in residential sleep therapy applications.
Technology:
Cost tier stratification separates premium hybrid architectures from commoditized single-mode units, with reimbursement eligibility driving hospital purchasing decisions.
- Warm Mist:Heated reservoirs maintain 40-60°C output temperatures that reduce bacterial proliferation risk. FDA 510(k) pathway streamlining accelerates US hospital procurement for devices with predicate thermal claims.
- Cool Mist:Ambient-temperature output eliminates burn hazards in pediatric and geriatric residential settings. Home-based respiratory care migration in the United States propels demand for whisper-quiet ultrasonic cool-mist platforms.
- Hybrid:Dual-mode systems switch between thermal and ultrasonic operation based on ambient conditions.
- Ionic:Electrostatic precipitation removes minerals before aerosolization.
Warm mist dominates reimbursed clinical applications; hybrid configurations are climbing the fastest as ARDS ventilation protocols extend beyond 72 hours.
End User:
Customer type determines specification stringency, with healthcare procurement committees imposing biocompatibility testing requirements that residential channels bypass entirely.
- Healthcare:ISO 80601-2-74 compliance mandates electrical safety validation and heated-wire circuit integration for mechanical ventilation. Infection control infrastructure prioritization across North American health systems compresses capital expenditure cycles for respiratory therapy departments.
- Industrial:Semiconductor fabs in Taiwan and South Korea demand sub-5% relative humidity variance for advanced node production, forcing sub-ppm precision in active humidification control loops.
- Residential:Sleep apnea patients migrating from clinical to home settings drive portable ultrasonic demand.
- Commercial:Building automation integration requirements favor HVAC-bundled humidification in office and retail installations.
Healthcare commands specification leadership; industrial applications are expanding most quickly as fab capacity scales in East Asia.
Distribution Channel:
Volume concentration favors direct sales for institutional contracts, while margin accretion shifts toward specialty channels with service bundling capabilities.
- Direct Sales:Manufacturer field organizations negotiate multi-year managed service agreements bundling device supply with preventive maintenance and consumable replenishment. National Health Service trusts across England consolidate purchasing authority at integrated care system level, marginalizing individual hospital autonomy in vendor selection.
- Specialty Stores:Respiratory therapy equipment dealers provide clinical consultation and mask fitting services that justify premium positioning.
- Online Retail:E-commerce platforms capture price-sensitive residential replacement purchases.
- Supermarkets:Mass merchandisers distribute entry-level evaporative units for seasonal residential demand.
Direct sales retain contract value leadership; specialty stores are gaining share fastest through clinical service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathway streamlining anchors the United States as the dominant geography for active humidifier device procurement, with hospital capital expenditure cycles compressing as healthcare systems prioritize infection control infrastructure.
United States
Neonatal intensive care bed expansion across tertiary hospitals drives demand for integrated heated-wire breathing circuits. FDA maintains stringent biocompatibility and electrical safety standards for humidifiers marketed as medical devices. Hospital procurement committees in Boston and Philadelphia are consolidating vendor relationships through multi-year managed service agreements.
Germany
Hospital infrastructure modernization programs emphasize precise climate control systems for respiratory therapy departments. EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants forces industrial humidifier manufacturers to redesign thermal evaporator heat pump circuits. Equipment destined for pharmaceutical cleanrooms in Belgium and the Netherlands faces 2027 compliance deadlines.
China
Domestic manufacturing zones in Guangdong and Jiangsu provinces are narrowing reliance on imported active humidifier components. NMPA medical device classification guidelines push manufacturers toward higher safety thresholds. Rare-earth element processing for high-frequency transducers clusters in Jiangxi province, creating single-source vulnerability for piezoelectric ceramic supply.
India
Production-linked incentives for domestic manufacturing of respiratory equipment reduce import dependence for hospital chains. CDSCO regulates antimicrobial claims and electrical safety validation for clinical-grade devices. Maharashtra and Gujarat hospital networks are expanding respiratory therapy capacity to serve aging urban populations.
Japan
Semiconductor fabs demand sub-5% relative humidity variance for advanced node production, forcing sub-ppm precision in active humidification control loops. METI industrial standards shape cleanroom equipment specifications for precision manufacturing. Kyushu and Chubu regional fab clusters are accelerating equipment refresh cycles.
Active Humidifier Devices Market Competitive Environment
Building-automation conglomerates and clinical-grade specialists split the market into divergent capability tiers. Consolidation pressure favors scaled manufacturers with dedicated regulatory affairs teams and established notified body relationships. Three archetypes dominate: diversified industrial technology groups, focused respiratory therapy platforms, and precision climate-control specialists. Competitive moves center on strategic partnerships for HVAC integration and geographic licensing agreements for regulatory pathway acceleration.
Among diversified technology groups, Honeywell International Inc. exemplifies the building-automation bundling archetype. ResMed and Fisher & Paykel Healthcare occupy positions within the clinical-grade specialist tier, representing integrated respiratory therapy platforms. These three anchors illustrate the structural divide between commercial HVAC-adjacent positioning and acute-care medical device specialization.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Dyson Ltd. |
| BONECO AG |
| Aprilaire |
| Philips Respironics |
| ResMed |
| Fisher & Paykel Healthcare |
| Vapotherm |
| Teleflex Incorporated |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Jiangxi province rare-earth processing facilities is compressing piezoelectric ceramic margins while simultaneously emboldening ultrasonic humidifier manufacturers to extend payment terms to downstream assemblers in Guangdong, creating divergent pricing power across the value chain.
Pricing Analysis
Price spreads between German hospital procurement contracts and Indian domestic tenders exceed threefold for ISO 80601-2-74 certified respiratory humidifiers. Pricing stratifies across premium, standard, and economy tiers, with FDA 510(k) clearance and heated-wire circuit integration commanding substantial premiums. Cost compression in the residential ultrasonic segment is intensifying because Chinese transducer oversupply enables aggressive OEM pricing. Healthcare procurement committees exhibit lowest price sensitivity due to reimbursement eligibility, while mass-market residential buyers drive commoditization pressure.
Supply Chain Analysis
Rare-earth element feedstock for high-frequency piezoelectric transducers draws from Jiangxi province in China, with secondary sourcing from Malaysian processing facilities and Japanese refined output. Critical component dependencies include piezoelectric ceramics, heated-wire breathing circuits, and precision humidity sensors. Single-source vulnerability in Jiangxi rare-earth concentration creates supply disruption exposure for ultrasonic platform manufacturers. Distribution runs through direct manufacturer field organizations for hospital contracts, specialty respiratory therapy dealers for clinical consultation, and e-commerce platforms for residential replacement purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated care system consolidation in England and GPO centralization across United States hospital networks, fragmenting vendor negotiation leverage and compressing margin capture for non-differentiated manufacturers.
For Market Incumbents: Build regulatory certification moats through accelerated FDA 510(k) predicate device filings and CE marking MDR transition readiness. Defensive moves center on backward integration into piezoelectric ceramic sourcing to neutralize Jiangxi supply concentration risk, and capacity addition in Tamil Nadu to exploit India PLI scheme incentives. The passive humidifier substitution threat in short-duration anesthesia settings demands heated-wire circuit innovation to lock in NICU and ARDS ventilation protocols. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point for HVAC-bundled humidification platforms, as Honeywell's building automation dominance remains incomplete in this tier. Home-based respiratory care in Brazil and Mexico offers secondary white-space, with sleep apnea patient migration outpacing local clinical-grade supply. Go-to-market execution should anchor on specialty respiratory therapy dealer partnerships that provide clinical consultation differentiation against mass-market e-commerce positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ultrasonic miniaturization platforms as piezoelectric transducer costs compress, improving return thresholds for mid-scale manufacturers. Long-term viability over the next decade favors acquisition targets with established notified body relationships and ISO 10993 biocompatibility testing completion, given 14-18 month queue times at accredited laboratories. The signal to watch is NMPA medical device classification guideline tightening in China, which would accelerate domestic manufacturer consolidation and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Expedited clearance timelines accelerate hospital procurement decisions in United States tertiary networks. |
| CE Marking MDR Transition | Stricter European medical device regulation creates first-mover advantage for established notified body relationships. |
| Backward Integration into Transducers | Captive piezoelectric ceramic supply neutralizes Jiangxi province single-source vulnerability for ultrasonic platforms. |
| Hospital System Partnership | Multi-year managed service agreements bundle device supply with preventive maintenance and consumable replenishment. |
| Software Companion Development | Predictive maintenance platforms compress separation between hardware OEMs and digital service providers. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with respiratory therapy department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided clinical procurement insight. Secondary validation drew from FDA 510(k) databases, NMPA medical device registration records, ISO 80601-2-74 certification listings, and hospital capital expenditure disclosures. Bottom-up demand modeling across end-user segments triangulated against top-down manufacturer revenue aggregation.
Calibration against historical hospital procurement cycle patterns and semiconductor fab equipment refresh timelines shaped the projection framework. Segmentation dimensions modeled include product type, technology configuration, end-user category, and distribution channel across the analysis window. CAGRs were derived from weighted average growth assumptions by segment, with specific inputs including NICU bed expansion rates, EU F-Gas Regulation compliance deadlines, and home-based respiratory care migration velocity.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, rare-earth element pricing volatility, or reimbursement policy shifts would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and technology substitution rates. Cross-checking against hospital procurement database trends and GPO contract award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Medical Cyclotron Market
Medical Devices
India Clear Aligners Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Airway Management Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Global Cryotherapy Market
Medical Devices
Cranial Closure and Fixation Devices Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Europe C-Arms Market