
 Hearing Aid with Lithium-Ion Battery Market | 2026-2036
Hearing Aid with Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Aid with Lithium-Ion Battery Market Insights
Lithium-ion is restructuring hearing aid power economics by displacing zinc-air disposable cells that dominated for decades. Sonova Holding AG leverages vertical integration across battery management systems and audio processing platforms. VARTA AG anchors European cell supply for major OEM programs. Starkey Hearing Technologies differentiates through domestic manufacturing scale in the United States.
Hearing aids with lithium-ion batteries are wearable medical devices integrating 3.7V rechargeable cells with digital signal processors, typically offering 16-30 hours of runtime per charge and 500-1000 cycle lifespans; they eliminate zinc-air cell replacement for users with dexterity limitations. Behind-the-Ear configurations dominate unit volume due to larger battery accommodation and amplified power budgets for wireless streaming. Receiver-in-Canal designs represent the fastest-growing product type as miniaturized lithium-ion cells enable discreet form factors without sacrificing connectivity features.
The FDA over-the-counter hearing aid rule reshapes United States distribution by permitting direct consumer access without audiological prescription, while CE marking under the EU MDR imposes clinical validation requirements on battery safety and biocompatibility. Germany's KBA does not regulate this sector; instead, BfArM oversees medical device registration for lithium-ion powered hearing aids entering the German market. Stakeholders must monitor how reimbursement policy evolution in Japan's MHLW and shifting battery chemistry standards from IEC influence product development roadmaps and regional launch sequencing.
Market Dynamics
Lithium-ion chemistry is compressing hearing aid lifecycle economics by eliminating zinc-air cell procurement and disposal logistics for users with limited dexterity.
Growth Catalysts
- FDA Over-the-Counter Rule:Direct consumer access without audiological prescription expands addressable population in the United States beyond traditional clinical channels.
- Japan's Aging Demographics:Geriatric end-users with reduced manual dexterity drive preference for rechargeable devices eliminating weekly battery replacement.
- Bluetooth Low Energy:Wireless streaming protocols increase power budgets and make rechargeable lithium-ion architectures economically superior to disposable cells.
Market Restraints
- Cobalt Supply Concentration:Cathode material sourcing concentrates in the Democratic Republic of Congo, exposing cell manufacturers to geopolitical and ethical sourcing risks.
- EU MDR Clinical Validation:Battery safety and biocompatibility documentation requirements extend product registration timelines for CE-marked devices.
- Zinc-Air Substitution:Disposable cells retain cost advantage in price-sensitive segments and emerging markets with unreliable electricity infrastructure.
Strategic Opportunities
- India's PLI Scheme:Domestic manufacturing incentives for electronics and medical devices attract lithium-ion cell assembly capacity for regional hearing aid production.
- Teleaudiology Distribution:Remote fitting and programming platforms enable direct-to-consumer channels bypassing traditional audiology clinic networks.
- Solid-State Convergence:Polymer electrolyte research combined with microelectromechanical systems enables smaller form factors with enhanced safety profiles.
Industry Challenges
- Audiological Talent Pipeline:Shortage of hearing instrument specialists capable of programming lithium-ion powered devices with advanced connectivity features constrains service capacity.
- IEC 62133 Certification Timeline:Secondary cell safety testing for transport and medical use creates bottlenecks between prototype completion and commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Aid with Lithium-Ion Battery Market |
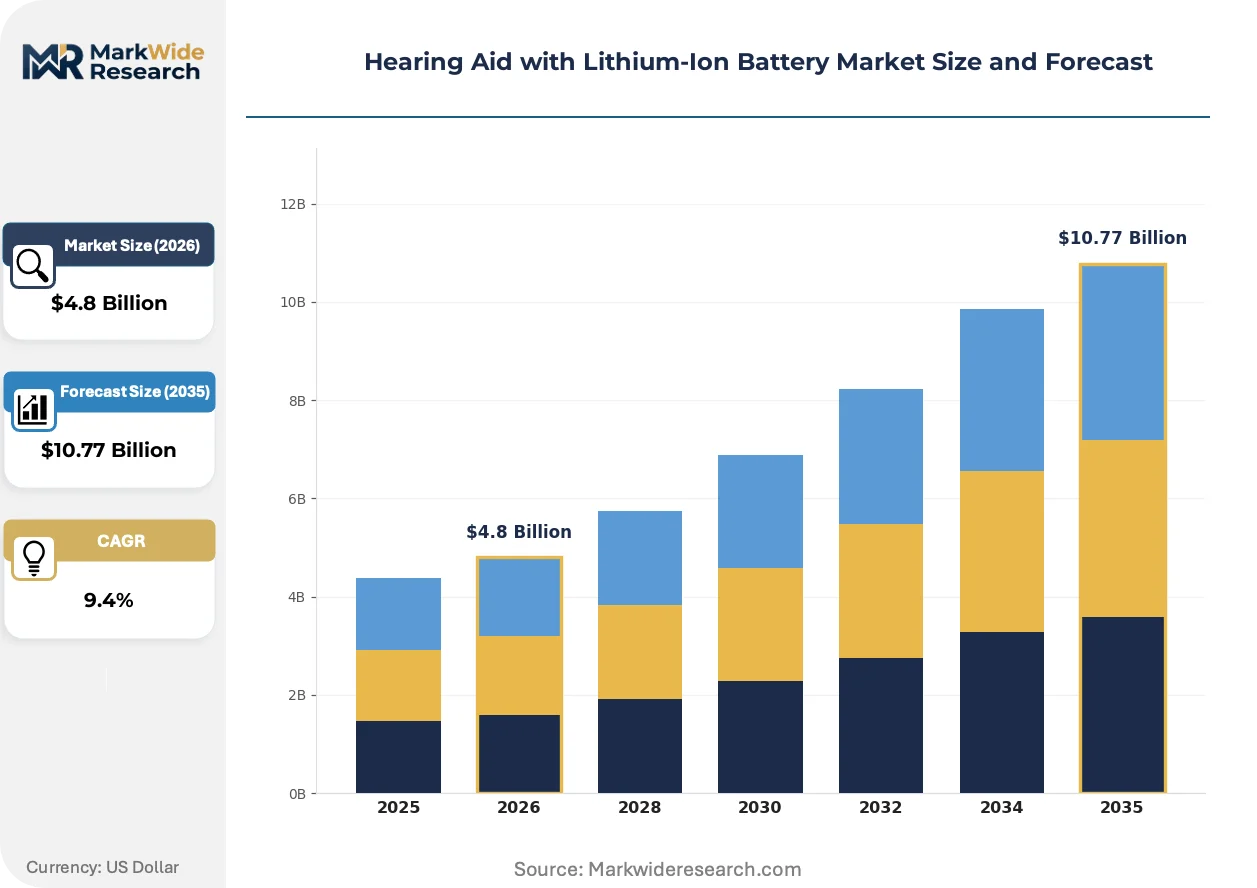
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Behind-the-Ear, In-the-Ear, Completely-in-Canal, Receiver-in-Canal End User: Adults, Pediatric, Geriatric, Individuals with Hearing Loss Distribution Channel: Retail Stores, Online Platforms, Audiology Clinics, Hospitals Technology: Digital, Analog, Programmable, Wireless |
| Companies Covered | Sonova Holding AG, Starkey Hearing Technologies, William Demant Holding A/S, GN Store Nord A/S, Widex A/S, Sivantos Pte Ltd, Cochlear Limited, VARTA AG, ZPower LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Aid with Lithium-Ion Battery Market Trends and Innovations
Integration of power management and audio processing is compressing device footprints while extending functional capabilities beyond amplification into health monitoring and connectivity.
Chip-scale packaging is unifying battery management systems with digital signal processors on single substrates. Premium-tier hearing aid manufacturers are adopting these integrated modules to reduce board area by forty percent. This convergence is unifying power delivery and audio processing architectures that previously required discrete component layouts.
REACH substance restrictions on nickel and cobalt compounds are forcing cathode chemistry pivots toward lithium iron phosphate and nickel-manganese-cobalt reduced-cobalt formulations. Cell suppliers must reformulate electrode materials while maintaining energy density targets for miniature hearing aid applications. European OEM programs are accelerating qualification of alternative cathode systems to maintain CE marking compliance.
Subscription-based device access is displacing outright purchase models in North American audiology clinics. Patients receive bundled hardware, maintenance, and upgrade cycles through monthly payments rather than capital expenditure. This shift concentrates in urban markets where consumers prioritize predictable healthcare budgeting over ownership.
Hearing Aid with Lithium-Ion Battery Market Segmentation
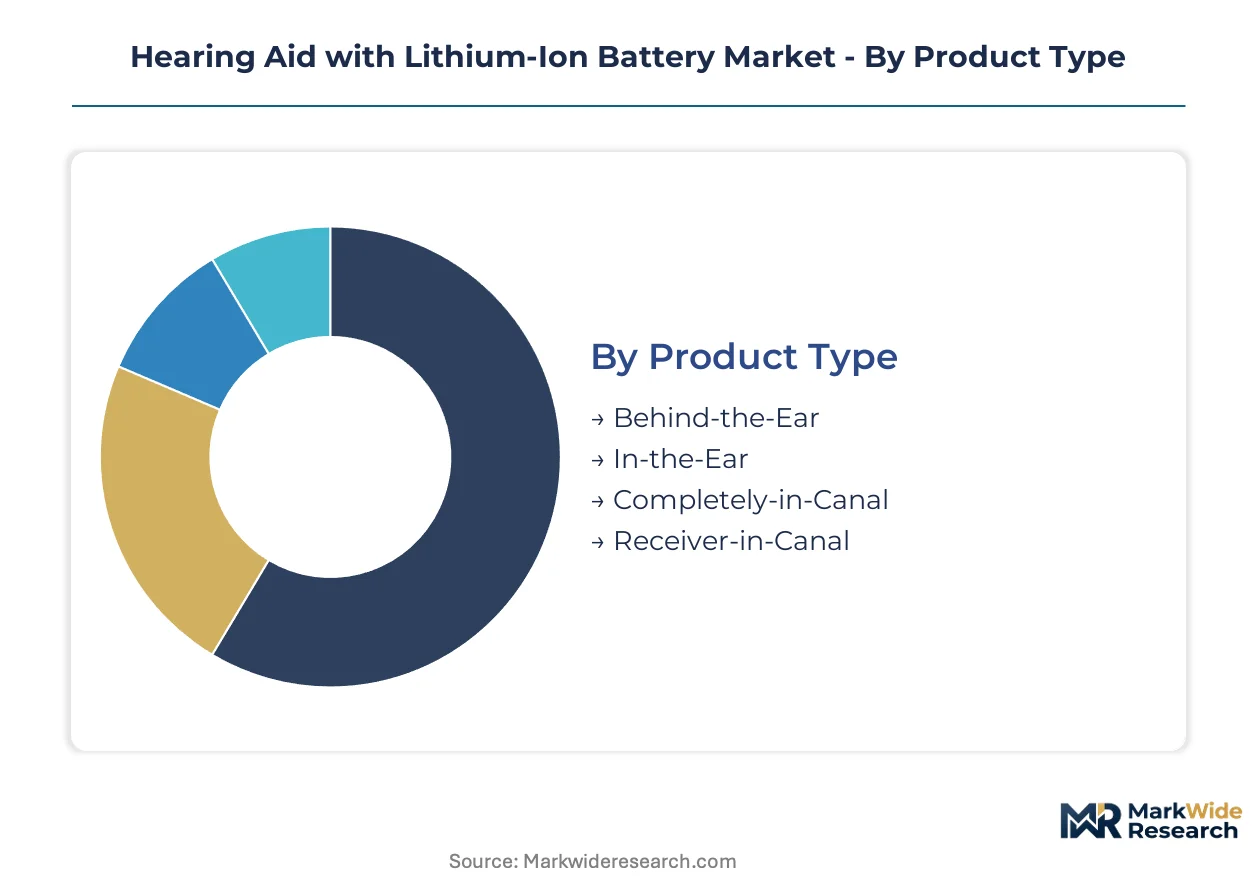
Hearing aid manufacturers calibrate form factor, user profile, and channel strategy against divergent power budgets and dexterity requirements. Segmentation reveals where lithium-ion rechargeability commands premium positioning versus where disposable cells retain cost advantages.
Product Type:
Customization intensifies as device miniaturization collides with battery capacity constraints, creating a spectrum from standardized power-agnostic designs to bespoke micro-architectures.
- Behind-the-Ear:Larger housing accommodates 3.7V cells with 30-hour runtime and integrated wireless antennas. Demand concentrates in Germany's audiology clinics serving geriatric patients prioritizing reliability over discretion.
- Receiver-in-Canal:Miniaturized lithium-ion cells enable slim receiver wires with full Bluetooth streaming capability. Japan's aging demographic drives fastest adoption as dexterity limitations eliminate weekly battery swaps.
- In-the-Ear:Custom-molded shells fit individual ear canal geometry with embedded rechargeable cells. Manufacturing scales through digital scanning workflows.
- Completely-in-Canal:Deep insertion designs demand smallest available cylindrical cells, limiting wireless features. Appeals to cosmetic-conscious users in professional settings.
Leading the category by volume: Behind-the-Ear. Expanding most quickly: Receiver-in-Canal.
End User:
Cost tiers stratify sharply across age-related reimbursement eligibility and technological sophistication requirements.
- Geriatric:Medicare and national health systems in Japan and Germany subsidize rechargeable devices for users over 65 with arthritic limitations. FDA over-the-counter access expands self-directed purchase pathways.
- Adults:Workforce-age users prioritize Bluetooth connectivity for video calls and smartphone integration. Employer-sponsored hearing benefits concentrate demand in North American corporate health plans.
- Pediatric:School-age fittings require tamper-resistant battery compartments and parental monitoring apps. Growth tied to newborn hearing screening program expansion.
- Individuals with Hearing Loss:Catch-all category capturing undiagnosed or untreated cases now addressable through direct-to-consumer channels.
Dominant by spending: Geriatric. Gaining share fastest: Adults in employer-sponsored programs.
Distribution Channel:
Channel margins compress where professional fitting services compete against algorithmic self-adjustment applications.
- Audiology Clinics:Professional fitting, real-ear verification, and ongoing programming support justify premium pricing. Concentrates in urban centers with aging populations.
- Online Platforms:Direct-to-consumer sales accelerate post-FDA over-the-counter ruling, with teleaudiology support replacing in-person verification. Self-fitting apps reduce return rates.
- Retail Stores:Big-box electronics retailers and pharmacy chains capture price-sensitive segments with limited service bundling.
- Hospitals:ENT departments handle complex cases with comorbidities requiring medical clearance before amplification fitting.
Highest value per transaction: Audiology Clinics. Steepest volume expansion: Online Platforms.
Technology:
Supply concentration in audio processing silicon creates divergence between programmable flexibility and fixed-function economy tiers.
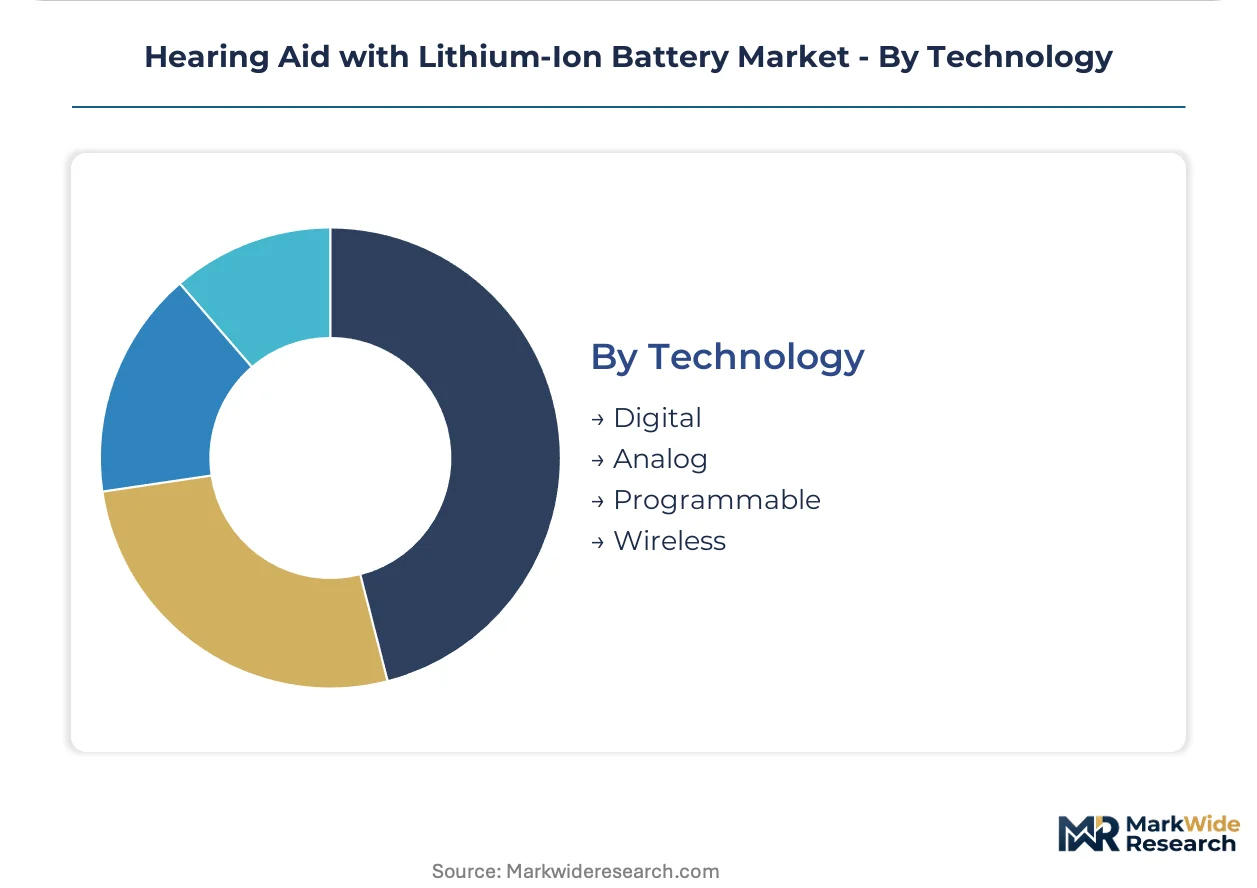
- Digital:DSP architectures enable noise reduction, directional microphones, and feedback cancellation. Universal standard across premium and mid-tier offerings.
- Wireless:Bluetooth Low Energy and proprietary 2.4GHz protocols enable smartphone streaming and remote programming. Power consumption drives lithium-ion necessity.
- Programmable:Software-defined frequency response curves allow audiologist adjustment without hardware modification. Fading as fully digital platforms absorb this capability.
- Analog:Basic amplification without digital processing retains niche in price-sensitive emerging markets with unreliable electricity infrastructure.
Technology foundation for volume: Digital. Climbing fastest: Wireless integration as default specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Singapore and Shenzhen anchor lithium-ion cell assembly for hearing aid OEMs serving Asia-Pacific demand. These specialized economic corridors concentrate battery management system integration and final device packaging within tariff-advantaged boundaries.
United States
Medicare Advantage plans and employer hearing benefits drive rechargeable device uptake among workforce-age adults. The FDA over-the-counter rule eliminates audiological prescription requirements, opening direct-to-consumer channels previously restricted to licensed clinics. Minneapolis-St. Paul hosts Starkey Hearing Technologies' domestic manufacturing campus serving North American distribution.
Germany
BfArM medical device registration requirements and statutory health insurance reimbursement create structured procurement pathways for geriatric users. REACH substance restrictions accelerate cathode chemistry pivots away from nickel-cobalt formulations. Berlin and Munich audiology clinic networks concentrate premium-tier fitting services for lithium-ion rechargeable models.
Japan
MHLW reimbursement policy evolution shapes product launch sequencing as aging demographics expand the addressable population over 65. METI battery safety standards intersect with IEC 62133 certification timelines for secondary cell medical use. Osaka-Kobe industrial corridor hosts precision electronics manufacturing supporting miniaturized cell integration.
India
PLI scheme incentives for electronics and medical devices attract lithium-ion cell assembly capacity targeting regional hearing aid production. BIS certification requirements for rechargeable medical devices create compliance thresholds for imported components. Gujarat and Karnataka special economic zones concentrate contract manufacturing for export-oriented OEM programs.
Switzerland
Swissmedic medical device authorization maintains stringent clinical validation requirements for battery-powered hearing aids entering the domestic market. Private health insurance models support premium-tier rechargeable device uptake among professional-class users. Zurich and Basel clusters concentrate audiology research and premium device distribution infrastructure.
Hearing Aid with Lithium-Ion Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated hearing aid OEMs controlling premium-tier distribution while cell suppliers capture component value in mid-market assemblies. The vendor base concentrates around vertically integrated audio processing platforms and captive battery management system capabilities. Two strategic archetypes dominate: full-stack device manufacturers with in-house cell integration, and specialized cell suppliers qualifying across multiple OEM programs. Competitive moves center on backward integration into battery chemistry and geographic expansion through teleaudiology-enabled direct channels.
Within the integrated device manufacturer tier, Sonova Holding AG and Starkey Hearing Technologies exemplify contrasting geographic anchoring strategies. Sonova's Swiss AG structure positions it within European regulatory frameworks, while Starkey's domestic US manufacturing scale addresses FDA pathway requirements. VARTA AG occupies a distinct position as a European cell supplier anchoring OEM programs with qualified lithium-ion architectures. These three entities represent the primary competitive vectors: integrated platform control, regional manufacturing scale, and specialized component supply.
| Leading Market Players |
|---|
| Sonova Holding AG |
| Starkey Hearing Technologies |
| William Demant Holding A/S |
| GN Store Nord A/S |
| Widex A/S |
| Sivantos Pte Ltd |
| Cochlear Limited |
| VARTA AG |
| ZPower LLC |
| Others |
Pricing and Supply Chain Analysis
Audiology clinic procurement concentration in Germany and Japan anchors premium subscription pricing for rechargeable lithium-ion devices, while direct-to-consumer channels emerging under FDA over-the-counter pathways compress margins through algorithmic self-fitting competition.
Pricing Analysis
Short lead-time premiums for IEC 62133-certified cell lots command fifteen to twenty percent markups over standard procurement cycles, reflecting certification bottlenecks between prototype completion and commercial launch. Three-tier pricing structure across premium, standard, and economy levels separates audiology clinic bundles with teleaudiology support from retail self-fit models and emerging market analog alternatives. Cost compression in mid-tier wireless SKUs is intensifying because Bluetooth Low Energy power budgets force lithium-ion architectures that eliminate zinc-air cost advantages. Employer-sponsored hearing benefits in North American corporate health plans show least price sensitivity; price-sensitive segments concentrate in retail pharmacy channels serving undiagnosed mild-to-moderate hearing loss.
Supply Chain Analysis
Regional distribution centers in Singapore and Shenzhen anchor hub-and-spoke patterns for Asia-Pacific OEM fulfillment, with secondary nodes in Minneapolis-St. Paul and Zurich serving North American and European clinical networks. Cell assembly concentrates in China, South Korea, and Japan; VARTA AG's European operations qualify alternative cathode systems for REACH compliance. Cathode material sourcing draws from cobalt concentrate in the Democratic Republic of Congo and processed lithium carbonate from Chilean salares. Single-source vulnerability in Congolese cobalt exposes manufacturers to ethical sourcing audits and geopolitical disruption. Distribution runs through audiology clinic networks for premium tiers, direct-to-consumer platforms for over-the-counter segments, and retail pharmacy chains for economy positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
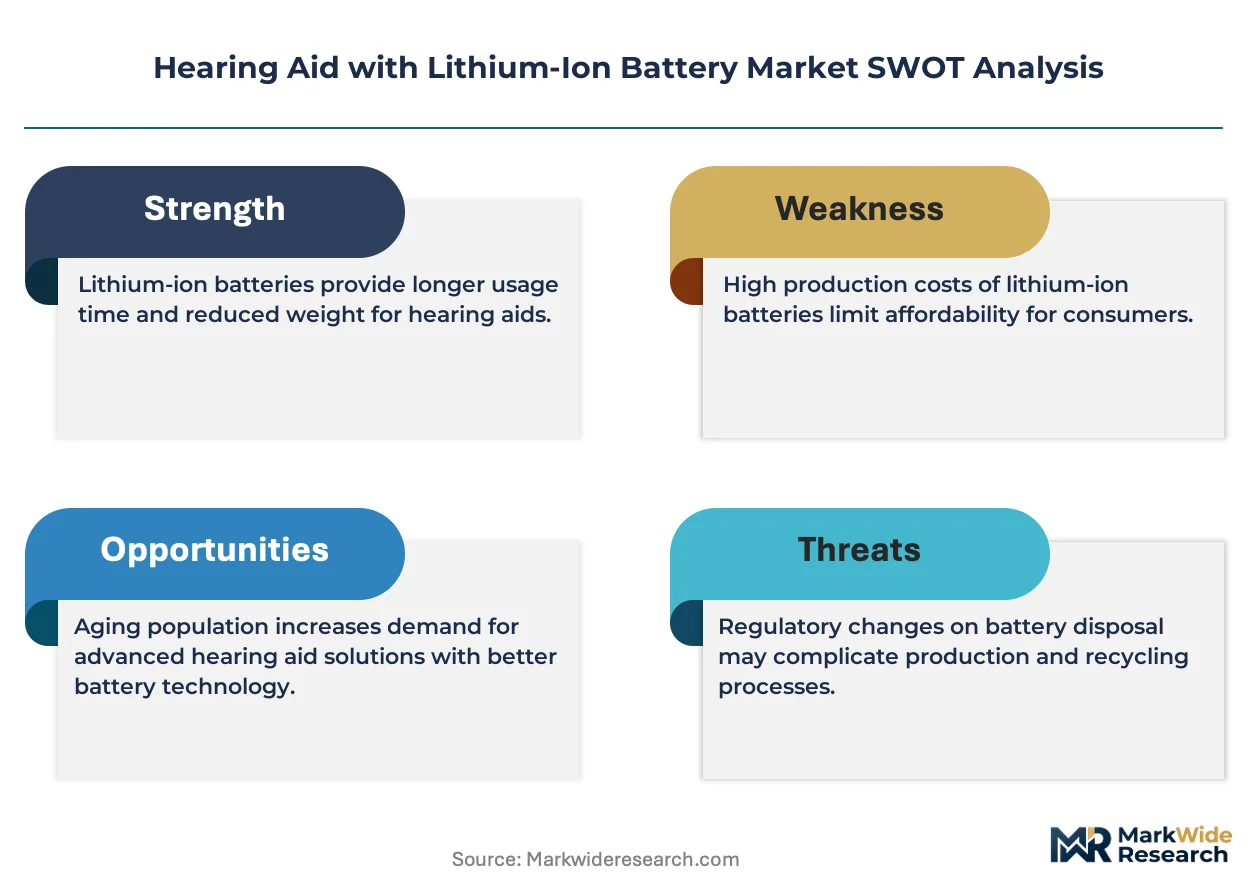
The hearing aid power architecture is transitioning from zinc-air disposable dominance to rechargeable lithium-ion systems, with solid-state polymer electrolyte research poised to displace conventional liquid electrolyte cells in premium form factors.
For Market Incumbents: Deepen backward integration into battery management system silicon to defend against chip-scale packaging convergence compressing board area. Capture domestic manufacturing scale in tariff-advantaged jurisdictions like the United States and Switzerland to offset supply chain fragmentation. Prioritize IEC 62133 pre-certification programs to compress lead-time premiums eroding margin.
For New Entrants and Emerging Players: Begin with teleaudiology-enabled direct channels in FDA over-the-counter segments where audiological talent shortages constrain incumbent service capacity. India's PLI scheme incentives offer the most penetrable geography for contract manufacturing entry. Self-fitting application development represents the critical go-to-market angle for reducing return rates without clinical infrastructure.
For Investors and Strategic Acquirers: The window for entry favors specialized cell suppliers with qualified lithium-ion architectures across multiple OEM programs rather than integrated device manufacturers facing margin compression. Long-term viability hinges on solid-state electrolyte qualification timelines and cobalt-reduced cathode chemistry pivots. Monitor BfArM and MHLW reimbursement policy evolution as the primary inflection signal for regional demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Management Systems | Sonova Holding AG and Starkey Hearing Technologies reduce board area through captive silicon design. |
| Cobalt-Reduced Cathode Qualification | VARTA AG accelerates lithium iron phosphate and NMC reduced-cobalt formulations for REACH compliance. |
| Teleaudiology Platform Development | Remote fitting algorithms bypass audiology clinic networks constrained by specialist talent shortages. |
| Domestic Manufacturing Scale Expansion | Starkey's Minneapolis-St. Paul campus addresses FDA pathway requirements and tariff exposure. |
| Subscription Access Model Rollout | North American audiology clinics bundle hardware, maintenance, and upgrade cycles through monthly payments. |
Research Methodology
Independent corroboration across FDA 510(k) filings, BfArM medical device registrations, and MHLW reimbursement databases underwrites the qualitative findings in this study. Primary interviews with hearing instrument specialists, biomedical engineers at audiology clinic networks, lithium-ion cell procurement managers, and GPO contracts managers combined with secondary validation from IEC standards documentation, REACH substance restriction updates, and PLI scheme disclosure records. Bottom-up unit economics modeling and top-down demographic penetration analysis triangulate volume estimates.
Rate-of-change decomposition across the analysis window segments expansion into aging demographic contributions, regulatory access expansion effects, and technology substitution elasticities. Modeled dimensions span product type, end user archetype, distribution channel, and wireless connectivity specification. CAGRs derive from fitted adoption curves against historical zinc-air displacement patterns, with cell cycle lifespan and runtime benchmarks serving as critical forecast inputs.
Underlying measurement precision varies by segment; audiology clinic channel data carries tighter precision than direct-to-consumer online platform estimates where return rate volatility complicates net unit calculations. Forecasts reflect assumptions about FDA over-the-counter penetration curves, MHLW reimbursement evolution timelines, and solid-state electrolyte commercialization readiness. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Cervical Fusion Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Syringeless Injector Market