
 North America Medical Device Regulatory Affairs Market | 2026-2036
North America Medical Device Regulatory Affairs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Device Regulatory Affairs Market Analytics
The FDA's Quality System Regulation alignment with ISO 13485:2016 is hardening compliance burdens for Class III device sponsors. IQVIA leverages its integrated data infrastructure to anchor regulatory strategy across multiple therapeutic areas. Laboratory Corporation of America Holdings sustains dominance in premarket clinical testing through its expansive laboratory network. ICON plc differentiates via specialized consulting for combination products spanning drug-device boundaries.
Medical device regulatory affairs encompasses the specialized discipline of preparing, submitting, and maintaining documentation required for market authorization, encompassing 510(k) premarket notifications, PMA applications, and De Novo classification requests with predicate device analysis and biocompatibility testing protocols. Its primary commercial purpose ensures lawful market entry while minimizing enforcement exposure. Consulting Services captures the largest margin pool as manufacturers outsource complex FDA interaction strategies, while Regulatory Submissions represents the fastest-growing segment driven by escalating PMA volume for AI-enabled diagnostics. Software Solutions within the Technology dimension is expanding rapidly as FDA's software as a medical device framework matures.
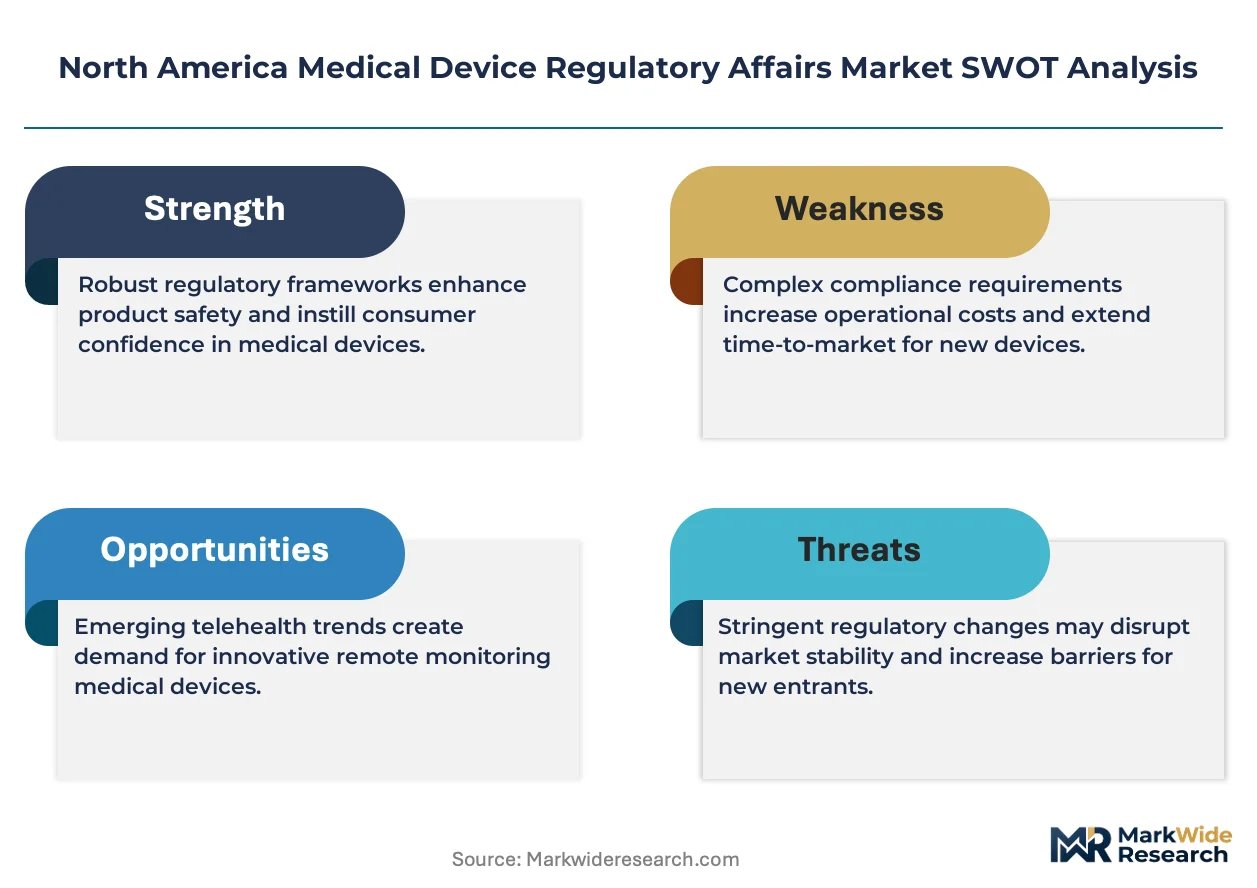
FDA's Center for Devices and Radiological Health, Health Canada's Medical Devices Bureau, and ISO 14971 risk management standards collectively shape submission requirements, clinical evidence thresholds, and post-market surveillance obligations across the United States and Canada. These frameworks elevate demand for specialized regulatory talent capable of navigating predicate device strategies and quality management system audits. Stakeholders must monitor FDA's forthcoming rulemaking on laboratory developed tests, which will redraw jurisdictional boundaries between device and clinical laboratory oversight.
Market Dynamics
FDA's pending alignment of Quality System Regulation with ISO 13485:2016 is compressing compliance timelines for Class III device sponsors across the United States and Canada. Orthopedic and cardiovascular manufacturers are accelerating regulatory team expansion to manage predicate device strategies and biocompatibility documentation under tighter review cycles.
Growth Catalysts
- AI-Enabled Diagnostics Surge:Breakthrough device designations for machine learning algorithms are expanding PMA submission volumes. Health Canada's parallel review pathways for software as a medical device are accelerating cross-border market entry.
- ISO 14971 Integration:Risk management standard harmonization across FDA and Health Canada is reducing duplicate documentation burdens. Canadian manufacturers are consolidating North American quality management systems under unified frameworks.
- Venture-Backed Startup Density:California's Bay Area medical technology corridor is concentrating demand for specialized regulatory consulting. Early-stage companies require predicate device analysis and 510(k) strategy support to secure Series B financing.
Market Restraints
- Specialized Talent Scarcity:Experienced FDA interaction strategists command premium compensation. Regulatory affairs professionals with PMA and De Novo classification expertise remain concentrated in Boston and San Diego metro areas.
- Biocompatibility Testing Bottlenecks:ISO 10993-compliant laboratory capacity constraints are extending premarket timelines. Third-party testing providers face backlog accumulation for cytotoxicity and sensitization protocols.
- Combination Product Complexity:Drug-device boundary disputes between FDA's Center for Drug Evaluation and Research and Center for Devices and Radiological Health create jurisdictional uncertainty. Sponsors navigate dual review pathways for novel delivery systems.
Strategic Opportunities
- Canadian Market Expansion:Health Canada's Medical Devices Bureau is streamlining priority review for AI diagnostics. US sponsors are establishing Toronto regulatory satellite offices to access accelerated pathways.
- Digital Health Pre-Certification:FDA's pilot program for software-based medical devices is creating new consulting service categories. Firms are developing real-world performance monitoring capabilities to support post-market surveillance obligations.
- Laboratory Developed Test Convergence:Pending FDA rulemaking on LDT oversight will redraw device-clinical laboratory boundaries. Regulatory affairs providers are building clinical evidence generation capabilities to capture diagnostic sponsor demand.
Industry Challenges
- Post-Market Surveillance Intensification:FDA's Medical Device Reporting requirements and Unique Device Identification mandates are expanding compliance infrastructure needs. Manufacturers must integrate complaint handling with quality management system audits.
- Predicate Device Obsolescence:Rapid technological iteration is complicating substantial equivalence determinations for 510(k) submissions. Sponsors face predicate hunting difficulties for next-generation materials and connectivity-enabled devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Device Regulatory Affairs Market |
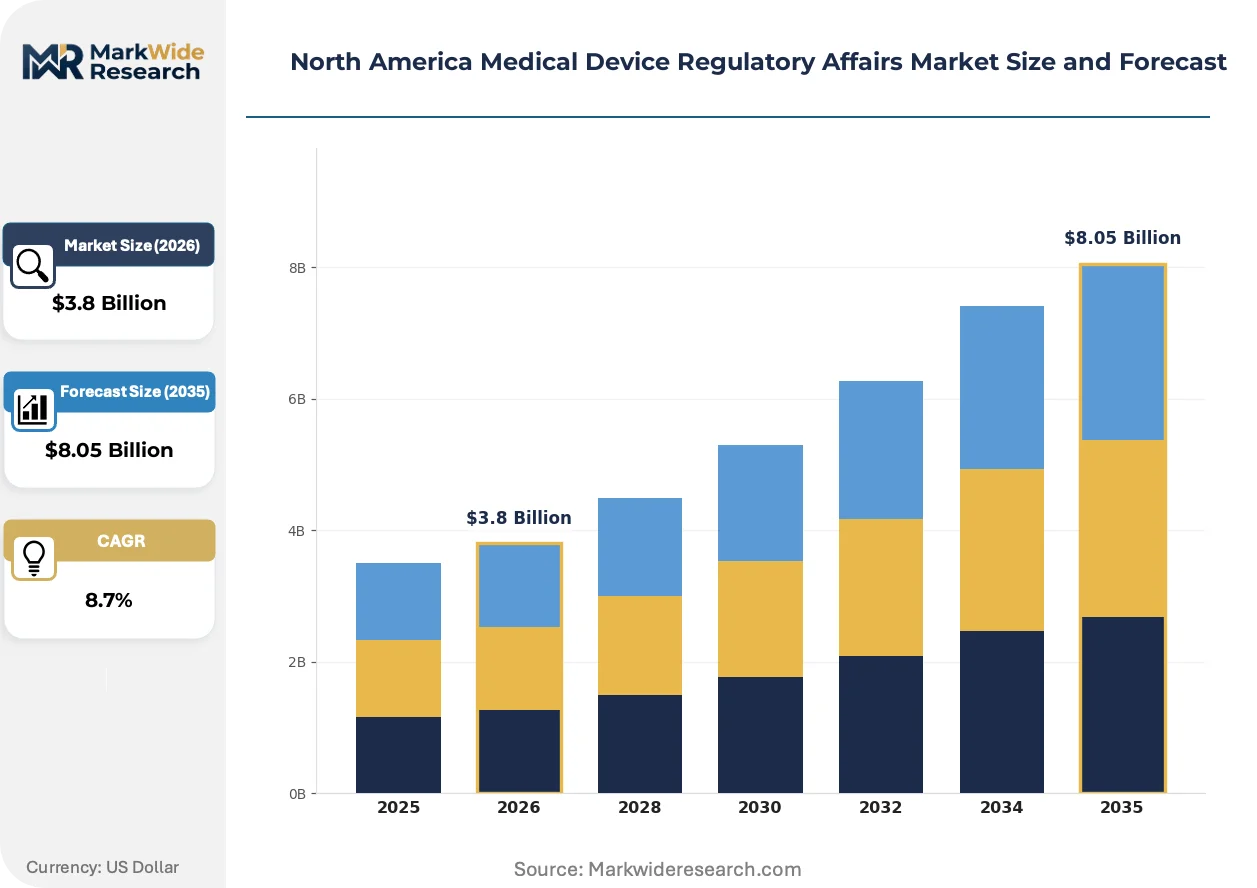
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting Services, Compliance Audits, Regulatory Submissions, Quality Assurance End User: Medical Device Manufacturers, Research Institutions, Regulatory Agencies, Healthcare Providers Technology: Software Solutions, Data Analytics, Information Management, Compliance Tracking Application: Risk Assessment, Documentation Management, Product Approval, Market Surveillance |
| Companies Covered | ICON plc, IQVIA, Laboratory Corporation of America Holdings, Emergo, Freyr, Medpace, Promedica International, Integer Holdings Corporation, SGS, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Device Regulatory Affairs Market Evolving Landscape
Regulatory technology platforms are absorbing documentation workflows previously managed through fragmented spreadsheet and document management systems. This infrastructure shift is compressing submission preparation timelines while elevating data integrity standards for FDA interactions.
Machine learning-based submission preparation tools are absorbing predicate device search and biocompatibility protocol generation tasks. Mid-sized orthopedic manufacturers are adopting these platforms to reduce reliance on external consulting for routine 510(k) filings. The technology is absorbing lower-complexity regulatory work, freeing specialized professionals for PMA and De Novo strategy.
Health Canada's implementation of expanded priority review pathways for digital health technologies is accelerating cross-border submission synchronization. Canadian sponsors are aligning quality management systems with FDA expectations to enable simultaneous US market entry. Software as a medical device manufacturers are restructuring clinical evidence packages to satisfy both regulators through modular documentation architectures.
Subscription-based regulatory intelligence services are displacing traditional periodic consulting engagements among venture-backed startups. California and Massachusetts medical device clusters are purchasing real-time FDA guidance tracking and competitive submission monitoring. This procurement model shift is most visible among Series A and B companies seeking predictable compliance spending ahead of pivotal trials.
North America Medical Device Regulatory Affairs Market Segmentation
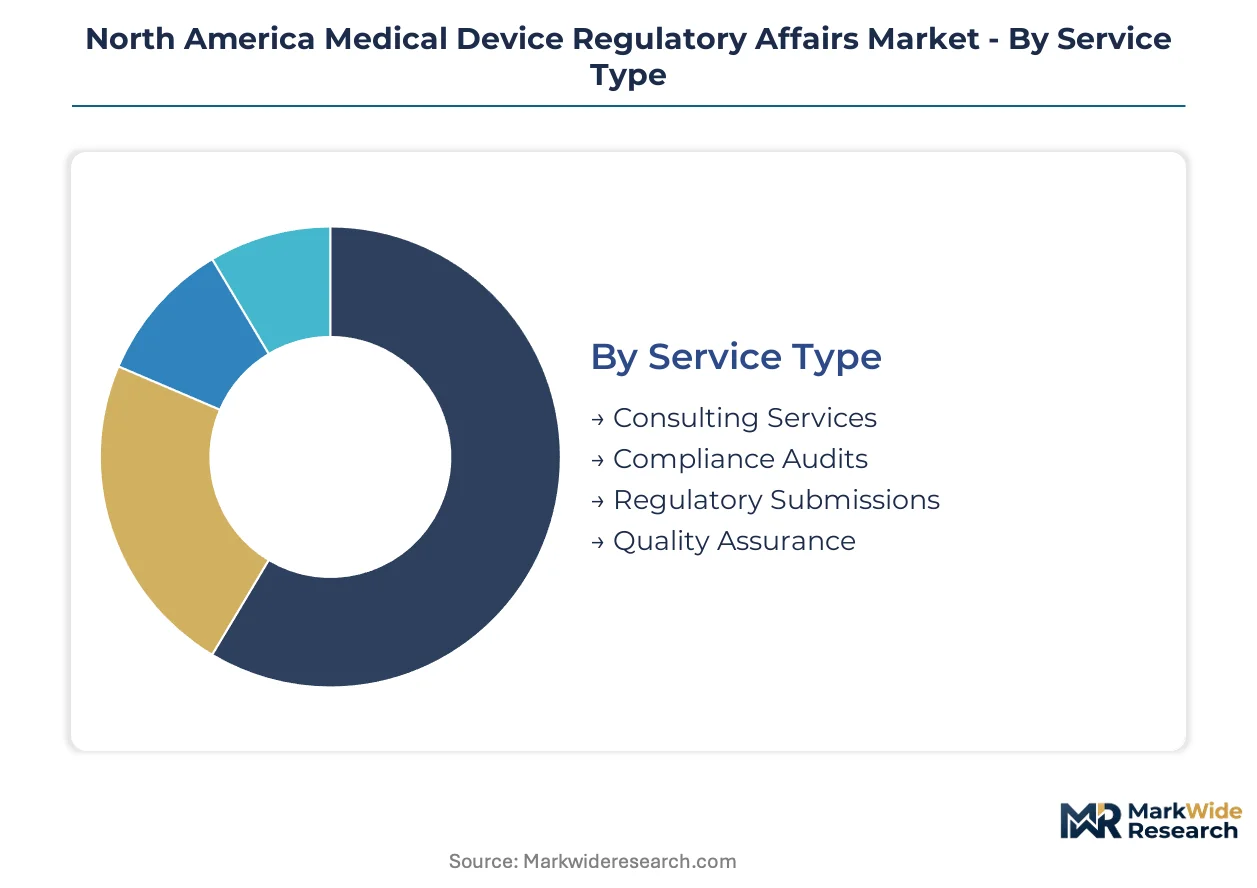
Regulatory affairs providers must align service architectures with distinct client capabilities and submission complexity tiers. Segmentation reveals where margin pools concentrate versus where volume expansion accelerates.
Service Type:
Volume concentrates in compliance maintenance, while premium capture sits with strategic FDA navigation.
- Consulting Services:Strategic advisory encompassing predicate device selection, breakthrough designation strategy, and FDA pre-submission meeting preparation. Demand concentrates among California and Massachusetts venture-backed startups seeking Series B financing validation through regulatory pathway clarity.
- Regulatory Submissions:End-to-end preparation of 510(k) notifications, PMA applications, and De Novo classification requests with biocompatibility protocol integration. PMA volume for AI-enabled diagnostics is expanding most quickly across the analysis window, compressing sponsor internal timelines.
- Compliance Audits:ISO 13485:2016 and FDA Quality System Regulation gap assessments with corrective action planning.
- Quality Assurance:Post-market surveillance infrastructure design including Medical Device Reporting and Unique Device Identification compliance.
Today's leader: Consulting Services. Tomorrow's challenger: Regulatory Submissions.
End User:
Customer sophistication tiers separate self-sufficient multinationals from dependency-heavy emerging manufacturers.
- Medical Device Manufacturers:Spanning Class I through Class III sponsors with varying internal regulatory capacity. Orthopedic and cardiovascular manufacturers in Minnesota and Indiana are expanding dedicated regulatory teams to manage predicate device obsolescence challenges for next-generation materials.
- Research Institutions:Academic medical centers and contract research organizations requiring investigational device exemption support. Boston and San Diego clusters drive demand for early-stage clinical trial regulatory navigation.
- Regulatory Agencies:Government bodies seeking external technical expertise for guidance development and policy implementation.
- Healthcare Providers:Hospital systems and integrated delivery networks managing institutional review board submissions for device trials.
Established revenue: Medical Device Manufacturers. Emerging opportunity: Research Institutions.
Technology:
Digital infrastructure investments separate efficiency leaders from documentation-lagged competitors.
- Software Solutions:Regulatory technology platforms automating submission assembly, predicate device search, and biocompatibility protocol generation. Mid-sized orthopedic manufacturers are adopting these tools to reduce external consulting dependency for routine 510(k) filings.
- Data Analytics:Real-world evidence synthesis and competitive submission intelligence monitoring. Bay Area startups are purchasing subscription-based FDA guidance tracking to normalize compliance spending ahead of pivotal trials.
- Information Management:Document control systems and quality management system integration platforms.
- Compliance Tracking:Post-market surveillance dashboards integrating complaint handling with audit workflows.
Current anchor: Software Solutions. Steepest expansion trajectory: Data Analytics.
Application:
Activity sequencing follows device lifecycle stages from conception through commercial maturity.
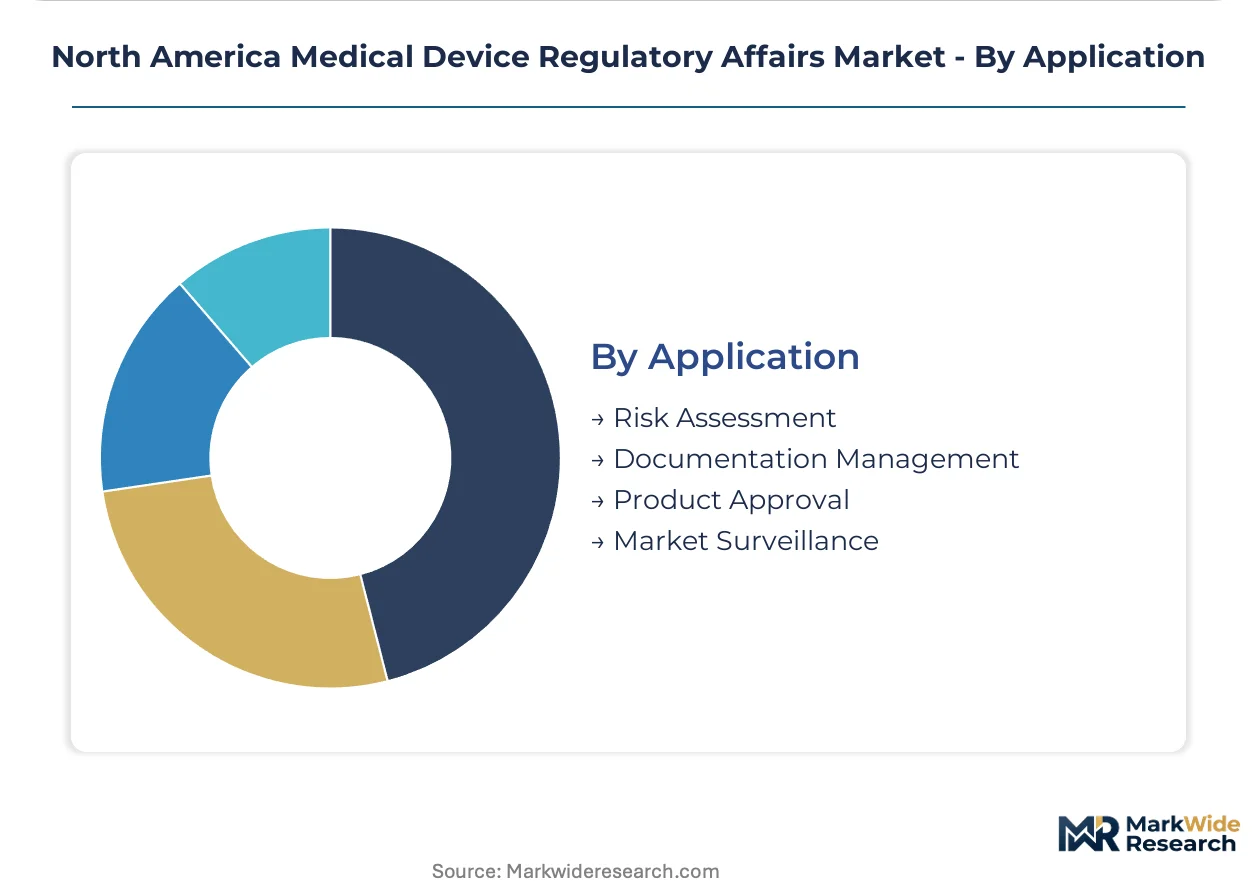
- Product Approval:Market authorization pathway execution encompassing premarket notification, approval application, or De Novo classification. Canadian sponsors are aligning quality management systems with FDA expectations to enable simultaneous US market entry through modular documentation architectures.
- Documentation Management:Technical file assembly, design history file maintenance, and regulatory correspondence archiving. ISO 14971 risk management standard harmonization across FDA and Health Canada is reducing duplicate documentation burdens for cross-border sponsors.
- Risk Assessment:ISO 14971-compliant hazard analysis and clinical evaluation planning.
- Market Surveillance:Post-approval vigilance including adverse event reporting and periodic safety updates.
Dominant share: Product Approval. Fastest climb: Documentation Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The medical device regulatory affairs industry traces its modern roots to post-war standardization efforts, with formalized quality management systems emerging from US and European harmonization initiatives during the 1990s.
United States
FDA's Center for Devices and Radiological Health processes over 3,000 510(k) submissions annually, with PMA review timelines compressing for breakthrough-designated AI diagnostics. Minnesota's Twin Cities corridor hosts concentrated orthopedic manufacturer regulatory teams navigating predicate device obsolescence for next-generation implant materials.
Canada
Health Canada's Medical Devices Bureau operates parallel priority review pathways for software as a medical device, accelerating cross-border synchronization with US sponsors. Toronto's regulatory satellite offices are expanding as US manufacturers establish dedicated Canadian submission capabilities to access accelerated market entry.
Massachusetts
Boston's medical technology cluster generates sustained demand for investigational device exemption support and early-stage clinical trial regulatory navigation. Academic medical centers and contract research organizations in the metro area require specialized guidance for breakthrough device designation strategy.
California
Venture-backed startups in the Bay Area medical technology corridor purchase subscription-based FDA guidance tracking to normalize compliance spending ahead of Series B financing. San Diego's concentration of PMA-experienced regulatory professionals supports cardiovascular and diagnostic device sponsors.
North America Medical Device Regulatory Affairs Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the regulatory services landscape. The market structures around three tiers: integrated clinical research organizations with regulatory divisions, pure-play regulatory consultancies, and technology-enabled platform providers. Consolidation pressure intensifies as sponsors seek unified clinical and regulatory strategy. Dominant competitive moves include strategic partnerships between CROs and specialized regulatory boutiques, plus technology licensing for submission automation platforms.
Within the integrated CRO tier, IQVIA and Laboratory Corporation of America Holdings exemplify scale-driven positioning through expansive laboratory networks and data infrastructure. ICON plc occupies a specialized niche at the drug-device boundary, representing the combination product consulting archetype. These three entities anchor the premium service segment where sponsors consolidate vendor relationships under unified clinical-regulatory strategies.
| Leading Market Players |
|---|
| ICON plc |
| IQVIA |
| Laboratory Corporation of America Holdings |
| Emergo |
| Freyr |
| Medpace |
| Promedica International |
| Integer Holdings Corporation |
| SGS |
| Others |
Value Network & Pricing Analysis
Horizontal consolidation among regulatory consulting boutiques anchors supply positioning and pricing power across the North American medical device regulatory affairs landscape. This integration pattern concentrates specialized FDA interaction expertise within fewer entities, enabling premium capture for breakthrough designation strategy while compressing margins for routine 510(k) preparation services.
Pricing Analysis
Project-based consulting fees with outcome-contingent components dominate revenue models for PMA and De Novo classification support. Price differentiation rests on FDA meeting success rates and predicate device search sophistication, with venture-backed startups in California and Massachusetts exhibiting highest price sensitivity due to Series B financing constraints. Cost compression in routine 510(k) preparation is intensifying because machine learning-based submission tools are displacing manual documentation workflows. Established orthopedic manufacturers in Minnesota demonstrate lowest price sensitivity, prioritizing regulatory certainty over per-project cost minimization.
Supply Chain Analysis
Direct-to-device-manufacturer channels handle enterprise sponsor demand, while platform-mediated marketplaces connect mid-sized manufacturers with freelance regulatory specialists. Supply concentrates in the United States and Canada, with regulatory talent pools anchored in Boston, San Diego, and Toronto metro areas. Raw material dependencies include ISO 10993-compliant biocompatibility testing laboratory capacity, predicate device database access, and real-world evidence generation infrastructure. Single-source vulnerability in specialized FDA interaction strategists creates bottleneck risk during PMA submission surges for AI-enabled diagnostics. Distribution runs through integrated CRO networks, pure-play regulatory consultancies, and emerging software-enabled platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Medical Device Regulatory Affairs Market functions as a regulatory compounder, with FDA's pending Quality System Regulation alignment with ISO 13485:2016 creating sustained compliance service demand across the projection horizon.
For Market Incumbents: Lock in specialized talent through retention structures targeting PMA-experienced professionals concentrated in Boston and San Diego. Deepen captive biocompatibility testing capabilities to reduce third-party laboratory dependency and compress client timelines. Vertical integration into real-world evidence generation infrastructure defends against software-enabled platform entrants displacing routine submission preparation work. For New Entrants and Emerging Players: Capture Health Canada priority review pathway specialization as US sponsors establish Toronto satellite offices for cross-border submission synchronization. Target mid-sized orthopedic manufacturers in Minnesota and Indiana seeking reduced external consulting dependency through regulatory technology platform adoption. A software-as-a-service go-to-market angle with predicate device search automation enables rapid scale without proportional headcount expansion. For Investors and Strategic Acquirers: Roll-up economics work for regulatory consulting boutiques because FDA interaction expertise remains geographically concentrated and founder-dependent. The five-to-ten year viability window favors platforms consolidating fragmented specialty practices under unified quality management systems. Acquisition targets should demonstrate breakthrough designation track records and Health Canada parallel review capabilities. The signal to watch is FDA's laboratory developed test rulemaking implementation, which will redraw jurisdictional boundaries and redirect diagnostic sponsor spending.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Automation | Machine learning platforms absorb predicate device search tasks previously requiring manual consultant hours. |
| Health Canada Parallel Review | Toronto satellite offices enable US sponsors to access accelerated AI diagnostic pathways. |
| ISO 13485:2016 Certification Investment | Unified quality management systems reduce duplicate documentation for cross-border manufacturers. |
| Real-World Evidence Infrastructure | Post-market surveillance capabilities support FDA's software pre-certification pilot requirements. |
| Biocompatibility Testing Laboratory Expansion | Captive ISO 10993 capacity compresses premarket timelines constrained by third-party backlogs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs directors, FDA submission specialists, venture capital investors in medical technology, and hospital procurement managers with secondary validation. FDA 510(k) and PMA submission databases, Health Canada Medical Devices Bureau filings, ISO certification registries, and venture financing disclosures anchored the data foundation. Bottom-up service provider revenue estimates and top-down market sizing triangulated volume and value outputs.
Segment-weighting approaches distributed value across consulting services, regulatory submissions, compliance audits, and quality assurance based on documented sponsor spending patterns. Technology adoption curves for software solutions and data analytics were modeled separately from traditional service delivery. CAGRs derived from historical growth trajectories adjusted for regulatory milestone impacts, with AI-enabled diagnostic PMA volume and ISO 14971 harmonization timing serving as key forecast inputs across the modeling period.
Regulatory rulemaking delays, biocompatibility testing laboratory capacity constraints, and predicate device obsolescence acceleration are the dominant revision risks. Forecasts reflect assumptions regarding FDA's Quality System Regulation alignment timeline and Health Canada's digital health priority review expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Gel Implants Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market