
 Cranial Stabilization Devices Market | 2026-2036
Cranial Stabilization Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cranial Stabilization Devices Market Intelligence
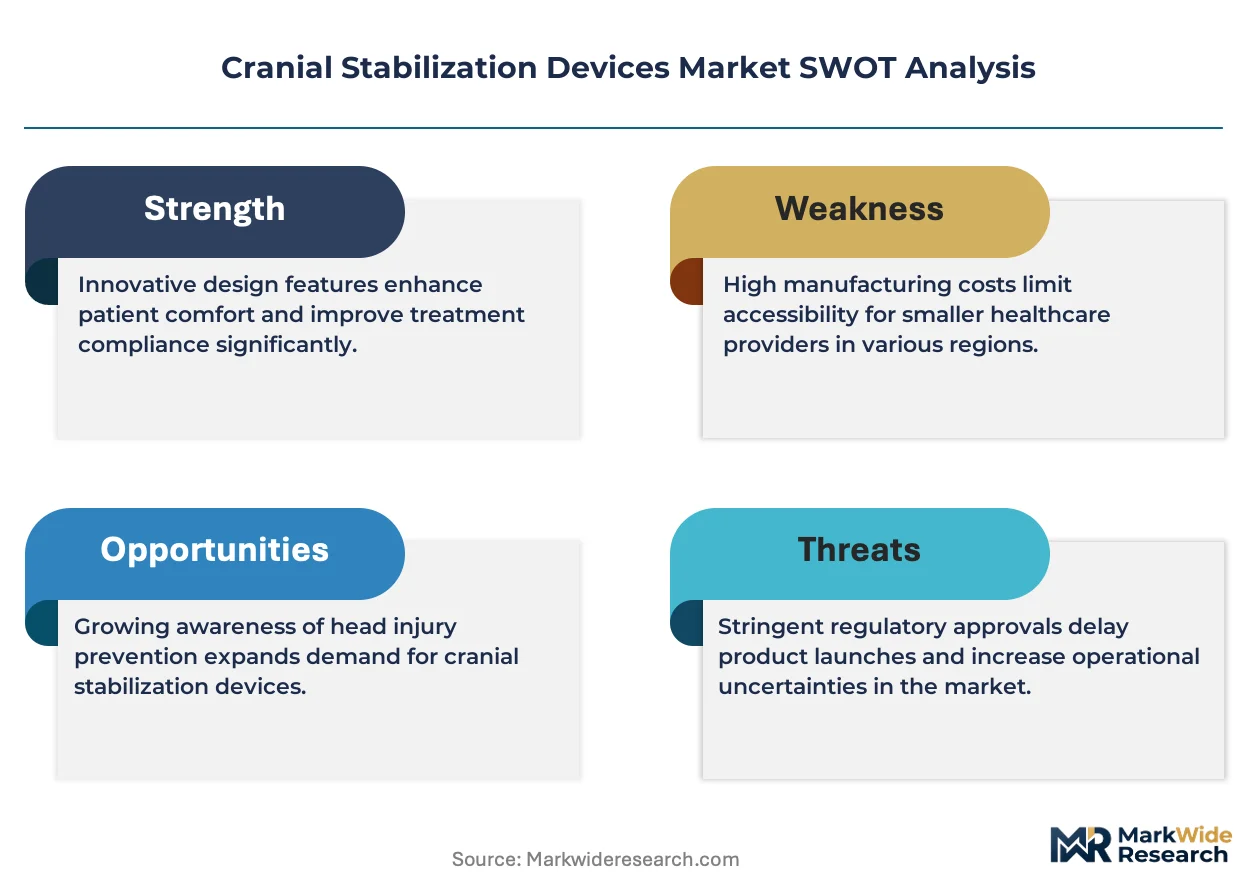
The substitution of traditional metal components with advanced radiolucent composites is consolidating the design of modern cranial stabilization systems. This shift favors manufacturers with strong materials science capabilities. Integra LifeSciences Corporation leverages its broad portfolio in neurosurgery to offer integrated solutions. Medtronic specializes in devices that integrate with its larger neuro-navigation platforms, while Stryker competes through its extensive hospital distribution network.
Cranial stabilization devices are mechanical apparatuses that immobilize a patient's head during neurosurgical procedures. These systems use a base unit and a skull clamp with pins to achieve rigid fixation, ensuring a stable surgical field. Hospitals constitute the primary end-user segment, driving demand for both fixed and adjustable systems. Neurosurgery applications represent the largest use case, followed by specialized trauma surgery.
Product approval is governed by bodies like the U.S. FDA, which typically requires 510(k) clearance. In Europe, compliance with the Medical Device Regulation (MDR) and obtaining a CE marking are mandatory for market access. These frameworks enforce strict standards for material biocompatibility and mechanical integrity. Future competitive positioning will depend on successfully integrating devices with advanced intraoperative imaging technologies.
Market Dynamics
The imperative for compatibility with intraoperative imaging technologies like MRI and CT is the central force shaping the market. This pressure drives material science innovation away from traditional metals toward advanced radiolucent composites for enhanced surgical visualization and precision.
Growth Catalysts
- Neurosurgery Volume:A rising incidence of neurological disorders and traumatic brain injuries in developed nations like Japan and Germany directly increases the volume of complex cranial procedures, sustaining core demand for stabilization systems.
- Radiolucent Material Adoption:The technological shift toward carbon fiber and PEEK composites improves intraoperative imaging quality, creating replacement demand from advanced surgical centers seeking to eliminate imaging artifacts caused by metal components.
- Minimally Invasive Procedures:The adoption of minimally invasive neurosurgical techniques requires highly precise patient positioning, which in turn supports demand for advanced, multi-axis adjustable cranial stabilization systems that facilitate such approaches.
Market Restraints
- High Device Cost:The significant capital investment required for advanced, radiolucent cranial stabilization systems limits adoption in hospitals with constrained budgets, particularly outside of specialized, high-volume neurosurgery centers.
- Material Sourcing Constraints:Reliance on specialized medical-grade composites, often sourced from a concentrated supplier base, creates vulnerability to supply chain disruptions and input price volatility for key raw materials.
- Sterilization and Maintenance Burden:Reusable components of these systems demand stringent and complex sterilization protocols, posing an operational burden and recurring cost for hospital sterile processing departments, which can deter initial purchase.
Strategic Opportunities
- Pediatric Neurosurgery:Developing scaled-down devices specifically designed for the anatomical requirements of pediatric patients represents an underserved market segment with distinct clinical needs not met by adult-sized systems.
- Integration with Surgical Robotics:The convergence of stabilization systems with robotic-assisted surgery platforms offers an opportunity to create highly automated and precise procedural workflows, appealing to technology-forward hospitals.
- Healthcare Infrastructure in Brazil:Expanding distribution and service networks into Brazil, where healthcare infrastructure is modernizing and private hospital investment is growing, provides a key growth avenue for established device manufacturers.
Industry Challenges
- Specialized Training Requirements:The proper and safe application of advanced stabilization systems requires specialized training for surgical staff, and a shortage of experienced personnel can slow the adoption and effective use of new technologies.
- EU MDR Compliance Timelines:Securing CE marking under the European Union's stringent Medical Device Regulation (MDR) involves lengthy and costly clinical evidence generation, delaying new product launches in the European market.
- System Interoperability:Ensuring seamless functional integration of a stabilization device with different brands of neuro-navigation systems and intraoperative imaging equipment presents a persistent technical challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranial Stabilization Devices Market |
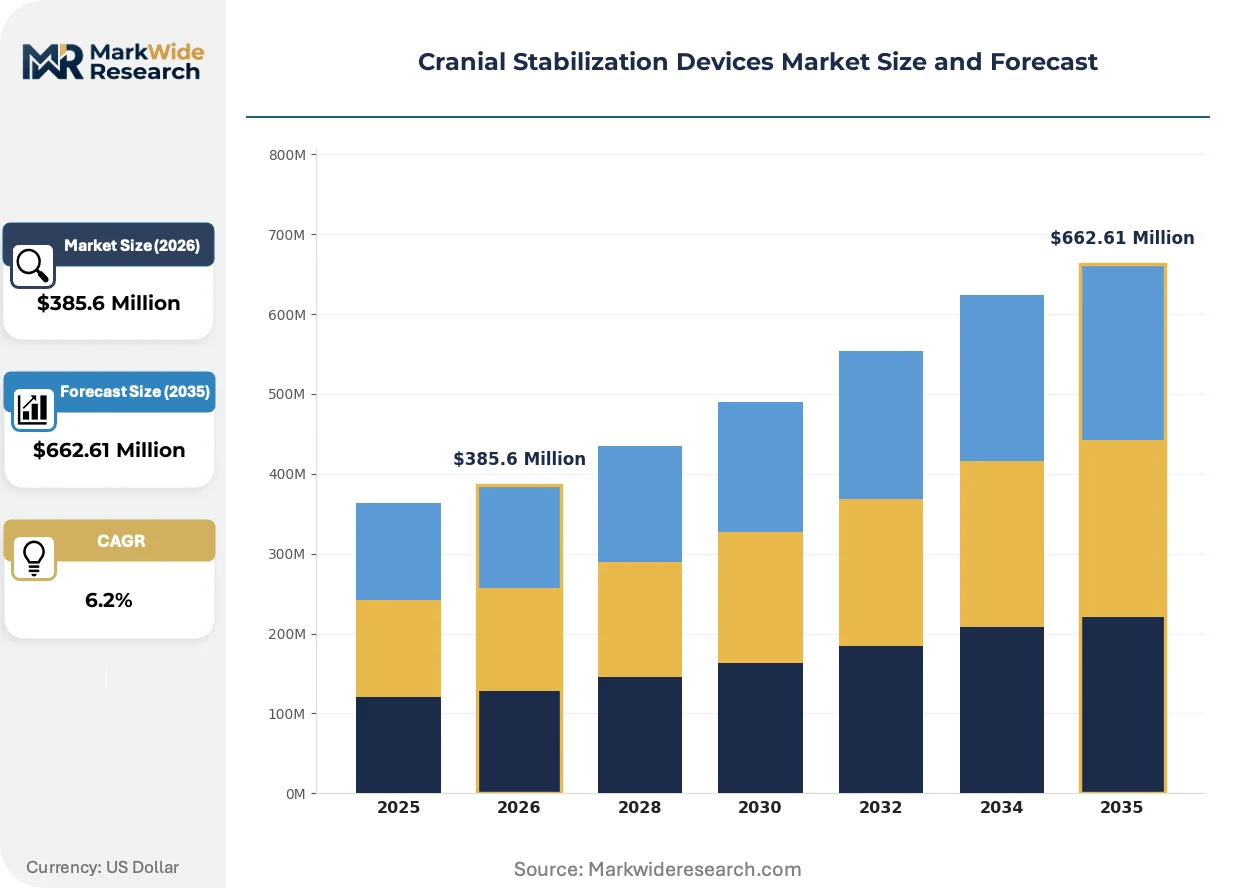
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $662.61 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Systems, Portable Systems, Adjustable Systems, Customizable Systems End User: Hospitals, Surgical Centers, Rehabilitation Facilities, Home Care Application: Trauma Surgery, Neurosurgery, Elective Surgery, Pediatric Surgery Material: Plastic, Metal, Foam, Composite |
| Companies Covered | Integra LifeSciences Corporation, Stryker, Medtronic, Johnson & Johnson, Zimmer Biomet Holdings, Inc., KLS Martin Group, B. Braun SE, evonos GmbH & Co. KG, OsteoMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranial Stabilization Devices Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of mechanical stabilization with digital surgical ecosystems. This movement prioritizes data-rich, intraoperative feedback loops and stricter regulatory oversight to enhance patient safety and surgical precision.
Radiolucent composite materials, such as carbon fiber, provide rigid head fixation without creating artifacts on medical scans. Specialized neurosurgery and trauma centers are the primary adopters, seeking to maximize the utility of their intraoperative imaging suites. This material science innovation is converging with neuro-navigation software to enable real-time, image-guided surgical adjustments.
Implementation of the European Union's Medical Device Regulation (MDR) imposes rigorous requirements for clinical evidence and post-market surveillance. This regulation elevates the compliance burden, demanding extensive technical documentation and lifecycle management from manufacturers. Devices with a long history under the previous directive are most affected, requiring new investment in clinical data to maintain CE marking.
Hospital procurement patterns are moving towards bundled purchasing of neurosurgical equipment from a single vendor. This trend disadvantages standalone device makers, favoring large companies that can offer integrated packages including navigation systems and imaging. This behavior is most prominent in large US hospital networks, where value analysis committees prioritize vendor consolidation and system interoperability.
Cranial Stabilization Devices Market Segmentation
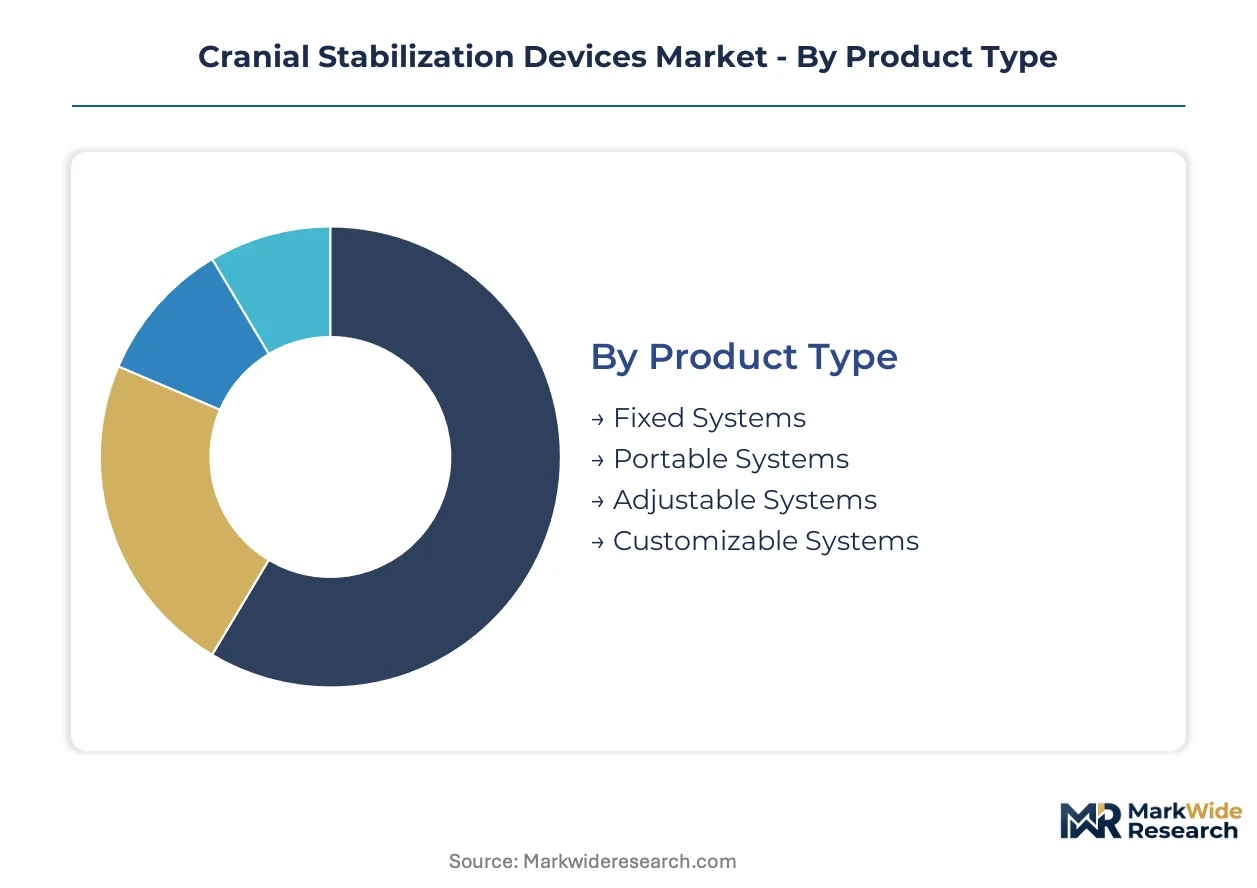
The cranial stabilization devices market segments reflect diverse clinical needs and technological advancements across neurosurgical practices. Understanding these distinctions helps manufacturers align product development with specific procedural demands and end-user capabilities, ensuring optimal patient outcomes during complex cranial surgeries.
Product Type:
Buyer decision drivers for cranial stabilization systems often center on the required level of surgical precision and the flexibility needed for various procedural approaches.
- Adjustable Systems:These devices offer multi-axis positioning and fine-tuning capabilities, crucial for minimally invasive neurosurgical techniques that demand highly precise patient head positioning. Demand concentrates in specialized neurosurgery centers in the United States and Germany, where advanced procedures are common.
- Fixed Systems:Designed for rigid, unyielding head immobilization, fixed systems provide a stable surgical field for standard open cranial procedures, prioritizing absolute immobility over positional adaptability. Hospitals in developed nations like Japan and Canada maintain consistent demand for these dependable systems.
- Portable Systems:These compact and lighter stabilization units facilitate rapid deployment in emergency trauma settings or for procedures requiring patient transport during surgery. Their utility is primarily for mobile surgical units and smaller regional hospitals.
- Customizable Systems:Tailored to specific patient anatomies or unique surgical requirements, these systems offer specialized configurations for complex or rare cranial conditions.
Adjustable Systems leads on scale; Fixed Systems leads on momentum.
End User:
The volume of complex neurosurgical procedures and the available infrastructure significantly determine end-user adoption patterns for cranial stabilization devices.
- Hospitals:These institutions represent the primary end-user segment, driven by the high volume of neurosurgical cases, comprehensive surgical departments, and established procurement channels for medical devices. Large hospital networks in the United States and specialized university hospitals in Germany drive substantial demand.
- Surgical Centers:Outpatient surgical centers and specialized neurosurgical clinics increasingly adopt these devices for less invasive or elective cranial procedures, seeking efficiency and precision. These centers often prioritize systems compatible with their existing imaging suites.
- Rehabilitation Facilities:While not direct surgical users, some rehabilitation centers utilize specialized head stabilization equipment for post-operative care or long-term management of neurological conditions.
- Home Care:This segment typically involves simpler, non-invasive head support devices for patients with chronic neurological conditions, distinct from surgical stabilization.
Hospitals command the largest share; Surgical Centers are expanding most quickly.
Application:
Procedural requirements and the urgency of intervention define the application segments for cranial stabilization devices.
- Neurosurgery:This application constitutes the largest use case, encompassing a wide range of procedures from tumor resections to vascular repairs, where precise and stable head fixation is paramount. Demand is consistently high in countries with advanced neurosurgical capabilities, including the United States and France.
- Trauma Surgery:Cranial stabilization devices are critical in managing severe traumatic brain injuries, providing essential head immobilization during emergency interventions and subsequent reconstructive surgeries. Specialized trauma centers in Germany and the United Kingdom frequently utilize these systems.
- Elective Surgery:Procedures such as craniotomies for epilepsy or chronic pain management, while planned, still require meticulous head positioning for optimal surgical access and patient safety.
- Pediatric Surgery:This specialized application demands scaled-down devices designed to accommodate the unique anatomical considerations of pediatric patients, requiring precise, gentle fixation.
Neurosurgery holds the largest market segment; Trauma Surgery exhibits rapid growth.
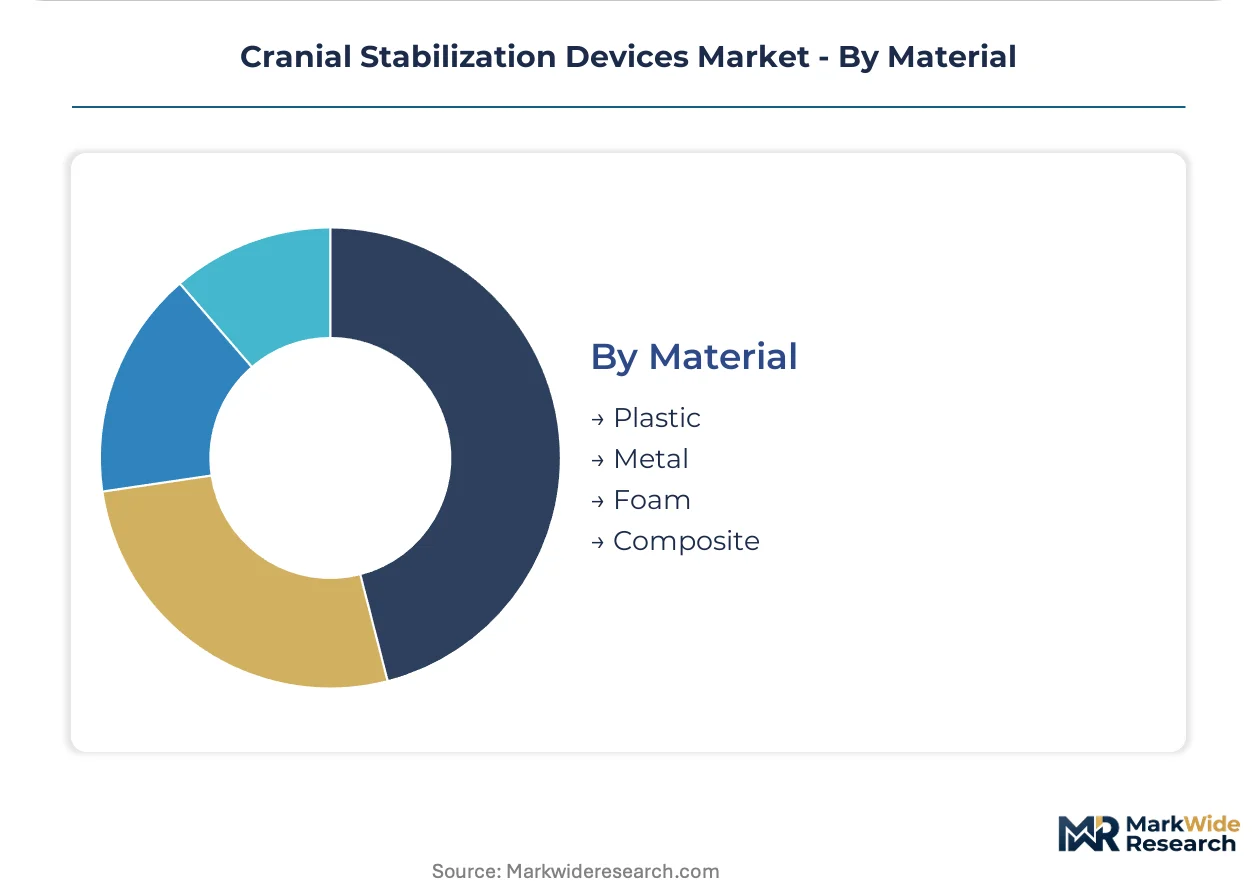
Material:
Performance characteristics, particularly radiolucency and biocompatibility, dictate material selection in cranial stabilization devices.
- Composite:Advanced radiolucent composites, such as carbon fiber and PEEK, are gaining prominence due to their compatibility with intraoperative MRI and CT scans, eliminating imaging artifacts caused by traditional metals. Specialized neurosurgery centers in advanced healthcare markets like the United States and Sweden are leading this material transition.
- Metal:Traditional metal components, primarily stainless steel or aluminum alloys, offer high rigidity and durability, forming the backbone of many established stabilization systems. Hospitals globally continue to rely on these robust, proven materials for general neurosurgical applications.
- Plastic:Certain plastic components are used for non-load-bearing parts or for systems where radiolucency is desired but extreme rigidity is not the primary requirement.
- Foam:Foam materials typically serve as padding or cushioning elements within stabilization systems, enhancing patient comfort and distributing pressure.
Metal materials represent the foundational segment; Composite materials show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized surgical centers in the United States drive significant demand for cranial stabilization devices. These advanced facilities perform a high volume of complex neurosurgical procedures, necessitating precise patient positioning. European and Asian healthcare markets also exhibit robust adoption of these critical medical technologies.
United States
Large hospital networks in the United States drive substantial demand for cranial stabilization devices. U.S. FDA 510(k) clearance ensures strict material biocompatibility and mechanical integrity. Major metropolitan areas like New York and Los Angeles prioritize bundled purchasing of advanced systems.
Germany
Rising incidence of neurological disorders in Germany fuels demand for complex cranial procedures. Compliance with the EU Medical Device Regulation (MDR) and CE marking are mandatory for market access. Specialized university hospitals in cities like Munich and Berlin are early adopters of advanced radiolucent systems.
Japan
Consistent demand for fixed systems characterizes the Japanese cranial stabilization market. PMDA approval processes ensure device safety and efficacy for all medical technologies. Major medical centers in Tokyo and Osaka maintain steady procurement for dependable neurosurgical tools.
France
Advanced neurosurgical capabilities in France necessitate precise head fixation for complex interventions. The ANSM oversees medical device market access and post-market surveillance within the country. University teaching hospitals in Paris and Lyon consistently invest in high-precision neurosurgical equipment.
Canada
Established procurement channels across Canada support the adoption of cranial stabilization devices. Health Canada regulates medical devices for market entry and ensures patient safety. Large hospital networks in Toronto and Montreal integrate these stabilization devices into their neurosurgical departments.
Cranial Stabilization Devices Market Key Industry Players
Global majors compete with regional champions across technological integration and distribution reach in the cranial stabilization devices market. The competitive structure features a tier of diversified medical technology conglomerates alongside specialized neurosurgical device manufacturers. These larger entities leverage their extensive resources for continuous product innovation, particularly in radiolucent materials and imaging compatibility. Companies often employ strategic partnerships to expand their product portfolios and invest in M&A for technology acquisition.
At the scale-driven end, Medtronic and Stryker exemplify large medical technology providers leveraging extensive distribution networks and integrated platforms. Medtronic, a US-based corporation, occupies a position focused on device integration with broader neuro-navigation systems. Stryker, another US-based entity, represents a company that capitalizes on its extensive hospital distribution network for market penetration. Integra LifeSciences Corporation, also headquartered in the US, anchors a segment of specialists with broad neurosurgery portfolios offering integrated solutions. These entities collectively shape the market's competitive dynamics.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| Stryker |
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet Holdings, Inc. |
| KLS Martin Group |
| B. Braun SE |
| evonos GmbH & Co. KG |
| OsteoMed |
Cost & Logistics Intelligence
The shift to radiolucent composite materials for cranial stabilization devices simultaneously elevates material costs and concentrates sourcing. This innovation demands specialized manufacturing processes, influencing overall product pricing.
Pricing Analysis
Input costs from specialized radiolucent composites are increasingly passed through to end-users in the cranial stabilization market. The dominant pricing model is per-unit transactional, influenced by quality grade, customization level, and bundled after-sales service. Pricing pressure stems from the rising expense of advanced materials and the substantial R&D investments required for device integration. Public hospitals with constrained budgets exhibit the highest price sensitivity, while specialized neurosurgery centers prioritize advanced features over cost.
Supply Chain Analysis
Logistics and freight costs significantly influence the final price of cranial stabilization devices, especially for specialized materials. Geographic supply concentration for advanced components centers on the United States, Germany, and Japan. The market relies heavily on raw materials like carbon fiber, PEEK, and specific medical-grade alloys. Single-source vulnerability for specialized composites presents a structural supply chain risk. Distribution runs through established hospital networks and direct sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cranial stabilization devices market functions as a regulatory compounder, with the EU Medical Device Regulation (MDR) driving demand for stricter compliance and more robust product development. This regulation elevates standards for material biocompatibility and clinical evidence.
For Market Incumbents: Cement market leadership by deepening integration with advanced neuro-navigation platforms and expanding global distribution networks. This defends against emerging specialized material providers offering niche solutions. Invest heavily in R&D for enhanced intraoperative imaging compatibility to maintain a competitive edge. Control of the hospital procurement channel remains paramount.
For New Entrants and Emerging Players: Begin with underserved niches like pediatric neurosurgery or customizable systems for rare cranial conditions. Specialized trauma surgery represents a penetrable segment due to urgent demand for rapid deployment solutions. Strategic partnerships with specialized surgical centers offer an effective go-to-market angle. Focus on cost-effective radiolucent materials.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized innovators with strong materials science capabilities, offering sustained growth over the next 5-10 years. These companies often possess proprietary radiolucent composite technologies. A key signal to watch is successful 510(k) clearance or CE marking for novel radiolucent composite devices. Invest in entities with robust regulatory compliance frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Radiolucent Composite Portfolio | This initiative addresses the imperative for intraoperative imaging compatibility in neurosurgery departments. |
| Integrate with Robotic Surgery Platforms | This convergence creates highly automated procedural workflows, appealing to technology-forward hospitals in the United States. |
| Invest in Pediatric Device R&D | This targets an underserved market segment with distinct anatomical requirements for cranial stabilization. |
| Accelerate EU MDR Compliance | This ensures continued market access and new product launches within the European healthcare markets. |
| Strengthen Distribution in Brazil | This capitalizes on modernizing healthcare infrastructure and growing private hospital investment in Brazil. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform this analysis. Primary research involved discussions with neurosurgeons, hospital procurement managers, medical device engineers, and regulatory affairs specialists. Secondary data sources included U.S. FDA filings, EU MDR guidance documents, medical journal publications, and neurosurgical society reports. Bottom-up and top-down triangulation validated all market size and growth estimates.
Segment weighting across product type, end user, application, and material dimensions defined the analytical framework across the analysis window. Regional adoption patterns were also modeled. Compound annual growth rates were derived based on historical trends and projected technological advancements. Neurosurgery procedure volumes and radiolucent composite material costs served as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including specific hospital system budget allocations and individual surgeon preferences. Forecasts reflect assumptions, but unforeseen supply chain disruptions or rapid competitive entry could revise projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Microscope Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Lactation Massager Market
Medical Devices
Solar Surgical Light Market