
 Medical Device and Equipment Tags Market | 2026-2036
Medical Device and Equipment Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device and Equipment Tags Market Foresight
Hospital procurement departments are collapsing legacy barcode-only purchasing in favor of RFID-enabled tag ecosystems. Zebra Technologies Corporation dominates enterprise-grade printing and encoding hardware for this transition. Avery Dennison Corporation specializes in adhesive substrate engineering that survives repeated sterilization cycles. 3M Company anchors hospital trust through decades of clinical supply chain partnerships.
Medical device and equipment tags are identification substrates affixed to instruments, devices, or packaging to enable traceability, authentication, and data capture across healthcare workflows, typically incorporating ISO 15415-compliant barcode symbologies or EPC Gen2 RFID inlays operating in the 860-960 MHz UHF band. Their primary commercial purpose is eliminating manual documentation errors while satisfying regulatory traceability mandates. RFID Tags command premium positioning due to real-time location system integration in operating theaters, while Passive Tags sustain volume leadership through lowest unit cost in high-disposable applications. Asset Tracking use cases generate recurring tag consumption as hospitals refresh circulating device pools.
The FDA enforces Unique Device Identification rules through GUDID database submission requirements, directly expanding serialized label demand. EUDAMED in Europe and Japan's PMDA traceability guidelines impose parallel compliance layers that manufacturers must satisfy for market access. GS1 standards provide the interoperable data syntax bridging these regional frameworks. Stakeholders must monitor which regulatory body moves first on mandating machine-readable tag durability standards for reusable surgical instruments.
Market Dynamics
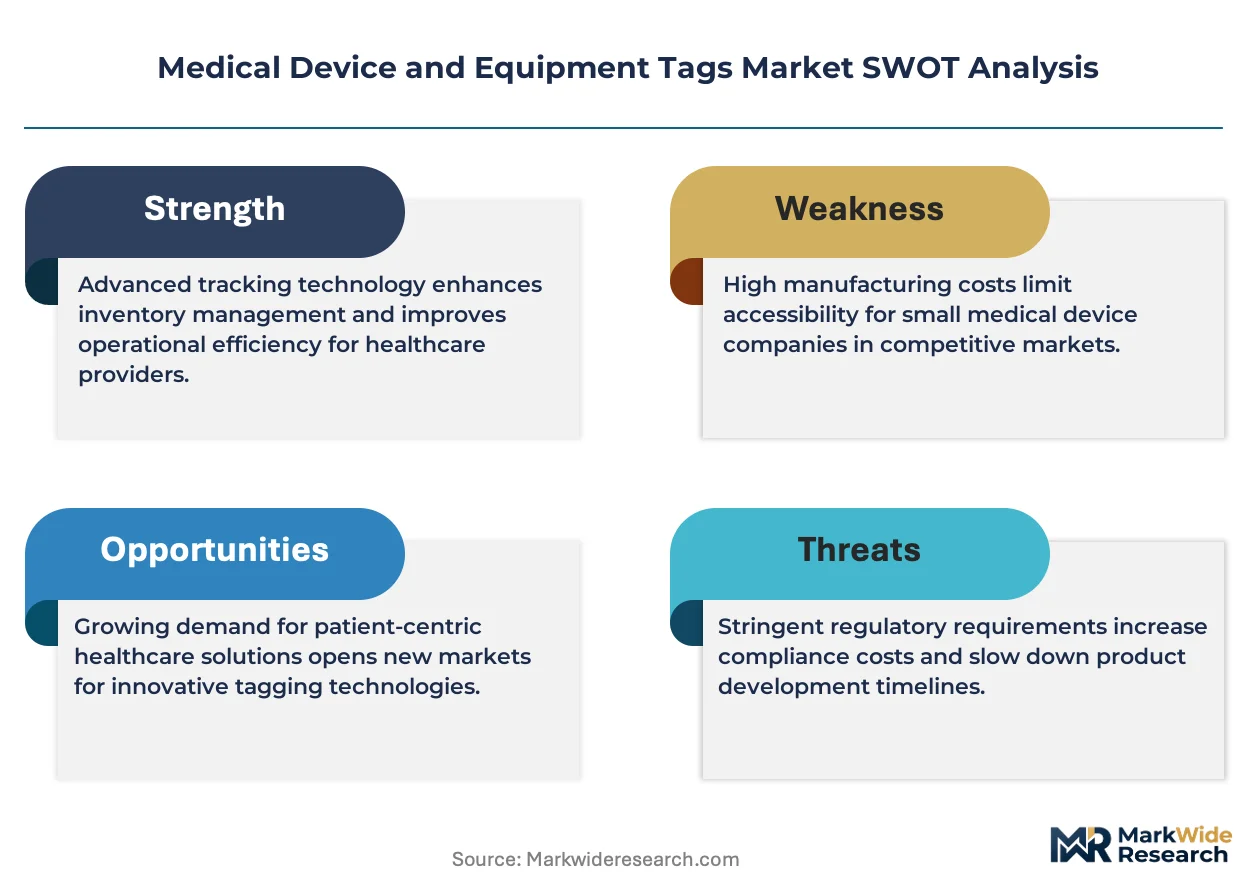
Hospital asset management systems are forcing a wholesale substrate upgrade from printed barcode labels to RFID inlays capable of withstanding autoclave sterilization cycles, compressing supplier margins while expanding total addressable spend per bed.
Growth Catalysts
- FDA UDI Mandate:The GUDID database submission requirement forces manufacturers to serialize every device label, directly expanding tag volumes for Class II and III medical devices distributed in the United States.
- EUDAMED Alignment:Germany's surgical instrument identification protocols are tightening traceability standards across European hospital systems, creating compliance-driven replacement cycles for legacy labeling.
- Real-Time Location Systems:Operating theater workflow optimization in US academic medical centers is pulling UHF RFID tags into asset tracking infrastructure at the department level.
Market Restraints
- Silicon Supply Concentration:RFID chip fabrication concentrates in East Asian foundries, exposing tag converters to lead time volatility and input cost spikes during semiconductor capacity constraints.
- Substrate Cost Structure:Medical-grade adhesive formulations containing platinum-cured silicones command 3-4x standard label material costs, compressing margins on sterilization-survivable products.
- Technical Durability Ceiling:Passive UHF RFID inlays degrade after 100+ autoclave cycles, limiting reusable surgical instrument tagging to semi-disposable applications despite sustainability pressures.
Strategic Opportunities
- Japan PMDA Traceability:The Pharmaceuticals and Medical Devices Agency's device tracking guidelines are expanding serialized label requirements beyond implants to diagnostic equipment, opening a premium market for GS1-compliant RFID solutions.
- Sensor-Tag Convergence:Temperature-logging RFID labels integrating NFC bridges are capturing cold chain verification contracts for biologics distribution, merging authentication with environmental monitoring.
- Direct Hospital Contracting:Bypassing group purchasing organizations through enterprise RFID platform partnerships lets tag vendors capture recurring consumable streams tied to asset management software subscriptions.
Industry Challenges
- ISO 15415 Verification Talent:Few print shops maintain certified operators for 2D Data Matrix grading, creating bottlenecks as FDA UDI compliance deadlines compress production timelines for device manufacturers.
- Legacy HIS Integration:Hospital information systems running 1990s-era inventory modules require expensive middleware development to parse EPC Gen2 RFID data streams, delaying ROI realization for asset tracking deployments.
- Multi-Regulatory Labeling:Manufacturers serving US, EU, and Japan markets must maintain parallel label SKUs with divergent data carrier requirements, fragmenting production runs and inflating working capital needs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device and Equipment Tags Market |
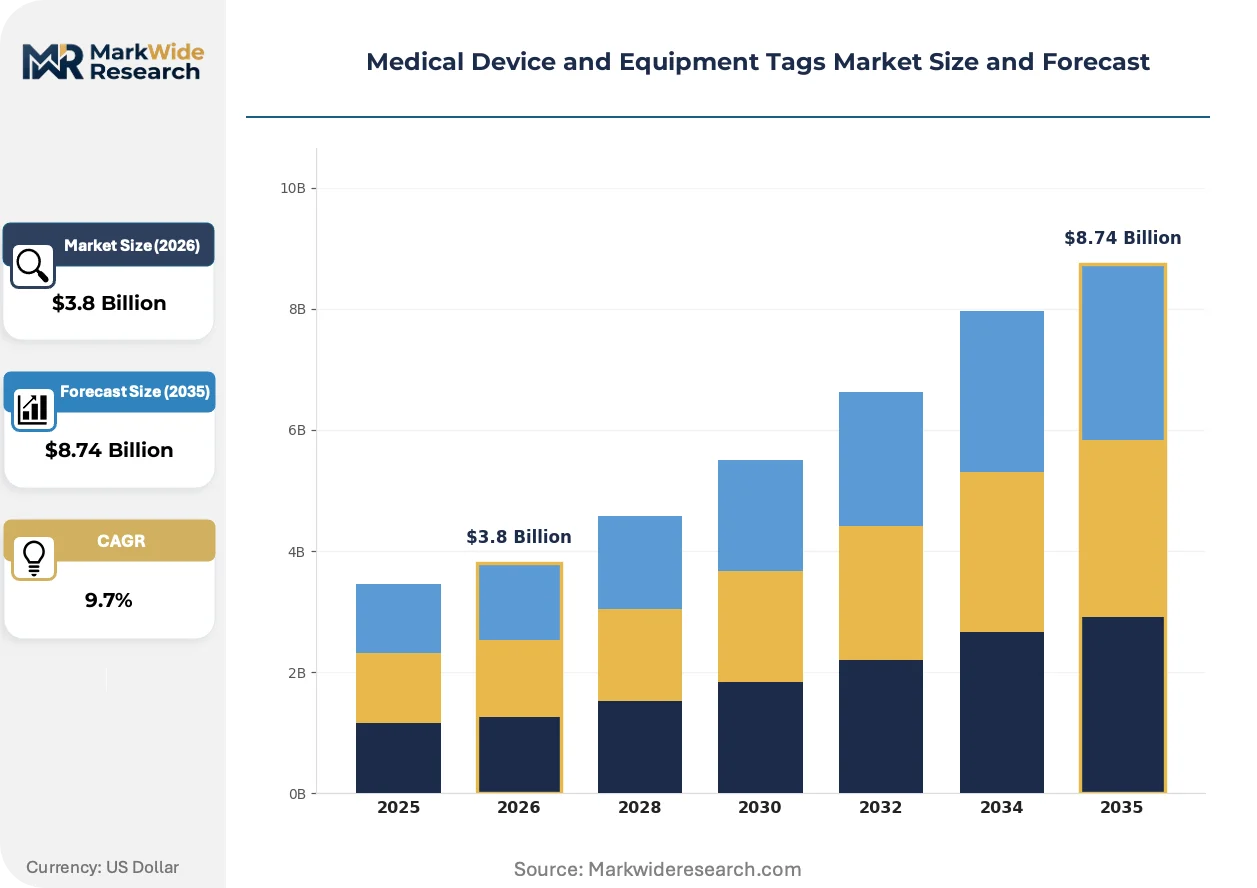
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RFID Tags, Barcode Labels, NFC Tags, QR Codes Technology: Active Tags, Passive Tags, Hybrid Tags, Smart Labels Use Case: Asset Tracking, Inventory Management, Patient Monitoring, Surgical Instrument Identification End User: Hospitals, Clinics, Labs, Research Facilities |
| Companies Covered | 3M Company, Zebra Technologies Corporation, Avery Dennison Corporation, CCL Industries, Multi-Color Corporation, GS1, Honeywell International, Impinj, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device and Equipment Tags Market Shifts & Advancements
Active temperature-sensing labels and blockchain-anchored authentication are converging with traditional identification substrates, transforming tags from passive data carriers into dynamic supply chain nodes.
Laser-etched direct part marking on surgical stainless steel is displacing adhesive labels for instruments exceeding 500 autoclave cycles. Academic medical centers in the US Northeast are adopting this technology fastest. The shift is compressing addressable volume for high-durability RFID substrates while expanding service revenue for laser system integrators.
The EU MDR's Article 27 unique device identifier requirements are forcing manufacturers to redesign label layouts for symbol density and human-readable redundancy. Industrial consequence includes capital expenditure on vision inspection systems for automated grading. Implantable device manufacturers face the tightest compliance timelines and are outsourcing label conversion to specialized converters.
Hospital supply chain departments are consolidating vendor relationships around integrated RFID platform providers, collapsing standalone label purchasing. The shift displaces commodity barcode suppliers in favor of encoding-hardware-software bundles. This pattern is most visible in US health systems exceeding 500 beds with centralized procurement authority.
Medical Device and Equipment Tags Market Segmentation
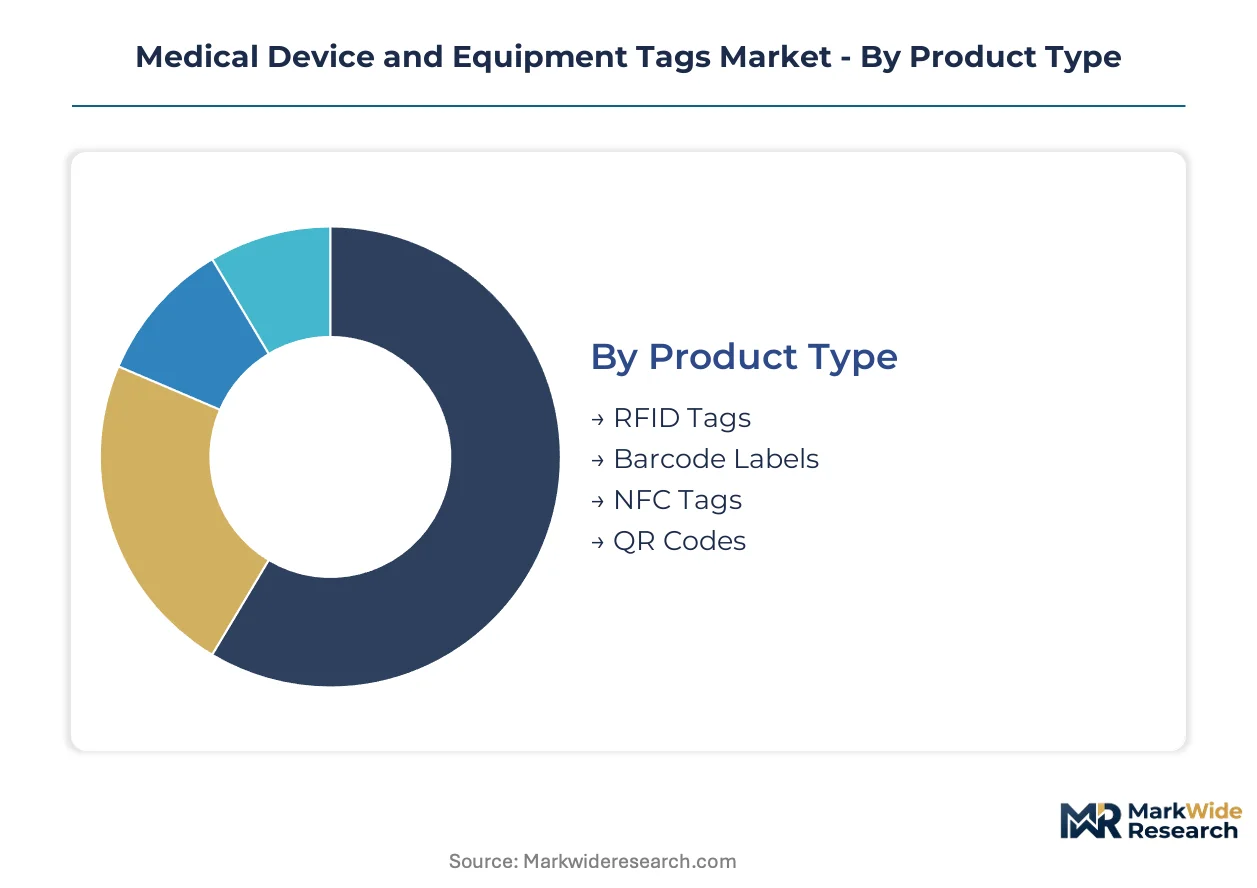
Tag selection in medical environments hinges on sterilization survivability, read-range requirements, and integration with legacy hospital information systems. Procurement teams evaluate total cost of ownership across adhesive degradation curves and RFID chip replacement cycles rather than unit price alone.
Product Type:
RFID inlays face intensifying substitution pressure from laser-etched direct part marking on surgical stainless steel, particularly for instruments exceeding 500 autoclave cycles.
- RFID Tags:UHF inlays operating in the 860-960 MHz band embed between medical-grade silicone substrates and polyester facestocks. Academic medical centers in the United States Northeast are pulling these into operating theater asset tracking infrastructure despite per-unit premiums over printed alternatives.
- Barcode Labels:ISO 15415-compliant 2D Data Matrix symbols printed on thermal-transfer substrates remain the default for disposable device packaging. FDA GUDID submission requirements are forcing manufacturers to serialize every label, sustaining volume despite RFID encroachment on reusable instruments.
- NFC Tags:13.56 MHz HF inlays enable smartphone-readable authentication for patient-facing applications.
- QR Codes:Open-source 2D symbologies support consumer-grade verification for home-use devices and post-market surveillance reporting.
Barcode Labels retain volume leadership; RFID Tags hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium active-tag deployments from commodity passive-tag volumes, with hybrid architectures capturing mid-market positioning.
- Active Tags:Battery-assisted UHF transponders with 100-meter read ranges integrate with real-time location systems for high-value mobile equipment. German hospital systems are adopting these for surgical instrument tracking under tightening EUDAMED alignment protocols.
- Passive Tags:Backscatter-dependent inlays without onboard power dominate disposable applications through lowest unit cost. Silicon supply concentration in East Asian foundries exposes converters to lead time volatility during semiconductor capacity constraints.
- Hybrid Tags:Dual-frequency architectures combining UHF RFID with NFC bridges enable both enterprise asset management and consumer smartphone interaction.
- Smart Labels:Temperature-logging substrates with integrated sensors are capturing cold chain verification contracts for biologics distribution.
Passive Tags dominate shipment volumes; Smart Labels are climbing the fastest on sensor-tag convergence.
Use Case:
Application maturity varies sharply, with asset tracking commanding established budgets while surgical instrument identification faces compliance-driven replacement cycles.
- Asset Tracking:Real-time location system integration for mobile medical equipment generates recurring tag consumption as hospitals refresh circulating device pools. US health systems exceeding 500 beds with centralized procurement authority are consolidating vendor relationships around integrated RFID platform providers.
- Inventory Management:Automated replenishment triggering through RFID portal reads reduces stockout incidents in catheterization labs and emergency departments.
- Patient Monitoring:Wearable tag integration with admission-discharge-transfer systems enables automated identity verification at medication administration points.
- Surgical Instrument Identification:Autoclave-survivable tagging for reusable toolsets is compressing addressable volume as laser etching displaces adhesives for high-cycle instruments.
Asset Tracking commands the largest installed base; Surgical Instrument Identification is gaining share fastest on regulatory compliance deadlines.
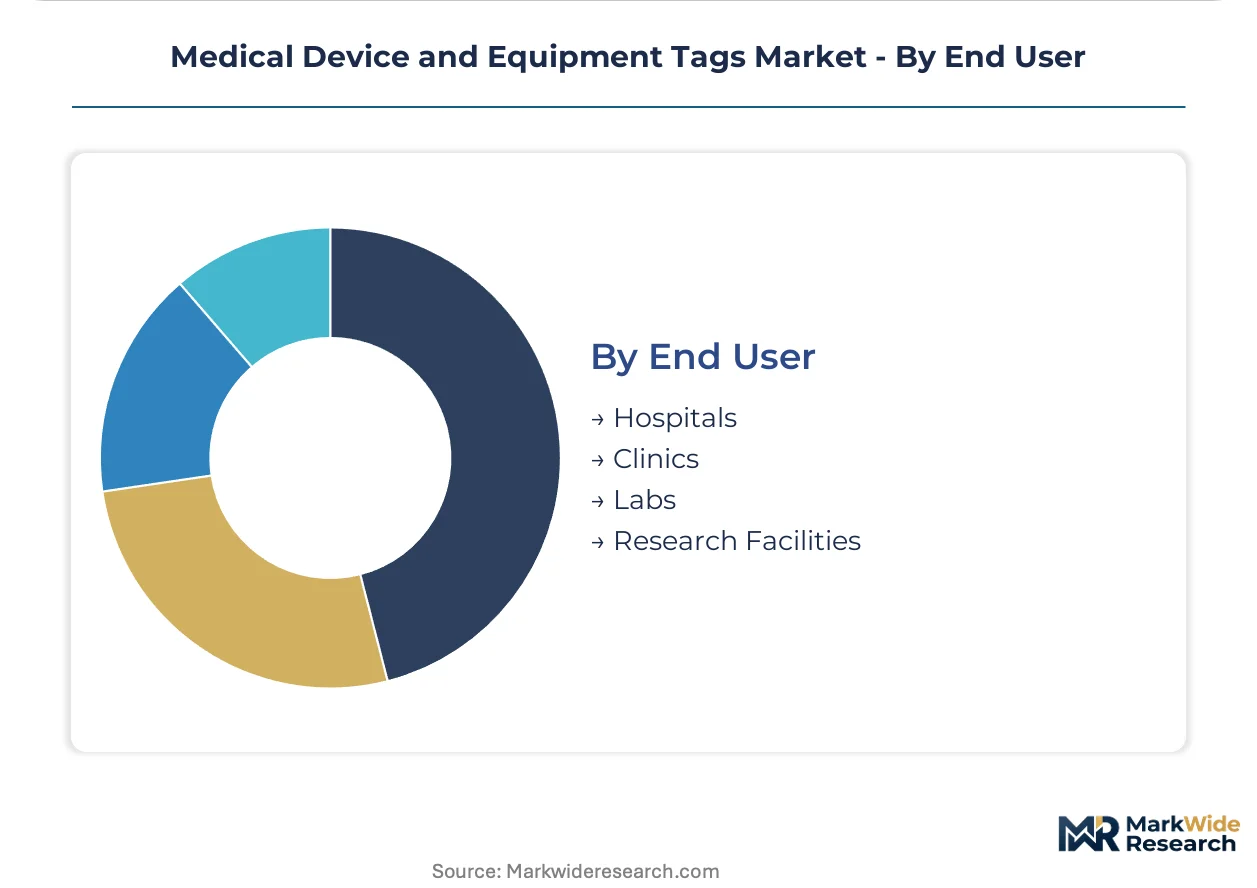
End User:
Customer type determines specification stringency, with hospitals demanding sterilization-grade durability while labs prioritize chemical resistance.
- Hospitals:Enterprise RFID platform deployments spanning multiple departments require middleware development to parse EPC Gen2 data streams into 1990s-era hospital information systems. Procurement departments are collapsing legacy barcode-only purchasing in favor of RFID-enabled tag ecosystems.
- Clinics:Smaller-scale outpatient facilities favor passive UHF tags for capital equipment tracking without real-time location infrastructure.
- Labs:Diagnostic facilities specify chemical-resistant substrates for reagent container tracking and specimen chain-of-custody documentation.
- Research Facilities:Preclinical testing environments utilize serialized labels for GLP-compliant audit trails on experimental device prototypes.
Hospitals anchor demand concentration; Research Facilities are expanding most quickly on preclinical trial volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's biologics distribution network, anchoring RFID tag demand for temperature-sensitive medical devices. This logistics backbone connects sterilization-grade substrate converters to hospital systems across the continent.
United States
Academic medical centers in the Northeast corridor are deploying UHF RFID inlays for operating theater asset tracking. The FDA enforces GUDID database submissions for Class II and III devices, forcing manufacturers to serialize every label. Minneapolis-St. Paul hosts the densest cluster of medical device headquarters, driving localized demand for ISO 15415-compliant printing services.
Germany
Surgical instrument manufacturers in Baden-Württemberg face tightening traceability protocols under EUDAMED alignment requirements. The EU MDR's Article 27 unique device identifier mandates are compressing compliance timelines for implantable device producers. Stuttgart's precision engineering cluster is adopting laser-etched direct part marking for instruments exceeding 500 autoclave cycles.
Japan
The Pharmaceuticals and Medical Devices Agency is expanding serialized label requirements beyond implants to diagnostic equipment. METI's traceability guidelines are pulling GS1-compliant RFID solutions into hospital procurement specifications. Osaka's medical device manufacturing corridor is retrofitting production lines for dual-frequency hybrid tags combining UHF RFID with NFC bridges.
China
NMPA's unique device identification rollout is accelerating domestic tag converter capacity expansion. The Yangtze River Delta's electronics manufacturing base is capturing semiconductor inlay fabrication for regional medical device exporters. Shanghai's free trade zone is piloting blockchain-anchored authentication layers for high-value implant shipments.
Switzerland
Swissmedic's device tracking requirements are converging with EU MDR standards, creating parallel compliance obligations for orthopedic implant manufacturers. The Basel-Zürich corridor's pharmaceutical-medical device hybrid companies are specifying platinum-cured silicone substrates for repeated sterilization cycles. Geneva's precision instrument cluster is sourcing autoclave-survivable tags from specialized European converters.
Medical Device and Equipment Tags Market Competitive Landscape
Concentration sits with diversified adhesive substrate engineers and enterprise encoding hardware specialists. The vendor base stratifies across three tiers: integrated platform providers bundling software-hardware-tag consumables, specialized medical-grade substrate converters, and commodity barcode suppliers facing displacement. Consolidation is accelerating through hospital GPO bypass strategies and RFID platform acquisitions. Capacity expansion concentrates in East Asian semiconductor foundries and European sterilization-grade adhesive formulation facilities.
Among diversified technology conglomerates, 3M Company and Honeywell International occupy positions anchored by decades of clinical supply chain partnerships. Zebra Technologies Corporation exemplifies the enterprise hardware tier, with encoding equipment deployed across US health systems exceeding 500 beds. Avery Dennison Corporation represents specialized substrate engineering, with adhesive formulations engineered for repeated autoclave exposure. Impinj and NXP Semiconductors sit within the semiconductor inlay tier, supplying RFID chips to tag converters worldwide.
| Leading Market Players |
|---|
| 3M Company |
| Zebra Technologies Corporation |
| Avery Dennison Corporation |
| CCL Industries |
| Multi-Color Corporation |
| GS1 |
| Honeywell International |
| Impinj |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for UHF RFID inlays from East Asian foundries concentrate pricing power with semiconductor suppliers while compressing converter margins on sterilization-grade substrates. Hospital procurement departments exploit this volatility through consolidated enterprise contracts that lock in volume pricing across multi-year RFID platform deployments.
Pricing Analysis
Three-tier pricing structure across premium autoclave-survivable, standard thermal-transfer, and economy paper-label levels separates medical-grade silicone substrates from polyester facestocks from disposable packaging grades. Price differentiation hinges on ISO 13485 certification tier and platinum-cured silicone formulation costs. Pricing pressure stems from laser-etched direct part marking displacing adhesive tags for instruments exceeding 500 sterilization cycles. Group purchasing organizations exhibit highest price sensitivity; academic medical centers with centralized procurement authority show lowest sensitivity due to bundled software-hardware contracts.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for RFID chips, while Germany and Switzerland concentrate sterilization-grade adhesive formulation. Medical-grade substrate production draws from platinum-cured silicone suppliers in the Basel-Zürich corridor and polyester film converters in Baden-Württemberg. Single-source vulnerability concentrates in East Asian semiconductor foundries during capacity constraints. Distribution runs through hospital group purchasing organizations and direct enterprise contracts with health systems exceeding 500 beds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser-etched direct part marking on surgical stainless steel threatens adhesive tag volumes for high-cycle instruments, forcing substrate suppliers to defend positioning through durability certification and software integration depth.
For Market Incumbents: Consolidate around autoclave-survivable substrate certification and embedded RFID inlay integration to offset laser etching displacement. Deepen hospital information system middleware capabilities to parse EPC Gen2 data streams into legacy inventory modules. Prioritize vertical integration into platinum-cured silicone formulation to defend margin structure against raw material cost spikes. For New Entrants and Emerging Players: Lead with sensor-tag convergence for cold chain verification in biologics distribution, where temperature-logging substrates merge authentication with environmental monitoring. Target Japan's diagnostic equipment segment under PMDA traceability expansion as the most penetrable geography. Pursue direct hospital contracting bypassing group purchasing organizations through enterprise RFID platform partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified adhesive conglomerates with underutilized medical-grade substrate capacity and dormant hospital supply chain relationships. Long-term viability rests on regulatory compliance deepening rather than commodity volume expansion. Watch FDA machine-readable tag durability standards for reusable surgical instruments as the inflection signal for premium substrate demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise RFID platform deployments with GPO bypass capture recurring consumable streams. |
| CE Marking Pathway | EUDAMED alignment and EU MDR Article 27 compliance open European hospital procurement channels. |
| Backward Integration into Silicone Formulation | In-house platinum-cured substrate production defends margins against medical-grade adhesive cost spikes. |
| Software Companion Development | Middleware parsing EPC Gen2 data into legacy HIS accelerates ROI realization for asset tracking. |
| Sensor-Tag Convergence R&D | Temperature-logging RFID labels with NFC bridges capture biologics cold chain verification contracts. |
Research Methodology
Cross-validation between hospital procurement database analysis and semiconductor trade flow data anchors the qualitative findings on substrate demand patterns. Primary interviews with biomedical engineers, GPO contracts managers, hospital purchasing committees, and sterilization-grade adhesive formulators combined with secondary validation from FDA GUDID filings, EUDAMED device registrations, GS1 standards documentation, and hospital capital expenditure disclosures. Bottom-up tag volume estimates triangulate with top-down medical device production data across the analysis window.
Sensitivity analysis tests forecast robustness against RFID chip lead time volatility and autoclave-survivable substrate cost inflation. Segmentation dimensions modeled include product type, technology tier, use case maturity, and end-user scale. CAGRs derive from installed base refresh cycles, regulatory compliance deadlines, and real-time location system adoption curves. Forecast inputs incorporate EUDAMED implementation timelines and FDA UDI enforcement intensity across the projection horizon.
Forecasts assume regulatory continuity in FDA UDI mandates and EU MDR device identification requirements; material policy shifts would require re-modeling. Semiconductor supply constraints, laser etching substitution acceleration, or hospital consolidation patterns represent specific risk factors that could revise volume projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Autoclaves Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Dialyzer Reprocessing Machines and Concentrates Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Photorejuvenation Equipment Market