
 Medical Oxygen Concentrators and Oxygen Cylinders Market | 2026-2036
Medical Oxygen Concentrators and Oxygen Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Oxygen Concentrators and Oxygen Cylinders Market Intelligence
Preventive maintenance subscription programs is repositioning how oxygen therapy equipment gets monetized, shifting capital purchases into recurring revenue relationships. Inogen Inc. leverages lightweight portable concentrator engineering to dominate direct-to-consumer channels. CAIRE Inc. anchors its position through stationary concentrator reliability and veteran administration contracting strength. Drive DeVilbiss Healthcare competes aggressively on price across home medical equipment distribution networks.
Medical oxygen concentrators and oxygen cylinders are electromechanical or compressed-gas systems that separate oxygen from ambient air or store medical-grade oxygen at pressures typically reaching 2,000 psi, delivering therapeutic flow rates from 0.5 to 10 liters per minute for patients with hypoxemic respiratory conditions. Portable concentrators now lead product type growth as ambulatory patients reject tethered home systems, while pulse dose delivery mode captures margin pools through algorithmic oxygen conservation that extends battery life and reduces cylinder exchange frequency. Hospitals remain the largest application segment by installed base, though home care is accelerating fastest as payors push readmission reduction.
FDA 510(k) clearance requirements and ISO 13485 quality management standards shape product development timelines and manufacturing audit intensity for all US-bound equipment. The EU Medical Device Regulation imposes stricter clinical evidence thresholds on concentrator software updates and connectivity features, slowing European launches relative to prior CE-marking pathways. Stakeholders must monitor how CMS competitive bidding reshapes reimbursement tiers for home oxygen therapy, as contract winners and losers will reorder manufacturer channel priorities without warning.
Market Dynamics
The shift from hospital-based oxygen therapy to post-acute home care is restructuring demand patterns across the value chain, forcing manufacturers to redesign products for ambulatory use and recurring service revenue models.
Growth Catalysts
- COPD Prevalence in Aging Populations:Rising chronic obstructive pulmonary disease incidence among patients over 65 in the United States, Germany, and Japan expands the addressable patient base for long-term oxygen therapy equipment.
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification procedures for concentrator hardware iterations accelerate product update cycles and reduce time-to-revenue for incremental innovations.
- Pulse Dose Algorithm Advancement:Machine learning-enabled oxygen delivery synchronization with patient breathing patterns extends portable device battery life and reduces cylinder dependency.
Market Restraints
- Zeolite Molecular Sieve Supply Concentration:Production of the critical adsorbent material for pressure swing absorption concentrators concentrates in Chinese manufacturing clusters, exposing OEMs to input volatility and geopolitical friction.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation mandates extensive post-market surveillance and software validation documentation, extending European launch timelines and compliance costs relative to prior CE-marking requirements.
- Stationary System Saturation:Legacy 5-liter and 10-liter home concentrators face replacement-cycle compression as durable equipment lifespans exceed payor reimbursement refresh schedules.
Strategic Opportunities
- Remote Patient Monitoring Integration:Cellular-enabled concentrators transmitting usage data and maintenance alerts create subscription revenue streams and strengthen payor relationships through adherence documentation.
- Veterans Administration Contracting:Specialized procurement channels for military-connected respiratory patients offer stable multi-year revenue commitments with reduced price competition.
- India Home Care Expansion:Underpenetrated oxygen therapy access in tier-2 and tier-3 Indian cities presents first-mover positioning as private hospital chains extend post-discharge services beyond metropolitan centers.
Industry Challenges
- ISO 13485 Audit Intensity:Quality management system recertification cycles demand dedicated compliance personnel and documentation infrastructure that strains mid-tier manufacturer resources.
- Field Service Technician Scarcity:Shortage of trained biomedical equipment specialists capable of concentrator repair and preventive maintenance constrains geographic service coverage expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Oxygen Concentrators and Oxygen Cylinders Market |
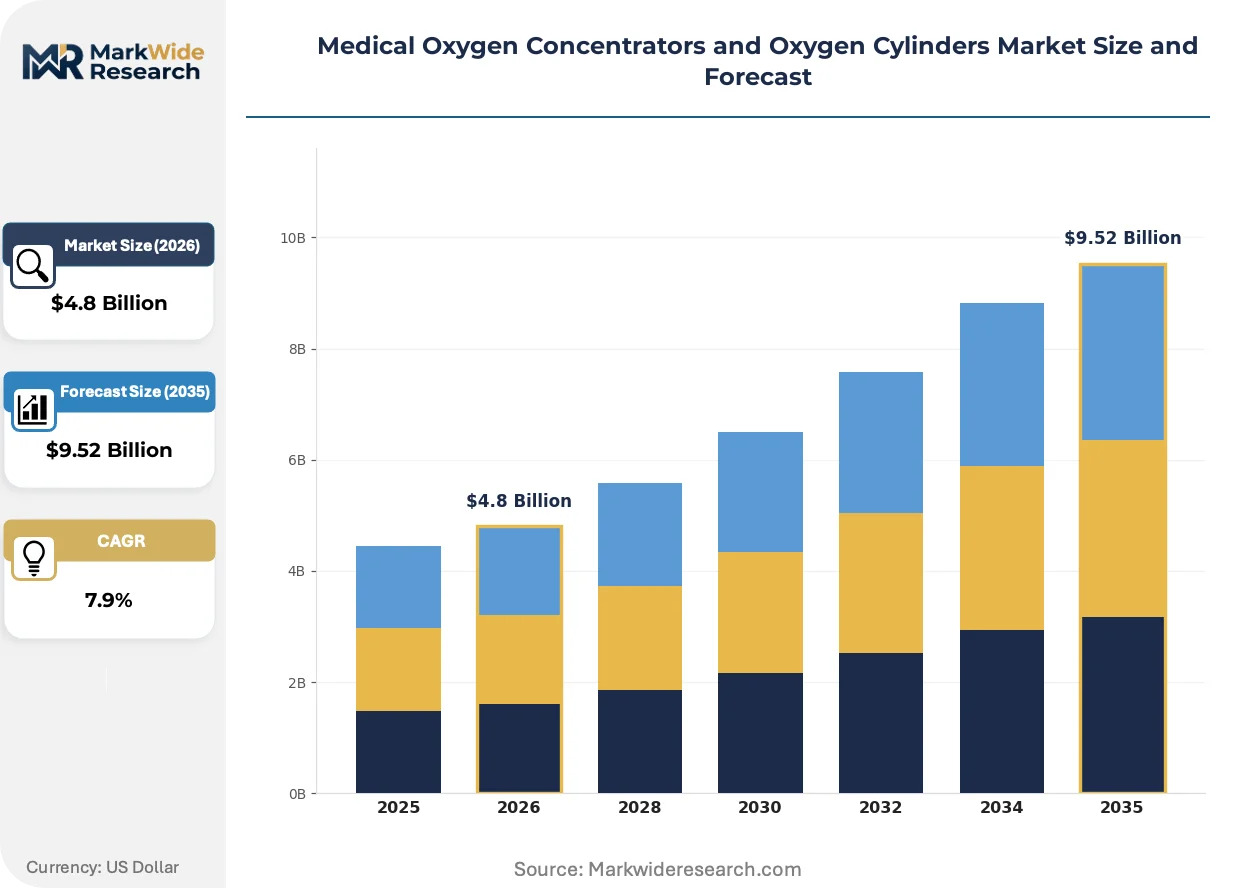
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Concentrators, Stationary Concentrators, Backup Cylinders, Liquid Cylinders Application: Home Care, Hospitals, Emergency Services, Long-term Care Facilities Delivery Mode: Continuous Flow, Pulse Dose, Combined Mode, Variable Flow End User: Patients, Healthcare Providers, Emergency Responders, Caregivers |
| Companies Covered | Drive DeVilbiss Healthcare, Chart Industries, Inogen Inc., O2 Concepts, Nidek Medical Products, Invacare Corporation, CAIRE Inc., Precision Medical, Philips Respironics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Oxygen Concentrators and Oxygen Cylinders Market Strategic Shifts & Innovations
Product architecture and commercial models are transforming simultaneously as hardware miniaturization intersects with connected health infrastructure and reimbursement pressure forces margin extraction from service layers rather than device sales alone.
Portable oxygen concentrator engineering is converging with lithium-ion battery management systems originally developed for electric mobility applications. Home care providers and ambulatory patients are adopting sub-five-pound pulse dose units at the expense of wheeled cart-based systems. This convergence is compressing the addressable market for traditional stationary concentrators while elevating software and sensor content as competitive differentiators.
The EU Medical Device Regulation imposes stricter clinical evidence thresholds on concentrator software updates and connectivity features. Manufacturers must now submit substantial equivalence documentation for algorithm modifications that previously qualified as routine engineering changes. European launch sequencing has shifted behind US FDA clearance timelines as firms prioritize 510(k) pathways with lower evidentiary burdens.
Direct-to-consumer channel development is displacing traditional durable medical equipment distributor relationships for portable concentrator purchases. Patients with private insurance or cash-pay capacity increasingly research and acquire devices through manufacturer websites rather than local home medical equipment suppliers. This behavioral shift concentrates most visibly in the United States where high-deductible health plans and health savings accounts expand out-of-pocket purchasing flexibility.
Medical Oxygen Concentrators and Oxygen Cylinders Market Segmentation
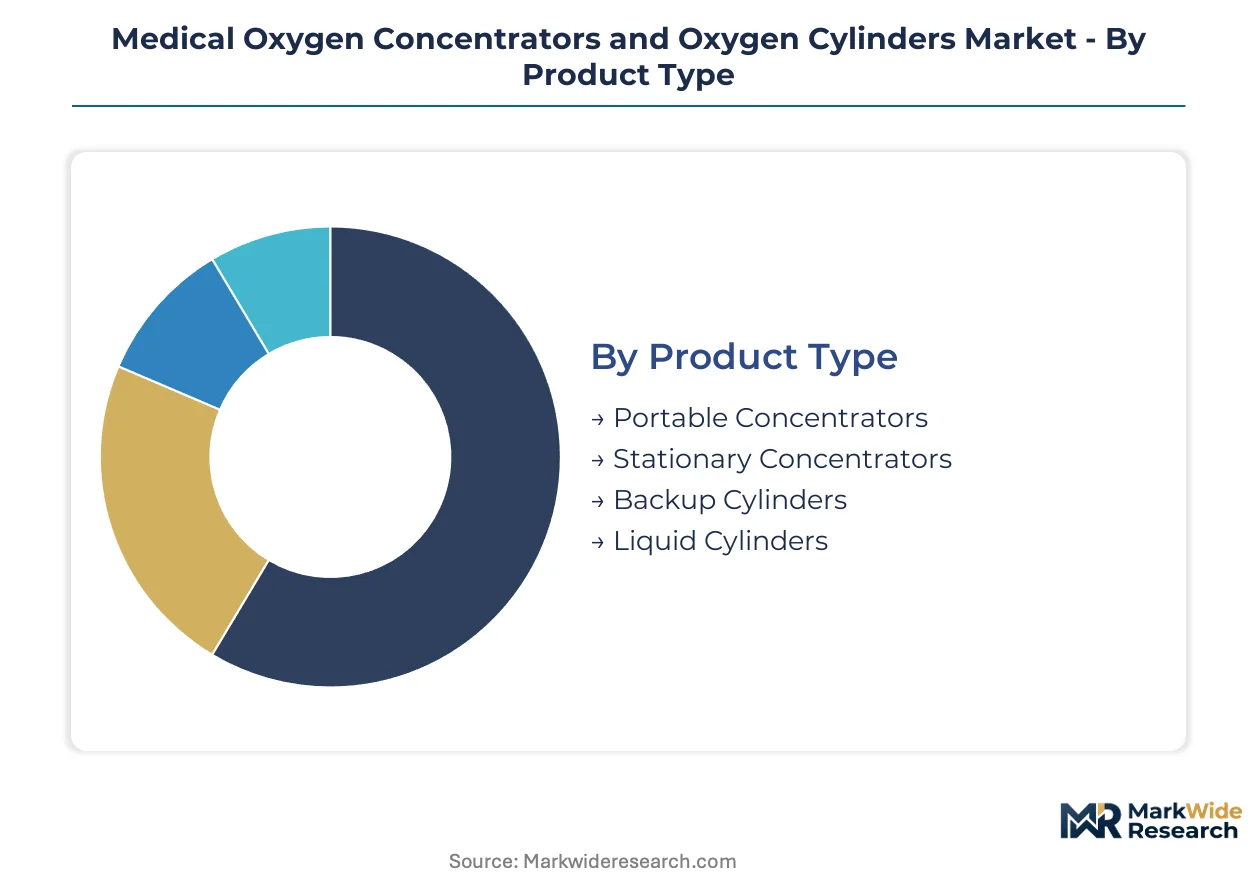
Segmentation in medical oxygen equipment determines regulatory pathway complexity, reimbursement eligibility, and service model design. Manufacturers must align product specifications with end-user mobility requirements and clinical settings to secure FDA 510(k) clearance and CMS competitive bidding contracts.
Product Type:
FDA 510(k) submissions for portable concentrators demand extensive battery safety testing and electromagnetic compatibility validation, while stationary systems face lower evidentiary thresholds for hardware iterations. ISO 13485 quality audits intensify for devices incorporating lithium-ion power management.
- Portable Concentrators:Electromechanical units weighing under five pounds that extract oxygen via pressure swing absorption, powered by rechargeable lithium-ion cells. Demand concentrates among ambulatory COPD patients in the United States seeking Medicare-reimbursed home oxygen therapy with travel flexibility. Pulse dose algorithms extend battery life but require software validation under EU MDR clinical evidence rules.
- Stationary Concentrators:Fixed-installation systems delivering continuous flow up to 10 liters per minute through zeolite molecular sieve beds. Demand clusters in German long-term care facilities and Japanese home care settings where reimbursement favors durable equipment with extended service intervals. Replacement cycles compress as device lifespans exceed payor refresh schedules.
- Backup Cylinders:Compressed oxygen reservoirs providing contingency supply during power outages or concentrator maintenance.
- Liquid Cylinders:Cryogenic storage vessels holding medical oxygen in liquid form for high-volume consumption scenarios.
Leading the category by volume: Stationary Concentrators. Growing fastest: Portable Concentrators.
Application:
Cost tier stratification separates capital-intensive hospital installations from recurring-revenue home care deployments. CMS reimbursement rates and competitive bidding outcomes reshape manufacturer channel priorities across settings.
- Home Care:Post-acute oxygen therapy delivered through concentrator rental programs with preventive maintenance subscriptions. Demand accelerates fastest in the United States as payors push readmission reduction and private hospital chains in India extend services beyond metropolitan centers.
- Hospitals:Centralized oxygen supply infrastructure serving emergency departments, surgical suites, and inpatient wards. Demand concentrates in Japanese tertiary centers and German university hospitals where installed base size drives replacement procurement.
- Emergency Services:Pre-hospital oxygen delivery for trauma and respiratory distress incidents.
- Long-term Care Facilities:Skilled nursing and assisted living environments with mixed concentrator and cylinder deployments.
Revenue concentrates in: Hospitals. Expanding most quickly: Home Care.
Delivery Mode:
Technology sophistication tiers separate algorithm-enabled pulse dose systems from mechanical continuous flow designs. Margin pools favor modes with embedded software and sensor content.
- Pulse Dose:Oxygen delivery synchronized with patient inhalation through machine learning-enabled breathing pattern detection. Demand concentrates in United States direct-to-consumer portable concentrator channels where battery life extension justifies premium pricing.
- Continuous Flow:Uninterrupted oxygen stream at fixed liter-per-minute rates. Demand anchors stationary concentrator deployments in German and Japanese reimbursement environments favoring clinical reliability over conservation features.
- Combined Mode:User-switchable pulse and continuous delivery in single device architecture.
- Variable Flow:Dynamically adjusted output responding to patient activity levels or clinician prescription changes.
Highest margin capture: Pulse Dose. Steepest expansion trajectory: Combined Mode.
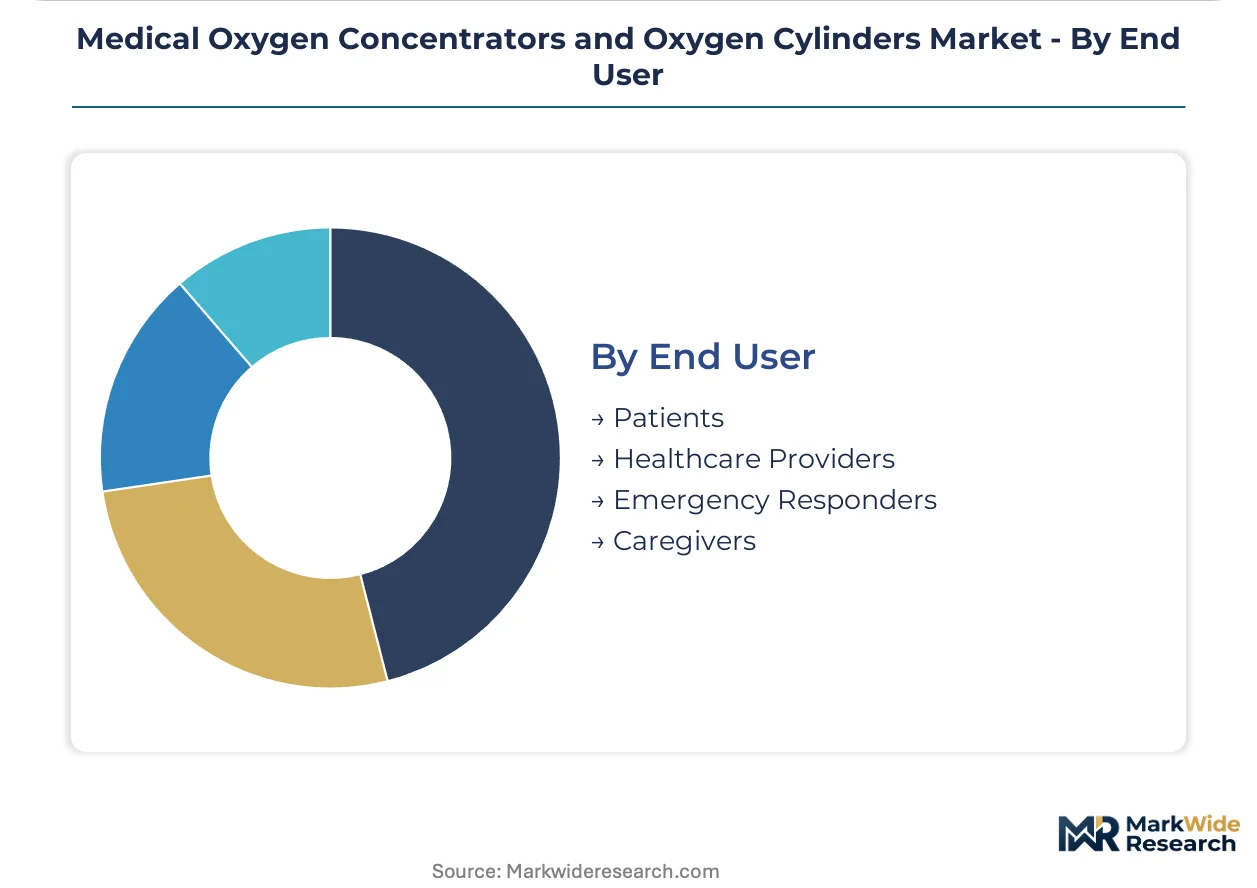
End User:
Customer type determines procurement authority, price sensitivity, and service expectation intensity. Direct-to-consumer channels displace traditional durable medical equipment distributors for patient-directed purchases.
- Patients:Individuals with chronic respiratory conditions acquiring equipment through insurance reimbursement, cash payment, or manufacturer direct channels. Demand concentrates among United States Medicare beneficiaries with high-deductible health plans and health savings accounts enabling out-of-pocket portable concentrator purchases.
- Healthcare Providers:Hospitals, physician practices, and home care agencies procuring through group purchasing organizations and competitive bidding contracts. Demand clusters in Veterans Administration channels offering stable multi-year commitments with reduced price competition.
- Emergency Responders:Fire departments, ambulance services, and disaster relief organizations with rapid-deployment requirements.
- Caregivers:Family members and home health aides operating equipment on behalf of non-ambulatory patients.
Procurement volume leader: Healthcare Providers. Gaining share fastest: Patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of zeolite molecular sieves concentrates in Chinese manufacturing clusters, while consumption anchors in aging Western economies with established reimbursement infrastructure for long-term oxygen therapy.
United States
Medicare competitive bidding and Veterans Administration procurement channels drive concentrator demand among COPD patients over 65. FDA 510(k) clearance requirements shape product development timelines for US-bound portable devices. Dallas and Minneapolis host major home medical equipment distributors expanding preventive maintenance subscription programs.
Germany
Long-term care facility installations and statutory health insurance reimbursement sustain stationary concentrator demand. EU Medical Device Regulation imposes stricter clinical evidence thresholds on software-enabled pulse dose systems. North Rhine-Westphalia clusters medical device engineering talent and ISO 13485-certified manufacturing operations.
Japan
Super-aging demographics and tertiary hospital infrastructure replacement cycles concentrate oxygen equipment procurement. METI industrial standards and PMDA device approvals govern market access for foreign manufacturers. Tokyo and Osaka anchor demand for compact stationary systems in high-density urban home care environments.
China
Domestic zeolite production supplies pressure swing absorption concentrator OEMs while export manufacturing scales for international markets. NMPA medical device registration and GB standards compliance shape product specifications. Zhengzhou and Shanghai concentrate molecular sieve manufacturing and concentrator assembly operations.
India
Private hospital chain expansion into tier-2 and tier-3 cities creates first-mover positioning for post-discharge oxygen therapy services. CDSCO medical device rules and BIS quality certification requirements structure import and domestic manufacturing pathways. Bengaluru and Hyderabad emerge as hubs for home care provider network development.
Medical Oxygen Concentrators and Oxygen Cylinders Market Key Industry Players
Top-tier vendors anchor FDA-cleared portable concentrator engineering, while mid-tier specialists compete on stationary system reliability and price positioning across home medical equipment distribution networks. The market exhibits tiered concentration with premium pulse-dose innovators, veteran administration contractors, and value-oriented durable equipment suppliers occupying distinct competitive positions. Strategic archetypes include direct-to-consumer channel developers, government procurement specialists, and maintenance-subscription platform operators. Dominant competitive moves encompass vertical integration into molecular sieve supply and geographic expansion through regional distributor acquisitions.
Within the portable concentrator tier, Inogen Inc. and CAIRE Inc. exemplify divergent strategic positioning—one toward lightweight ambulatory engineering and consumer-direct channels, the other toward stationary reliability and institutional contracting strength. Drive DeVilbiss Healthcare occupies a position in value-oriented home medical equipment distribution, representing the price-competitive archetype serving reimbursement-sensitive procurement channels.
| Leading Market Players |
|---|
| Drive DeVilbiss Healthcare |
| Chart Industries |
| Inogen Inc. |
| O2 Concepts |
| Nidek Medical Products |
| Invacare Corporation |
| CAIRE Inc. |
| Precision Medical |
| Philips Respironics |
| Others |
Cost & Logistics Intelligence
Medicare competitive bidding compression in the United States is forcing manufacturers to absorb service costs into device pricing, compelling sourcing shifts toward Chinese zeolite suppliers and lithium-ion cell producers to preserve margins on portable concentrator contracts.
Pricing Analysis
Margin tightening in the home care segment reflects CMS reimbursement rate compression and Veterans Administration price benchmarking. Pricing stratifies across pulse-dose premium tiers, continuous-flow standard configurations, and economy stationary units differentiated by ISO 13485 certification depth and battery management sophistication. Cost-down pressure on mid-tier OEMs accelerates because GPO procurement consolidation favors contract winners with scale-advantaged service networks. Cash-pay patients through direct-to-consumer channels exhibit lowest price sensitivity, while Medicaid-dependent home care agencies face acute budget constraints.
Supply Chain Analysis
Dual-sourcing mandates from FDA-inspected device manufacturers now require qualified zeolite molecular sieve suppliers in China and emerging backup qualification programs in India and Germany. Critical inputs include lithium-ion battery cells from South Korean and Japanese producers, precision compressors from German and Italian specialists, and medical-grade aluminum for cylinders. Single-source vulnerability concentrates in Zhengzhou-area molecular sieve production exposed to regional logistics disruption. Distribution runs through home medical equipment distributors, direct-to-consumer fulfillment centers, and hospital GPO contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around FDA-cleared portable engineering capabilities and preventive maintenance platform scale, with ISO 13485 audit intensity and field service technician scarcity forcing subscale competitors toward exit or acquisition.
For Market Incumbents: Deepen backward integration into zeolite molecular sieve supply to decouple from Chinese production volatility, while expanding cellular-enabled remote monitoring subscriptions to lock in payor adherence documentation contracts. Defend against direct-to-consumer channel displacement by acquiring regional home medical equipment distributors with established technician workforces. For New Entrants and Emerging Players: Enter via India's tier-2 and tier-3 city home care networks where private hospital chains are extending post-discharge services without established oxygen therapy infrastructure. Target cash-pay ambulatory patients in United States direct-to-consumer channels with lightweight pulse-dose units priced below Inogen's premium positioning. Pursue CDSCO fast-track registration and local assembly partnerships to bypass import duty exposure. For Investors and Strategic Acquirers: The window for entry favors mid-tier stationary concentrator specialists with Veterans Administration contracting relationships and ISO 13485-certified manufacturing footprints. Long-term viability hinges on software-enabled service revenue attachment rates rather than hardware shipment volumes. Watch CMS competitive bidding contract awards as inflection signals for channel power redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Zeolite Supply Backward Integration | Captive sourcing from Zhengzhou manufacturers reduces input volatility for pressure swing absorption OEMs. |
| Cellular Connectivity Platform Launch | Remote patient monitoring integration strengthens payor relationships through adherence documentation in Medicare channels. |
| India CDSCO Registration Pathway | Early regulatory positioning secures first-mover advantage in tier-2 city home care expansion. |
| Veterans Administration Contract Capture | Multi-year procurement commitments provide revenue stability with reduced price competition in institutional channels. |
| Preventive Maintenance Subscription Scale-Up | Recurring service revenue transforms capital equipment economics and raises switching costs for home care providers. |
Research Approach
Independent corroboration across FDA 510(k) filing databases, CMS Medicare claims data, and EU MDR notified body documentation underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, home medical equipment distributor executives, Veterans Administration procurement officers, and GPO contracts managers combined with secondary validation from ISO 13485 audit records, hospital procurement databases, and customs trade data. Bottom-up concentrator shipment estimates and top-down oxygen therapy patient population sizing were cross-referenced for triangulation.
Rate-of-change decomposition across the analysis window separated volume growth from pricing dynamics and mix shift toward portable pulse-dose systems. Segmentation dimensions modeled include product type, delivery mode, application setting, and end-user procurement authority, with regional regulatory cluster effects layered across United States, German, Japanese, and Indian reimbursement environments. CAGRs were derived from installed base replacement cycles, patient population epidemiology, and payor policy trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR software validation delays or zeolite supply chain disruption. Model outputs reflect documented assumptions regarding CMS competitive bidding schedule adherence and lithium-ion cell cost curves. A model refresh is warranted upon material change in Medicare reimbursement tier structure or FDA 510(k) evidentiary requirement modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
Cath Lab Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Durable Medical Equipment Market