
 Water Bath Vaporizer Market | 2026-2036
Water Bath Vaporizer Market Size, Share, and Industry Trends Forecast 2026-2036
Water Bath Vaporizer Market Analytics
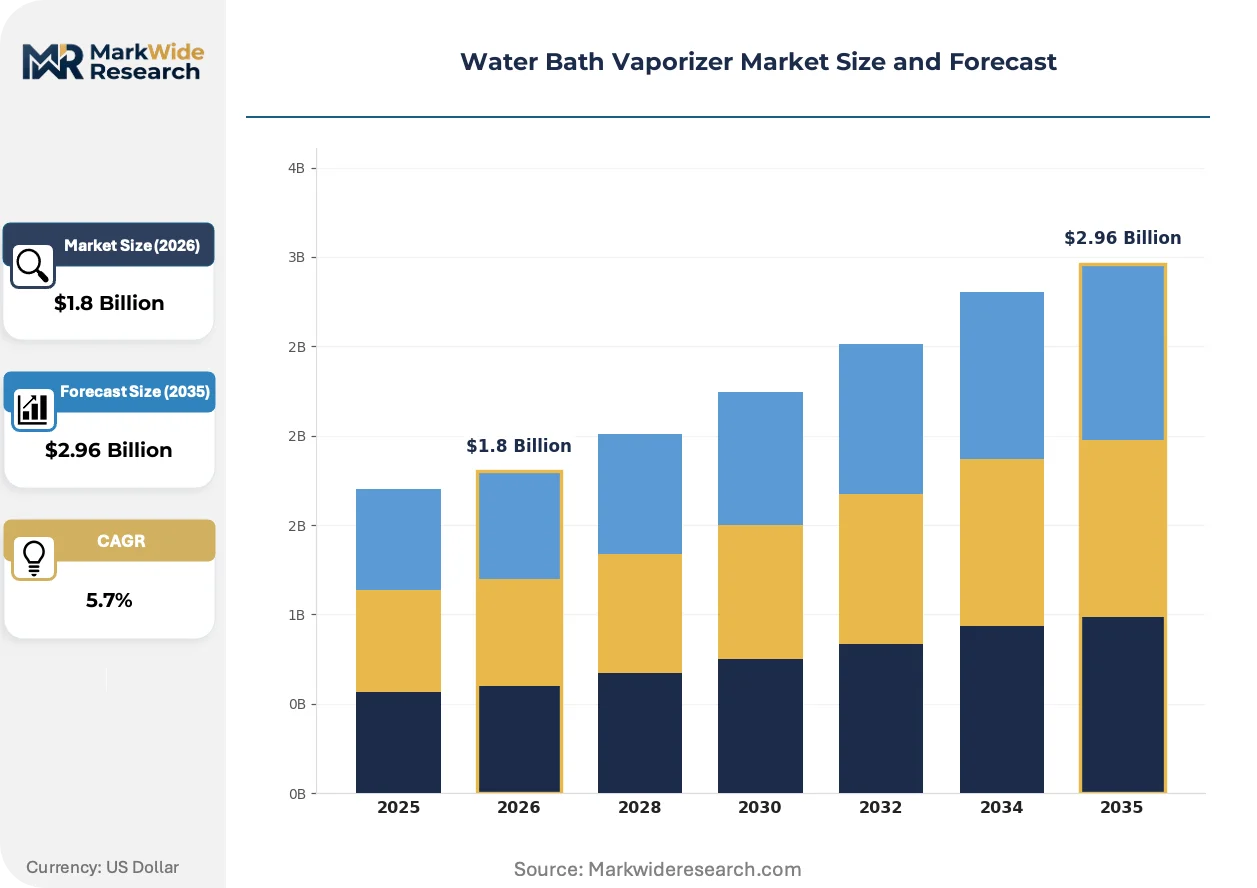
Maintenance service contracts are repositioning how water bath vaporizer vendors capture lifetime value from LNG infrastructure operators. Chart Industries leverages its aftermarket network to sustain recurring revenue across North American terminal installations. Linde anchors its position through integrated cryogenic system servicing that extends equipment uptime guarantees. Nikkiso Co., Ltd (Cryoquip) specializes in region-specific technical support that dominates aftermarket presence across East Asian LNG facilities.
A water bath vaporizer is a heat exchange device that submerges cryogenic fluid coils in a temperature-controlled water reservoir, typically operating at 40–60°C, to convert liquefied natural gas or industrial gases from liquid to gaseous phase for pipeline injection or process feed. Desktop vaporizers lead the product type segment in fixed industrial installations where continuous duty cycles and precise thermal output control command premium positioning, while portable units represent the fastest-growing category as modular LNG satellite plants and mobile regasification skids expand deployment flexibility. Pharmaceutical production applications concentrate margin pools where cGMP compliance and batch validation documentation requirements elevate equipment specification thresholds.
China's SAMR enforces GB standards compliance for pressure-containing cryogenic equipment, while Japan's METI mandates JIS-certified thermal performance testing for gas utility interconnects. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in vaporizer heating systems, redirecting R&D toward electric and waste-heat recovery configurations. Stakeholders must monitor how national decarbonization timelines reshape heating source specifications and retrofit obligations across installed bases.
Market Dynamics
Japan and South Korea are accelerating LNG regasification terminal buildouts as energy security priorities displace nuclear baseload, tightening equipment certification timelines and compressing vendor qualification cycles for water bath vaporizer suppliers.
Growth Catalysts
- Japan's METI energy security mandates:LNG import terminal expansion in Chita and Himeji is pulling specialized cryogenic equipment orders from domestic fabricators.
- Coastal industrial cluster densification:China's Yangtze River Delta and Pearl River Delta are concentrating demand for modular regasification skids at satellite power plants.
- Pharmaceutical cGMP compliance:Batch validation documentation requirements for sterile gas supply are elevating specification thresholds in biologics manufacturing.
Market Restraints
- Stainless steel coil input volatility:316L grade price swings are compressing fabrication margins for pressure-containing components.
- East Asian supply concentration:Cryogenic valve and control system sourcing depends heavily on specialized machine shops in Osaka and Busan.
- EU F-Gas Regulation heating restrictions:Fluorinated greenhouse gas bans are forcing R&D redirection toward electric resistance and waste-heat recovery configurations.
Strategic Opportunities
- India's LNG terminal greenfield pipeline:Dahej and Kochi expansion projects present underpenetrated demand for modular vaporizer skids.
- Carbon capture integration:Post-combustion amine stripping units are creating demand for CO2 vaporization at cement and steel facilities.
- China's dual carbon policy incentives:Waste-heat recovery vaporizer configurations qualify for accelerated depreciation under MEE guidelines.
Industry Challenges
- Cryogenic welding certification scarcity:ASME Section IX qualified technicians command premium wages and extended lead times.
- GB standards compliance timelines:SAMR pressure equipment certification cycles are stretching project delivery schedules for imported systems.
- Legacy SCADA integration friction:Terminal automation retrofits require protocol bridging between new vaporizer controls and existing distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Bath Vaporizer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Vaporizers, Desktop Vaporizers, Analog Vaporizers, Digital Vaporizers End User: Hospitals, Clinics, Home Users, Research Laboratories Application: Aromatherapy, Pharmaceutical Production, Laboratory Testing, Personal Use Distribution Channel: Online Retail, Specialty Stores, Medical Supply Distributors, Direct Sales |
| Companies Covered | Chart Industries, Linde, Nikkiso Co., Ltd (Cryoquip), Cryonorm BV, Meeder Equipment, Nebimak, Algas-SDI, Theisen GmbH & Co. KG, TransTech Energy, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Bath Vaporizer Market Evolving Landscape
Heating source decarbonization is forcing equipment architecture redesigns across the installed base. Vendors are repositioning around thermal efficiency guarantees and modular retrofit compatibility.
Electric immersion heating is converging with industrial heat pump integration for water bath vaporizers serving pharmaceutical and food-grade gas applications. Biologics manufacturers in Switzerland and Singapore are specifying all-electric configurations to eliminate combustion emissions from batch records. This convergence is compressing the addressable market for gas-fired heating modules in regulated end-uses.
China's GB standards for cryogenic pressure equipment are tightening material traceability and weld inspection protocols under SAMR oversight. Domestic fabricators are absorbing compliance costs into base pricing while foreign suppliers face extended type-approval timelines. The standard revision most impacts imported systems destined for utility-scale LNG terminals in Fujian and Zhejiang.
Terminal operators are unbundling after-sales service contracts from original equipment procurement, compressing vendor lock-in and expanding third-party maintenance access. Japanese gas utilities are leading this shift through open tendering for thermal performance audits and coil replacement programs. The unbundling is most advanced at aging regasification facilities in Tokyo Bay and Osaka Bay industrial corridors.
Water Bath Vaporizer Market Segmentation
Water bath vaporizer procurement patterns diverge sharply between integrated cryogenic systems and standalone units. Equipment specification thresholds vary by heating source architecture, certification grade, and automation depth.
Product Type:
Desktop configurations dominate fixed industrial installations where continuous duty cycles demand precise thermal control, while portable units serve modular deployment scenarios requiring field mobility.
- Desktop Vaporizers:Submerged coil arrays in temperature-controlled reservoirs operate at 40–60°C for LNG regasification and process gas feed. Demand clusters at coastal industrial terminals in Japan and South Korea where METI energy security mandates accelerate terminal buildouts.
- Portable Vaporizers:Skid-mounted configurations enable rapid redeployment across satellite power plants and mobile regasification units. China's Yangtze River Delta satellite LNG facilities are absorbing modular units to densify distributed energy infrastructure.
- Analog Vaporizers:Mechanical control systems persist in legacy terminal retrofits where SCADA integration friction limits digital upgrade feasibility.
- Digital Vaporizers:Programmable logic controllers with remote monitoring capabilities serve pharmaceutical cGMP environments requiring batch validation documentation.
Volume placements concentrate in desktop configurations; the faster expansion belongs to portable units.
End User:
Procurement authority shifts between centralized capital committees and distributed operational budgets across user categories.
- Hospitals:Central medical gas supply systems require redundant vaporization capacity for oxygen and nitrous oxide distribution networks. JIS-certified thermal performance testing governs utility interconnect specifications in Japanese healthcare facilities.
- Clinics:Smaller-scale installations prioritize compact footprint and simplified maintenance protocols over peak throughput capacity.
- Home Users:Consumer aromatherapy applications represent negligible addressable market for industrial water bath vaporizer manufacturers.
- Research Laboratories:Precision temperature stability requirements elevate specification thresholds for cryogenic fluid handling in biologics research.
Capital deployment concentrates in hospital systems; research laboratories are climbing the fastest in specification complexity.
Application:
Regulatory intensity varies dramatically across use cases, with pharmaceutical and food-grade applications imposing the most stringent compliance burdens.
- Pharmaceutical Production:cGMP compliance mandates sterile gas supply validation documentation and all-electric heating configurations to eliminate combustion emissions from batch records. Swiss and Singaporean biologics manufacturers specify these systems exclusively.
- Laboratory Testing:Analytical precision requirements drive demand for digital control systems with temperature stability within narrow operating bands.
- Aromatherapy:Consumer wellness applications fall outside industrial water bath vaporizer technical specifications and commercial focus.
- Personal Use:Individual consumption patterns do not align with commercial-grade equipment procurement channels.
Equipment qualification concentrates in pharmaceutical production; laboratory testing is gaining share fastest in digital automation requirements.
Distribution Channel:
Channel strategy must navigate unbundling trends where terminal operators separate aftermarket service from original equipment procurement.
- Direct Sales:Integrated cryogenic system vendors anchor relationships through combined equipment and long-term service contracts. Linde and Chart Industries leverage direct channels to sustain recurring revenue across North American and East Asian terminal installations.
- Medical Supply Distributors:Regional networks serve hospital and clinic procurement with localized technical support and spare parts availability.
- Specialty Stores:Limited relevance for industrial-grade equipment; primarily serve consumer aromatherapy segments.
- Online Retail:Minimal penetration for certified pressure equipment requiring installation supervision and commissioning validation.
Contract value concentrates in direct sales; medical supply distributors are expanding fastest in third-party maintenance access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of pressure-containing cryogenic components while Japan and South Korea absorb the highest terminal installation volumes. This production-consumption split concentrates procurement authority in East Asian industrial clusters and compresses delivery timelines for imported systems.
China
Yangtze River Delta and Pearl River Delta satellite LNG facilities are absorbing modular vaporizer skids to densify distributed energy infrastructure. SAMR enforces GB standards compliance for pressure-containing cryogenic equipment with extended type-approval timelines for imported systems. Fujian and Zhejiang utility-scale terminals face the tightest certification scrutiny under revised material traceability protocols.
Japan
METI energy security mandates are accelerating LNG import terminal expansion in Chita and Himeji, pulling specialized cryogenic equipment orders from domestic fabricators. JIS-certified thermal performance testing governs gas utility interconnect specifications for all new installations. Tokyo Bay and Osaka Bay industrial corridors lead the shift toward unbundled aftermarket service contracts and open tendering for thermal performance audits.
South Korea
Energy security priorities are displacing nuclear baseload and tightening equipment certification timelines for water bath vaporizer suppliers. The national gas utility regulator mandates specific thermal efficiency benchmarks for coastal regasification facilities. Busan specialized machine shops dominate cryogenic valve and control system sourcing, creating supply concentration risk for terminal operators.
United States
FERC permitting timelines for LNG export terminals are extending equipment procurement windows and favoring domestic fabricators with established ASME certification. Gulf Coast industrial corridors concentrate demand for large-scale regasification capacity serving petrochemical feedstock requirements. Chart Industries leverages its aftermarket network to sustain recurring revenue across North American terminal installations.
Switzerland
Biologics manufacturers specify all-electric water bath vaporizer configurations to eliminate combustion emissions from batch records under Swissmedic oversight. Precision temperature stability requirements elevate specification thresholds for sterile gas supply validation. Basel and Zurich pharmaceutical clusters drive premium-tier demand for cGMP-compliant equipment with full documentation packages.
Water Bath Vaporizer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the water bath vaporizer supply base. The market structure fragments between integrated cryogenic system vendors, specialized pressure equipment fabricators, and regional aftermarket service providers. Three archetypes dominate: full-system integrators bundling equipment with long-term service contracts; component specialists focusing on coil arrays and heat exchange surfaces; and third-party maintenance operators capturing unbundled service opportunities. Consolidation pressure runs through capacity expansion in East Asian fabrication hubs and strategic partnerships linking European technology licensors with Chinese manufacturing partners.
Among integrated cryogenic system vendors, Chart Industries and Linde occupy positions anchoring premium-tier procurement through combined equipment and service offerings. Nikkiso Co., Ltd (Cryoquip) exemplifies the regional specialization archetype, with its aftermarket presence concentrated across East Asian LNG facilities. These three entities represent distinct competitive vectors: scale-driven system integration, global gas technology conglomeration, and geography-specific technical support depth.
| Leading Market Players |
|---|
| Chart Industries |
| Linde |
| Nikkiso Co., Ltd (Cryoquip) |
| Cryonorm BV |
| Meeder Equipment |
| Nebimak |
| Algas-SDI |
| Theisen GmbH & Co. KG |
| TransTech Energy, LLC |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between SAMR-approved domestic systems and extended-approval imports manifests in both pricing power concentration and supply chain segmentation across East Asian terminal procurement. Premium-tier vendors capture margin through bundled aftermarket guarantees while commodity fabricators compete on 316L coil input costs and delivery velocity.
Pricing Analysis
Margin tightening in standard-grade equipment reflects stainless steel coil input volatility and compressed fabrication economics at Chinese domestic shops. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification depth: SAMR fast-track approval commands premium positioning, JIS-certified thermal performance testing adds mid-tier markup, and non-certified rebuilds occupy price-sensitive utility procurement. Cost-down pressure on economy-tier imports accelerates because extended GB standards compliance timelines stretch project delivery schedules. Hospital systems and pharmaceutical manufacturers show lowest price sensitivity due to cGMP documentation requirements, while satellite power plant operators in China's coastal industrial clusters prioritize capital efficiency.
Supply Chain Analysis
Regional distribution centers in Osaka, Busan, and Shanghai coordinate hub-and-spoke patterns for cryogenic valve and control system fulfillment. Manufacturing gravity centers on China for pressure-containing coil arrays, Japan for precision thermal control assemblies, and South Korea for integrated skid packaging. Raw material dependencies draw from 316L stainless steel feedstock, specialized cryogenic welding consumables, and PLC automation components. Single-source vulnerability concentrates at ASME Section IX qualified technician pools and Osaka-Busan machine shop networks. Distribution runs through direct sales channels for integrated system vendors and medical supply distributors for hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as GB standards compliance costs and certification timeline compression force sub-scale fabricators toward strategic exit. SAMR regulatory escalation and electric heating R&D redirection favor capitalized incumbents with captive technical resources.
For Market Incumbents: Acquire cryogenic welding certification capacity and ASME-qualified technician pools to defend against aftermarket unbundling trends. Anchor terminal relationships through integrated service contracts that extend equipment uptime guarantees. Invest in waste-heat recovery vaporizer configurations to capture China's dual carbon policy incentives and preempt EU F-Gas Regulation compliance requirements. For New Entrants and Emerging Players: Launch via third-party maintenance contracts at aging Tokyo Bay and Osaka Bay regasification facilities where unbundling trends compress vendor lock-in. Target India's Dahej and Kochi LNG terminal greenfield pipeline with modular skid configurations. Prioritize carbon capture integration applications at cement and steel facilities where CO2 vaporization demand remains underpenetrated. For Investors and Strategic Acquirers: Exit pathways concentrate in regional aftermarket service providers with established East Asian LNG facility presence and SAMR compliance infrastructure. Long-term viability hinges on electric heating technology transition completion and waste-heat recovery configuration standardization. Watch for METI energy security mandate acceleration as inflection indicator for Japanese terminal expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Fabrication | Captive 316L supply secures margin against stainless steel price volatility. |
| Electric Heating Configuration Development | Swissmedic and EU F-Gas Regulation compliance opens pharmaceutical tier. |
| Modular Skid Standardization | China's Yangtze River Delta satellite LNG facilities demand rapid deployment. |
| Aftermarket Service Unbundling Response | Open tendering at Tokyo Bay terminals requires thermal audit capabilities. |
| Carbon Capture Integration Partnership | Post-combustion amine stripping units create CO2 vaporization demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with LNG terminal engineering directors, cryogenic equipment procurement managers, SAMR certification consultants, aftermarket service heads, and pharmaceutical facility maintenance directors. SAMR GB standards documentation, METI energy security policy releases, JIS certification registries, EU F-Gas Regulation implementation guidance, and terminal operator procurement databases provided validation layers. Bottom-up equipment shipment analysis and top-down terminal capacity modeling enabled cross-verification.
Segment-level granularity modeled product type distinctions between desktop and portable configurations, heating source architecture differentiation, certification grade tiers, and automation depth categories across the projection horizon. CAGRs derived from terminal buildout pipeline analysis and equipment replacement cycle patterns. Industry-specific inputs included LNG import volume forecasts, nuclear baseload displacement timelines, and pharmaceutical cGMP compliance expenditure trends.
Regulatory timeline acceleration, stainless steel commodity price shocks, and electric heating technology adoption curves are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding SAMR certification cycle durations and METI mandate implementation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
Global Otoscopes Market
Medical Devices
Arthroscopy Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Critical Care Devices Market