
 Bone Marrow Processing Systems Market | 2026-2036
Bone Marrow Processing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Marrow Processing Systems Market Analytics
ISO 13485 certification for medical device quality management is unwinding the competitive landscape, forcing smaller participants to either invest heavily in compliance infrastructure or exit the market. Merck Millipore Corporation leverages its filtration expertise to dominate upstream cell separation workflows. STEMCELL Technologies anchors its position through specialized media and reagent portfolios that integrate with processing hardware. Sanofi-Aventis LLC competes by extending its therapeutic development pipeline into autologous cell therapies that require captive processing capacity.
Bone marrow processing systems comprise automated and semi-automated devices that isolate, concentrate, and prepare mononuclear cells from aspirated marrow using centrifugation speeds typically ranging from 400 to 2,000 relative centrifugal force, with primary purpose of yielding standardized cellular products for transplantation and research. Centrifugation technology leads in installed base due to decades of clinical validation, though magnetic beads and immunomagnetic selection are gaining fastest in precision research settings where cell purity thresholds exceed 95 percent. Hospitals represent the most mature end-user segment with predictable replacement cycles, while biopharmaceutical companies concentrate margin pools through custom system configurations for drug development.
The FDA regulates these systems as medical devices or human cells, tissues, and cellular and tissue-based products depending on intended use, creating divergent approval pathways that shape R&D investment and commercial timelines. ISO standards for cell processing equipment, combined with EMA's advanced therapy medicinal products framework in Europe, establish interoperability benchmarks that manufacturers must satisfy for multi-regional market access. Stakeholders should monitor evolving regulatory harmonization between FDA and EMA guidance documents, as alignment or divergence will determine whether unified platform designs or region-specific product variants prove more capital-efficient.
Market Dynamics
ISO 13485 certification requirements are compressing vendor margins and forcing capital reallocations toward quality infrastructure, fundamentally restructuring competitive viability for equipment manufacturers serving transplant centers and biopharmaceutical developers.
Growth Catalysts
- Advanced Therapy Medicinal Products framework:EMA's ATMP classification creates predictable commercialization pathways for cell therapy developers in Europe, accelerating captive processing system deployments.
- Tertiary hospital transplant volume expansion:Academic medical centers in the United States are consolidating bone marrow transplant services, driving centralized procurement of high-throughput processing platforms.
- Centrifugation speed optimization:Automated systems operating at 400-2,000 RCF ranges now achieve mononuclear cell yields that match manual protocols, reducing operator variability in clinical workflows.
Market Restraints
- Filtration membrane supply concentration:Specialized cell separation membranes depend on limited German and Japanese specialty materials suppliers, creating input vulnerability.
- FDA dual-pathway friction:Systems classified as either medical devices or HCT/P products face divergent validation requirements that extend commercialization timelines by 18-36 months.
- Magnetic bead cost structure:Immunomagnetic selection reagents carry per-procedure consumable costs that constrain adoption outside research settings.
Strategic Opportunities
- India CDSCO pathway acceleration:India's streamlined medical device registration framework for cell processing equipment opens access to price-sensitive emerging transplant infrastructure.
- Point-of-care processing convergence:Integration of microfluidic cell separation with closed-system bioreactors enables decentralized manufacturing models for autologous therapies.
- Service contract unbundling:Separating equipment sales from validation and training services creates recurring revenue streams among biopharmaceutical contract manufacturers.
Industry Challenges
- Cell therapy manufacturing talent scarcity:Qualified operators capable of maintaining ISO 14644 cleanroom standards during bone marrow processing remain concentrated at established academic centers.
- Legacy centrifuge integration complexity:Hospital laboratories face workflow disruption when connecting new automated systems to existing sample tracking and temperature monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Marrow Processing Systems Market |
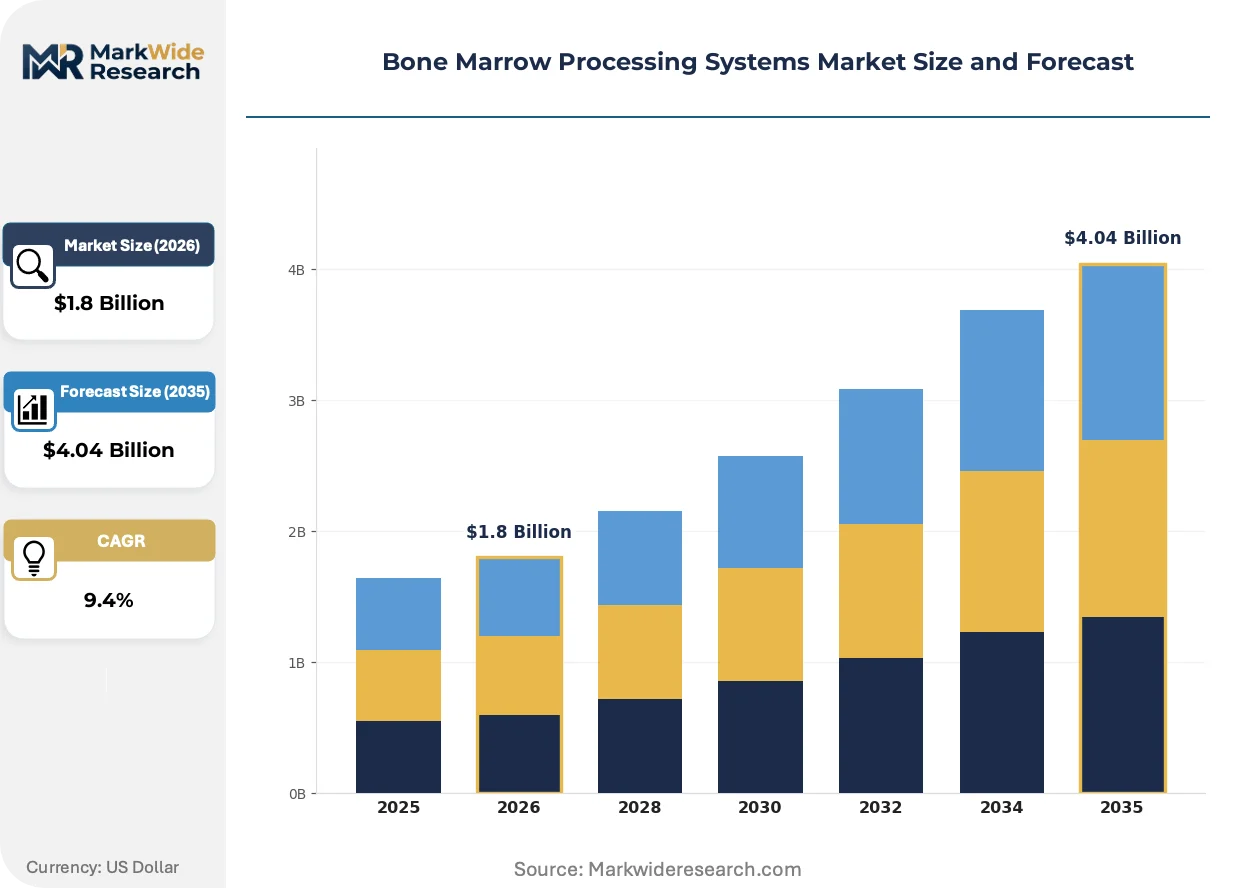
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Separator, Plasma Extractor, Sterilization System, Storage Container Technology: Centrifugation, Filtration, Magnetic Beads, Immunomagnetic Selection End User: Hospitals, Research Laboratories, Blood Banks, Biopharmaceutical Companies Application: Transplantation, Research, Therapeutic Applications, Drug Development |
| Companies Covered | Merck Millipore Corporation, Sanofi-Aventis LLC, AllCells LLC, STEMCELL Technologies, Hemacare Corporation, Cellular Dynamics International, ReachBio LLC, Cesca Therapeutics, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Marrow Processing Systems Market Evolving Landscape
Closed-system automation architectures are displacing open-platform processing workflows across clinical and manufacturing environments, compressing contamination risk profiles while demanding new operator competencies and facility configurations.
Microfluidic cell separation technology is fragmenting the historical dominance of density-gradient centrifugation in research applications. Contract development and manufacturing organizations are piloting these systems for small-batch autologous therapies where cell purity requirements exceed 95 percent. The technology is fragmenting established vendor relationships by enabling modular, software-configurable platforms that reduce hardware switching costs.
FDA's ongoing updates to cell therapy manufacturing guidance are tightening environmental monitoring and documentation requirements for systems handling HCT/P materials. Manufacturers must now validate closed-system integrity across temperature excursion scenarios previously exempt from protocol. Biopharmaceutical developers with captive processing capacity face the steepest compliance reinvestment cycles.
Academic medical centers are consolidating vendor relationships through multi-year enterprise agreements that bundle equipment, disposables, and technical support. Purchasing committees now prioritize interoperability with electronic health record systems over standalone processing performance. This concentration is most visible in the United States, where transplant center accreditation requirements drive standardization across hospital networks.
Bone Marrow Processing Systems Market Segmentation
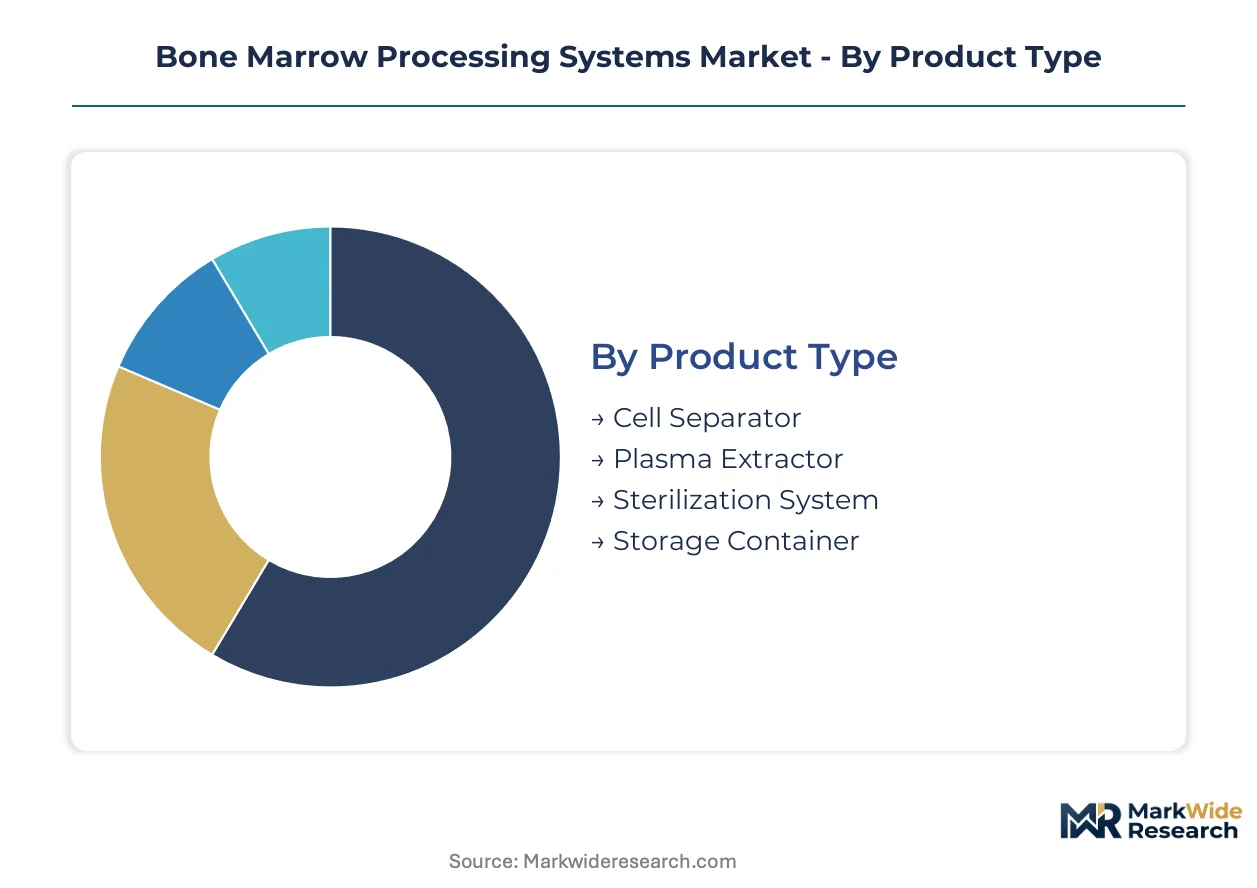
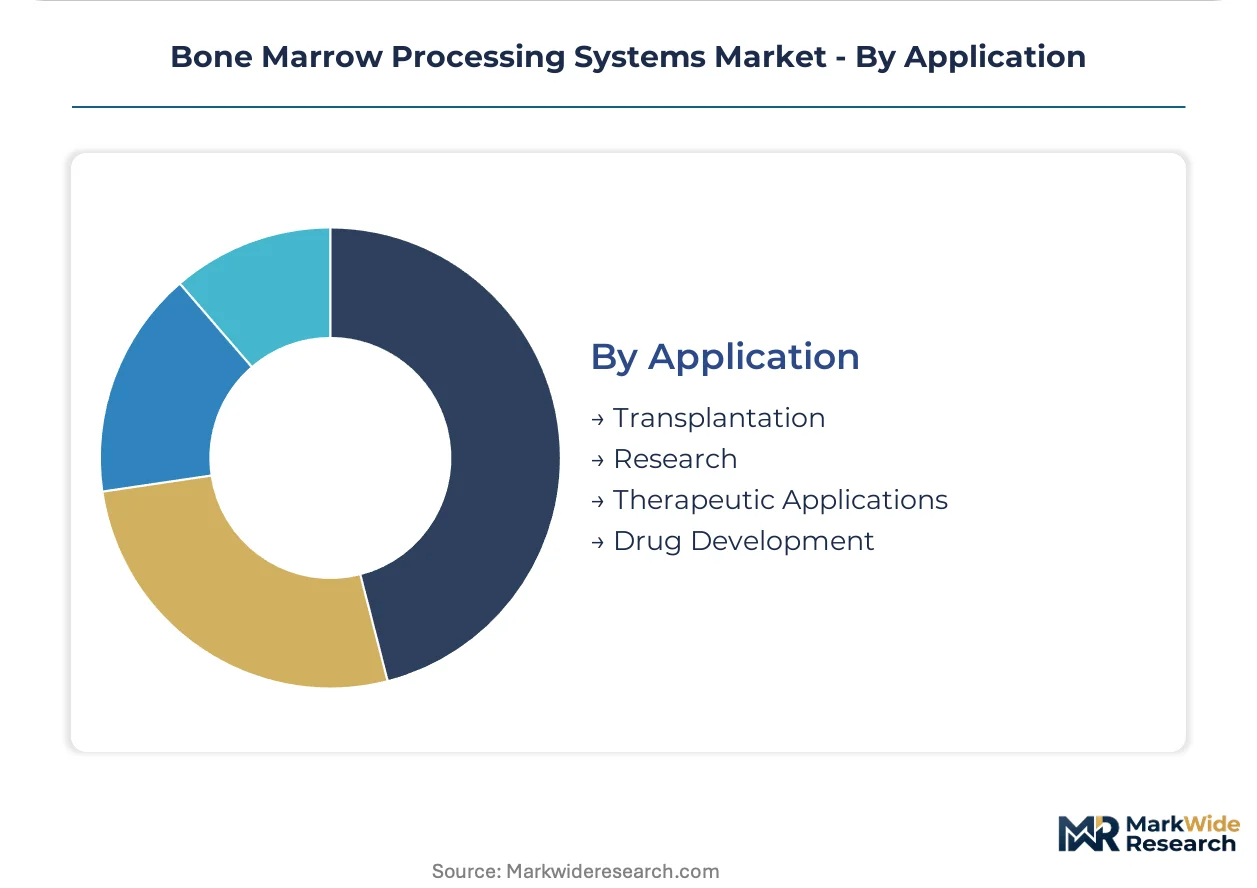
Segmentation in bone marrow processing systems reveals how regulatory pathways, clinical workflows, and research requirements create distinct procurement patterns across equipment categories. Understanding these divisions exposes where capital concentrates and which technologies face accelerated compliance reinvestment cycles.
Product Type:
FDA classifies cell separators as medical devices under 21 CFR Part 864 while sterilization systems handling HCT/P materials fall under dual-pathway scrutiny, creating divergent validation timelines that shape vendor R&D allocation.
- Cell Separator:Automated and semi-automated devices isolate mononuclear cells through programmable centrifugation at 400-2,000 RCF. Tertiary hospitals in the United States anchor procurement volumes as academic medical centers consolidate transplant services and standardize on closed-system architectures.
- Plasma Extractor:Peripheral blood and marrow-derived plasma separation modules integrate with downstream cryopreservation workflows. Blood banks in Germany and Japan drive specification requirements due to stringent national hemovigilance standards that exceed baseline FDA benchmarks.
- Sterilization System:Closed-loop decontamination units validate ISO 14644 cleanroom integrity during processing cycles.
- Storage Container:Cryogenic and controlled-rate freezing vessels maintain cell viability across temperature excursion protocols.
Cell separators handle the majority of throughput; sterilization systems are gaining share fastest as closed-system mandates tighten across both FDA and EMA jurisdictions.
Technology:
Cost stratification separates established centrifugation platforms from premium magnetic bead workflows, with per-procedure consumable economics determining adoption ceilings outside research settings.
- Centrifugation:Density-gradient separation leverages decades of clinical validation with standardized RCF protocols. Hospital laboratories in the United States prioritize this technology for predictable operator training curves and established reimbursement coding.
- Magnetic Beads:Immunomagnetic selection achieves cell purity thresholds exceeding 95 percent for autologous therapy manufacturing. Biopharmaceutical companies in Switzerland and the Netherlands absorb higher per-run costs to meet EMA advanced therapy medicinal products specifications.
- Filtration:Membrane-based separation reduces shear stress on fragile cell populations during upstream processing.
- Immunomagnetic Selection:Antibody-coated microspheres enable positive and negative cell sorting with minimal sample volume requirements.
Centrifugation dominates installed base; magnetic beads are expanding most quickly in precision research and cell therapy manufacturing segments.
End User:
Customer type determines procurement authority, with hospitals operating through centralized capital committees while biopharmaceutical developers pursue custom system configurations for captive manufacturing capacity.
- Hospitals:Tertiary academic medical centers manage predictable replacement cycles tied to transplant center accreditation renewals. The United States concentrates demand where hospital networks consolidate vendor relationships through multi-year enterprise agreements bundling equipment and technical support.
- Biopharmaceutical Companies:Contract manufacturers and integrated developers deploy captive processing systems for autologous cell therapy pipelines. CDMOs in India leverage streamlined CDSCO registration pathways to establish regional manufacturing hubs for export markets.
- Research Laboratories:Academic and institutional labs pilot novel separation technologies before clinical translation.
- Blood Banks:National and regional blood services maintain processing capacity for allogeneic transplant material preparation.
Hospitals manage the highest equipment throughput; biopharmaceutical companies are climbing the fastest on capital deployment intensity per processing lane.
Application:
Maturity gradients separate transplantation's established reimbursement infrastructure from therapeutic applications' emerging commercial models, with research serving as the entry point for technology validation.
- Transplantation:Allogeneic and autologous bone marrow transplant preparation represents the most validated clinical application with defined CPT coding. Centers in the United States drive volume concentration as service consolidation reduces the number of accredited transplant programs.
- Drug Development:Cell therapy developers require processing systems for investigational new drug manufacturing and Phase I/II clinical supply. European developers navigate EMA's ATMP framework to establish predictable commercialization pathways that accelerate equipment procurement decisions.
- Research:Preclinical and translational studies generate demand for flexible, multi-modal processing platforms.
- Therapeutic Applications:Approved cell and gene therapies create recurring demand for validated manufacturing processes.
Transplantation commands the largest installed base; drug development is seeing the steepest expansion trajectory as autologous therapy pipelines mature toward commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridor underwrites European distribution efficiency for temperature-sensitive cell processing equipment, while the US Interstate highway network and dedicated medical device air freight lanes at Memphis and Louisville anchor North American supply chain velocity.
United States
Academic medical centers in Boston, Houston, and Seattle consolidate bone marrow transplant services, driving centralized procurement of high-throughput processing platforms. FDA dual-pathway classification for HCT/P materials creates 18-36 month validation timelines that shape vendor market entry strategies. The Research Triangle Park corridor in North Carolina anchors contract manufacturing organization clustering for autologous cell therapy development.
Germany
National hemovigilance standards exceed baseline FDA benchmarks, driving specification requirements for plasma extraction modules across university hospitals in Heidelberg and Munich. EMA's ATMP framework creates predictable commercialization pathways that accelerate equipment procurement decisions among cell therapy developers. The Frankfurt-Rhine-Main biotechnology cluster concentrates CDMO infrastructure for European autologous therapy manufacturing.
Switzerland
Swissmedic's alignment with EMA advanced therapy standards positions Basel and Zurich as regulatory reference points for precision cell processing workflows. The country's private hospital networks absorb premium pricing for magnetic bead-based separation systems where purity thresholds exceed 95 percent. The Lake Geneva biotech corridor hosts captive processing capacity for autologous therapy pipelines.
India
CDSCO's streamlined medical device registration framework opens access to price-sensitive emerging transplant infrastructure in Mumbai and Hyderabad. Tertiary hospitals in Delhi and Bangalore expand bone marrow transplant programs, driving demand for automated centrifugation platforms at 400-2,000 RCF ranges. The Genome Valley cluster near Hyderabad anchors regional manufacturing hubs for export markets.
Japan
PMDA's cell therapy product classification system creates defined approval pathways that reduce commercialization uncertainty for bone marrow processing system vendors. Academic medical centers in Tokyo and Osaka standardize on closed-system architectures to meet stringent environmental monitoring requirements. The Kobe biomedical innovation cluster concentrates translational research infrastructure for regenerative medicine applications.
Bone Marrow Processing Systems Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure, as public companies leverage capital market access to fund ISO 13485 compliance while private operators retreat from quality reinvestment cycles. The vendor base stratifies into three tiers: diversified life science conglomerates with filtration expertise, specialized cell biology reagent houses, and captive therapeutic developers with in-house processing capacity. Dominant competitive moves include backward integration into membrane supply and geographic expansion through distributor acquisition in emerging transplant markets.
Among diversified conglomerates with filtration heritage, Merck Millipore Corporation exemplifies the scale-driven archetype through its upstream cell separation workflow dominance. Specialized reagent specialists occupy a distinct tier, with STEMCELL Technologies representing the integrated media-and-hardware positioning. Therapeutic developers with captive capacity, including Sanofi-Aventis LLC, sit within a third archetype defined by pipeline-driven processing infrastructure deployment rather than equipment market participation.
| Leading Market Players |
|---|
| Merck Millipore Corporation |
| Sanofi-Aventis LLC |
| AllCells LLC |
| STEMCELL Technologies |
| Hemacare Corporation |
| Cellular Dynamics International |
| ReachBio LLC |
| Cesca Therapeutics |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Long-term enterprise agreements bundling equipment, disposables, and technical support lock in supply access for tertiary hospitals while freezing price visibility across multi-year procurement cycles. This contract structure concentrates purchasing power among academic medical centers in the United States and shields vendors from spot-market volatility in specialized membrane inputs.
Pricing Analysis
Certification level (ISO 13485/FDA-grade) creates the primary spread between premium and standard system tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with magnetic bead-based workflows commanding premium positioning due to 95 percent-plus purity thresholds. Cost compression in economy-tier centrifugation platforms is intensifying because CDSCO-registered Indian manufacturers are entering price-sensitive transplant infrastructure. Biopharmaceutical companies show lowest price sensitivity, absorbing per-procedure consumable premiums for ATMP-compliant workflows.
Supply Chain Analysis
German and Japanese specialty materials suppliers constitute the critical chokepoint for filtration membranes used in upstream cell separation. Manufacturing draws from concentrated inputs: precision centrifuge rotors from Germany, immunomagnetic bead coatings from Switzerland, and cryogenic storage vessels from Japan. Single-source vulnerability in membrane supply creates exposure to regulatory restriction if EMA or FDA tighten materials traceability requirements. Distribution runs through dedicated medical device air freight lanes at Memphis and Louisville, with temperature-controlled pharmaceutical corridors at Rotterdam underwriting European access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling now generates recurring revenue expanding faster than hardware sales, as biopharmaceutical contract manufacturers seek validation and training services separate from capital equipment procurement.
For Market Incumbents: Secure backward integration into membrane manufacturing to neutralize German and Japanese supplier concentration. Lock hospital networks into multi-year enterprise agreements before microfluidic entrants fragment vendor relationships with modular, software-configurable platforms. For New Entrants and Emerging Players: Differentiate on point-of-care processing convergence by integrating microfluidic separation with closed-system bioreactors for decentralized autologous therapy manufacturing. Target India's emerging transplant infrastructure through CDSCO-registered centrifugation platforms at 400-2,000 RCF ranges, leveraging streamlined registration against incumbent certification burdens. For Investors and Strategic Acquirers: Specialized cell biology reagent houses with integrated media-and-hardware positioning offer acquisition exposure to fastest-expanding magnetic bead segments. Watch EMA-FDA guidance harmonization as the inflection indicator determining whether unified platform designs or region-specific variants prove more capital-efficient.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality infrastructure separates viable vendors from forced exits under tightening FDA guidance updates. |
| Hospital System Partnership | Academic medical center enterprise agreements bundle equipment, disposables, and EHR interoperability. |
| Backward Integration into Membrane Supply | German and Japanese specialty materials concentration creates input vulnerability for non-integrated vendors. |
| Software Companion Development | Closed-system automation architectures demand new operator competencies and facility configuration tools. |
| Reimbursement Strategy | Defined CPT coding for transplantation anchors predictable replacement cycles in United States hospital networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across transplant center biomedical engineers, hospital GPO contracts managers, biopharmaceutical manufacturing executives, and CDMO regulatory affairs leads. Secondary validation drew from FDA 510(k) filings, EMA ATMP submissions, hospital procurement databases, and CMS Medicare transplant center accreditation records. Bottom-up equipment unit estimates and top-down market sizing triangulated through cross-referencing vendor shipment disclosures with end-user installation tracking.
Across the analysis window, projections incorporate technology segmentation by centrifugation, magnetic bead, filtration, and immunomagnetic selection modalities alongside end-user stratification across hospitals, biopharmaceutical companies, research laboratories, and blood banks. CAGRs derive from regression against transplant volume expansion, regulatory pathway acceleration, and replacement cycle patterns. Industry-specific inputs include tertiary hospital consolidation rates and autologous therapy pipeline maturation trajectories.
Material uncertainties — FDA dual-pathway reclassification, EMA-FDA guidance divergence, filtration membrane supply disruption — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as closed-system mandate timelines and CDSCO pathway evolution reshape competitive viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Tanning Units Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Single-Coated Medical Tape Market