
 Global Oxygen Flow Meters Market | 2026-2036
Global Oxygen Flow Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oxygen Flow Meters Market Foresight
Aftermarket calibration and recertification services is rewriting margin allocation across the oxygen flow meter value chain. Ohio Medical leverages its installed base in North American hospitals to sustain recurring revenue from sensor replacement programs. Precision Medical, Inc. competes through specialized mechanical flow meter designs that dominate home care channels. Megasan Medical anchors its position in emerging markets with cost-optimized pneumatic devices.
Oxygen flow meters are precision instruments that regulate and quantify oxygen delivery from pressurized sources to patients, typically operating within flow ranges of 0-15 liters per minute with accuracy tolerances of ±10% or tighter depending on clinical application. Digital variants incorporate thermal mass or ultrasonic sensing elements with integrated data logging for ventilator synchronization and remote monitoring compliance. Mechanical flow meters retain the largest revenue pool across hospitals and emergency care settings where durability and power independence outweigh connectivity requirements. Electronic segments are expanding fastest in respiratory clinics and hyperbaric therapy centers where real-time flow integration with electronic medical records is becoming standard.
FDA 510(k) clearance pathways and the EU Medical Device Regulation (MDR) Class IIa requirements shape product development timelines and testing expenditures for manufacturers seeking multi-regional market access. ISO 15002 standards for oxygen concentrator compatibility and the EU F-Gas Regulation governing medical gas handling create additional compliance layers that favor established players with dedicated regulatory affairs capacity. Stakeholders must monitor how NMPA harmonization efforts in China and emerging South Asian regulatory frameworks alter competitive entry costs across manufacturing and distribution strategies.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around digital oxygen flow meters capable of EMR integration, compressing mechanical meter margins while elevating sensor replacement contracts as the primary profit pool across the value chain.
Growth Catalysts
- EU MDR Class IIa accuracy mandates:Tighter tolerances for oxygen delivery devices are accelerating hospital replacement cycles across Germany, France, and Italy as legacy mechanical units face compliance deadlines.
- Critical care infrastructure expansion:China, the United States, and Saudi Arabia are commissioning new ICU capacity with integrated respiratory monitoring systems that require digital flow meter compatibility.
- Thermal mass sensing miniaturization:Reduced component costs are enabling mid-tier manufacturers to offer electronic variants at price points competitive with premium mechanical designs.
Market Restraints
- Brass and aluminum input volatility:Mechanical flow meter housings depend on non-ferrous metal prices that have fluctuated sharply, compressing margins for pneumatic device specialists serving price-sensitive segments.
- Sensor supplier concentration in East Asia:Thermal mass and ultrasonic sensing elements concentrate among South Korean and Japanese component houses, creating single-source vulnerability for digital meter assemblers.
- ISO 15002 compatibility testing costs:Oxygen concentrator interoperability certification requires specialized chamber testing that adds months to product launch timelines and six-figure expenditures per SKU.
Strategic Opportunities
- Home respiratory therapy underpenetration:Brazil, Mexico, and Indonesia maintain low digital flow meter penetration in COPD patient home care, presenting channel expansion potential for cost-optimized electronic designs.
- F-Gas Regulation service bundling:EU medical gas handling compliance creates recurring revenue potential through certified calibration and recertification programs attached to initial device sales.
- Ultrasonic-thermal sensor convergence:Hybrid sensing architectures that combine drift stability with real-time responsiveness are opening premium positioning in hyperbaric therapy and aviation medicine applications.
Industry Challenges
- Embedded firmware validation timelines:FDA 510(k) submissions for software-controlled digital meters require extensive documentation of algorithm behavior across edge-case flow conditions, extending regulatory cycles.
- Legacy pneumatic system integration:Hospitals with extensive wall-mounted oxygen infrastructure face mechanical-to-digital retrofit complexity that stalls procurement decisions despite connectivity benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oxygen Flow Meters Market |
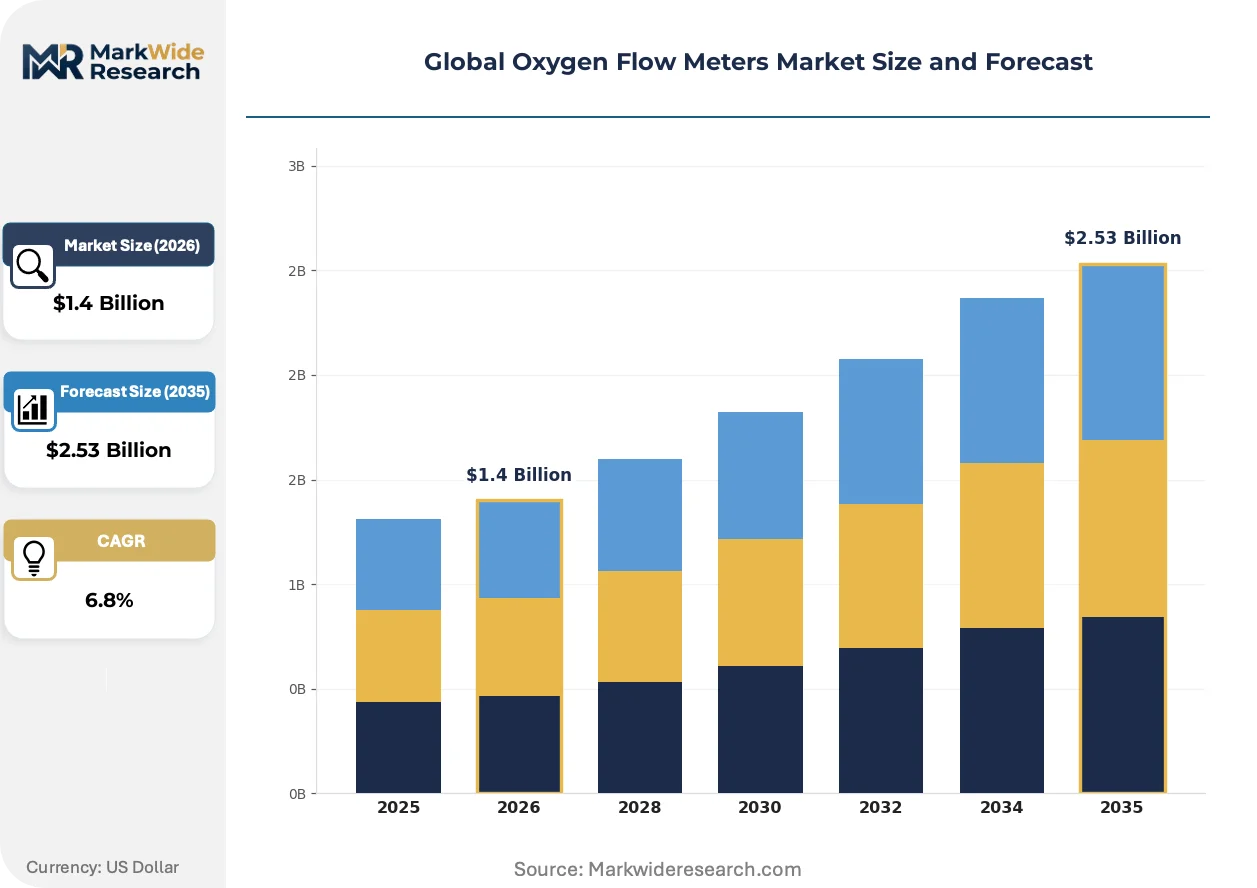
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Digital, Pneumatic, Electronic Application: Home Care, Emergency Care, Surgery, Recovery Rooms, Hyperbaric Therapy End User: Hospitals, Clinicians, Respiratory Clinics, Ambulance Services, Nursing Facilities Distribution Channel: Online Retailers, Medical Distributors, Direct Sales, Pharmacies, Specialized Stores |
| Companies Covered | Ohio Medical, Precision Medical, Inc., Heyer Medical AG, HERSILL, Penlon Ltd., Dwyer Instruments LTD., Megasan Medical, Burak Metering Pvt Ltd, Smiths Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oxygen Flow Meters Market Shifts & Advancements
Sensor fusion architectures and regulatory data requirements are compressing the traditional divide between mechanical durability and digital intelligence, forcing manufacturers to develop dual-competency engineering teams.
Thermal mass flow sensing with integrated temperature compensation is hybridizing with legacy variable-area (rotameter) mechanical designs to create meters that maintain power-independent operation while offering Bluetooth-enabled data logging for ventilator synchronization. German and Swiss hospital systems are piloting these transitional devices in step-down units where electrical reliability concerns persist. The hybrid approach is hybridizing category boundaries, allowing incumbents with mechanical expertise to defend installed base relationships while building digital service revenue streams.
The EU F-Gas Regulation is tightening leak-rate documentation requirements for medical gas handling equipment, compelling flow meter manufacturers to redesign sealing interfaces and add pressure-decay monitoring capabilities. Industrial consequence includes accelerated obsolescence of 1990s-era pneumatic designs that cannot meet traceability mandates. Hyperbaric therapy centers in France and the Netherlands are responding fastest, specifying meters with integrated data logging as standard procurement criteria.
After-sales service unbundling is separating calibration and recertification from original equipment purchases, enabling third-party service providers to capture margin previously retained by manufacturers. Hospital procurement in the United States is driving this shift through multi-year total-cost-of-ownership evaluations that favor lower capital outlays with contracted service agreements. The model is most visible in Texas and California health systems where group purchasing organizations have standardized around service-inclusive pricing templates.
Global Oxygen Flow Meters Market Segmentation
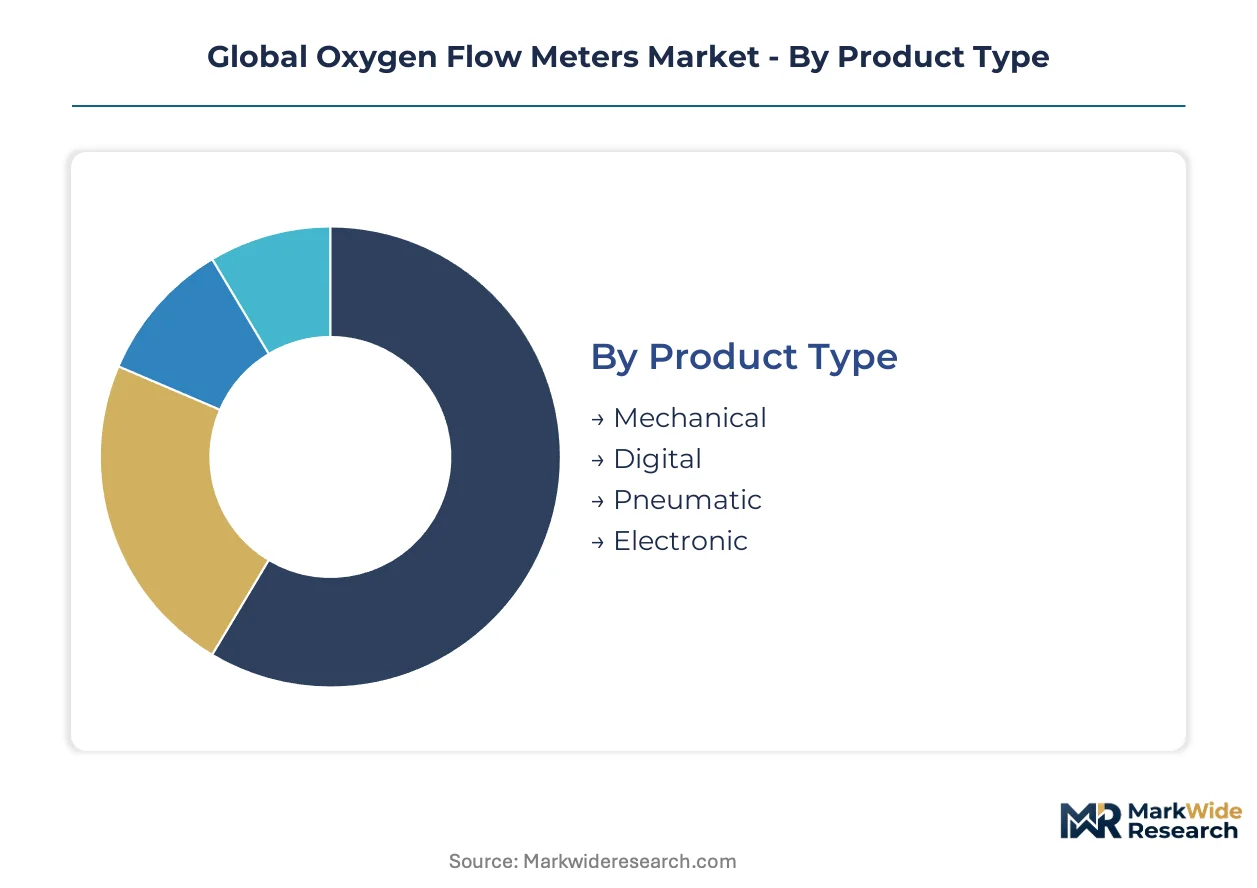
Segmentation in oxygen flow meters reveals divergent margin structures across product architectures and procurement channels. After-sales intensity varies sharply: digital platforms generate recurring sensor replacement revenue, while mechanical units depend on decade-long replacement cycles with minimal service attachment.
Product Type:
After-sales-service intensity splits sharply across this category, with electronic variants demanding continuous calibration contracts while pneumatic designs operate with minimal post-sale engagement.
- Mechanical:Variable-area rotameter designs with brass or aluminum housings deliver flow readings through physical float displacement without electrical power. Hospital procurement in Germany and France favors these units for emergency departments where electrical failure risks override connectivity benefits.
- Digital:Thermal mass or ultrasonic sensing elements with integrated microprocessors enable real-time data logging and ventilator synchronization. Respiratory clinics in the United States and hyperbaric therapy centers in the Netherlands specify these for EMR integration mandates.
- Pneumatic:Pressure-driven diaphragm mechanisms serve cost-sensitive installations with minimal maintenance requirements.
- Electronic:Software-controlled architectures with embedded firmware validation for FDA 510(k) pathways dominate premium critical care specifications.
By volume, Mechanical leads. By growth pace, Digital is ahead.
Application:
Cost tier stratification governs equipment specifications, with hyperbaric therapy commanding premium sensing accuracy while home care prioritizes price accessibility over precision.
- Home Care:Compact flow meters with simplified interfaces serve COPD patients requiring long-term oxygen therapy. Brazil, Mexico, and Indonesia show underpenetration of digital variants, creating channel expansion potential for cost-optimized designs with basic data logging.
- Emergency Care:Ruggedized mechanical units with impact-resistant housings dominate ambulance and field hospital deployments where power independence proves essential. Saudi Arabia's expanding pre-hospital infrastructure drives procurement of military-specification pneumatic devices.
- Surgery:Operating theater installations demand ISO 15002 compatibility with anesthesia machine integration.
- Recovery Rooms:Step-down units pilot hybrid mechanical-digital designs with Bluetooth-enabled monitoring.
- Hyperbaric Therapy:Multi-atmosphere pressure environments require specialized sealing interfaces and pressure-decay monitoring under EU F-Gas Regulation mandates.
By patient contact hours, Emergency Care leads. By equipment value per installation, Hyperbaric Therapy climbs the fastest.
End User:
Customer type determines procurement sophistication, with hospitals consolidating around multi-year service contracts while ambulance services prioritize capital cost minimization.
- Hospitals:Integrated health systems in Texas and California leverage group purchasing organizations to standardize around digital meters with service-inclusive pricing templates. ICU expansion in China and the United States specifies ventilator-compatible flow sensing with remote monitoring compliance.
- Clinicians:Individual practitioner offices favor portable electronic units with plug-and-play concentrator compatibility.
- Respiratory Clinics:Specialized pulmonary facilities in France and Switzerland pilot thermal mass sensing with temperature compensation for chronic disease management programs.
- Ambulance Services:Fleet operators select mechanical durability over connectivity for field reliability.
- Nursing Facilities:Long-term care operators balance staff training constraints against regulatory documentation requirements.
By installed base value, Hospitals lead. By procurement flexibility, Respiratory Clinics gain share fastest.
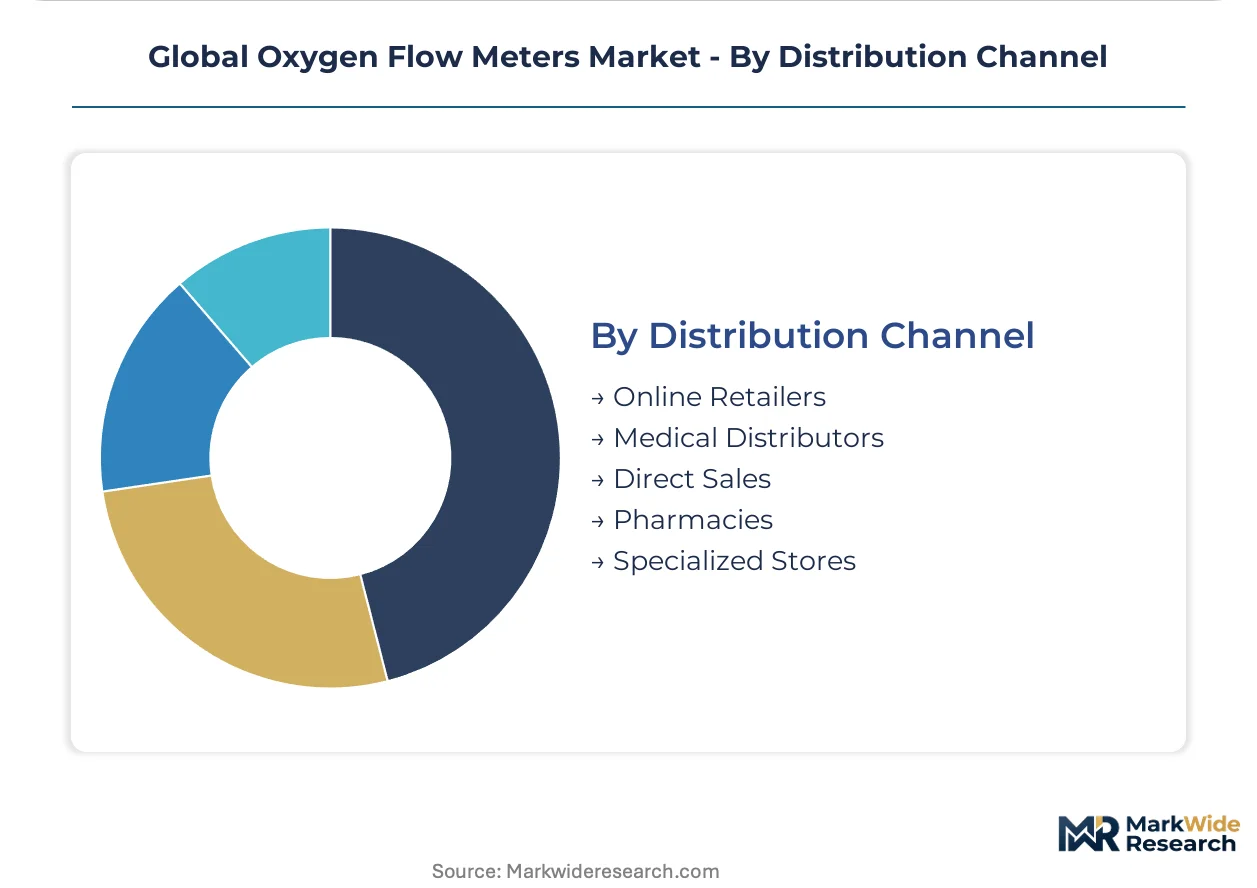
Distribution Channel:
Supply concentration shapes margin capture, with direct sales retaining service revenue while online retailers commoditize hardware transactions.
- Online Retailers:E-commerce platforms aggregate home care demand through price-transparent mechanical meter offerings. Third-party calibration providers increasingly unbundle service from original equipment purchases through this channel.
- Medical Distributors:Regional specialists with ISO 13485 warehousing maintain hospital relationships through just-in-time delivery and field technical support.
- Direct Sales:Manufacturer field organizations capture multi-year service contracts alongside capital equipment in large health system negotiations.
- Pharmacies:Retail pharmacy chains extend into durable medical equipment with basic pneumatic flow meters for walk-in oxygen therapy patients.
- Specialized Stores:Respiratory therapy boutiques provide fitting services and patient education for home care transitions.
By transaction volume, Medical Distributors lead. By expansion trajectory, Online Retailers show steepest growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German hospitals prioritize mechanical durability for emergency departments, while Chinese health systems commission digital-native ICU infrastructure. United States procurement consolidates around service-inclusive contracts, and Saudi Arabia's pre-hospital expansion favors ruggedized field specifications.
United States
Texas and California health systems drive digital meter adoption through group purchasing organization standardization. FDA 510(k) clearance pathways shape product development timelines for ventilator-compatible designs. The Greater Boston cluster anchors respiratory device innovation with hyperbaric therapy center procurement leading EMR integration mandates.
Germany
Hospital procurement in Bavaria and North Rhine-Westphalia favors mechanical rotameters for emergency power independence. EU MDR Class IIa accuracy mandates accelerate replacement cycles for legacy pneumatic units. The Baden-Württemberg medical technology corridor concentrates hybrid mechanical-digital development for step-down unit pilots.
China
ICU capacity expansion in Shanghai and Beijing specifies thermal mass sensing with remote monitoring compliance. NMPA harmonization efforts alter competitive entry costs for multi-regional manufacturers. The Yangtze River Delta manufacturing base concentrates sensor assembly capacity for cost-optimized electronic variants.
Saudi Arabia
Pre-hospital infrastructure investment drives military-specification pneumatic device procurement for ambulance fleets. The national pharmaceutical regulator enforces medical gas handling standards aligned with EU F-Gas frameworks. Riyadh and the Eastern Province anchor critical care construction with integrated respiratory monitoring system specifications.
Netherlands
Hyperbaric therapy centers in Amsterdam and Rotterdam mandate integrated data logging for pressure-decay monitoring compliance. The Eindhoven Region medical device cluster specializes in ultrasonic-thermal sensor convergence for multi-atmosphere applications. Dutch hospital procurement leads EU adoption of Bluetooth-enabled transitional device pilots.
Global Oxygen Flow Meters Market Competitive Landscape
Capability concentration sits with sensor-integrated specialists; scale advantage sits with mechanical heritage incumbents. The vendor base organizes around three tiers: pneumatic device assemblers serving price-sensitive emerging markets, digital platform developers capturing hospital EMR integration contracts, and hybrid architects bridging mechanical durability with connectivity. Strategic moves center on sensor supplier partnerships for East Asian component security and aftermarket service unbundling to capture recurring calibration revenue.
Among North American incumbents, Ohio Medical anchors the installed base defense archetype through hospital relationship leverage. Precision Medical, Inc. occupies the specialized mechanical design position for home care channel dominance. Megasan Medical exemplifies emerging market cost optimization through pneumatic device standardization. These three represent distinct competitive vectors: legacy base monetization, channel-specific mechanical expertise, and price-engineered volume penetration.
| Leading Market Players |
|---|
| Ohio Medical |
| Precision Medical, Inc. |
| Heyer Medical AG |
| HERSILL |
| Penlon Ltd. |
| Dwyer Instruments LTD. |
| Megasan Medical |
| Burak Metering Pvt Ltd |
| Smiths Medical Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in East Asian sensor component fabrication is forcing digital flow meter assemblers to accept extended lead times and elevated input costs, compressing margins for mid-tier manufacturers while reinforcing pricing power among integrated incumbents with captive supply arrangements.
Pricing Analysis
Long-term service contracts dominate hospital procurement, with group purchasing organizations in Texas and California standardizing around multi-year calibration agreements that bundle hardware with recurring maintenance. Price differentiation separates FDA 510(k)-cleared electronic units from pneumatic designs serving home care channels. Pricing pressure stems from brass and aluminum input volatility affecting mechanical meter housings. Ambulance services exhibit highest price sensitivity, while hyperbaric therapy centers accept premium positioning for pressure-decay monitoring compliance.
Supply Chain Analysis
Upstream feedstock concentration centers on South Korean and Japanese component houses for thermal mass and ultrasonic sensing elements, with Chinese assembly operations completing final meter integration. Brass and aluminum ingots for mechanical housings draw from German and Turkish smelters. Single-source vulnerability in East Asian sensor supply creates procurement risk for digital meter specialists. Distribution runs through medical distributors with ISO 13485 warehousing for hospital relationships, while online retailers commoditize home care transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxygen flow meters market is emerging from a cyclical trough driven by EU MDR Class IIa compliance deadlines that forced accelerated replacement spending. Hospital procurement consolidation and sensor supplier concentration are reshaping competitive economics.
For Market Incumbents: Harden installed base defenses through sensor replacement program lock-in and backward integration into calibration service capacity. Ohio Medical's recurring revenue model from North American hospital relationships demonstrates the defensibility of service-attached pricing. Counter emerging market pneumatic specialists by accelerating hybrid mechanical-digital development for step-down unit pilots.
For New Entrants and Emerging Players: Build out cost-optimized electronic designs for Brazil, Mexico, and Indonesia home care channels where digital penetration remains underdeveloped. Target respiratory clinic specifications in France and Switzerland piloting thermal mass sensing with temperature compensation. Lead with concentrator compatibility certification to bypass hospital procurement consolidation barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital platform development as FDA 510(k) software validation timelines extend and East Asian sensor supply security requires strategic inventory positions. The five-to-ten-year viability window favors acquisition targets with established regulatory affairs capacity and hospital GPO contract access. Monitor NMPA harmonization progress as the inflection signal for Chinese market entry cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Investment | Accelerates hospital replacement cycles in Germany, France, and Italy as compliance deadlines approach. |
| East Asian Sensor Supply Partnership | Secures thermal mass and ultrasonic component access against South Korean and Japanese supplier concentration. |
| Hybrid Mechanical-Digital Development | Bridges emergency department durability requirements with Bluetooth-enabled data logging for step-down units. |
| Service Contract Unbundling | Captures recurring calibration revenue as Texas and California GPOs shift toward total-cost-of-ownership evaluation. |
| Home Care Channel Expansion | Addresses underpenetration in Brazil, Mexico, and Indonesia COPD patient populations with cost-optimized designs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR notified body documentation, and hospital procurement contract registries. Primary interviews engaged biomedical engineers, GPO contracts managers, respiratory therapists, and aftermarket service heads across the United States, Germany, China, and Saudi Arabia. Secondary validation incorporated ISO 15002 certification records, F-Gas Regulation implementation guidance, and customs trade data for brass and aluminum medical device component flows. Bottom-up unit economics and top-down regional demand aggregation were cross-referenced for triangulation.
Forecast inputs span product type segmentation across mechanical, digital, pneumatic, and electronic architectures; application segmentation from home care through hyperbaric therapy; and end-user segmentation distinguishing hospital system procurement sophistication from ambulance fleet capital constraints. CAGRs were derived from installed base replacement cycle analysis and ICU capacity expansion pipelines. Modeling incorporated EU MDR compliance deadline phasing, NMPA harmonization trajectory, and thermal mass sensing miniaturization cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by pneumatic specialists or sensor supplier acquisition activity by digital platform developers would shift outcomes. Cross-checking against hospital capital expenditure surveys and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Dual Energy X-Ray Absorptiometry (Dexa) Equipment Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Irradiation Apparatus Market