
 Global Blood Viscometer Market | 2026-2036
Global Blood Viscometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Viscometer Market Foresight
Modular sensor cartridge design is hardening as the dominant product configuration, letting buyers swap between capillary and microfluidic measurement modes within single instrument platforms. Anton Paar GmbH leverages its precision optics heritage to dominate high-end laboratory installations across Europe. RheoSense Inc. specializes in microfluidic chip architectures that reduce sample volumes for pediatric and neonatal applications. Thermo Fisher Scientific Inc. extends its clinical diagnostics footprint by bundling viscometry modules into integrated hematology workcells.
A blood viscometer measures the resistance of whole blood or plasma to flow under controlled shear conditions, typically reporting viscosity in centipoise or millipascal-seconds across physiological shear rate ranges from 0.1 to 1000 s⁻¹; this parameter serves critical functions in diagnosing hyperviscosity syndromes, monitoring anticoagulant therapy efficacy, and assessing cardiovascular risk biomarkers. Rotational viscometer systems anchor the installed base in hospital laboratories due to established clinical validation and broad assay compatibility, while microfluidic viscometer platforms represent the fastest-expanding segment as pharmaceutical manufacturers adopt them for high-throughput drug formulation screening. The point-of-care testing application category is maturing slowly because regulatory clearance pathways for near-patient viscosity assays remain more stringent than for central laboratory methods.
The FDA's Clinical Laboratory Improvement Amendments and the EU's In Vitro Diagnostic Regulation jointly shape product development roadmaps by mandating traceable calibration protocols and risk-classification documentation for hematology analyzers. China's NMPA enforces GB standards for electromagnetic compatibility that complicate market entry for instruments incorporating novel thermal or ultrasonic detection technologies. Stakeholders must monitor evolving harmonization between ISO 15189 laboratory accreditation requirements and national metrology institute standards for biological fluid rheology reference materials.
Market Dynamics
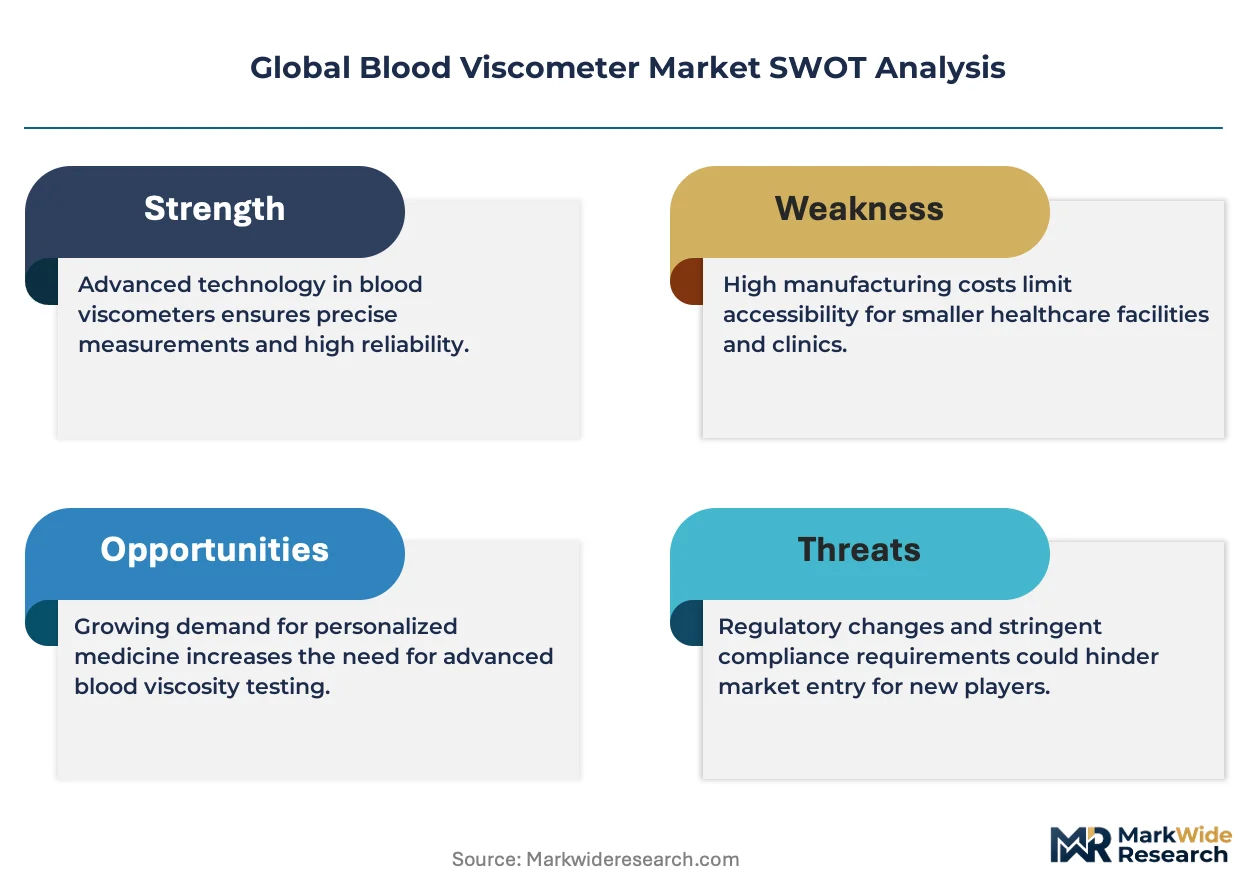
Hospital laboratories are consolidating instrument procurement around modular platforms that accommodate multiple assay modalities, compressing vendor selection cycles and elevating technical service capabilities as decisive purchase criteria over standalone device specifications.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:The MDR's risk-classification documentation requirements for hematology analyzers are accelerating replacement of legacy viscometry systems in German cardiovascular research institutes and French hospital laboratories.
- Microfluidic chip architectures:Pharmaceutical manufacturers deploying high-throughput drug formulation screening are driving procurement of reduced-sample-volume systems for pediatric and neonatal applications.
- Point-of-care testing maturation:Central laboratory backlog pressures in US academic medical centers are expanding pilot programs for near-patient viscosity assays despite stringent FDA clearance pathways.
Market Restraints
- Precision optics supply concentration:European manufacturers depend on a limited base of German and Swiss optical component suppliers for high-end rotational viscometer assemblies, creating vulnerability to input bottlenecks.
- GB electromagnetic compatibility standards:China's NMPA enforcement complicates market entry for instruments incorporating novel thermal or ultrasonic detection technologies, extending registration timelines.
- Established clinical validation protocols:Rotational viscometer systems anchor hospital laboratory installed bases through decades of assay compatibility data, creating substitution friction for microfluidic alternatives.
Strategic Opportunities
- Integrated hematology workcells:Bundling viscometry modules into automated diagnostic platforms opens procurement channels through large clinical diagnostics distributors serving US health system networks.
- ISO 15189 harmonization:Convergence between laboratory accreditation requirements and national metrology institute standards for biological fluid rheology reference materials creates first-mover advantage for calibration-traceable system vendors.
- Pediatric subspecialty expansion:Neonatal intensive care units in Japan and South Korea are adopting reduced-sample-volume microfluidic platforms faster than general hematology departments.
Industry Challenges
- Rheology metrology expertise scarcity:Hospital laboratory technicians trained in conventional hematology analyzers require specialized competency development for shear-rate-controlled measurement interpretation.
- Legacy LIS integration complexity:Microfluidic viscometer platforms face extended deployment timelines where hospital information systems lack HL7 FHIR compatibility for viscosity data transmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Viscometer Market |
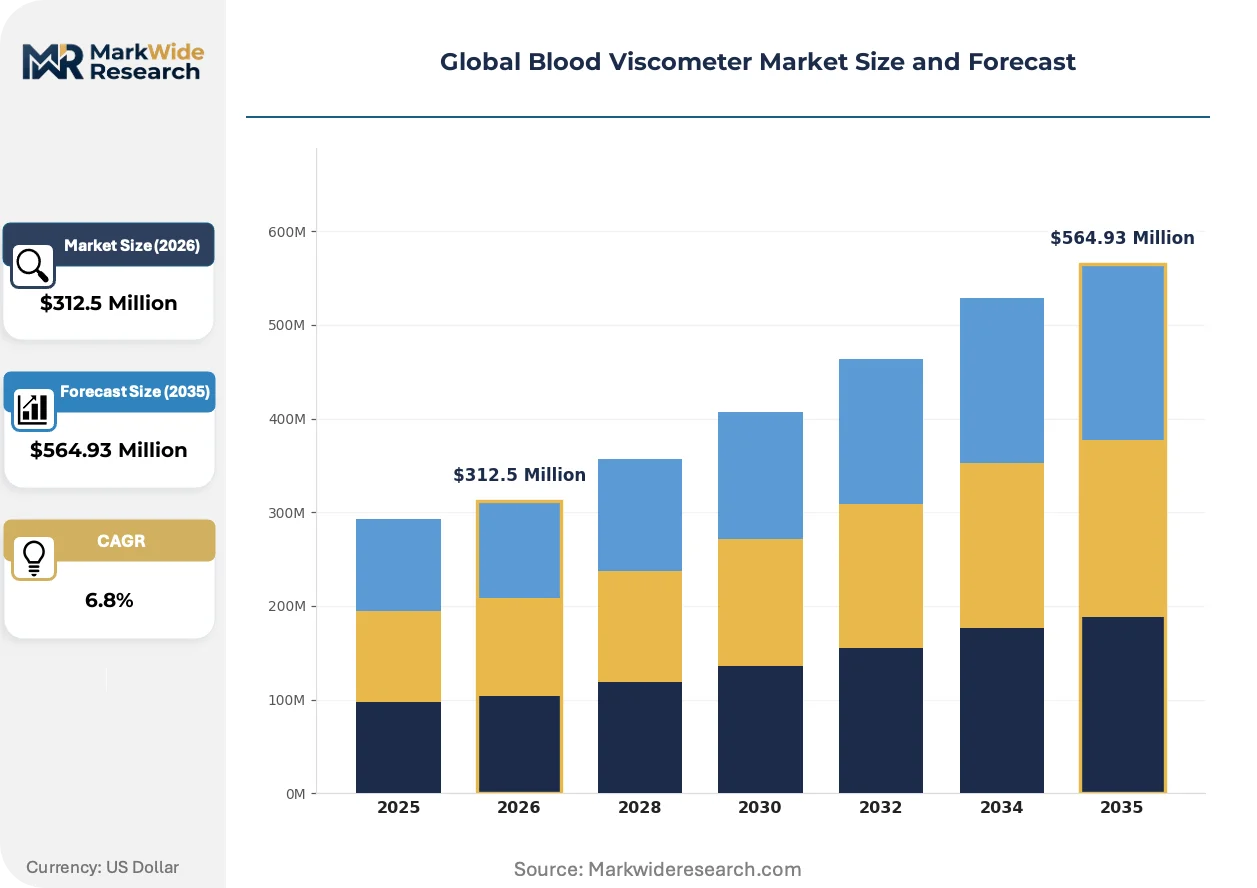
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary Viscometer, Rotational Viscometer, Microfluidic Viscometer, Oscillatory Viscometer, Vibrational Viscometer Technology: Optical, Electromagnetic, Mechanical, Ultrasonic, Thermal Application: Hematology Analysis, Cardiovascular Monitoring, Drug Development, Research Laboratories, Point-of-Care Testing End User: Hospitals, Diagnostic Centers, Research Institutes, Pharmaceutical Manufacturers |
| Companies Covered | AMETEK Inc., Benson Viscometers Ltd., RheoSense Inc., Cambridge Viscosity Inc., BioFluid Technology Inc., Thermo Fisher Scientific Inc., A and D Co Ltd., China Beijing Steellex Scientific Instrument Co., Anton Paar GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Viscometer Market Shifts & Advancements
Modular sensor cartridge design is compressing the traditional distinction between capillary and rotational measurement modalities, enabling single-instrument flexibility that reconfigures laboratory capital planning and vendor relationship structures.
Multi-mode measurement platforms are unifying capillary, rotational, and microfluidic architectures within shared instrument housings. Academic medical centers in Germany and the Netherlands are piloting these systems to consolidate redundant device footprints. This unification is compressing vendor margins on standalone rotational systems while elevating service contract values for integrated technical support.
REACH substance restriction evaluations are expanding disclosure requirements for viscometer lubricants and thermal interface materials used in precision spindle assemblies. Manufacturers serving European hospital laboratories are reformulating component specifications to maintain CE marking eligibility. Rotational viscometer producers with established supply chain documentation systems are capturing procurement preference over newer market entrants.
Consolidated procurement through regional laboratory purchasing cooperatives is displacing individual hospital tender processes in the US and Germany. These cooperatives are unbundling after-sales service contracts from instrument purchase agreements, creating separate competitive arenas for technical support providers. The shift is most visible in cardiovascular research institute networks where multi-site standardization drives volume commitments.
Global Blood Viscometer Market Segmentation
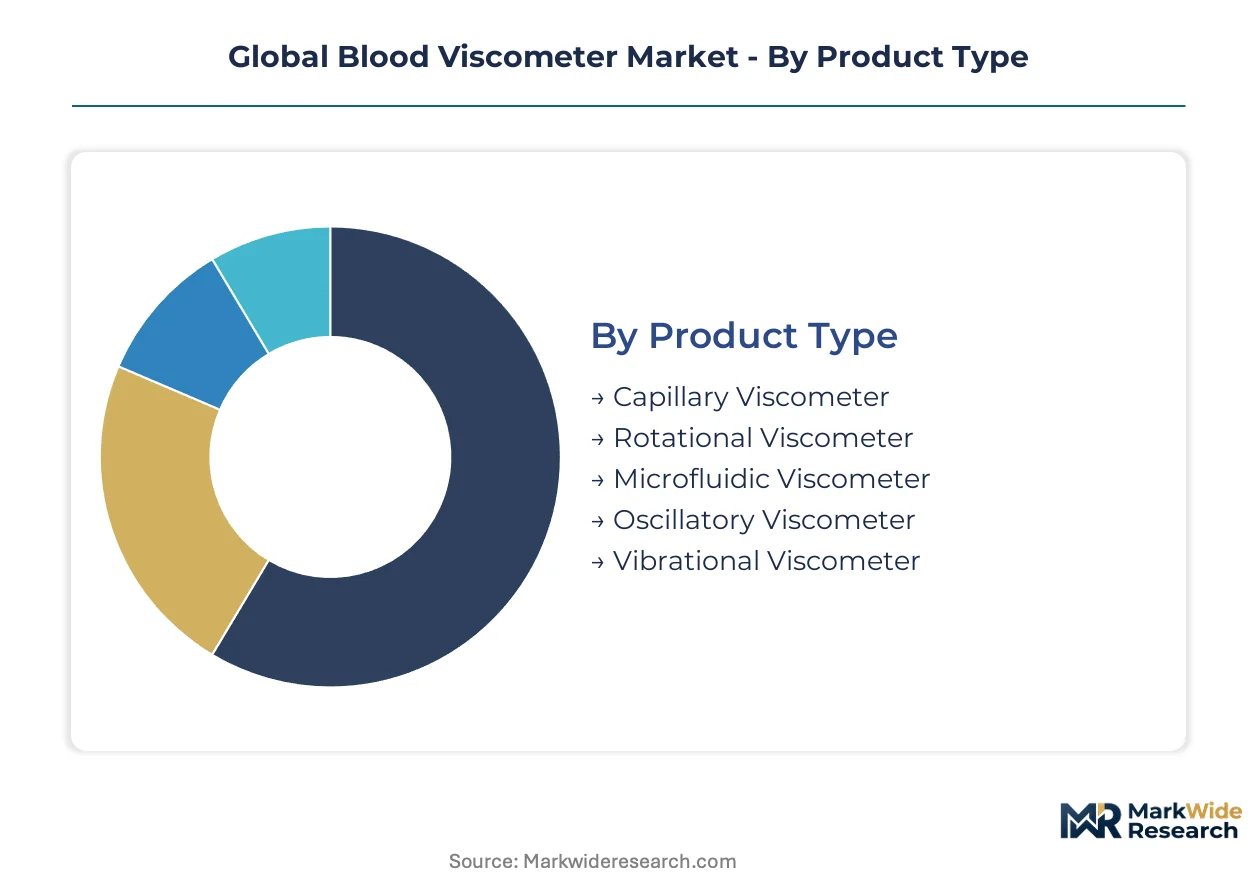
Blood viscometer procurement patterns diverge sharply across measurement modalities and care settings. Upgrade cycles and assay compatibility requirements drive replacement decisions more than raw specification comparisons.
Product Type:
Replacement cycles favor platforms that preserve existing assay validation data while adding measurement flexibility.
- Rotational Viscometer:Shear-rate-controlled measurement systems dominate hospital laboratory installed bases through decades of cardiovascular risk biomarker validation. German cardiovascular research institutes anchor demand for high-precision spindle assemblies that operate across 0.1 to 1000 s⁻¹ physiological ranges.
- Microfluidic Viscometer:Reduced-sample-volume architectures using chip-based flow channels are expanding fastest in neonatal intensive care units in Japan and South Korea. Pharmaceutical manufacturers deploy these systems for high-throughput anticoagulant formulation screening where microliter sample consumption compresses reagent costs.
- Capillary Viscometer:Gravity-driven flow through calibrated tubes retains cost advantage in resource-limited diagnostic centers.
- Oscillatory Viscometer:Dynamic mechanical analysis of viscoelastic blood properties serves specialized coagulation research.
- Vibrational Viscometer:Resonant frequency-based measurement offers maintenance simplicity for point-of-care pilot programs.
Rotational viscometer systems sit at the top of the volume ranking, with microfluidic viscometer platforms climbing the fastest.
Technology:
Component sourcing constraints and calibration traceability requirements shape technology selection more than raw measurement precision.
- Optical:Laser interferometry and imaging-based shear visualization anchor premium laboratory installations. Anton Paar GmbH leverages precision optics heritage from analytical instrumentation to capture high-end procurement in France and the Netherlands.
- Mechanical:Precision spindle and bearing assemblies constitute the established reliability standard for central hospital laboratories. REACH substance restriction evaluations are forcing reformulation of thermal interface materials and lubricants used in these systems.
- Electromagnetic:Eddy current and magnetic bearing technologies enable contactless torque measurement.
- Ultrasonic:Acoustic attenuation methods face extended China NMPA registration timelines due to GB electromagnetic compatibility standard complexity.
- Thermal:Microcalorimetric viscosity inference remains experimental for biological fluid applications.
Mechanical detection retains the largest installed base, though optical methods are gaining share fastest in replacement procurement.
Application:
Reimbursement coding and clinical utility documentation determine application-level demand concentration.
- Hematology Analysis:Whole blood and plasma viscosity measurement integrates into automated complete blood count workflows. Thermo Fisher Scientific bundles viscometry modules into integrated hematology workcells serving US health system networks.
- Cardiovascular Monitoring:Hyperviscosity syndrome diagnosis and anticoagulant therapy monitoring drive repeat testing volume. EU MDR risk-classification documentation requirements are accelerating system replacement in French hospital laboratories.
- Drug Development:Rheological characterization of biologic formulations and excipient compatibility testing supports pharmaceutical pipeline decisions.
- Research Laboratories:Academic medical centers pilot multi-mode measurement platforms to consolidate redundant device footprints.
- Point-of-Care Testing:Near-patient viscosity assays mature slowly due to FDA clearance pathway stringency exceeding central laboratory methods.
Hematology analysis commands the highest procedure volume, with drug development applications showing the steepest expansion trajectory.
End User:
Procurement consolidation through purchasing cooperatives is compressing vendor selection criteria toward service capability and platform flexibility.
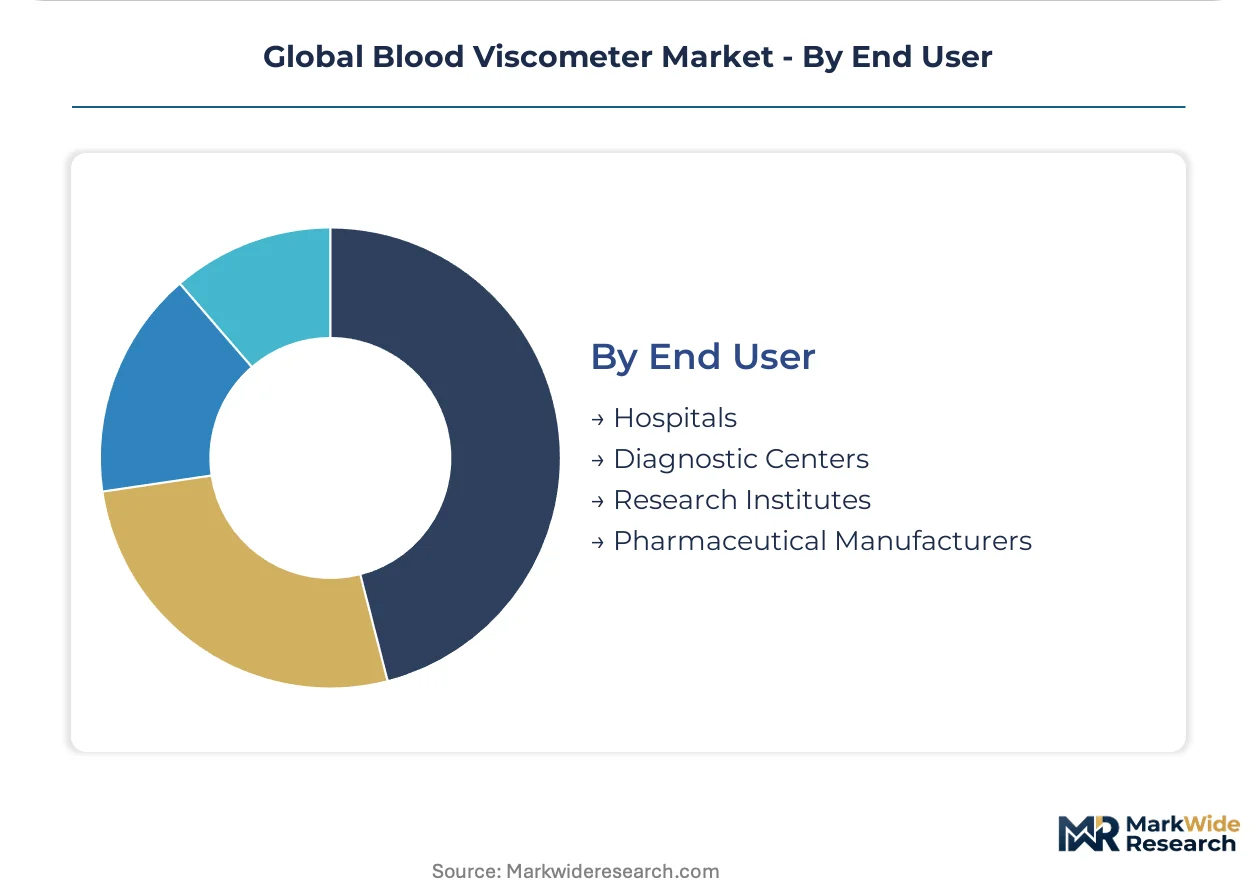
- Hospitals:Central laboratory consolidation around modular multi-assay platforms elevates technical service responsiveness over standalone device specifications. Regional laboratory purchasing cooperatives in the US and Germany unbundle after-sales contracts from instrument purchases.
- Pharmaceutical Manufacturers:High-throughput screening operations demand reduced-sample-volume systems with automated sample handling. Microfluidic chip architectures from RheoSense Inc. serve pediatric and neonatal application development programs.
- Diagnostic Centers:Independent reference laboratories prioritize cost-efficient capillary systems for routine viscosity panels.
- Research Institutes:German and Dutch cardiovascular research networks drive multi-site standardization and volume commitment structures.
Hospitals represent the dominant procurement channel, while pharmaceutical manufacturers are expanding their equipment budgets most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The blood viscometer industry traces its commercial origins to post-war European precision instrumentation, with German optical engineering establishing the foundational standards for rotational measurement systems that persist in hospital laboratories today.
Germany
Cardiovascular research institutes in Munich and Heidelberg drive procurement of high-precision rotational systems with spindle assemblies spanning physiological shear rates. The EU Medical Device Regulation accelerates replacement of legacy viscometry platforms in French and German hospital networks. Baden-Württemberg's analytical instrumentation cluster hosts supply chain concentration for precision optical components serving rotational viscometer assemblies.
United States
Academic medical centers in Boston and the Research Triangle expand pilot programs for near-patient viscosity assays under central laboratory backlog pressure. FDA Clinical Laboratory Improvement Amendments tighten analytical performance requirements for hematology instrumentation. The Southeast health system networks consolidate procurement through regional laboratory purchasing cooperatives that unbundle service contracts from instrument purchases.
China
Domestic manufacturers in Beijing and Shanghai target cost-efficient capillary systems for diagnostic centers in lower-tier cities. NMPA enforcement of GB electromagnetic compatibility standards extends registration timelines for instruments incorporating thermal or ultrasonic detection. The Yangtze River Delta concentration of medical device production faces input bottlenecks from precision optics supply concentration in Europe.
Japan
Neonatal intensive care units in Tokyo and Osaka adopt reduced-sample-volume microfluidic platforms faster than general hematology departments. METI industrial standards harmonization with ISO 15189 laboratory accreditation requirements creates calibration-traceable procurement preferences. The Kansai region's pharmaceutical manufacturing base drives high-throughput screening demand for microliter sample consumption systems.
South Korea
Pediatric subspecialty expansion in Seoul and Busan accelerates microfluidic platform deployment for neonatal applications. MFDS medical device classification aligns with EU MDR risk-documentation requirements for hematology analyzers. The Daegu-Gyeongbuk medical technology cluster concentrates domestic assembly capacity for chip-based flow channel architectures.
Global Blood Viscometer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration traceability and service responsiveness dimensions, compressing mid-tier vendors into specification-driven competition. The vendor structure fragments across precision laboratory systems and reduced-sample-volume platforms, with consolidation pressure building in the central laboratory segment. Three archetypes dominate: precision optics heritage manufacturers, microfluidic chip specialists, and integrated diagnostics bundlers. M&A activity concentrates on calibration-traceable technology assets, while strategic partnerships between instrument makers and reference material suppliers harden competitive moats.
Within the precision optics tier, Anton Paar GmbH exemplifies European analytical instrumentation heritage, while RheoSense Inc. occupies a position among microfluidic architecture specialists. Thermo Fisher Scientific Inc. anchors the integrated diagnostics bundler archetype through clinical diagnostics footprint extension. These three represent distinct competitive vectors: optical precision heritage, chip-based sample reduction, and automated platform integration.
| Leading Market Players |
|---|
| AMETEK Inc. |
| Benson Viscometers Ltd. |
| RheoSense Inc. |
| Cambridge Viscosity Inc. |
| BioFluid Technology Inc. |
| Thermo Fisher Scientific Inc. |
| A and D Co Ltd. |
| China Beijing Steellex Scientific Instrument Co. |
| Anton Paar GmbH |
| Others |
Supply & Pricing Matrix
Backward integration into precision spindle and optical component production anchors supply position for European rotational viscometer manufacturers while compressing margin flexibility for modular platform competitors sourcing from fragmented supplier bases. This captive production capability supports premium pricing persistence against commodity-tier capillary system vendors dependent on open-market component procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-marked precision laboratory systems from FDA-cleared clinical platforms and uncertified research-grade instruments. Price differentiation rests on calibration traceability documentation and bundled technical service contracts rather than raw measurement specifications. Cost compression in the economy tier intensifies as Chinese domestic manufacturers expand capillary system output for diagnostic centers. Hospital purchasing cooperatives exhibit lowest price sensitivity; independent reference laboratories demonstrate highest.
Supply Chain Analysis
Specialized rheology metrology technicians concentrate in Baden-Württemberg's analytical instrumentation cluster and Boston's academic medical center corridor, constraining production scale-up for microfluidic platform assemblers. Manufacturing draws from precision optical component suppliers in Germany and Switzerland, precision spindle foundries in Japan, and polymer chip fabrication facilities in South Korea. Single-source vulnerability concentrates in laser interferometry subassemblies. Distribution runs through large clinical diagnostics distributors serving consolidated health system networks and regional laboratory purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood viscometer market functions as a regulatory compounder where EU MDR risk-classification documentation requirements and FDA CLIA analytical performance amendments accelerate replacement demand across hospital laboratory networks.
For Market Incumbents: Cement calibration-traceable system positions through exclusive reference material partnerships with national metrology institutes, insulating against microfluidic substitution threats in neonatal applications. Extend service contract values by embedding HL7 FHIR compatibility modules that reduce legacy LIS integration friction for hospital information systems. For New Entrants and Emerging Players: EU MDR in France and Germany opens a window for reduced-sample-volume platform penetration where cardiovascular research institutes face accelerated legacy system replacement timelines. Target neonatal intensive care units in Japan and South Korea as the most penetrable segment, leveraging pediatric subspecialty expansion faster than general hematology department procurement cycles. Pursue pharmaceutical manufacturer high-throughput screening partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for precision optics heritage manufacturers because calibration-traceable technology assets command scarcity premiums in consolidated laboratory purchasing cooperative environments. Five-to-ten-year viability hinges on multi-mode measurement platform integration capabilities. Watch for ISO 15189 harmonization completion with national metrology institute standards as the inflection indicator signaling first-mover advantage crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR documentation accelerates replacement procurement in German and French hospital networks. |
| Hospital System Partnership | Consolidated purchasing cooperatives unbundle service contracts from instrument agreements. |
| Software Companion Development | HL7 FHIR compatibility reduces legacy LIS integration timelines for microfluidic platforms. |
| Reimbursement Strategy | Clinical utility documentation for hyperviscosity syndrome diagnosis drives repeat testing volume. |
| Backward Integration | Captive precision spindle production insulates against German and Swiss optical supplier bottlenecks. |
Research Methodology
Multiple input streams — primary interviews with hospital laboratory directors, biomedical engineers, and GPO contracts managers; secondary synthesis of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases; plus customs records for precision optical component trade flows — were reconciled through bottom-up instrument shipment tracking and top-down healthcare capital expenditure allocation modeling.
Historical shipment trajectories were cross-referenced against panel-derived replacement cycle assumptions across product type, technology, application, and end user segmentation dimensions. CAGRs emerged from curve-fitting procedures applied to normalized adoption S-cycles, with pharmaceutical manufacturer high-throughput screening demand and neonatal intensive care unit expansion patterns serving as key demand-side anchors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA registration timeline extensions for ultrasonic detection technologies or REACH substance restriction enforcement disruptions affecting precision spindle lubricant formulations. Material deviation in EU MDR harmonization progress or ISO 15189 metrology standard convergence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Operating Light Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Animal Operating Table Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Global Examination Lights Market